
 Egypt Trucks Market | 2026-2036
Egypt Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Trucks Market Insights
Dealer networks across Upper Egypt and the Delta is rewriting how manufacturers reach fleet buyers outside Cairo. GB Corp leverages its assembly footprint to sustain dominance in light and medium-duty categories. Toyota Egypt anchors the pickup segment through established rural distribution. Mercedes-Benz Egypt competes at the heavy-duty tier with premium chassis configurations for long-haul operators.
Trucks are motor vehicles engineered primarily for cargo transport, distinguished by gross vehicle weight ratings, ladder-frame construction, and powertrains typically exceeding 150 horsepower for heavy configurations. Their core commercial purpose centers on moving goods across distances where rail or pipeline infrastructure remains absent or underdeveloped. Heavy-duty trucks command the highest absolute value pool due to unit pricing and fleet replacement cycles, while electric fuel type represents the fastest-growing category as charging infrastructure deploys along the Cairo-Alexandria corridor. Light-duty pickups maintain volume leadership in agricultural applications, where owner-operator economics favor versatile double-cab configurations.
Egypt's Ministry of Environment enforces emission benchmarks that progressively restrict pre-Euro IV diesel imports, compelling manufacturers to certify cleaner powertrains. The General Authority for Roads, Bridges and Land Transport mandates axle-load limits and safety inspections that shape chassis design and brake system specifications. Stakeholders must monitor how Suez Canal Economic Zone customs protocols and potential carbon-border adjustments from European trading partners recalibrate total cost of ownership calculations for fleet renewal decisions.
Market Dynamics
Egypt's Ministry of Environment is enforcing Euro V emission benchmarks that compel fleet operators to retire pre-Euro IV diesel powertrains ahead of normal replacement cycles, compressing demand into cleaner heavy-duty categories and accelerating procurement decisions.
Growth Catalysts
- Suez Canal Economic Zone expansion:Customs protocols and logistics corridor investments are concentrating fleet orders from international freight operators seeking duty-advantaged staging points.
- Construction sector vehicle demand:Infrastructure investment programs are expanding heavy-duty truck orders from contractors mobilizing for transport and earthmoving contracts.
- Euro V regulatory push:The Ministry of Environment's emission benchmarks are disqualifying older imports and redirecting procurement toward certified cleaner powertrains.
Market Restraints
- Foreign exchange volatility:Egyptian pound fluctuations against hard currencies are inflating landed costs for imported chassis and powertrain components.
- Charging infrastructure gaps:Electric truck adoption faces range anxiety outside the Cairo-Alexandria corridor where fast-charging networks remain sparse.
- Domestic assembly input dependence:Local plants rely on imported knock-down kits, exposing production schedules to maritime shipping disruptions through Suez Canal transit.
Strategic Opportunities
- Upper Egypt dealer network expansion:Rural agricultural buyers in Minya and Sohag governorates remain underserved by authorized service and financing infrastructure.
- Electric last-mile logistics:Cairo's urban freight consolidation centers are creating demand for battery-electric light-duty distribution vehicles.
- Natural gas powertrain conversion:Egypt's compressed natural gas infrastructure offers a lower-carbon bridge technology for fleet operators awaiting full electrification.
Industry Challenges
- Technician certification gaps:Euro V powertrain diagnostics and after-treatment system maintenance require training pipelines that technical institutes have not yet scaled.
- Financing tenor mismatches:Leasing products for commercial vehicles rarely extend beyond three years, while Euro V asset depreciation cycles favor five-year ownership models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Trucks Market |
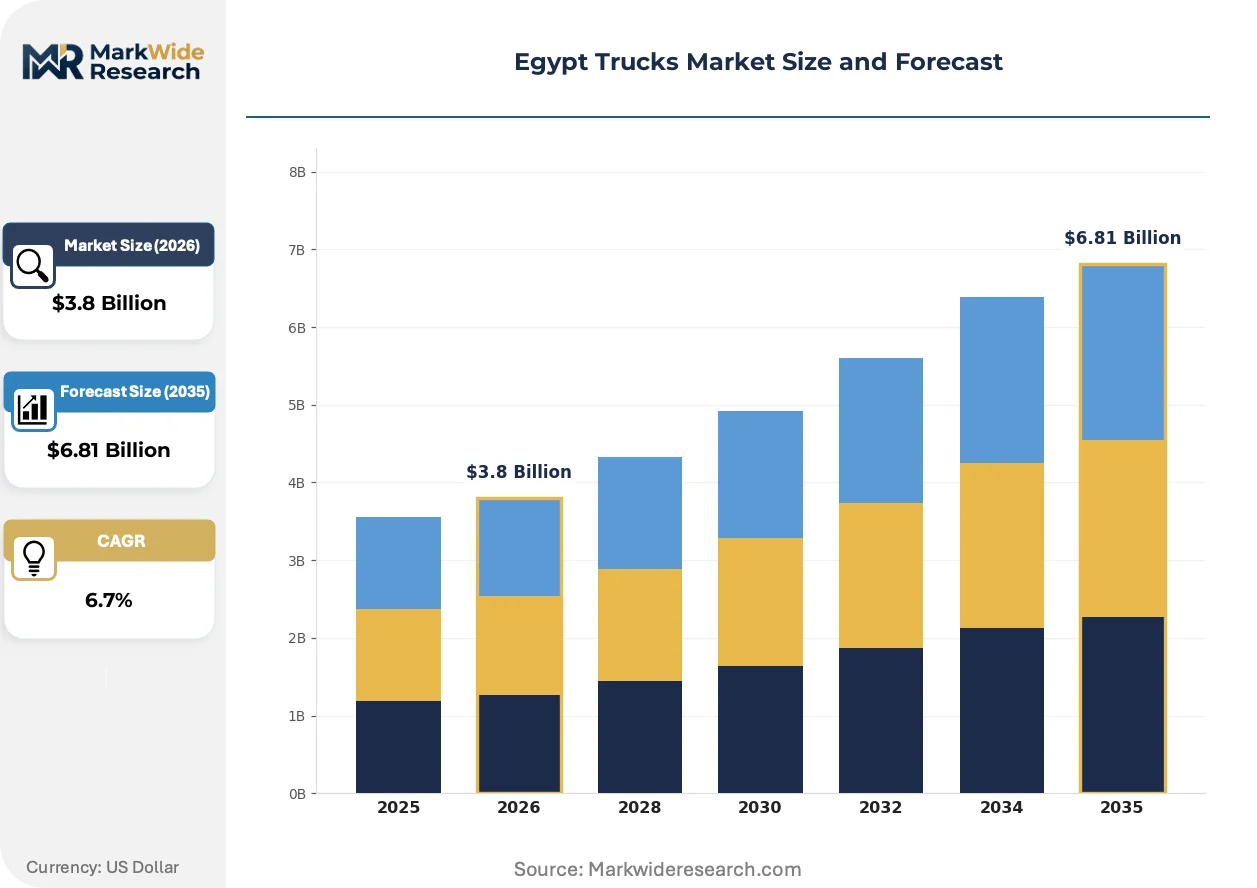
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Light-Duty, Medium-Duty, Heavy-Duty, Pickup Fuel Type: Diesel, Petrol, Electric, Hybrid Application: Construction, Logistics, Agriculture, Mining Sales Channel: Direct Sales, Distributors, Online, Rentals |
| Companies Covered | Volvo Trucks Egypt, Suzuki Motor Corporation, Toyota Egypt, General Motors Egypt, GB Corp (Ghabbour Group), Isuzu Motors Egypt, Nissan Motor Egypt, MCV, Mercedes-Benz Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Trucks Market Trends and Innovations
Powertrain architecture, emission compliance protocols, and procurement contracting models are converging to reshape how Egyptian fleet operators specify and acquire commercial vehicles.
Hybrid diesel-electric powertrains are hybridizing heavy-duty long-haul specifications as manufacturers bridge the range limitations of full battery-electric platforms. Fleet operators along the Cairo-Alexandria corridor are piloting these configurations for intercity freight. The technology is hybridizing total cost of ownership calculations by preserving diesel infrastructure while capturing fuel efficiency gains.
Egypt's Ministry of Environment is progressively tightening import restrictions on pre-Euro IV diesel engines through phased enforcement deadlines. This regulatory trajectory is accelerating fleet renewal decisions and compressing residual values for non-compliant assets. Heavy-duty categories face the steepest compliance costs, prompting operators to advance replacement timelines.
Service bundling is displacing discrete parts-and-labor transactions as fleet operators seek predictable maintenance expenditures. Authorized dealers are restructuring contracts to encompass preventive maintenance, telematics monitoring, and guaranteed uptime commitments. Agricultural owner-operators in the Delta region remain resistant, preferring transactional repair relationships that preserve cash flow flexibility.
Egypt Trucks Market Segmentation
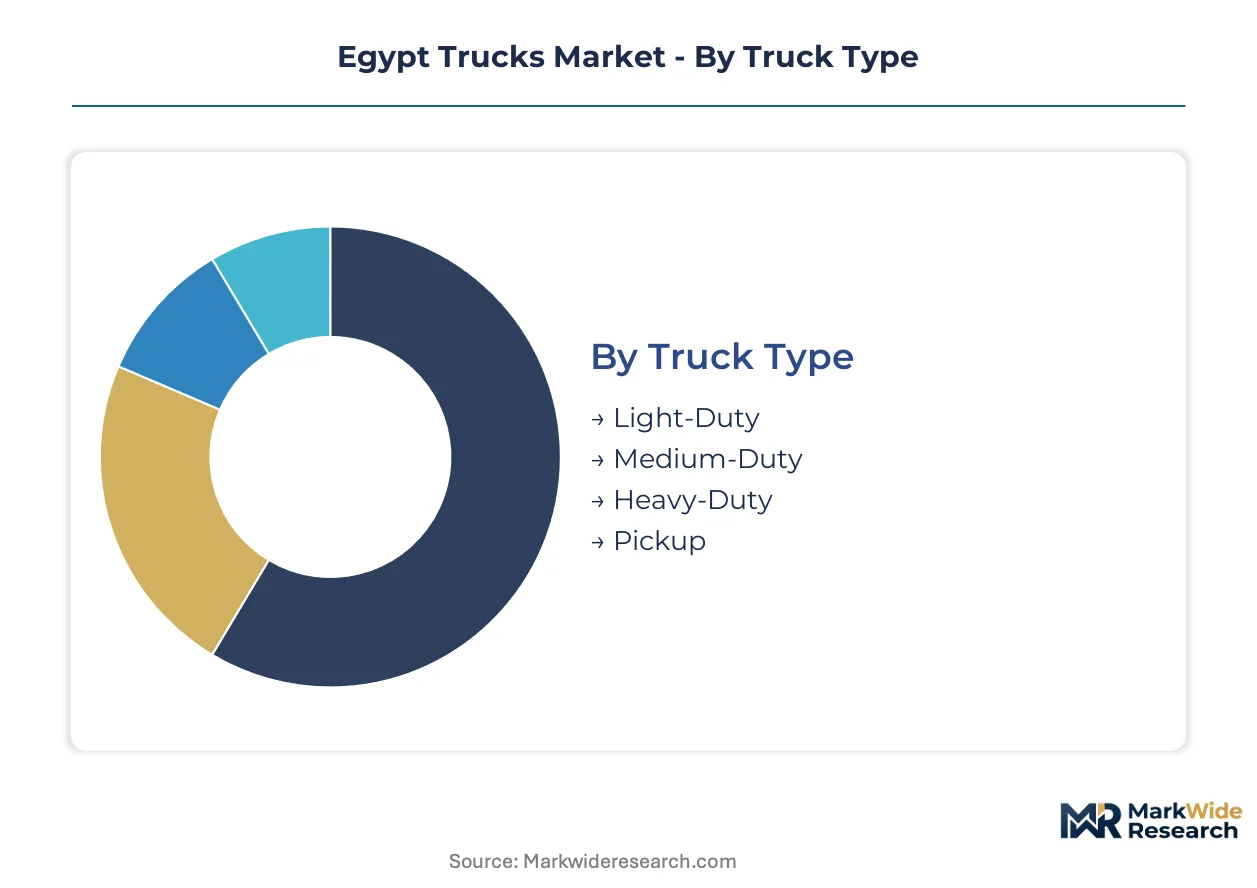
Fleet procurement patterns across Egypt diverge sharply by payload requirement, duty cycle intensity, and access to authorized service networks. Understanding these segment boundaries clarifies where powertrain investments and distribution partnerships concentrate.
Truck Type:
After-sales-service intensity escalates with axle count and engine displacement, conditioning how manufacturers structure dealer territories and parts stocking.
- Light-Duty:Gross vehicle weight ratings below 6 tonnes define this category, with cab-over-engine configurations dominating urban freight corridors. Cairo-based courier fleets and small traders in Alexandria generate concentrated demand for compact chassis with tight turning radii. Euro V compliance costs remain manageable for these powertrains, sustaining import volume despite currency pressure.
- Heavy-Duty:Multi-axle tractors and rigid trucks engineered for 16+ tonne payloads anchor long-haul routes between Suez Canal Economic Zone ports and Upper Egypt industrial zones. Fleet operators here face compressed replacement cycles as Ministry of Environment enforcement tightens on pre-Euro IV units, accelerating procurement of compliant engines with selective catalytic reduction systems.
- Medium-Duty:Single and tandem-axle configurations serve regional distribution networks connecting Delta governorates to Greater Cairo consumption centers.
- Pickup:Double-cab and single-cab variants dominate rural owner-operator economics across agricultural belts in Minya and Sohag.
Heavy-Duty holds the largest share; momentum sits with Light-Duty as last-mile logistics densifies around Cairo freight consolidation hubs.
Fuel Type:
Powertrain selection hinges on total cost of ownership calculations shaped by fuel subsidy regimes, charging infrastructure density, and residual value risk.
- Diesel:Compression-ignition engines retain dominance across long-haul and heavy-duty applications where energy density and refueling speed remain critical. Suez Canal Economic Zone logistics operators specify Euro V diesel powertrains to preserve cross-border operating rights into European markets.
- Electric:Battery-electric configurations are penetrating light-duty distribution fleets serving Cairo-Alexandria corridor urban centers. Fast-charging station deployment along this axis is easing range anxiety for fixed-route operators, though Upper Egypt adoption lags due to grid reliability concerns.
- Petrol:Spark-ignition engines persist in pickup segments where purchase price sensitivity outweighs fuel economy considerations.
- Hybrid:Diesel-electric parallel systems are emerging in pilot configurations for intercity freight operators seeking fuel efficiency gains without full infrastructure dependency.
Diesel retains volume leadership; electric configurations are expanding most quickly along electrified logistics corridors.
Application:
End-use sector cyclicality determines fleet utilization rates and financing tenor preferences across Egyptian commercial vehicle buyers.
- Construction:Tipper trucks and concrete mixers face severe duty cycles on infrastructure project sites from New Administrative Capital development to Sinai road networks. Contractors specify reinforced chassis and high-torque powertrains for unimproved terrain, accepting premium pricing for durability.
- Logistics:Container tractors and box trucks concentrate in Suez Canal Economic Zone customs-advantaged staging facilities. International freight forwarders demand telematics-equipped assets with guaranteed uptime contracts to meet just-in-time delivery obligations.
- Agriculture:Pickup trucks and light-duty flatbeds serve cotton and wheat harvest logistics across Delta and Upper Egypt governorates.
- Mining:Heavy-duty dump trucks operate in phosphate extraction zones and limestone quarries where dust filtration and cooling system robustness determine asset longevity.
Construction commands the highest absolute unit values; logistics is gaining share fastest as supply chain formalization accelerates.
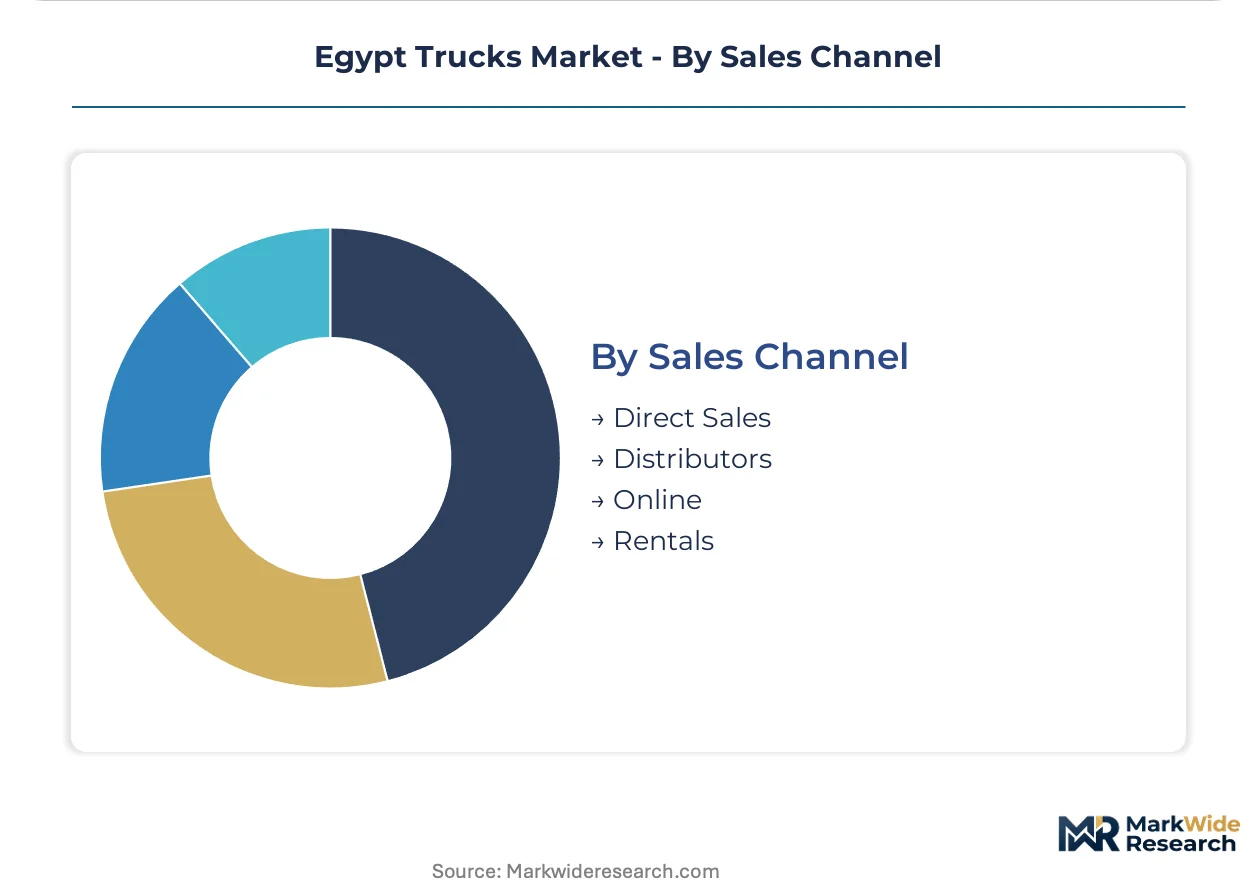
Sales Channel:
Channel selection reflects buyer sophistication, fleet scale, and access to working capital financing instruments.
- Distributors:Authorized dealer networks dominate medium and heavy-duty transactions, bundling financing, preventive maintenance contracts, and residual value guarantees. GB Corp and Toyota Egypt leverage assembly plant proximity to stock configured chassis for rapid delivery.
- Direct Sales:Large fleet operators with 50+ unit requirements negotiate manufacturer-direct procurement for standardized specifications, bypassing dealer margin layers.
- Rentals:Short-term leasing addresses construction contractors with project-specific peak demand and uncertain contract duration.
- Online:Digital platforms facilitate used truck transactions and light-duty new vehicle price discovery, though heavy-duty procurement remains relationship-driven.
Distributors hold the largest share; direct sales channels are expanding most quickly among consolidated logistics fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone anchors Egypt's logistics infrastructure, channeling international freight through customs-advantaged corridors that concentrate fleet procurement decisions around maritime connectivity.
Greater Cairo
Cairo-based courier fleets and last-mile logistics operators drive concentrated demand for light-duty cab-over-engine configurations with tight turning radii. The Ministry of Environment's Euro V enforcement timeline accelerates fleet renewal decisions among urban freight consolidators. Industrial zones in 10th of Ramadan and Obour Cities host assembly plants supplying configured chassis for rapid delivery to metropolitan buyers.
Suez Canal Economic Zone
International freight forwarders operating customs-advantaged staging facilities generate demand for telematics-equipped heavy-duty tractors and container handlers. Suez Canal Authority protocols shape procurement specifications for cross-border operating rights into European markets. Logistics corridors thickening around Port Said and Sokhna are concentrating orders from regional shipping lines seeking duty-efficient cargo staging.
Delta Governorates
Agricultural owner-operators across Gharbia and Dakahlia governorates sustain volume demand for double-cab pickups serving cotton and wheat harvest logistics. Rural distribution networks remain underserved by authorized service infrastructure, compressing financing access for small-scale buyers. Dealer expansion into Tanta and Mansoura is rewriting manufacturer reach beyond Cairo-centric distribution.
Upper Egypt
Limestone quarries and phosphate extraction zones in Minya and Sohag generate severe-duty demand for heavy-duty dump trucks with reinforced cooling systems. Grid reliability concerns outside the Cairo-Alexandria corridor delay electric truck adoption despite national emission targets. Technical institutes in Assiut are scaling technician certification pipelines for Euro V after-treatment maintenance.
Alexandria and North Coast
Fast-charging infrastructure deployment along the Cairo-Alexandria corridor is easing range anxiety for pilot electric light-duty distribution fleets. Alexandria Port container traffic drives tractor-trailer demand from international logistics operators. Borg El Arab industrial zone hosts knock-down kit assembly exposing production schedules to maritime shipping disruptions through canal transit.
Egypt Trucks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying powertrain and chassis subsystems to assembly plants. The Egypt Trucks Market structures around a consolidated assembly layer with fragmented import distribution beneath it. Three archetypes dominate: multinational assemblers with local plant presence, authorized distributors bundling financing and service contracts, and regional dealer networks penetrating rural agricultural demand. Competitive moves concentrate on dealer territory expansion into Upper Egypt and service bundling contracts that displace transactional repair relationships.
Within the multinational assembler tier, Volvo Trucks Egypt and Mercedes-Benz Egypt anchor heavy-duty premium positioning through long-haul chassis configurations. Toyota Egypt exemplifies the distributor-anchored archetype in light-duty pickups through rural network penetration. GB Corp occupies a distinctive position spanning assembly integration and distribution control across multiple brand portfolios. These three patterns illustrate how geographic coverage, service bundling intensity, and assembly proximity differentiate competitive positioning in fleet procurement decisions.
| Leading Market Players |
|---|
| Volvo Trucks Egypt |
| Suzuki Motor Corporation |
| Toyota Egypt |
| General Motors Egypt |
| GB Corp (Ghabbour Group) |
| Isuzu Motors Egypt |
| Nissan Motor Egypt |
| MCV |
| Mercedes-Benz Egypt |
| Others |
Pricing and Supply Chain Analysis
The Cairo-Alexandria logistics corridor concentrates fleet procurement volumes where Egyptian pound volatility against hard currencies feeds directly into chassis landed costs and downstream price stratification across premium, standard, and economy tiers. Supply concentration in Greater Cairo assembly plants amplifies pricing power for GB Corp and Toyota Egypt while compressing margins for import-dependent distributors serving Upper Egypt agricultural buyers.
Pricing Analysis
Volume-discount tiering structures separate authorized dealer networks from direct sales channels, with fleet operators commanding 15-20% price advantages at 50+ unit thresholds. Price differentiation rests on Euro V certification grade and after-sales bundling intensity, where preventive maintenance contracts offset currency-driven chassis inflation. Pricing pressure stems from Egyptian pound depreciation inflating knock-down kit import costs, squeezing standard-tier distributors most acutely. Agricultural owner-operators in Minya and Sohag exhibit highest price sensitivity, while Suez Canal Economic Zone logistics operators absorb premiums for telematics-equipped uptime guarantees.
Supply Chain Analysis
Steel feedstock and engine knock-down kits draw primarily from China, Japan, and Germany, with selective catalytic reduction systems sourcing from European Tier 1 suppliers. Local assembly plants depend on imported axle components, turbochargers, and emission after-treatment hardware that transit through Suez Canal maritime chokepoints. Single-source vulnerability concentrates in Euro V-compliant engine management systems where alternative certification pathways remain limited. Distribution runs through authorized dealer networks in Greater Cairo, with rural penetration into Delta and Upper Egypt governorates expanding through sub-distributor arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's truck market rewards players who control certified technician pipelines and charging infrastructure deployment timelines, as Euro V diagnostics capability and electric fleet readiness gaps outpace current training institute output.
For Market Incumbents: Pre-empt technician certification bottlenecks by scaling in-house training academies ahead of Ministry of Environment enforcement deadlines, while securing exclusive fast-charging partnerships along the Cairo-Alexandria corridor to lock out electric entrant challengers. Defensive consolidation through backward integration into axle and brake component production mitigates knock-down kit currency exposure. For New Entrants and Emerging Players: Upper Egypt's Sohag and Assiut governorates present dealer infrastructure white space where authorized service networks remain sparse and agricultural fleet buyers face financing access constraints. Natural gas conversion kits offer a penetrable entry angle for operators awaiting full electrification, with compressed natural gas infrastructure already densifying through state-backed station deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core commercial vehicle distribution assets amid currency pressure and working capital intensity. Long-term viability hinges on electric platform readiness and Euro V service capability buildout. The signal to watch is Suez Canal Economic Zone customs protocol adjustments that would accelerate fleet renewal cycles or compress residual values for non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Euro V Technician Certification Academy | Ministry of Environment enforcement deadlines accelerate demand for SCR system diagnostics capability. |
| Fast-Charging Infrastructure Partnership | Cairo-Alexandria corridor electrification enables battery-electric pilot fleet expansion for urban logistics. |
| Natural Gas Powertrain Conversion Program | State-backed CNG station deployment creates bridge technology demand ahead of full electrification. |
| Upper Egypt Dealer Network Expansion | Rural agricultural buyers in Minya and Sohag remain underserved by authorized financing infrastructure. |
| Backward Integration into Axle Components | Knock-down kit currency exposure compels in-house production of brake and chassis subsystems. |
Research Methodology
A standing panel of fleet operations managers, dealer network principals, Ministry of Environment compliance officers, and Suez Canal Economic Zone logistics coordinators provided ongoing calibration against secondary validation from General Authority for Roads customs records, automotive production databases, and Euro V certification registries. Primary fieldwork combined structured interviews with construction contractors and agricultural owner-operators across Delta and Upper Egypt governorates. Bottom-up unit economics triangulated against top-down sectoral expenditure flows from infrastructure investment programs.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specific year anchoring, with segmentation modeling spanning truck type, fuel architecture, application sector, and sales channel dimensions. CAGRs derived from fleet replacement cycle analysis and emission compliance deadline impact assessment, incorporating Egyptian pound volatility assumptions and charging infrastructure deployment trajectories as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese electric truck manufacturers or accelerated Suez Canal Economic Zone customs liberalization would shift outcomes beyond modeled ranges. Cross-checking against Suez Canal Authority freight volume statistics and Ministry of Environment enforcement action frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Global Connected Truck Market