
 Stacker Truck Market | 2026-2036
Stacker Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Stacker Truck Market Analytics
Multi-source procurement for drive systems and mast assemblies is broadening as OEMs reduce dependency on captive component lines. Toyota Industries Corporation leverages in-house motor production to control lead times for electric stacker platforms. Jungheinrich AG sustains R&D intensity in lithium-ion integration for narrow-aisle warehouse configurations. Hangcha Group Co., Ltd. anchors volume production through automated welding lines at its Zhejiang facilities.
A stacker truck is a powered or manually operated material handling vehicle with a vertical mast and fork carriage designed to lift, transport, and stack palletized loads at heights typically exceeding 3 meters, utilizing hydraulic lift mechanisms and load backrests for stability. Electric stacker units dominate warehouse deployments where zero-emission operation and reduced noise levels align with indoor air quality mandates, while reach stacker variants command premium positioning in high-density storage applications. The warehousing vertical absorbs the largest share of unit shipments as third-party logistics providers expand fulfillment networks, and battery-powered configurations are displacing diesel alternatives in facilities subject to indoor emissions protocols.
The EPA enforces Tier 4 Final emissions standards for diesel-powered industrial trucks operating in US facilities, while the EU F-Gas Regulation restricts fluorinated greenhouse gases in refrigeration and ancillary systems, indirectly pressuring fleet operators toward fully electric material handling equipment. OSHA mandates operator training certification and load capacity labeling, shaping procurement specifications and aftermarket service requirements. Stakeholders must monitor battery recycling infrastructure development and charging standard harmonization as fleet electrification scales.
Market Dynamics
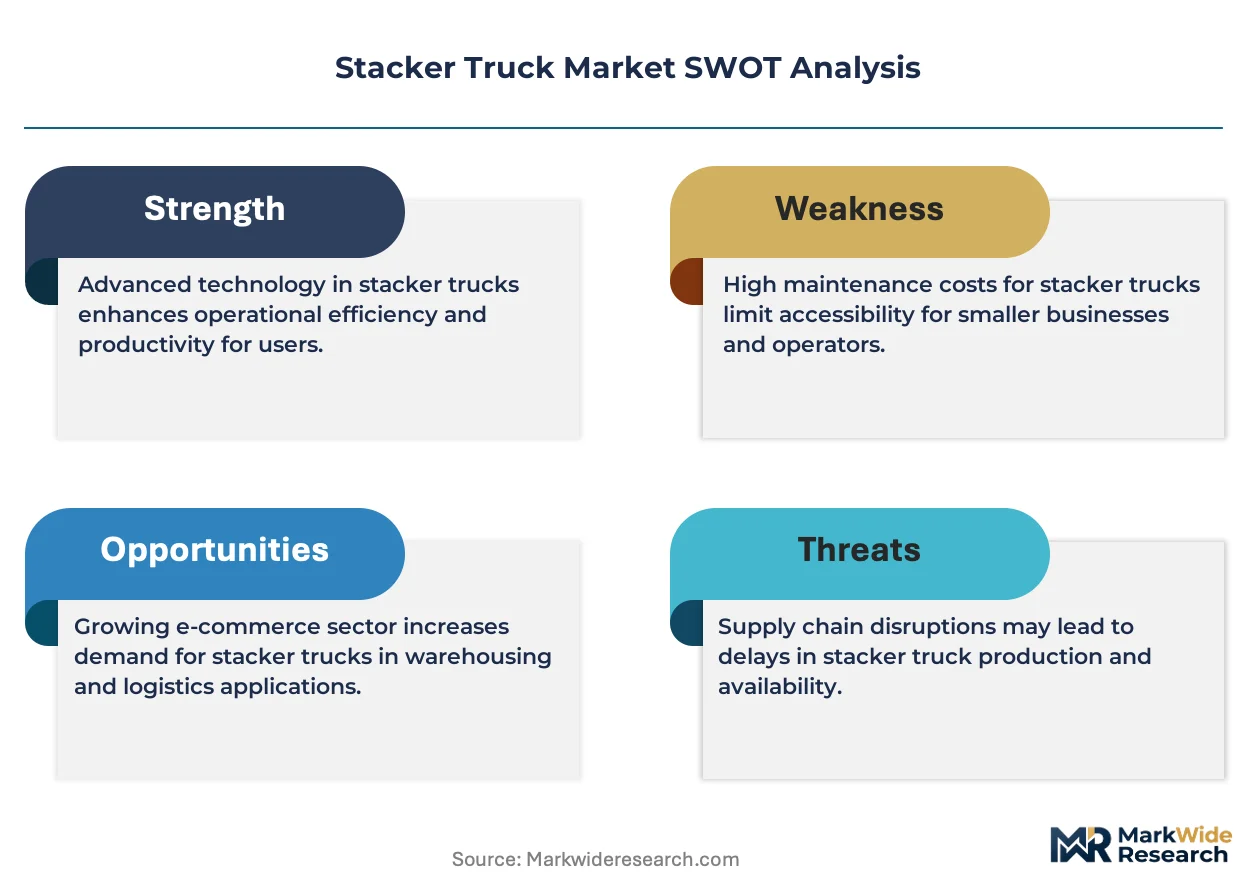
Fleet electrification is compressing diesel stacker residual values while lithium-ion battery pack costs reshape total cost of ownership calculations for warehouse operators. This technology transition is forcing capital allocation decisions across third-party logistics networks and manufacturing facilities.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases in ancillary refrigeration systems are redirecting cold-chain facilities toward fully electric material handling fleets.
- E-commerce fulfillment density:Narrow-aisle warehouse configurations in Germany, China, and the United States are accelerating orders for electric reach stacker variants.
- Battery chemistry improvements:Lithium-ion platforms with faster charge cycles and opportunity charging capability are displacing lead-acid configurations in multi-shift operations.
Market Restraints
- Lithium supply concentration:Cathode material processing capacity clusters in limited geographies, exposing OEMs to input cost volatility and supply security risks.
- Charging infrastructure capex:Fleet electrification requires substantial facility electrical upgrades, including high-capacity grid connections and distributed charging stations.
- Operator certification friction:OSHA-mandated training programs and load capacity certification requirements extend procurement-to-deployment timelines for new equipment.
Strategic Opportunities
- India warehousing expansion:PLI scheme incentives for manufacturing and logistics infrastructure are creating underpenetrated demand for electric stacker deployments in emerging industrial corridors.
- Automated guided vehicle convergence:Integration of autonomous navigation with electric stacker platforms opens high-density storage applications previously served by manual equipment.
- CSRD disclosure requirements:Corporate sustainability reporting mandates in Europe are elevating procurement preference for zero-emission material handling equipment with verified carbon footprints.
Industry Challenges
- High-voltage technician scarcity:Maintenance of lithium-ion battery systems and onboard power electronics requires specialized electrical safety training that outpaces workforce development.
- Legacy fleet integration:Mixed-facility operations combining diesel, lead-acid electric, and lithium-ion equipment create operational complexity in charging protocols and maintenance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stacker Truck Market |
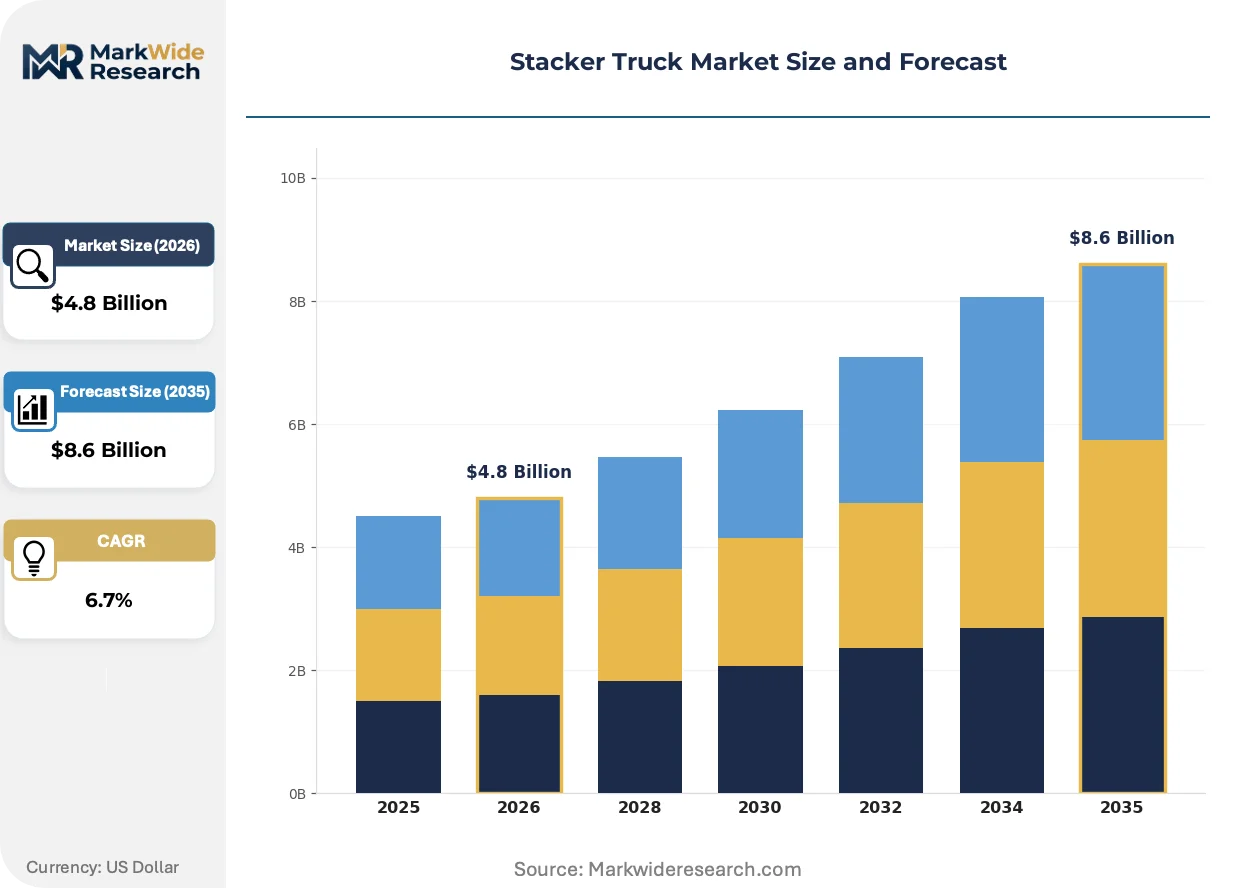
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric Stacker, Manual Stacker, Reach Stacker, Straddle Stacker Industry Vertical: Warehousing, Manufacturing, Retail, Logistics Load Capacity: 1 Ton, 2 Tons, 3 Tons, 5 Tons Power Source: Battery-Powered, Diesel-Powered, Electric-Powered, Hybrid |
| Companies Covered | Crown Equipment Corporation, Toyota Industries Corporation, Clark Material Handling Company, Hangcha Group Co., Ltd., Jungheinrich AG, KION Group AG, Mitsubishi Logisnext Co., Ltd., Hyster-Yale Materials Handling Inc, Doosan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stacker Truck Market Evolving Landscape
Electrification is fragmenting the competitive landscape as battery technology becomes a primary differentiator alongside traditional mast and chassis engineering. Equipment buyers now evaluate total ecosystem costs rather than unit purchase price alone.
Lithium-iron-phosphate battery chemistry is decentralizing fleet energy management by enabling opportunity charging at distributed points throughout warehouse facilities rather than centralized battery rooms. Third-party logistics providers in high-velocity fulfillment centers are adopting this architecture to eliminate battery changeover downtime. The structural consequence is compressing facility footprint requirements for charging infrastructure while extending effective equipment utilization rates.
The EU F-Gas Regulation is accelerating refrigerant system redesigns that indirectly favor electric stacker procurement in temperature-controlled warehousing. Cold storage operators face compliance deadlines for fluorinated gas reduction that align with fleet replacement cycles. German and Dutch facilities are responding fastest, integrating electric material handling with low-GWP refrigeration as combined sustainability investments.
Third-party logistics providers are unbundling after-sales service contracts from equipment procurement, selecting specialized regional maintenance firms over OEM captive service networks. This channel disintermediation is most pronounced in the United States where independent service organizations offer faster response times in distributed fulfillment networks. The shift is compressing OEM service revenue streams while expanding parts-only distribution opportunities.
Stacker Truck Market Segmentation
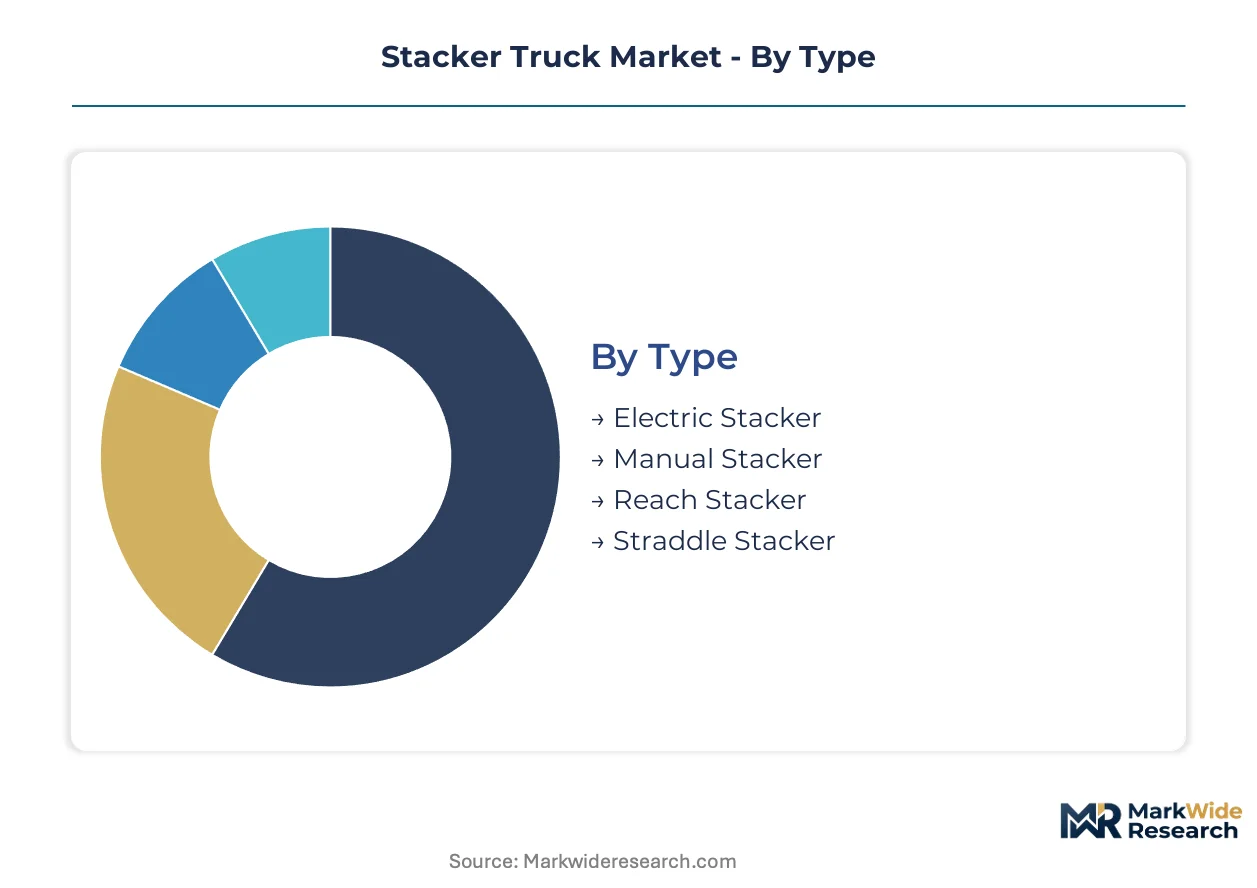
Stacker truck procurement specifications diverge sharply across facility types and operational intensities. Certification requirements for battery systems and operator training programs create compliance-driven segmentation that shapes vendor selection and deployment timelines.
Type:
OSHA mandates Class I and Class II operator certifications for powered industrial trucks, with electric and reach stacker variants triggering the most stringent training protocols. Manual stackers fall outside powered equipment classifications, reducing compliance overhead for low-throughput operations.
- Electric Stacker:Zero-emission platforms utilizing AC motor drives and lithium-ion battery packs dominate indoor warehouse deployments. German third-party logistics providers and Chinese e-commerce fulfillment centers are concentrating fleet orders here as EU F-Gas Regulation deadlines and indoor air quality mandates converge.
- Reach Stacker:Telescoping mast designs enable pallet retrieval at heights exceeding 10 meters in narrow-aisle configurations. High-density storage facilities in the United States are accelerating adoption as land costs in major distribution corridors compress facility footprints.
- Manual Stacker:Hand-pump hydraulic systems serve low-volume operations without electrical infrastructure requirements. Small retail backrooms and light manufacturing cells in India rely on these units where capital constraints limit powered equipment procurement.
- Straddle Stacker:Outrigger legs straddle pallet loads for enhanced stability in outdoor or uneven surface applications. Construction material yards and lumber distribution centers utilize these configurations where ground conditions preclude standard counterbalance designs.
Electric Stacker sits at the top of the volume ranking, with Reach Stacker climbing the fastest.
Industry Vertical:
Capital deployment patterns across verticals reflect divergent throughput requirements and facility ownership structures. Third-party logistics providers amortize equipment costs across contract durations, while captive manufacturing fleets optimize for total cost of ownership over extended holding periods.
- Warehousing:Multi-shift operations in temperature-controlled and ambient storage facilities absorb the largest share of electric stacker shipments. Battery opportunity charging infrastructure and narrow-aisle racking configurations define procurement specifications in this vertical.
- Logistics:Cross-dock terminals and freight consolidation centers prioritize rapid load turnover over vertical reach. Diesel-powered units retain residual presence in outdoor yard operations, though electrification is compressing this installed base.
- Manufacturing:Just-in-time production lines require synchronized material delivery with minimal inventory buffers. Stackers here integrate with manufacturing execution systems for real-time location tracking and dispatch optimization.
- Retail:Store-level receiving docks and backroom storage impose space constraints that favor compact electric walkie stacker designs. Big-box retailers in the United States are standardizing on lithium-ion platforms to eliminate battery maintenance labor.
Warehousing commands the dominant revenue share, with Logistics expanding most quickly as parcel network density increases.
Load Capacity:
Rated capacity determines mast engineering, counterweight mass, and battery sizing in ways that cascade through manufacturing cost structures. Higher-capacity units require proportionally larger electrical infrastructure for charging, segmenting facility upgrade requirements.
- 1 Ton:Compact walk-behind and rider platforms serve light-duty applications in retail and small parcel handling. These units minimize aisle width requirements and enable high-density storage configurations in constrained facilities.
- 2 Tons:Standard pallet weights in consumer goods distribution center this segment as the volume anchor. Most electric stacker OEMs optimize production lines around this capacity rating, achieving manufacturing scale efficiencies.
- 3 Tons:Industrial manufacturing and heavier retail merchandise push demand toward this intermediate rating. Battery pack sizing and motor thermal management become critical engineering constraints at this threshold.
- 5 Tons:Heavy manufacturing inputs, bulk beverages, and building materials require reinforced mast structures and enhanced stability systems. Diesel configurations retain market presence here where electrification faces technical barriers.
2 Tons anchors procurement volume, with 1 Ton gaining share fastest as micro-fulfillment formats proliferate.
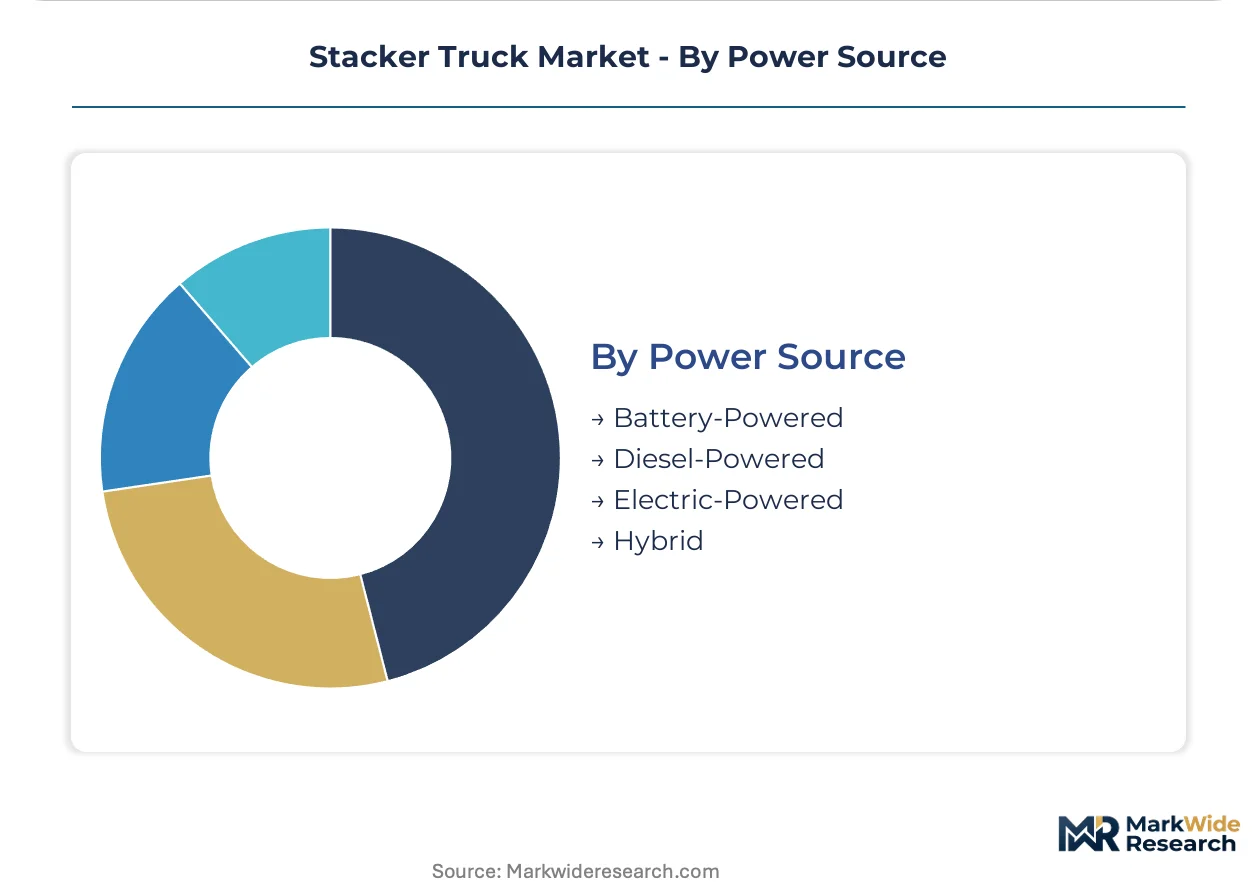
Power Source:
EPA Tier 4 Final emissions compliance and EU F-Gas Regulation refrigerant phase-downs are redirecting procurement decisions across power source categories. Total cost of ownership calculations now incorporate carbon pricing exposure and residual value risk in ways that favor electrification.
- Battery-Powered:Lithium-ion chemistry with opportunity charging capability is displacing lead-acid across multi-shift warehouse operations. German cold storage operators are pairing these fleets with low-GWP refrigeration systems as combined sustainability investments.
- Electric-Powered:Grid-connected cable or rail systems eliminate battery weight and charging downtime in fixed-route applications. Automated storage and retrieval systems in high-bay warehouses utilize this architecture for continuous operation.
- Diesel-Powered:Outdoor yard operations and facilities lacking electrical infrastructure sustain residual demand. Residual values are compressing as emissions regulations tighten and electrification alternatives mature.
- Hybrid:Dual-power architectures combine battery operation indoors with diesel range extension for outdoor transport. Port terminals and lumber yards with mixed indoor-outdoor workflows evaluate these configurations for operational flexibility.
Battery-Powered leads deployment scale, with Electric-Powered showing the steepest expansion trajectory in automated warehouse installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German warehouse automation investments anchor procurement volumes for electric stacker platforms as narrow-aisle configurations dominate fulfillment center expansions. Fleet operators across major industrial economies face converging regulatory deadlines and infrastructure upgrade cycles.
United States
Third-party logistics providers in Dallas-Fort Worth and Chicago metropolitan corridors are consolidating fulfillment networks around lithium-ion electric stackers. OSHA mandates operator training certification and load capacity labeling, extending procurement-to-deployment timelines for equipment buyers. Big-box retailers in California are eliminating lead-acid battery maintenance through standardized lithium-ion platform adoption.
Germany
Cold storage operators in the Ruhr industrial region pair electric material handling fleets with low-GWP refrigeration systems as combined sustainability investments. The EU F-Gas Regulation accelerates refrigerant system redesigns that indirectly favor fully electric stacker procurement in temperature-controlled warehousing. Bavarian automotive suppliers integrate narrow-aisle reach stackers into just-in-time production line feeding operations.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta are expanding fleet orders for narrow-aisle electric units. The country's dual carbon goals pressure warehouse operators toward zero-emission material handling equipment. Hangcha Group's Zhejiang manufacturing facilities anchor volume production through automated welding lines serving domestic and export demand.
India
PLI scheme incentives for manufacturing and logistics infrastructure are creating demand for electric stacker deployments in emerging industrial corridors around Pune and Chennai. The country's national logistics regulator emphasizes warehouse modernization standards that favor powered equipment over manual alternatives. Gujarat-based pharmaceutical distributors are upgrading receiving dock operations with compact battery-powered walkie stackers.
Japan
Automotive component suppliers in Aichi Prefecture deploy electric stackers for synchronized material delivery to assembly lines. METI efficiency standards for industrial equipment shape procurement specifications toward energy recovery systems and opportunity charging architectures. Osaka-based third-party logistics providers are retrofitting existing facilities with distributed lithium-ion charging infrastructure to eliminate centralized battery rooms.
Stacker Truck Market Competitive Landscape
Global majors compete with regional champions across battery technology integration and narrow-aisle engineering capabilities. Market structure consolidates around vertically integrated Japanese and European conglomerates with captive component production, while Chinese volume specialists expand export capacity through automated manufacturing lines. Strategic archetypes include integrated industrial conglomerates with in-house motor and battery production, scale-focused fabricators serving price-sensitive emerging markets, and narrow-aisle specialists targeting high-density warehousing applications. Competitive positioning depends on backward integration into powertrain components and geographic expansion through distribution partnerships.
Among Asia-Pacific-based industrial conglomerates, Toyota Industries Corporation and Mitsubishi Logisnext Co., Ltd. exemplify the integrated archetype with captive supply of electric drive systems. Hangcha Group Co., Ltd. occupies a position within the volume-production tier, representing Chinese manufacturing scale advantages in standardized equipment segments. Jungheinrich AG anchors the European specialist tier, exemplifying engineering-intensive positioning in high-reach narrow-aisle configurations for premium warehouse automation deployments.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Toyota Industries Corporation |
| Clark Material Handling Company |
| Hangcha Group Co., Ltd. |
| Jungheinrich AG |
| KION Group AG |
| Mitsubishi Logisnext Co., Ltd. |
| Hyster-Yale Materials Handling Inc |
| Doosan Corporation |
| Others |
Value Network & Pricing Analysis
Third-party logistics providers with hyperscale fulfillment contracts dominate procurement volumes, compressing pricing power toward contract-based long-term offtake structures with volume-scaled rebates. OEMs respond by unbundling after-sales service from equipment sales, creating hybrid pricing models that separate capital expenditure from lifecycle maintenance costs.
Pricing Analysis
Lithium cathode material costs pass through directly to battery pack pricing, forcing OEMs to absorb margin compression or renegotiate annual contracts. Three-tier pricing structure across premium, standard, and economy levels separates Jungheinrich and Toyota captive-motor platforms from Hangcha volume production and manual stacker alternatives. Price differentiation hinges on ISO 3691 safety certification tier and after-sales service bundling intensity. Small retail operators show highest price sensitivity, while German cold storage facilities prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and DHL fulfillment networks, bypassing distributor markups for fleet-scale orders. Manufacturing concentrates in China, Germany, and Japan, with Zhejiang province anchoring welded mast production and Aichi Prefecture supplying precision drive motors. Supply chains draw from lithium carbonate processing in Chile and Australia, high-grade steel from Japanese mills, and semiconductor power modules from Taiwan. Single-source vulnerability in lithium hydroxide refining creates tariff exposure as EU battery regulations tighten material traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stacker truck margins are expanding through lithium-ion platform standardization that eliminates lead-acid battery maintenance labor and compresses total cost of ownership for fleet operators. Premium-tier shift toward reach stacker configurations in narrow-aisle warehousing supports pricing power for engineering-intensive OEMs.
For Market Incumbents: Acquire regional aftermarket service networks to defend against channel disintermediation by independent service organizations in US fulfillment corridors. Deepen backward integration into lithium-ion battery pack assembly to secure cathode supply against processing concentration in China. Counter emerging Chinese volume exporters by accelerating EU F-Gas Regulation compliance certification for cold storage applications. For New Entrants and Emerging Players: Small pharmaceutical distributors in Gujarat and Pune industrial corridors represent underserved buyer archetypes with unmet demand for compact walkie stackers in temperature-controlled receiving docks. Target India's PLI scheme warehousing incentives with localized assembly partnerships avoiding full import duties. Pursue fast-charging lithium-iron-phosphate platforms as differentiation against legacy lead-acid incumbents. For Investors and Strategic Acquirers: Industrial conglomerates with captive logistics divisions are the most active acquirer in this space, seeking narrow-aisle engineering capabilities for in-house fulfillment network modernization. Five-to-ten year viability favors OEMs with integrated motor production and established lithium-ion service infrastructure. Watch battery recycling infrastructure development as inflection indicator for residual value risk in electrified fleet financing models.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Platform Standardization | Eliminates lead-acid maintenance labor for US big-box retailers and German cold storage operators. |
| Backward Integration into Battery Assembly | Reduces cathode cost volatility exposure for OEMs serving multi-shift warehouse contracts. |
| Narrow-Aisle Engineering Investment | Captures premium positioning in Dallas-Fort Worth and Chicago fulfillment corridor expansions. |
| Regional Service Network Acquisition | Defends against independent service organization disintermediation in distributed US logistics networks. |
| EU F-Gas Compliance Certification | Unlocks combined sustainability procurement with low-GWP refrigeration in German Ruhr facilities. |
Research Methodology
Direct dialogue with warehouse operations directors, OEM procurement teams, aftermarket service heads, and lithium-ion battery system engineers grounded qualitative findings in facility-level deployment constraints. Secondary validation drew from OSHA enforcement databases, EPA Tier 4 Final compliance filings, EU F-Gas Regulation implementation reports, and customs trade data on industrial truck imports. Bottom-up equipment shipment tallies triangulated against top-down logistics infrastructure investment flows.
Bottom-up volume modeling tracked unit deployments by type, power source, and load capacity across the projection horizon, while top-down analysis calibrated against third-party logistics capex disclosures and warehouse automation investment surveys. Segmentation dimensions spanned equipment type, industry vertical, load capacity tier, power source architecture, and regional regulatory cluster. CAGRs were derived from slope-log regression on normalized shipment data, stress-tested against lithium supply elasticity and charging infrastructure deployment curves.
Underlying measurement precision varies by segment; electric stacker and battery-powered categories carry tighter precision than manual stacker and diesel residual demand due to disclosure consistency among publicly traded OEMs. Forecasts reflect assumptions on EU F-Gas Regulation enforcement timing, lithium carbonate price normalization, and India PLI scheme disbursement velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Bucket Trucks Market