
 Dump Truck & Body Market | 2026-2036
Dump Truck & Body Market Size, Share, and Industry Trends Forecast 2026-2036
Dump Truck & Body Market Insights
Aftermarket service revenue is tilting toward fleet management and predictive maintenance contracts as OEMs seek recurring income streams. Caterpillar Inc. leverages its extensive dealer network to control parts availability and service scheduling across mining territories. Volvo Group anchors its position through integrated telematics platforms that connect vehicle diagnostics with customer fleet operations. Komatsu Ltd. differentiates by specializing in autonomous haulage retrofit kits that extend equipment lifecycle value.
A dump truck and body constitutes a motorized or towed vehicle chassis fitted with a hydraulically actuated open-box bed designed for transporting loose bulk materials such as aggregate, ore, or demolition debris, with typical payloads ranging from ten to over four hundred metric tons depending on configuration. The assembly serves primary industrial purposes in earthmoving, mineral extraction, and waste transport where material density and haul distance dictate chassis specification. Articulated dump trucks dominate severe-terrain mining applications where oscillating hitch designs preserve traction across unimproved haul roads. Standard dump trucks maintain stronghold positions in urban construction segments where maneuverability and licensing simplicity outweigh payload maximization. Steel body material retains volume leadership for abrasive ore transport despite aluminum alternatives gaining traction in weight-sensitive highway configurations.
The EPA regulates on-road and non-road engine emissions under Tier 4 Final and emerging Clean Truck standards, compelling manufacturers to invest in alternative fuel platforms or face market exclusion. OSHA and MSHA mandate rollover protection, operator visibility, and braking performance standards that directly influence cab design and body mounting specifications. ISO 3834 welding quality requirements and regional type-approval frameworks further segment market access for body fabricators serving multinational fleet operators. Stakeholders must monitor regulatory divergence between North American and European emissions timelines when allocating powertrain development budgets.
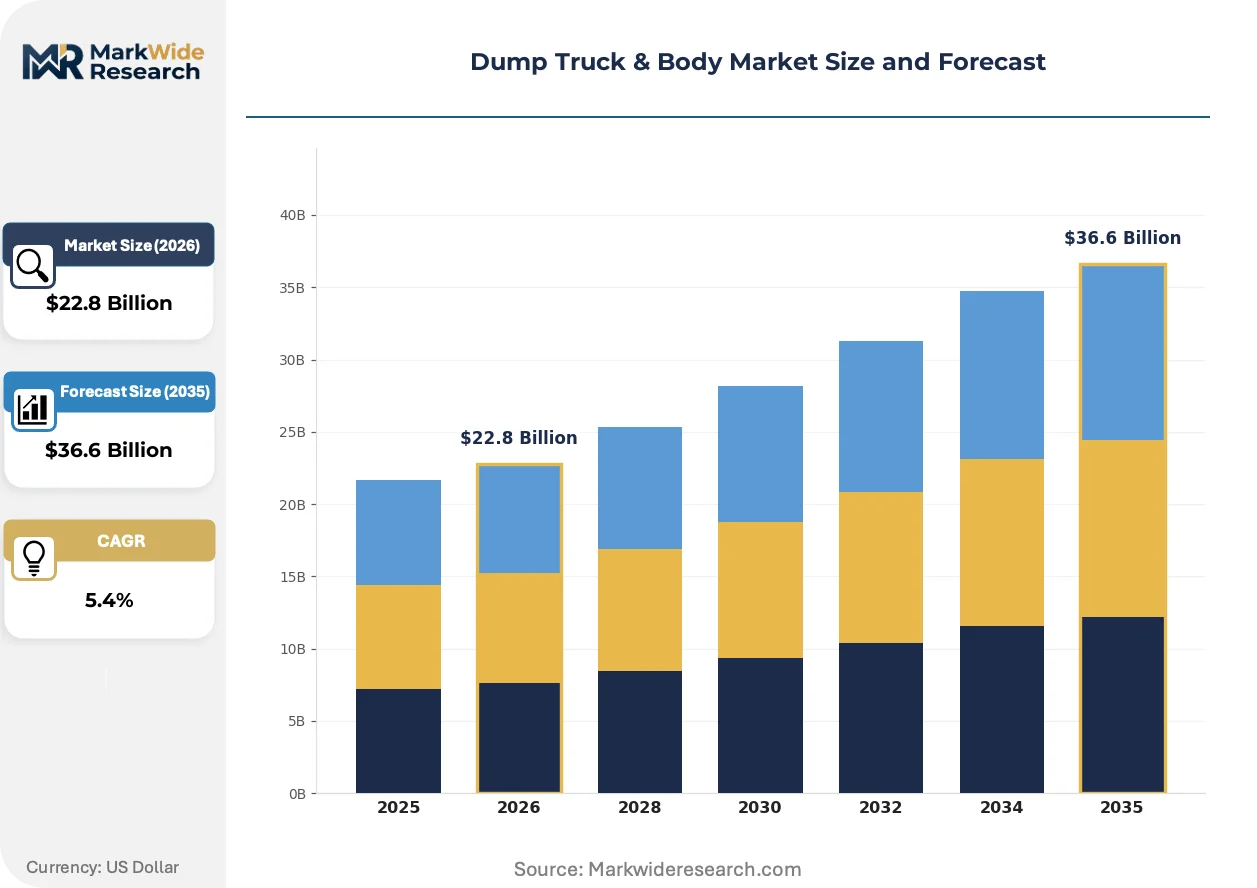
Market Dynamics
The transition from mechanical to electric powertrains is compressing development cycles and forcing chassis-body integration decisions earlier in the design process than traditional build practices allowed.
Growth Catalysts
- EPA Tier 4 Final and Euro VI Phase D:These emissions frameworks are mandating particulate matter and NOx reductions that accelerate fleet turnover toward cleaner configurations across US and European mining corridors.
- Autonomous haulage retrofit demand:Mining operators in Western Australia and northern Chile are retrofitting existing articulated fleets with sensor-integrated body systems to extend asset lifecycles without full replacement.
- Steel price volatility hedging:Body fabricators are securing multi-year ore supply agreements with Brazilian and Australian mills to stabilize input costs for high-wear mining applications.
Market Restraints
- Battery cell supply concentration:Lithium-ion cell production for electric dump truck prototypes remains concentrated in Chinese and South Korean facilities, creating procurement bottlenecks for North American OEM pilot programs.
- Welding certification fragmentation:ISO 3834 Part 2 and Part 3 requirements diverge across Australian, Canadian, and US state-level type-approval frameworks, multiplying compliance costs for multinational body suppliers.
- Aluminum body penetration ceiling:Abrasive ore transport in Pilbara and Carajás mining districts limits aluminum body adoption to sub-20% of severe-duty applications despite weight advantages.
Strategic Opportunities
- Underpenetrated African copper belt:Zambian and Congolese mining expansion lacks established body refurbishment infrastructure, creating openings for mobile service units and regional parts depots.
- Telematics-integrated predictive maintenance:OEMs are bundling hydraulic system monitoring with fleet management software to capture recurring revenue from autonomous-ready articulated units.
- US Inflation Reduction Act commercial vehicle credits:Federal incentives for domestic battery assembly are accelerating electric chassis development partnerships between body fabricators and powertrain specialists.
Industry Challenges
- Autonomous systems integration complexity:Retrofitting legacy articulated trucks with lidar and radar mounting requires structural body modifications that void original manufacturer warranties.
- Specialized welder scarcity:High-strength steel and aluminum alloy fabrication for lightweight highway bodies demands certified technicians that mining-region labor pools rarely supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dump Truck & Body Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Dump Trucks, Articulated Dump Trucks, Transfer Dump Trucks, Semi-Trailer Dump Trucks Application: Construction, Mining, Agriculture, Waste Management Body Material: Steel, Aluminum, Composite, Plastic End User: Contractors, Municipalities, Waste Management Companies, Mining Firms |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Group, Hitachi Construction Machinery, Liebherr Group, BELAZ, SANY Group, XCMG Group, Crysteel Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dump Truck & Body Market Trends and Innovations
Digital integration is penetrating every layer of dump truck operation, from real-time payload monitoring to predictive hydraulic maintenance, compressing the traditional separation between vehicle and fleet management systems.
Sensor-integrated body weighing systems are digitizing load management for mining operators. Articulated haulers in Western Australia's iron ore districts are adopting strain-gauge and pressure-transducer arrays that transmit real-time tonnage data to dispatch centers. This capability is digitizing the historical gap between loading equipment and haul fleet optimization, enabling dynamic route assignments based on actual versus rated capacity.
REACH substance restrictions and EU Green Deal carbon border adjustments are reshaping steel sourcing for European body fabricators. The regulations are compelling mills to document Scope 3 emissions across ore extraction and reduction processes. German and Swedish manufacturers are responding by certifying domestic recycled-content steel for highway dump configurations, creating procurement preference hierarchies that disadvantage non-EU suppliers.
Maintenance contracts are unbundling from equipment purchase agreements as mining operators seek operational expenditure predictability. Tier-1 contractors in Chile's copper districts are replacing time-and-material service arrangements with fixed-cost availability guarantees. Western Australian iron ore producers are driving this shift hardest, pressuring OEMs to assume uptime risk through guaranteed parts availability clauses and on-site technician deployment commitments.
Dump Truck & Body Market Segmentation
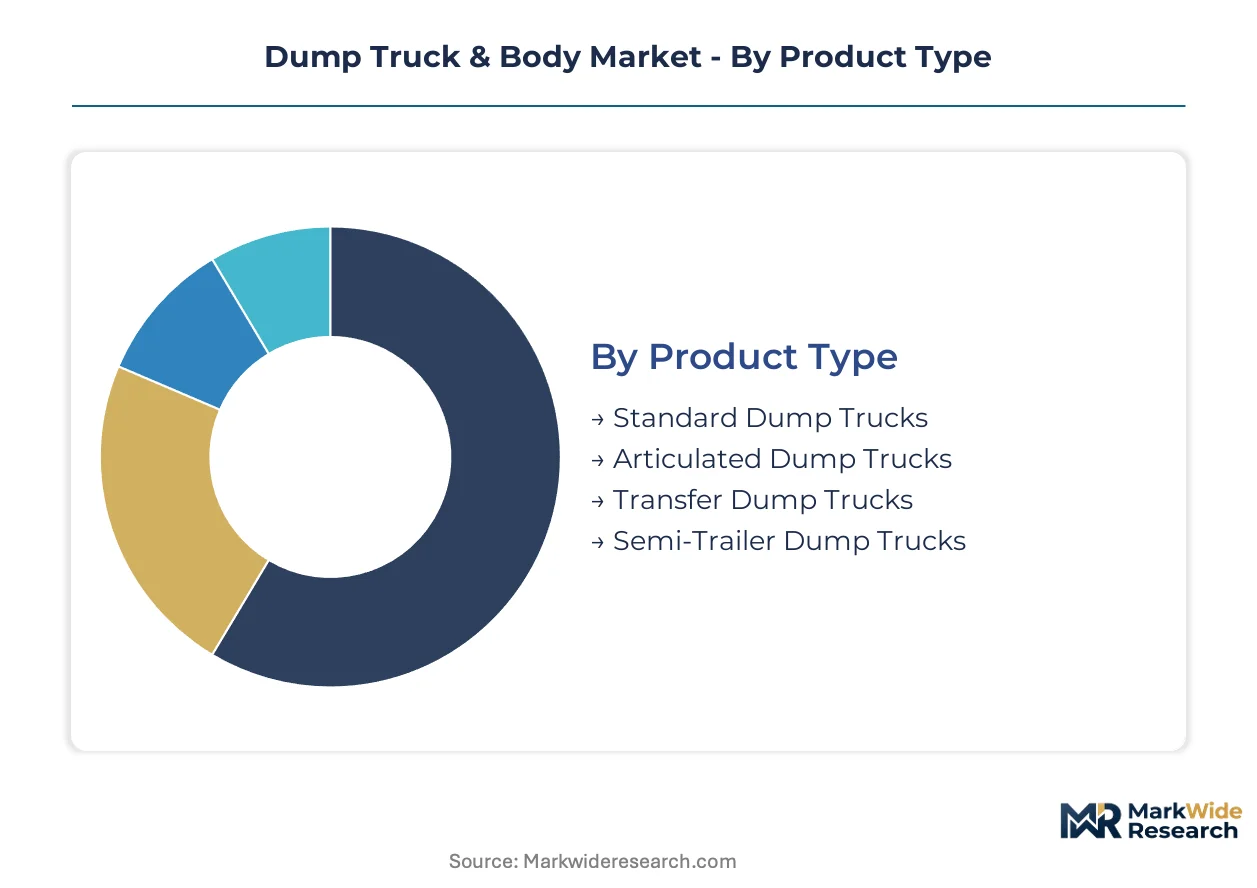
Segmentation in dump truck and body markets reveals how equipment specification, duty cycle intensity, and regulatory exposure create divergent replacement rhythms and margin profiles across customer portfolios.
Product Type:
Articulated dump trucks turn over fastest in mining fleets exposed to 24/7 haul cycles, while highway-configured standards depreciate slower under intermittent municipal use.
- Standard Dump Trucks:Rigid chassis designs with fixed rear axles dominate urban construction corridors where maneuverability outweighs payload maximization. Demand concentrates across North American infrastructure projects where EPA Tier 4 Final compliance has accelerated fleet renewal among municipal contractors facing procurement mandates.
- Articulated Dump Trucks:Oscillating hitch configurations preserve traction across unimproved haul roads in severe-terrain mining. Australian iron ore producers in the Pilbara and Chilean copper operators in the Atacama are expanding autonomous retrofit programs to extend asset lifecycles without full replacement.
- Transfer Dump Trucks:Tandem trailer configurations maximize highway-legal payload volumes for aggregate haulers.
- Semi-Trailer Dump Trucks:Detachable body systems serve long-distance material transport with tractor interchangeability.
Standard dump trucks dominate installed base. Articulated dump trucks are where expansion concentrates.
Application:
Cost tier stratification separates capital-intensive mining deployments from operational-expenditure-driven municipal fleets.
- Construction:Earthmoving and site preparation duties drive demand for mid-size rigid trucks with steel bodies. North American infrastructure corridors are absorbing elevated equipment orders as federal highway funding translates into project mobilization.
- Mining:Mineral extraction commands the highest payload specifications and harshest duty cycles. Western Australian and northern Chilean operators are retrofitting existing fleets with sensor-integrated body systems rather than purchasing new autonomous chassis.
- Agriculture:Seasonal grain and fertilizer transport favors lighter-duty configurations with corrosion-resistant finishes.
- Waste Management:Refuse collection and landfill operations prioritize compaction-resistant body designs with sealed tailgate mechanisms.
Mining commands premium pricing per unit. Construction delivers volume scale across fragmented contractor bases.
Body Material:
Volume concentration in steel reflects mining abrasion tolerance, while weight-sensitive highway segments drive aluminum penetration.
- Steel:High-strength alloy fabrication withstands abrasive ore transport in Pilbara and Carajás mining districts. Brazilian and Australian mills are securing multi-year supply agreements with body fabricators to hedge price volatility for severe-duty applications.
- Aluminum:Lightweight extrusion profiles reduce tare weight for highway aggregate haulers facing axle load regulations. European Green Deal carbon border adjustments are reshaping sourcing decisions as mills document Scope 3 emissions across reduction processes.
- Composite:Fiberglass-reinforced polymer panels serve corrosion-resistant niche applications in chemical and salt transport.
- Plastic:Molded polyethylene liners protect steel substrates in sticky material handling.
Steel retains volume leadership. Aluminum is climbing the fastest as weight regulations tighten.
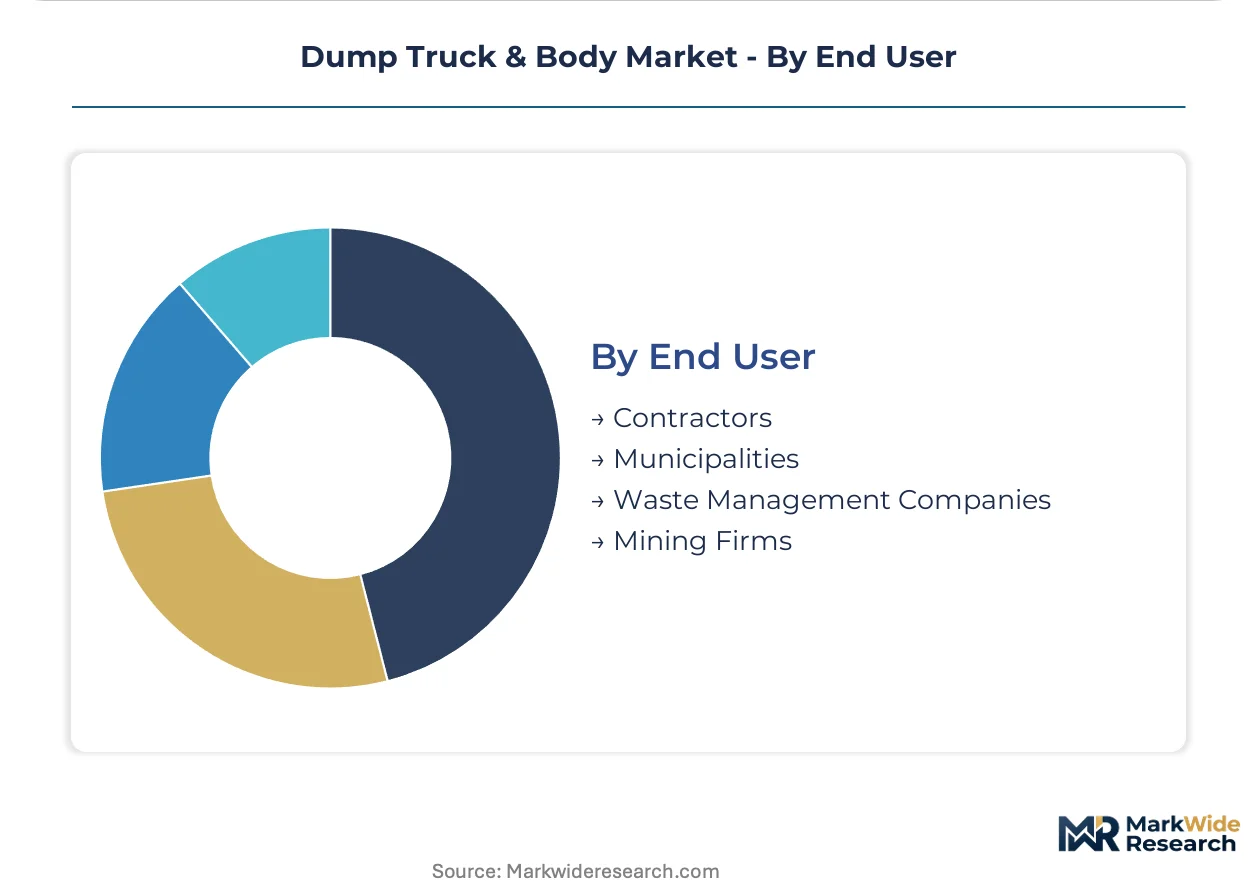
End User:
Customer type determines procurement rhythm, with mining firms executing synchronized fleet renewals against municipalities' staggered replacement schedules.
- Contractors:Project-based equipment utilization drives rental and lease preferences over ownership in volatile construction markets.
- Municipalities:Tax-funded procurement cycles extend replacement intervals beyond commercial norms, creating aftermarket service dependencies.
- Waste Management Companies:Route density optimization favors specialized compaction bodies with telematics integration for fleet visibility.
- Mining Firms:Capital intensity and uptime requirements drive long-term maintenance contracts with guaranteed availability clauses. Tier-1 contractors in Chile's copper districts are replacing time-and-material arrangements with fixed-cost guarantees.
Mining firms concentrate revenue per relationship. Contractors represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal contractors in Germany and Japan exhibit acute price sensitivity to steel body costs, while Australian and Chilean mining operators prioritize uptime guarantees over unit procurement economics.
United States
Infrastructure spending through the Inflation Reduction Act is accelerating fleet turnover among highway contractors. EPA Tier 4 Final enforcement is compelling body fabricators to certify emissions-compliant configurations for interstate commerce. Texas and California aggregate haulers are absorbing elevated equipment orders as federal funding translates into project mobilization.
Australia
Pilbara iron ore producers are retrofitting existing articulated fleets with sensor-integrated body systems rather than purchasing new autonomous chassis. The country's national mining safety regulator mandates rollover protection and operator visibility standards that directly influence cab design specifications. Western Australian operators in the Karratha-Port Hedland corridor are driving fixed-cost maintenance contracts with guaranteed availability clauses.
Chile
Copper extraction in the Atacama Desert commands the highest payload specifications and harshest duty cycles among Latin American mining jurisdictions. The national environmental regulator enforces emissions frameworks that accelerate fleet turnover toward cleaner configurations. Tier-1 contractors in the Antofagasta region are replacing time-and-material service arrangements with fixed-cost availability guarantees.
Germany
REACH substance restrictions and EU Green Deal carbon border adjustments are reshaping steel sourcing decisions for body fabricators. The country's federal motor transport authority enforces axle load regulations that drive aluminum body penetration in highway aggregate transport. Bavarian and North Rhine-Westphalian manufacturers are certifying domestic recycled-content steel to create procurement preference hierarchies.
China
Domestic mining expansion in Inner Mongolia and Shanxi provinces is absorbing elevated orders for severe-duty steel body configurations. The Ministry of Ecology and Environment enforces dual carbon goals that compel powertrain transitions toward electric and hybrid platforms. Xuzhou and Changsha industrial clusters are anchoring integrated chassis-body production for Belt and Road infrastructure exports.
Dump Truck & Body Market Competitive Landscape
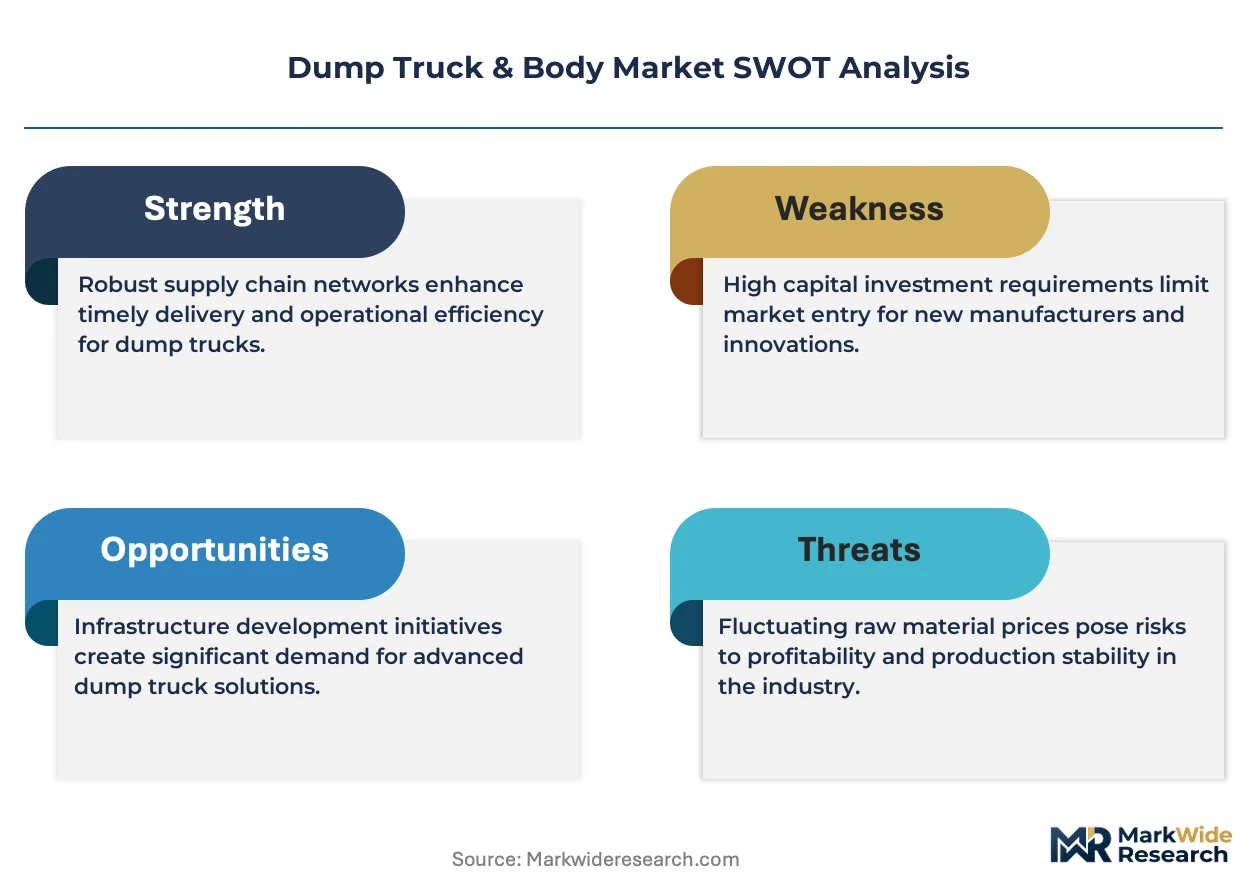
Capability concentration sits with full-line OEMs commanding integrated telematics and autonomous retrofit architectures; scale advantage sits with regional body fabricators securing multi-year steel supply agreements. The vendor base stratifies across three tiers: multinational chassis manufacturers, specialized body fabricators, and emerging electric powertrain integrators. Dominant competitive moves include backward integration into battery assembly partnerships and geographic expansion through mobile service unit deployment.
Within the full-line OEM tier, Caterpillar Inc., Komatsu Ltd., and Volvo Group exemplify divergent strategic positioning. Caterpillar leverages its extensive dealer network to control parts availability across mining territories. Komatsu differentiates by specializing in autonomous haulage retrofit kits that extend equipment lifecycle value. Volvo anchors its position through integrated telematics platforms connecting vehicle diagnostics with customer fleet operations.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Group |
| Hitachi Construction Machinery |
| Liebherr Group |
| BELAZ |
| SANY Group |
| XCMG Group |
| Crysteel Manufacturing Inc. |
| Others |
Pricing and Supply Chain Analysis
Battery cell supply concentration in Chinese and South Korean facilities determines both pricing tier spreads across electric and diesel configurations and supply chain shape for North American OEM pilot programs. Steel price volatility from Brazilian and Australian ore markets feeds directly into body fabrication cost structures, compressing margins for severe-duty mining applications while elevating premium pricing for hedged supply agreements.
Pricing Analysis
Aftermarket service revenue from predictive maintenance contracts and guaranteed availability agreements drives lifetime value more than initial chassis procurement. Three-tier pricing structure across premium autonomous-ready configurations, standard Tier 4 Final compliant units, and economy remanufactured platforms separates mining firms with uptime requirements from municipal contractors with capital constraints. Cost compression in entry-level articulated haulers is intensifying because of oversupply in used equipment markets. Municipal contractors exhibit highest price sensitivity, while Australian iron ore producers prioritize fixed-cost service bundles over unit economics.
Supply Chain Analysis
Contract manufacturing for electric powertrain integration concentrates among Xuzhou and Changsha industrial clusters anchoring integrated chassis-body production. High-strength steel draws from Brazilian and Australian mills, lithium-ion cells rest on South Korean and Chinese cathode supply, and hydraulic systems feed from German and Japanese component specialists. Single-source vulnerability in battery cell procurement creates procurement bottlenecks for North American OEMs developing electric prototypes. Distribution runs through Caterpillar and Komatsu dealer networks controlling parts availability across mining territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where telematics-integrated fleet management systems are displacing transactional equipment sales with recurring revenue architectures. Interoperability between autonomous haulage retrofit kits and legacy chassis is reshaping competitive positioning toward software-defined lifecycle extension.
For Market Incumbents: Harden warranty protection clauses against autonomous retrofit modifications that void original coverage. Deepen backward integration into battery assembly partnerships to secure cell allocation for electric chassis development. Threat substitution from emerging electric powertrain integrators demands captive control over critical powertrain supply.
For New Entrants and Emerging Players: Establish a beachhead in mobile body refurbishment services across the African copper belt where fixed infrastructure is absent. Target Zambian and Congolese mining expansion with regional parts depots and on-site welding certification capabilities. Go-to-market leverage through telematics-integrated predictive maintenance contracts captures recurring revenue without heavy manufacturing capital.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized body fabricators with multi-year steel supply hedges and autonomous retrofit certification capabilities. Long-term viability centers on equipment-as-a-service transition enabling operational expenditure predictability for mining operators. Signal to watch is fixed-cost availability guarantee penetration in Chilean and Australian contracts as inflection indicator toward recurring revenue dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Retrofit Certification | Extends asset lifecycles for Pilbara and Atacama mining fleets without full replacement capex. |
| Battery Supply Partnership | Secures lithium-ion cell allocation from South Korean suppliers for North American electric chassis pilots. |
| Mobile Service Unit Deployment | Captures African copper belt demand lacking established body refurbishment infrastructure. |
| Telematics Platform Integration | Connects Volvo and Komatsu vehicle diagnostics with customer fleet operations for recurring revenue. |
| Recycled-Content Steel Sourcing | Meets EU Green Deal carbon border adjustments for German and Swedish highway body fabricators. |
Research Methodology
Cross-validation between OEM procurement interviews and aftermarket service data anchors the qualitative findings in operational reality. Primary sources include maintenance directors at Australian iron ore operations, fleet managers at Chilean copper contractors, body fabrication procurement leads, and hydraulic systems engineers. Secondary validation draws from EPA Tier 4 Final enforcement records, ISO 3834 welding certification databases, SEC filings from Caterpillar and Komatsu, and mining equipment trade flow data. Bottom-up unit economics triangulate against top-down market sizing across the projection horizon.
Calibration against historical replacement cycles in mining and construction fleets informs the analytical framework. Segmentation dimensions modeled include product type articulation, body material specification, end-user procurement rhythm, and regional regulatory cluster. CAGRs derive from equipment stock turnover analysis and fleet renewal program announcements. Industry-specific inputs incorporate autonomous haulage adoption curves and electric powertrain development partnerships.
Stress conditions across steel price volatility, battery cell supply disruption, and emissions timeline divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mining capital expenditure cycles and infrastructure funding trajectories. Quarterly review of fleet renewal program announcements and welding certification regulatory harmonization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Bucket Trucks Market