
 China Full Truckload Road Freight Transport Market | 2026-2036
China Full Truckload Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China Full Truckload Road Freight Transport Market Outlook
GB 1589-2016 vehicle dimension and weight limits is rotating the competitive landscape toward operators with modernized fleets. Deppon Logistics Co., Ltd. leverages its heavy-asset network to control lane density on core trunk routes. SF Express anchors premium express freight through proprietary air-ground coordination. JD Logistics sustains captive demand via backward integration into its parent company's fulfillment infrastructure.
Full truckload road freight transport denotes the movement of cargo from a single shipper occupying an entire vehicle's capacity, typically involving shipments exceeding three tons or fifteen cubic meters with direct point-to-point routing and minimal handling. Flatbed trucks dominate construction materials and machinery haulage, while refrigerated trucks command premium pricing in temperature-controlled food and pharmaceutical distribution. E-commerce clients represent the fastest-growing client type segment as direct-to-consumer fulfillment networks displace traditional wholesale consolidation patterns.
China's Ministry of Transport enforces commercial vehicle operating permits through provincial road transport administrations, while SAMR monitors platform economy pricing under anti-monopoly guidelines. MEE emissions standards and MIIT new energy vehicle mandates are accelerating diesel fleet replacement timelines. Stakeholders must weigh asset ownership against platform-mediated capacity access as regulatory compliance costs diverge across fleet vintages.
Market Dynamics
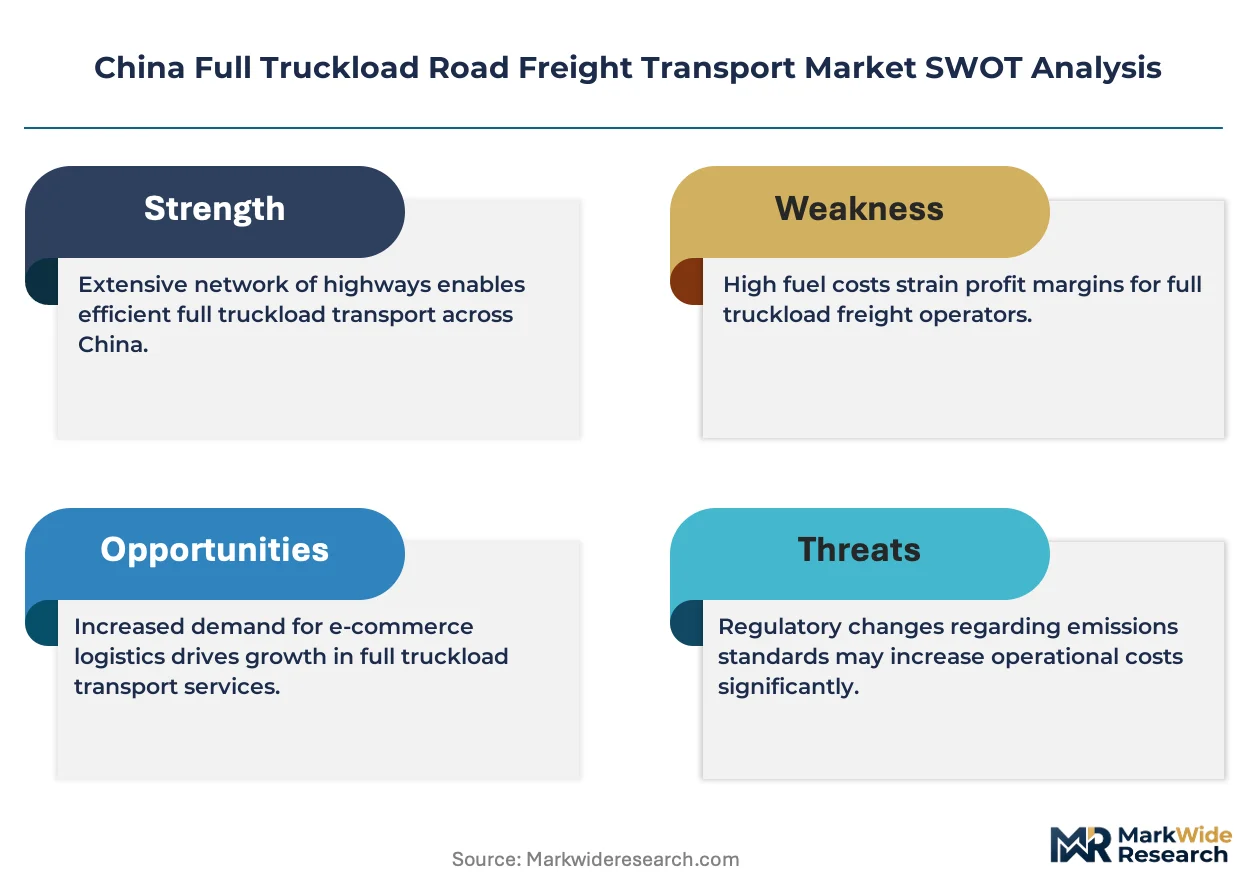
China's full truckload road freight transport market is undergoing structural compression as MIIT's new energy vehicle mandates and MEE emissions standards force diesel fleet obsolescence, while e-commerce fulfillment networks bypass traditional wholesale consolidation layers entirely.
Growth Catalysts
- E-commerce platform procurement:Direct-to-consumer fulfillment networks are capturing dedicated freight capacity previously routed through wholesale distributors, creating sustained demand for point-to-point trunk haulage.
- GB standards compliance:GB 1589-2016 vehicle dimension and weight limits are accelerating fleet modernization cycles, advantaging operators with capital reserves for compliant asset acquisition.
- Yangtze River Delta manufacturing density:The Shanghai-Jiangsu-Zhejiang corridor generates concentrated freight volumes that support high-frequency lane operations and backhaul optimization.
Market Restraints
- Diesel fuel price volatility:Input cost swings compress margins for non-NEV fleet operators unable to pass through surcharges to contract shippers.
- Driver supply contraction:Aging demographics and vocational preference shifts among younger workers constrain qualified operator availability across long-haul routes.
- Highway toll structure rigidity:Provincial toll administration policies limit route flexibility and erode competitiveness against rail intermodal alternatives on select corridors.
Strategic Opportunities
- Western China corridor development:Chongqing-Chengdu manufacturing clusters and Belt and Road Initiative gateway ports offer underpenetrated origin-destination pairs with rising freight generation.
- Refrigerated pharmaceutical distribution:Cold chain infrastructure gaps in tier-two and tier-three cities create white space for temperature-controlled full truckload specialization.
- Digital freight platform integration:SAMR-supervised platform economy frameworks enable asset-light capacity aggregation models that reduce empty-mile ratios.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to interface with national vehicle monitoring platforms mandated by transport authorities.
- NEV charging infrastructure gaps:Battery electric heavy truck deployment faces range anxiety and charging station scarcity on interprovincial trunk routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Full Truckload Road Freight Transport Market |
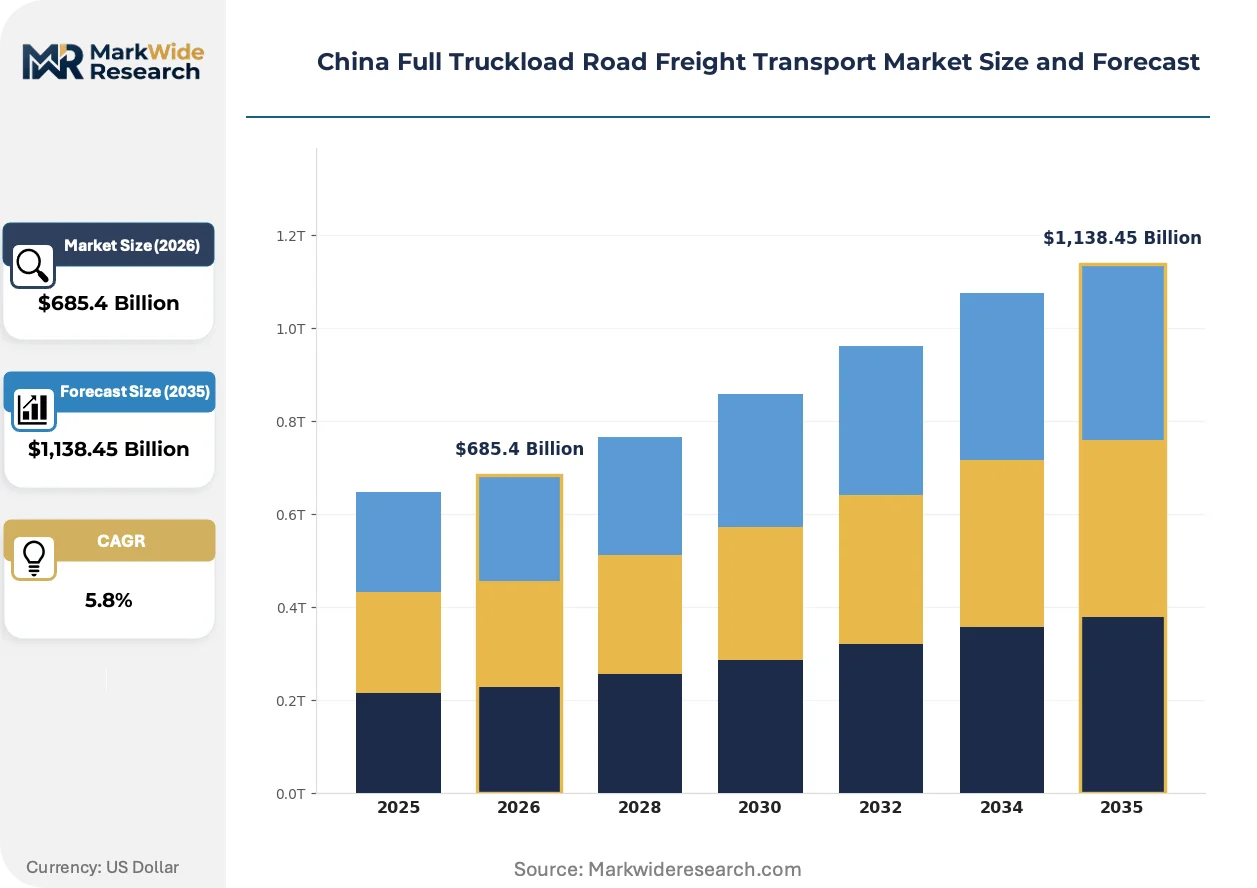
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,138.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Dump Trucks, Box Trucks, Flatbed Trucks, Refrigerated Trucks Service Type: Long Haul, Short Haul, Intermodal, Dedicated Freight Client Type: Manufacturers, Wholesalers, Retailers, E-Commerce Load Capacity: Lightweight, Medium, Heavyweight, Oversized |
| Companies Covered | Deppon Logistics Co., Ltd., SF Express, SINOTRUK, JD Logistics, SAIC Anji Logistics, Shanghai YTO Express (Logistics) Co., Ltd., STO Express Co., Ltd., ZTO Express (Cayman) Inc., CMST Development Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Full Truckload Road Freight Transport Market Strategic Shifts
Telematics and autonomous driving assistance systems are fragmenting traditional dispatch models, while regulatory pressure on emissions intensifies technology substitution timelines across fleet vintages.
Autonomous trucking technology is fragmenting the driver-dependent operating model through supervised platooning and highway autopilot functions. E-commerce fulfillment centers and express parcel networks are piloting these systems on designated trunk routes between sorting hubs. The technology is fragmenting labor cost structures and enabling 24-hour continuous operations previously constrained by hours-of-service regulations.
MIIT's new energy commercial vehicle mandate and MEE's China VI emissions standards are compressing diesel engine production timelines. Manufacturers must redirect R&D expenditure toward battery electric and hydrogen fuel cell powertrains while managing residual value collapse in existing diesel assets. Heavy-asset operators with Yangtze River Delta concentration face accelerated replacement schedules due to municipal low-emission zone expansions in Shanghai and surrounding prefectures.
Shipper procurement preferences are consolidating around dedicated contract capacity rather than spot market brokerage. Automotive and electronics manufacturers with just-in-time production requirements are displacing fragmented broker relationships with direct carrier agreements. This pattern concentrates volume with fleet operators capable of guaranteed capacity allocation, most visible in Jiangsu province's automotive component supply corridors.
China Full Truckload Road Freight Transport Market Segmentation
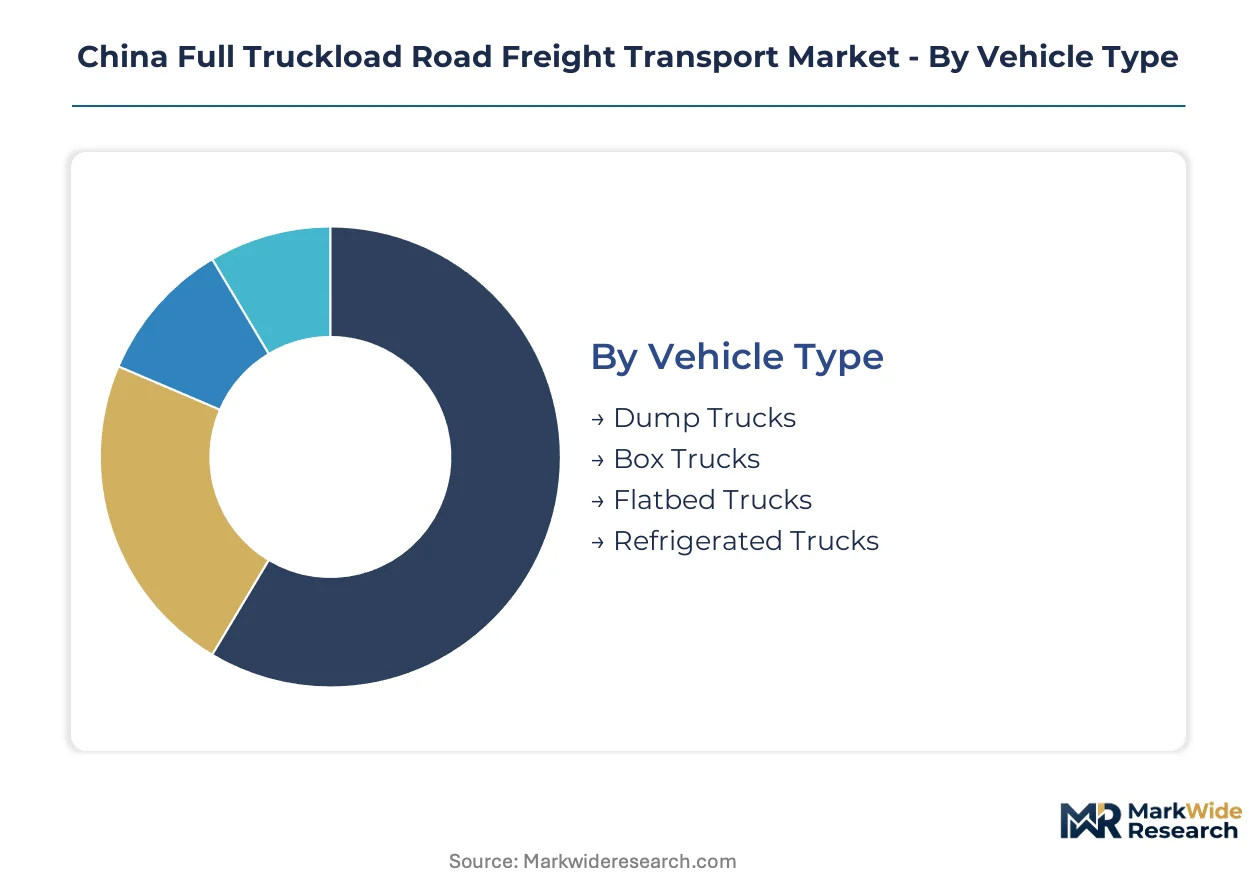
Segmentation in China's full truckload market reveals how regulatory pressure and shipper procurement preferences are redistributing value across asset configurations. Fleet operators must align vehicle specifications and service models with corridor-specific demand patterns to capture margin in an increasingly compliance-driven environment.
Vehicle Type:
Margin pools concentrate in specialized temperature-controlled assets where premium pricing offsets higher capital intensity, while standardized dry freight vehicles face commoditization pressure from platform-mediated capacity aggregation.
- Refrigerated Trucks:Insulated cargo compartments with integrated refrigeration units maintain precise temperature bands for pharmaceutical and fresh food distribution. Demand concentrates in tier-two and tier-three city cold chain gaps across Jiangsu and Zhejiang provinces, where MEE emissions standards are accelerating diesel fleet replacement timelines. The segment commands rate premiums of 40-60% above dry freight equivalents.
- Flatbed Trucks:Open-deck configurations accommodate oversized machinery and construction materials with flexible loading geometries. Shanghai port hinterland operations and Yangtze River Delta manufacturing clusters generate concentrated volumes for steel, automotive components, and industrial equipment haulage. GB 1589-2016 dimension compliance requirements favor newer fleet vintages with optimized axle configurations.
- Box Trucks:Enclosed van bodies protect general cargo from weather and theft on multi-drop distribution routes.
- Dump Trucks:Hydraulic lift mechanisms enable rapid unloading of aggregates and construction debris at project sites.
The dominant share belongs to Box Trucks, while Refrigerated Trucks is closing the gap fastest.
Service Type:
Contract duration and asset dedication levels determine pricing power, with guaranteed capacity arrangements capturing superior margins compared to spot-market exposure.
- Dedicated Freight:Exclusive vehicle allocation to single shippers on fixed schedules eliminates co-loading complexity and minimizes handling. E-commerce fulfillment networks in the Yangtze River Delta are capturing this capacity directly, bypassing traditional wholesale consolidation layers entirely. The model enables 24-hour continuous operations through supervised platooning on designated trunk routes.
- Long Haul:Interprovincial movements exceeding 500 kilometers connect manufacturing origins with consumption markets or gateway ports. Chongqing-Chengdu manufacturing clusters and Belt and Road Initiative corridors offer underpenetrated origin-destination pairs with rising freight generation. Driver supply constraints and toll structure rigidity compress margins on non-dedicated lanes.
- Short Haul:Intra-metropolitan and regional movements within 200-kilometer radii feed consolidation hubs and last-mile distribution nodes.
- Intermodal:Coordinated rail-truck movements leverage cost advantages on select corridors where highway tolls erode pure road competitiveness.
Dedicated Freight holds the largest revenue pool, though Long Haul is expanding most quickly as manufacturing gravity shifts westward.
Client Type:
Procurement sophistication and volume predictability separate price-takers from price-makers in shipper-carrier negotiations.
- E-Commerce:Direct-to-consumer fulfillment networks displace traditional wholesale consolidation patterns with point-to-point trunk haulage requirements. JD Logistics and similar platforms sustain captive demand through backward integration into parent company fulfillment infrastructure. The segment demands guaranteed capacity allocation and real-time visibility compliance.
- Manufacturers:Automotive and electronics producers with just-in-time production requirements displace fragmented broker relationships with direct carrier agreements. Jiangsu province's automotive component supply corridors exhibit this concentration pattern most visibly. MIIT new energy vehicle mandates are accelerating production schedule volatility and freight demand fluctuations.
- Wholesalers:Traditional distribution intermediaries face volume erosion as upstream suppliers and downstream retailers build direct logistics relationships.
- Retailers:Store replenishment networks prioritize reliability over speed for non-perishable merchandise flows.
Manufacturers retain the deepest contract penetration, yet E-Commerce is gaining share fastest through platform-controlled procurement.
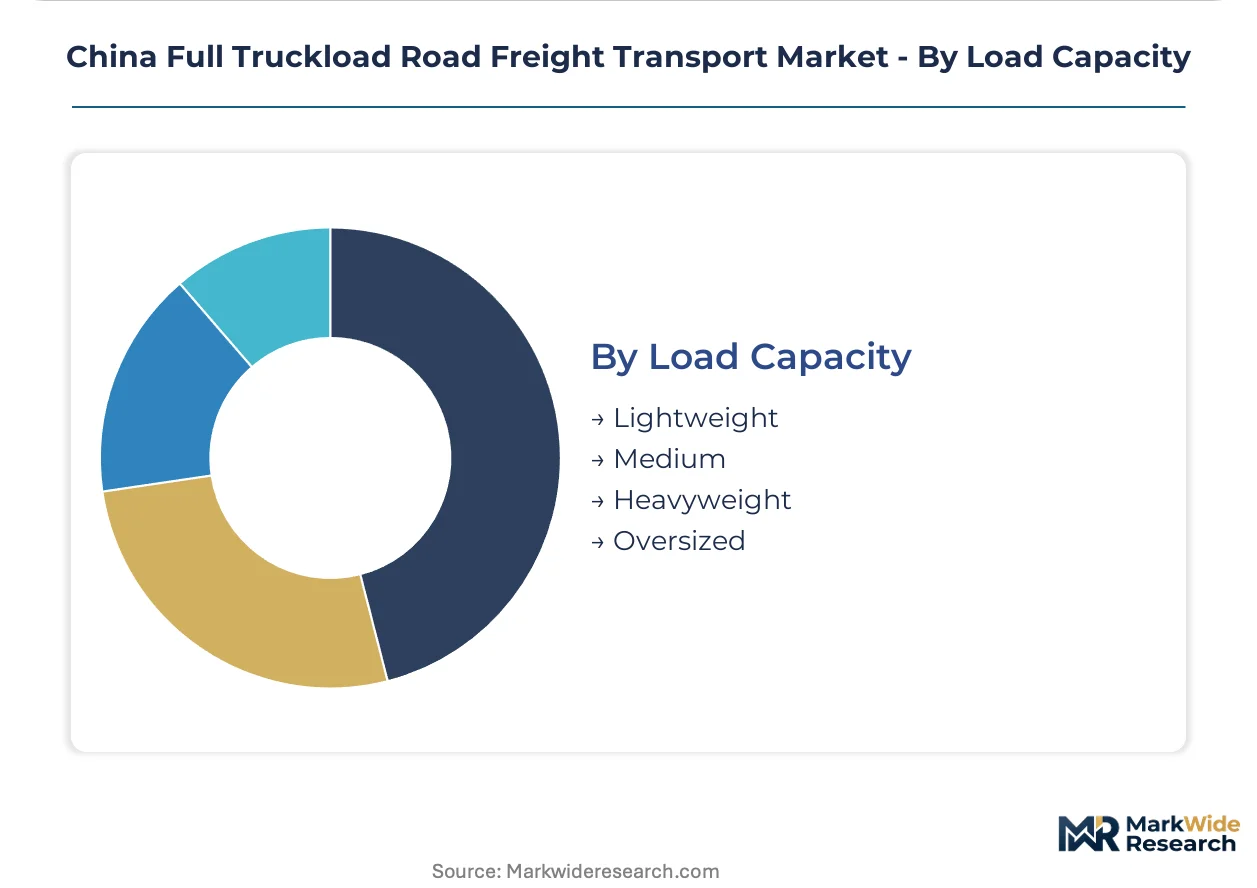
Load Capacity:
Asset utilization efficiency and lane density economics favor specific weight classes in China's corridor-specific freight geography.
- Heavyweight:Vehicles rated above 14 tons gross vehicle weight dominate trunk route economics with maximum payload efficiency. GB 1589-2016 weight limits have rotated competitive advantage toward operators with modernized fleets compliant with axle load regulations. The segment anchors Deppon Logistics Co., Ltd.'s heavy-asset network control on core Yangtze River Delta lanes.
- Medium:6-14 ton configurations balance maneuverability in urban delivery zones with highway route eligibility. Municipal low-emission zone expansions in Shanghai and surrounding prefectures are accelerating NEV replacement schedules in this category.
- Lightweight:Sub-6 ton vehicles serve urban last-mile and short-haul feeder operations with restricted highway access.
- Oversized:Special permit configurations accommodate indivisible loads exceeding standard dimension and weight limits for industrial project cargo.
Heavyweight vehicles command the dominant fleet share, while Medium capacity is climbing the fastest as urban access restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipper procurement concentration clusters in manufacturing-intensive provinces where just-in-time production requirements and e-commerce fulfillment networks command dedicated capacity allocation.
Yangtze River Delta
Automotive component supply corridors in Jiangsu province and Shanghai port hinterland operations generate the densest freight volumes nationally. GB 1589-2016 vehicle dimension compliance mandates rotate competitive advantage toward operators with modernized heavy-asset fleets. The Shanghai-Jiangsu-Zhejiang corridor supports high-frequency lane operations with superior backhaul optimization economics.
Pearl River Delta
Electronics manufacturing clusters in Guangdong province demand guaranteed capacity allocation for export-oriented production schedules. Municipal low-emission zone expansions in Shenzhen and Guangzhou accelerate NEV replacement timelines for medium-duty urban access vehicles. Dongguan and Foshan industrial zones exhibit concentrated demand for flatbed configurations serving machinery and construction materials haulage.
Beijing-Tianjin-Hebei
Capital region logistics nodes prioritize emissions-compliant fleet deployment under MEE China VI standards enforcement. SAMR platform economy supervision shapes digital freight aggregation models serving the Tianjin port gateway. Hebei province steel and heavy industry corridors generate specialized demand for heavyweight configurations on interprovincial trunk routes.
Sichuan-Chongqing
Western manufacturing gravity centers on Chongqing-Chengdu automotive and electronics production bases with rising freight generation rates. Belt and Road Initiative gateway ports create underpenetrated origin-destination pairs for long-haul dedicated services. Provincial road transport administrations enforce commercial vehicle operating permits with accelerating diesel fleet obsolescence timelines.
Shandong Peninsula
Qingdao and Yantai port hinterlands concentrate containerized cargo conversion to full truckload road distribution. Cold chain infrastructure gaps in Jinan and surrounding prefectures create white space for temperature-controlled pharmaceutical specialization. MIIT new energy commercial vehicle mandates compress residual value horizons for existing diesel assets serving regional manufacturing clients.
China Full Truckload Road Freight Transport Market Competitive Environment
Player mix skews toward heavy-asset network operators with Yangtze River Delta lane density control and platform-integrated capacity aggregators serving fragmented spot demand. Three strategic archetypes dominate: dedicated contract carriers with captive shipper relationships, express freight operators with proprietary air-ground coordination, and backward-integrated logistics arms of major e-commerce platforms. Competitive moves concentrate on fleet modernization cycles compliant with tightening GB standards and strategic partnerships securing guaranteed capacity allocation from automotive and electronics manufacturers.
Within the heavy-asset carrier tier, Deppon Logistics Co., Ltd. and SAIC Anji Logistics exemplify operators controlling core trunk route density through owned fleet deployment. Among express-integrated operators, SF Express occupies a position anchoring premium freight services through coordinated modal networks. JD Logistics represents the backward-integrated archetype, sustaining captive demand via in-house production of fulfillment infrastructure tied to parent company e-commerce operations. SINOTRUK and CMST Development Co., Ltd. sit within the equipment and infrastructure supply layer supporting fleet operator asset acquisition strategies.
| Leading Market Players |
|---|
| Deppon Logistics Co., Ltd. |
| SF Express |
| SINOTRUK |
| JD Logistics |
| SAIC Anji Logistics |
| Shanghai YTO Express (Logistics) Co., Ltd. |
| STO Express Co., Ltd. |
| ZTO Express (Cayman) Inc. |
| CMST Development Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
GB 1589-2016 vehicle dimension and weight limits simultaneously gate fleet operator qualification and stratify rate premiums across compliant and non-compliant asset vintages. Shippers with just-in-time production mandates pay differential rates for guaranteed capacity from modernized fleets, while diesel-era operators absorb margin compression from fuel surcharge volatility.
Pricing Analysis
Cost-plus contracts with diesel fuel indexation dominate long-haul dedicated freight arrangements, transferring input volatility risk to automotive and electronics manufacturers with JIT requirements. Price differentiation rests on GB standards compliance certification and real-time telematics visibility integration, with e-commerce platforms exhibiting lowest price sensitivity due to captive fulfillment network requirements. Cost compression in spot-market brokerage tiers is intensifying because platform-mediated capacity aggregation erodes traditional broker margins. Refrigerated pharmaceutical distributors face least price sensitivity given cold chain infrastructure scarcity in tier-two and tier-three cities.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on Asia-Europe trade lanes feed into chassis and refrigeration unit procurement timelines for fleet operators. Vehicle manufacturing concentrates in China, Germany, and Japan, while battery electric powertrain components draw from South Korean and Japanese suppliers. Supply chain risk centers on single-source vulnerability for hydrogen fuel cell stack technology. Distribution runs through provincial road transport administration permit systems that fragment national network coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modernized fleet assets compliant with tightening MEE emissions standards are becoming scarce just as e-commerce fulfillment networks demand guaranteed capacity allocation, creating a structural capability gap that rewards early movers in NEV transition.
For Market Incumbents: Consolidate lane density control on Yangtze River Delta trunk routes through accelerated diesel-to-NEV fleet replacement ahead of municipal low-emission zone expansions. Secure backward integration into charging infrastructure partnerships to deflect range anxiety constraints on interprovincial corridors. Threat substitution from autonomous trucking pilot programs demands telematics retrofit investment to maintain shipper eligibility. For New Entrants and Emerging Players: Lead with refrigerated pharmaceutical distribution specialization targeting tier-two and tier-three city cold chain gaps across Jiangsu and Zhejiang provinces. Capture white-space volume from automotive component supply corridors where incumbent broker relationships are fragmenting. Go-to-market angle should emphasize SAMR-compliant platform integration for real-time capacity visibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heavy-asset fleet operators due to compressed NEV replacement timelines under MIIT mandates. Long-term viability favors operators with Yangtze River Delta corridor concentration and direct shipper contract penetration. Acquisition target archetype: mid-scale carriers with GB 1589-2016 compliant fleets and automotive manufacturing client relationships. Signal to watch: municipal low-emission zone expansion announcements in Shanghai satellite prefectures.| Strategic Initiative | Industry Significance |
|---|---|
| NEV Fleet Transition Acceleration | MIIT mandates compress diesel asset residual values, advantaging early electrification adopters in permit-constrained corridors. |
| Telematics Platform Integration | SAMR-supervised digital freight frameworks reduce empty-mile ratios through real-time capacity matching algorithms. |
| Refrigerated Asset Specialization | Cold chain infrastructure gaps in western provinces command 40-60% rate premiums over dry freight equivalents. |
| Charging Infrastructure Partnership | Interprovincial trunk route coverage mitigates battery electric heavy truck range anxiety for long-haul dedicated services. |
| Direct Shipper Contract Consolidation | Automotive and electronics manufacturers displace fragmented broker relationships with guaranteed capacity arrangements. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations directors, shipper procurement managers, provincial road transport administration officials, and digital freight platform engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of MIIT production disclosures, MEE emissions compliance databases, SAMR platform economy supervision filings, and customs vehicle import records. Bottom-up volume estimates from lane-specific freight generation rates were triangulated against top-down market sizing from carrier revenue disclosures.
Variance decomposition across vehicle type, service model, client category, and regional corridor dimensions structured the analytical framework. Segmentation modeling incorporated NEV penetration trajectories, GB standards compliance vintages, and municipal low-emission zone expansion schedules throughout the projection horizon. CAGRs were derived from corridor-specific freight volume elasticities against manufacturing output indices and e-commerce fulfillment network expansion rates.
Forecasts assume regulatory continuity in MIIT new energy vehicle mandates and MEE emissions enforcement regimes; material policy shifts would require re-modeling. Model boundaries exclude potential autonomous trucking regulatory frameworks and hydrogen fuel cell infrastructure subsidy programs not yet codified. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
US Vacuum Truck Market