
 Garbage Truck Bodies Market | 2026-2036
Garbage Truck Bodies Market Size, Share, and Industry Trends Forecast 2026-2036
Garbage Truck Bodies Market Intelligence
A shift from single-source municipal contracts toward multi-source procurement frameworks is realigning competitive dynamics across the garbage truck bodies sector. Heil Environmental leverages its automated arm technology leadership to sustain premium positioning in front-loader configurations. McNeilus Truck and Manufacturing anchors its presence through backward integration into refuse body fabrication, controlling cost structures across the Midwest manufacturing corridor. Dennis Eagle competes aggressively in European markets with low-entry-height designs that meet stricter urban emissions zones.
Garbage truck bodies are specialized vehicular enclosures engineered from high-tensile steel or aluminum alloys, typically rated for 20-32 cubic yard capacities, designed to receive, compact, and transport municipal or commercial solid waste. Their primary purpose is to maximize payload density while minimizing collection cycle times and operator exposure to hazards. Rear loader configurations retain the largest installed base among municipal fleets, though side loader demand is accelerating fastest as labor shortages intensify automation requirements. Carbon fiber and composite material segments command the highest margin pools despite smaller volumes, driven by weight-reduction mandates and extended corrosion-resistance specifications.
EPA greenhouse gas standards for heavy-duty vehicles and OSHA ergonomic requirements directly shape body design specifications and manufacturer compliance costs in the United States. EU F-Gas Regulation and CE marking requirements constrain refrigerant choices and hydraulic system certifications for bodies sold into European member states. Stakeholders must monitor evolving battery-electric chassis compatibility standards, as powertrain electrification will force fundamental redesigns of hydraulic compaction systems and weight distribution architectures.
Market Dynamics
Fleet electrification timelines are compressing design cycles for garbage truck bodies as municipal buyers demand chassis-agnostic compaction systems compatible with battery-electric and hydrogen fuel cell platforms.
Growth Catalysts
- EPA greenhouse gas standards:Heavy-duty vehicle emissions rules in the United States are forcing municipal fleet managers to retire diesel chassis ahead of schedule, triggering replacement demand for lightweight aluminum bodies that preserve electric range.
- Automated side-loader configurations:Labor shortages across North American sanitation departments are accelerating deployment of single-operator collection systems that reduce crew requirements from three workers to one.
- EU Green Deal decarbonization mandates:European municipal procurement rules now weight lifecycle carbon intensity in bid scoring, favoring composite-material bodies with corrosion resistance extending service intervals.
Market Restraints
- High-tensile steel price volatility:Raw material input costs for conventional body fabrication swing with scrap metal and energy markets, compressing margins for mid-tier fabricators without captive steel supply.
- Hydraulic system supplier concentration:Specialized piston and valve manufacturing for compaction mechanisms clusters in German and Japanese industrial corridors, creating single-source vulnerability for North American assemblers.
- Battery-electric chassis payload penalties:Current cell chemistry energy density forces trade-offs between refuse capacity and range, limiting body size specifications for routes exceeding 120 miles daily.
Strategic Opportunities
- India urban sanitation expansion:Smart Cities Mission funding is creating first-time mechanized waste collection demand in tier-2 municipalities previously served by manual haulage.
- Carbon fiber composite adoption:Material convergence between aerospace manufacturing scrap streams and truck body fabrication is opening cost-competitive lightweighting pathways for premium fleet segments.
- Right-to-repair regulatory momentum:Emerging state-level legislation in the United States mandating diagnostic access and spare part availability is enabling independent service network expansion for aftermarket body refurbishment.
Industry Challenges
- Electric-hydraulic system integration:Conventional power take-off designs assume internal combustion engine torque curves, requiring complete re-engineering of pump sizing and control logic for electric motor characteristics.
- Welding technician scarcity:Aluminum alloy body fabrication demands specialized gas metal arc welding certification that outpaces vocational training pipeline output in Midwest manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garbage Truck Bodies Market |
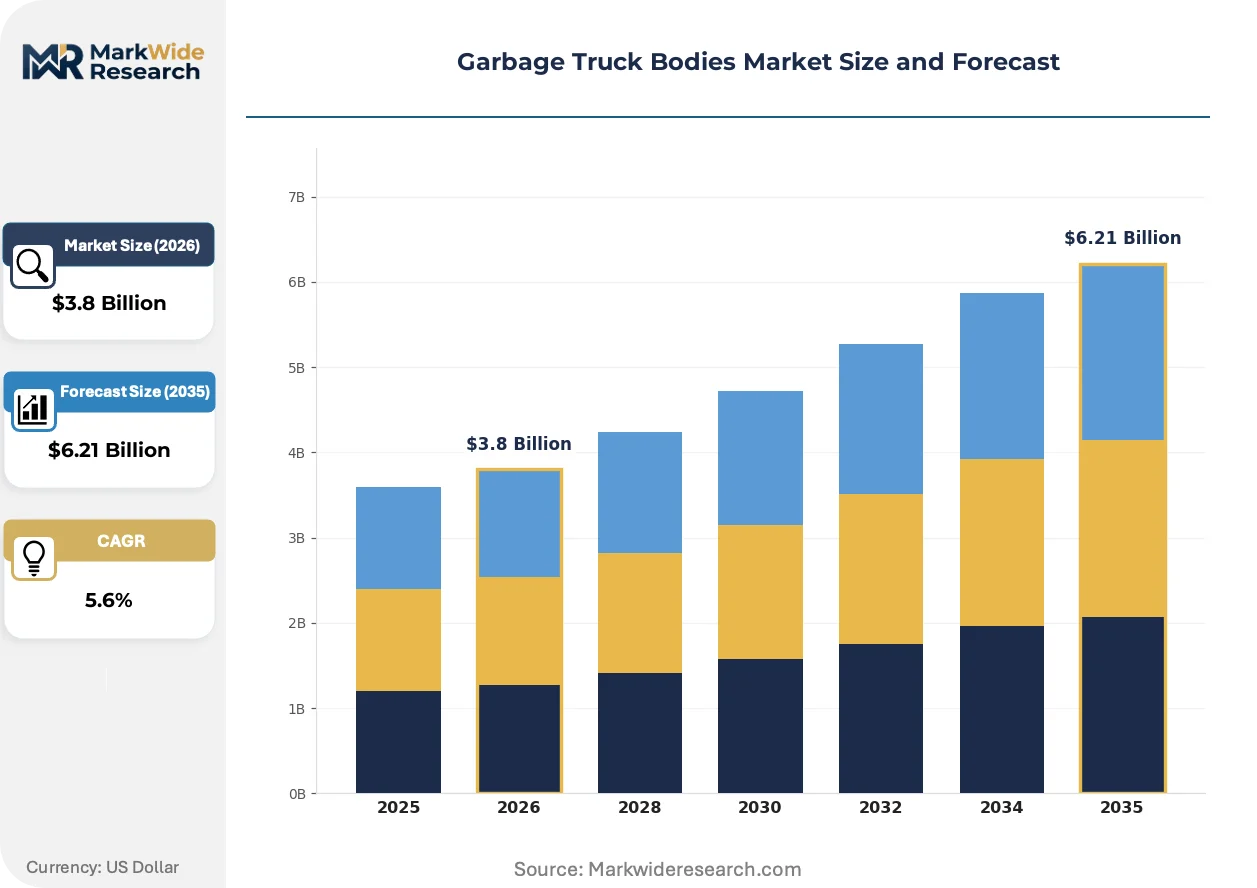
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Body Type: Rear Loader, Front Loader, Side Loader, Roll-Off, Compactor Material: Steel, Aluminum, Carbon Fiber, Fiberglass, Composite Application: Municipal Waste Collection, Commercial Waste Management, Industrial Waste Handling, Construction Debris Removal End User: Public Sanitation Departments, Waste Disposal Contractors, Recycling Facilities, Landfill Operators |
| Companies Covered | Labrie Environmental Group, Amrep, Heil Environmental, Oshkosh Corporation, EZ Pack, New Way Trucks, Dennis Eagle, Chengli Special Automobile, McNeilus Truck and Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garbage Truck Bodies Market Strategic Shifts & Innovations
Digitalization of fleet management is merging with mechanical body design as telematics-enabled compaction monitoring and predictive maintenance reshape how municipalities spec and operate refuse collection assets.
Smart compaction control systems using load-cell weight sensors and GPS-mapped route optimization are integrating with municipal enterprise software platforms. Sanitation departments in California and Texas are deploying these configurations fastest, using real-time fullness data to eliminate unnecessary truck rolls. The technology is integrating dynamic routing algorithms that compress fuel consumption and labor hours per ton collected.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerant options for bodies equipped with climate-controlled compartments. Manufacturers serving German and French markets are retrofitting specifications to accept natural refrigerants and CO2-based systems. European urban emissions zones in London, Paris, and Berlin are tightening enforcement, pushing fleet operators toward zero-emission chassis that demand redesigned hydraulic architectures.
Municipal procurement officers are consolidating vendor relationships through multi-year fleet replacement contracts that bundle body fabrication, chassis supply, and full-maintenance leasing. This pattern displaces transactional spot purchasing historically fragmented across separate body builders and truck dealers. The shift is most visible in United States metropolitan regions where public-sector procurement centralization is reducing supplier count per fleet from eight to three.
Garbage Truck Bodies Market Segmentation
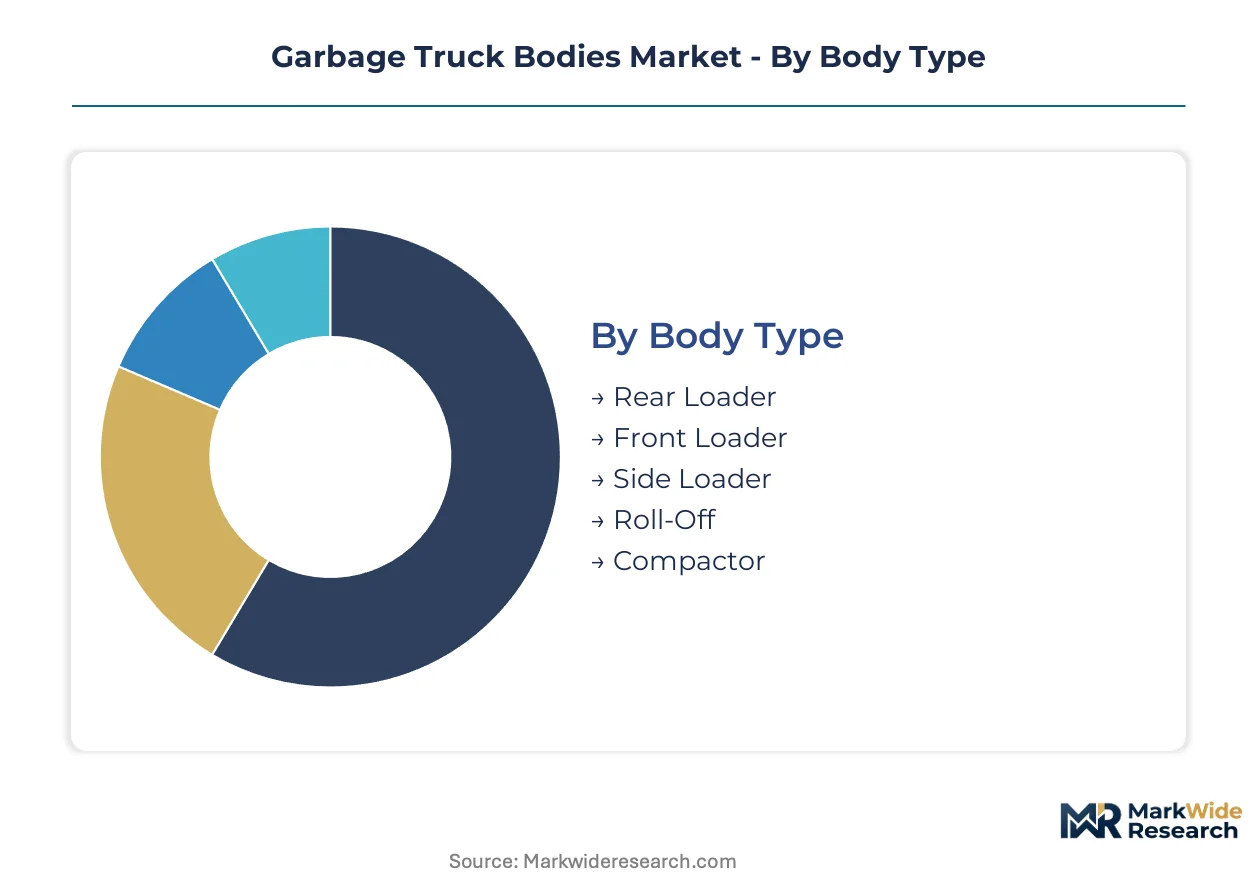
Garbage truck body specifications diverge sharply based on route density, payload requirements, and chassis compatibility constraints. Material selection and loader configuration determine total cost of ownership across fleet replacement cycles.
Body Type:
Standalone configurations dominate municipal procurement, while embedded compaction systems integrate with specialized chassis platforms.
- Rear Loader:Traditional tailgate compaction with manual or semi-automated bin positioning. Demand concentrates in legacy municipal fleets across the United States where route density justifies three-person crew deployment despite labor cost pressures.
- Side Loader:Curbside arm automation enables single-operator collection from standardized bins. European urban emissions zones and North American labor shortages are accelerating specification for this configuration.
- Front Loader:Overhead arm systems service commercial dumpsters with 6-8 cubic yard capacity.
- Roll-Off:Hook-lift or cable-hoist platforms for containerized industrial waste.
- Compactor:Stationary or self-contained units for high-volume transfer stations.
Rear loader configurations retain the largest installed base; side loader demand is climbing the fastest.
Material:
Cost tiers separate commodity fabrication from premium lightweighting investments.
- Steel:High-tensile alloy construction rated for 20-32 cubic yard payloads with abrasion-resistant floor plating. Price volatility in scrap metal and energy markets compresses margins for fabricators without captive supply.
- Aluminum:Corrosion-resistant extrusions and sheet forming reduce curb weight by 30-40% versus steel equivalents. EPA greenhouse gas standards for heavy-duty vehicles are forcing fleet managers to prioritize aluminum bodies that preserve electric range on battery-electric chassis.
- Carbon Fiber:Aerospace scrap stream convergence is opening cost-competitive pathways for premium fleet segments.
- Fiberglass:Molded panels for specialized compartmentalization and corrosion protection.
- Composite:Hybrid material systems combining fiber reinforcement with polymer matrices.
Steel dominates current procurement volumes; aluminum specifications are gaining share fastest.
Application:
Customer type determines duty cycle intensity and body durability requirements.
- Municipal Waste Collection:Residential route optimization with standardized 32-96 gallon bin interfaces. Smart Cities Mission funding in India is creating first-time mechanized demand in tier-2 municipalities previously served by manual haulage.
- Commercial Waste Management:Front-loader and roll-off configurations for business districts with variable container sizing. Private contractors in Texas and California are deploying telematics-enabled compaction monitoring to eliminate unnecessary truck rolls.
- Industrial Waste Handling:Heavy-duty specifications for manufacturing byproduct and process residue.
- Construction Debris Removal:Reinforced bodies with impact-resistant flooring for aggregate and demolition material.
Municipal applications anchor procurement volumes; commercial waste management is expanding most quickly.
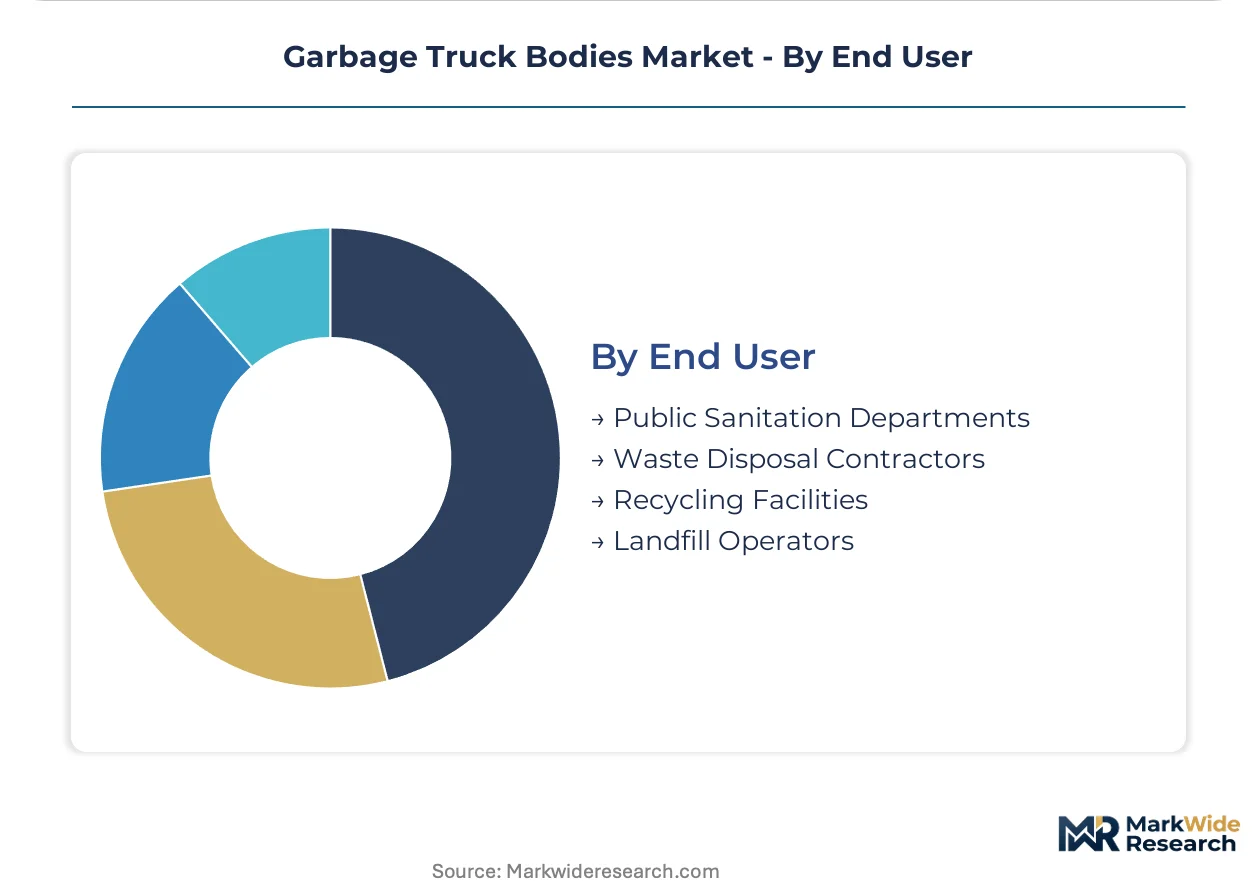
End User:
Procurement authority separates public-sector centralized buying from fragmented private contractor decision-making.
- Public Sanitation Departments:Centralized municipal fleet management with multi-year replacement cycles. United States metropolitan regions are consolidating vendor relationships, reducing supplier count per fleet from eight to three through bundled fabrication and maintenance contracts.
- Waste Disposal Contractors:Private operators with asset utilization metrics driving specification choices. Right-to-repair legislation in select United States states is enabling independent service network expansion for aftermarket body refurbishment.
- Recycling Facilities:Specialized compartmentalization for source-separated material streams.
- Landfill Operators:Transfer station and compaction equipment for final disposal operations.
Public sanitation departments lead absolute procurement volumes; waste disposal contractors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio-Michigan manufacturing corridor anchors global garbage truck body fabrication, with Detroit-area metalworking clusters supplying high-tensile steel stampings and hydraulic assemblies to North American fleet operators.
United States
Federal infrastructure spending and aging municipal fleet replacement cycles are converging to drive procurement volumes across metropolitan regions. EPA greenhouse gas standards for heavy-duty vehicles are forcing fleet managers to retire diesel chassis ahead of schedule, triggering demand for lightweight aluminum bodies. Chicago and Dallas sanitation departments are consolidating vendor relationships through multi-year bundled contracts.
Germany
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerant options for climate-controlled body compartments. The country's national environmental regulator is enforcing stricter urban emissions zones in Berlin, Hamburg, and Munich. Stuttgart's automotive engineering cluster is re-engineering hydraulic pump sizing and control logic for electric motor characteristics.
China
Dual carbon goals and urban sanitation modernization programs are accelerating mechanized waste collection deployment in tier-2 municipalities. The Ministry of Ecology and Environment is tightening emissions standards for commercial vehicle fleets. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou are scaling aluminum extrusion capacity for export-oriented body fabricators.
India
Smart Cities Mission funding is creating first-time mechanized demand in municipalities previously served by manual haulage. The Bureau of Indian Standards is developing certification protocols for refuse collection vehicle safety. Gujarat's automotive component cluster in Ahmedabad is attracting joint ventures for hydraulic system localization.
Japan
METI industrial decarbonization roadmaps are pressuring fleet operators toward battery-electric chassis platforms. JIS standards committees are revising weight rating specifications for composite-material body applications. Nagoya's industrial machinery corridor is specializing in precision hydraulic valve manufacturing for compaction mechanisms.
Garbage Truck Bodies Market Key Industry Players
Global majors compete with regional champions across automation technology and material specialization tiers, producing a market structure where scale-driven fabricators coexist with niche configuration specialists. The vendor base clusters around three strategic archetypes: integrated chassis-body assemblers with captive hydraulic supply, standalone body fabricators serving multi-brand chassis platforms, and composite-material specialists targeting premium lightweighting segments. Competitive moves center on backward integration into refuse body fabrication and geographic expansion through municipal fleet service contracts.
Among North American fabricators, Heil Environmental and McNeilus Truck and Manufacturing occupy positions within the integrated-assembler archetype, while Dennis Eagle exemplifies the regional-specialist model serving European urban emissions zones. Chengli Special Automobile represents the scale-driven Chinese manufacturing tier. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Labrie Environmental Group |
| Amrep |
| Heil Environmental |
| Oshkosh Corporation |
| EZ Pack |
| New Way Trucks |
| Dennis Eagle |
| Chengli Special Automobile |
| McNeilus Truck and Manufacturing |
| Others |
Cost & Logistics Intelligence
Scrap steel price indices cascade through garbage truck body fabrication tiers, compressing margins for mid-tier fabricators without captive supply while amplifying pricing power for aluminum and composite specialists serving electrified municipal fleets.
Pricing Analysis
Input-cost pass-through from high-tensile steel and aluminum alloy markets structures three-tier pricing across premium, standard, and economy levels. Price differentiation rests on certification grade and volume scale, with CE-marked bodies for EU urban emissions zones commanding premiums over uncertified equivalents. Cost compression in steel-intensive configurations is intensifying because scrap metal volatility outpaces contract hedging capacity. Municipal sanitation departments exhibit highest price sensitivity due to centralized procurement scrutiny, while private waste disposal contractors show lowest sensitivity where asset utilization metrics dominate specification choices.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale municipal fleet demand, while regional fabricators serve spot replacement markets through dealer networks. Manufacturing gravity centers on the United States, Germany, and China, with hydraulic system dependencies drawing from Japanese and German industrial corridors. Raw material inputs hinge on high-tensile steel scrap streams, aluminum extrusion billets, and specialized hydraulic piston assemblies. Single-source vulnerability concentrates in precision valve manufacturing for compaction mechanisms. Distribution runs through chassis OEM captive networks, independent body builders, and municipal procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet electrification forces premium aluminum and composite specifications over commodity steel alternatives.
For Market Incumbents: Extend automation technology leadership into electric-hydraulic system integration before battery-electric chassis penetration accelerates. Backward integration into aluminum extrusion capacity secures margin control against scrap price volatility. Defensive consolidation through multi-year municipal service contracts locks out emerging competitors. For New Entrants and Emerging Players: Carbon fiber composite manufacturing expertise offers a technology-first wedge into premium fleet segments previously closed to new suppliers. White-space concentration sits with tier-2 Indian municipalities receiving Smart Cities Mission funding for first-time mechanized collection. Target aftermarket refurbishment networks enabled by right-to-repair legislative momentum as the go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with composite-material specialists possessing aerospace scrap stream partnerships and electric chassis compatibility roadmaps. Long-term viability favors acquisition targets with certified aluminum body platforms and municipal maintenance contract backlogs. Watch EPA heavy-duty vehicle emissions rule enforcement timing as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of lightweight materials preserves margins under EPA fuel economy mandates. |
| Electric-Hydraulic System Development | Re-engineered pump architectures unlock battery-electric chassis compatibility for municipal fleets. |
| Multi-Year Fleet Service Contracts | Bundled fabrication and maintenance agreements reduce supplier count per fleet from eight to three. |
| Carbon Fiber Composite Adoption | Aerospace scrap convergence opens cost-competitive lightweighting for premium procurement tiers. |
| Smart Cities Mission Partnership | Joint ventures in Gujarat and Maharashtra capture first-time mechanized demand in Indian tier-2 municipalities. |
Research Approach
Direct dialogue with municipal fleet managers, hydraulic system engineers, aluminum extrusion procurement leads, and aftermarket service heads grounded qualitative findings in operational realities. Secondary validation drew from EPA regulatory filings, EU F-Gas Regulation documentation, SEC 10-K disclosures from chassis OEMs, and municipal procurement database records. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity and fleet replacement cycle data.
Bottom-up modeling segmented the analysis window by body type, material grade, loader configuration, and chassis propulsion architecture. CAGRs were derived from regression analysis against municipal capital expenditure trajectories and electrification policy timelines. Industry-specific forecast inputs incorporated battery-electric chassis payload constraints and aluminum alloy welding technician pipeline constraints.
The model holds under stable scrap metal pricing and gradual electrification adoption; deviation in steel volatility spikes or accelerated EPA enforcement would shift replacement cycle timing. Forecasts reflect documented assumptions regarding fleet age distribution and infrastructure spending authorization levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market