
 Global Connected Truck Market | 2026-2036
Global Connected Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Truck Market Analysis
UNECE WP.29 cybersecurity certification is bifurcating the supplier landscape into qualified Tier-1 integrators and excluded component vendors. Daimler Truck leverages in-house telematics development to control firmware update cycles across its global installed base. Continental sustains R&D intensity in V2X module production, anchoring its position in European OEM supply chains.
Connected trucks integrate cellular, satellite, and short-range radio modules with onboard diagnostic systems to transmit real-time vehicle, cargo, and environmental data to fleet control centers. Telematics and V2X represent the most technically demanding layers, where proprietary protocol stacks create margin concentration for module suppliers. Cloud-based deployment is expanding fastest among logistics companies seeking scalable route optimization without capital-intensive infrastructure, while edge computing retains traction in mining and construction fleets operating beyond reliable cellular coverage.
The EU AI Act and UNECE WP.29 regulations together mandate algorithmic transparency and cybersecurity management systems for autonomous-capable commercial vehicles, forcing OEMs to restructure software supply chains. The US NHTSA and FMCSA maintain separate but converging mandates on electronic logging devices and automatic emergency braking, creating compliance complexity for multinational fleet operators. Stakeholders must monitor regulatory divergence between Brussels and Washington to determine whether to centralize or regionalize connected platform architectures.
Market Dynamics
The connected truck sector is being restructured by the collision of UNECE WP.29 cybersecurity mandates with fragmented cellular infrastructure, forcing OEMs to choose between unified global platforms or regionally siloed architectures.
Growth Catalysts
- EU Green Deal truck CO2 standards:German and Swedish OEMs are accelerating powertrain optimization investments to meet fleet-average emissions targets, embedding telematics as mandatory compliance infrastructure.
- Cold-chain logistics expansion:Pharmaceutical and fresh-food distributors in the Netherlands and Denmark are deploying temperature-monitoring modules to protect high-value cargo across multimodal routes.
- Edge computing adoption:Mining operators in Australia and Canada are installing onboard processing units to maintain operational continuity beyond cellular dead zones.
Market Restraints
- Semiconductor supply concentration:V2X module production remains captive to Taiwanese and South Korean foundry capacity, exposing European Tier-1 suppliers to allocation volatility.
- UNECE WP.29 certification costs:The cybersecurity management system mandate imposes fixed compliance burdens that disproportionately squeeze mid-volume truck manufacturers.
- Legacy fleet inertia:Owner-operators running pre-2018 vehicles face retrofit economics that delay connected platform penetration in fragmented long-haul segments.
Strategic Opportunities
- Brazilian agribusiness corridors:Soy and meat exporters are piloting satellite-integrated telematics to track refrigerated containers across the BR-163 highway network.
- EU AI Act algorithmic transparency:Autonomous-capable truck developers can differentiate through documented decision-audit trails that satisfy Brussels compliance requirements.
- 5G-V2X convergence:The intersection of cellular vehicle-to-everything and edge AI is creating new service layers for predictive maintenance in German automotive manufacturing supply chains.
Industry Challenges
- Embedded software engineering scarcity:Functional safety expertise for ISO 26262-compliant truck systems is concentrated among a handful of German and Japanese engineering consultancies.
- Multi-jurisdiction logging device fragmentation:Fleet operators must reconcile US FMCSA hours-of-service rules with EU tachograph mandates, complicating cross-border platform design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Truck Market |
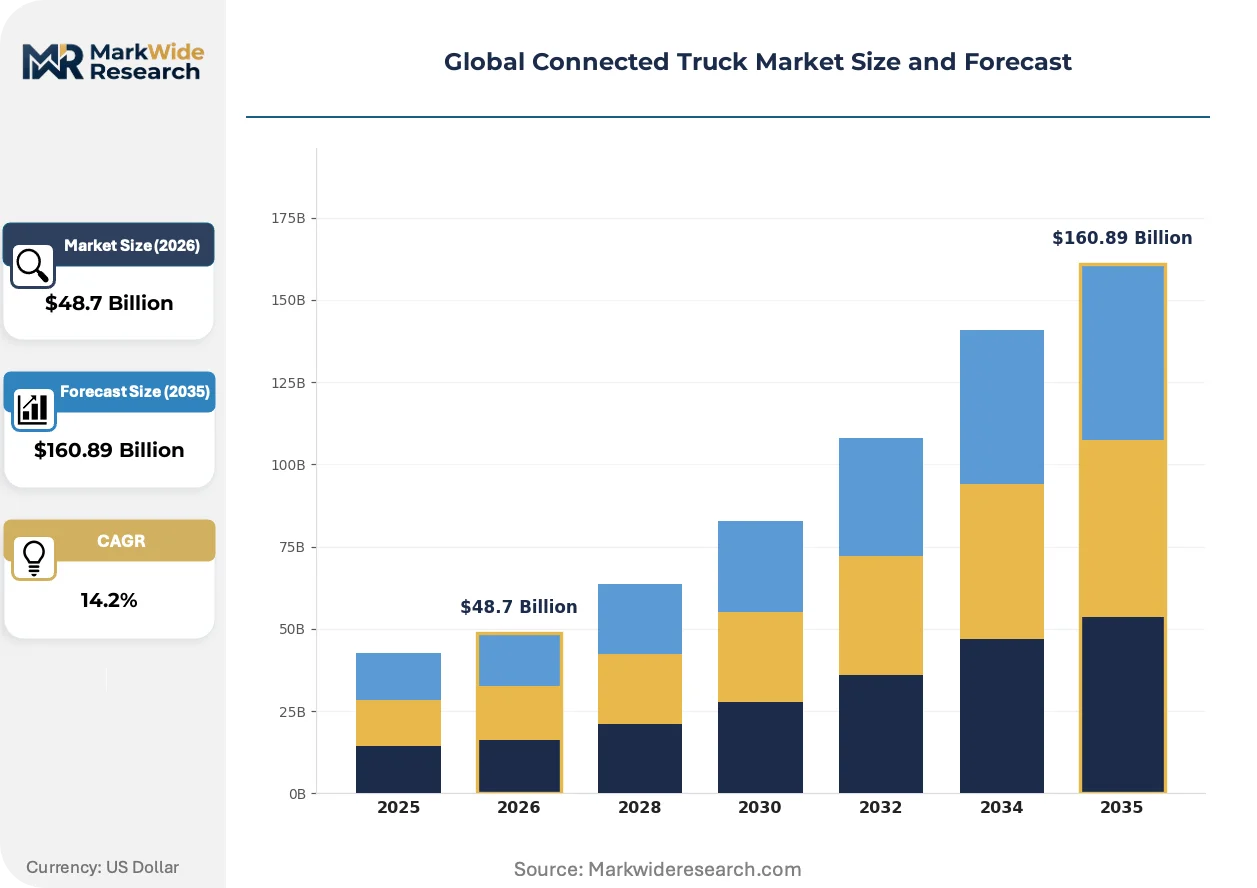
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, GPS, V2X, IoT Sensors End User: Fleet Operators, Logistics Companies, Truck Manufacturers, Carrier Services Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution: Fleet Management, Route Optimization, Predictive Maintenance, Safety Tracking |
| Companies Covered | Daimler Truck, Volvo, PACCAR, Continental, Robert Bosch GmbH, MAN Truck & Bus, Scania, ZF Friedrichshafen AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Truck Market Emerging Trajectories
Three distinct vectors are compressing development cycles in connected truck architectures: cybersecurity protocol stratification, regulatory divergence between Brussels and Washington, and the unbundling of fleet management software from hardware bundles.
Cellular-to-satellite hybrid connectivity is bifurcating the telematics supplier landscape. Long-haul freight operators traversing Siberian and Australian outback routes are demanding seamless handoff between terrestrial and orbital networks. This dual-mode requirement is compressing margins for single-technology vendors while rewarding module suppliers with multi-orbit partnerships.
The EU AI Act's algorithmic transparency requirements are forcing OEMs to restructure software supply chains. Autonomous-capable commercial vehicles must now maintain auditable decision logs for every safety-critical maneuver. German manufacturers are responding by bringing perception-stack development in-house to control documentation liability.
Fleet procurement patterns are fragmenting around subscription-versus-ownership models. Large logistics aggregators in the US and Germany are unbundling telematics hardware from SaaS contracts, treating onboard units as commoditized infrastructure. This shift is visible most acutely in Dutch port-centric distribution networks, where third-party platform providers are displacing OEM-captive systems.
Global Connected Truck Market Segmentation
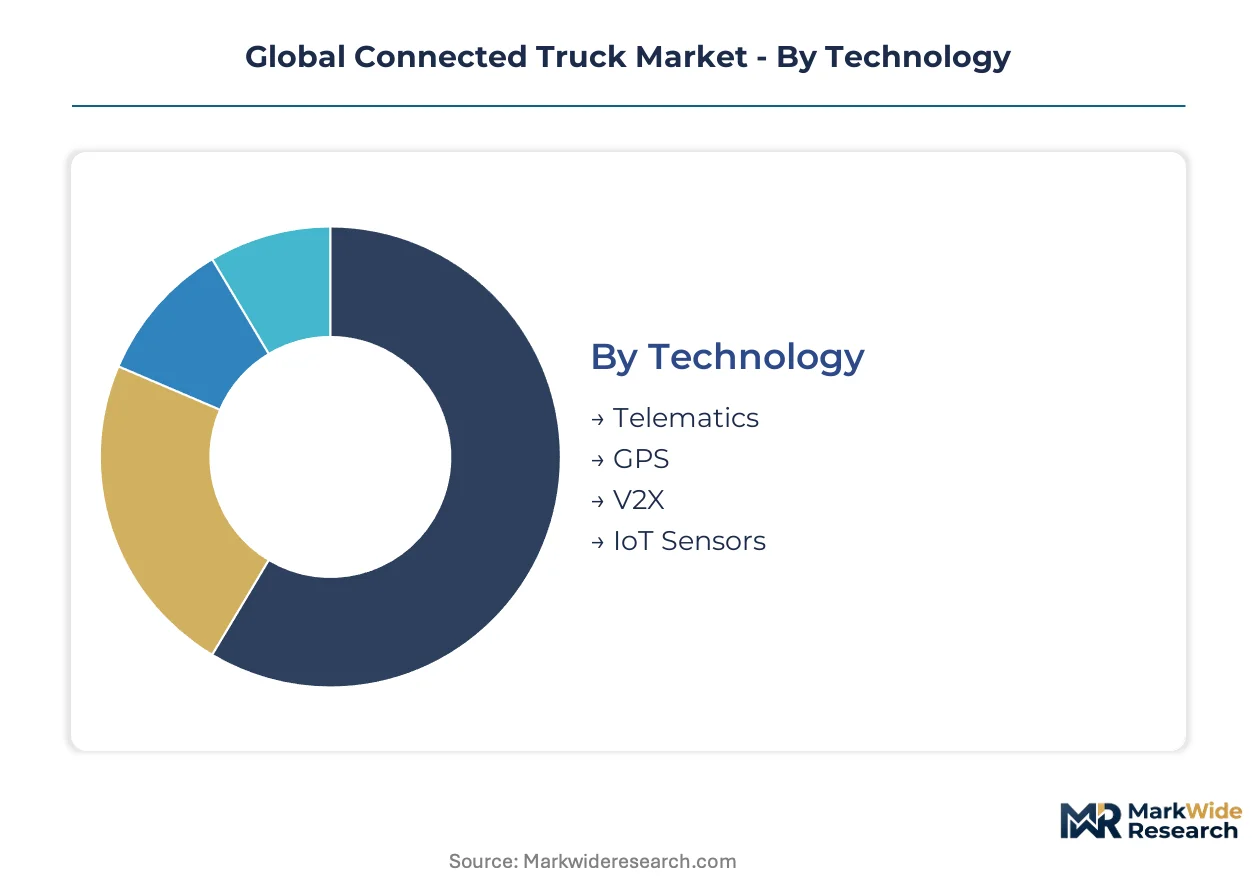
Technology layering in connected trucks determines compliance pathways and margin structures. Regulatory mandates from UNECE WP.29 and the EU AI Act create divergent certification requirements across hardware, software, and connectivity modules.
Technology:
UNECE WP.29 cybersecurity certification applies differentially across hardware and communication layers, concentrating procurement decisions on certified integrators.
- Telematics:Onboard units combine cellular modems with diagnostic interfaces to stream vehicle health and location data. German fleet operators favor integrated telematics to satisfy EU Green Deal emissions reporting mandates for powertrain optimization.
- V2X:Vehicle-to-everything modules enable direct communication with infrastructure and other vehicles using dedicated short-range radio. Stuttgart and Munich development clusters anchor European V2X supply chains as OEMs prepare for autonomous-capable truck deployment.
- GPS:Satellite positioning provides foundational location tracking for route verification and geofencing applications.
- IoT Sensors:Environmental and cargo-condition monitors protect temperature-sensitive loads in pharmaceutical and fresh-food distribution networks.
Established volume favors telematics; emerging adoption favors V2X.
End User:
Procurement authority concentrates differently across asset ownership models, reshaping vendor access and contract structures.
- Fleet Operators:Asset-owning logistics companies deploy connected platforms to optimize utilization and comply with hours-of-service regulations. Dutch cold-chain distributors invest heavily in temperature-monitoring infrastructure to protect high-value cargo across multimodal routes.
- Logistics Companies:Third-party providers unbundle telematics hardware from SaaS contracts, treating onboard units as commoditized infrastructure. Port-centric distribution networks in Rotterdam and Hamburg accelerate this shift toward platform-agnostic procurement.
- Truck Manufacturers:OEMs retain captive telematics development to control firmware update cycles and protect software liability.
- Carrier Services:Subcontracted hauliers face retrofit economics that delay connected platform penetration in fragmented long-haul segments.
Contract scale favors logistics companies; integration depth favors truck manufacturers.
Deployment:
Connectivity reliability requirements vary sharply between urban corridors and remote extraction zones, driving architecture divergence.
- Cloud-Based:Centralized processing enables scalable route optimization without capital-intensive infrastructure. Large US and German logistics aggregators prioritize this model for hub-and-spoke distribution networks.
- Edge Computing:Onboard processing maintains operational continuity beyond cellular dead zones. Mining operators in Australia and Canada install these units for autonomous haulage in remote extraction sites.
- Hybrid:Architectures combine cloud analytics with local decision-making for resilience against connectivity interruption.
- On-Premise:Self-hosted infrastructure retains traction among defense and government fleet operators with data sovereignty requirements.
Scalability economics favor cloud-based deployment; operational resilience favors edge computing.
Solution:
Functional modules align with distinct operational pain points, creating segment-specific margin profiles.
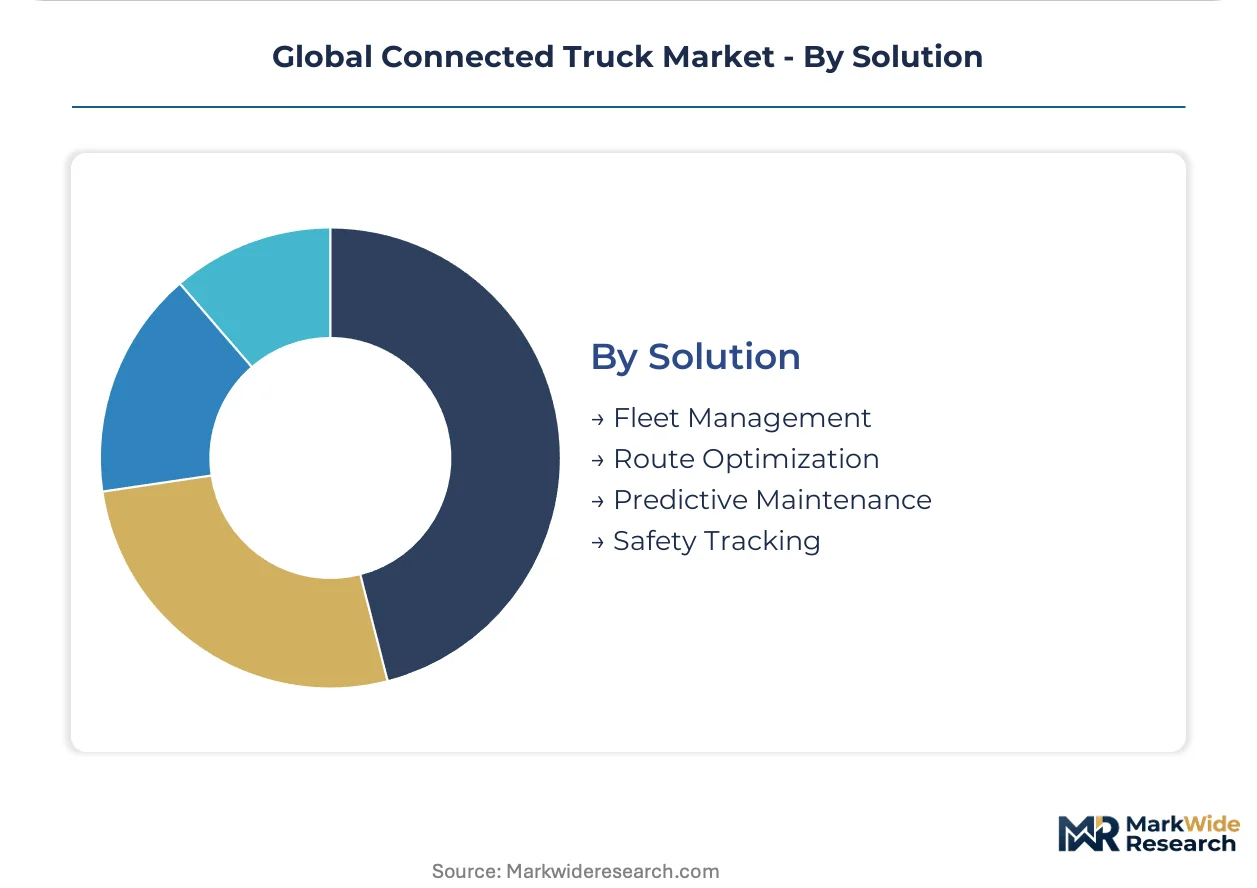
- Fleet Management:Integrated platforms combine vehicle tracking, driver behavior monitoring, and maintenance scheduling. Brazilian agribusiness corridors pilot satellite-integrated systems to track refrigerated containers across the BR-163 highway network.
- Predictive Maintenance:Algorithmic analysis of sensor data anticipates component failure before unplanned downtime. German automotive manufacturing supply chains are early adopters of 5G-V2X convergence for this application.
- Route Optimization:Real-time traffic and fuel-price data reduce empty miles and detention time.
- Safety Tracking:Automatic emergency braking and collision avoidance systems satisfy FMCSA mandates while generating insurance premium reductions.
Operational efficiency favors fleet management; compliance differentiation favors predictive maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators anchor procurement volume for connected truck platforms, while logistics aggregators in the United States and cold-chain distributors in the Netherlands drive technology adoption across distinct regulatory environments.
United States
Large logistics aggregators unbundle telematics hardware from SaaS contracts, treating onboard units as commoditized infrastructure. NHTSA and FMCSA mandates on electronic logging devices and automatic emergency braking create compliance complexity for multinational fleet operators. Dallas-Fort Worth and Chicago distribution corridors concentrate hub-and-spoke deployment of cloud-based fleet management systems.
Germany
Commercial vehicle manufacturers anchor V2X development clusters around Stuttgart and Munich as OEMs prepare for autonomous-capable truck deployment. The EU Green Deal truck CO2 standards accelerate powertrain optimization investments, embedding telematics as mandatory compliance infrastructure. Baden-Württemberg engineering consultancies concentrate functional safety expertise for ISO 26262-compliant truck systems.
Netherlands
Pharmaceutical and fresh-food distributors deploy temperature-monitoring modules to protect high-value cargo across multimodal routes through Rotterdam and Amsterdam port networks. EU AI Act algorithmic transparency requirements force software supply chain restructuring for autonomous-capable commercial vehicles. Dutch port-centric distribution networks accelerate the shift toward platform-agnostic procurement models.
Brazil
Soy and meat exporters pilot satellite-integrated telematics to track refrigerated containers across the BR-163 highway network connecting Mato Grosso to Pará ports. ANVISA and national transport regulations shape cold-chain compliance requirements for agribusiness corridors. São Paulo-based fleet operators invest in hybrid connectivity to maintain cargo visibility across cellular dead zones in interior states.
Australia
Mining operators in Western Australia and Queensland install onboard edge computing units to maintain operational continuity beyond cellular coverage in remote extraction sites. The country's national transport safety regulator maintains separate heavy vehicle standards that intersect with autonomous haulage development. Perth and Brisbane anchor deployment clusters for predictive maintenance systems in resource extraction supply chains.
Global Connected Truck Market Vendor Landscape
Player mix skews toward integrated OEM-captive systems and modular Tier-1 suppliers, creating a tiered structure where scale advantages concentrate with full-line truck manufacturers. The supplier landscape bifurcates around UNECE WP.29 cybersecurity certification, separating qualified integrators from excluded component vendors. Two strategic archetypes dominate: vertically integrated OEMs controlling firmware update cycles, and specialized module suppliers anchoring European supply chains. Competitive moves center on in-house telematics development and multi-orbit connectivity partnerships.
Within the integrated OEM tier, Daimler Truck and Volvo exemplify the captive-systems archetype, each leveraging in-house development to control software liability and update cadence across global installed bases. Among European Tier-1 suppliers, Continental occupies a position representing the certified-integrator archetype, sustaining R&D intensity in V2X module production to anchor procurement relationships with Stuttgart and Munich development clusters. These three entities collectively illustrate how cybersecurity mandates and powertrain optimization requirements are restructuring vendor selection criteria across the value chain.
| Leading Market Players |
|---|
| Daimler Truck |
| Volvo |
| PACCAR |
| Continental |
| Robert Bosch GmbH |
| MAN Truck & Bus |
| Scania |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Cellular-to-satellite module substitution in long-haul telematics is simultaneously redrawing procurement geography toward multi-orbit vendors and compressing margins for single-technology suppliers locked into terrestrial-only architectures. This input shift concentrates pricing power with certified integrators capable of seamless orbital handoff while fragmenting contract structures across hybrid connectivity tiers.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate V2X module procurement, exposing European Tier-1 suppliers to silicon wafer price volatility. Three-tier pricing structure across UNECE-certified integrators, qualified component vendors, and excluded suppliers reflects cybersecurity compliance tiering rather than performance differentiation. Cost compression in mid-volume truck manufacturer segments intensifies because WP.29 certification burdens fall disproportionately on smaller OEMs. Fleet operators running 500-plus vehicle assets show lowest price sensitivity due to bundled SaaS economics, while owner-operators exhibit acute sensitivity to per-unit hardware costs.
Supply Chain Analysis
Inventory lead times for automotive-grade semiconductors stretch 26-40 weeks, forcing telematics suppliers into speculative capacity commitments. V2X module production draws from Taiwanese foundry capacity, South Korean memory fabrication, and German automotive PCB assembly. Single-source vulnerability concentrates in 5G baseband silicon where Qualcomm and MediaTek anchor global supply. Distribution runs through Stuttgart and Munich development clusters for European OEM integration, with Rotterdam and Hamburg port networks serving logistics aggregator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward logistics aggregators unbundling hardware from SaaS contracts, as fleet operator consolidation in US and German hub-and-spoke networks concentrates procurement volume with fewer decision-makers.
For Market Incumbents: Consolidate firmware update control through in-house telematics development to protect software liability exposure under EU AI Act algorithmic transparency mandates. Deepen backward integration into edge computing silicon design to secure supply continuity against Taiwanese foundry allocation volatility. Prioritize UNECE WP.29 certification maintenance as a barrier against mid-volume OEM challengers. For New Entrants and Emerging Players: UNECE WP.29 cybersecurity fast-track pathways offer entry into mid-volume truck manufacturer supply chains excluded by certification cost barriers. Brazilian agribusiness corridors present the most penetrable geography, with satellite-integrated cold-chain tracking underserved by incumbent terrestrial-only vendors. Lead with outcome-based cargo-visibility contracts rather than hardware-centric pricing to bypass entrenched OEM-captive relationships. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward perception-stack developers with auditable decision-log capabilities. Five-to-ten year viability favors certified Tier-1 integrators over component vendors facing exclusion from OEM supply chains. Watch NHTSA-FMCSA convergence timeline on automatic emergency braking mandates as a signal for US-EU regulatory alignment or divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Connectivity Partnership | Hybrid cellular-satellite modules capture long-haul routes across Siberian and Australian dead zones. |
| UNECE WP.29 Certification Investment | Cybersecurity management system qualification separates qualified integrators from excluded component vendors. |
| In-House Perception-Stack Development | Algorithmic transparency documentation protects OEM liability under EU AI Act mandates. |
| Edge Computing Silicon Design | Onboard processing units maintain mining fleet continuity beyond cellular coverage in Western Australia. |
| Platform-Agnostic Telematics Unbundling | Hardware-SaaS separation aligns with Dutch port-centric logistics aggregator procurement patterns. |
Methodological Framework
A standing panel of fleet operations directors, OEM platform engineers, Tier-1 supplier procurement leads, and cold-chain logistics managers provided ongoing calibration across primary interview rounds and secondary validation. Fleet operator contract structures, UNECE WP.29 certification databases, EU Green Deal emissions reporting filings, and FMCSA hours-of-service compliance records anchored bottom-up volume estimates against top-down market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology layer, deployment architecture, end-user procurement authority, and solution functional module. CAGRs derived from installed base penetration curves and replacement cycle analysis, with powertrain optimization investment intensity and autonomous-capable truck development timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable Taiwanese foundry allocation; material deviation in semiconductor supply or WP.29 implementation timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Utility Trucks Market