
 Solid Control Equipment Market | 2026-2036
Solid Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Control Equipment Market Analysis
Buyer concentration among supermajors and large independents is restructuring procurement dynamics across the solid control equipment supply base. Schlumberger Limited leverages integrated drilling services bundling to capture multi-year contracts, while Halliburton Company anchors its position through captive manufacturing of centrifuge systems. Baker Hughes Company differentiates via digital diagnostics embedded in mud cleaner units, reducing unplanned downtime for offshore fleets.
Solid control equipment encompasses mechanical systems engineered to remove drilled solids from circulating drilling fluid, with shale shakers operating at 7.5–8.5 G-force vibration intensity to process 500–1,200 gallons per minute of weighted mud. These systems preserve rheological properties of drilling fluid, cut additive consumption, and minimize waste disposal volumes across rotary drilling operations. Shale shakers occupy the largest installed base due to universal deployment at every wellsite, though centrifugation technology captures expanding share in high-temperature high-pressure wells where ultra-fine solids separation determines rate-of-penetration economics. Cyclonic separation systems sustain margin pools in offshore environments where space constraints and discharge limits elevate equipment specification thresholds.
API RP 13C governs shaker screen labeling and performance certification, while EPA effluent limitations under the Clean Water Act constrain offshore cuttings discharge, directly shaping equipment specification requirements for Gulf of Mexico operators. OSHA silica exposure standards and BSEE well control regulations compound compliance burdens, forcing contractors toward closed-loop systems with automated monitoring. Stakeholders must weigh capital intensity of full-loop automation against regulatory penalty exposure and rising waste transport costs when configuring fleet procurement strategies.
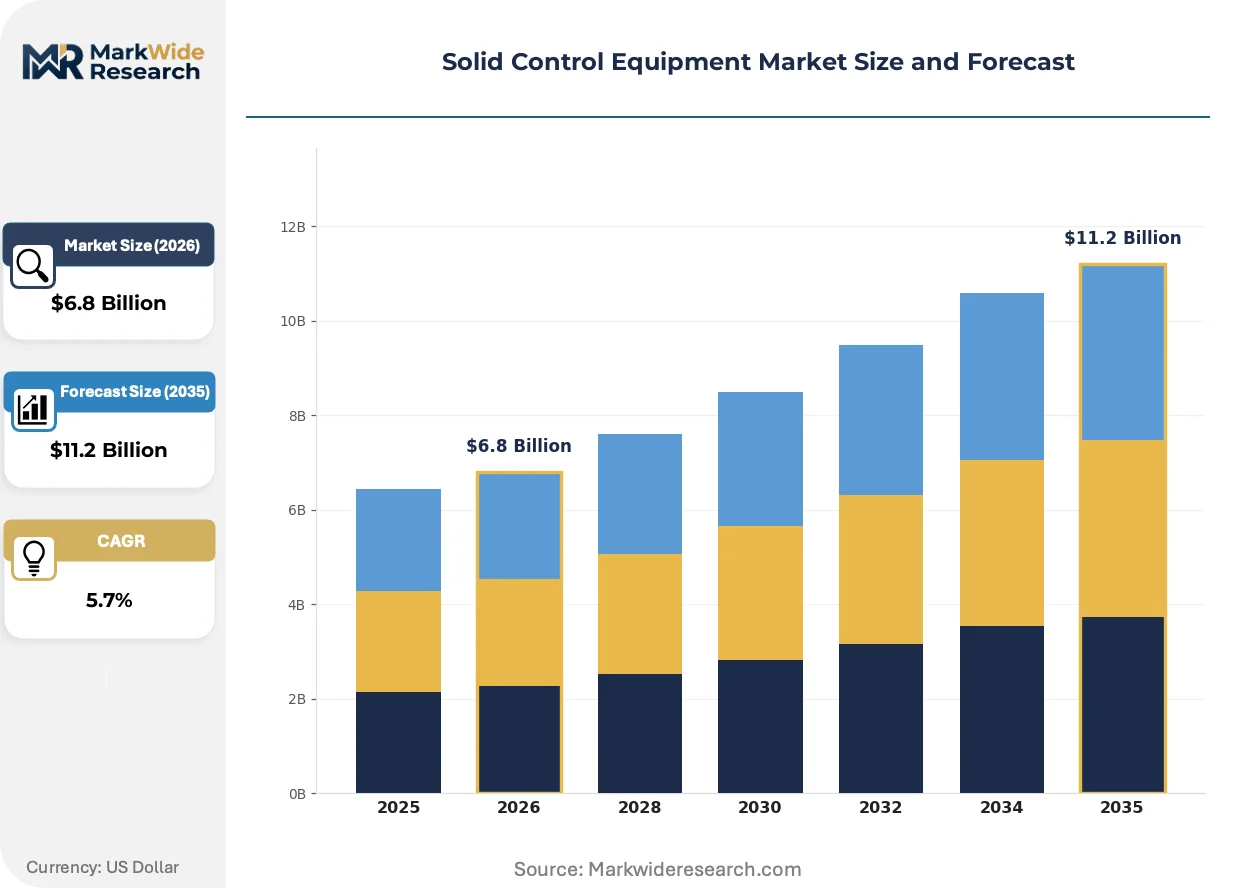
Market Dynamics
Automated shale shaker systems are compressing labor intensity and redefining procurement criteria across drilling contractor fleets, as pad drilling density in the Permian Basin forces simultaneous optimization of throughput, footprint, and real-time diagnostics.
Growth Catalysts
- EPA effluent limitations under the Clean Water Act:Offshore operators in the Gulf of Mexico face tightening discharge thresholds, mandating closed-loop solids control systems with enhanced cuttings dewatering capability.
- Pad drilling intensification:Multi-well pad configurations in the Permian Basin generate 40-60% higher mud recycling volumes per site, amplifying demand for high-capacity shale shakers and integrated centrifuge trains.
- API RP 13C screen certification:Standardized performance labeling enables contractors to specify mesh efficiency with precision, reducing trial-and-error procurement and accelerating technology substitution cycles.
Market Restraints
- Steel alloy price volatility:Shaker screen manufacturing depends on specialized wire mesh alloys whose input costs fluctuate with nickel and chromium commodity markets, compressing margin predictability for fabricators.
- Equipment supply concentration:High-G-force vibratory motors and composite screen frames source predominantly from German and Japanese precision manufacturers, creating single-source vulnerability for mid-tier system integrators.
- Centrifuge technical ceiling:Ultra-fine solids separation below 2 microns remains thermally and mechanically constrained in high-temperature high-pressure well conditions, limiting rate-of-penetration gains in deep gas plays.
Strategic Opportunities
- Digital twin integration:Convergence of vibration telemetry with predictive analytics platforms enables remote screen failure forecasting, opening subscription-based service models for offshore fleet operators.
- Argentina Vaca Muerta development:Underpenetrated shale infrastructure creates first-mover advantage for automated solids control packages as international operators scale drilling activity in Neuquén Basin.
- EU Green Deal methane monitoring alignment:Drilling waste minimization protocols tied to EU sustainability disclosure requirements position closed-loop systems for preferential contractor qualification in North Sea licensing rounds.
Industry Challenges
- Vibration analysis technician scarcity:Automated diagnostics require field personnel capable of interpreting spectral frequency data and correlating anomalies to mechanical failure modes, a skill set concentrated among aging specialist workforces.
- Legacy mud system integration:Retrofitting automated shale shakers onto 1990s-vintage circulating systems demands custom manifold reconfiguration and control system bridging, extending commissioning timelines and disrupting rig scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Control Equipment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shale Shakers, Desanders, Desilters, Mud Cleaners End User: Oil & Gas, Mining, Construction, Environmental Services Technology: Cyclonic Separation, Centrifugation, Gravity Separation, Filtration Delivery Mode: Onshore, Offshore, Mobile Units, Fixed Installations |
| Companies Covered | Schlumberger Limited, Halliburton Company, Weatherford International Plc, Baker Hughes Company, GN Solids Control, Derrick Corporation, KOSUN Machinery Co. Ltd, China Petroleum Technology & Development Corporation (CPTDC), KES Energy Equipment Manufacturing Hebei Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Control Equipment Market Emerging Trajectories
Electrification of surface processing equipment and embedded sensor architectures are compressing the operational envelope between mechanical separation and real-time optimization, with regulatory compliance and labor cost reduction as parallel forcing functions.
Variable frequency drive (VFD) technology is electrifying shale shaker powertrains, replacing fixed-speed motors with adaptive vibration control that modulates G-force intensity based on solids loading. Onshore contractors in Texas and New Mexico are deploying these systems at replacement cycle pace. The technology is electrifying competitive differentiation around energy efficiency metrics and screen life extension, displacing conventional pneumatic tensioning systems in premium contract bids.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are reshaping offshore cuttings treatment chemistry, eliminating legacy surfactants used in synthetic-based mud systems. European North Sea operators must reformulate or substitute thermal desorption unit feedstocks. Centrifuge manufacturers serving Norway and UK sectors are accelerating ceramic-matrix screen development to handle more aggressive chemical environments without PFAS-based lubricants.
Contractor procurement departments are consolidating vendor relationships around integrated package providers, unbundling standalone equipment purchases in favor of performance-guaranteed service agreements. Independent shale shaker specialists face displacement by bundled drilling fluid and solids control contractors. The shift is most pronounced in US land markets where supermajors centralize supply chain decision-making at divisional headquarters rather than rig-site level.
Solid Control Equipment Market Segmentation
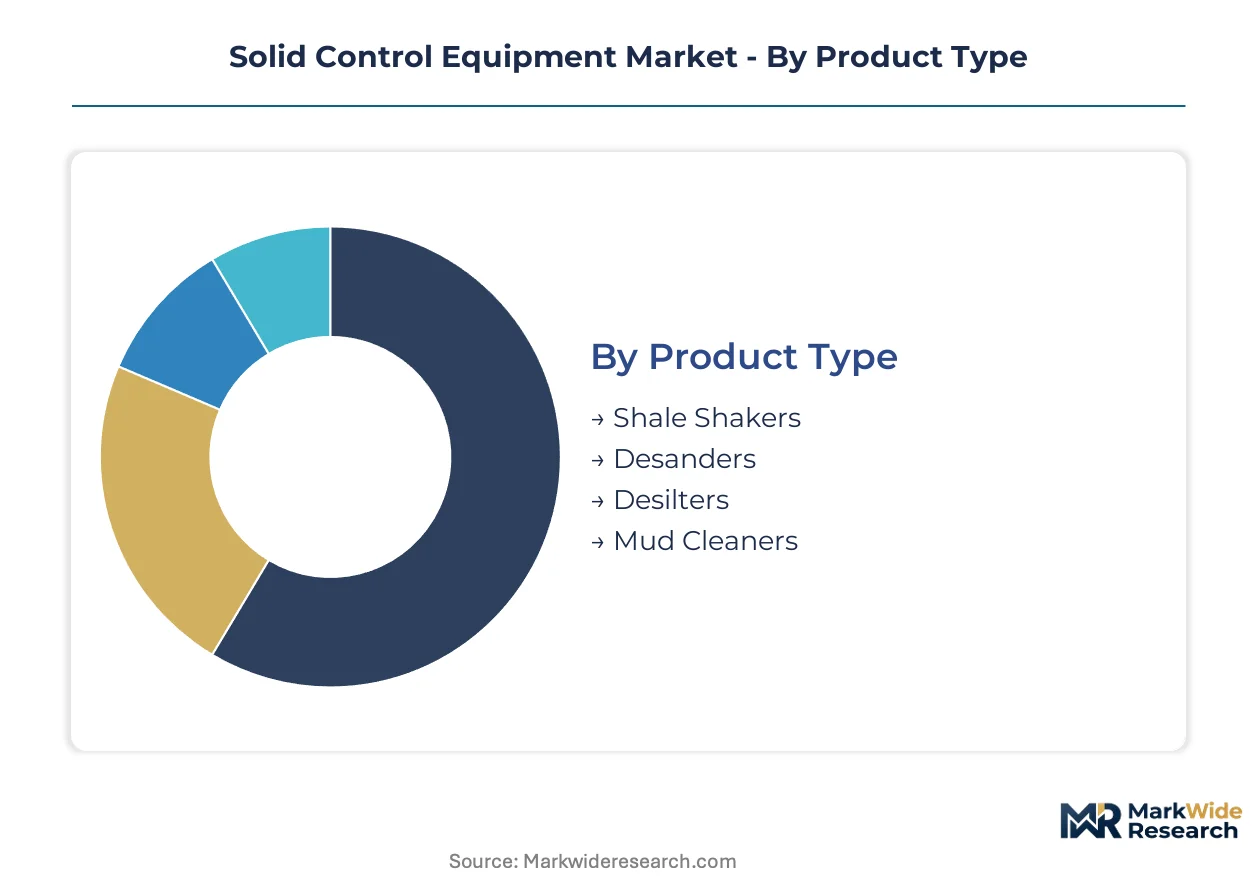
Segmentation in solid control equipment reveals divergent capital requirements and operational intensity across drilling environments. Equipment specification varies sharply between high-volume onshore pad operations and space-constrained offshore platforms, while technology choice directly determines both upfront investment and lifecycle operating cost profiles.
Product Type:
Capital intensity peaks with integrated mud cleaner systems, while standalone shale shakers demand lower upfront outlay but higher consumables spend over time.
- Shale Shakers:Vibratory screening systems operating at 7.5–8.5 G-force process 500–1,200 gallons per minute of weighted drilling fluid. Permian Basin contractors specify high-capacity units with automated screen tensioning to handle 40–60% elevated mud recycling volumes from multi-well pad configurations.
- Mud Cleaners:Combined desander-desilter-shaker assemblies deliver integrated solids control in a single skid-mounted package. Gulf of Mexico operators favor these systems for offshore platforms where deck space constraints and BSEE discharge regulations mandate compact, closed-loop processing with real-time cuttings monitoring.
- Desanders:Hydrocyclone-based units remove coarse solids in the 40–100 micron range upstream of finer separation stages.
- Desilters:Smaller-diameter hydrocyclones target silt-sized particles between 15–40 microns in unweighted mud systems.
Shale shakers absorb the bulk of installed capacity across drilling contractor fleets; mud cleaners are expanding most quickly in offshore contract specifications.
End User:
Application-driven performance requirements separate high-specification oilfield deployments from general industrial uses with lower technical thresholds.
- Oil & Gas:Exploration and production operators specify API RP 13C-certified equipment with automated diagnostics and remote monitoring capability. Supermajors and large independents in Texas and New Mexico centralize procurement decisions at divisional headquarters, favoring multi-year performance contracts over standalone equipment purchases.
- Environmental Services:Remediation contractors deploy mobile solids control for drill cuttings processing and contaminated soil washing. EPA effluent limitations under the Clean Water Act drive specification of closed-loop systems with enhanced dewatering for offshore waste management contracts.
- Mining:Mineral processing operations adapt drilling-derived separation technology for tailings dewatering and process water recovery.
- Construction:Tunnel boring and foundation drilling applications require portable shale shaker packages with rapid mobilization capability.
Oil & gas commands the dominant share of equipment revenue; environmental services is climbing the fastest as regulatory enforcement intensifies.
Technology:
Energy and maintenance cost profiles distinguish mechanically intensive separation methods from precision-driven alternatives.
- Centrifugation:High-speed rotating bowl technology achieves ultra-fine solids separation below 2 microns in weighted mud systems. Deep gas plays in high-temperature high-pressure conditions depend on centrifuge trains to preserve rate-of-penetration economics, though thermal and mechanical constraints limit performance at extreme well depths.
- Cyclonic Separation:Hydrocyclone arrays without moving parts handle high-volume coarse solids removal with minimal energy input. Offshore contractors in the Gulf of Mexico specify ceramic-lined cyclones to withstand abrasive synthetic-based muds as REACH restrictions eliminate PFAS-based surfactants from cuttings treatment chemistry.
- Filtration:Pressurized membrane and media-based systems target specialized applications requiring absolute solids exclusion.
- Gravity Separation:Settling tank and flotation-based methods serve low-cost, low-throughput operations with generous space availability.
Cyclonic separation holds the largest operating footprint by unit count; centrifugation is gaining share fastest in premium drilling contracts.
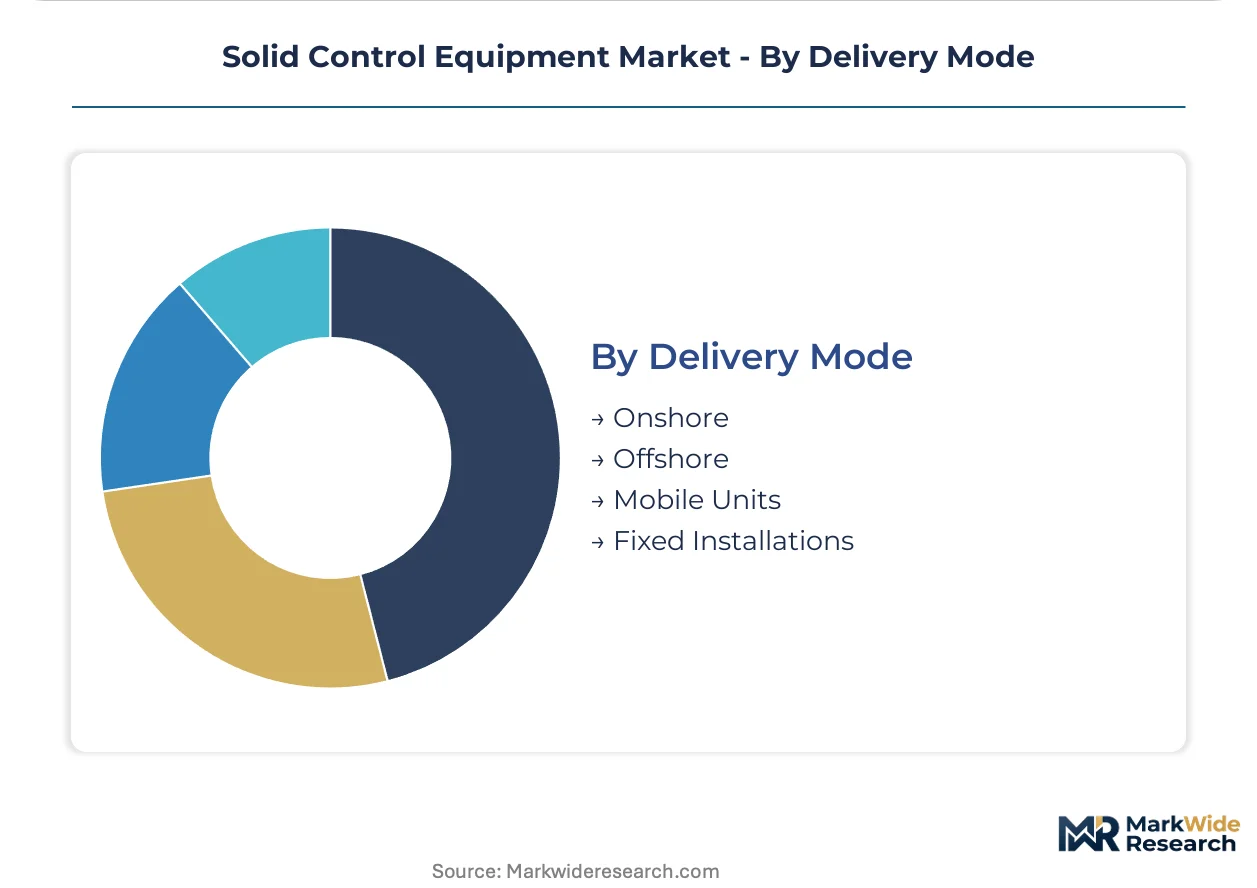
Delivery Mode:
Logistics and commissioning complexity separate rapidly deployable mobile packages from permanent installations with extended lead times.
- Onshore:Fixed and skid-mounted systems dominate land drilling markets with established infrastructure and road access. Pad drilling density in the Permian Basin drives demand for centralized solids control facilities serving multiple wells from a single processing train.
- Offshore:Platform-integrated and modular systems must satisfy space, weight, and discharge constraints. BSEE regulations and EPA effluent limitations mandate automated monitoring and closed-loop cuttings management for Gulf of Mexico operations.
- Mobile Units:Trailer-mounted and containerized packages enable rapid redeployment between exploration sites.
- Fixed Installations:Permanent processing facilities serve long-duration production drilling and waste management centers.
Onshore deployment accounts for the majority of active equipment; offshore specifications are expanding most quickly as deepwater activity resumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for solid control equipment concentrates in hydrocarbon-producing regions where drilling intensity and regulatory stringency intersect. The United States dominates procurement volumes through Permian Basin activity, while offshore markets in the North Sea and Middle East drive premium equipment specifications.
United States
Pad drilling density in the Permian Basin of Texas and New Mexico generates 40-60% elevated mud recycling volumes per site, forcing contractors toward high-capacity automated shale shakers. EPA effluent limitations under the Clean Water Act constrain offshore cuttings discharge in the Gulf of Mexico, mandating closed-loop systems with enhanced dewatering. Houston anchors the national supply chain, hosting fabrication facilities and service company headquarters that coordinate fleet procurement for supermajors and large independents.
Norway
Deepwater drilling in the North Sea and Barents Sea demands centrifuge systems capable of ultra-fine solids separation below 2 microns under high-temperature high-pressure conditions. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy surfactants from synthetic-based mud systems, forcing reformulation of thermal desorption unit feedstocks. Stavanger clusters offshore equipment engineering and subsea technology development, with contractors specifying ceramic-matrix screens for aggressive chemical environments.
Saudi Arabia
Gas drilling expansion in the Jafurah unconventional field drives demand for integrated solids control packages with real-time monitoring capability. The country's national oil company centralizes procurement decisions at headquarters level, favoring multi-year performance contracts over standalone equipment purchases. Dhahran serves as the operational hub, with drilling contractors deploying automated systems to minimize labor intensity across remote desert wellsites.
China
Shale gas development in the Sichuan-Chongqing region accelerates adoption of variable frequency drive shale shakers with adaptive vibration control. GB standards and MEE environmental regulations tighten drilling waste management requirements, pushing domestic operators toward closed-loop configurations. Chengdu anchors southwestern equipment manufacturing, with state-owned enterprises expanding captive production of high-G-force vibratory motors to reduce import dependence.
Brazil
Pre-salt drilling campaigns in the Santos Basin require space-constrained offshore solids control systems with automated cuttings monitoring. ANP regulatory frameworks align with international discharge standards, compelling contractors to specify API RP 13C-certified equipment with embedded diagnostics. Rio de Janeiro concentrates offshore engineering expertise, with international operators qualifying local service providers for integrated drilling fluid and solids control contracts.
Solid Control Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital diagnostics and automated control architectures. The market exhibits tiered concentration with integrated oilfield service conglomerates commanding multi-year contracts, while specialized fabricators compete on equipment customization and regional proximity. Strategic archetypes include bundled service providers, standalone equipment specialists, and captive manufacturing divisions of drilling contractors. Competitive dynamics center on vertical integration into screen manufacturing and technology licensing agreements for vibration telemetry platforms.
Within the integrated services tier, Schlumberger Limited and Halliburton Company exemplify bundled procurement strategies that combine solids control with broader drilling fluid management. Baker Hughes Company occupies a position emphasizing digital differentiation through embedded sensor architectures. Among Asian fabricators, GN Solids Control and KOSUN Machinery Co. Ltd represent the equipment-specialist archetype, with Zhengzhou and Xi'an origins respectively indicating concentration in Chinese manufacturing clusters. Derrick Corporation anchors the North American specialist segment. These named entities illustrate how competitive positioning fragments across geographic origin and service-model architecture rather than consolidating around uniform technology platforms.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Weatherford International Plc |
| Baker Hughes Company |
| GN Solids Control |
| Derrick Corporation |
| KOSUN Machinery Co. Ltd |
| China Petroleum Technology & Development Corporation (CPTDC) |
| KES Energy Equipment Manufacturing Hebei Co. Ltd |
| Others |
Supply Flow & Price Mechanics
EPA effluent limitations under the Clean Water Act gate qualified supply access for offshore contractors, with closed-loop system certification requirements propping premium-tier pricing while standard onshore configurations face cost compression from commoditized shale shaker manufacturing.
Pricing Analysis
High-volume onshore deployments compete on per-unit transactional pricing, while offshore closed-loop systems command project-based premiums tied to BSEE compliance certification and real-time monitoring integration. Price differentiation separates API RP 13C-certified units with automated diagnostics from standard shale shakers lacking embedded sensor architectures. Margins are tightening in the onshore tier due to buyer consolidation among supermajors centralizing procurement at divisional headquarters. Environmental services contractors exhibit highest price sensitivity, while Gulf of Mexico operators prioritize compliance guarantee over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Stavanger, and Dhahran anchor hub-and-spoke patterns serving drilling contractor fleets with rapid spare parts replenishment. Manufacturing concentrates in China, Germany, and the United States, with high-G-force vibratory motors sourcing predominantly from Japanese and German precision suppliers. Raw material dependencies span nickel-chromium wire mesh alloys, composite screen substrates, and ceramic matrix formulations. Single-source vulnerability for precision motor components creates supply chain risk. Distribution runs through integrated service company logistics networks and independent equipment rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized wire mesh alloy supply constraints prop pricing power for certified fabricators, with EPA discharge enforcement tightening qualified supplier pools faster than capacity expansion in precision vibratory motor manufacturing.
For Market Incumbents: Cement multi-year performance contracts with supermajors by bundling solids control with drilling fluid management services, insulating against standalone equipment commoditization. Deepen backward integration into shaker screen manufacturing to capture alloy price volatility margins and reduce German-Japanese motor supplier dependence. Prioritize captive production of high-G-force vibratory motors in Chengdu or Xi'an manufacturing clusters. For New Entrants and Emerging Players: Enter via Argentina's Vaca Muerta development with automated shale shaker packages targeting international operators scaling Neuquén Basin activity. White-space exists in digital twin subscription services for offshore fleet vibration telemetry, with predictive analytics platforms underserved by incumbent hardware-centric business models. Pursue partnership routes with drilling contractors seeking to retrofit legacy circulating systems rather than greenfield equipment sales. For Investors and Strategic Acquirers: API RP 13C certification acceleration among second-tier fabricators is the leading indicator that consolidation pressure is intensifying for uncertified equipment specialists. Long-term viability favors integrated package providers with captive screen manufacturing and embedded diagnostics capability over standalone shale shaker fabricators. Acquisition target archetype: mid-tier system integrators with regional proximity to Permian Basin or North Sea contract flows but lacking digital service layer. Monitor REACH restriction implementation timelines for PFAS-free surfactant substitution as inflection signal for ceramic-matrix screen demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Screen Manufacturing | Captures nickel-chromium alloy margin pools and reduces Japanese-German motor supplier dependence for system integrators. |
| Digital Twin Platform Development | Opens subscription revenue streams from offshore fleet operators seeking remote screen failure forecasting capabilities. |
| Ceramic-Matrix Screen Certification | Positions equipment for REACH-compliant synthetic-based mud systems in Norway and UK North Sea sectors. |
| Automated Shale Shaker Deployment | Compresses labor intensity for Permian Basin pad drilling contractors facing 40-60% elevated mud recycling volumes. |
| Performance-Guaranteed Service Contracts | Aligns procurement with supermajor centralization trends displacing standalone equipment purchases in US land markets. |
Methodological Framework
Document review covered API RP 13C certification databases, EPA effluent limitation filings, BSEE regulatory guidance, and equipment procurement contracts from supermajors and large independents, complemented by interviews with drilling contractor operations managers, solids control equipment procurement directors, shale shaker maintenance technicians, and offshore platform engineering leads. Secondary sources included SEC 10-K filings from integrated oilfield service companies, customs trade data for wire mesh alloy imports, and patent filings for vibration telemetry systems. Bottom-up equipment unit deployment estimates triangulated against top-down drilling activity projections across the analysis window.
Segmentation outputs span product type, end user, technology, and delivery mode dimensions, with additional modeling of API certification tier and automation level as industry-specific variables. CAGRs were derived from regression analysis against drilling rig count trajectories, pad drilling intensity metrics, and regulatory enforcement timelines. Forecast inputs incorporated Permian Basin well density assumptions, Gulf of Mexico deepwater activity resumption patterns, and REACH restriction implementation schedules affecting cuttings treatment chemistry.
Revisions become necessary when EPA effluent limitation enforcement intensity shifts, steel alloy commodity prices destabilize manufacturing cost structures, or precision vibratory motor supply disruptions alter equipment availability timelines. Forecasts reflect documented assumptions regarding regulatory trajectory and drilling contractor capital allocation priorities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
United States Crane Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Europe Crane Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Powered Screed Market
Construction Equipment
Jib Crane Market
Construction Equipment
Europe Ground Penetrating Radar Market