
 Autoclave Aerated Concrete Market | 2026-2036
Autoclave Aerated Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Autoclave Aerated Concrete Market Intelligence
The integration of automated production controls and digital quality assurance systems is narrowing the performance variability between AAC products from different manufacturers. Xella International leverages its extensive European production footprint and R&D in high-performance panels. UltraTech Cement Ltd. anchors its market position in India through its vast distribution network and brand recognition in the cement industry.
Autoclave Aerated Concrete is a lightweight, precast building material produced from a mix of sand, cement, lime, and an expansion agent. Cured in an autoclave under high pressure and steam, it develops a microporous structure, providing excellent thermal insulation and fire resistance. AAC blocks constitute the largest product segment due to their flexibility in wall construction applications for diverse building types. The residential sector remains the principal end user, although commercial applications are expanding with the use of large-format panels.
Building energy codes and standards, such as the EU's CE marking and India's BIS requirements, mandate specific performance criteria for thermal and structural properties. In the United States, ASTM International standards govern the physical and mechanical properties of AAC, ensuring product quality and safety for construction. Manufacturers must balance investments in production capacity with the logistical challenges of transporting a lightweight but voluminous product to varied construction sites.
Market Dynamics
The market's core dynamic is the tension between AAC's superior thermal insulation, which aligns with stringent building energy codes, and its high-volume, low-weight nature, which creates significant logistical and transportation cost challenges for manufacturers.
Growth Catalysts
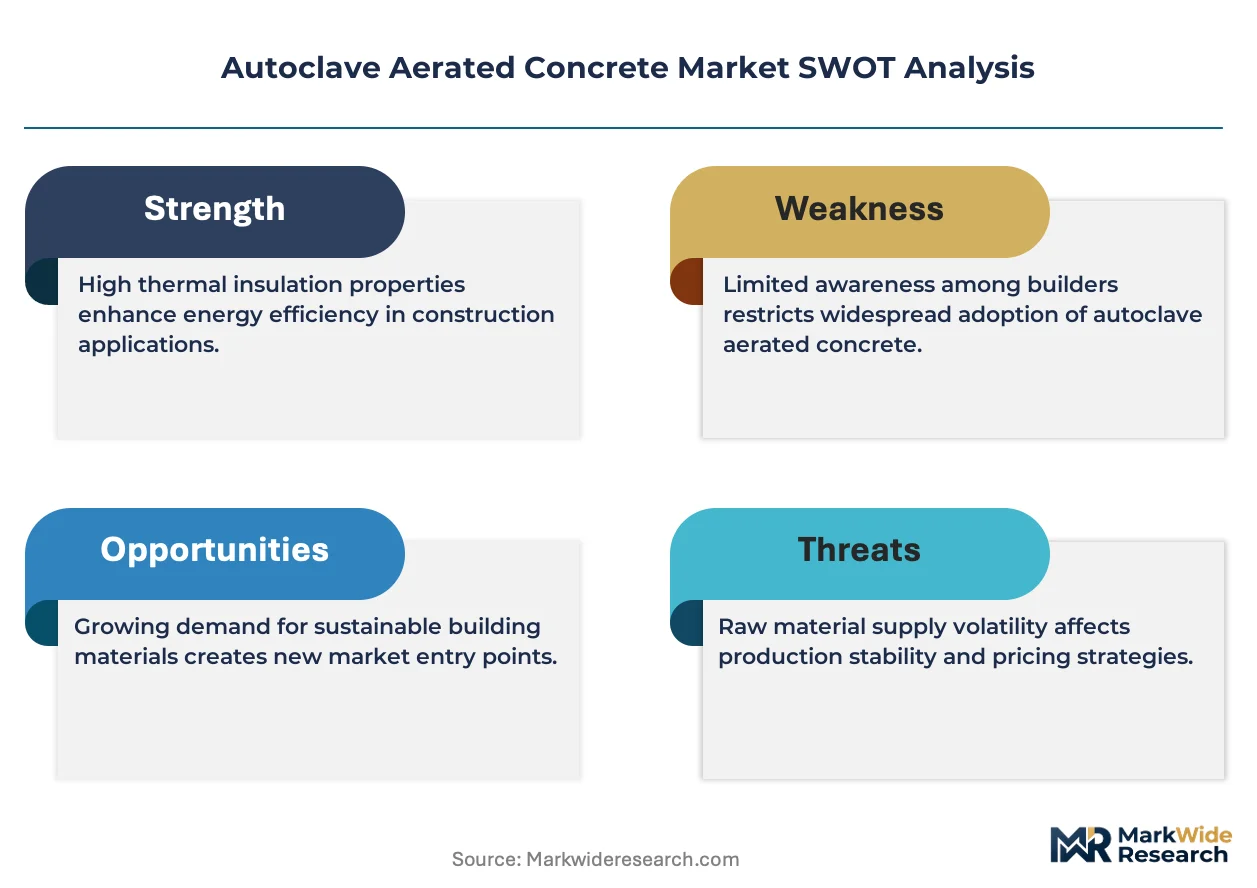
- EU Green Deal:Mandates for nearly zero-energy buildings in the European Union drive the specification of materials like AAC with high thermal performance, particularly in residential and commercial construction.
- Urban Residential Construction:Rapid urbanization in Southeast Asian nations, including Vietnam and Indonesia, requires fast, scalable construction methods, favoring the use of AAC blocks for walling systems.
- Material Science Advances:Innovations in slurry composition and curing processes are creating lighter AAC products with improved strength-to-weight ratios, expanding their application potential.
Market Restraints
- Energy-Intensive Production:The autoclaving process consumes substantial energy, exposing manufacturers to volatile natural gas and electricity prices, which can impact final product cost and competitiveness against other materials.
- Lower Compressive Strength:Compared to traditional dense concrete, AAC exhibits lower compressive strength, limiting its use in certain high-load-bearing structural applications without additional steel reinforcement.
- Substitution by ICFs:Insulated Concrete Forms present a direct substitution threat, offering both structure and insulation in a single system that is familiar to many concrete contractors.
Strategic Opportunities
- North American Market Penetration:Changing building codes favoring energy efficiency and fire resistance create an opening for AAC to gain share from traditional wood-frame construction in the US and Canada.
- Large-Format Panels:The development of reinforced, large-format AAC panels opens new applications in commercial facades and industrial wall systems, moving beyond the block-dominated residential sector.
- Seismic Zone Adoption:In earthquake-prone regions like Japan and the US West Coast, the lightweight nature of AAC is a significant advantage for designing resilient and safer building structures.
Industry Challenges
- Logistical Complexity:The high volume-to-weight ratio makes AAC expensive to transport over long distances, requiring production facilities to be located near major consumption centers to remain cost-competitive.
- Specialized Installation Skills:Proper installation of AAC requires specific techniques and mortars, and a shortage of trained masons can lead to quality issues and limit adoption rates.
- Multi-Standard Compliance:Manufacturers must navigate and secure certifications for multiple international standards, such as ASTM in the United States and CE marking in Europe, increasing testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoclave Aerated Concrete Market |
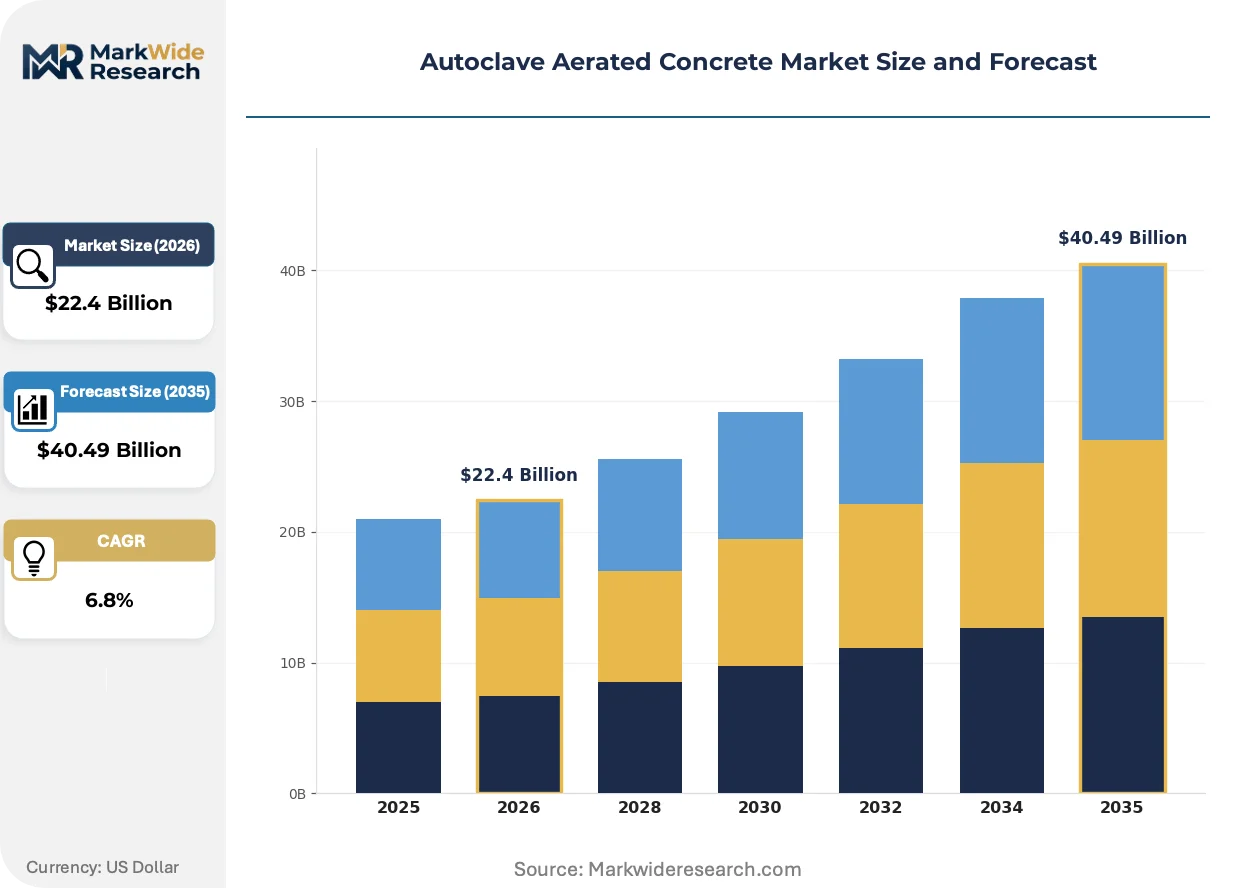
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blocks, Panels, Precast Elements, Others End User: Residential, Commercial, Industrial, Infrastructure Application: Wall Construction, Roof Construction, Floor Construction, Partition Walls Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Xella International, H+H International, UltraTech Cement Ltd., ACICO Group, Biltech Building Elements Limited, JK Lakshmi Cement Ltd., CSR Ltd., Masa Group, Tarmac Building Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoclave Aerated Concrete Market Strategic Shifts & Innovations
Digitalization is fundamentally altering how Autoclave Aerated Concrete is specified and integrated into construction projects. This shift, combined with a focus on whole-building performance, is compelling manufacturers to innovate beyond the basic block.
Advanced material science is developing products that deliver multifunctional performance in a single unit. Prefabrication and modular construction firms are early adopters of these enhanced panels for building envelopes. This development is hybridizing the roles of structure and insulation, compressing on-site construction schedules by integrating building envelope functions into one component.
Building energy performance standards are becoming stricter globally, directly benefiting materials with superior thermal properties. The EU's Energy Performance of Buildings Directive and India's Energy Conservation Building Code both set high targets for insulation. Consequently, the residential and commercial building sectors are increasingly specifying AAC to meet these non-negotiable thermal resistance mandates.
Specification is shifting from personal relationships with distributors to data-driven selection within digital platforms. Architects and structural engineers now use Building Information Modeling (BIM) software with integrated material libraries to select and model components. This trend, most advanced in North American and European commercial projects, favors manufacturers who provide detailed, accessible digital twins of their AAC products.
Autoclave Aerated Concrete Market Segmentation
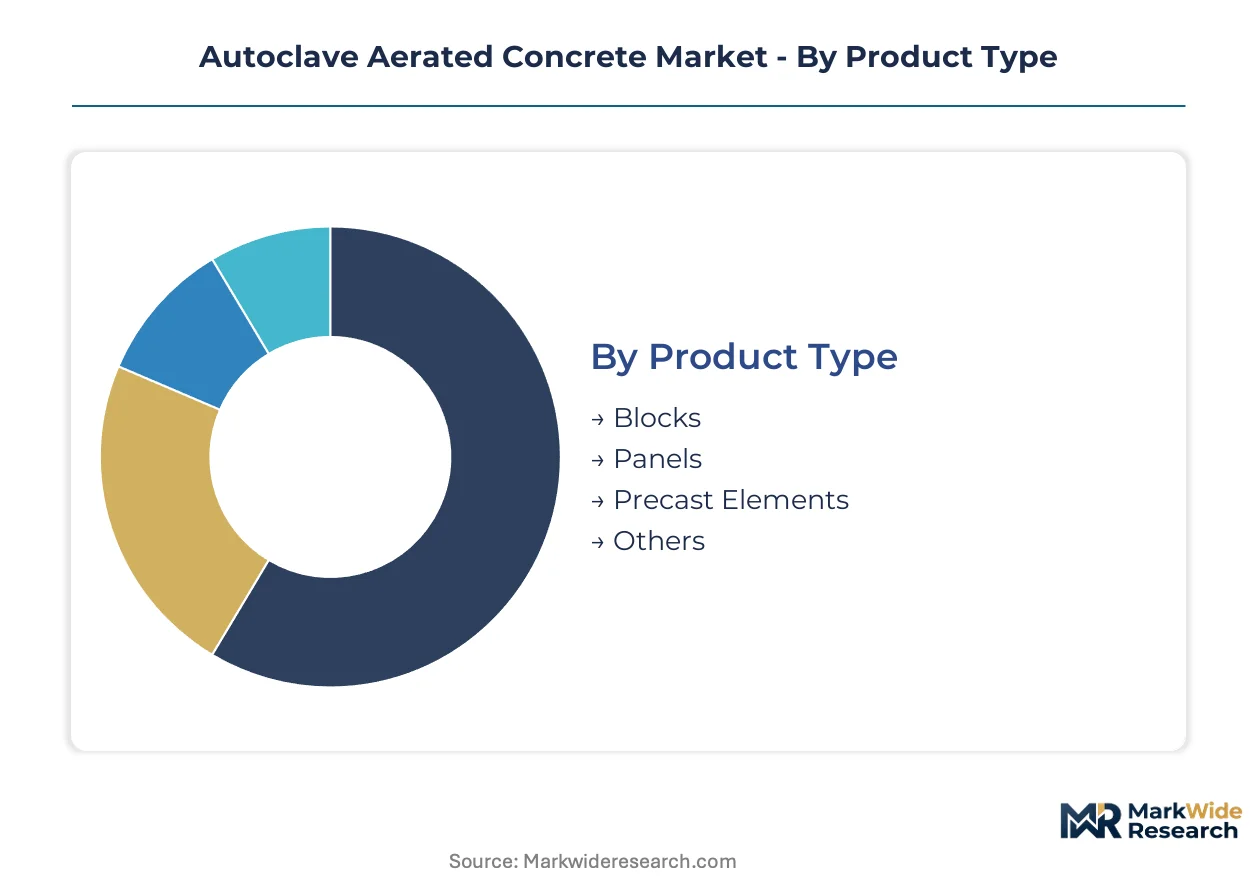
The Autoclave Aerated Concrete market categorizes products and applications to reflect diverse industry requirements and consumption patterns. Understanding these segments helps manufacturers tailor offerings and optimize distribution strategies. This detailed segmentation highlights where product innovation and market demand intersect across various construction activities.
Product Type:
The intensity of after-sales service requirements varies significantly across different AAC product types, influencing manufacturer support structures and customer engagement models.
- Blocks:These are the most common form of AAC, typically used for non-load-bearing walls and infill panels. Blocks are produced with a microporous structure from sand, cement, lime, and an expansion agent. Demand concentrates in residential construction in Southeast Asian nations like Vietnam, driven by rapid urbanization and the need for efficient walling systems.
- Panels:Reinforced, large-format AAC panels offer structural and insulation properties, often used in commercial facades and industrial wall systems. These panels reduce on-site labor and construction time, finding strong demand in European commercial projects seeking faster building envelope completion.
- Precast Elements:These include custom-shaped AAC components designed for specific architectural or structural requirements. Precast elements offer design flexibility for specialized building projects.
- Others:This segment encompasses niche AAC products, including lintels, floor elements, and specialized insulation boards. These products address specific construction challenges.
By volume, Blocks leads. By growth pace, Panels is ahead.
End User:
The cost tier of construction projects directly influences the specification of AAC products, with different end-user segments exhibiting distinct budget considerations and performance expectations.
- Residential:This sector includes single-family homes, multi-story apartments, and housing developments. Residential construction remains the principal end user for AAC, driven by the need for thermal insulation in new builds and renovations.
- Commercial:This segment comprises office buildings, retail spaces, hotels, and educational institutions. Commercial applications increasingly use large-format AAC panels for faster construction and energy efficiency compliance, particularly in European markets adhering to the EU Green Deal mandates.
- Industrial:Industrial facilities, such as factories, warehouses, and power plants, utilize AAC for its fire resistance and insulation properties. These applications often prioritize durability and safety standards.
- Infrastructure:Public works projects, including sound barriers, tunnel linings, and utility buildings, employ AAC for its lightweight properties and ease of installation. Infrastructure projects benefit from reduced structural load.
A significant portion of revenue stems from Residential, while Commercial exhibits the most dynamic expansion.
Application:
The sheer volume of material required for different applications dictates the scale of AAC production and delivery logistics for various construction functions.
- Wall Construction:This application includes both interior and exterior walls in various building types. AAC blocks constitute the largest product segment for wall construction due to their thermal performance and ease of handling.
- Partition Walls:These non-load-bearing internal walls separate rooms within a structure. AAC is favored for partition walls due to its lightweight nature and acoustic insulation properties, offering design flexibility for diverse building types.
- Roof Construction:AAC is used for roof elements, providing insulation and structural support. This application helps reduce overall building weight and improves thermal performance.
- Floor Construction:AAC floor panels contribute to thermal and acoustic insulation in multi-story buildings. Floor construction applications benefit from the material's lightweight characteristics.
The largest share of demand originates from Wall Construction, with Partition Walls showing considerable traction.
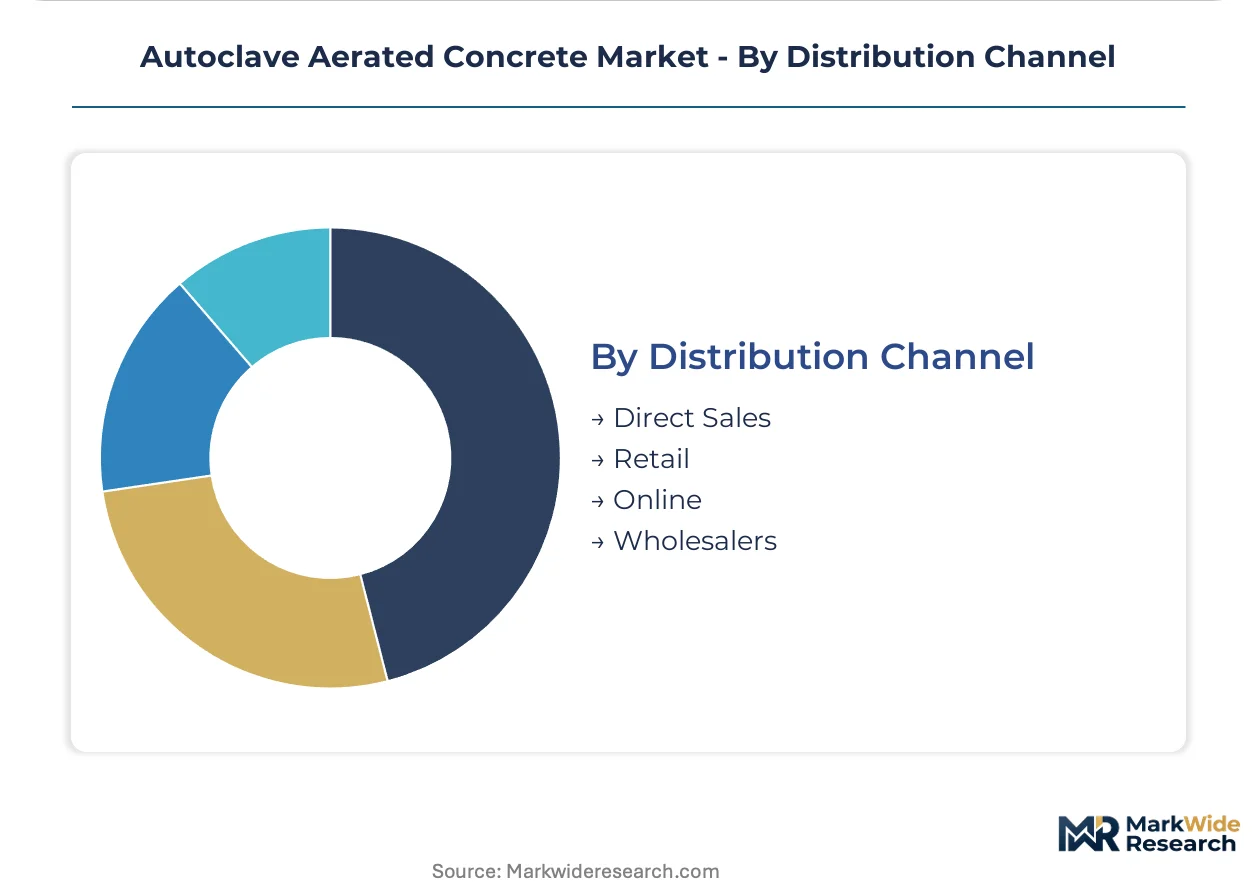
Distribution Channel:
The type of customer served significantly shapes the preferred distribution channel, ranging from large contractors to individual homeowners, each requiring different logistical and sales approaches.
- Direct Sales:Manufacturers engage directly with large construction companies, developers, and government projects. This channel facilitates bulk orders and customized solutions for major building initiatives.
- Wholesalers:Wholesalers purchase AAC products in large quantities from manufacturers and distribute them to smaller contractors, retailers, and local building material suppliers. This channel provides broad market penetration.
- Retail:Retail outlets, including hardware stores and building material chains, make AAC products accessible to individual builders and smaller-scale projects. Retail serves a fragmented customer base.
- Online:E-commerce platforms facilitate direct purchases by contractors and individuals, offering convenience and potentially wider product selection. Online channels are gaining traction for specialized orders.
The majority of product movement occurs through Direct Sales, and Wholesalers demonstrates a strong trajectory for future growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential builders and commercial developers represent a significant buyer archetype for Autoclave Aerated Concrete across diverse geographies. These buyers prioritize materials offering energy efficiency and rapid construction, aligning with modern building standards. Specific regional dynamics influence material specification and project scale for AAC.
Germany
German construction demand for AAC arises from stringent energy efficiency mandates in residential and commercial sectors. The EU Green Deal and CE marking requirements drive specification for high thermal performance materials. In Bavaria, sustainable building initiatives are integrating AAC panels for their insulation and structural benefits.
India
India's rapid urbanization and affordable housing initiatives create substantial demand for AAC blocks. The BIS requirements and India's Energy Conservation Building Code set performance criteria for thermal and structural properties. Around Mumbai, large-scale residential projects increasingly adopt AAC for faster construction and thermal insulation.
Vietnam
Vietnam exhibits strong demand for AAC due to rapid urban development and infrastructure expansion. National building codes increasingly support materials that reduce construction time and improve energy performance. In Ho Chi Minh City, high-rise residential developments extensively utilize AAC blocks for efficient walling systems.
United States
United States construction seeks AAC for improved energy efficiency and fire resistance in new builds. ASTM International standards govern AAC properties, while evolving building codes favor non-combustible materials. California's seismic zones benefit from AAC's lightweight properties for resilient and safer building structures.
Autoclave Aerated Concrete Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the Autoclave Aerated Concrete market structure. The market exhibits a tiered structure, with large diversified construction material groups alongside focused AAC manufacturers. Strategic archetypes include integrated cement producers, European AAC specialists, and regional building material suppliers. Capacity expansion and strategic partnerships are dominant competitive moves to secure market share and optimize logistics.
Within the integrated materials tier, UltraTech Cement Ltd. anchors its market position in India, representing a diversified construction materials group with a vast distribution network. Xella International exemplifies a European AAC specialist, leveraging an extensive production footprint and continuous R&D in high-performance panels across Europe. H+H International also occupies a strong position among European manufacturers, specializing in a comprehensive range of AAC products for diverse construction applications. These companies collectively illustrate the scale and regional focus required to succeed in the AAC market.
| Leading Market Players |
|---|
| Xella International |
| H+H International |
| UltraTech Cement Ltd. |
| ACICO Group |
| Biltech Building Elements Limited |
| JK Lakshmi Cement Ltd. |
| CSR Ltd. |
| Masa Group |
| Tarmac Building Products Limited |
| Others |
Cost & Logistics Intelligence
Volatile energy prices, particularly for natural gas, concentrate upstream cost pressures, directly impacting manufacturer margins across global Autoclave Aerated Concrete markets.
Pricing Analysis
Cost-plus contract structures, often indexed to regional energy and raw material prices, define many large-volume AAC procurement agreements. Price differentiation stems from product quality, validated by certifications like CE marking and ASTM International standards, alongside geographic delivery costs. Pricing softness reflects intense competition from substitute materials, such as Insulated Concrete Forms. Residential builders typically exhibit the highest price sensitivity, while commercial and industrial projects prioritize performance specifications.
Supply Chain Analysis
The upstream supply chain for Autoclave Aerated Concrete relies heavily on regionally sourced sand, cement, and lime. Production facilities in India and Europe draw from local raw material deposits. Commodity price volatility for natural gas and electricity presents a significant structural risk for manufacturers. Distribution runs through a dual model, with direct sales to large construction firms and wholesalers serving smaller contractors and retail outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Autoclave Aerated Concrete market is experiencing a buyer-power shift, driven by the increasing consolidation among large-scale commercial and infrastructure project developers.
For Market Incumbents: Entrench market share by expanding production capacity in high-demand urban centers, particularly across Southeast Asia and India. Invest in R&D for advanced lightweight formulations to counter the threat from substitute materials like ICFs. Secure long-term energy supply contracts to mitigate volatile natural gas prices. Strengthen distribution networks in emerging markets to maintain channel control.
For New Entrants and Emerging Players: Build out market presence by targeting underpenetrated North American residential and commercial segments, leveraging evolving energy codes. Focus on developing large-format AAC panels for commercial facades and industrial wall systems. A go-to-market angle emphasizing digital twins and BIM integration for architects offers a distinct competitive advantage. Penetrate seismic zones in Japan and the US West Coast with lightweight solutions.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated AAC manufacturers with strong European R&D capabilities and established distribution networks in high-growth Asian markets. Companies demonstrating leadership in digital quality assurance systems present attractive long-term viability. The signal to watch is the accelerated adoption of AAC panels in prefabrication and modular construction projects, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Meets rapid urbanization demand in Vietnam and Indonesia for efficient walling systems. |
| R&D in Large-Format Panels | Expands AAC application beyond blocks into commercial facades and industrial systems. |
| Digital Quality Assurance Integration | Narrows performance variability, enhancing product consistency across manufacturers. |
| Strategic Partnerships with Prefabricators | Accelerates adoption of AAC in modular construction, compressing on-site schedules. |
| North American Market Penetration | Captures demand from changing building codes favoring energy efficiency and fire resistance. |
Research Approach
A spread of perspectives from construction project managers, material scientists, and building code officials converged on the working assumptions for this Autoclave Aerated Concrete market analysis. Primary interviews with procurement leads at large construction firms and architects were combined with secondary validation from ASTM International standards, CE marking documentation, and national building codes. This approach ensured bottom-up and top-down triangulation for robust data.
The demand-supply balance for Autoclave Aerated Concrete was meticulously modeled across the analysis window, integrating historical consumption with production capacities. Segmentation dimensions included product type, end-user, application, and regional market maturity. Compound annual growth rates were derived from historical trends, market drivers like urbanization rates, and expert projections on infrastructure spending and energy efficiency mandates.
Sensitivities concentrate around volatile raw material costs and evolving global building energy codes. Forecasts reflect these assumptions, but significant shifts in energy prices or building material regulations could revise projections. Cross-checking against national construction output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
US Metal Stadium Seating Market