
 Cement Tiles Market | 2026-2036
Cement Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Tiles Market Analysis
Digital patterning technology is reshaping how cement tiles achieve design fidelity at production scale. K.G. Group leverages automated hydraulic pressing to sustain consistent thickness tolerance across large-format decorative runs. Granada Tile anchors its competitive position through deep specialization in hand-poured encaustic methods for heritage restoration projects. Bisazza SpA extends its design influence by controlling exclusive pigment supply partnerships with Italian color houses.
Cement tiles are composite surfacing elements manufactured from Portland cement, fine sand, mineral pigments, and marble dust aggregates, hydraulically pressed and air-cured to achieve densities between 1,800 and 2,200 kg per cubic meter. Their primary commercial purpose spans interior flooring, wall cladding, and architectural decorative elements where moisture resistance and artisan aesthetics converge. Handmade tiles occupy the premium margin tier due to labor intensity and batch uniqueness, while machine-made tiles dominate volume throughput for commercial flooring specifications. Decorative and patterned tiles represent the fastest-growing product category as designers specify statement surfaces for hospitality and residential environments.
The European Chemicals Agency enforces REACH pigment safety standards that restrict heavy metal content in decorative tile colorants, compelling reformulation across export-oriented manufacturers. Vietnam's Ministry of Construction maintains GB-equivalent cement product standards that govern dimensional stability and abrasion resistance for both domestic use and re-export. India's Bureau of Indian Standards certifies cement-based tile products under IS 1237 for flexural strength and water absorption thresholds. Stakeholders must monitor evolving chemical compliance regimes while calibrating production investments between artisan capacity and automated scale.
Market Dynamics
REACH compliance is compressing formulation flexibility across European supply chains while artisan production clusters in Vietnam absorb displaced export volume from reformulating manufacturers.
Growth Catalysts
- Heritage restoration mandates:Mediterranean municipalities specify handmade encaustic tiles for protected building renovations, creating protected demand channels immune to machine-made substitution.
- REACH pigment reformulation:ECHA enforcement of heavy metal restrictions is accelerating R&D investment in mineral-based colorant alternatives that command premium positioning.
- Hospitality specification surge:Boutique hotel designers across Portugal and Morocco specify statement patterned floors as signature interior elements, concentrating procurement in decorative tile specialists.
Market Restraints
- White cement price volatility:Energy-intensive kiln operations for clinker production expose margins to natural gas cost swings in European manufacturing bases.
- Artisan labor scarcity:Ho Chi Minh City tile clusters face generational skill attrition as younger workers migrate to electronics assembly, constraining handmade batch capacity.
- Porcelain tile substitution:Thin-format digital-print ceramics from Italian producers capture commercial flooring specifications through lower installed weight and faster setting times.
Strategic Opportunities
- Carbon-capture curing:Mineral carbonation during air-curing phases offers pathway to negative-emission product certification under EU Green Deal construction material standards.
- Direct-to-designer platforms:Digital pattern libraries connecting Ho Chi Minh artisans with European interior architects bypass traditional distributor markups and compress lead times.
- GB-equivalent export alignment:Vietnam's Ministry of Construction standards harmonization with Chinese construction material codes opens cross-border specification in ASEAN infrastructure projects.
Industry Challenges
- Pigment chemistry retooling:REACH-compliant colorant validation timelines extend new product development cycles by 8-14 months for export-oriented manufacturers.
- Dimensional consistency at scale:Automated hydraulic pressing achieves thickness tolerance but sacrifices surface variation prized by heritage restoration clients, forcing parallel production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Tiles Market |
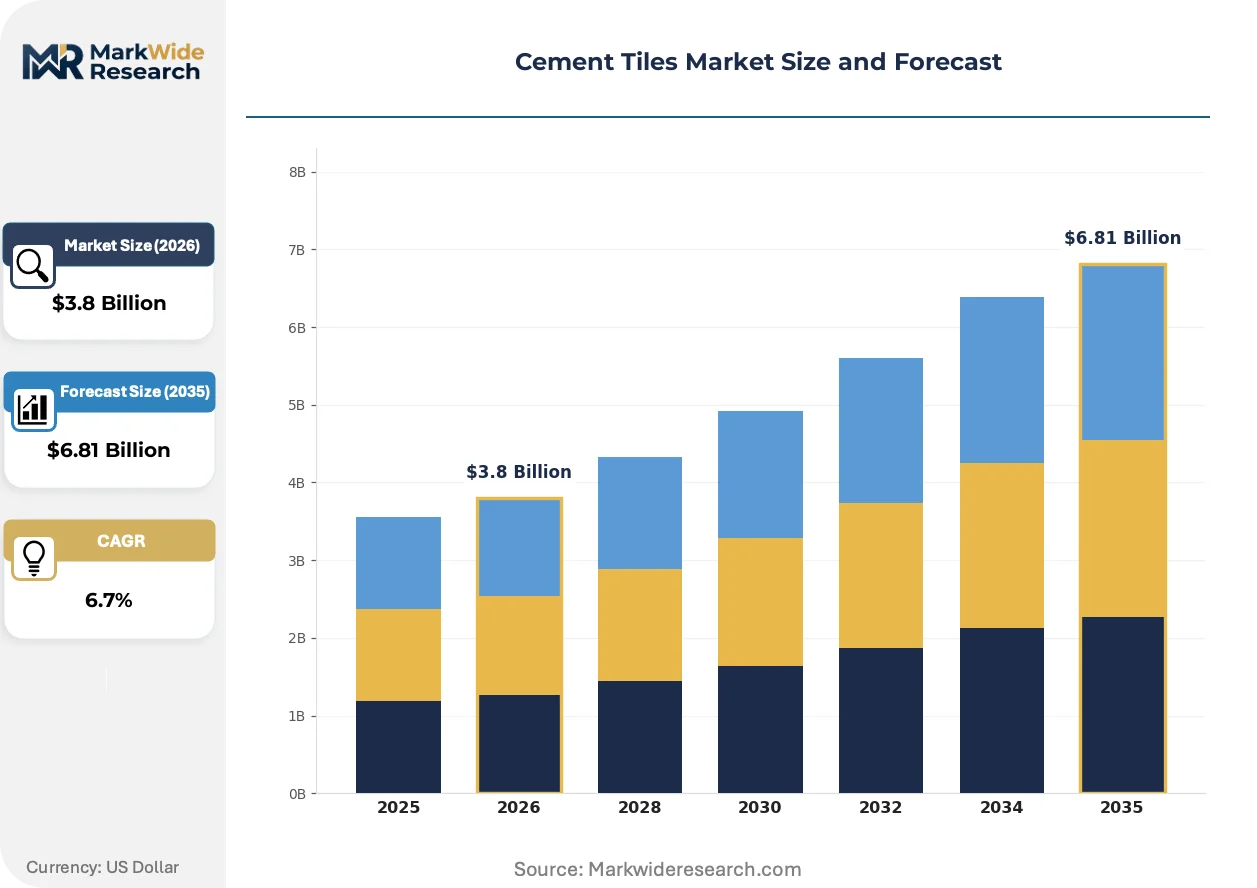
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handmade Tiles, Machine-made Tiles, Decorative Tiles, Patterned Tiles Material: Cement, Sand, Pigments, Aggregates End User: Residential, Commercial, Industrial, Institutional Application: Flooring, Wall Cladding, Outdoor Spaces, Decorative Elements |
| Companies Covered | K.G. Group, Mosafil GmbH, H & R Johnson, Villa Lagoon Tile, Granada Tile, Wausau Tile, Sabine Hill, Hindustan Marble and Granite, Bisazza SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Tiles Market Emerging Trajectories
Digital design-to-production workflows are dissolving the traditional boundary between artisan pattern development and scalable manufacturing execution.
Water-jet cutting integration with CNC patterning is collapsing the cost differential between custom geometric layouts and standard repeating motifs. High-end residential developers in Barcelona and Lisbon specify site-specific floor designs without the historical labor premium. The technology is collapsing the artisan premium tier into mid-market accessibility.
REACH Annex XVII restrictions on cadmium and lead-based pigments entered full enforcement across EU member states in 2023. Export manufacturers serving European hospitality chains must maintain dual pigment inventories or abandon saturated colorways entirely. Italian color houses with pre-qualified mineral alternatives capture specification influence from reformulating competitors.
Architects now source cement tiles through aggregated material platforms that bundle specification, sampling, and freight coordination. Traditional tile distributors in France and Spain lose specification influence to digital procurement channels that compress vendor comparison cycles from weeks to days. The shift concentrates purchasing power among platforms with exclusive Ho Chi Minh City manufacturing partnerships.
Cement Tiles Market Segmentation
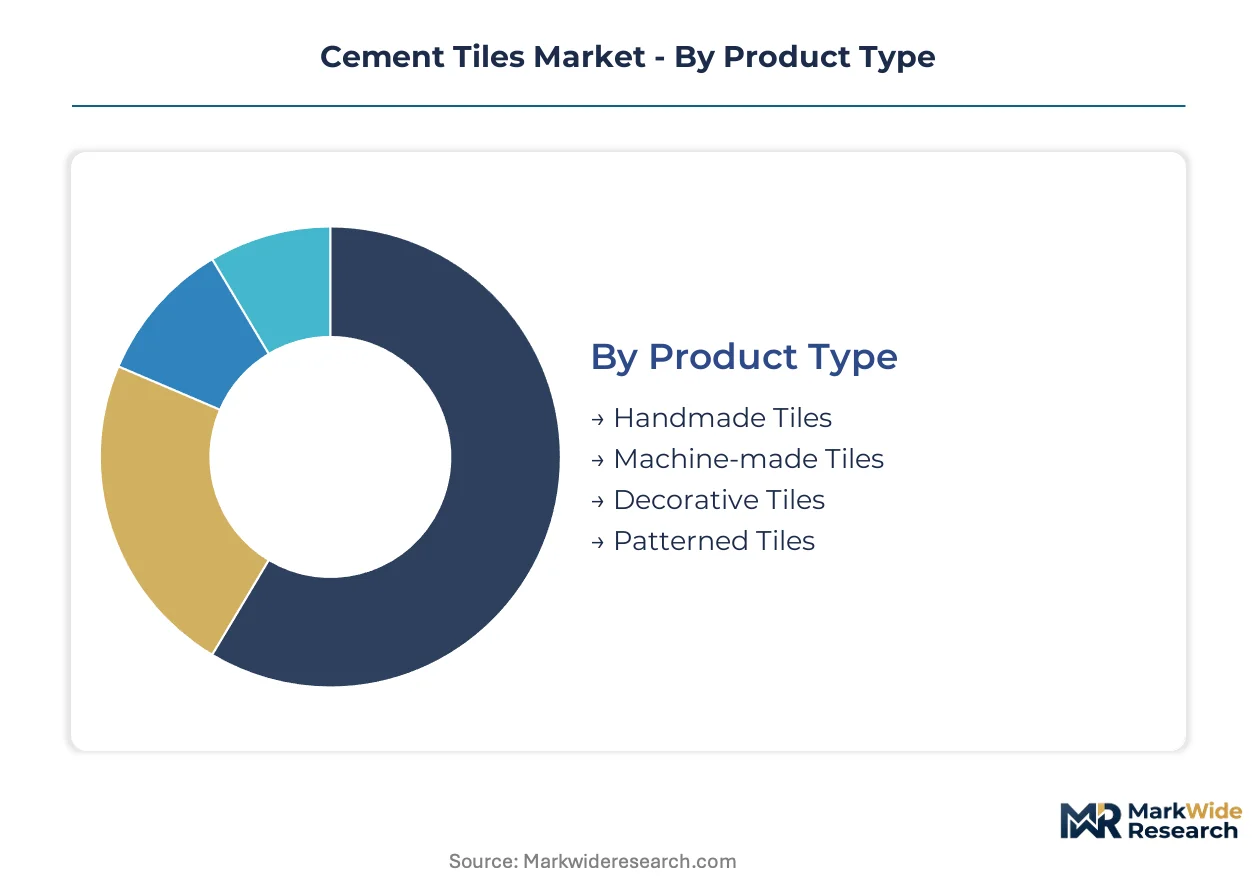
Cement tiles fragment across production method, material composition, and end-use intensity. Each dimension carries distinct margin profiles and specification cycles that reshape procurement patterns across Mediterranean renovation and Southeast Asian manufacturing clusters.
Product Type:
Handmade tiles turn inventory slowest due to batch variability and restoration-mandate procurement timelines, while machine-made tiles rotate fastest through commercial flooring channels.
- Handmade Tiles:Individual molds receive hand-poured pigment layers before hydraulic pressing, yielding surface variation prized for heritage authenticity. Lisbon and Barcelona restoration contractors specify these for protected building compliance, absorbing 14-18 week lead times as a project cost.
- Decorative Tiles:Statement surfaces with complex multi-color patterns command specification influence from boutique hospitality designers in Portugal and Morocco. Water-jet cutting integration is collapsing the labor premium for custom geometries, accelerating adoption in high-end residential developments.
- Machine-made Tiles:Automated hydraulic pressing achieves consistent 1,800-2,200 kg/m³ density for commercial flooring volume.
- Patterned Tiles:Repeating geometric motifs serve cost-sensitive renovation segments through standardized production runs.
Machine-made tiles dominate installed base across commercial flooring specifications. Decorative tiles are where expansion concentrates as digital patterning erodes the artisan premium tier.
Material:
Cost tier stratification runs from commodity white cement through REACH-compliant mineral pigments that reformulation mandates have pushed into premium positioning.
- Pigments:Mineral-based colorants from Italian supply partnerships now capture specification influence as ECHA enforcement eliminates cadmium and lead-based alternatives. Export manufacturers serving European hospitality chains maintain dual inventories or abandon saturated colorways entirely.
- Cement:Portland cement binder constitutes 60-70% of tile mass, exposing margins to energy-intensive clinker production cost swings.
- Sand:Fine silica aggregate governs surface texture and abrasion resistance under Vietnam's GB-equivalent standards.
- Aggregates:Marble dust inclusion elevates density and polishability for premium flooring applications.
Cement dominates installed base by mass volume. Pigments are where margin expansion concentrates as compliance-driven reformulation reshapes supplier qualification.
End User:
Volume concentration sits with commercial flooring specifications, while residential renovation cycles drive pattern innovation through direct-to-designer procurement channels.
- Residential:Mediterranean homeowners specify statement patterned floors as signature interior elements, concentrating procurement in specialists with Ho Chi Minh City manufacturing partnerships. Digital platforms now compress vendor comparison cycles from weeks to days.
- Commercial:Boutique hotel designers across Portugal and Morocco drive decorative tile specification as brand differentiation tools.
- Industrial:Abrasion-resistant machine-made tiles serve manufacturing facility flooring with minimal aesthetic specification.
- Institutional:Heritage restoration mandates in protected building zones create protected demand channels immune to substitution.
Commercial applications dominate installed base across hospitality and retail flooring. Residential end-use is where specification innovation concentrates as digital procurement dissolves traditional distributor influence.
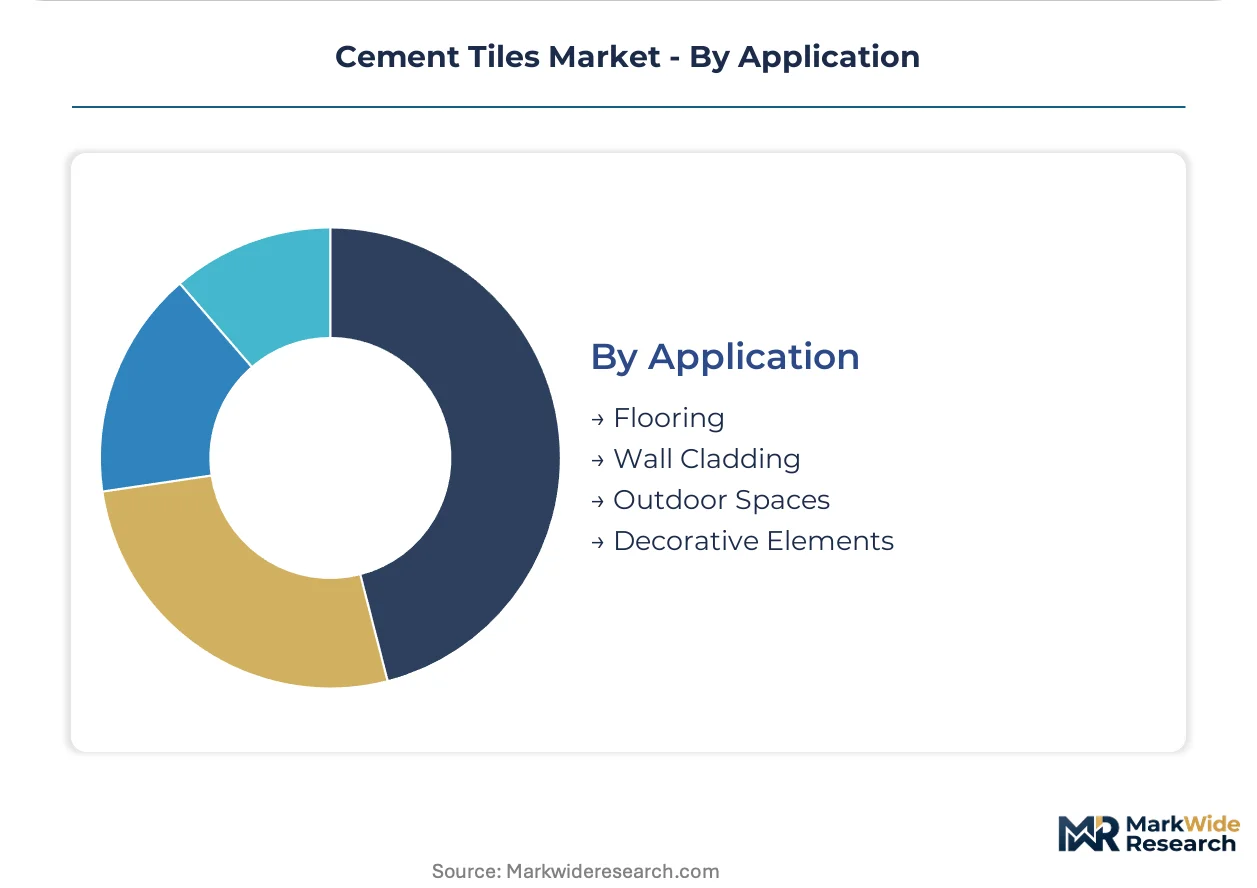
Application:
Margin structure inverts across the install surface — flooring absorbs volume throughput while decorative elements capture design-fee premiums through architectural specification.
- Flooring:Interior and exterior surfacing specifications demand dimensional stability under Vietnam's Ministry of Construction abrasion resistance standards. Thin-format porcelain substitution threatens commercial share through lower installed weight and faster setting times.
- Wall Cladding:Vertical installations emphasize lighter weight aggregates and reduced thickness profiles for seismic compliance.
- Outdoor Spaces:Freeze-thaw resistance and slip coefficient ratings govern terrace and courtyard specifications in Northern European climates.
- Decorative Elements:Bespoke architectural features such as column bases and frieze panels command project-specific pattern development fees.
Flooring dominates installed base across residential and commercial construction. Decorative elements are where value-per-square-meter expansion concentrates as architects specify site-specific designs without historical labor premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports handmade cement tiles to European hospitality chains and Mediterranean restoration contractors, with Ho Chi Minh City manufacturing clusters absorbing displaced volume from REACH-reformulating producers.
Italy
Heritage restoration mandates in Rome and Florence drive specification of hand-poured encaustic tiles for protected building renovations. ECHA REACH Annex XVII enforcement restricts cadmium and lead-based pigments, compelling reformulation partnerships with domestic color houses. Italian manufacturers in Emilia-Romagna and Tuscany maintain dual pigment inventories to serve both domestic heritage projects and export hospitality chains.
Spain
Barcelona and Lisbon residential developers specify statement patterned floors as signature interior elements, concentrating procurement in specialists with Southeast Asian manufacturing partnerships. The country's national construction standards govern dimensional stability and abrasion resistance for both domestic installation and re-export specifications. Valencia and Andalusia host distributor networks losing specification influence to digital procurement platforms.
Portugal
Boutique hotel designers across Lisbon and Porto drive decorative tile specification as brand differentiation tools, creating protected demand channels immune to machine-made substitution. EU Green Deal construction material standards incentivize carbon-capture curing certifications for export-oriented manufacturers. The Algarve region concentrates hospitality renovation cycles that absorb 14-18 week handmade tile lead times.
Vietnam
Artisan manufacturing clusters near Ho Chi Minh City supply handmade tiles to European heritage restoration and hospitality specification channels. The Ministry of Construction maintains GB-equivalent cement product standards governing dimensional stability and abrasion resistance for re-export certification. Generational skill attrition constrains handmade batch capacity as younger workers migrate to electronics assembly.
Morocco
Hospitality developers in Marrakech and Casablanca specify complex multi-color patterned tiles for boutique hotel interiors, sourcing through direct-to-designer platforms that bypass traditional distributor markups. The country's national construction material regulator enforces import standards aligned with European technical specifications. Fez and Meknes retain traditional artisan production methods serving both domestic heritage projects and export decorative markets.
Cement Tiles Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: automated hydraulic pressing specialists achieving dimensional consistency at scale, hand-poured encaustic artisans serving heritage restoration mandates, and pigment-integrated design houses controlling colorant supply partnerships. Dominant competitive moves include exclusive manufacturing partnerships with Ho Chi Minh City clusters and REACH-compliant pigment pre-qualification to capture specification influence from reformulating competitors.
Among Italy-based specialists, Bisazza SpA occupies a position exemplifying pigment-integrated design influence through exclusive supply partnerships with domestic color houses. Granada Tile represents the hand-poured encaustic archetype, anchoring competitive positioning through deep specialization in heritage restoration methods. K.G. Group sits within the automated scale tier, leveraging hydraulic pressing technology for consistent thickness tolerance across large-format decorative production runs.
| Leading Market Players |
|---|
| K.G. Group |
| Mosafil GmbH |
| H & R Johnson |
| Villa Lagoon Tile |
| Granada Tile |
| Wausau Tile |
| Sabine Hill |
| Hindustan Marble and Granite |
| Bisazza SpA |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Ho Chi Minh City artisan clusters is compressing batch availability and elevating handmade tile premiums, while automated hydraulic pressing capacity in European bases runs excess and forces price competition in machine-made tiers.
Pricing Analysis
The pricing gap between hand-poured encaustic methods and automated hydraulic pressing defines market stratification, with water-jet CNC integration collapsing the middle tier. Three-tier pricing structure across premium handmade, standard machine-made, and economy patterned levels separates heritage restoration budgets from commercial flooring specifications. Price differentiation hinges on REACH-compliant pigment certification and artisan labor intensity. Cost compression in machine-made tiers is intensifying because thin-format porcelain substitution erodes specification share. Commercial flooring contractors exhibit highest price sensitivity, while heritage restoration mandates absorb premium positioning.
Supply Chain Analysis
Tariff exposure between Vietnam and European Union member states dominates supply chain risk calculus for export-oriented manufacturers serving hospitality chains. Production gravity centers on Vietnam, Italy, and Spain, with raw material dependencies on Portland cement clinker, mineral pigments from Italian color houses, and fine silica aggregate. Single-source vulnerability concentrates in REACH-compliant pigment supply partnerships. Distribution runs through digital procurement platforms that bypass traditional French and Spanish distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cement tiles market functions as a service-attach opportunity where direct-to-designer pattern libraries and site-specific custom geometry services expand faster than commodity tile throughput.
For Market Incumbents: Build exclusive Ho Chi Minh City manufacturing partnerships as the defensive moat against platform-based competitors. Secure REACH-compliant pigment pre-qualification to capture specification influence from reformulating rivals. Add automated hydraulic pressing capacity in Vietnam to hedge European energy cost volatility. Deepen backward integration into mineral pigment supply to control colorant access. For New Entrants and Emerging Players: Pursue carbon-capture curing certification as the entry wedge for EU Green Deal construction material specifications. Target boutique hospitality renovation cycles in Portugal and Morocco where brand differentiation budgets absorb premium positioning. Deploy water-jet CNC patterning to collapse custom geometry premiums without artisan labor dependency. For Investors and Strategic Acquirers: Capital is best deployed toward pigment-integrated design houses with exclusive Italian color house partnerships across the 5-10 year viability window. Monitor ECHA enforcement intensity as the inflection signal for mineral-based colorant supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Pigment Pre-Qualification | ECHA enforcement eliminates cadmium alternatives and rewards pre-qualified Italian color house partnerships. |
| Exclusive Ho Chi Minh City Manufacturing Partnership | Platform procurement concentrates purchasing power among clusters with direct artisan access. |
| Carbon-Capture Curing Certification | EU Green Deal construction standards create negative-emission product differentiation for export specifications. |
| Water-Jet CNC Patterning Integration | Barcelona and Lisbon developers now specify site-specific designs without historical labor premiums. |
| Direct-to-Designer Digital Platform Launch | Aggregated material platforms compress vendor comparison cycles from weeks to days for Mediterranean architects. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tile manufacturing plant managers, heritage restoration contractors, hospitality procurement leads, and Italian color house technical directors; and secondary validation against Vietnam Ministry of Construction standards filings, ECHA REACH Annex XVII regulatory updates, and customs trade data for cement tile re-export volumes. Bottom-up triangulation across production cluster capacity assessments and top-down demand modeling across Mediterranean renovation cycles anchored value estimates.
Forecast inputs span production method segmentation, material composition tiers, end-use intensity across residential and commercial channels, and application surface distribution. CAGRs were derived from capacity-utilization trends in Ho Chi Minh City clusters and specification velocity in Portuguese hospitality renovation. Industry-specific inputs include artisan labor attrition rates and REACH reformulation timeline impacts on new product development cycles throughout the forecast period.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing for European clinker production or Vietnamese electronics assembly wage growth would shift the trajectory. Forecasts reflect assumptions around ECHA enforcement continuity and GB-equivalent standards harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Roofing and Insulation Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
France Architectural Coatings Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Qatar Facade Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Spain Cement Market
Building Materials
HDG Steel Pipe Market
Building Materials
Foam Concrete Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
East Africa White Cement Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Portland Cement Market