
 Mass Timber Construction Market | 2026-2036
Mass Timber Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Timber Construction Market Analysis
Canadian glulam and cross-laminated timber producers is expanding manufacturing footprints to serve accelerating North American project pipelines. Element5 leverages integrated design-build capabilities across the value chain. Swinerton Incorporated anchors large-scale commercial timber construction with established union labor networks. Hasslacher Norica Timber dominates European supply of engineered timber components exported to premium North American developments.
Mass timber construction employs engineered wood products—cross-laminated timber panels typically 3-9 layers thick, glued laminated timber beams, and laminated veneer lumber—fabricated under controlled moisture and pressure conditions to achieve structural performance comparable to steel and concrete for mid-rise and tall building applications. Cross-laminated timber leads product type adoption in multi-family residential and commercial structures due to established supply chains and code familiarity, while hybrid systems combining timber with steel or concrete connections represent the fastest-growing technology segment as engineers push height and span boundaries. Prefabrication concentrates margin pools with manufacturers controlling digital fabrication workflows and panelized delivery logistics.
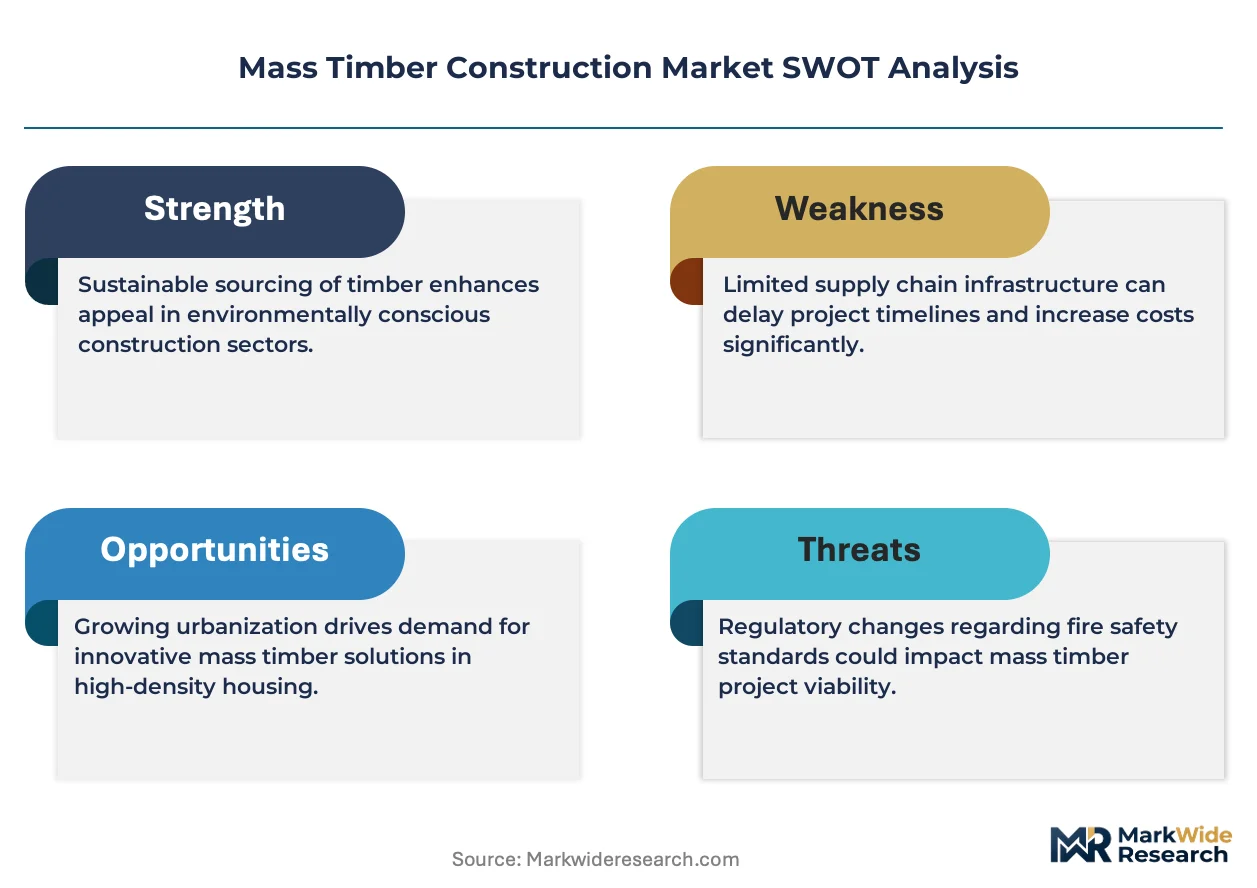
Federal procurement guidelines from the US General Services Administration and Canada's National Building Code both mandate embodied carbon disclosure for major construction, directly steering public project awards toward mass timber alternatives. The International Code Council's tall wood building provisions, adopted variably by state and provincial jurisdictions, create a patchwork compliance environment that shapes manufacturer certification investments and project feasibility assessments. Stakeholders must monitor code harmonization progress and carbon accounting standard convergence to time capacity commitments and geographic market entry decisions.
Market Dynamics
The International Building Code's Type IV-A, IV-B, and IV-C construction categories have removed height restrictions that previously capped wood structures at six stories, triggering a fundamental reallocation of capital toward engineered timber systems in mid-rise development.
Growth Catalysts
- Type IV-A Construction Category:The International Building Code permits mass timber buildings up to 18 stories, unlocking high-rise residential and commercial applications previously reserved for steel and concrete.
- Federal Embodied Carbon Mandates:The US General Services Administration requires carbon disclosure for major construction projects, steering public procurement toward low-carbon mass timber alternatives.
- Pacific Northwest Supply Chain Density:Concentrated engineered wood manufacturing in Oregon, Washington, and British Columbia reduces logistics costs and accelerates project delivery timelines.
Market Restraints
- Adhesive Cost Volatility:Cross-laminated timber production depends on polyurethane and phenolic resins, exposing manufacturers to petrochemical price swings that compress margins.
- European Import Concentration:Premium glulam beam supply for North American tall wood projects relies heavily on Austrian and German producers, creating single-source vulnerability.
- Fire-Rating Technical Limitations:Current mass timber assemblies require additional encapsulation to achieve three-hour fire ratings, adding material cost and construction complexity.
Strategic Opportunities
- Underpenetrated Southeastern US:States like Georgia and North Carolina lack mature mass timber supply chains but possess abundant softwood feedstock and growing metropolitan construction pipelines.
- Hybrid Structural Systems:Convergence of mass timber with post-tensioned concrete cores and steel moment frames enables taller buildings while maintaining carbon advantages.
- Canada's Green Building Strategy:Federal incentives for net-zero construction create direct procurement preference for mass timber in government and institutional projects.
Industry Challenges
- Specialized Design-Build Talent Scarcity:Project success requires architects and engineers with integrated timber-structural expertise, a skill set concentrated in Pacific Northwest and select European firms.
- Multi-Jurisdiction Certification Complexity:Manufacturers must navigate varying state and provincial adoption timelines for the International Building Code tall wood provisions, fragmenting quality assurance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Timber Construction Market |
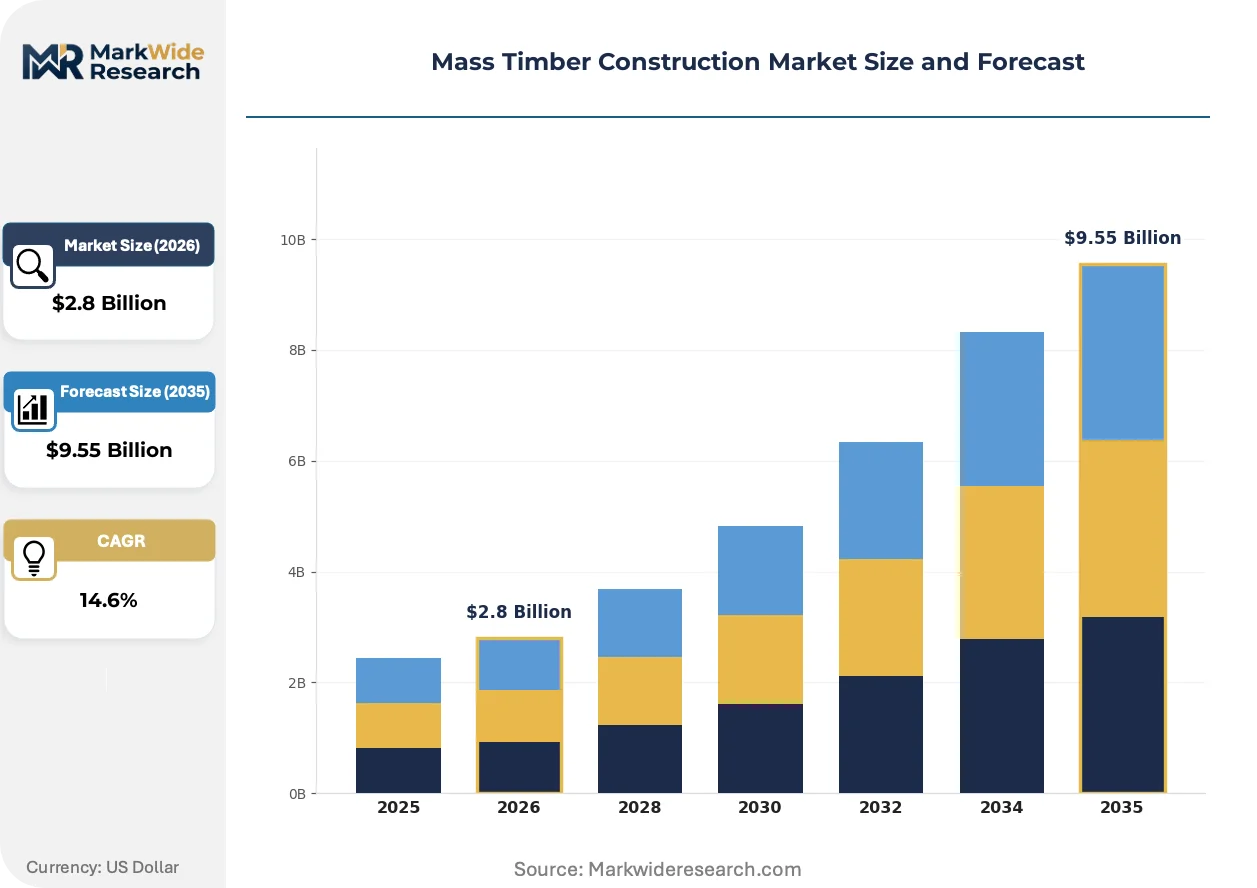
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Laminated Timber, Glulam, Laminated Veneer Lumber, Nail-Laminated Timber Application: Residential Buildings, Commercial Structures, Institutional Facilities, Industrial Construction End User: Architects, Contractors, Developers, Government Agencies Technology: Prefabrication, Modular Construction, Hybrid Systems, Digital Fabrication |
| Companies Covered | Element5, DLR Group, Swinerton Incorporated, Gensler, LEVER Architecture, Timberlab Inc., Hasslacher Norica Timber, Thornton Tomasetti, SmartLam North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Timber Construction Market Emerging Trajectories
Digital fabrication workflows are compressing traditional construction timelines by shifting structural assembly from job sites to controlled factory environments, fundamentally altering where value accumulates in the building delivery chain.
Hybrid mass timber systems combining cross-laminated timber floor plates with steel perimeter frames and concrete core walls are expanding into 18-25 story commercial and residential towers. Developers in Vancouver, Portland, and Minneapolis are specifying these assemblies to capture carbon reduction metrics while meeting stringent lateral load requirements. The technology is expanding into markets previously considered unreachable for pure timber construction.
The European Union's Construction Products Regulation now requires Environmental Product Declarations for structural materials in public buildings, creating compliance pressure that favors mass timber over conventional concrete and steel. Manufacturers exporting to EU markets must certify through notified bodies under harmonized EN standards. North American producers with European certifications are capturing premium positioning in both continental and export markets.
Institutional investors and pension funds are embedding embodied carbon thresholds into real estate acquisition criteria, forcing developers to document lifecycle emissions before capital commitment. This behavioral shift compresses the window for material substitution decisions to early design phases. The phenomenon is most visible in British Columbia and California, where public pension capital dominates large-scale commercial development financing.
Mass Timber Construction Market Segmentation
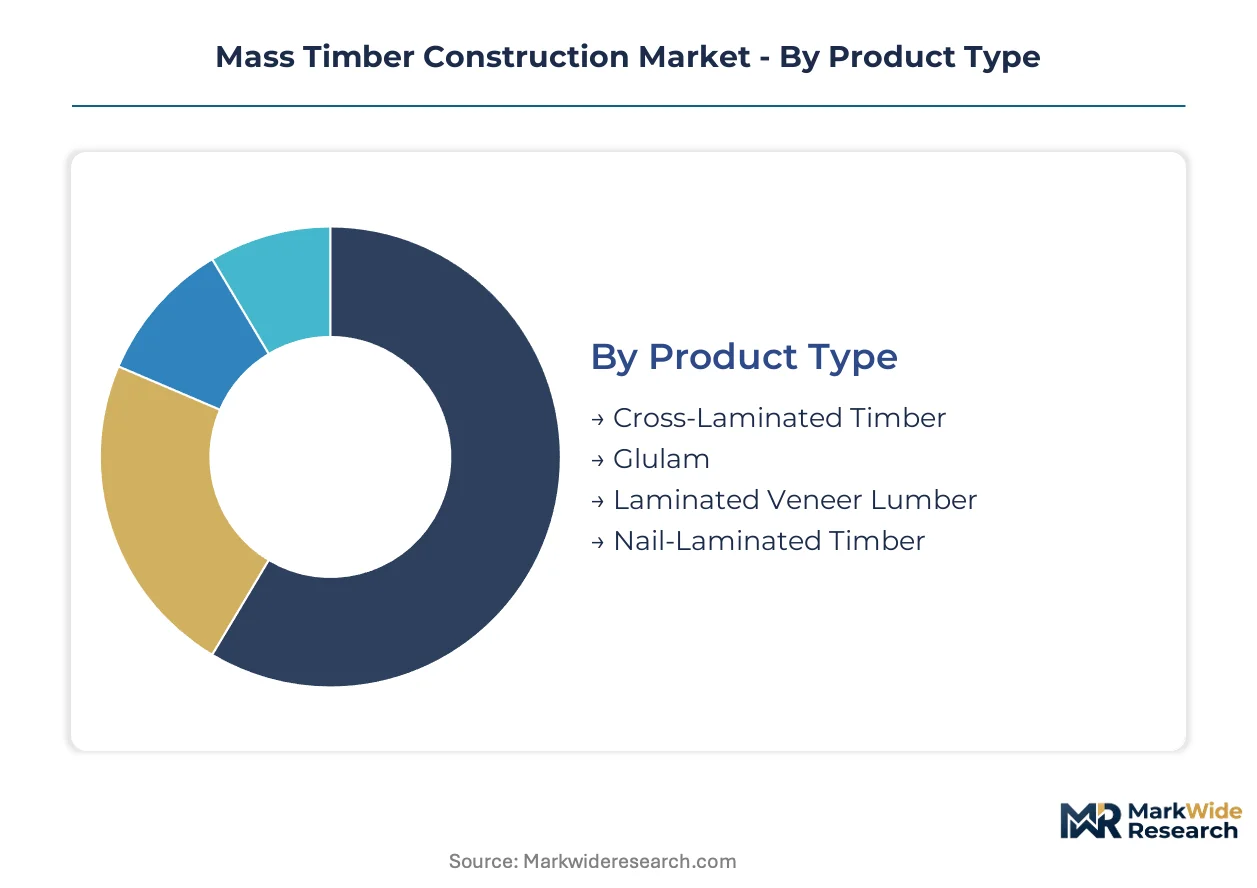
Segmentation in mass timber construction reveals how engineered wood products compete across distinct technical specifications, project scales, and procurement workflows. Buyers select products based on structural span requirements, fire-rating needs, and supply chain proximity rather than commodity pricing alone.
Product Type:
Structural performance requirements and code familiarity drive product selection, with architects and engineers weighing panel thickness, beam depth, and connection detailing against project-specific load paths.
- Cross-Laminated Timber:Engineered panels constructed from 3-9 perpendicular layers of dimensional lumber bonded under pressure, delivering planar structural capacity for floors and walls. Demand concentrates in multi-family residential towers across British Columbia and Oregon, where the International Building Code's Type IV-A provisions permit 18-story wood construction and contractors possess installation experience with panelized systems.
- Glulam:Long-span structural beams formed by laminating lumber laminations with moisture-resistant adhesives, enabling curved and cambered profiles impossible with solid timber. Commercial developers in Portland and Minneapolis specify glulam for atrium roofs and open-plan offices, though European import dependence from Austrian and German producers creates lead-time risk for North American projects.
- Laminated Veneer Lumber:High-strength engineered lumber manufactured from rotary-peeled veneers arranged in parallel grain orientation, offering dimensional stability superior to solid sawn lumber. Residential contractors in the Pacific Northwest favor LVL for headers and rim boards in mid-rise wood-frame construction.
- Nail-Laminated Timber:Structural panels created by face-nailing dimensional lumber together in alternating grain directions, providing a lower-cost alternative to adhesive-bonded systems with comparable fire performance. Institutional clients in Canada specify NLT for aesthetic ceiling exposure in schools and community centers.
Volume sits with Cross-Laminated Timber; growth tilts toward Hybrid Systems combining timber with steel or concrete connections.
Application:
Building typology determines fire-rating assemblies, lateral load requirements, and the economic viability of prefabricated delivery versus site-built alternatives.
- Residential Buildings:Multi-family housing from four to eighteen stories represents the dominant deployment category, with developers in Vancouver and Portland leveraging mass timber for carbon reduction metrics required by institutional capital providers. British Columbia's building code amendments explicitly permit taller wood structures, accelerating permit timelines relative to conventional jurisdictions.
- Commercial Structures:Office and retail developments utilize exposed timber for biophilic design appeal and tenant attraction, though structural engineers must resolve vibration criteria and longer-span requirements through hybrid systems. The US General Services Administration's embodied carbon disclosure mandate steers federal procurement toward low-carbon alternatives in this category.
- Institutional Facilities:Schools, libraries, and community centers adopt mass timber for public visibility of sustainability commitments, with Canada's Green Building Strategy creating direct procurement preference for government projects.
- Industrial Construction:Warehousing and manufacturing facilities employ mass timber for roof structures and mezzanines, capitalizing on speed of erection where architectural exposure is secondary to functional performance.
Residential Buildings command current deployment volumes; Commercial Structures are climbing the fastest as carbon accounting permeates corporate real estate finance.
End User:
Professional role within the project delivery chain shapes information needs, risk tolerance, and the timing of material substitution decisions.
- Architects:Design professionals specify mass timber for aesthetic and environmental performance, requiring technical support on fire engineering and acoustic detailing from manufacturers.
- Contractors:Construction managers evaluate prefabricated systems based on labor productivity, crane schedule coordination, and weather-independent fabrication timelines.
- Developers:Project sponsors assess mass timber against conventional alternatives through lifecycle cost analysis and carbon disclosure requirements imposed by institutional capital sources.
- Government Agencies:Public procurement officers apply federal embodied carbon mandates and green building incentives to material selection for schools, administrative buildings, and infrastructure.
Developers control capital commitment timing; Government Agencies are gaining share fastest as procurement policy hardens around carbon thresholds.
Technology:
Fabrication methodology determines where value accumulates in the building delivery chain and the degree of schedule compression achievable relative to site-built construction.
- Prefabrication:Factory-controlled production of structural elements enables parallel site preparation and manufacturing workflows, compressing overall project duration.
- Modular Construction:Volumetric units complete with MEP rough-in and interior finishes shift construction labor from job sites to manufacturing facilities.
- Hybrid Systems:Integration of mass timber with post-tensioned concrete cores and steel moment frames expands height and span capabilities beyond pure timber limits. Engineers in Vancouver and Minneapolis are specifying these assemblies for 18-25 story towers previously unreachable for conventional wood construction.
- Digital Fabrication:CNC machining and BIM-to-factory workflows enable complex geometries and precision connection detailing that manual fabrication cannot achieve.
Prefabrication anchors current implementation; Digital Fabrication shows the steepest expansion trajectory as manufacturers invest in automated production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Softwood forests across the Pacific Northwest anchor North American mass timber supply chains, with British Columbia and Oregon hosting the continent's densest concentrations of cross-laminated timber manufacturing capacity.
United States
Multi-story residential developers in Portland and Minneapolis are specifying hybrid timber systems for 18-25 story towers. The International Building Code's Type IV-A provisions, adopted variably by state jurisdictions, permit mass timber construction up to 18 stories. Oregon and Washington manufacturers control panelized delivery logistics for projects spanning the Mountain West and Southwest.
Canada
British Columbia's building code amendments explicitly permit taller wood structures, accelerating permit timelines relative to conventional jurisdictions. Canada's Green Building Strategy creates direct procurement preference for mass timber in federal and institutional projects. Quebec and Ontario producers are expanding manufacturing footprints to serve accelerating North American project pipelines.
Austria
Austrian glulam producers dominate European supply of engineered timber components exported to premium North American developments. The European Union's Construction Products Regulation requires Environmental Product Declarations for structural materials in public buildings. Hasslacher Norica Timber anchors supply chains serving high-specification commercial and residential towers.
Germany
German manufacturers supply precision-engineered beams for atrium roofs and open-plan offices across North American markets. REACH compliance and harmonized EN standards govern certification for materials entering EU public procurement. Bavarian and Baden-Württemberg fabrication clusters specialize in curved and cambered profiles impossible with solid timber.
United Kingdom
London developers are embedding embodied carbon thresholds into real estate acquisition criteria, forcing early-phase material substitution decisions. The UK's national building regulations increasingly reference mass timber for mid-rise residential and commercial applications. Southeast England architectural practices are accumulating integrated timber-structural expertise previously concentrated in Pacific Northwest firms.
Mass Timber Construction Market Vendor Landscape
Global majors compete with regional champions across fabrication capacity and design-build integration. The vendor base spans vertically integrated manufacturers controlling digital workflows, specialized engineering consultancies, and general contractors with established union labor networks. Three archetypes dominate: integrated design-build operators, pure-play engineered wood manufacturers, and construction managers with timber-specific project experience. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for code harmonization across jurisdictions.
Among North American fabricators, Element5 exemplifies the integrated design-build archetype through value chain control. Swinerton Incorporated anchors large-scale commercial timber construction with established contractor networks. Hasslacher Norica Timber represents the European export-specialist tier supplying premium components to height-specification developments.
| Leading Market Players |
|---|
| Element5 |
| DLR Group |
| Swinerton Incorporated |
| Gensler |
| LEVER Architecture |
| Timberlab Inc. |
| Hasslacher Norica Timber |
| Thornton Tomasetti |
| SmartLam North America |
| Others |
Supply Flow & Price Mechanics
Random Lengths Framing Composite pricing volatility cascades through mass timber manufacturing, compressing margins at panel producers while concentrating pricing power with adhesive suppliers and European glulam exporters serving premium North American developments.
Pricing Analysis
Warranty-backed fire-performance certification bundles separate premium-tier suppliers from unbundled commodity panel producers. Project-based pricing dominates, with differentiation driven by UL 263 fire-rating certification and geographic delivery radius from Pacific Northwest fabrication clusters. Cost compression in standard-grade CLT intensifies because polyurethane resin prices track petrochemical indices. Multi-family residential developers exhibit highest price sensitivity; institutional clients with federal procurement mandates show least.
Supply Chain Analysis
Single-source vulnerability sits with Austrian and German glulam beam suppliers serving tall-wood projects exceeding 12 stories. Manufacturing concentrates in Canada, the United States, and Austria. Production draws from Douglas fir and spruce-pine-fir feedstocks, polyurethane adhesives, and phenolic resins. Tariff exposure on European-engineered components threatens project feasibility for height-specification developments. Distribution runs through panelized delivery direct to job sites with crane-schedule coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass timber construction occupies a technology-transition phase where hybrid timber-steel-concrete systems displace pure steel and concrete assemblies for mid-rise and tall building applications.
For Market Incumbents: Anticipate adhesive cost volatility by securing long-term resin supply agreements or exploring bio-based binder alternatives. Incumbent panel manufacturers should deepen backward integration into forestry assets in British Columbia and Oregon to defend feedstock access against emerging Southeastern US entrants. Certification investment in EN 14080 harmonized standards protects European export positioning. For New Entrants and Emerging Players: Southeastern US contractors represent an underserved buyer archetype lacking mature mass timber supply chains despite abundant softwood resources. New entrants should target Georgia and North Carolina metropolitan construction pipelines with prefabricated hybrid systems. A design-build partnership model with regional general contractors accelerates market entry faster than greenfield fabrication investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated design-build operators in Pacific Northwest markets where project pipelines exceed current fabrication capacity. Long-term viability hinges on code harmonization progress across state jurisdictions. Investors should monitor International Building Code adoption timelines as the inflection signal for capacity commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Technology Licensing | Enables 18-25 story construction previously unreachable for pure timber assemblies. |
| Backward Integration into Forestry Assets | Secures Douglas fir feedstock access in British Columbia and Oregon. |
| European Certification Investment | Unlocks premium positioning in EU public procurement under Construction Products Regulation. |
| Digital Fabrication Automation | Compresses panel production timelines through BIM-to-CNC factory workflows. |
| Southeastern US Manufacturing Footprint | Captures latent demand in Georgia and North Carolina metropolitan pipelines. |
Methodological Framework
Multi-period observation of building code adoption timelines, permit issuance data, and manufacturer capacity announcements anchored the trend analysis, supplemented by interviews with mass timber fabricators, structural engineering consultants, multi-family developers, and procurement officers at the US General Services Administration. Secondary validation drew from International Code Council proceedings, National Building Code of Canada amendments, Environmental Product Declaration databases, and engineered wood product trade flow records. Bottom-up project pipeline tracking triangulated against top-down construction spending forecasts.
Input-output matrices modeled demand drivers across product type, application, and technology segments throughout the forecast period. Segmentation dimensions included structural system configuration, building height tier, fire-rating assembly specification, and regional regulatory cluster. CAGRs derived from regression analysis of historical adoption curves adjusted for code harmonization velocity and institutional capital carbon disclosure penetration rates. Forecast inputs incorporated softwood lumber price indices and adhesive cost trajectories.
Revisions become necessary when building code adoption timelines diverge from modeled pathways or when petrochemical price shocks alter adhesive economics materially. Deviation in International Building Code state-level adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Africa Green Cement Market
Building Materials
Geocells Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Building and Construction Plastics Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Brick Adhesive Market
Building Materials
Cladding Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
India Concealed Cistern Market
Building Materials
Composite Decking and Railing Market
Building Materials
Construction Repair Composites Market