
 Precast Concrete Retaining Walls Market | 2026-2036
Precast Concrete Retaining Walls Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Concrete Retaining Walls Market Insights
Project finance leasing for municipal infrastructure is reconfiguring competitive entry barriers in precast concrete retaining walls. Oldcastle Infrastructure leverages captive concrete supply and fabrication capacity across North American markets. Forterra sustains geographic dominance through distributed production assets near major transportation corridors. CEMEX S.A.B. de C.V. anchors its position with vertically integrated cement-to-installation capabilities in Latin American growth corridors.
Precast concrete retaining walls are factory-cast reinforced concrete elements, typically produced with compressive strengths of 4,000–6,000 psi and steel reinforcement ratios of 1–3 percent, designed for lateral earth retention in civil and commercial construction. Modular wall systems lead product type demand due to faster installation cycles and reduced labor dependency on constrained job sites. Gravity wall configurations occupy mature margin pools in residential landscaping, while cantilever designs are gaining share in industrial applications requiring taller retention heights. Commercial application segments concentrate value as developers prioritize speed-to-enclosure in retail and logistics pad development.
The EPA enforces stormwater runoff standards under the National Pollutant Discharge Elimination System, directly shaping product specifications for permeability and durability in retaining wall specifications. ASTM C1577 and ACI 318 provide structural design benchmarks that govern market access for precast manufacturers serving public infrastructure contracts. State departments of transportation, including Caltrans and Texas DOT, maintain qualified product lists that filter supplier participation in highway projects. Stakeholders must monitor evolving Buy America domestic content thresholds and their cascading effects on raw material sourcing strategies and fabrication location decisions.
Market Dynamics
Mechanized installation systems are compressing project timelines and reshaping contractor procurement patterns across highway infrastructure programs. The EPA's stormwater enforcement under the Clean Water Act is mandating higher durability specifications, forcing specification upgrades throughout public infrastructure channels.
Growth Catalysts
- Highway Infrastructure Expansion:United States federal transportation appropriations are accelerating mechanized wall system deployment across interstate corridor projects. State DOT qualified product lists are filtering supplier participation toward precast specialists.
- EPA Stormwater Mandates:The National Pollutant Discharge Elimination System is requiring permeable facing and enhanced durability in erosion control applications. Municipal engineers are specifying precast concrete over segmental block alternatives.
- Mining Corridor Development:Australia's Pilbara and Bowen Basin extraction zones are concentrating demand for tall cantilever configurations. Resource sector capital budgets prioritize rapid-installation retaining solutions.
Market Restraints
- Steel Reinforcement Volatility:Rebar input costs fluctuate with scrap metal commodity cycles. Fabricators face margin compression when long-term project bids lock in pricing ahead of material procurement.
- Transportation Radius Constraints:Precast elements face economic shipping limits of approximately 200 miles. Remote project sites beyond this threshold trigger prohibitive logistics premiums or local casting requirements.
- Segmental Masonry Substitution:Dry-stacked concrete block systems compete for residential landscaping applications. Gravity wall configurations face share erosion where aesthetic flexibility outweighs structural efficiency.
Strategic Opportunities
- Coastal Protection Programs:Australia's eastern seaboard climate adaptation funding is expanding seawall and revetment specifications. State infrastructure agencies are consolidating procurement around factory-cast durability guarantees.
- Project Finance Leasing:Municipal infrastructure leasing structures are reconfiguring capital deployment for precast wall systems. Contractors can propose performance-based installation contracts with extended maintenance terms.
- BIM-Integrated Design:Building information modeling convergence with precast detailing software is compressing engineering review cycles. Early-stage design collaboration is locking in specification decisions before competitive bidding.
Industry Challenges
- Skilled Erection Labor Scarcity:Certified crane operators and rigging specialists command premium wages on constrained job sites. Installation bottlenecks delay project completion despite factory production capacity availability.
- ASTM C1577 Certification Timelines:New product qualification for state DOT approved lists requires extended third-party testing protocols. Market entry delays stretch 18-24 months for innovative wall configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Concrete Retaining Walls Market |
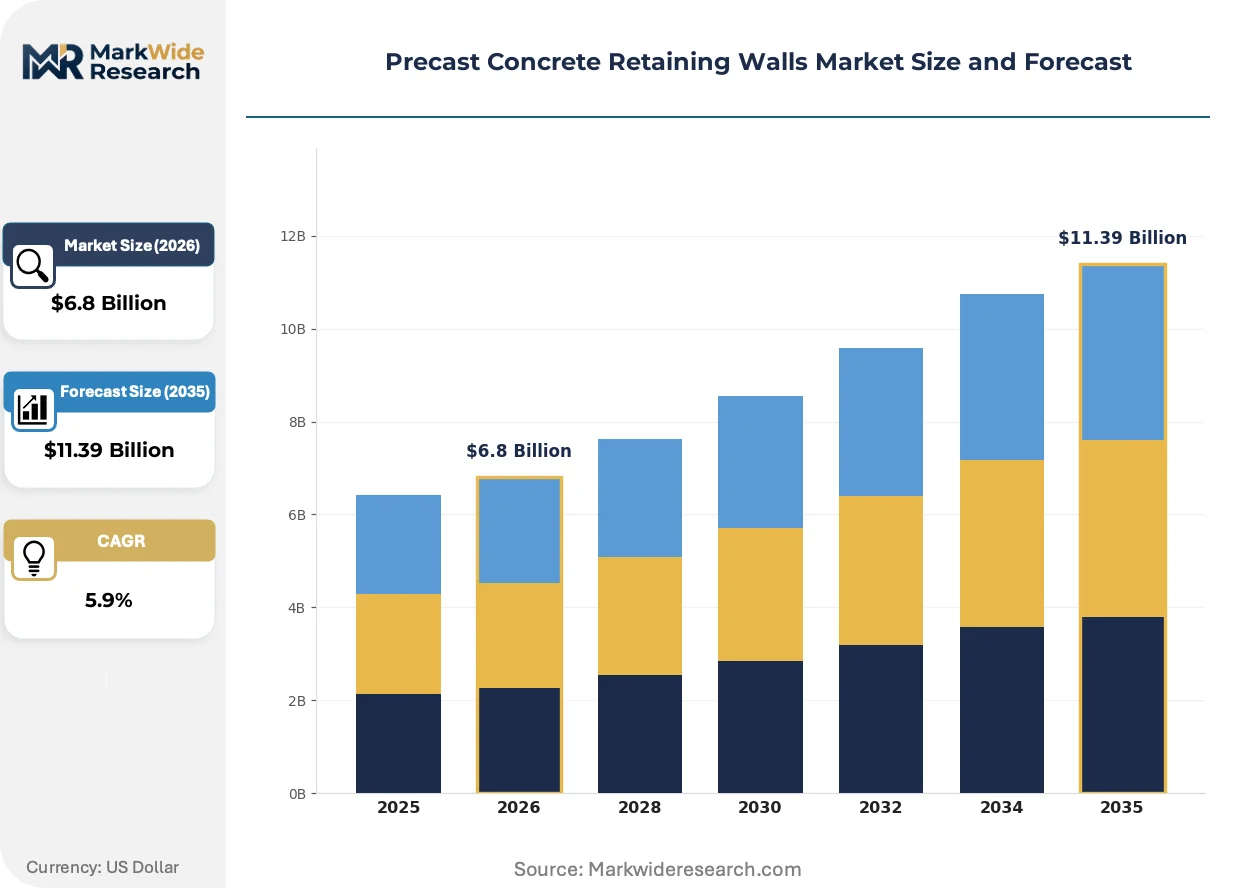
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Walls, Gravity Walls, Cantilever Walls, Sheet Piling Application: Commercial, Residential, Landscape, Industrial Installation Method: Pre-assembled, Site-cast, Assembly, Mechanized End User: Contractors, Architects, Builders, Engineers |
| Companies Covered | Oldcastle Infrastructure, Forterra, CEMEX S.A.B. de C.V., Holcim, CRH, Boral Limited, Tindall Corporation, Jensen Precast, Coreslab Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Concrete Retaining Walls Market Trends and Innovations
Twin-wall hollow core precast systems are compressing material intensity while maintaining structural capacity. Digital fabrication controls and alternative cement chemistries are simultaneously reshaping production economics and specification standards.
Twin-wall panel technology integrates two thin concrete wythes connected by internal lattice reinforcement. Highway contractors in Texas and California are specifying these systems for sound barrier and retaining wall combinations. The configuration is rendering obsolete solid cross-section designs that consume excess concrete volume for equivalent moment capacity.
The EPA's enforcement of Total Maximum Daily Load allocations under the Clean Water Act is tightening stormwater retention requirements. Industrial site developers must now demonstrate post-construction runoff controls that exceed previous permit thresholds. Commercial logistics pad construction in the United States is responding with permeable precast facing systems that integrate detention capacity within wall footprints.
Design-build procurement consolidation is compressing traditional bid-specify-install sequences. General contractors are engaging precast fabricators during schematic design phases to optimize wall geometry for production efficiencies. Australia's mining and coastal infrastructure sectors exhibit the most advanced early-involvement contracting, with lump-sum turnkey agreements replacing unit-price competitive bidding.
Precast Concrete Retaining Walls Market Segmentation
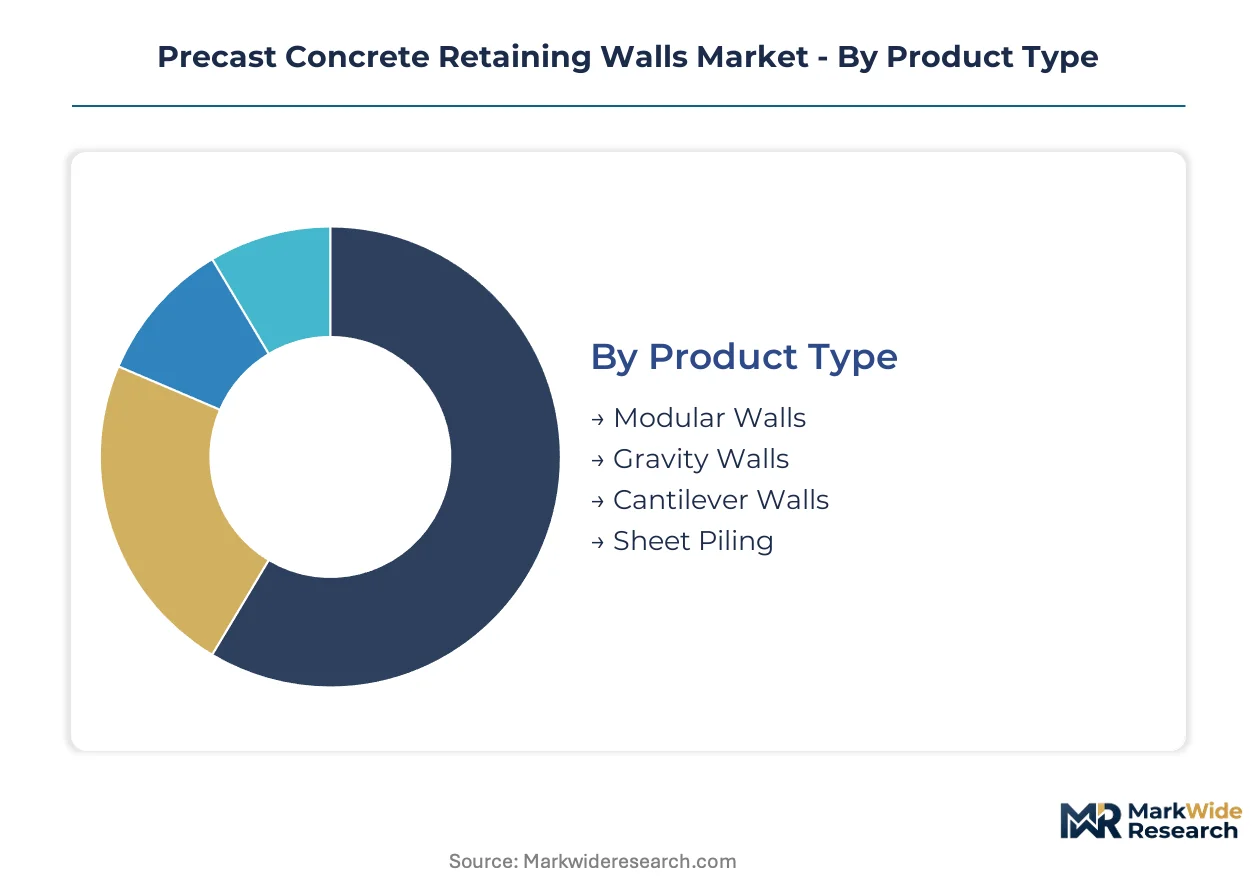
Precast concrete retaining walls fragment across four structural dimensions. Product geometry determines material intensity and installation labor. Application context governs specification stringency and procurement channel. Installation method and end-user type reshape competitive positioning and margin capture.
Product Type:
Cost tier differentiation separates factory-efficiency systems from engineered specialty configurations.
- Modular Walls:Factory-cast interlocking panels with standardized connection hardware enable crane-assisted placement without field welding. Demand concentrates in United States retail logistics pads where speed-to-enclosure compresses project finance timelines. Developers specify these systems to meet EPA stormwater detention requirements within wall footprints.
- Gravity Walls:Mass-dependent configurations rely on unit weight and setback geometry rather than mechanical anchorage. Residential landscaping across Australian coastal municipalities sustains procurement volumes where aesthetic flexibility outweighs structural height requirements.
- Cantilever Walls:Stem-and-base configurations with steel reinforcement ratios up to 3 percent serve industrial retention heights exceeding 20 feet. Australia's Pilbara mining corridors specify these for vertical excavation support.
- Sheet Piling:Thin-section driven or vibrated interlocks provide temporary or permanent earth retention in constrained rights-of-way. Highway widening projects in Texas and California deploy these where utility congestion prevents conventional footing excavation.
Modular walls command the established base. The steepest expansion runs through cantilever configurations.
Application:
Volume concentration tracks infrastructure capital allocation and private development cycles.
- Commercial:Logistics pad developers prioritize precast speed-to-enclosure to accelerate tenant occupancy and lease commencement. United States industrial construction permits are driving specification upgrades toward permeable facing systems.
- Residential:Subdivision developers and individual homeowners specify gravity configurations for grade separation and aesthetic terracing. Australian state climate adaptation funding is expanding seawall procurement in this channel.
- Landscape:Public park and recreational trail projects balance visual integration with structural performance. Municipal engineers in coastal jurisdictions specify factory-cast durability guarantees over segmental block alternatives.
- Industrial:Mining, energy, and heavy manufacturing sites require tall retention with live load surcharge capacity. Australia's Bowen Basin extraction zones concentrate demand for rapid-installation cantilever systems.
Commercial applications anchor revenue concentration. Industrial end-uses are climbing the fastest.
Installation Method:
Customer type and project scale dictate procurement patterns across labor-intensity spectrum.
- Pre-assembled:Factory-complete panel-and-footing units arrive on flatbed for direct crane placement. United States highway contractors facing skilled erection labor scarcity are specifying these to compress field schedules.
- Site-cast:Mobile batching and casting operations serve projects beyond 200-mile economic shipping radius from fixed fabrication plants. Remote Australian mining sites trigger this approach despite quality control variability.
- Assembly:Component-based systems requiring field bolting, grouting, or welding of discrete elements. State DOT qualified product lists in Texas and California filter supplier participation toward fabricators with documented assembly protocols.
- Mechanized:Automated or semi-automated placement systems reduce crane operator dependency and accelerate production rates. Federal transportation appropriations are accelerating deployment across interstate corridor projects.
Assembly methods retain the largest installed base. Mechanized systems are gaining share fastest.
End User:
Specification authority and procurement execution separate across professional roles in project delivery.
- Contractors:Design-build and lump-sum turnkey agreements concentrate procurement authority with construction firms. Australian mining and coastal infrastructure sectors exhibit the most advanced early-involvement contracting.
- Architects:Schematic design phase engagement locks in precast specification before competitive bidding. BIM-integrated detailing software is compressing engineering review cycles.
- Builders:Production homebuilders and commercial generalists prioritize standardized, repeatable wall configurations. Municipal infrastructure leasing structures are reconfiguring capital deployment channels.
- Engineers:Structural and geotechnical consultants govern technical compliance with ASTM C1577 and ACI 318 benchmarks. State DOT approved list qualification requires extended third-party testing protocols.
Contractors control the dominant procurement channel. Engineer-driven specification is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal transportation appropriations and climate adaptation funding are redirecting capital toward factory-cast retaining systems across multiple jurisdictions. Australia, the United States, and select European markets concentrate procurement authority through qualified product lists and domestic content thresholds.
United States
Highway infrastructure expansion across interstate corridors accelerates mechanized wall system deployment. The EPA's National Pollutant Discharge Elimination System mandates permeable facing specifications that favor precast concrete over segmental alternatives. Texas and California state DOTs filter supplier participation through rigorous approved list protocols.
Australia
Coastal protection programs and mining corridor development concentrate demand for tall cantilever configurations. State climate adaptation funding expands seawall and revetment specifications along the eastern seaboard. The Pilbara and Bowen Basin extraction zones prioritize rapid-installation retaining solutions for vertical excavation support.
Canada
Municipal infrastructure leasing structures reconfigure capital deployment channels for precast wall systems. Provincial transportation agencies enforce domestic content requirements that shape fabrication location decisions. Ontario and Quebec concentrate production assets near major transportation corridors.
Germany
Industrial site developers respond to tightened stormwater retention requirements through permeable precast facing systems. The country's national environmental regulator enforces construction runoff standards that exceed previous permit thresholds. The Rhine-Ruhr and Bavarian industrial clusters specify factory-cast durability guarantees for logistics pad construction.
Mexico
Latin American growth corridors anchor vertically integrated cement-to-installation capabilities. Federal infrastructure programs accelerate procurement of mechanized installation systems across highway expansion zones. The Mexico City metro area and northern border states concentrate demand for commercial logistics pad development.
Precast Concrete Retaining Walls Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement channels. The vendor base separates into captive concrete suppliers, distributed production networks, and vertically integrated multinationals. Three archetypes dominate: scale-driven fabricators with captive raw material supply, regional specialists with DOT qualification depth, and turnkey contractors with design-build authority. Competitive moves concentrate on capacity rationalization near transportation corridors and early-stage design collaboration to lock specifications before competitive bidding.
Among North American fabricators, Oldcastle Infrastructure and Forterra occupy distinct positions within the channel-control tier. Oldcastle leverages captive concrete supply across production assets positioned near major transportation corridors. Forterra sustains geographic dominance through distributed fabrication capacity that minimizes shipping radius constraints. CEMEX S.A.B. de C.V. anchors the vertically integrated archetype with cement-to-installation capabilities concentrated in Latin American growth corridors.
| Leading Market Players |
|---|
| Oldcastle Infrastructure |
| Forterra |
| CEMEX S.A.B. de C.V. |
| Holcim |
| CRH |
| Boral Limited |
| Tindall Corporation |
| Jensen Precast |
| Coreslab Structures |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Ruhr industrial cluster anchors European precast capacity, with fabricators there leveraging captive cement supply to command premium pricing on DOT-qualified wall systems exported to infrastructure corridors across Germany and neighboring jurisdictions.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified supply, with ASTM C1577 and state DOT approved list status commanding 15-25 percent premiums over generic precast alternatives. Three-tier pricing structure across DOT-certified, commercial-grade, and economy residential tiers reflects quality grade differentiation and volume scale. Cost compression in the residential gravity wall segment is intensifying because dry-stacked segmental block substitutes erode share where aesthetic flexibility outweighs structural efficiency. Municipal highway contractors exhibit the lowest price sensitivity due to federal transportation appropriations and performance-based procurement, while individual residential buyers drive the hardest bargain on per-linear-foot quotes.
Supply Chain Analysis
Steel reinforcement tariff exposure between the United States and select trading partners dominates margin risk for fabricators locked into long-term project bids ahead of rebar procurement. Geographic supply concentration centers on the United States, Australia, and Germany, with production assets clustered within 200 miles of major transportation corridors to respect economic shipping limits. Raw material dependencies draw from Portland cement, steel rebar, and chemical admixtures, with scrap metal commodity cycles amplifying input cost volatility. Single-source vulnerability in certified crane operator availability creates installation bottlenecks that delay project completion despite factory production capacity availability. Distribution runs through design-build contractors with early-stage specification authority and state DOT procurement channels filtering qualified product lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precast concrete retaining walls market sits in early-cycle expansion, with EPA stormwater enforcement under the Clean Water Act accelerating specification upgrades that displace segmental block alternatives in municipal infrastructure channels.
For Market Incumbents: Pre-empt share erosion in highway infrastructure by securing mechanized installation system partnerships before federal transportation appropriations lock in contractor procurement patterns. Anchor capacity additions within 150 miles of Texas and California DOT corridors to exploit qualified product list barriers against emerging entrants. Defend margin position through backward integration into captive concrete supply rather than exposure to spot cement markets.
For New Entrants and Emerging Players: Australia's Pilbara and Bowen Basin mining corridors represent the most penetrable entry point, with resource sector capital budgets prioritizing rapid-installation cantilever configurations over established supplier relationships. Coastal protection programs along Australia's eastern seaboard offer second-mover opportunity as state climate adaptation funding expands seawall specifications. Pursue lump-sum turnkey contracting models that compress traditional bid-specify-install sequences and lock in specification decisions before competitive bidding.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fabricators with DOT qualification depth and extended maintenance terms embedded in municipal infrastructure leasing structures. Long-term viability over the next decade hinges on positioning for climate adaptation capital deployment and mechanized installation system adoption. Target acquisition archetypes include regional specialists with state DOT approved list presence in high-growth corridors. The signal to watch is consolidation in crane-assisted mechanized placement capabilities as skilled erection labor scarcity intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Supply | Captive Portland cement production insulates margin compression from spot market volatility in Texas and California corridors. |
| Mechanized Installation System Deployment | Federal highway appropriations accelerate crane-assisted placement adoption across interstate corridor projects in the United States. |
| DOT Qualification Investment | ASTM C1577 certification and state approved list status filter supplier participation in public infrastructure procurement channels. |
| Coastal Protection Capability Buildout | Australia's eastern seaboard climate adaptation funding expands factory-cast seawall specifications with durability guarantees. |
| BIM-Integrated Design Collaboration | Early-stage engagement with architects and engineers locks precast specifications before competitive bidding compresses margins. |
Research Methodology
Operator-level perspectives from precast fabrication plant managers, state DOT procurement officers, highway contractors, and geotechnical engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through ASTM standards documentation, EPA Clean Water Act enforcement records, state transportation department qualified product lists, and federal transportation appropriations disclosures. Bottom-up unit economics from modular wall, gravity wall, cantilever, and sheet piling configurations were triangulated against top-down infrastructure capital allocation estimates across the analysis window.
Scenario-bracketing framed the analytical approach, with volume and value outputs reflecting sensitivity testing across highway infrastructure expansion intensity, EPA enforcement rigor, and steel reinforcement commodity cycle assumptions. Segmentation dimensions modeled include product geometry, application context, installation method, and end-user procurement authority, with geographic production cluster and regulatory qualification tier as industry-specific overlays. CAGRs were derived from installed base evolution and replacement cycle dynamics, with twin-wall hollow core technology adoption and mechanized placement penetration as specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure appropriations, scrap metal pricing, or construction labor availability would shift the trajectory materially. Forecasts reflect assumptions on DOT qualification timelines, shipping radius economics, and substitution elasticity between precast and segmental block systems. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Stone Adhesive Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Engineered Wood Product Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Germany Architectural Coatings Market
Building Materials
China Architectural Coatings Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
United States White Cement Market
Building Materials
Composite Decking and Railing Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Cribbing Blocks Market
Building Materials
US Cement Tiles Market
Building Materials
Stone Coated Steel Roofing Market