
 India Construction Ornamental Stone Market | 2026-2036
India Construction Ornamental Stone Market Size, Share, and Industry Trends Forecast 2026-2036
India Construction Ornamental Stone Market Insights
The price gap between premium Italian-finish marble and unprocessed quarry blocks is hardening across Indian distribution channels. Pokarna Limited leverages captive granite mines in Andhra Pradesh to sustain consistent slab supply for commercial tower projects. RK Marbles India anchors its position through deep Rajasthan quarry access, while Stonex India Pvt. Ltd differentiates via imported marble collections targeted at luxury hospitality developers in Mumbai and Bangalore.
India Construction Ornamental Stone comprises dimensionally cut and surface-finished natural rock slabs and tiles, primarily granite, marble, limestone, and quartzite, specified by Mohs hardness rating, water absorption percentage below 0.4%, and polished gloss units for architectural surfacing. Granite dominates volume in commercial flooring applications due to abrasion resistance and lower lifecycle cost, while marble captures margin pools in residential and hospitality wall cladding where aesthetic differentiation commands price premiums. Quartzite represents the fastest-growing product type among institutional clients seeking granite-like durability with distinctive veining patterns.
BIS dimensional stone standards, CDSCO-adjacent building material safety protocols, and state-level mining lease regulations under the Mines and Minerals Act collectively shape product certification requirements and quarry operating permissions across Indian states. Compliance with BIS IS 1130 and IS 14223 specifications now gates access to government infrastructure tenders and large-scale commercial contracts. Stakeholders must monitor evolving royalty structures and environmental clearance timelines as these determine viable supply expansion in Karnataka and Telangana deposit zones.
Market Dynamics
Mechanized Italian finishing technology is compressing the price-performance gap between domestic processing clusters and imported slab supply, forcing Rajasthan and Gujarat processors to upgrade capital equipment or cede margin to integrated quarry-to-finish operators.
Growth Catalysts
- Luxury residential tower specifications:Mumbai and Delhi developers now mandate BIS-certified polished granite for common-area flooring, pulling volume through Gujarat processing hubs.
- BIS IS 1130 dimensional standards:Mandatory certification for government infrastructure tenders is filtering substandard quarry output and consolidating contract awards to certified processors.
- Quartzite aesthetic differentiation:Institutional clients seeking granite durability with distinctive veining are specifying quartzite for flagship commercial facades.
Market Restraints
- Diesel-powered quarry extraction:Fuel cost volatility and environmental clearance delays under the Mines and Minerals Act constrain block output expansion in Karnataka deposit zones.
- Water-scarce processing clusters:Gujarat's mechanized cutting facilities face input constraints as groundwater withdrawal permits tighten under state pollution control norms.
- Engineered stone substitution:Aggressively priced quartz surfacing products from Southeast Asian suppliers capture mid-market kitchen countertop specifications.
Strategic Opportunities
- Telangana greenfield quarry development:Untapped granite deposits in the state's eastern belt offer first-mover lease acquisition potential ahead of competing bidders.
- Direct-to-developer digital platforms:Bypassing traditional distributor layers, slab suppliers are building project-specification relationships with Bangalore and Hyderabad commercial developers.
- PLI scheme capital subsidies:Central government production-linked incentives for domestic manufacturing equipment are defraying Italian finishing machinery upgrade costs for mid-scale processors.
Industry Challenges
- Certified stone mason shortage:Skilled installers capable of BIS-specified wet polishing and seam-matching are concentrated in Rajasthan and Gujarat, constraining project velocity in southern states.
- Multi-state royalty compliance:Quarry operators holding leases across Karnataka, Telangana and Andhra Pradesh face fragmented state mineral department reporting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Construction Ornamental Stone Market |
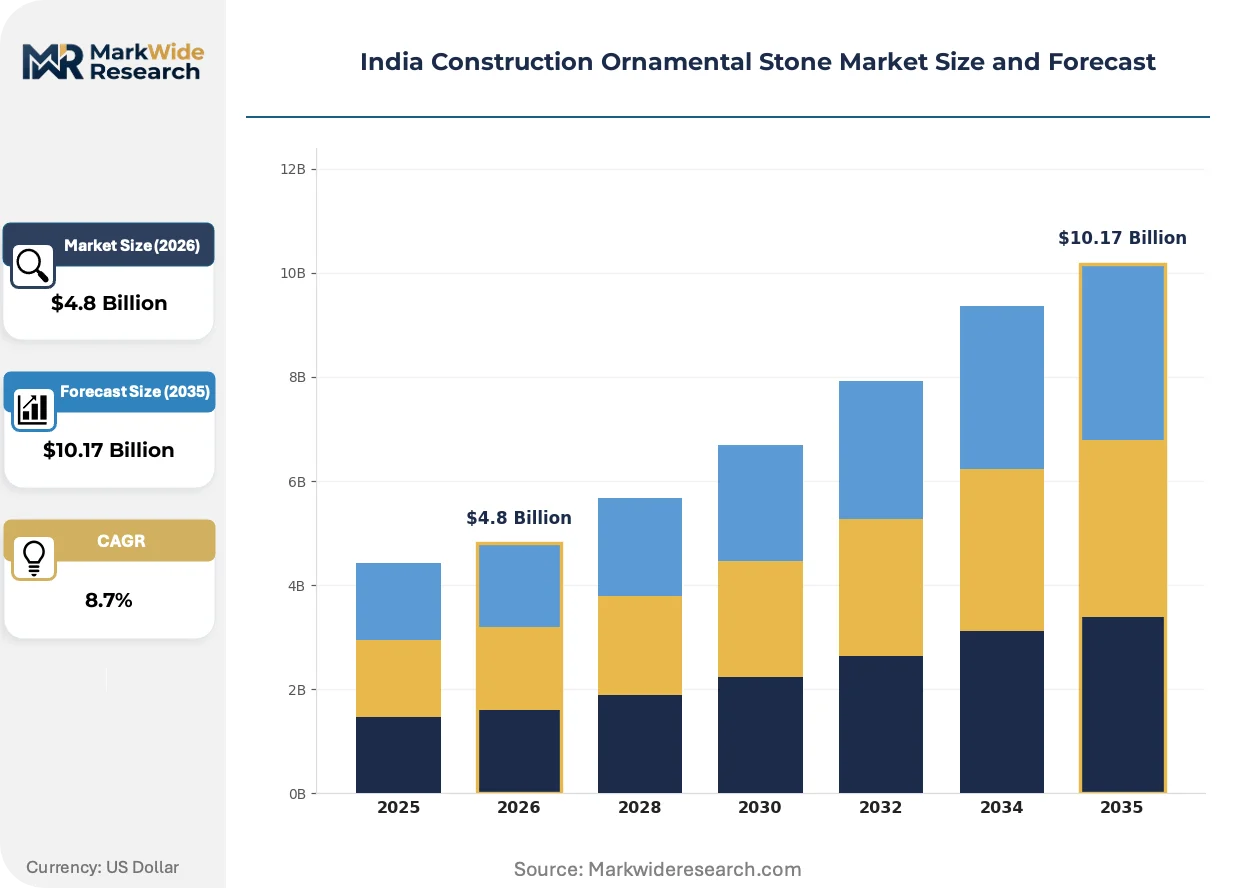
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite, Marble, Limestone, Quartzite Application: Flooring, Wall Cladding, Countertops, Landscaping End Use: Residential, Commercial, Institutional, Hospitality Distribution Channel: Direct Sale, Retail Stores, Online, Wholesale |
| Companies Covered | Pokarna Limited, RK Marbles India, Stonex India Pvt. Ltd, Aro Granite Industries Ltd, Tab India Granite Pvt. Ltd, Inani Marbles & Industries Ltd, Asian Granito India Ltd, A-Class Marble, Classic Marble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Construction Ornamental Stone Market Trends and Innovations
Italian-origin processing equipment is modularizing production workflows across Indian stone clusters, compressing batch turnaround times while fragmenting capital requirements into staged upgrade paths rather than monolithic facility investments.
Multi-wire diamond cutting technology is modularizing block-slab conversion efficiency in Rajasthan processing yards. Mid-scale operators in Udaipur and Jaipur are adopting refurbished Italian multi-wire frames in phased deployments. This modularizing investment pattern is lowering entry barriers for second-tier processors seeking to compete with integrated quarry-to-finish leaders.
BIS dimensional stone certification under IS 1130 and IS 14223 is hardening quality gates for government infrastructure tenders. Large-scale commercial contractors now require documented compliance traceability from quarry block through polished slab. Road and metro rail projects in Maharashtra and Karnataka are driving the steepest certification adoption curves among public-sector buyers.
Developer procurement teams are consolidating slab specification authority away from traditional distributor networks. Mumbai and Bangalore luxury residential developers now engage directly with Rajasthan quarry operators for project-specific color matching and volume commitments. This disintermediation concentrates margin with upstream processors while compressing distributor inventory carrying roles to logistics-only functions.
India Construction Ornamental Stone Market Segmentation
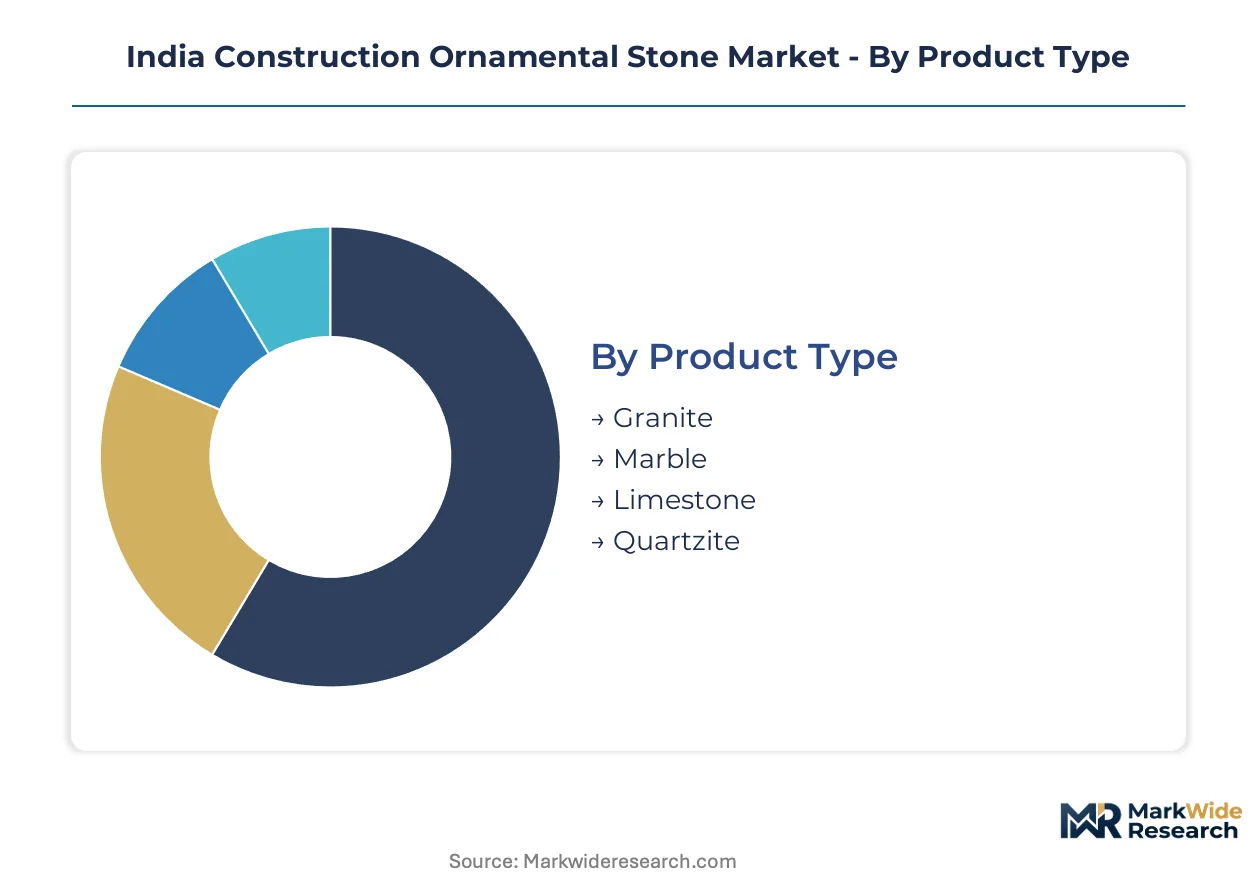
Segmentation in India's ornamental stone market reveals how specification authority, procurement scale, and finish complexity fragment buyer requirements across quarries, processors, and project developers. Each dimension exposes distinct margin pools and capital intensity thresholds that determine competitive positioning.
Product Type:
Cost tier differentiation separates quarry block economics from polished slab premiums, with hardness ratings and water absorption specifications driving specification authority.
- Granite:Igneous rock with Mohs hardness above 6 and water absorption below 0.4%, specified for abrasion-resistant commercial flooring. Mumbai and Delhi luxury residential towers now mandate BIS-certified polished granite for common areas, pulling volume through Gujarat mechanized processing hubs.
- Marble:Metamorphic calcium carbonate with distinctive veining, surface-finished to 80+ gloss units for aesthetic wall cladding. Hospitality developers in Bangalore specify imported Italian-finish marble for lobby and suite applications where visual differentiation commands price premiums.
- Limestone:Sedimentary calcium carbonate with higher porosity, specified for landscaping and exterior paving where weathering patina is desirable.
- Quartzite:Metamorphosed sandstone combining granite-like durability with marble-like veining patterns, gaining traction among institutional clients seeking distinctive facade aesthetics.
Volume sits with granite; growth tilts toward quartzite.
Application:
Surface area exposure and wear intensity determine finish grade requirements and installation skill thresholds.
- Flooring:High-traffic surfaces requiring abrasion-resistant granite with polished or flamed finishes. Commercial tower specifications in Hyderabad and Chennai drive demand for 20mm+ thickness slabs with documented BIS compliance.
- Wall Cladding:Vertical surfaces prioritizing aesthetic differentiation over structural load, where marble and quartzite thin slabs reduce structural dead load. Mumbai luxury residential developers specify book-matched veining patterns for feature walls.
- Countertops:Kitchen and vanity surfaces requiring stain resistance and seam-matching precision, where engineered quartz substitutes capture mid-market specifications.
- Landscaping:Exterior hardscaping with lower finish grades, sourced from unprocessed quarry blocks to minimize cost.
Revenue concentrates in flooring; margin expansion favors wall cladding.
End Use:
Procurement scale and specification complexity separate project developer direct purchasing from distributor-mediated retail transactions.
- Residential:Individual homeowners and small developers purchasing through retail stores for renovation and custom home construction, price-sensitive to slab grade variations.
- Commercial:Office tower and retail space developers with volume commitments and color-matching requirements, increasingly bypassing distributors to contract directly with Rajasthan quarry operators.
- Institutional:Government infrastructure and educational facility tenders mandating BIS IS 1130 certification with full traceability documentation, filtering substandard suppliers from contract awards.
- Hospitality:Hotel and resort developers specifying imported marble collections for lobby and guest room aesthetics, with Stonex India and similar importers capturing premium positioning.
Contract value peaks in hospitality; certification compliance gates institutional participation.
Distribution Channel:
Inventory carrying risk and specification authority determine margin allocation between upstream processors and downstream intermediaries.
- Direct Sale:Quarry-to-developer transactions eliminating distributor markups, enabled by digital platforms and project-specific volume commitments. Bangalore commercial developers now source directly for 10,000+ square meter specifications.
- Retail Stores:Slab yards with physical inspection capability for homeowner and small contractor selection, concentrated in Udaipur, Jaipur, and Ahmedabad stone markets.
- Online:Digital catalog platforms with logistics coordination for standardized grades, limited by inability to assess color variation and surface defects remotely.
- Wholesale:Distributor networks aggregating multi-quarry supply for regional contractor access, compressing to logistics-only functions as direct procurement expands.
Transaction volume flows through wholesale; margin capture shifts toward direct sale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's polished stone processing clusters dominate India's ornamental stone value chain, with Italian finishing technology driving mechanized output from Ahmedabad and Surat corridor facilities.
Rajasthan
Udaipur and Jaipur quarry belts supply premium marble and granite blocks to domestic and export markets. BIS dimensional stone standards under IS 1130 and IS 14223 govern quality certification for government infrastructure tenders. Jaipur's stone mandis aggregate multi-quarry supply for wholesale distribution to Mumbai and Delhi developers.
Andhra Pradesh
Captive granite mines in Prakasam and Guntur districts feed commercial tower projects across southern metros. State mining lease regulations under the Mines and Minerals Act determine quarry operating permissions and expansion timelines. Visakhapatnam port facilities handle bulk block shipments to Gujarat processing hubs.
Karnataka
Granite deposits in Bangalore Rural and Kolar districts attract institutional facade specifications seeking distinctive quartzite veining. Environmental clearance delays constrain diesel-powered extraction expansion in eastern belt zones. Bangalore commercial developers now contract directly with quarry operators for large-volume color-matched commitments.
Telangana
Untapped granite reserves in the state's eastern belt present greenfield lease acquisition opportunities ahead of competing bidders. Central PLI scheme subsidies for domestic manufacturing equipment reduce capital barriers for mechanized processing entry. Hyderabad's luxury residential developers drive demand for BIS-certified polished slabs in common-area flooring specifications.
Maharashtra
Mumbai's luxury residential towers mandate premium granite and marble for lobby and amenity space surfacing. Metro rail and road infrastructure projects under state urban development authorities require documented BIS compliance traceability from quarry to finished slab. Pune's emerging commercial corridor pulls processed stone supply through Gujarat distributor networks.
India Construction Ornamental Stone Market Competitive Landscape
Premium-margin players sit above commodity-margin players across quarry access and finishing technology dimensions. The market structure fragments between integrated quarry-to-finish operators and standalone processing specialists dependent on third-party block supply. Three archetypes dominate: captive mine holders with Italian finishing lines, Rajasthan-based quarry aggregators with deep deposit access, and import-focused distributors serving luxury hospitality specifications. Competitive moves concentrate on mechanized equipment upgrades and direct-to-developer procurement relationships that bypass traditional wholesale layers.
Among integrated quarry operators, Pokarna Limited and RK Marbles India exemplify archetypes with distinct geographic anchoring. Pokarna Limited represents the captive-mine model with Andhra Pradesh granite deposit control, while RK Marbles India occupies a position anchored through deep Rajasthan quarry access. Stonex India Pvt. Ltd sits within the import-specialist tier, targeting premium hospitality developers in Mumbai and Bangalore with curated international marble collections. These three players illustrate how supply chain positioning—captive extraction, domestic quarry aggregation, or import curation—determines margin capture and customer segment focus.
| Leading Market Players |
|---|
| Pokarna Limited |
| RK Marbles India |
| Stonex India Pvt. Ltd |
| Aro Granite Industries Ltd |
| Tab India Granite Pvt. Ltd |
| Inani Marbles & Industries Ltd |
| Asian Granito India Ltd |
| A-Class Marble |
| Classic Marble Company |
| Others |
Pricing and Supply Chain Analysis
BIS IS 1130 certification mandates for government infrastructure tenders are forcing quarry operators to absorb compliance costs or surrender contract eligibility, compressing margins for uncertified processors while concentrating pricing power with integrated quarry-to-finish leaders in Rajasthan and Gujarat.
Pricing Analysis
Project-specific volume commitments anchor value-based pricing for commercial tower developers in Mumbai and Hyderabad, with polished slab premiums scaling to documented BIS traceability and color-matching precision. Three-tier pricing structure across premium Italian-finish, certified domestic polished, and unprocessed quarry block tiers separates hospitality specifications from mid-market residential flooring. Cost compression in mid-tier granite intensifies as mechanized Italian equipment spreads through Gujarat clusters. Government infrastructure contractors demonstrate highest price sensitivity due to tender-based procurement, while luxury hospitality developers accept premium positioning for imported marble collections.
Supply Chain Analysis
Regional distribution centers in Ahmedabad and Surat operate as hub-and-spoke consolidation points for polished slab output destined to Mumbai, Delhi, and Bangalore project sites. Supply concentrates in Rajasthan quarry belts, Gujarat processing clusters, and Andhra Pradesh captive granite mines. Raw material flows draw from diesel-powered extraction in Karnataka, multi-wire diamond cutting equipment sourced from Italian OEMs, and resin-based polishing compounds. Single-source vulnerability concentrates in Italian finishing machinery dependency. Distribution runs through direct quarry-to-developer channels for large-volume specifications, with wholesale networks compressing to logistics-only functions for smaller retail transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental clearance delays under the Mines and Minerals Act constrain quarry expansion timelines across Karnataka and Telangana, propping block pricing for operators with secured lease permissions.
For Market Incumbents: Anticipate engineered quartz substitution pressure in mid-market countertop segments by deepening captive quarry access in Andhra Pradesh and Rajasthan while accelerating BIS certification coverage for institutional tender eligibility. Prioritize Italian multi-wire equipment upgrades in Gujarat facilities to defend polished slab margins against import competition. For New Entrants and Emerging Players: Direct-to-developer digital platforms offer lowest-friction entry for Telangana greenfield quarry operators seeking bypass relationships with Hyderabad and Bangalore commercial developers. Target untapped quartzite specifications in institutional facade projects where granite durability and marble aesthetics command hybrid premiums. For Investors and Strategic Acquirers: The window for entry favors integrated quarry-to-finish operators with certified block reserves and mechanized processing capacity over standalone distributors. Long-term viability hinges on lease security duration and environmental clearance pipeline velocity. Watch Telangana mining lease auction timing as inflection signal for southern supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Acquisition | Secures block supply continuity ahead of competing bidders in Telangana and Karnataka deposit zones. |
| Italian Equipment Upgrade | Compresses batch turnaround times for Gujarat processors competing with integrated quarry-to-finish leaders. |
| BIS Certification Investment | Gates access to Maharashtra and Karnataka metro rail and road infrastructure tender awards. |
| Direct-to-Developer Platform Launch | Bypasses wholesale distributor markups for Bangalore commercial tower volume specifications. |
| Quartzite Product Line Expansion | Captures institutional facade demand seeking granite durability with distinctive veining aesthetics. |
Research Methodology
Document review covered BIS dimensional stone standards, state mining lease records under the Mines and Minerals Act, and central PLI scheme disclosures, complemented by interviews with quarry operators in Rajasthan and Andhra Pradesh, Gujarat processing facility managers, Mumbai commercial procurement directors, and Bangalore hospitality developers. Secondary validation drew from customs block import data, state mineral department production statistics, and infrastructure tender documentation. Bottom-up segment sizing triangulated against top-down value chain analysis.
Output projections span product type, application surface, end-use procurement scale, and distribution channel fragmentation across the analysis window. CAGRs derived from segment-level volume trajectories weighted by polished slab premium realization rates. Forecast inputs incorporated quarry lease expansion timelines, Italian equipment import patterns, and BIS certification adoption curves among government contractors.
Caveats apply where environmental clearance delays, diesel fuel cost volatility, or engineered quartz substitution acceleration could materially shift the outlook beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Portland Cement Market
Building Materials
Shotcrete Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Sanded Grout Market
Building Materials
Composite Decking and Railing Market
Building Materials
Global Building Panels Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Geocells Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Natural Stone Market
Building Materials
Cement Market
Building Materials
ASEAN Dry Mix Mortar Market