
 Global Drywall and Building Plaster Market | 2026-2036
Global Drywall and Building Plaster Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drywall and Building Plaster Market Analysis
Buyer concentration among national homebuilders and large-scale commercial contractors is hardening across North America and Western Europe. Saint-Gobain leverages its vertically integrated gypsum sourcing and finishing systems to lock in specification-driven projects. Knauf Gips KG anchors its position through dense manufacturing footprints in Central and Eastern Europe. USG Corporation competes on specification depth, sustaining relationships with architect and engineer communities that influence material selection.
Drywall and building plaster comprise gypsum-core panels and cementitious or lime-based finishing compounds engineered to ASTM C1396, EN 520, or GB/T 9775 standards for fire rating, acoustic dampening, and surface preparation. Manufacturers calcine raw gypsum at controlled temperatures to produce hemihydrate plaster, then form it between paper facers or apply it as wet-coat finishes for interior wall and ceiling systems. Gypsum board dominates product type volumes due to its speed of installation and code-mandated fire performance in multi-story structures. Plaster of Paris retains share in decorative and repair applications where artisanal finishing and heritage restoration command premium pricing. Joint compounds represent a steady margin pool tied to installation labor rather than commodity gypsum costs.
FDA oversight of silica exposure in construction materials intersects with OSHA permissible exposure limits that shape jobsite handling protocols and product formulation choices in the United States. REACH registration requirements and CE marking under the EU Construction Products Regulation govern gypsum imports and domestic production across European member states. ASTM International, ISO 8336, and national GB standards in China collectively define the compliance landscape that manufacturers must navigate for cross-border market access. Stakeholders should monitor evolving carbon-accounting rules for gypsum calcination and the pace of synthetic gypsum substitution as these forces reshape input cost structures and facility siting decisions.
Market Dynamics
Residential construction recovery across suburban United States corridors is absorbing larger drywall volumes, while ASTM C1396 and EN 520 fire-resistance certifications are hardening specification barriers that favor vertically integrated producers with captive gypsum supply.
Growth Catalysts
- ASTM C1396 compliance mandates:Multi-story residential and commercial builds in the United States now require enhanced fire-rated board systems, locking in specification-driven demand for certified manufacturers.
- China-India metro buildouts:Domestic producers in both countries are scaling gypsum board lines to serve concentrated commercial construction in Shanghai, Beijing, Mumbai, and Delhi corridors.
- Synthetic gypsum substitution:Flue-gas desulfurization byproduct streams are displacing mined gypsum in calcination feeds, lowering input cost volatility for integrated plasterboard mills.
Market Restraints
- Natural gas price exposure:Calcination kilns consume substantial thermal energy, and European manufacturers face input cost spikes tied to continental supply disruptions.
- China production concentration:Over half of new plaster capacity additions sit in Shandong and Hebei provinces, creating geographic supply risk and freight cost premiums for distant markets.
- Cement board substitution:Fiber-cement exterior sheathing and magnesium oxide panels are capturing specification share in moisture-prone commercial envelope applications.
Strategic Opportunities
- India secondary cities:Tier-2 and Tier-3 urban centers like Pune, Ahmedabad, and Hyderabad show underpenetrated drywall adoption versus traditional lime plaster finishes.
- EU Green Deal carbon accounting:Embedded emissions disclosure requirements for construction products create first-mover advantage for manufacturers with synthetic gypsum and renewable kiln energy.
- Prefabricated wall panel integration:Offsite construction modules combining steel framing, insulation, and pre-finished gypsum surfaces are compressing site labor for national homebuilders.
Industry Challenges
- Skilled finishing labor scarcity:Journeyman plasterers and Level 5 drywall finishers are aging out of the workforce faster than apprenticeship programs in Germany and the United States can replenish them.
- CE marking timeline compression:EU Construction Products Regulation factory production control audits are extending lead times for Asian exporters seeking continental market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drywall and Building Plaster Market |
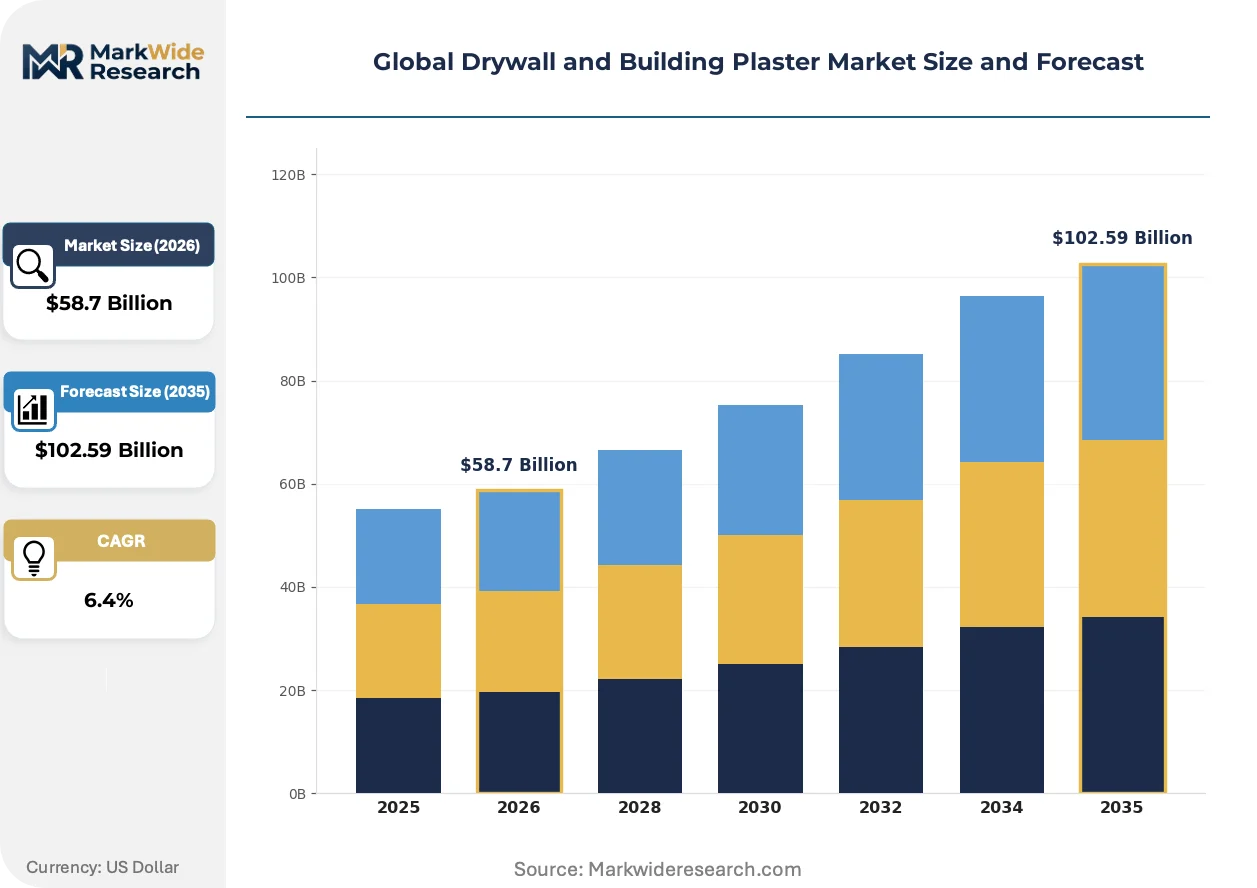
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum Board, Plaster of Paris, Joint Compounds, Decorative Plaster Application: Residential Construction, Commercial Construction, Interior Finishing, Repair Solutions Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms End User: Contractors, DIY Enthusiasts, Builders, Architects |
| Companies Covered | Saint-Gobain, Knauf Gips KG, USG Corporation, Etex S.A., Georgia-Pacific, National Gypsum Company, Beijing New Building Materials, Yoshino Gypsum Co., Ltd., Global Gypsum Company Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drywall and Building Plaster Market Emerging Trajectories
Active reformulation of core chemistries and panel geometries is compressing weight-per-board-foot while preserving fire and acoustic performance ratings. These shifts are reshaping freight economics and installer ergonomics simultaneously.
Lightweight gypsum core technology is unifying high-strength glass fiber reinforcement with reduced density hemihydrate formulations. National homebuilders in the United States are specifying these panels for upper-story residential framing to reduce manual handling strain. The technology is unifying fire performance with logistics cost reduction, compressing delivered price per square foot for distant distribution.
REACH registration requirements for crystalline silica content are forcing reformulation of joint compounds and setting-type plasters across EU member states. Manufacturers are substituting perlite and cellulose extenders for silica-bearing fillers to maintain workability. Wet-coat plaster systems for heritage restoration are most affected, with Italian and French specialty producers accelerating alternative binder testing.
Buyer concentration among national homebuilders is compressing procurement cycles toward annual framework agreements with volume-tier pricing. Regional distributors in the United States are losing specification influence as direct manufacturer relationships with D.R. Horton, Lennar, and PulteGroup consolidate material selection authority. The shift is most visible in Sun Belt suburban corridors where production home construction dominates absorption.
Global Drywall and Building Plaster Market Segmentation
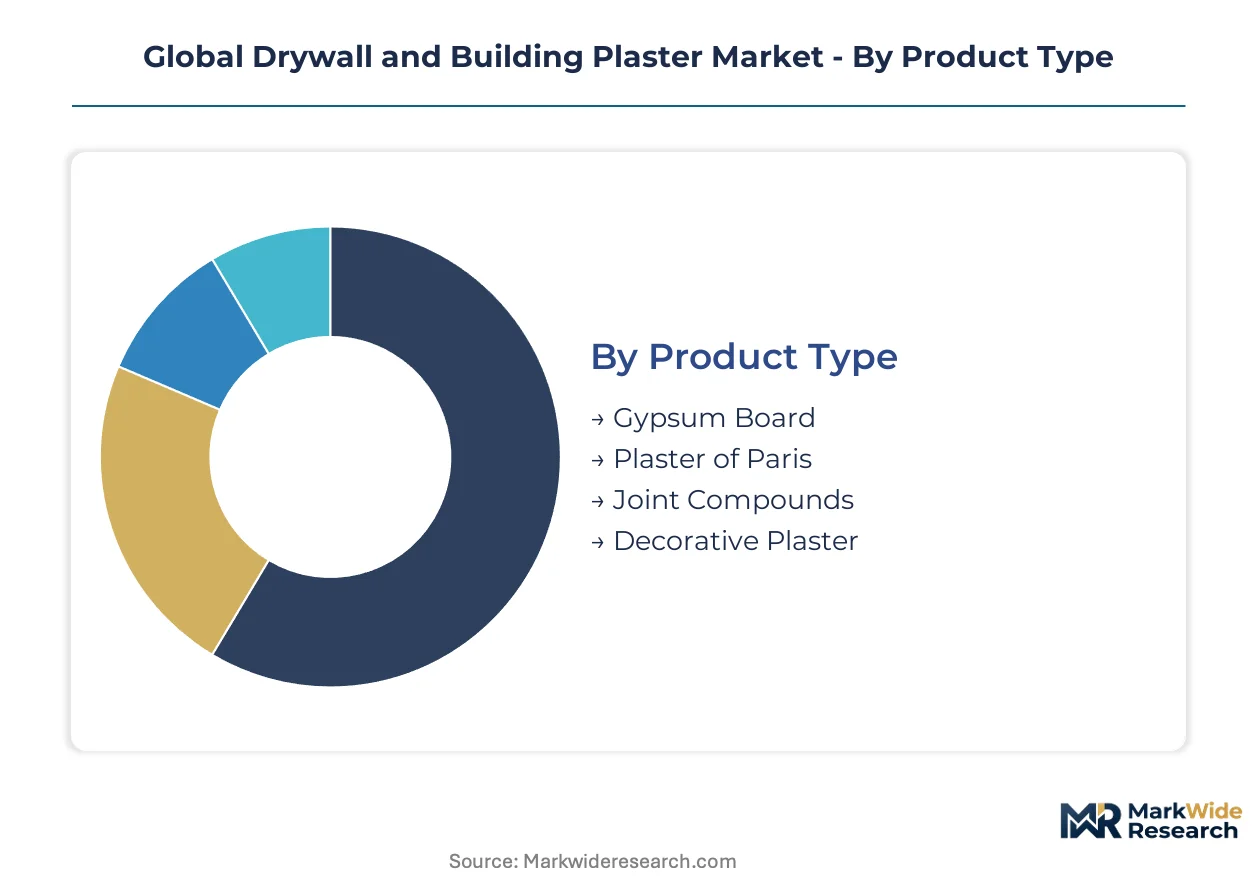
Drywall and building plaster markets fragment across product chemistry, construction phase, and procurement relationships. Certification requirements under ASTM C1396, EN 520, and GB/T 9775 create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
ASTM C1396 fire-rating mandates in the United States and EN 520 classifications in Europe impose distinct testing protocols on each product category, with gypsum board facing the heaviest third-party certification load.
- Gypsum Board:Paper-faced panels formed from calcined hemihydrate plaster between continuous facers. Residential construction in suburban United States corridors absorbs the largest volumes as housing starts recover and multi-story builds require code-mandated fire performance. Manufacturers with captive synthetic gypsum supply chains capture specification-driven projects through vertical integration.
- Plaster of Paris:Fine hemihydrate powder requiring on-site mixing with water for wet-coat application. Heritage restoration projects in Italian and French urban centers sustain premium pricing for artisanal finishing where decorative moldings and surface repair demand traditional material chemistry. REACH silica restrictions are accelerating perlite-based reformulations.
- Joint Compounds:Pre-mixed or setting-type finishing materials for seam concealment and surface preparation. Ready-mix formulations dominate new construction while powder compounds serve repair contractors.
- Decorative Plaster:Lime-based or acrylic-enhanced finishes for ornamental interior surfaces. Venetian and textured applications in high-end commercial fit-outs command material-plus-labor premiums.
Gypsum Board sits at the top of the volume ranking, with Joint Compounds climbing the fastest as production homebuilders consolidate annual framework agreements.
Application:
Cost tier differentiation separates commodity new-build materials from premium renovation systems, with labor attachment rates determining margin capture.
- Residential Construction:Single-family and multi-family housing drives standardized board specifications. Sun Belt suburban corridors in the United States concentrate absorption among national homebuilders with direct manufacturer relationships.
- Commercial Construction:Office, retail, and hospitality builds require enhanced acoustic and fire-rated assemblies. Metro-area buildouts in Shanghai, Beijing, Mumbai, and Delhi absorb expanding domestic capacity.
- Interior Finishing:Final surface preparation including Level 5 drywall and ornamental plaster. Skilled labor scarcity in Germany and the United States compresses project timelines and elevates wage premiums.
- Repair Solutions:Patch compounds and restoration plasters for existing building maintenance. Insurance-driven remediation in hurricane and flood corridors sustains seasonal demand spikes.
Residential Construction maintains volume leadership, though Interior Finishing is expanding most quickly as aging housing stock requires surface renewal.
Distribution Channel:
Customer type concentration among national builders and large contractors is compressing procurement toward direct relationships, marginalizing traditional distributor influence.
- Direct Sales:Manufacturer-to-builder contracts with volume-tier pricing. D.R. Horton, Lennar, and PulteGroup in the United States consolidate material selection authority through annual framework agreements.
- Wholesalers:Regional distributors serving mid-size contractors and independent builders. Inventory holding and credit extension remain differentiation levers despite eroding specification influence.
- Retailers:Big-box and specialty stores targeting DIY enthusiasts and small repair contractors. Pro-desk services and delivery logistics compete for professional foot traffic.
- Online Platforms:E-commerce channels for standardized products with predictable specifications. Joint compounds and accessories show strongest digital penetration due to shipping weight constraints.
Direct Sales dominates value capture, with Online Platforms gaining share fastest as procurement digitization accelerates among smaller contractors.
End User:
Supply concentration among vertically integrated manufacturers favors specification influence held by architects and national builders over fragmented contractor bases.
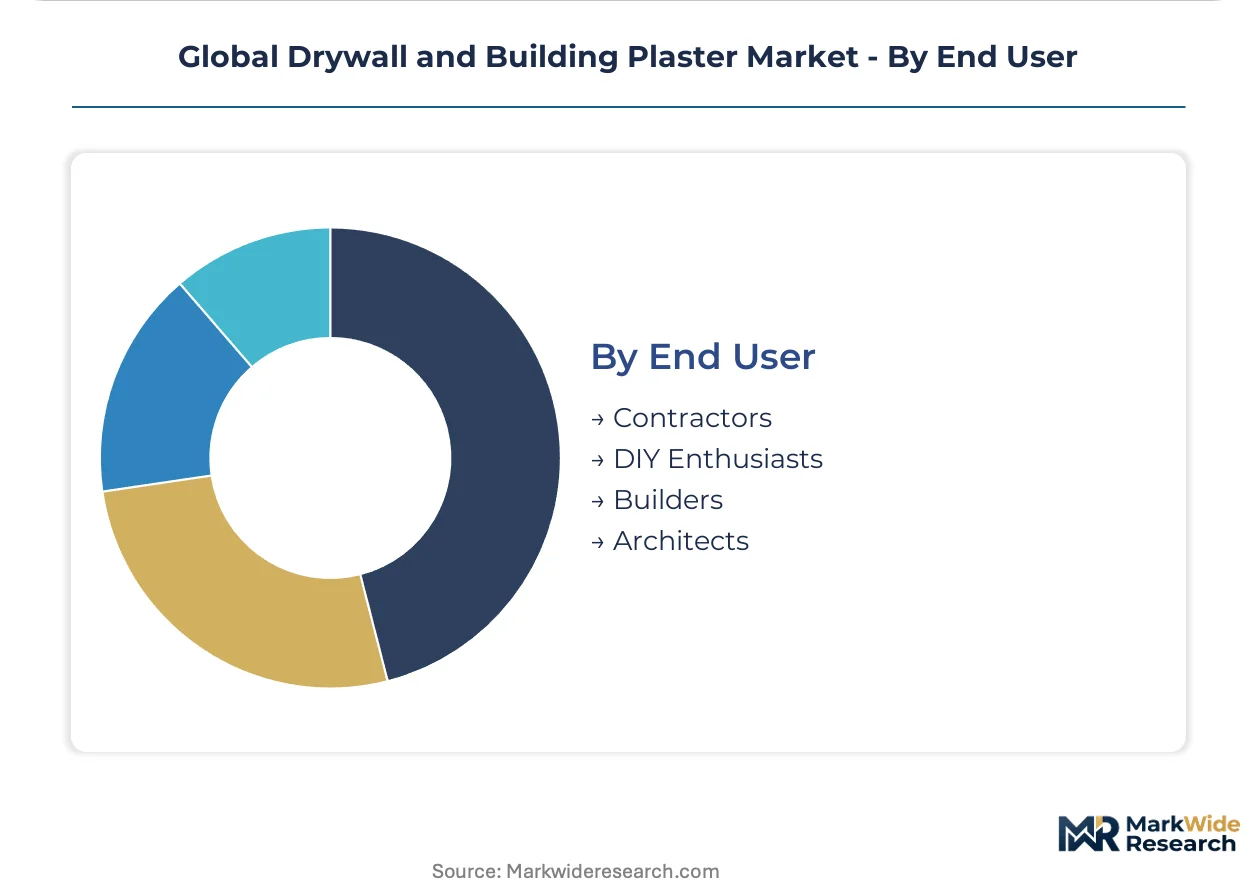
- Contractors:Installation specialists purchasing materials through wholesale or direct channels. Union finishing crews in Germany and the United States face apprenticeship pipeline gaps as journeyman plasterers age out.
- DIY Enthusiasts:Homeowners executing repair and renovation projects. Repair Solutions and Joint Compounds represent primary purchase categories through retail and online channels.
- Builders:Production and custom home developers with consolidated procurement authority. Direct manufacturer relationships compress distributor margins in high-volume suburban markets.
- Architects:Specification professionals influencing material selection through fire-rating and acoustic performance requirements. Continuing education relationships with manufacturers sustain brand preference in commercial projects.
Builders command the largest volume share, with Architects driving the steepest specification-value expansion as certification requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled finishing labor pools in Germany and the United States are aging out faster than apprenticeship pipelines can replenish them, compressing project timelines across suburban construction corridors. This workforce scarcity is reshaping where manufacturers prioritize capacity investments and specification relationships.
United States
National homebuilders including D.R. Horton and Lennar consolidate annual framework agreements, locking in direct manufacturer relationships across Sun Belt suburban corridors. OSHA silica exposure limits under 29 CFR 1926.1153 shape jobsite handling protocols and joint compound formulation choices. Atlanta and Phoenix metro areas absorb expanding gypsum board volumes as multi-family housing starts recover.
Germany
Journeyman plasterer shortages in Bavaria and North Rhine-Westphalia elevate wage premiums and extend project timelines for heritage restoration work. REACH registration requirements for crystalline silica content force reformulation of wet-coat finishing compounds. The Rhine-Ruhr industrial corridor concentrates synthetic gypsum processing capacity serving domestic and export markets.
China
Domestic producers scale gypsum board lines to serve concentrated commercial buildouts in Shanghai and Beijing metro corridors. GB/T 9775 fire-resistance standards govern product certification for high-rise applications. Shandong and Hebei provinces host over half of new plaster capacity additions, creating geographic supply concentration.
India
Tier-2 urban centers including Pune, Ahmedabad, and Hyderabad show underpenetrated drywall adoption versus traditional lime plaster finishes. BIS certification requirements under IS 2095 establish quality benchmarks for imported and domestic products. The Delhi-Mumbai Industrial Corridor drives commercial construction absorption for fire-rated board systems.
France
Artisanal plastering traditions in Paris and Lyon sustain premium pricing for decorative finishes and heritage restoration projects. EU Green Deal carbon accounting requirements create compliance advantages for manufacturers with synthetic gypsum feeds. The Île-de-France region concentrates specification influence among architect communities shaping material selection.
Global Drywall and Building Plaster Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across specification-driven and commodity volume segments. The vendor base organizes into three tiers: vertically integrated multinationals with captive gypsum supply, regional specialists with dense manufacturing footprints, and emerging Asian producers scaling export capacity. Two dominant competitive moves are reshaping positioning: M&A activity consolidating distribution relationships, and backward integration into synthetic gypsum processing to dampen input cost volatility.
Among European-based manufacturers, Saint-Gobain and Knauf Gips KG exemplify the vertically integrated archetype, while USG Corporation occupies a position representing specification-depth competitive strategy. These three anchors demonstrate how geographic manufacturing density and regulatory compliance capabilities translate into procurement relationship durability.
| Leading Market Players |
|---|
| Saint-Gobain |
| Knauf Gips KG |
| USG Corporation |
| Etex S.A. |
| Georgia-Pacific |
| National Gypsum Company |
| Beijing New Building Materials |
| Yoshino Gypsum Co., Ltd. |
| Global Gypsum Company Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
National homebuilder procurement consolidation across Sun Belt suburban corridors locks in annual framework agreements with volume-tier pricing, compressing distributor margins while rewarding manufacturers with captive synthetic gypsum supply and direct specification relationships.
Pricing Analysis
Bundled material-plus-labor contracts dominate commercial and large residential projects, while unbundled product-only transactions persist in repair and DIY channels. Three-tier pricing structure across premium fire-rated, standard Type X, and economy residential board levels tracks ASTM C1396 certification grade and volume commitment scale. Cost compression in standard-grade segments is intensifying because synthetic gypsum substitution has commoditized base material inputs. National homebuilders exhibit lowest price sensitivity due to specification lock-in, while independent repair contractors face highest sensitivity to joint compound per-unit differentials.
Supply Chain Analysis
Direct-to-builder channels handle hyperscale demand from D.R. Horton, Lennar, and PulteGroup, while regional wholesalers serve mid-tier contractors with inventory and credit extension. Manufacturing concentrates in the United States, China, and Germany, with Shandong and Hebei provinces hosting over half of new plaster capacity additions. Raw material flows draw from flue-gas desulfurization byproduct streams, mined gypsum deposits, and natural gas for calcination kilns. Single-source vulnerability in synthetic gypsum processing creates geographic concentration risk for distant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Drywall and Building Plaster Market functions as a stable compounder anchored by code-mandated fire-resistance requirements that sustain replacement demand across residential and commercial building cycles.
For Market Incumbents: Deepen backward integration into synthetic gypsum processing to dampen input cost volatility and defend margin position against emerging Asian exporters. Prioritize certification investment under EU Green Deal carbon accounting rules to capture specification premium in continental commercial projects. Expand manufacturing footprint in India Tier-2 cities before domestic producers achieve scale. For New Entrants and Emerging Players: Tier-2 Indian contractors represent the most penetrable buyer archetype, with Pune, Ahmedabad, and Hyderabad showing underpenetrated drywall adoption versus traditional lime plaster finishes. Target heritage restoration specialists in France and Italy with REACH-compliant perlite-based reformulations for wet-coat decorative applications. Pursue direct e-commerce channels for joint compounds and accessories to bypass consolidated wholesale distribution. For Investors and Strategic Acquirers: Building materials conglomerates with captive gypsum supply are the most active acquirer in this space, seeking regional density in Central and Eastern Europe. Mid-cap specialists with synthetic gypsum processing capabilities and CE marking compliance represent the optimal acquisition profile. Monitor the pace of EU carbon-accounting enforcement as the inflection signal for premium pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Gypsum Backward Integration | Captive FGD byproduct processing locks in input cost stability for integrated mills. |
| Lightweight Core Technology Scale-Up | Glass fiber-reinforced reduced-density formulations compress freight economics for distant distribution. |
| EU Green Deal Carbon Certification | Embedded emissions disclosure creates first-mover specification advantage in continental markets. |
| Prefabricated Panel Partnerships | Offsite construction module integration captures national homebuilder direct procurement relationships. |
| India Tier-2 Distribution Buildout | Early presence in Pune and Hyderabad corridors preempts domestic producer scale advantages. |
Methodological Framework
Bottom-up residential and commercial construction modeling reconciled against top-down gypsum board production tracking forms the analytical core. Primary interviews with plant managers at calcination facilities, procurement leads at national homebuilders, distribution channel partners, and technical R&D directors at finishing compound manufacturers were cross-validated against secondary sources including ASTM certification registries, EU Construction Products Regulation audit filings, customs and trade data, and SEC 10-K disclosures from publicly traded building materials conglomerates.
Historical trendline analysis of housing starts, commercial square footage permits, and gypsum consumption intensity per construction dollar established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product chemistry tier, construction phase application, procurement channel structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included natural gas price volatility indices and synthetic gypsum substitution rates.
Underlying measurement precision varies by segment; gypsum board volume estimates carry tighter precision than ornamental plaster artisanal application data. Forecasts reflect assumptions regarding housing start recovery trajectories, REACH silica reformulation compliance timelines, and carbon-accounting enforcement pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global FRP Rebar Market
Building Materials
Cribbing Blocks Market
Building Materials
Sanded Grout Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Foam Concrete Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Cement Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Italy Facade Market
Building Materials
US Contract Glazing Market
Building Materials
United States Architectural Coatings Market
Building Materials
Concrete and Cement Market
Building Materials
Spain Cement Market
Building Materials
Global Commercial Paving Slabs Market