
 Latin America Aluminum Door and Window Market | 2026-2036
Latin America Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Aluminum Door and Window Market Analytics
Specifiers and large-scale contractors are rewriting distribution economics across Latin America. Hydro leverages captive aluminum smelting and extrusion capacity to sustain cost advantages in Brazilian project markets. Reynaers specializes in thermally advanced systems and anchors premium positioning among architects specifying high-rise commercial towers. Ykk Corporation competes through vertically integrated hardware and frame manufacturing that extends quality control across Mexican and Colombian operations.
Latin America aluminum door and window systems combine extruded aluminum alloy profiles with polyamide thermal breaks, glazing gaskets, and hardware assemblies engineered for structural load, air infiltration, and acoustic performance. Primary commercial purpose spans climate-responsive building envelopes that reduce HVAC energy transfer while meeting wind-load and water-penetration standards in tropical and subtropical zones. Sliding doors dominate new construction volumes across residential and commercial sectors where expansive glass walls maximize natural ventilation and daylight penetration. Thermal break technology leads margin pools as energy codes tighten across Mexico, Brazil, and Chile, while automated systems represent the fastest-growing technology segment driven by smart building integration in premium commercial developments.
Brazil's INMETRO certification mandates thermal performance labeling for fenestration products, directly shaping manufacturer R&D priorities and product line rationalization. Mexico's CONUEE energy efficiency standards for building envelopes and Colombia's NSR-10 seismic-resistant design codes collectively filter market access and elevate technical compliance costs for imported systems. Stakeholders must monitor regulatory divergence across national codes and assess localized extrusion capacity before committing capital to regional expansion strategies.
Market Dynamics
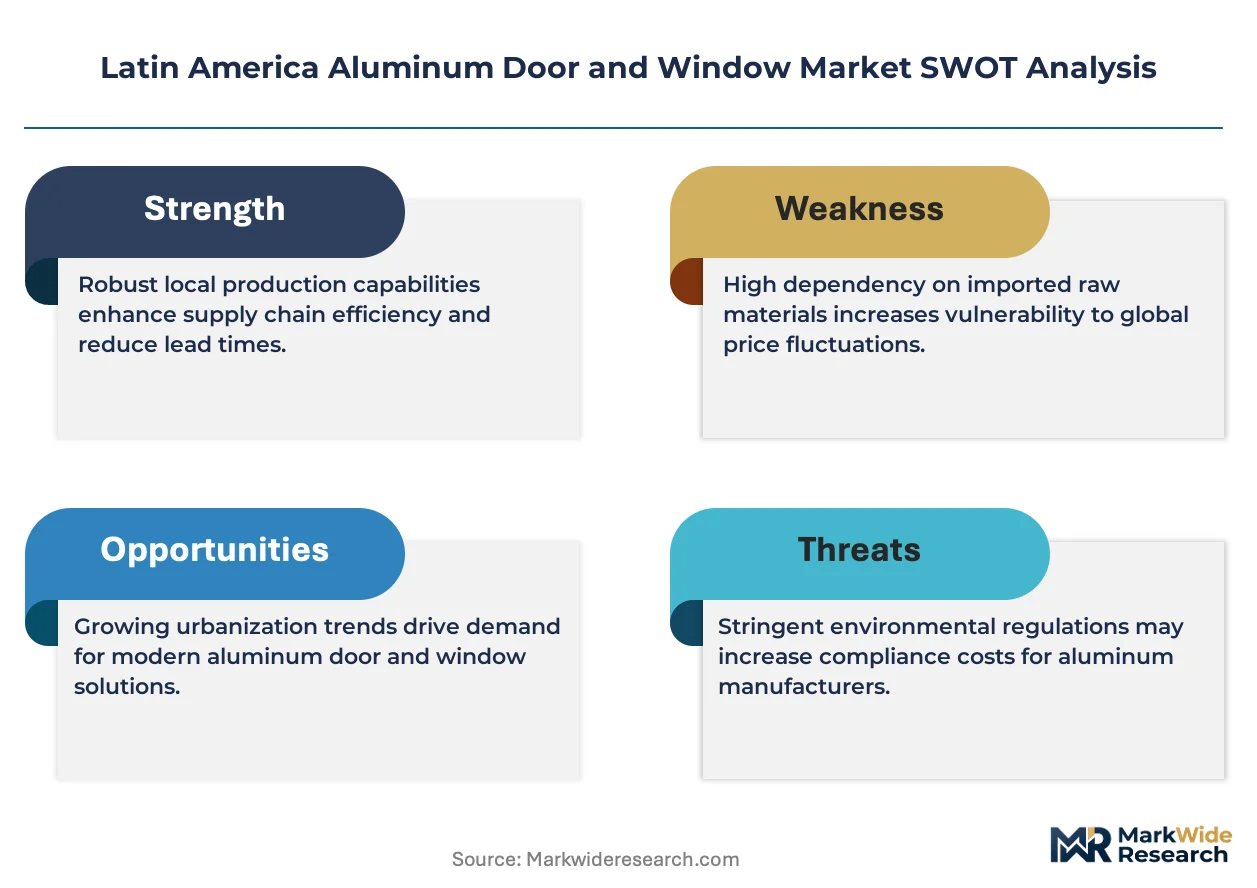
Energy code convergence across Brazil, Mexico, and Chile is forcing manufacturers to reengineer thermal break systems and extrusion alloys simultaneously, compressing product development cycles while elevating compliance costs.
Growth Catalysts
- INMETRO thermal labeling mandate:Brazil's certification requirement for fenestration performance creates pull for thermally broken aluminum systems as builders seek labeled products for residential high-rises in São Paulo and Rio de Janeiro.
- Commercial real estate expansion:Office tower construction in Mexico City and Monterrey drives specification of high-performance curtain wall systems with integrated automated ventilation.
- Seismic-resistant design codes:Colombia's NSR-10 standards for structural performance accelerate replacement of older steel and wood window systems with engineered aluminum frames in Bogotá and Medellín high-rises.
Market Restraints
- Primary aluminum price volatility:Smelter capacity concentration in northern Brazil exposes extruders to LME price swings that compress margin stability during project bidding cycles.
- Polyamide thermal break supply concentration:Limited regional production of PA66 GF25 isolators forces dependence on Asian and European suppliers, extending lead times for certified systems.
- PVC-u substitution in mass housing:Lower upfront costs of vinyl frames capture entry-level residential segments in Brazilian northeast and Colombian peripheral markets where thermal performance requirements remain unenforced.
Strategic Opportunities
- Smart building integration:Sensor-embedded automated opening systems represent white space as Mexico's CONUEE standards evolve to reward responsive envelope technologies in premium commercial developments.
- Chilean market penetration:Underdeveloped local extrusion capacity creates import opportunity for Brazilian and Mexican manufacturers with INMETRO-certified thermal systems as Santiago's building codes tighten.
- Retrofit channel development:Direct-to-property-manager sales models bypass traditional distributor markups in aging commercial stock across Buenos Aires and Lima where envelope upgrades lag new construction standards.
Industry Challenges
- Thermal modeling expertise scarcity:Finite pool of engineers capable of NFRC-equivalent simulation and INMETRO documentation creates bottlenecks for product line expansion.
- Multi-jurisdiction certification timelines:Sequential approval requirements across Brazilian state-level environmental permits, Mexican PROFEPA clearances, and Colombian seismic testing extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Aluminum Door and Window Market |
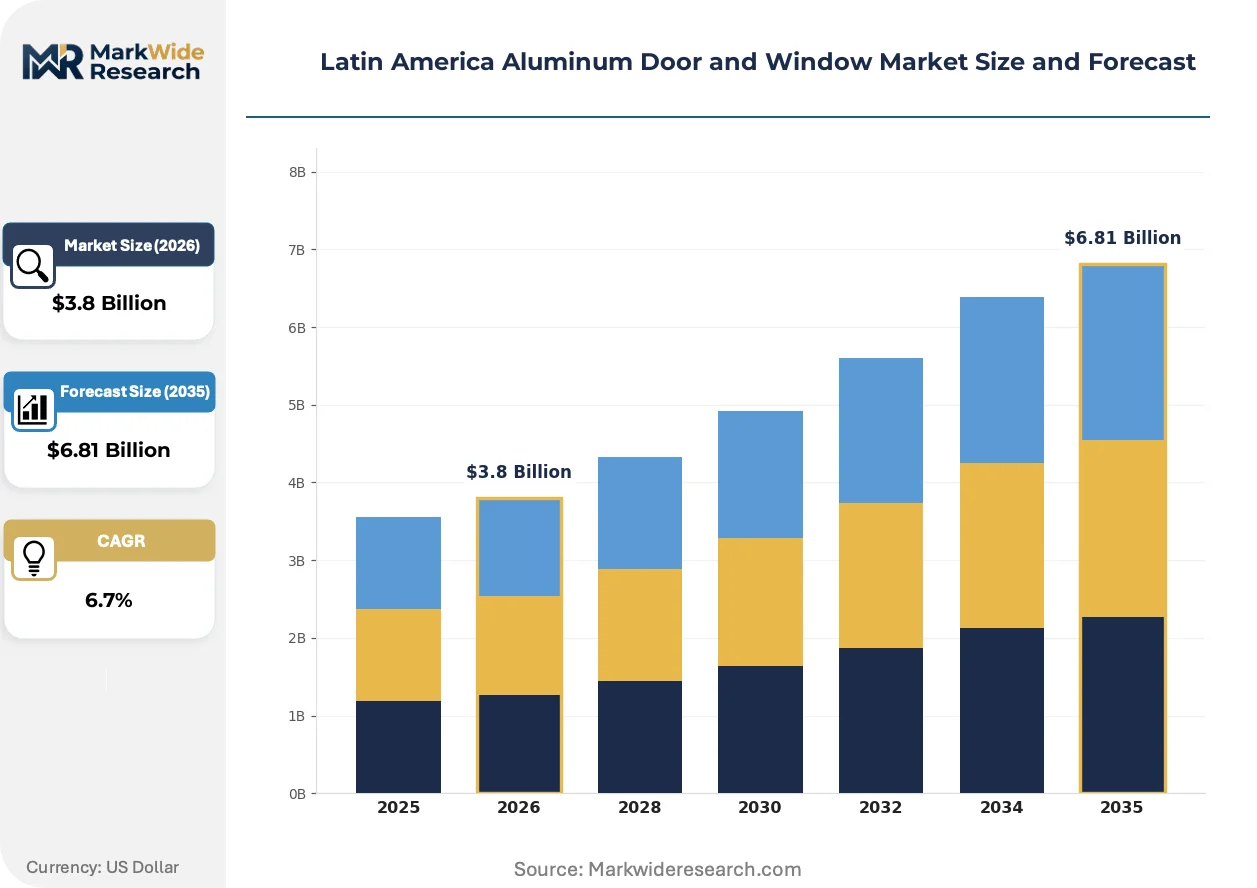
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Hinged Windows, Bi-Fold Doors, Casement Windows End User: Residential Sector, Commercial Sector, Industrial Sector, Government Buildings Application: New Construction, Renovation, Replacement, Architectural Design Technology: Thermal Break, Laminated Glass, Frames, Automated Systems |
| Companies Covered | Hydro, Schuco, AL-PROMT S.R.L, Lixil Corporation, Ykk Corporation, Arcom Glass, Reynaers, Fletcher Building Limited, Aluprof, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Aluminum Door and Window Market Evolving Landscape
Thermal performance engineering and automation integration are converging to redefine competitive advantage as code compliance becomes inseparable from digital building management.
Polyamide-aluminum hybrid thermal break technology is hybridizing conventional extrusion architectures with fiber-reinforced isolator geometries that reduce thermal transmittance below 1.4 W/m²K. Specifiers in São Paulo's Class A commercial towers are mandating these systems for LEED-equivalent certifications. The technology is hybridizing cost structures by compressing the premium gap between standard and high-performance frames.
CONUEE's updated building envelope efficiency standards for non-residential structures now mandate U-value disclosure and air infiltration testing for systems above 15 square meters of glazed area. Mexican manufacturers must retool extrusion dies and gasket channels to meet the 2024-2025 compliance window. Large-format sliding systems for Monterrey industrial parks face the steepest redesign requirements.
Developer procurement teams are consolidating vendor relationships around single-source envelope responsibility. Traditional separation between window contractors and facade specialists collapses as Grupo Carso and similar conglomerates demand turnkey performance guarantees. This consolidation is most visible in Mexico City's mixed-use mega-developments where envelope commissioning now falls to integrated suppliers.
Latin America Aluminum Door and Window Market Segmentation
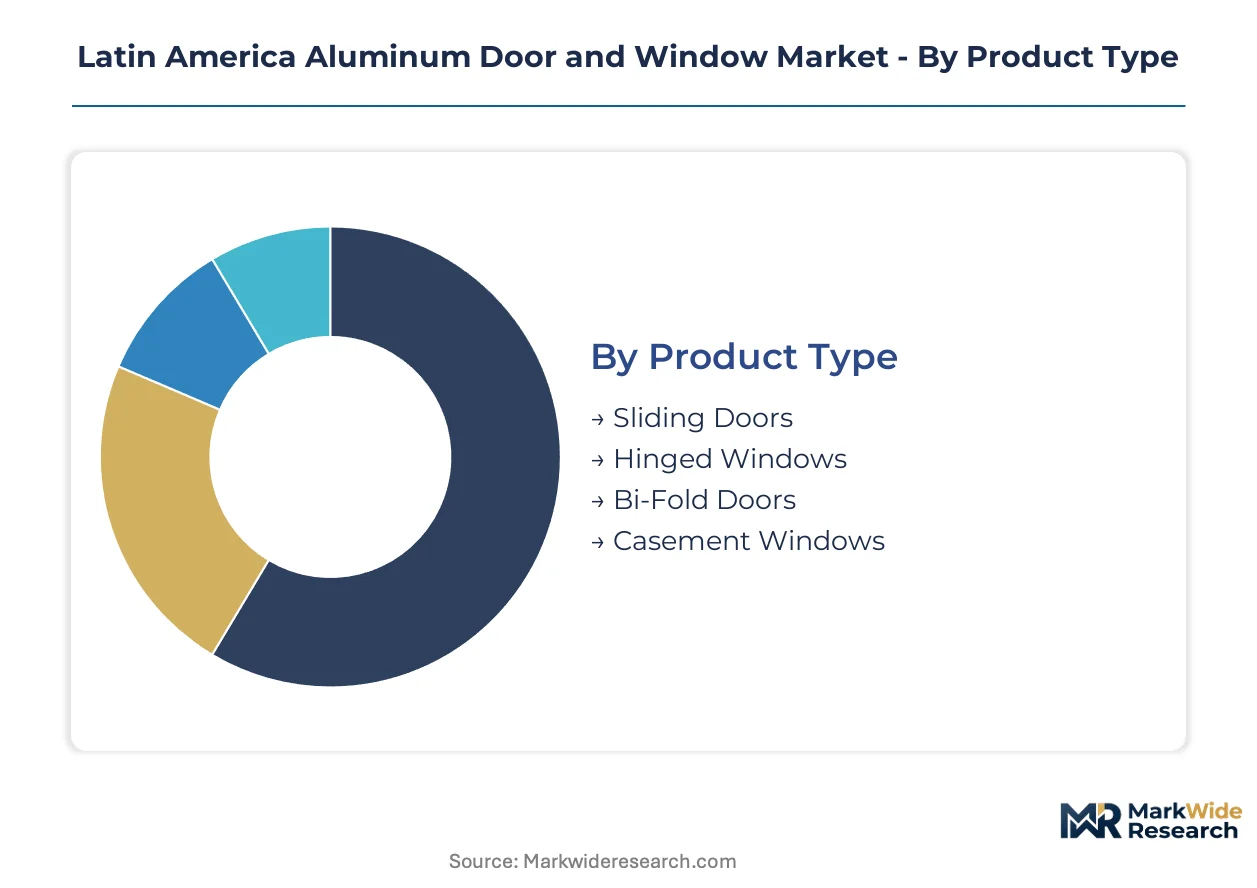
Segmentation in Latin American aluminum fenestration reveals how product specifications, end-user procurement patterns, and regulatory compliance requirements fragment addressable markets across national boundaries. Builders in São Paulo high-rises source differently than Monterrey industrial developers or Bogotá seismic-retrofit contractors, creating distinct competitive arenas within each slice.
Product Type:
Product portfolios span the functional spectrum from space-efficient sliding mechanisms to precision-ventilated casement systems, each commanding distinct specification logic among architects and contractors.
- Sliding Doors:Horizontal track systems with tandem roller assemblies and reinforced bottom rails support expansive glass spans up to six meters. Residential towers across Brazil's southeastern states specify these for balcony access in compact floor plans where swing radius is constrained. The format dominates new construction volumes through its ventilation efficiency and daylight maximization.
- Hinged Windows:Side-hung sash configurations with multi-point locking hardware deliver superior air infiltration control versus sliding alternatives. Mexico's CONUEE envelope standards are accelerating specification in Monterrey and Mexico City commercial towers where pressurized HVAC systems demand tight perimeter seals.
- Bi-Fold Doors:Accordion-folding panel systems with continuous hinge lines and bottom-guide tracks enable complete wall apertures. Colombian luxury residential developments in Medellín's El Poblado district favor these for indoor-outdoor integration.
- Casement Windows:Outward-projecting sash designs with crank-operated hardware optimize catchment of prevailing breezes in tropical coastal zones. Brazilian northeast residential markets specify these for natural ventilation compliance.
The dominant share belongs to Sliding Doors, while Bi-Fold Doors is closing the gap fastest.
End User:
Procurement sophistication varies sharply across customer categories, from volume-driven residential developers to performance-specifying government agencies with extended compliance documentation requirements.
- Residential Sector:Single-family builders and multi-family developers constitute the volume foundation, with Brazilian Minha Casa Minha Vida program participants and Mexican INFONAVIT-subsidized projects driving standardized thermal break adoption. Pricing pressure is intense at entry tiers.
- Commercial Sector:Office tower developers and retail chain constructors specify integrated curtain wall systems with automated ventilation. Mexico City's Santa Fe and Polanco districts concentrate Class A demand where LEED-equivalent certification is table stakes.
- Industrial Sector:Manufacturing facility constructors prioritize large-format sliding systems for loading bays and natural illumination in production halls. Monterrey industrial park developers specify heavy-duty frames with enhanced wind-load ratings.
- Government Buildings:Federal and municipal procurement mandates thermal performance labeling and seismic certification, extending sales cycles but securing premium pricing. Colombian Ministry of Housing projects require NSR-10 compliance documentation.
Residential Sector commands the largest addressable base, though Commercial Sector is expanding most quickly as energy codes tighten.
Application:
Project timing relative to construction phase determines specification flexibility, with new construction permitting full system optimization versus retrofit constraints imposed by existing structural openings.
- New Construction:Ground-up projects allow integrated envelope design with thermal modeling from schematic phase. Brazilian residential high-rises in São Paulo's Brooklin district specify INMETRO-labeled systems during pre-construction to secure financing.
- Renovation:Partial envelope upgrades in aging commercial stock across Buenos Aires and Lima replace failed seals and degraded hardware without full frame replacement. Property managers seek drop-in compatibility with minimal facade disruption.
- Replacement:Like-for-like swaps of failed units in residential and light commercial buildings prioritize dimensional matching over performance upgrade. Brazilian northeast markets show concentration where salt corrosion degrades coastal installations.
- Architectural Design:Signature projects with custom-engineered solutions command premium engineering fees and extended lead times. Colombian high-end residential architects in Bogotá specify bespoke bi-fold configurations for penthouse terraces.
New Construction absorbs the majority of system value, yet Renovation is climbing the fastest as commercial retrofit incentives proliferate.
Technology:
Technology tiers separate commodity extruders from performance specialists, with thermal engineering and automation integration defining margin architecture.
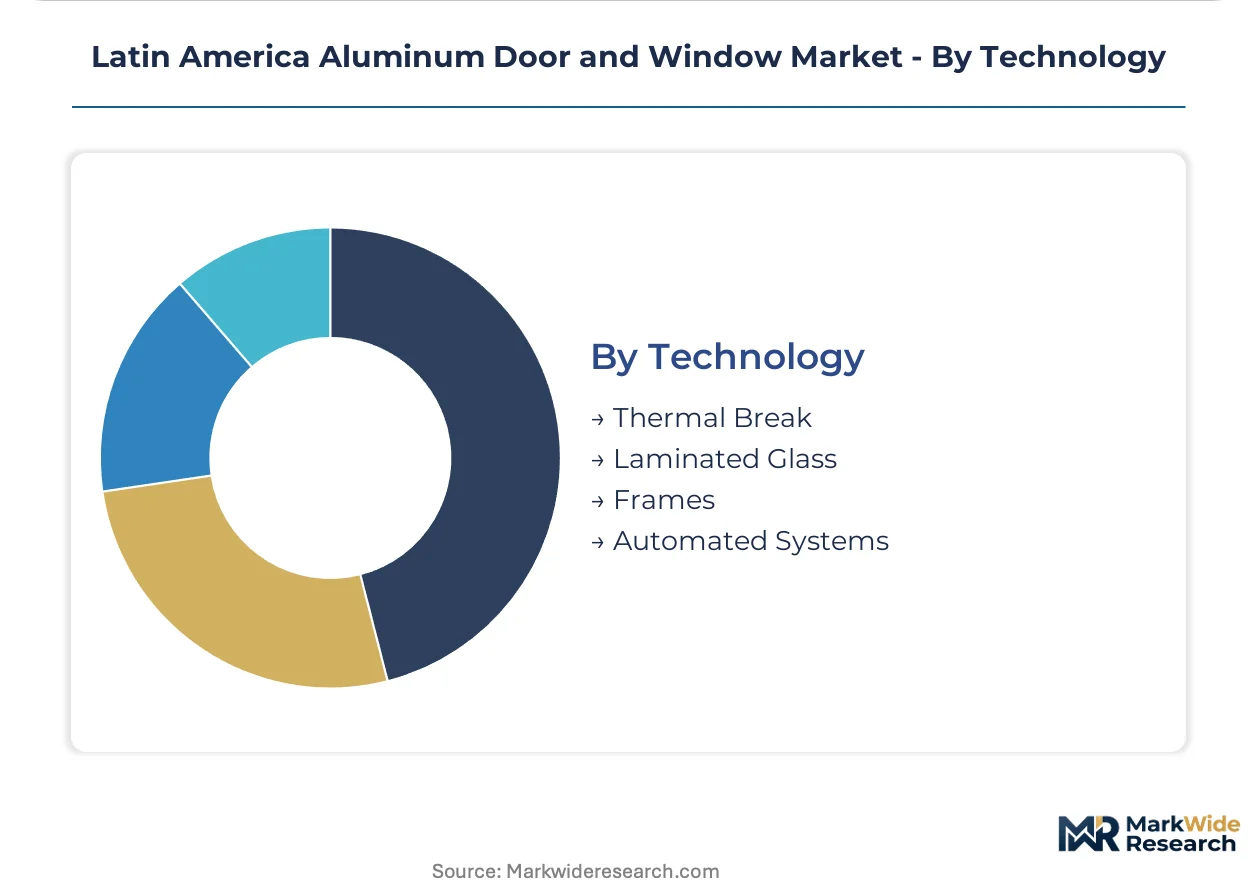
- Thermal Break:Polyamide-aluminum hybrid isolator systems reduce frame U-values below 1.4 W/m²K through fiber-reinforced PA66 GF25 barriers. INMETRO certification mandates are converting Brazilian manufacturers from standard to thermally broken product lines.
- Laminated Glass:Interlayer-bonded glazing assemblies with acoustic dampening and security retention properties. Mexico City airport-adjacent commercial towers specify these for noise attenuation compliance.
- Frames:Base extrusion systems without thermal isolation serve price-sensitive markets where energy codes remain unenforced. Brazilian northeast mass housing and Colombian peripheral developments concentrate demand.
- Automated Systems:Sensor-integrated motorized opening mechanisms with building management system connectivity. Premium commercial developments in Mexico City's Santa Fe corridor are piloting responsive envelope technologies.
Thermal Break holds the established technology lead, while Automated Systems is gaining share fastest as smart building integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's import capacity for polyamide thermal break isolators and precision hardware, anchoring the region's supply chain for high-performance fenestration systems.
Brazil
São Paulo's Brooklin and Pinheiros districts concentrate Class A residential tower construction where INMETRO thermal labeling mandates drive specification of thermally broken aluminum frames. The Minha Casa Minha Vida housing program extends standardized thermal break adoption to entry-level segments. Extrusion clusters in Minas Gerais and São Paulo states supply project markets across the southeastern industrial corridor.
Mexico
Monterrey's industrial park expansion and Mexico City's Santa Fe commercial corridor generate sustained demand for automated curtain wall systems. CONUEE envelope efficiency standards for non-residential structures mandate U-value disclosure, compressing manufacturer retooling timelines through 2025. Nuevo León's manufacturing base anchors northern distribution networks serving border-adjacent developments.
Colombia
Medellín's El Poblado and Bogotá's Chapinero districts favor bi-fold and thermally advanced systems for luxury residential and commercial retrofits. NSR-10 seismic-resistant design codes accelerate replacement of legacy steel and wood frames in high-rise construction. Antioquia Department's engineering services cluster supports compliance documentation for national certification.
Chile
Santiago's tightening building energy codes and underdeveloped local extrusion capacity create import dependence for INMETRO-certified thermal systems. Valparaíso port infrastructure enables Brazilian and Mexican manufacturer access to central Chilean project markets. Metropolitan Region construction activity concentrates demand for high-performance envelope components.
Argentina
Buenos Aires commercial retrofit activity lags new construction standards, creating channel opportunity for direct-to-property-manager sales models. Aging envelope stock in Puerto Madero and Retiro districts drives replacement demand for drop-in compatible aluminum systems. Local currency volatility constrains large-scale project financing and import capacity.
Latin America Aluminum Door and Window Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying thermal breaks, hardware, and glazing gaskets to fabricators and installers. The Latin American aluminum fenestration market structures around three archetypes: captive smelter-extruders with backward integration into primary aluminum, European system houses specializing in thermally advanced architectural solutions, and Asian manufacturers with vertically integrated hardware production. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into automated opening systems.
Among the named participants, Hydro exemplifies the captive smelter-extruder archetype with Brazilian project market presence. Reynaers occupies a position representing European system house specialization in thermally advanced commercial solutions. Ykk Corporation anchors the Asian vertically integrated hardware manufacturer tier across Mexican and Colombian operations.
| Leading Market Players |
|---|
| Hydro |
| Schuco |
| AL-PROMT S.R.L |
| Lixil Corporation |
| Ykk Corporation |
| Arcom Glass |
| Reynaers |
| Fletcher Building Limited |
| Aluprof |
| Others |
Value Network & Pricing Analysis
Polyamide thermal break isolator production concentrates in Asian and European supplier bases, anchoring margin capture downstream with fabricators who secure PA66 GF25 inventory through long-term offtake agreements. Brazilian extruders with captive smelting capacity retain pricing power in project bidding cycles where LME volatility otherwise compresses margins.
Pricing Analysis
Volume-discount tiering structures separate government procurement mandates from speculative builder purchases and retrofit channel spot buying. Three-tier pricing stratification across INMETRO-certified thermal systems, standard extrusion frames, and non-thermally broken commodity profiles reflects certification grade and volume scale differentiation. Cost compression in entry-level residential tiers intensifies as PVC-u substitution captures Brazilian northeast and Colombian peripheral markets. Mass housing developers under INFONAVIT and Minha Casa Minha Vida programs exhibit highest price sensitivity; Class A commercial tower specifiers in São Paulo and Mexico City demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Brazilian extrusion clusters in Minas Gerais and São Paulo states, Mexican integrated system houses in Nuevo León, and Colombian fabrication networks anchored in Antioquia Department. Primary aluminum feedstock draws from northern Brazilian smelter capacity, polyamide isolators source from European and Asian chemical producers, and precision hardware feeds from Ykk Corporation's vertically integrated Mexican operations. Single-source vulnerability in thermal break supply extends lead times for certified systems. Distribution runs through project-direct channels for large-scale developments and regional distributor networks for residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including envelope commissioning, automated system integration, and post-installation thermal performance auditing expand faster than hardware sales as building management system connectivity becomes standard in premium commercial specifications.
For Market Incumbents: Harden thermal modeling engineering capabilities against scarcity bottlenecks that constrain product line expansion across Brazilian state-level environmental permits and Colombian seismic testing protocols. Deepen backward integration into polyamide isolator supply through strategic partnerships with European chemical producers to reduce Asian import dependency. Prioritize certification investment in sequential INMETRO, CONUEE, and NSR-10 approvals to compress multi-jurisdiction launch timelines. For New Entrants and Emerging Players: Pursue Chilean market penetration where underdeveloped local extrusion capacity creates import opportunity for INMETRO-certified thermal systems as Santiago's building codes tighten. Target retrofit channel development in aging Buenos Aires and Lima commercial stock where direct-to-property-manager sales models bypass traditional distributor markups. Anchor go-to-market positioning around envelope commissioning services rather than hardware-only supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Brazilian extrusion specialists with captive smelting capacity and established INMETRO certification portfolios. Long-term viability across the analysis window favors platform integrators with single-source envelope responsibility capabilities over component-only suppliers. Monitor CONUEE standard evolution toward responsive envelope technologies as inflection indicator for automated system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Break Technology Investment | PA66 GF25 isolator capacity secures INMETRO certification access for Brazilian high-rise specifications. |
| Automated System Integration | Sensor-embedded opening mechanisms capture CONUEE-responsive envelope rewards in Mexico City Santa Fe developments. |
| Retrofit Channel Development | Direct property-manager sales bypass distributor markups in aging Buenos Aires commercial envelope stock. |
| Chilean Market Entry | Santiago code tightening and import-dependent extrusion capacity create white-space for certified system suppliers. |
| Backward Integration Partnerships | Polyamide isolator supply agreements reduce Asian import lead times and certification documentation delays. |
Research Methodology
Desk research of trade association publications, national energy regulator filings, and customs import records preceded structured interviews with aluminum extrusion plant managers, commercial construction procurement leads, thermal systems R&D directors, and facade engineering consultants. Secondary validation drew from INMETRO certification databases, CONUEE technical standards documentation, and Colombian NSR-10 seismic compliance records. Bottom-up project pipeline analysis and top-down construction spending forecasts were triangulated to establish market sizing.
Assumptions held fixed include continued enforcement of INMETRO thermal labeling mandates, CONUEE envelope efficiency standard implementation timelines, and NSR-10 seismic code applicability across high-rise construction. Segmentation modeling spanned product type, end-user sector, application timing, and technology tier dimensions. CAGRs were derived from regression analysis of historical construction completion data against fenestration intensity coefficients. Industry-specific forecast inputs included LME aluminum price trajectory assumptions and polyamide thermal break supply elasticity estimates.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Mexican peso volatility, or Chilean construction credit availability would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and energy code adoption pace. Quarterly review of national construction permit issuance, thermal certification application volumes, and primary aluminum inventory levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Fireproof Cladding Market
Building Materials
Global Metal Cladding Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Qatar Facade Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Construction Repair Composites Market
Building Materials
Door Frame Metal Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Portland Cement Market
Building Materials
Facade Gasket Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Natural Stone Slab Market