
 Automated Fiber Placement Market | 2026-2036
Automated Fiber Placement Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Fiber Placement Market Analysis
Defense procurement channels is rewriting how AFP equipment flows from European and North American builders to prime contractors. Electroimpact Inc. leverages its long-standing position in wing fabrication systems to sustain orders from Boeing and Airbus-aligned programs. Fives Group anchors the French supply base with integrated automation lines for aerostructures. Ingersoll Machine Tools Inc. competes on gantry-scale systems for wind turbine blade and aerospace applications.
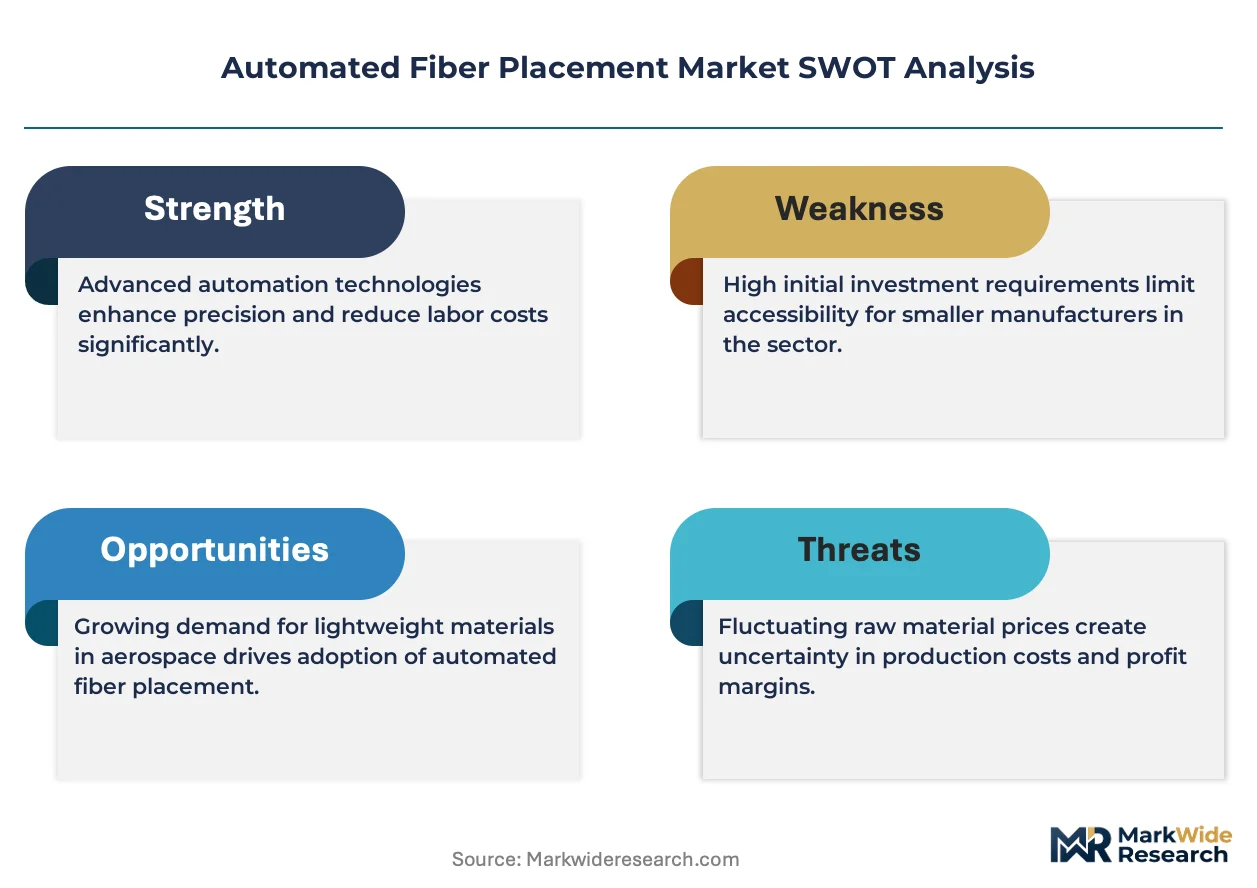
Automated fiber placement deposits thermoset or thermoplastic composite tapes onto contoured molds via computer-guided heads, achieving fiber angles within 0.5 degrees and void contents below 2 percent for primary load-bearing structures. The process replaces hand layup in aerospace fuselage sections and wing skins where weight reduction targets exceed 20 percent against metallic alternatives. Thermoplastic AFP systems represent the fastest-growing technology segment as out-of-autoclave processing slashes cure cycle energy and tooling capital. Aerospace applications dominate current value capture, though wind energy blade spar manufacturing is expanding the addressable equipment base. Component-level demand tilts toward machines and software as OEMs and Tier-1 suppliers internalize programming capability and reduce reliance on external tape path engineering services.
FAA airworthiness standards, EASA CS-25 certification requirements, and ISO 9001 quality management frameworks govern AFP-produced part qualification for commercial aviation. These bodies mandate traceable fiber placement records, automated inspection integration, and statistical process control that elevate equipment specification thresholds and exclude non-compliant suppliers. Stakeholders must monitor evolving thermoplastic welding standards and sustainability-linked procurement criteria from defense agencies and commercial OEMs.
Market Dynamics
Thermoplastic AFP systems are compressing cure cycles and reshaping capital allocation across aerospace manufacturing, forcing equipment suppliers to reconfigure automation architectures around out-of-autoclave processing requirements.
Growth Catalysts
- FAA Airworthiness Standards:Traceable fiber placement mandates for primary structures drive automated inspection integration and elevate equipment specification thresholds for commercial aviation suppliers.
- Wind Energy Blade Spar Manufacturing:Gantry-scale AFP systems penetrate renewable energy applications as turbine OEMs seek weight reduction in carbon fiber spar caps.
- Defense Procurement Channels:Sustainability-linked procurement criteria from defense agencies accelerate thermoplastic system adoption for reduced energy intensity in military airframe production.
Market Restraints
- Carbon Fiber Tape Supply Concentration:Toray Industries, Hexcel, and Solvay control prepreg supply, creating input cost volatility and qualification bottlenecks for Tier-2 equipment buyers.
- EASA CS-25 Certification Friction:Statistical process control documentation requirements extend supplier qualification timelines and exclude non-compliant automation vendors from European aerospace programs.
- Hand Layup Substitution Resistance:Low-volume aerostructure producers retain manual processes for complex geometries where AFP programming costs exceed labor arbitrage savings.
Strategic Opportunities
- Urban Air Mobility Airframes:eVTOL manufacturers in the United States and Germany present greenfield demand for compact AFP cells producing thermoplastic fuselage sections.
- ISO 9001 Quality Framework Convergence:Automated inspection integration creates white space for software vendors bundling path planning with statistical process control modules.
- Digital Twin Integration:Real-time fiber placement monitoring fused with predictive maintenance algorithms enables outcome-based equipment service contracts.
Industry Challenges
- Composite Process Engineer Scarcity:Programming expertise for multi-axis path generation concentrates at OEMs and major Tier-1 suppliers, constraining Tier-2 automation adoption.
- Legacy System Integration Complexity:Retrofitting thermoplastic-capable heads onto existing gantry infrastructure requires proprietary control architecture reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Fiber Placement Market |
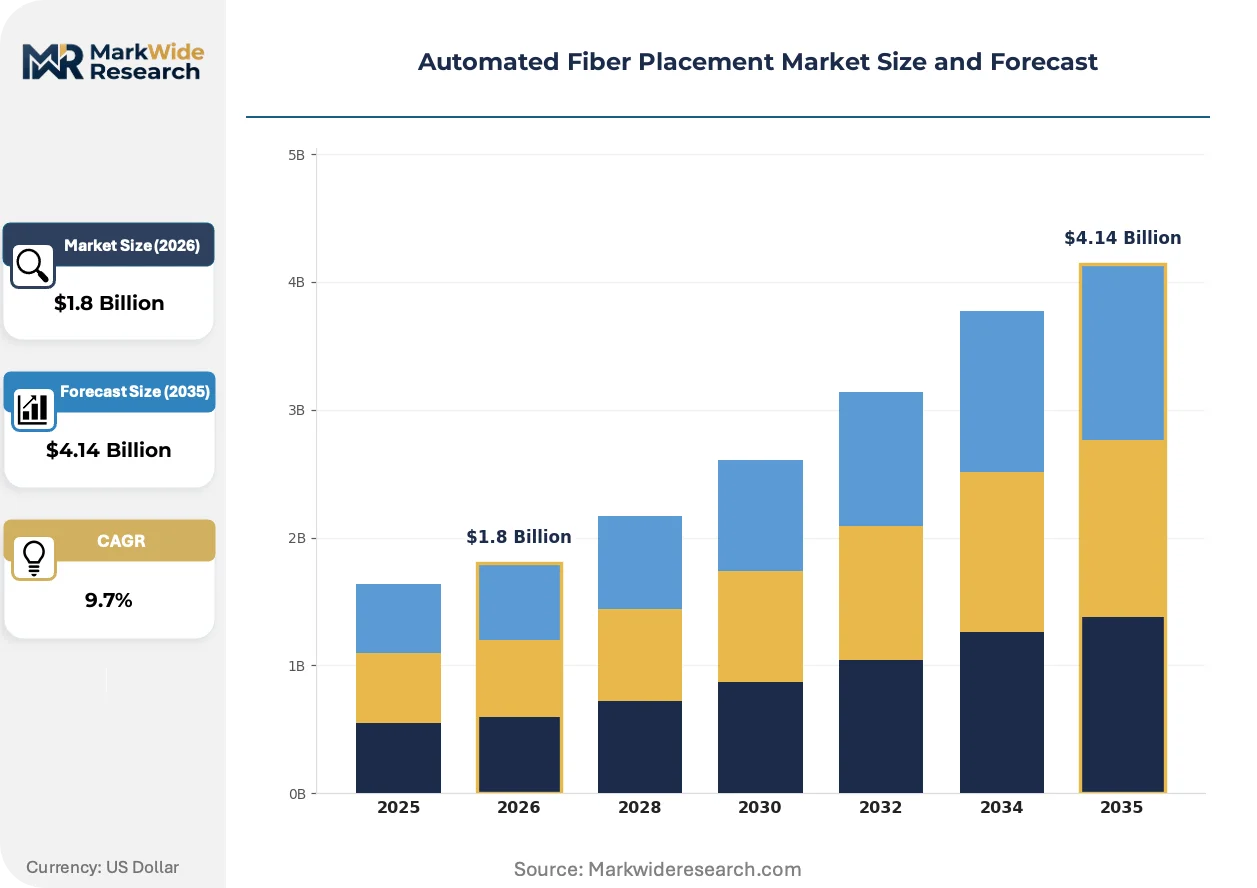
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Out-of-Autoclave, Thermoplastic, Thermosetting, Resin Infusion Application: Aerospace, Automotive, Wind Energy, Sports Equipment Component: Software, Machine, Tooling, Raw Material End User: OEMs, Tier-1 Suppliers, Composite Manufacturers, Aerospace Companies |
| Companies Covered | KUKA AG, Electroimpact Inc., Hexcel Corporation, M.Torres Diseños Industriales S.A.U., Coriolis Composites Technologies SAS, Boeing Company, Fives Group, Ingersoll Machine Tools Inc., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Fiber Placement Market Emerging Trajectories
Automation architectures are bifurcating between thermoset legacy installations and thermoplastic-native systems, with software-defined process control emerging as the decisive capability differentiator across equipment tiers.
Laser-assisted fiber placement is hybridizing thermal management with precision deposition. Aerospace OEMs in France and Germany adopt this technology for complex curvature wing skins. The convergence of localized heating and real-time compaction is hybridizing process steps previously separated into discrete autoclave cycles.
EU Green Deal carbon accounting requirements are mandating embodied energy disclosure for aerostructure imports. Equipment suppliers must now document electricity consumption per deposited kilogram. French and German machine builders are responding with out-of-autoclave system configurations that eliminate thermal cure infrastructure.
Buyer concentration among Boeing and Airbus-aligned programs is compressing equipment procurement cycles. Tier-1 suppliers internalize programming capability and reduce reliance on external tape path engineering services. This behavioral shift is most visible in the United States, where Electroimpact and Ingersoll compete on software licensing models rather than hardware margins alone.
Automated Fiber Placement Market Segmentation
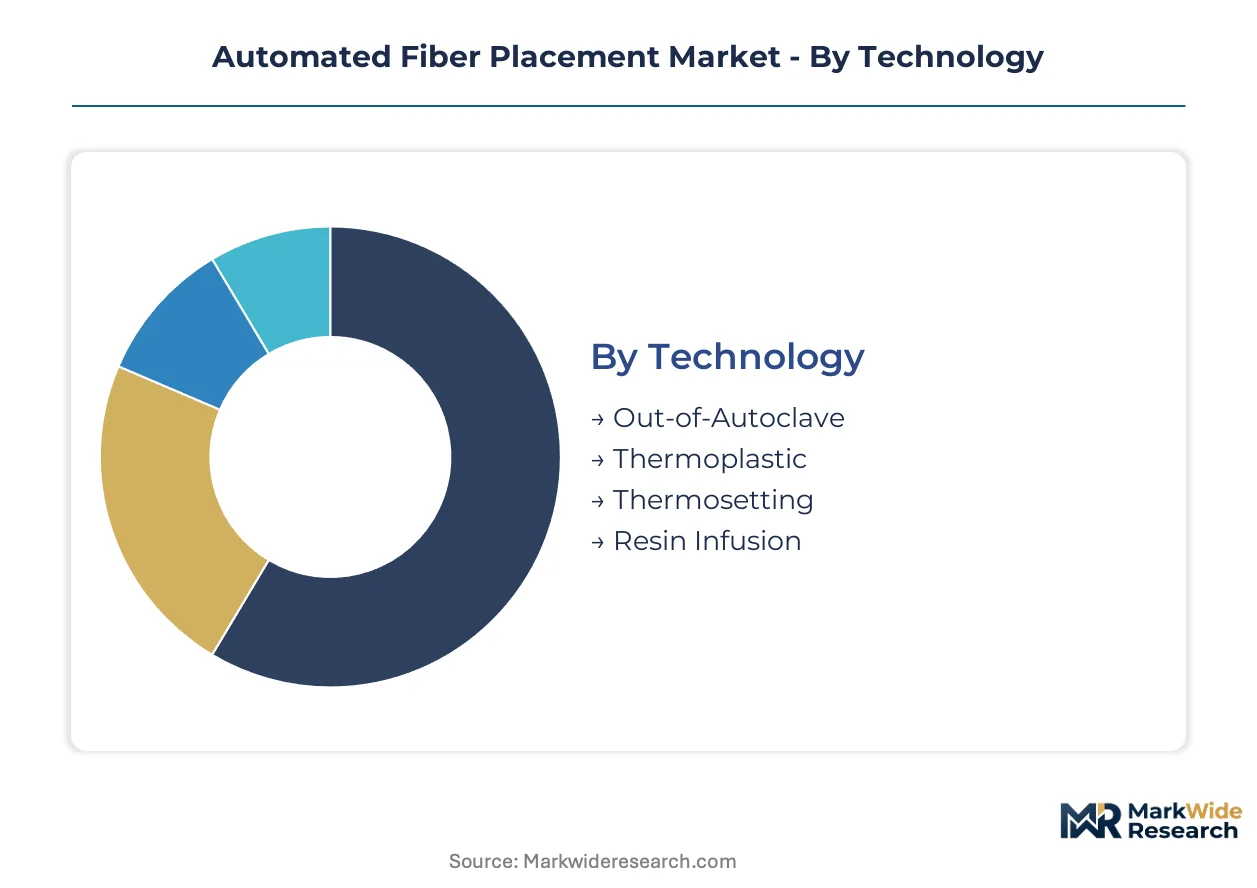
Technology choice dictates capital intensity and processing speed for AFP equipment buyers. Application mix shifts with composite adoption in mobility sectors. Component and end-user segmentation reveals where value capture concentrates across the supply chain.
Technology:
Process thermal management defines the use-case spectrum from legacy autoclave-dependent systems to emerging out-of-autoclave architectures.
- Thermoplastic:Laser- or ultrasonic-assisted deposition enables in-situ consolidation without post-cure cycles. Demand concentrates in United States defense programs and European commercial aerospace where Boeing and Airbus-aligned suppliers seek energy reduction. This segment gains share fastest as sustainability-linked procurement criteria harden.
- Out-of-Autoclave:Oven-cured thermoset systems eliminate pressure vessel infrastructure while maintaining aerospace-grade void content specifications. United States wind turbine blade manufacturers and Tier-1 aerostructure suppliers drive gantry-scale installations where cure cycle compression justifies equipment premiums.
- Thermosetting:Autoclave-cured prepreg deposition remains dominant in legacy aerospace programs with established qualification pathways. Established volume favors Thermosetting; emerging adoption favors Thermoplastic.
- Resin Infusion:Dry fiber placement combined with liquid resin injection suits large marine and industrial components where tape cost sensitivity exceeds deposition precision requirements.
Established volume favors Thermosetting; emerging adoption favors Thermoplastic.
Application:
Weight reduction targets scale inversely with production volumes across mobility sectors, concentrating equipment procurement in high-value, low-volume domains.
- Aerospace:Primary structure airworthiness mandates from FAA and EASA CS-25 specifications drive automated inspection integration and traceable fiber placement records. Boeing and Airbus sustain the largest installed base of gantry and robotic AFP cells for fuselage sections and wing skins.
- Wind Energy:Carbon fiber spar caps in turbine blades above 80-meter length require gantry-scale systems with multi-tow heads. Vestas and Siemens Gamesa procurement in Denmark and Spain expands the addressable equipment base beyond aerospace.
- Automotive:Structural battery enclosures and body-in-white components from BMW and Porsche programs in Germany adopt compact AFP cells where cycle time compression justifies thermoplastic processing.
- Sports Equipment:Bicycle frames and hockey sticks in Taiwan and China use tabletop systems where labor arbitrage still limits automation penetration.
Aerospace commands equipment specification thresholds; Wind Energy expands volume scale.
Component:
Value migration from hardware to software reshapes supplier margins as programming capability internalizes at OEMs.
- Machine:Gantry, robotic, and compact cell configurations span deposition widths from 3.2mm slit tape to 50mm tow. Electroimpact and Fives Group compete on control architecture integration in United States and French supply bases.
- Software:Path planning, collision avoidance, and statistical process control modules bundle with hardware or license separately. Tier-1 suppliers in Germany and Japan reduce reliance on external tape path engineering through in-house programming investment.
- Tooling:Mold surface preparation and sacrificial mandrel systems adapt to thermoplastic thermal expansion coefficients.
- Raw Material:Prepreg tape and slit tow supply from Toray, Hexcel, and Solvay creates input cost volatility for equipment buyers.
Machine captures capital expenditure; Software captures recurring revenue expansion.
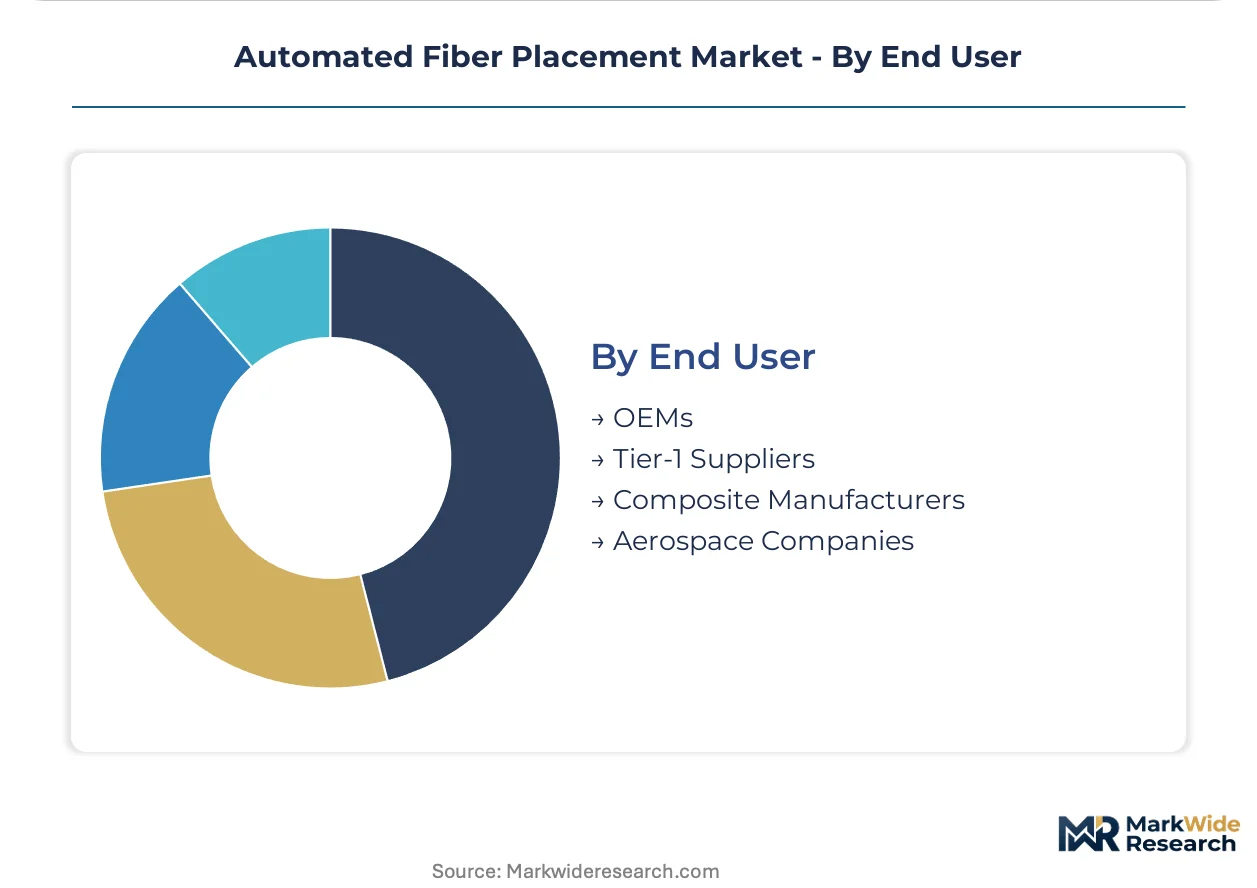
End User:
Procurement authority concentrates at OEMs while Tier-1 suppliers seek automation autonomy.
- OEMs:Boeing, Airbus, and Lockheed Martin direct equipment specification and supplier qualification through program-level contracts. Internal AFP programming groups in Seattle, Toulouse, and Fort Worth reduce external engineering dependency.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace operate captive AFP cells for wing and fuselage subassemblies. Qualification bottlenecks from FAA and EASA documentation requirements extend supplier onboarding timelines.
- Composite Manufacturers:Independent processors serving industrial and sports markets favor lower-specification systems where hand layup substitution economics remain marginal.
- Aerospace Companies:Defense primes including Northrop Grumman and BAE Systems sustain thermoplastic system adoption for reduced energy intensity in military airframe production.
OEMs dictate specification; Tier-1 Suppliers scale operational deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where defense procurement sustains equipment premiums, while European suppliers absorb certification cost burdens that compress margins in France and Germany.
United States
Boeing and Lockheed Martin direct gantry-scale AFP procurement for next-generation military and commercial programs. FAA airworthiness mandates for primary structures elevate automated inspection integration requirements. Seattle and Fort Worth clusters house internal programming groups that reduce external engineering dependency.
France
Airbus-aligned suppliers in Toulouse sustain integrated automation line demand for wing skin fabrication. EU Green Deal carbon accounting requirements mandate embodied energy disclosure for aerostructure equipment. Fives Group anchors the French supply base with out-of-autoclave system configurations.
Germany
BMW and Porsche programs adopt compact thermoplastic cells for structural battery enclosures and body-in-white components. EASA CS-25 certification documentation requirements extend supplier qualification timelines. Bavaria and Baden-Württemberg host Tier-1 suppliers internalizing path planning capability.
China
Domestic wind turbine OEMs expand gantry-scale installations for carbon fiber spar caps exceeding 80-meter blade lengths. The country's national aviation regulator aligns with ISO 9001 quality frameworks for composite part qualification. Yangtze River Delta manufacturing clusters absorb technology transfer from European equipment partnerships.
Japan
Toray Industries controls prepreg tape supply chains that feed equipment buyers across Asia-Pacific. METI industrial policy supports automation adoption in aerospace subcontractor networks. Nagoya-area suppliers serve as Tier-2 processors for Boeing and Airbus-aligned programs.
Automated Fiber Placement Market Vendor Landscape
Systems integrators and component specialists split the market into complementary tiers rather than direct competition. Concentration remains moderate with four to six significant equipment builders commanding aerospace specification authority. Two archetypes dominate: gantry-scale infrastructure providers serving OEM programs, and compact cell specialists penetrating automotive and urban air mobility. Competitive moves center on software licensing model transitions and thermoplastic-native system architectures that displace legacy thermoset installations.
Among United States-based fabricators, Electroimpact Inc. and Ingersoll Machine Tools Inc. occupy positions within the gantry-scale infrastructure tier, while Coriolis Composites Technologies SAS represents the European compact cell specialization. These three exemplify the geographic bifurcation of equipment supply, with North American builders commanding defense procurement channels and French specialists advancing laser-assisted fiber placement for complex curvature applications.
| Leading Market Players |
|---|
| KUKA AG |
| Electroimpact Inc. |
| Hexcel Corporation |
| M.Torres Diseños Industriales S.A.U. |
| Coriolis Composites Technologies SAS |
| Boeing Company |
| Fives Group |
| Ingersoll Machine Tools Inc. |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Toray Industries, Hexcel, and Solvay concentration in carbon fiber prepreg supply anchors cost volatility at the equipment buyer level, compressing margins for Tier-2 automation vendors while OEMs and Tier-1 suppliers capture downstream specification premiums through captive programming capability.
Pricing Analysis
Configured-to-order pricing for gantry-scale AFP systems commands 40-60 percent premiums over standard compact cell configurations, with differentiation driven by FAA/EASA certification tier and after-sales software licensing bundling. Price erosion runs through the wind energy segment as turbine OEMs force equipment commoditization for blade spar manufacturing. Tier-1 aerostructure suppliers exhibit lowest price sensitivity due to qualification lock-in effects, while independent composite manufacturers in sports equipment resist automation where hand layup labor arbitrage persists.
Supply Chain Analysis
Export control regimes under ITAR and dual-use technology classifications restrict thermoplastic AFP head flows from United States and French builders to Chinese and Russian end-users, fragmenting equipment availability across geopolitical blocs. Supply concentrates in United States, France, and Germany for system integration, while Japan and South Korea feed carbon fiber tape inputs. Single-source vulnerability concentrates in laser-assisted deposition optics sourced from German and United States precision optics houses. Distribution runs through direct OEM program contracts rather than channel intermediaries, with Boeing and Airbus-aligned suppliers negotiating frame agreements that span multiple aircraft development cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automated Fiber Placement Market rewards service-attach strategies as software licensing and predictive maintenance contracts expand recurring revenue pools faster than hardware depreciation cycles permit.
For Market Incumbents: Pre-empt thermoplastic-native system displacement of legacy thermoset installations by accelerating laser-assisted fiber placement R&D partnerships with French and German aerospace OEMs. Defend specification authority at Boeing and Airbus through embedded programming groups in Seattle and Toulouse that reduce customer reliance on external path engineering services. For New Entrants and Emerging Players: Build out compact AFP cell offerings targeting urban air mobility manufacturers in United States and Germany, where eVTOL airframe programs present greenfield demand absent entrenched supplier relationships. Penetrate through outcome-based service contracts bundling equipment with real-time fiber placement monitoring and predictive maintenance algorithms. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined automation specialists with statistical process control module capabilities, as OEM internalization of programming capability shifts value capture from hardware to recurring license revenue. Monitor thermoplastic welding standard finalization at FAA and EASA as inflection signal for out-of-autoclave system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Assisted Fiber Placement Investment | Enables in-situ consolidation for complex curvature wing skins at Airbus and Boeing suppliers. |
| Software Licensing Model Transition | Captures recurring revenue from path planning and collision avoidance modules at Tier-1 internalization trend. |
| Out-of-Autoclave System Configuration | Meets EU Green Deal embodied energy disclosure requirements for French aerostructure exports. |
| Predictive Maintenance Algorithm Development | Supports outcome-based service contracts with real-time fiber placement monitoring integration. |
| Urban Air Mobility Compact Cell Deployment | Addresses eVTOL fuselage manufacturing demand in United States and German greenfield programs. |
Methodological Framework
A standing panel of AFP equipment program managers, composite process engineers at Tier-1 suppliers, and aftermarket service directors provided ongoing calibration against operating reality. Primary interviews with Boeing and Airbus procurement leads, Fives Group and Electroimpact sales engineers, and wind turbine OEM manufacturing heads combined with secondary validation from FAA airworthiness directives, EASA CS-25 certification databases, and SEC filings from listed composite material suppliers. Bottom-up equipment shipment tracking and top-down aerospace program composite content estimates were triangulated to anchor market sizing.
Scenario bracketing around thermoplastic adoption pace, defense procurement cycle timing, and wind energy capacity expansion generated high-low range estimates across the projection horizon. Segmentation dimensions modeled include technology type, application sector, component category, and end-user tier, with CAGRs derived from equipment replacement cycles and new program ramp schedules. Industry-specific forecast inputs incorporated FAA certification queue depth and EU Green Deal carbon accounting implementation timelines.
Practitioners should monitor thermoplastic welding standard finalization, defense sustainability-linked procurement criteria evolution, and carbon fiber tape supply allocation shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
North America Mining Equipment Market
Construction and Engineering
Radiant Heating and Cooling Systems Market
Construction and Engineering
Brazil Construction Equipment Market
Construction and Engineering
Caulking Gun Market
Construction and Engineering
Saudi Arabia Residential Construction Market
Construction and Engineering
Spiral Fitting Machines Market
Construction and Engineering
US Hitter Based Hand Tools Market
Construction and Engineering
Reinforced Ultrafine Mill Market
Construction and Engineering
Flooring Tools Market
Construction and Engineering
Autonomous Construction Equipment Market
Construction and Engineering
Tower Bolt Market
Construction and Engineering
Sand Washing Machine Market
Construction and Engineering
Screw Compressor Rental Market
Construction and Engineering
Africa Prefabricated Housing Market
Construction and Engineering
Steam Humidifiers Market
Construction and Engineering
Canada Commercial Construction Market