
 Geocells Market | 2026-2036
Geocells Market Size, Share, and Industry Trends Forecast 2026-2036
Geocells Market Analysis
The geocells market is shifting between premium engineered-grade systems and commodity-priced alternatives as specification standards diverge across public and private projects. NAUE GmbH & Co. KG leverages its German manufacturing base to sustain certification-heavy supply into European rail embankment programs. Strata Systems, Inc. anchors its position through deep channel control across North American state Department of Transportation approved-product lists. Tensar International Corporation differentiates via proprietary welding technology that extends performance claims in load-bearing roadway applications.
Geocells are three-dimensional honeycomb structures manufactured from high-density polyethylene, ultrasonically welded at joints to form expandable panels that confine and stabilize infill materials under cyclic loading. The cellular confinement system distributes vertical loads laterally, reducing base course thickness requirements by up to fifty percent in unpaved road construction. Polymeric geocells occupy the dominant volume position due to chemical resistance and deployment speed, while composite geocells command margin premiums in mining tailings and heavy-haul corridors where tensile demands exceed standard polymer capacity. Soil stabilization leads application demand as transportation agencies specify geocells for soft subgrade bridging, with slope protection emerging as the fastest-growing segment where vegetated face systems replace concrete riprap on environmental grounds.
Federal Highway Administration guidelines, EN 13249 geosynthetic standards under the EU Construction Products Regulation, and India's BIS certification requirements for geosynthetics in road works collectively shape product testing protocols and market access conditions. The EU Green Deal's embodied carbon tracking is forcing manufacturers to document recycled feedstock percentages and end-of-life recovery pathways. Stakeholders must monitor how procurement shifts from first-cost bidding toward lifecycle performance contracting reshape supplier qualification criteria and pricing power across regional markets.
Market Dynamics
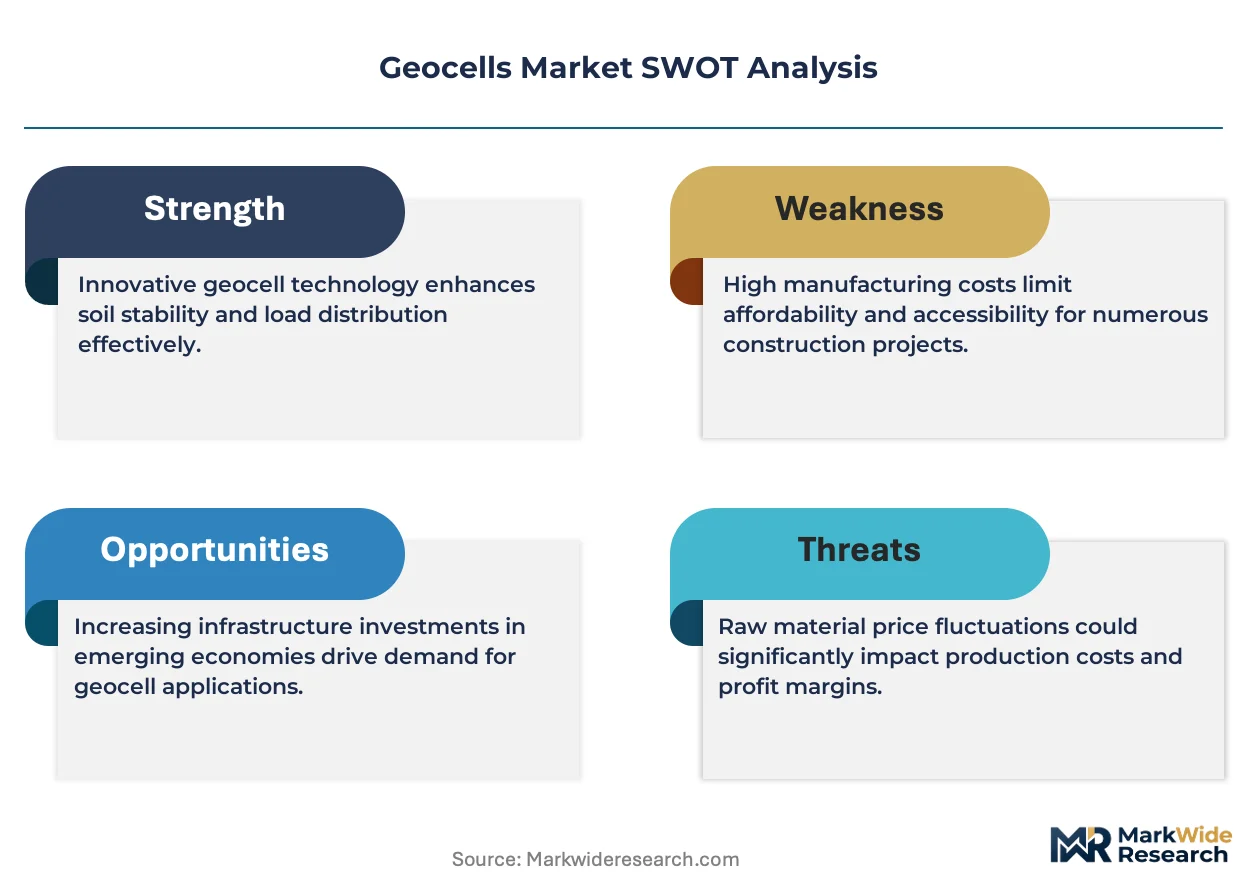
The geocells market is bifurcating between specification-grade cellular confinement systems and commodity alternatives as infrastructure procurement migrates toward lifecycle performance contracting. This structural tension compresses margins for undifferentiated suppliers while rewarding manufacturers with certified welding protocols and documented carbon footprints.
Growth Catalysts
- EU Green Deal carbon accounting:Embodied carbon tracking mandates are accelerating specification of recycled-content HDPE geocells in French and German rail embankment programs.
- India's highway widening pipeline:The Ministry of Road Transport and Highways is embedding geocell specifications into national highway tenders, creating concentrated demand for subgrade stabilization systems.
- Ultrasonic welding advancement:Proprietary joint welding technology is extending performance claims in load-bearing unpaved road applications, reducing base course thickness requirements.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings for high-density polyethylene constrain margin predictability for manufacturers without backward integration into polymer supply.
- Supplier concentration in Germany:Certification-heavy European rail programs depend on a narrow manufacturing base, creating supply vulnerability for time-sensitive infrastructure tenders.
- Concrete riprap substitution economics:Established slope protection materials retain cost advantages in markets without carbon pricing or vegetated face mandates.
Strategic Opportunities
- Indian state-level penetration:Underpenetrated district road networks beyond national highways offer volume expansion for cellular confinement systems in rural connectivity programs.
- Mining tailings containment:Composite geocell configurations with enhanced tensile capacity are capturing specification in heavy-haul corridors and extractive waste management.
- BIS certification alignment:India's Bureau of Indian Standards geosynthetic testing protocols create first-mover advantage for suppliers achieving early product listing approval.
Industry Challenges
- Geotechnical engineering talent scarcity:Qualified field engineers capable of specifying cellular confinement systems remain concentrated in established infrastructure consultancies, limiting deployment scale.
- Multi-standard certification timelines:Concurrent compliance with EN 13249, FHWA guidelines, and BIS requirements extends product qualification cycles and strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geocells Market |
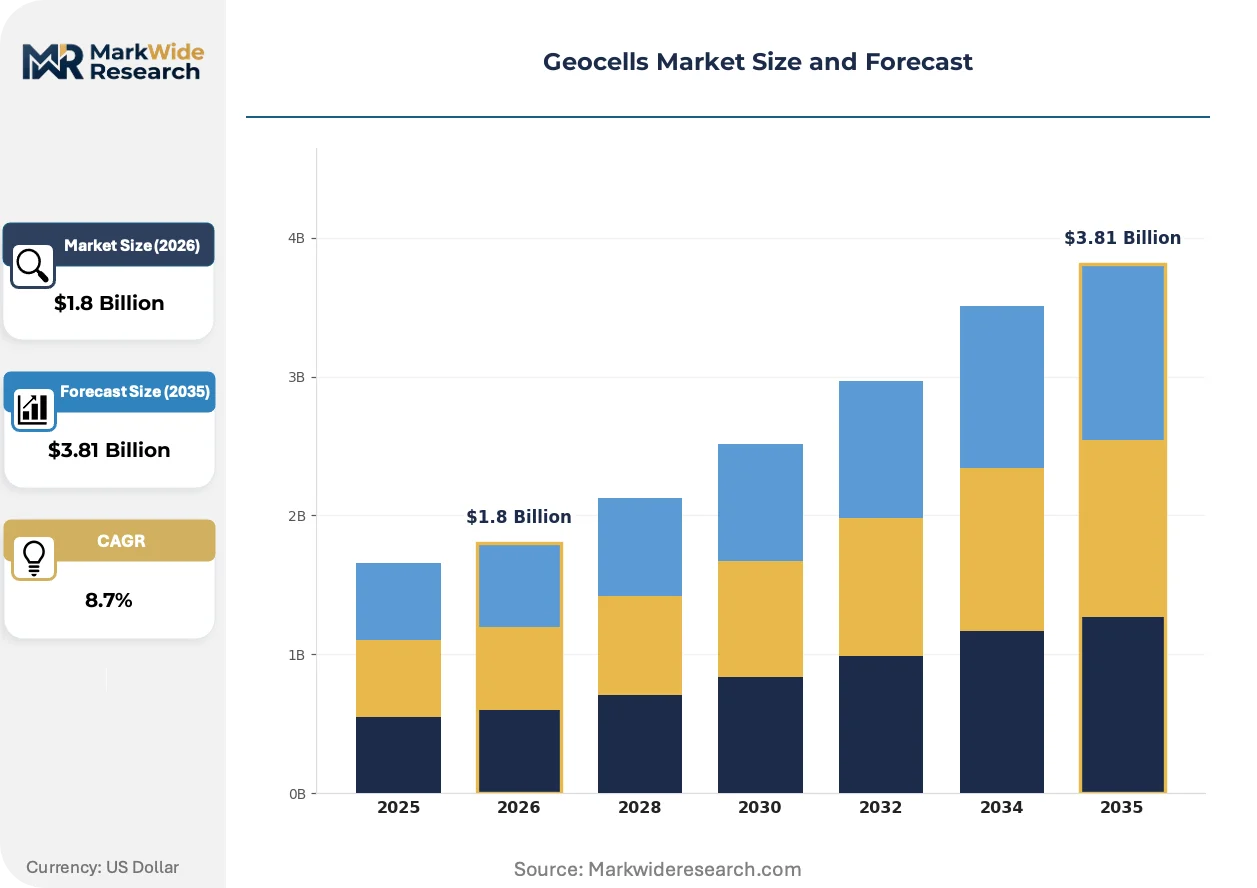
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Geocells, Metallic Geocells, Composite Geocells, Polyester Geocells Application: Soil Stabilization, Retaining Walls, Slope Protection, Erosion Control End User: Construction, Transportation, Landscaping, Mining Installation Method: On-Site Installation, Prefabricated Panels, Manual Installation, Automated Systems |
| Companies Covered | NAUE GmbH & Co. KG, Strata Systems, Inc., Tensar International Corporation, PRS Mediterranean Ltd., Tenax International S.p.A., Maccaferri S.p.A., HUESKER Synthetic GmbH, Solmax International Inc., Presto Geosystems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geocells Market Emerging Trajectories
Cellular confinement technology is converging with digital specification tools and carbon transparency platforms, reshaping how infrastructure buyers evaluate geosynthetic performance. Three developments are compressing traditional procurement cycles and redefining supplier qualification criteria.
Ultrasonic welding automation is automating quality consistency across geocell joint fabrication, reducing manual inspection dependency in high-volume manufacturing. State Departments of Transportation in the United States are specifying automated-welded panels for heavy-haul access roads, recognizing the structural reliability gains. This automation is compressing the qualification timeline for new suppliers entering approved-product lists.
REACH chemical disclosure requirements under the EU Construction Products Regulation are mandating full material composition transparency for geosynthetic products placed on European markets. Manufacturers must now document additive packages and stabilizer chemistries through the SCIP database, increasing compliance overhead. Recycled-content HDPE geocells face heightened scrutiny where feedstock provenance cannot be traced to post-consumer waste streams.
Performance-based contracting is displacing first-cost bidding in Scandinavian and Dutch infrastructure procurement, unbundling geocell supply from installation and long-term performance guarantees. Engineering-procurement-construction firms are absorbing lifecycle risk, shifting supplier relationships toward partnership frameworks with shared outcome accountability. This behavioral shift concentrates specification authority with integrated contractors capable of modeling total cost of ownership across twenty-year design horizons.
Geocells Market Segmentation
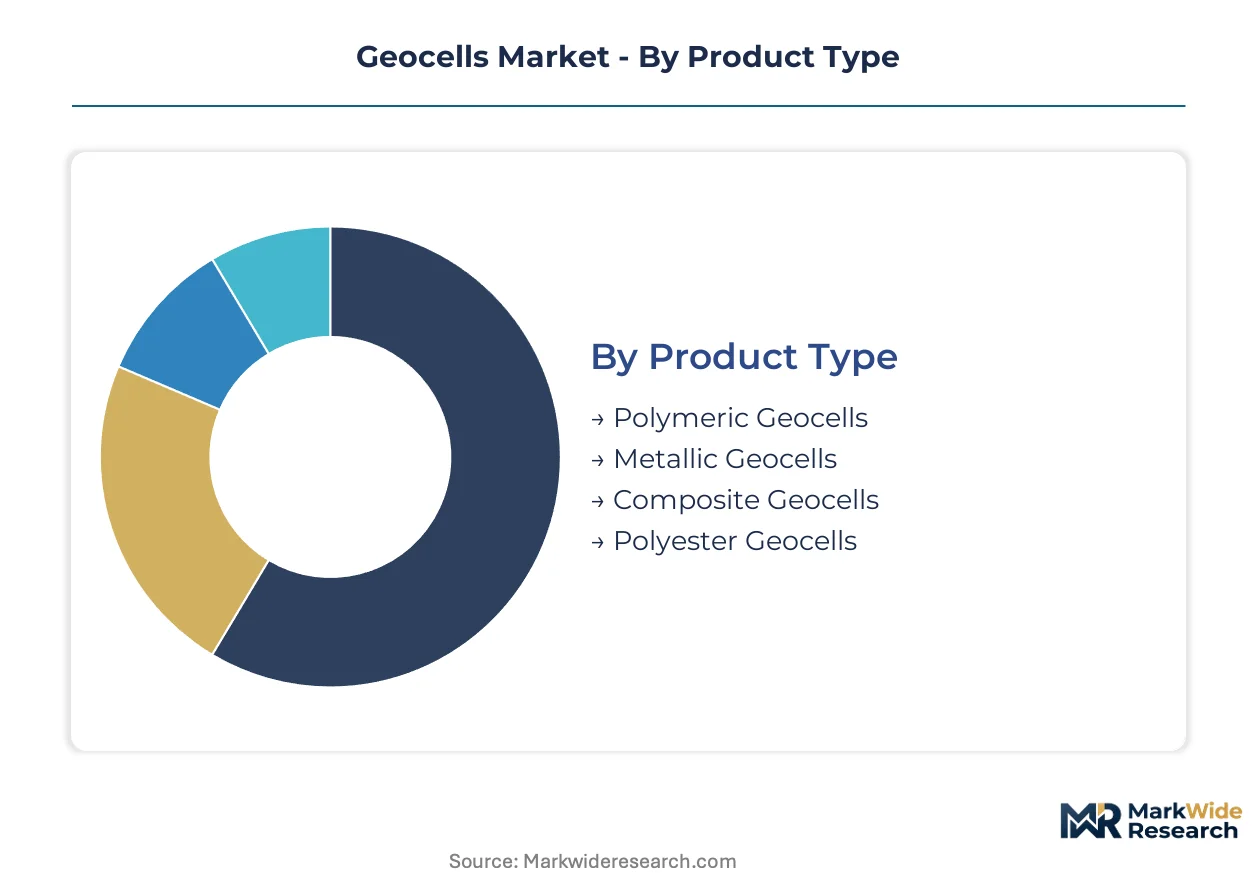
Cellular confinement systems exhibit divergent performance characteristics across material compositions, installation protocols, and end-use environments. Specification authority concentrates with engineering consultancies capable of matching geocell configurations to subgrade conditions, slope geometries, and loading cycles.
Product Type:
Supply concentration among German and North American manufacturers favors polymeric systems with certified welding protocols, while composite alternatives capture margin premiums in specialized heavy-load applications.
- Polymeric Geocells:High-density polyethylene panels dominate volume through chemical resistance, deployment speed, and ultrasonic weld reliability. India's Ministry of Road Transport and Highways specifies HDPE geocells for national highway widening projects, creating concentrated demand for recycled-content variants under EU Green Deal carbon accounting mandates.
- Composite Geocells:Hybrid configurations combining polymeric matrices with high-tensile reinforcements command specification in mining tailings containment and heavy-haul corridors where standard polymer capacity proves insufficient. Scandinavian performance-based contracting models favor these systems for twenty-year design horizon guarantees.
- Metallic Geocells:Steel-based cellular systems persist in permanent infrastructure where corrosion protection and structural permanence outweigh polymer flexibility.
- Polyester Geocells:Woven synthetic configurations serve niche applications requiring specific tensile modulus characteristics and UV stability profiles.
Today's leader: Polymeric Geocells. Tomorrow's challenger: Composite Geocells.
Application:
Cost tier differentiation separates specification-grade engineered systems from commodity alternatives across infrastructure procurement cycles.
- Soil Stabilization:Subgrade bridging applications lead volume demand as transportation agencies deploy cellular confinement for soft ground improvement. The Federal Highway Administration guidelines shape North American specification protocols, while India's BIS certification requirements govern product approval for road works.
- Slope Protection:Vegetated face systems displace concrete riprap on environmental grounds across European rail embankment programs subject to EU Green Deal mandates. REACH chemical disclosure requirements through the SCIP database heighten scrutiny of material composition transparency for these exposed applications.
- Retaining Walls:Structural earth reinforcement configurations integrate geocell facing with geogrid backfill for vertical load support.
- Erosion Control:Channel lining and shoreline protection applications emphasize rapid deployment and vegetative establishment.
Soil Stabilization commands current procurement volume. Slope Protection gains share fastest where carbon pricing and vegetated face mandates displace conventional armoring.
End User:
Volume concentration tracks public infrastructure investment cycles, with private mining and landscaping segments exhibiting divergent specification behaviors.
- Construction:General civil engineering applications span building foundations, parking structures, and temporary access roads. State Departments of Transportation in the United States maintain approved-product lists that gate market access for cellular confinement suppliers.
- Transportation:Highway, railway, and airport pavement systems represent the specification core. EN 13249 geosynthetic standards under the EU Construction Products Regulation define testing protocols for European rail embankment programs.
- Mining:Extractive waste management and heavy-haul access roads demand enhanced tensile capacity and abrasion resistance.
- Landscaping:Residential and commercial green infrastructure applications emphasize aesthetic integration and vegetative performance.
Transportation agencies anchor specification authority. Mining operators present the steepest expansion trajectory for high-performance composite configurations.
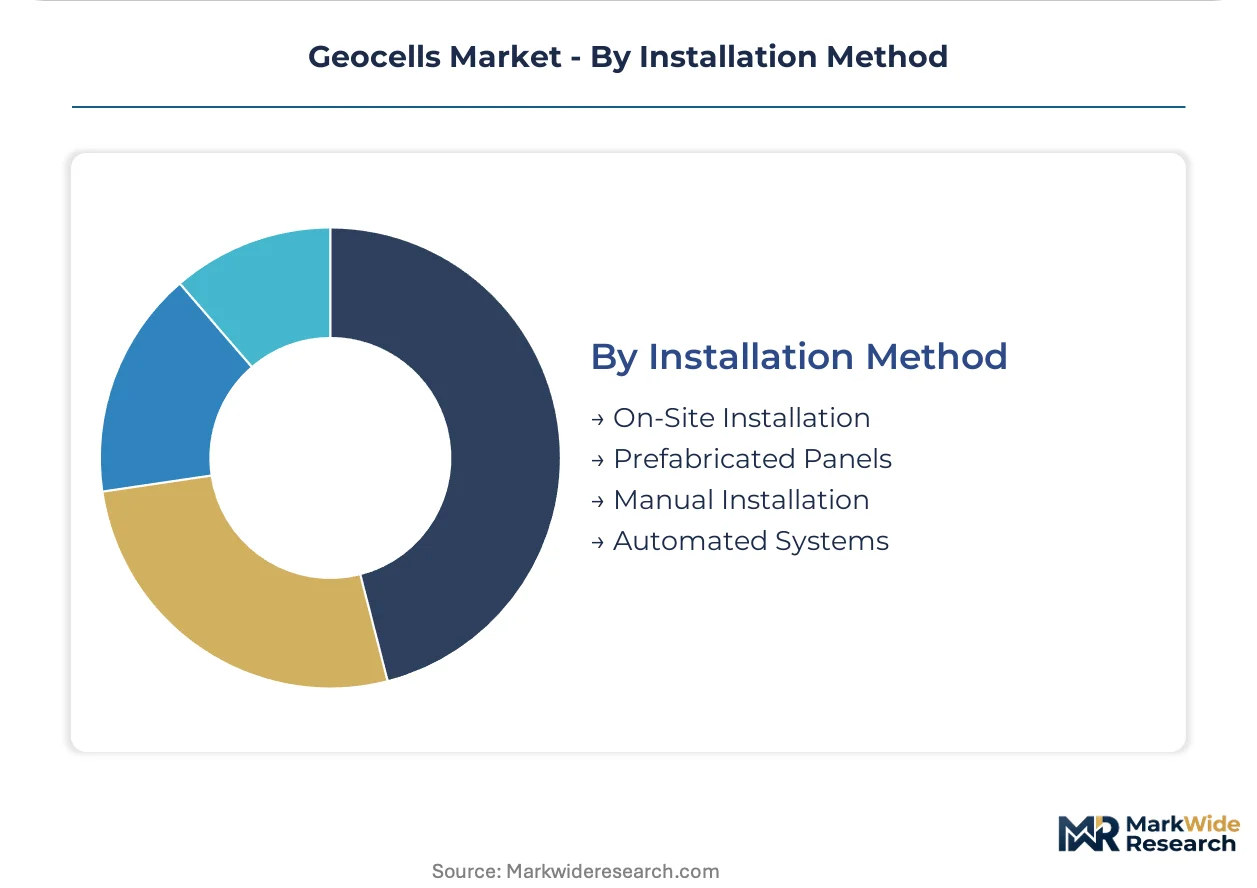
Installation Method:
Customer type stratification separates integrated engineering-procurement-construction firms from fragmented contractor networks across deployment scale.
- Prefabricated Panels:Factory-welded cellular systems reduce field joint variability and compress installation timelines for large-scale infrastructure programs. Automated welding quality consistency satisfies heavy-haul roadway specifications in North American state DOT frameworks.
- On-Site Installation:Expandable panel deployment at project locations accommodates irregular geometries and last-minute design adjustments. Indian district road networks beyond national highways rely on this flexibility for rural connectivity programs with limited engineering oversight.
- Manual Installation:Labor-intensive panel expansion and staking persists in constrained access sites and developing markets.
- Automated Systems:Mechanized deployment equipment accelerates placement rates for linear corridor projects with repetitive cross-sections.
Prefabricated Panels dominate specification-grade procurement. On-Site Installation retains volume in underpenetrated regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geotechnical engineering talent clusters in Germany, India, and the United States anchor specification authority for cellular confinement systems. Regional procurement patterns diverge sharply between carbon-accounting European rail programs and cost-optimized highway widening in emerging economies.
Germany
EU Green Deal embodied carbon tracking accelerates recycled-content HDPE geocell specification in French and German rail embankment programs. ECHA REACH chemical disclosure requirements through the SCIP database mandate full material composition transparency for geosynthetic products. The Ruhr industrial corridor hosts NAUE GmbH & Co. KG and HUESKER Synthetic GmbH manufacturing bases serving certification-heavy European infrastructure tenders.
United States
Federal Highway Administration guidelines shape North American specification protocols for subgrade stabilization and heavy-haul access roads. State Departments of Transportation maintain approved-product lists that gate market access for cellular confinement suppliers. The Southeast corridor exhibits concentrated demand from state DOT widening programs and mining tailings containment projects.
India
The Ministry of Road Transport and Highways embeds geocell specifications into national highway widening tenders, creating concentrated demand for subgrade stabilization systems. BIS certification requirements for geosynthetics in road works govern product approval and create first-mover advantage for early-listed suppliers. District road networks in Maharashtra and Gujarat rely on on-site installation flexibility for rural connectivity programs with limited engineering oversight.
China
Dual carbon goals under the 14th Five-Year Plan accelerate specification of recycled-content infrastructure materials in transportation and mining applications. GB standards for geosynthetics define testing protocols that shape domestic manufacturer qualification. The Yangtze River Delta industrial cluster concentrates polymer processing capacity serving domestic highway and rail embankment programs.
United Arab Emirates
MOHAP and federal infrastructure agencies specify cellular confinement systems for desert subgrade stabilization and coastal erosion control in mega-development corridors. Carbon transparency requirements in government procurement favor suppliers with documented recycled feedstock percentages. Dubai and Abu Dhabi anchor demand through airport expansion, port modernization, and desert highway programs.
Geocells Market Vendor Landscape
Capital-heavy producers compete with asset-light designers and regional fabricators across tiered certification requirements. The market structure concentrates specification-grade supply among German and North American manufacturers with certified welding protocols, while commodity alternatives fragment across Asian fabricators. Three archetypes dominate: integrated polymer producers with backward control over HDPE feedstock, specialized geosynthetic engineers with proprietary joint technologies, and regional distributors with state-level DOT relationships. Competitive moves center on BIS and EN 13249 certification alignment and automated welding quality consistency.
Within the premium engineered tier, NAUE GmbH & Co. KG and Tensar International Corporation exemplify manufacturers leveraging proprietary welding technology and German manufacturing bases to sustain certification-heavy supply. Strata Systems, Inc. occupies a position anchored through North American state Department of Transportation channel control. Among composite system specialists, PRS Mediterranean Ltd. and Maccaferri S.p.A. represent suppliers capturing margin premiums in mining tailings and heavy-haul corridor applications where tensile demands exceed standard polymer capacity.
| Leading Market Players |
|---|
| NAUE GmbH & Co. KG |
| Strata Systems, Inc. |
| Tensar International Corporation |
| PRS Mediterranean Ltd. |
| Tenax International S.p.A. |
| Maccaferri S.p.A. |
| HUESKER Synthetic GmbH |
| Solmax International Inc. |
| Presto Geosystems, Inc. |
| Others |
Supply Flow & Price Mechanics
Ultrasonic welding automation is compressing manufacturing cost curves while simultaneously concentrating supply among German and North American producers with certified production protocols. This technological shift rewards capital-intensive manufacturers capable of documenting weld consistency for state Department of Transportation approved-product lists, while squeezing margin recovery for commodity fabricators lacking backward integration into polymer feedstock.
Pricing Analysis
Bundled supply-and-install contracts are displacing pure product sales in Scandinavian and Dutch infrastructure procurement, unbundling geocell supply from long-term performance guarantees. Three-tier pricing structure across premium certified-grade, standard DOT-listed, and economy unbranded levels tracks certification investment and welding automation intensity. Cost compression in the economy tier is intensifying because Asian fabricators without EN 13249 or BIS alignment compete on first-cost bidding alone. State transportation agencies exhibit lowest price sensitivity where lifecycle performance contracting governs award criteria, while rural connectivity programs in underpenetrated districts prioritize unit economics over certification depth.
Supply Chain Analysis
Dual-sourcing requirements in European rail embankment programs and Indian national highway tenders are forcing buyers to qualify multiple suppliers despite geographic concentration. Manufacturing gravity centers on Germany, the United States, and China, with polymer processing clusters in the Ruhr corridor, the American Southeast, and the Yangtze River Delta. HDPE resin, ultrasonic welding equipment, and post-consumer recycled feedstock constitute critical input dependencies. Single-source vulnerability persists where EN 13249 certification timelines extend qualification cycles for new entrants. Distribution runs through engineering-procurement-construction firms absorbing lifecycle risk in performance-based markets, and through regional distributors serving state-level DOT relationships elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geocells market functions as a regulatory compounder where EU Green Deal embodied carbon tracking and India's BIS certification requirements are structurally expanding addressable demand for documented recycled-content systems.
For Market Incumbents: Hedge margin exposure to HDPE resin volatility through backward integration into polymer recycling streams or long-term offtake agreements with post-consumer waste processors. Defend specification authority in European rail programs by accelerating SCIP database compliance ahead of REACH enforcement waves. Channel control investments in North American state DOT approved-product lists remain the priority defensive lever against automated welding entrants from Asian manufacturing bases. For New Entrants and Emerging Players: Begin with BIS certification alignment for India's district road networks beyond national highways, where on-site installation flexibility and limited engineering oversight create white-space penetration opportunities. Target mining tailings containment applications demanding composite geocell configurations, as heavy-haul corridor specifications reward tensile capacity premiums over brand heritage. A go-to-market partnership with engineering-procurement-construction firms capable of modeling total cost of ownership compresses sales cycle friction in performance-contracting markets. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with state-level DOT relationships but lacking automated welding capabilities or carbon transparency documentation. The five-to-ten-year viability window favors acquisition targets with concurrent EN 13249, FHWA, and BIS qualification rather than single-market certification depth. The signal to watch is procurement migration from first-cost bidding toward lifecycle performance contracting in Indian state-level tenders, which would revalue certified welding capabilities and recycled feedstock traceability.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Certification | EU Green Deal carbon accounting mandates documentation of post-consumer HDPE provenance for rail embankment specification. |
| Automated Welding Scale-Up | State DOT heavy-haul programs are specifying factory-welded panels with quality consistency exceeding manual fabrication. |
| BIS Certification Investment | India's Bureau of Indian Standards geosynthetic testing protocols create first-mover advantage for early product listing approval. |
| Performance-Based Contracting Partnership | Engineering-procurement-construction firms absorbing lifecycle risk demand supplier alignment with twenty-year design horizon guarantees. |
| Composite Configuration Development | Mining tailings and heavy-haul corridor applications reward hybrid geocell systems with tensile capacity exceeding standard polymer limits. |
Methodological Framework
Multiple input streams — technical interviews with geotechnical engineering consultants, procurement discussions with state Department of Transportation materials engineers, and regulatory validation with EU Construction Products Regulation compliance officers — were reconciled against secondary data from EN 13249 certification databases, FHWA guideline publications, and Indian BIS geosynthetic testing records. Bottom-up project pipeline tracking across national highway widening programs was cross-referenced with top-down polymer consumption estimates from HDPE resin trade data.
Historical capacity deployment patterns were cross-referenced against expert panel assessments of certification timeline compression and procurement behavioral shifts. Segmentation dimensions modeled include material composition tier, application type, end-user industry vertical, installation protocol, and regional regulatory cluster. CAGRs were derived through regression analysis of specification-grade versus commodity volume trajectories, incorporating ultrasonic welding automation adoption curves and recycled-content mandate enforcement intensity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt HDPE resin price dislocations, retroactive REACH chemical disclosure enforcement, and geopolitical disruption to German manufacturing bases serving certification-heavy European tenders. Deviation in Indian state-level adoption of lifecycle performance contracting would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Drywall Joint Tape Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
East Africa White Cement Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Construction Stone Market
Building Materials
Solar Control Window Film Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Facade Gasket Market
Building Materials
Exterior Doors Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Thin Brick Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Steel Sleepers Market
Building Materials
Bolt (Fastener) Market