
 Lightweight Cellular Concrete Market | 2026-2036
Lightweight Cellular Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Cellular Concrete Market Insights
Direct supply relationships between cellular concrete producers and infrastructure contractors is reconfiguring as project-scale bundling replaces spot purchasing. CEMEX S.A.B. de C.V. leverages its vertically integrated cement network to control raw material costs across Latin American and European batching operations. Aerix Industries anchors its position through specialized foam generation equipment that locks air content precision at the job site. Saint-Gobain competes by extending its building materials distribution reach into specification-driven commercial segments where thermal performance credentials determine bid outcomes.
Lightweight cellular concrete is a cementitious material containing uniformly distributed air voids introduced through foaming agents or gas-forming additives, typically achieving dry densities between 300 and 1800 kg/m³ while maintaining compressive strengths suitable for structural and non-structural applications. Its primary industrial purpose centers on reducing dead loads in buildings, improving thermal insulation in envelopes, and enabling rapid placement in geotechnical fill and void-filling operations. Foam concrete dominates volume in infrastructure fill and trench backfill where pumpability over long distances and low bearing pressure on underlying soils create structural advantages. Aerated concrete leads margin pools in residential and commercial wall systems where factory-cured precision blocks command specification premiums for thermal efficiency and fire resistance.
The European Construction Products Regulation and associated CE marking requirements govern mechanical performance declarations for cellular concrete placed in permanent structures across EU member states. ASTM C796 and C869 in the United States establish standard test methods for foaming agents and preformed foam used in producing cellular concrete, shaping quality benchmarks that influence contractor acceptance and warranty terms. China's GB standards for autoclaved aerated concrete products set density and strength classifications that manufacturers must meet for building code compliance in residential construction. Stakeholders must monitor evolving embodied carbon accounting rules in multiple jurisdictions, as these frameworks will progressively reweight material selection criteria toward lower-carbon density solutions without compromising structural verification protocols.
Market Dynamics
Federal transport investment in Germany is converging with the EU Green Deal's embodied carbon mandates to redirect specification decisions toward lower-density cementitious systems across highway and tunnel infrastructure.
Growth Catalysts
- EU Green Deal carbon accounting:Embodied carbon reduction mandates in building materials are redirecting specification decisions toward thermally efficient lightweight solutions in commercial envelope applications.
- German federal transport investment:Highway embankment and tunnel backfill projects are expanding procurement volumes as contractors seek dead load reduction and accelerated construction schedules.
- Foam generation equipment precision:Job-site air content control technology is enabling pumpability over long distances for geotechnical fill operations.
Market Restraints
- Cement feedstock volatility:Energy-intensive clinker production exposes batching operations to natural gas and electricity price swings across European manufacturing zones.
- Factory-cured block supply concentration:Autoclaved aerated concrete capacity clusters in Central European production corridors, creating geographic supply vulnerability for residential wall systems.
- ASTM C796 testing friction:Foaming agent certification protocols extend contractor qualification timelines and warranty negotiation cycles in US infrastructure bidding.
Strategic Opportunities
- India PLI scheme alignment:Domestic manufacturing incentives for construction materials create localization pathways for cellular concrete block production serving residential verticals.
- Building envelope retrofit demand:Existing stock thermal upgrades in Northern European housing stock favor low-density insulation infill for floor and roof assemblies.
- Carbon capture concrete convergence:Mineralization-cured binders paired with foam injection processes offer negative-emission positioning for specification-driven commercial segments.
Industry Challenges
- Foam stability technician scarcity:Job-site air void distribution control requires specialized batching expertise that outpaces vocational training program output.
- CE marking compliance timelines:European Construction Products Regulation mechanical performance declarations extend product launch cycles for novel density formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Cellular Concrete Market |
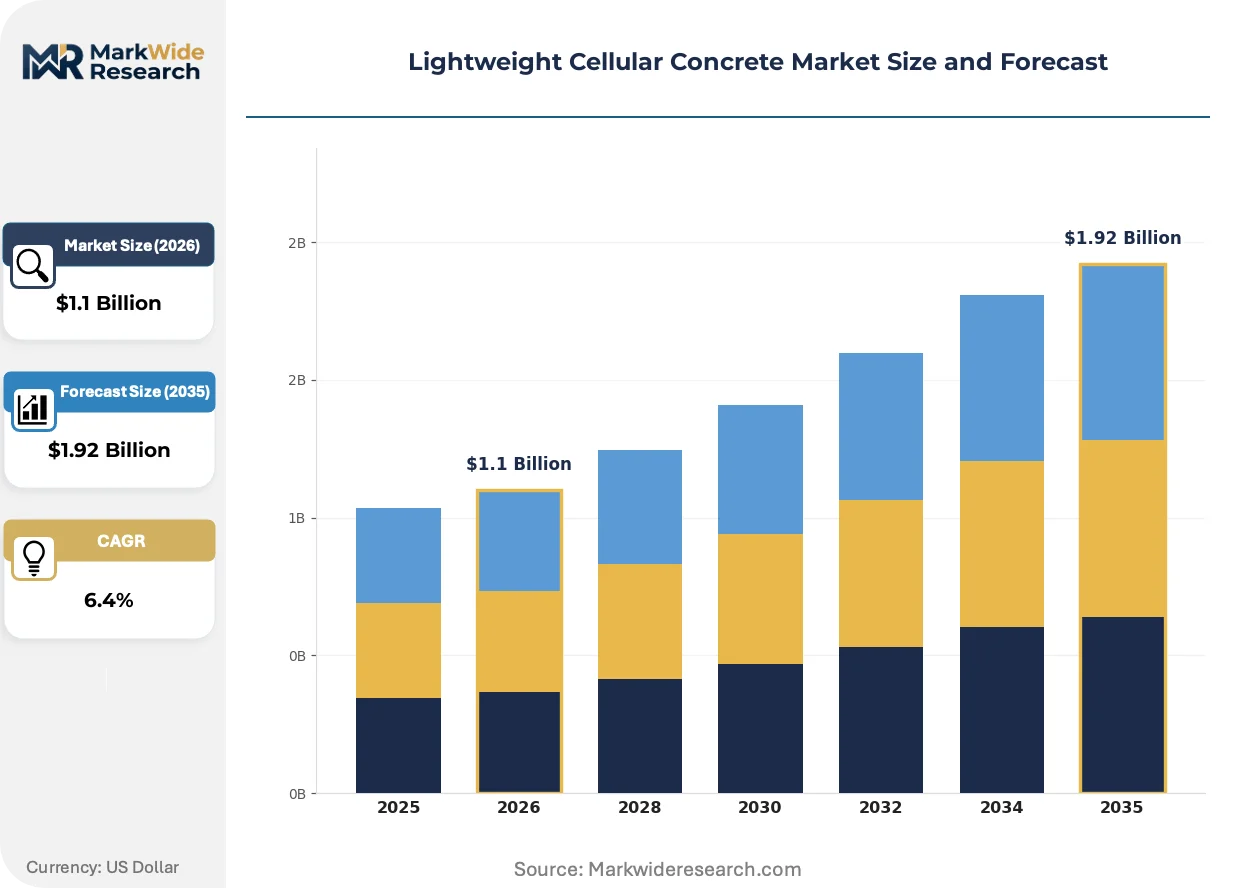
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Concrete, Aerated Concrete, Lightweight Concrete, Cellular Lightweight Concrete Application: Construction, Insulation, Precast Elements, Fill Material End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Saint-Gobain, LafargeHolcim, CEMEX S.A.B. de C.V., Aerix Industries, ACICO, H+H, Xella Group, Contech Engineered Solutions LLC, Cematrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Cellular Concrete Market Trends and Innovations
Specification authority is migrating from general contractors to infrastructure asset owners as lifecycle cost modeling and carbon accounting tools reshape material selection workflows.
Preformed foam injection systems are collapsing traditional density-performance tradeoffs in highway embankment applications. State transportation departments in the US are adopting these systems for void-filling operations where pumpability over 500-meter distances eliminates mechanical compaction stages. The structural consequence is collapsing project timelines from weeks to days for trench backfill completion.
REACH chemical registration requirements for synthetic foaming agents are tightening formulation disclosure standards across EU member states. Manufacturers must now submit full toxicity profiles for surfactant chemistries used in air-void generation. The commercial segment is responding by accelerating bio-based foaming agent R&D to preempt authorization withdrawal risks.
Direct sourcing relationships between cellular concrete specialists and infrastructure asset owners are displacing distributor-mediated procurement in German transport projects. Project-scale bundling contracts covering multi-year maintenance programs now lock in volume commitments and density specifications upfront. This pattern is most visible in federal highway tunnel rehabilitation frameworks where thermal performance guarantees extend across 25-year service life contracts.
Lightweight Cellular Concrete Market Segmentation
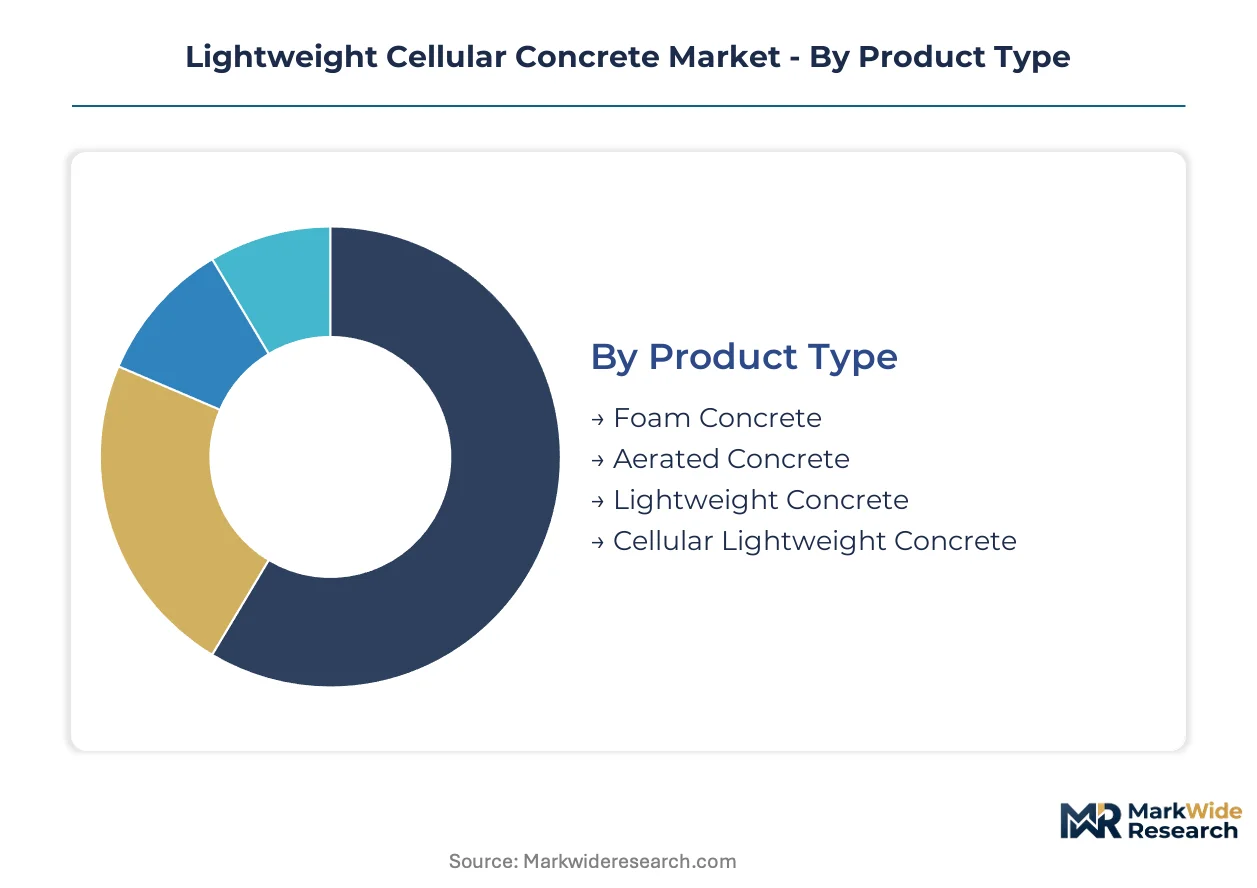
Product chemistry, placement method, and density-performance tradeoffs fragment the lightweight cellular concrete market into distinct specification tiers. Each segment carries unique regulatory footprints, supply chain configurations, and margin structures that determine competitive positioning across construction verticals.
Product Type:
Density range and curing methodology separate these material categories into distinct specification tiers with divergent capital intensity and geographic supply patterns.
- Foam Concrete:Hydraulically set cement paste with preformed foam injection achieves 300–1600 kg/m³ densities with pumpable placement over 500-meter distances. German federal highway embankment projects are expanding procurement volumes where dead load reduction accelerates construction schedules.
- Aerated Concrete:Aluminum powder reactions within slurry generate autoclave-cured blocks with precision thermal performance for commercial envelope systems. Factory-cured precision commands specification premiums in Northern European residential wall applications under stringent energy codes.
- Lightweight Concrete:Expanded shale or clay aggregates replace conventional coarse fractions to achieve moderate density reduction without foam generation equipment. Infrastructure contractors in India favor this category for PLI scheme-aligned domestic manufacturing where equipment import costs constrain foam system adoption.
- Cellular Lightweight Concrete:Hybrid formulations combining foam injection with lightweight aggregate fractions target mid-density applications requiring both thermal insulation and structural bearing capacity.
Foam concrete commands the established base. The steepest expansion runs through aerated concrete factory-cured systems.
Application:
Placement environment and performance verification requirements determine specification authority and procurement channel selection across these use cases.
- Construction:Structural and non-structural building elements including floor slabs, roof decks, and wall panels where compressive strength verification governs code compliance. CE marking requirements under the European Construction Products Regulation extend mechanical performance declaration timelines for novel density formulations.
- Insulation:Thermal envelope infill for floor and roof assemblies in Northern European housing retrofit programs where lambda values below 0.10 W/mK justify material premiums. The EU Green Deal embodied carbon mandates redirect specification decisions toward lower-density cementitious systems in commercial envelope applications.
- Precast Elements:Factory-manufactured panels and blocks with controlled curing environments enabling precision dimensional tolerance and fire resistance ratings.
- Fill Material:Geotechnical void-filling and trench backfill operations where pumpability eliminates mechanical compaction stages.
Construction absorbs the dominant volume share. Insulation applications are climbing the fastest as energy retrofit programs accelerate across EU member states.
End User:
Project scale, specification authority concentration, and lifecycle cost modeling sophistication vary sharply across these customer categories.
- Residential:Single-family and multi-family housing developers prioritizing thermal efficiency credentials for building code compliance and mortgage eligibility. Autoclaved aerated concrete block demand concentrates in Central European production corridors.
- Commercial:Office, retail, and institutional developers where specification decisions migrate toward asset owners wielding lifecycle cost and carbon accounting tools. Direct sourcing relationships between cellular concrete specialists and infrastructure asset owners are displacing distributor-mediated procurement in German transport projects.
- Industrial:Manufacturing facilities and warehouses requiring fire-resistant envelope systems with rapid installation schedules.
- Infrastructure:Highway agencies, tunnel operators, and rail authorities bundling multi-year maintenance programs with 25-year thermal performance guarantees.
Commercial projects command specification premiums. Infrastructure end users are gaining share fastest through project-scale bundling contracts.
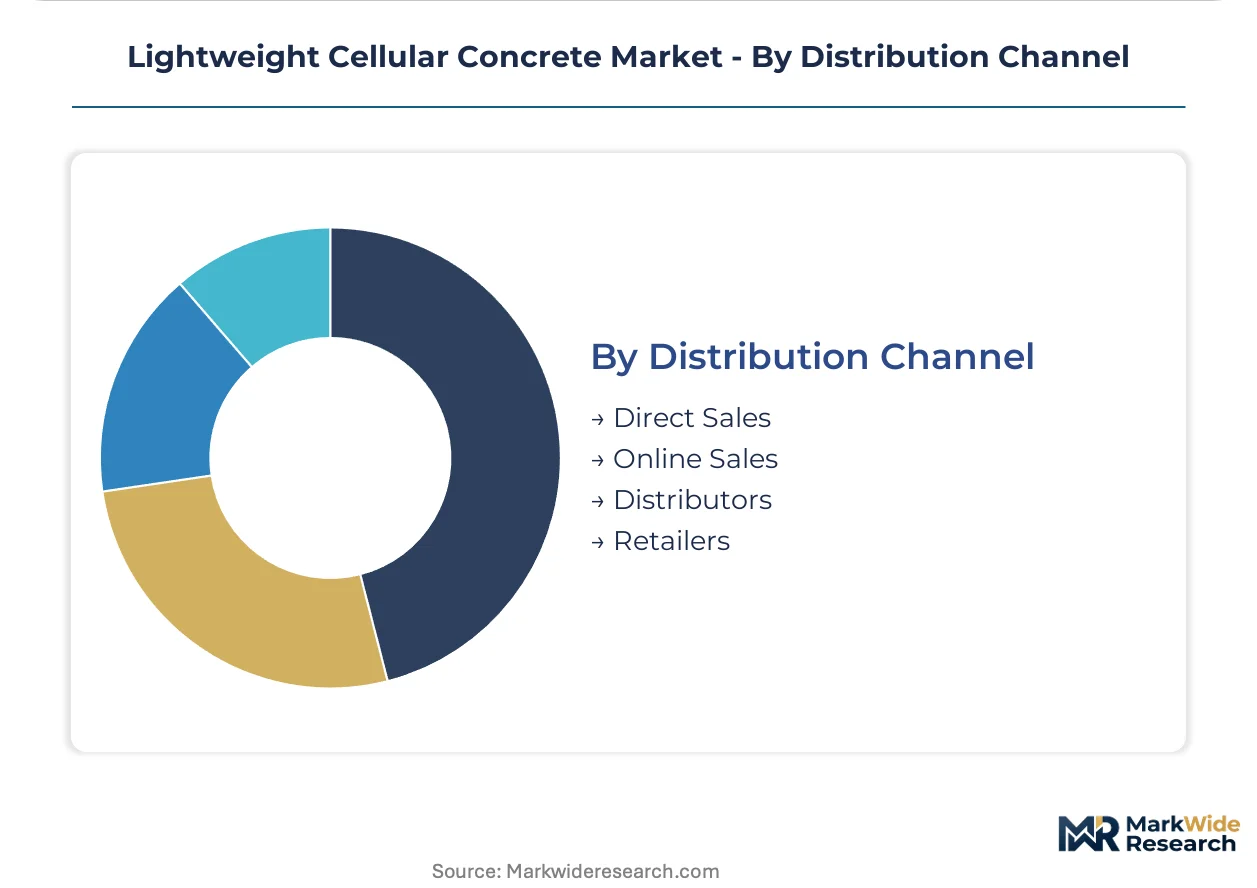
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to batching operations or factory curing facilities.
- Direct Sales:Project-scale volume commitments with embedded technical service for foam generation equipment calibration and job-site air content control. State transportation departments in the US specify direct relationships for void-filling operations requiring ASTM C796 foaming agent certification.
- Distributors:Building materials networks extending geographic reach into specification-driven commercial segments where thermal performance credentials determine bid outcomes.
- Online Sales:Standardized block and panel products with documented CE marking for residential contractors in digitally mature European markets.
- Retailers:Small-volume repair and renovation applications with limited technical service requirements.
Direct sales anchor the infrastructure and large commercial base. Distributor channels are expanding most quickly as building materials networks deepen specialty concrete coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German infrastructure contractors command pricing premiums unavailable to their US counterparts, reflecting tighter embodied carbon regulations and concentrated federal transport investment that reshape procurement power across Atlantic markets.
Germany
Federal highway embankment and tunnel backfill projects are expanding cellular concrete procurement volumes as contractors seek dead load reduction. The EU Green Deal's embodied carbon mandates redirect specification decisions toward lower-density cementitious systems. Production clusters in North Rhine-Westphalia and Bavaria serve Rhine-Ruhr transport corridors where thermal performance guarantees extend across 25-year maintenance contracts.
United States
State transportation departments are adopting preformed foam injection systems for void-filling operations requiring pumpability over 500-meter distances. ASTM C796 and C869 establish standard test methods for foaming agents that shape contractor acceptance and warranty terms. Manufacturing activity concentrates in the Southeast and Texas where energy costs influence batching operation economics.
China
GB standards for autoclaved aerated concrete products set density and strength classifications for residential construction compliance. Dual carbon goals from MEE are tightening embodied carbon accounting for cementitious materials. Production gravity sits in Shandong and Jiangsu provinces where factory-cured block capacity serves rapid urbanization in the Yangtze River Delta.
India
PLI scheme incentives for domestic construction materials manufacturing create localization pathways for cellular concrete block production. BIS standards govern product quality for residential verticals where expanded shale aggregate systems dominate due to equipment import cost constraints. Industrial corridors in Gujarat and Maharashtra are attracting batching facility investments serving Mumbai-Ahmedabad infrastructure projects.
United Arab Emirates
MOHAP building code enforcement and Dubai's green building regulations are redirecting commercial envelope specifications toward thermally efficient lightweight solutions. Infrastructure asset owners in Abu Dhabi are bundling multi-year maintenance programs with direct sourcing relationships that displace distributor-mediated procurement. Manufacturing clusters in Jebel Ali and Dubai Industrial City supply Gulf Cooperation Council tunnel and highway projects.
Lightweight Cellular Concrete Market Competitive Landscape
Vertically integrated cement majors and specialized foam equipment fabricators split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: multinational building materials conglomerates controlling raw material costs through captive cement supply, job-site technology specialists locking in air content precision through equipment differentiation, and regional batching operators securing infrastructure contracts through project-scale bundling. Dominant competitive moves include backward integration into foaming agent formulation and geographic expansion through distributor network deepening.
Among building materials conglomerates, Saint-Gobain and CEMEX S.A.B. de C.V. exemplify scale-driven positioning where distribution reach and specification authority determine bid outcomes in commercial envelope segments. Aerix Industries occupies a position within the job-site technology specialist archetype, anchoring competitive differentiation through foam generation equipment that locks precision at the point of placement. These three companies represent the strategic poles around which mid-cap regional operators and emerging carbon-capture concrete developers are clustering.
| Leading Market Players |
|---|
| Saint-Gobain |
| LafargeHolcim |
| CEMEX S.A.B. de C.V. |
| Aerix Industries |
| ACICO |
| H+H |
| Xella Group |
| Contech Engineered Solutions LLC |
| Cematrix |
| Others |
Pricing and Supply Chain Analysis
Cement feedstock volatility exposes batching operations to natural gas and electricity price swings that compress margin structures across European manufacturing zones while simultaneously widening spreads between configured-to-order density formulations and standardized block products. This input cost instability forces producers to recalibrate procurement strategies toward captive clinker supply or regional sourcing hubs that can buffer spot market exposure.
Pricing Analysis
The customization-premium spread separates project-specific density configurations from commodity-grade block products, with thermal performance guarantees and 25-year service life contracts commanding substantial uplifts over standard residential wall systems. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification burdens: CE-marked autoclaved blocks for commercial envelopes sit at the top, followed by infrastructure-grade foam concrete with ASTM C796 compliance, with non-certified fill material at the base. Pricing pressure stems from energy-intensive clinker production costs that outpace contractor pass-through capacity in competitive bidding environments. Infrastructure asset owners exhibit lowest price sensitivity due to lifecycle cost modeling sophistication, while residential developers face acute margin compression from mortgage eligibility requirements and building code compliance costs.
Supply Chain Analysis
Export-control regime restrictions on synthetic foaming agent chemistries under REACH registration requirements are tightening formulation disclosure standards and redirecting R&D investment toward bio-based surfactant alternatives across EU member states. Manufacturing gravity centers on Germany, China, and India, with autoclaved block capacity clustering in North Rhine-Westphalia and Shandong province while foam concrete batching expands in Gujarat and Texas. Raw material dependencies rest on Portland cement clinker, aluminum powder for gas generation, and specialized surfactant chemistries for air-void stabilization. Single-source vulnerability concentrates in Central European autoclaved block corridors where factory-cured precision capacity cannot relocate quickly. Distribution runs through project-scale direct sales for infrastructure volumes and building materials networks for commercial envelope specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lightweight cellular concrete occupies an early-cycle expansion trajectory where EU Green Deal embodied carbon mandates and German federal transport investment are converging to accelerate specification migration toward lower-density cementitious systems.
For Market Incumbents: Build captive cement supply moats through backward integration into clinker production or long-term offtake agreements with regional kiln operators, insulating batching economics from energy price volatility. Incumbents should simultaneously deepen distributor relationships in commercial envelope segments where Saint-Gobain and CEMEX are consolidating specification authority through thermal performance credentials, while monitoring carbon-capture concrete developers as emerging substitution threats in premium specification tiers. For New Entrants and Emerging Players: Build out regional batching capacity in Indian industrial corridors where PLI scheme incentives and equipment import cost constraints favor expanded shale aggregate systems over foam injection technologies. The most penetrable white space sits in Northern European building envelope retrofit demand for low-density insulation infill, where existing stock thermal upgrades outpace factory-cured block supply. A targeted go-to-market angle pairs mineralization-cured binder partnerships with local contractors to claim negative-emission positioning in specification-driven commercial segments. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors acquisition targets with proven foam generation equipment expertise and locked infrastructure bundling contracts. Long-term viability over the coming decade hinges on positioning for embodied carbon accounting rule convergence across multiple jurisdictions without compromising structural verification protocols. The signal to watch is authorization withdrawal risk for synthetic foaming agents under REACH tightening, which would abruptly revalue bio-based formulation capabilities and mineralization-cured technology pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Supply | Captive cement sourcing buffers German and Indian batching operations from natural gas price volatility. |
| Bio-Based Foaming Agent R&D Acceleration | Preempts REACH authorization withdrawal risks for synthetic surfactant chemistries across EU member states. |
| Project-Scale Bundling Contract Expansion | Locks 25-year thermal performance guarantees with German federal highway tunnel rehabilitation frameworks. |
| Carbon-Capture Concrete Technology Partnership | Positions mineralization-cured systems for EU Green Deal specification criteria in commercial envelopes. |
| Distributor Network Deepening in Commercial Segments | Extends building materials reach where thermal performance credentials determine bid outcomes against CEMEX. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with infrastructure contractors, batching facility operators, foam equipment technicians, and specification engineers at transport authorities; alongside secondary validation through EU Construction Products Regulation filings, ASTM C796 certification databases, German federal transport investment disclosures, and customs records tracking clinker and aluminum powder trade flows. Bottom-up volume estimates from project-level procurement data were triangulated against top-down cementitious materials consumption models.
Forecast inputs across the projection horizon incorporated density-performance segmentation by product chemistry, placement methodology, and end-use vertical, with CAGRs derived from infrastructure investment pipeline analysis and embodied carbon policy trajectory modeling. Segment-specific growth rates reflected German highway embankment project backlogs, Northern European housing retrofit program acceleration, and Indian PLI scheme manufacturing incentive uptake curves.
Stress conditions across cement feedstock price bands, REACH authorization timelines for foaming agents, and CE marking compliance duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity for EU Green Deal implementation and federal transport investment stability in Germany. Material shifts in synthetic surfactant authorization status or clinker production energy cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ductile Iron Pipe Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Concrete Market
Building Materials
Geocells Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
United States Construction Materials Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Latin America Facade Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Brick Adhesive Market
Building Materials
South Africa White Cement Market
Building Materials
Basalt Rock Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Global FRP Rebar Market
Building Materials
Timber Frames Market