
 Construction Repair Composites Market | 2026-2036
Construction Repair Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Repair Composites Market Analysis
Modular repair kits bundling pre-cut fiber sheets with matched epoxy chemistries is hardening as the default procurement format for infrastructure contractors. Sika AG leverages its adhesive formulation depth to control specification channels across European public works. Owens Corning anchors North American supply through vertically integrated glass fiber production. Mapei S.p.A. specializes in site-applicable mixing systems that reduce contractor labor hours on bridge deck projects.
Construction repair composites are fiber-reinforced polymer systems combining high-strength fibers with thermoset resin matrices, typically achieving tensile strengths exceeding 1,500 MPa while adding minimal dead load to existing structures. Their primary purpose is to restore or enhance structural capacity in deteriorated concrete, steel, and timber elements without full replacement. Epoxy resin formulations dominate value capture due to their superior bond characteristics and established qualification protocols for structural strengthening. Infrastructure applications represent the deepest margin pool, driven by department of transportation maintenance backlogs and lifecycle cost mandates. Fiber reinforcement technology leads volume adoption, though nanotechnology-modified matrices are gaining specification traction for extreme environment durability.
US Federal Highway Administration guidelines and ASTM D3039 testing protocols govern material qualification for bridge retrofit applications, while EU CE marking under Construction Products Regulation mandates factory production control for structural composites. Germany's Federal Institute for Research on Building, Urban Affairs and Spatial Development and France's CSTB shape national annexes that determine product acceptance criteria. Stakeholders must monitor evolving embodied carbon accounting rules that threaten to disqualify conventional resin systems and reward bio-based or recycled-content alternatives.
Market Dynamics
Bridge rehabilitation mandates across aging infrastructure networks are compressing contractor procurement cycles toward pre-qualified fiber-reinforced polymer systems. Federal durability requirements and embodied carbon thresholds are disqualifying conventional repair methods while elevating composite specifications.
Growth Catalysts
- US Infrastructure Investment and Jobs Act:Federal highway maintenance backlogs are accelerating state DOT adoption of composite strengthening systems for concrete superstructures.
- EU Green Deal thresholds:Embodied carbon limits on construction materials are redirecting public works specifications toward low-carbon epoxy formulations.
- German BAST guidelines:Federal highway authority technical directives now prioritize composite-based rehabilitation for aging bridge decks.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin formulations remain exposed to propylene and bisphenol-A price swings that compress contractor margins.
- Specialized applicator scarcity:Certified FRP installation contractors concentrate in Germany, France, and the US Northeast, creating bottlenecked deployment capacity elsewhere.
- Steel plate bonding legacy:Conventional metallic reinforcement retains specification inertia among conservative municipal engineers despite lifecycle cost disadvantages.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure renewal programs are creating first-mover advantage for composite retrofit specialists in seismic-prone metropolitan construction.
- Prefabricated modular kits:Pre-cut fiber sheet and matched epoxy bundles are opening specification channels among mid-tier contractors lacking in-house mixing capability.
- Japan's seismic retrofit mandates:METI building safety directives are expanding demand for carbon fiber wrapping systems in commercial and public facilities.
Industry Challenges
- Site-specific qualification protocols:ASTM D3039 and EN 15422 testing requirements create multi-month certification timelines that delay project mobilization.
- Substrate preparation labor intensity:Concrete surface profiling and epoxy primer application consume disproportionate crew hours relative to composite installation itself.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Repair Composites Market |
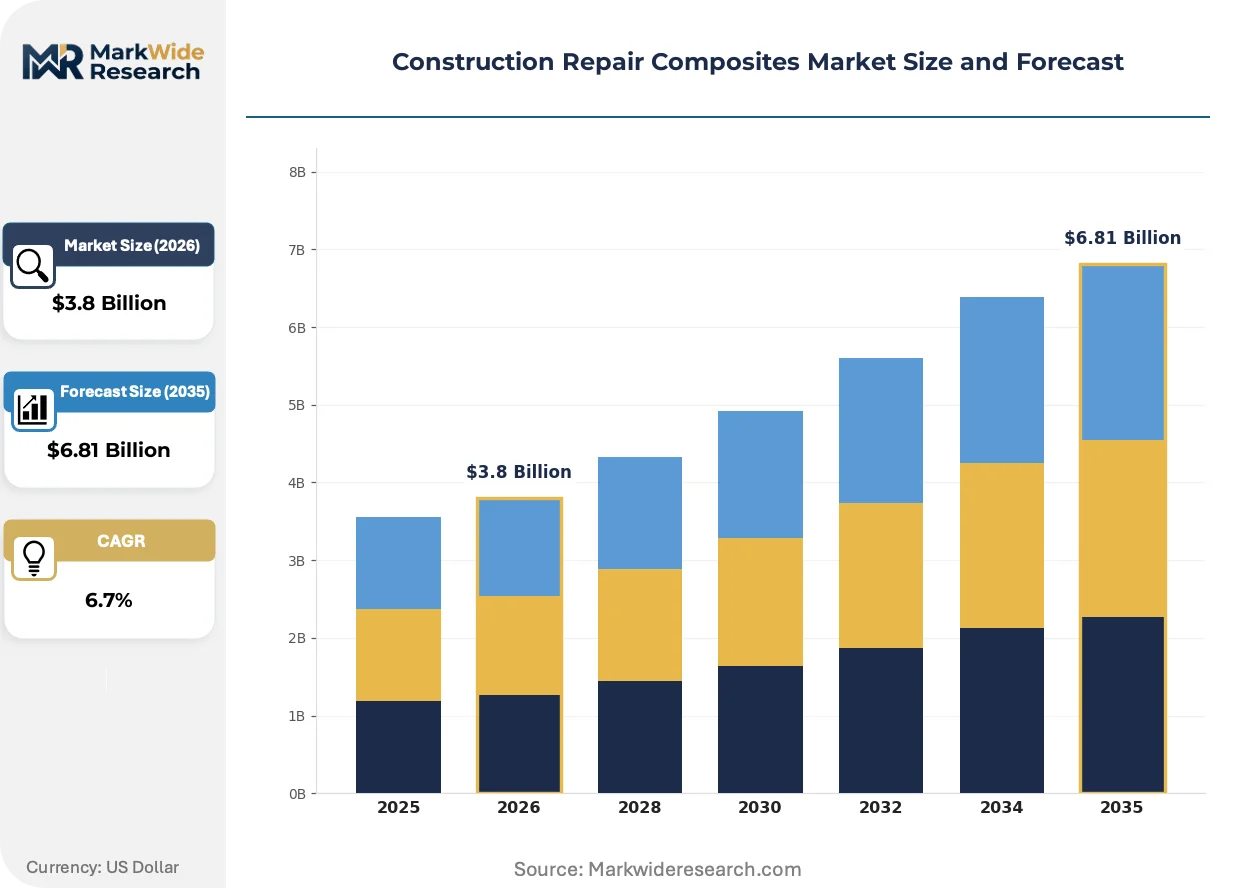
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Polyurethane, Vinyl Ester, Polyester Application: Infrastructure, Marine, Transportation, Industrial Maintenance End User: Contractors, Government Agencies, Private Sector, Construction Firms Technology: SNS Technologies, Fiber Reinforcement, Nanotechnology, Adhesive Bonding |
| Companies Covered | Owens Corning, DuPont de Nemours, Inc., Sika AG, Mapei S.p.A., Henkel AG & Co. KGaA, BASF SE, Saint-Gobain S.A., Fosroc International Limited, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Repair Composites Market Emerging Trajectories
Material science convergence with digital specification tools is compressing the gap between engineering design and field deployment. Regulatory carbon accounting and automated quality assurance are reshaping how repair composites qualify for public infrastructure awards.
Nanotechnology-modified resin matrices are unifying extreme-environment durability with standard epoxy processing parameters. Arctic and marine infrastructure contractors are specifying silica nanoparticle-enhanced formulations for freeze-thaw and salt-spray resistance. This convergence is compressing the historical trade-off between performance tier and application simplicity.
EU CE marking under the Construction Products Regulation is hardening factory production control requirements for structural composite manufacturers. Third-party certification bodies now audit continuous fiber placement and resin mixing protocols. German and French public works agencies are restricting procurement to CE-marked systems, compressing market access for uncertified suppliers.
Engineering firms are bundling composite material supply with structural health monitoring installation. Turnkey retrofit contracts now specify fiber optic strain sensing embedded within FRP laminates. This service integration is most visible in US bridge rehabilitation projects where federal lifecycle cost mandates reward predictive maintenance capabilities.
Construction Repair Composites Market Segmentation
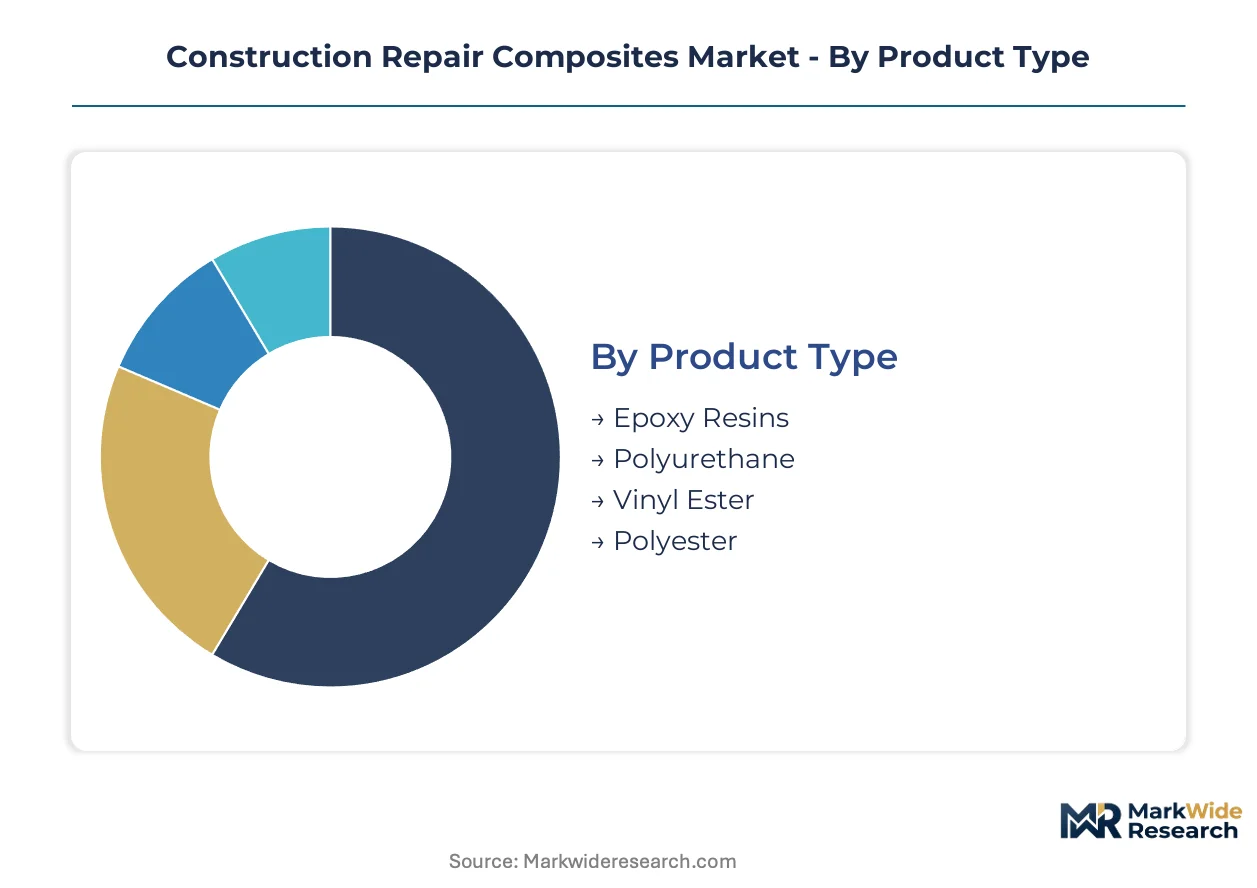
Construction repair composites segment along resin chemistry, structural application, procurement authority, and installation methodology. Each dimension shapes specification pathways, margin capture, and competitive positioning differently across infrastructure and industrial end-uses.
Product Type:
Cost tier stratification separates premium-specification resins from commodity alternatives in contractor procurement decisions.
- Epoxy Resins:Thermoset formulations achieve tensile strengths exceeding 1,500 MPa with superior substrate adhesion for concrete superstructure rehabilitation. German Federal Institute for Research on Building guidelines and US Federal Highway Administration protocols prioritize epoxy systems for load-bearing bridge repairs, though propylene and bisphenol-A feedstock volatility compresses applicator margins during petrochemical price spikes.
- Polyurethane:Elastomeric matrices deliver crack-bridging flexibility for dynamic load applications and seismic retrofitting. Japan's METI building safety directives specify polyurethane-modified systems for commercial facility earthquake reinforcement, where deformation tolerance outweighs absolute tensile strength requirements.
- Vinyl Ester:Hybrid chemistry balances epoxy-grade mechanical properties with polyester processing economics for industrial tank and pipe rehabilitation.
- Polyester:Unsaturated formulations dominate non-structural architectural restoration where cost sensitivity exceeds performance thresholds.
Epoxy resins lead volumes today; polyurethane is gaining share fastest in seismic-prone geographies.
Application:
Project scale and regulatory oversight intensity vary dramatically across structural versus non-structural deployment contexts.
- Infrastructure:Bridge deck strengthening, column wrapping, and seismic retrofitting of aging concrete superstructures drive specification volume. US Infrastructure Investment and Jobs Act maintenance backlogs accelerate state DOT procurement of pre-qualified fiber-reinforced polymer systems for federal highway rehabilitation projects.
- Marine:Salt-spray and freeze-thaw exposure demands silica nanoparticle-enhanced matrices for port infrastructure, offshore platforms, and coastal protection structures. Arctic contractors specify extreme-environment formulations where standard epoxy degradation rates would compromise structural integrity.
- Transportation:Railway tunnel lining repair and airport pavement rehabilitation require rapid-cure chemistries to minimize service disruption windows.
- Industrial Maintenance:Chemical processing facilities and power generation plants deploy corrosion-resistant wrapping systems for tank and pipeline life extension.
Infrastructure commands the deepest margin pool; marine applications show steepest specification growth as climate resilience mandates harden.
End User:
Procurement authority concentration determines specification complexity, qualification timeline, and contract bundling strategies.
- Government Agencies:Department of transportation maintenance divisions and federal highway authorities mandate ASTM D3039 testing protocols and CE marking compliance. EU Green Deal embodied carbon thresholds redirect public works specifications toward low-carbon epoxy formulations, disqualifying conventional repair methods in Germany, France, and Benelux jurisdictions.
- Contractors:Mid-tier infrastructure specialists lacking in-house mixing capability drive demand for prefabricated modular kits bundling pre-cut fiber sheets with matched epoxy chemistries.
- Construction Firms:Turnkey retrofit contractors integrate composite supply with structural health monitoring installation for predictive maintenance contracts.
- Private Sector:Commercial facility owners prioritize lifecycle cost optimization over first-cost minimization in seismic retrofit decisions.
Government agencies dominate specification authority today; contractor-direct procurement is expanding fastest as modular kit formats simplify field deployment.
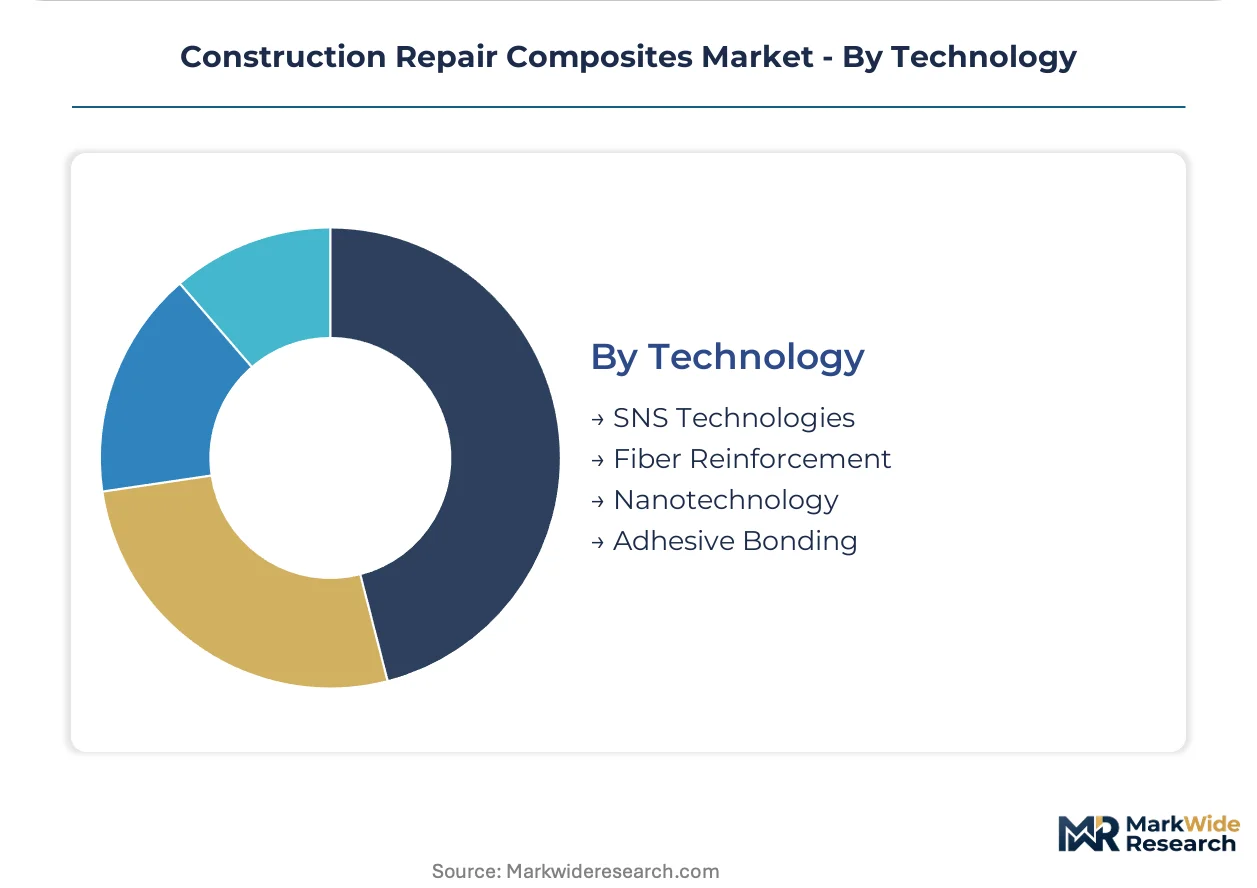
Technology:
Installation methodology and material science sophistication separate qualified applicator networks from generalist competitors.
- Fiber Reinforcement:Glass and carbon fiber systems achieve structural capacity restoration with minimal dead load addition to deteriorated concrete and steel elements. CE marking under EU Construction Products Regulation hardens factory production control requirements, with German and French public works agencies restricting procurement to third-party-certified systems.
- Nanotechnology:Silica nanoparticle-modified resin matrices unify extreme-environment durability with standard epoxy processing parameters for Arctic and marine infrastructure.
- Adhesive Bonding:Surface preparation protocols and primer application chemistries determine bond integrity in field conditions.
- SNS Technologies:Fiber optic strain sensing embedded within FRP laminates enables predictive maintenance capabilities for federal lifecycle cost mandates.
Fiber reinforcement anchors current specification volume; nanotechnology-modified matrices are climbing the fastest as climate exposure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction repair composites trace their industrial scaling to post-war European bridge reconstruction programs. German engineering standards subsequently migrated to North American infrastructure agencies. Japanese seismic retrofitting mandates later accelerated Asian specification adoption.
United States
State transportation departments face maintenance backlogs exceeding federal highway rehabilitation targets. The Infrastructure Investment and Jobs Act channels funding toward pre-qualified fiber-reinforced polymer systems for concrete superstructure strengthening. Texas and California DOTs concentrate procurement volume where seismic and corrosion exposure demands accelerate composite deployment.
Germany
The Federal Institute for Research on Building, Urban Affairs and Spatial Development prioritizes composite-based rehabilitation in technical directives for aging bridge decks. EU Green Deal embodied carbon thresholds redirect public works specifications toward low-carbon epoxy formulations. Industrial clusters along the Rhine-Main corridor host certified applicator networks serving federal highway authority contracts.
Japan
METI building safety directives expand demand for carbon fiber wrapping systems in commercial and public facilities. Seismic retrofit mandates concentrate procurement in metropolitan construction across Tokyo, Osaka, and Nagoya. Prefabricated modular kits simplify field deployment for contractors lacking in-house mixing capability.
China
Urban infrastructure renewal programs in seismic-prone regions create first-mover opportunities for composite retrofit specialists. National standards under MIIT align with international qualification protocols for structural strengthening applications. Yangtze River Delta municipalities pilot fiber-reinforced polymer systems for port infrastructure rehabilitation.
India
Smart Cities Mission funding accelerates bridge and building retrofit procurement in metropolitan construction. Bureau of Indian Standards certification requirements shape product acceptance criteria for public infrastructure awards. Maharashtra and Gujarat industrial corridors concentrate contractor capability development for composite installation.
Construction Repair Composites Market Vendor Landscape
Premium-margin players sit above commodity-margin players across specification channel control and adhesive formulation depth. Market structure fragments between multinational chemical conglomerates with captive resin production and specialized construction material suppliers focused on site-applicable systems. Three archetypes dominate: vertically integrated fiber-resin manufacturers, formulation specialists controlling public works specifications, and regional applicator-integrators bundling materials with installation services. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships with engineering firms for turnkey retrofit contracts.
Among Swiss and German formulation specialists, Sika AG and BASF SE occupy positions anchored by adhesive chemistry depth and European public works specification channels. Owens Corning exemplifies the fiber-centric archetype with North American glass fiber production integration. Mapei S.p.A. represents Italian construction material specialists focused on site-applicable mixing systems that reduce contractor labor hours.
| Leading Market Players |
|---|
| Owens Corning |
| DuPont de Nemours, Inc. |
| Sika AG |
| Mapei S.p.A. |
| Henkel AG & Co. KGaA |
| BASF SE |
| Saint-Gobain S.A. |
| Fosroc International Limited |
| Arkema SA |
| Others |
Supply Flow & Price Mechanics
Family-owned German and Swiss formulation specialists anchor supply discipline through multi-generational control over adhesive chemistry IP, compressing margin volatility for CE-marked epoxy systems while pricing power concentrates with certified applicator networks along the Rhine-Main corridor.
Pricing Analysis
Three-tier pricing structure across premium CE-marked systems, standard DOT-qualified formulations, and economy-grade polyester alternatives dominates contractor procurement. Price differentiation hinges on certification tier—ASTM D3039 and EN 15422 compliance commands substantial premiums—and volume scale for federal highway projects. Cost compression in standard epoxy tiers intensifies because propylene and bisphenol-A feedstock volatility squeezes applicator margins. Municipal DOTs exhibit highest price sensitivity due to fixed maintenance budgets, while turnkey retrofit contractors integrating structural health monitoring show lowest sensitivity.
Supply Chain Analysis
Epoxy resin supply rests on German, Dutch, and Belgian petrochemical producers with captive bisphenol-A capacity. Raw material dependencies include propylene derivatives, amine hardeners, and high-modulus carbon fiber tow from Japanese and South Korean manufacturers. Single-source vulnerability concentrates in aerospace-grade carbon fiber qualified for seismic wrapping applications. Distribution runs through authorized applicator networks certified under German Federal Institute for Research on Building protocols, with direct procurement from Sika AG and BASF SE formulation specialists for major infrastructure awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction repair composites market reads as a late-cycle quality story as bridge rehabilitation mandates and EU embodied carbon thresholds displace conventional steel plate bonding toward premium FRP specifications.
For Market Incumbents: Acquire certified applicator networks in underserved US Southeast and Indian metropolitan construction corridors. Consolidate backward into carbon fiber preform manufacturing to capture margin from Japanese and South Korean fiber suppliers. Threat displacement from nanotechnology-modified resin startups demands accelerated R&D in silica nanoparticle formulation capabilities. CE marking investment remains the priority lever for European public works specification control. For New Entrants and Emerging Players: Nanotechnology-enabled extreme-environment formulations offer specification traction in Arctic marine infrastructure and Japanese seismic retrofit markets. White-space concentrates in India's Smart Cities Mission bridge procurement and Chinese Yangtze River Delta port rehabilitation programs. Prefabricated modular kit formats penetrate mid-tier contractors lacking in-house mixing capability. Go-to-market through engineering firm partnerships for turnkey retrofit contracts bypasses established specification channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional applicator-integrators bundling materials with installation services in fragmented US and Asian markets. Long-term viability frames around 5-10 year infrastructure maintenance backlog duration and lifecycle cost mandate durability. Acquisition targets center on CE-marked formulation specialists with German Federal Highway Authority specification relationships. Watch EU Green Deal embodied carbon threshold tightening as inflection signal for bio-based epoxy formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Preforms | Captures margin from Toray and Toho Tenax supply concentration for seismic wrapping applications. |
| CE Marking Certification Investment | Unlocks German BAST and French CSTB specification channels for federal highway rehabilitation contracts. |
| Nanotechnology R&D Partnership | Develops silica nanoparticle-enhanced matrices for Arctic marine and Japanese METI-mandated seismic projects. |
| Modular Kit Format Launch | Penetrates mid-tier contractor segment lacking in-house epoxy mixing and fiber placement capability. |
| Structural Health Monitoring Integration | Bundles fiber optic strain sensing with FRP laminates for US Federal Highway Administration lifecycle cost mandates. |
Methodological Framework
Coverage spans Germany, the United States, Japan, China, and India, with primary inputs from each market's infrastructure procurement ecosystem. Field engagement combined project managers at state DOTs, certified FRP applicators, formulation R&D directors at adhesive specialists, and procurement leads at turnkey retrofit contractors with secondary validation from German Federal Institute for Research on Building technical directives, US Federal Highway Administration guideline publications, ASTM D3039 testing protocols, EU Construction Products Regulation CE marking databases, and customs records for carbon fiber and epoxy resin trade flows. Bottom-up project pipeline analysis triangulated against top-down infrastructure spending forecasts.
Granularity-level modeling addressed resin chemistry tier, structural application type, procurement authority concentration, and installation methodology sophistication across the projection horizon. Segmentation dimensions included epoxy versus polyurethane versus vinyl ester formulations, infrastructure versus marine versus industrial end-uses, government agency versus contractor-direct procurement, and fiber reinforcement versus nanotechnology-modified technology tiers. CAGRs derived from weighted infrastructure maintenance backlog projections and regulatory mandate implementation timelines. Industry-specific inputs encompassed German BAST guideline revision schedules and US Infrastructure Investment and Jobs Act funding disbursement patterns.
The model holds under stable petrochemical feedstock pricing and sustained federal highway maintenance funding; deviation in propylene cost spikes or infrastructure appropriation delays would shift volume and value trajectories. Forecasts reflect assumptions around CE marking compliance timelines and certified applicator network expansion rates. Regulatory carbon accounting rule evolution and Japanese seismic retrofit mandate acceleration constitute the small set of named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
North America Architectural Coatings Market
Building Materials
Long Steel Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Sanded Grout Market
Building Materials
Fiber Cement Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Natural Stone Slab Market
Building Materials
Fireproof Cladding Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
East Africa Cement Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Europe Cement Market
Building Materials
Global Corrugated Steel Sheets Market