
 Elevator Component Market | 2026-2036
Elevator Component Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Component Market Insights
The capital-intensity divergence between integrated manufacturers and component specialists is unwinding competitive dynamics across the supply base. Otis Elevator Company leverages captive production of hoisting machines to sustain margin control in high-rise commercial projects. KONE Corporation anchors its position through R&D intensity in machine room-less traction systems, while Schindler Group differentiates via channel control across European maintenance networks.
Elevator components comprise electromechanical subsystems—control systems, hoisting machines, safety devices, and elevator cars—engineered to vertical transport specifications typically rated between 1.0 and 10.0 meters per second depending on building height and traffic class. These assemblies translate electrical energy into controlled mechanical motion while maintaining redundant braking and overspeed governance for passenger safety. Control systems and safety devices command the deepest margin pools due to firmware complexity and certification barriers, whereas hoisting machines face price pressure from standardized magnetic core designs. Machine room-less traction technology expands fastest among technology segments, displacing hydraulic installations in mid-rise residential buildings where footprint constraints dominate architect specifications.
The US FDA oversees elevator safety in healthcare facilities through device-specific risk classifications, while China's SAMR enforces GB standards for electromagnetic compatibility and energy consumption in new installations. The EU's CE marking and Machinery Directive shape market access by mandating third-party conformity assessment for safety circuits and door locking mechanisms. Stakeholders must monitor regulatory divergence between ASME A17 codes in North America and emerging GB revisions in China when configuring global product platforms.
Market Dynamics
Machine room-less traction technology is compressing traditional hydraulic system demand across mid-rise residential construction, while China's GB standard revisions force component recertification throughout the supply chain.
Growth Catalysts
- Urban hospital infrastructure expansion:Southeast Asian healthcare facilities specify advanced safety devices and destination control systems for patient transport reliability.
- GB standard tightening:China's SAMR mandates electromagnetic compatibility and energy efficiency benchmarks that accelerate replacement cycles in existing building stock.
- Metropolitan high-rise density:Indian residential clusters in Mumbai, Delhi, and Bangalore drive procurement volume for traction and machine room-less configurations.
Market Restraints
- Copper and rare earth magnet volatility:Hoisting machine manufacturers face margin compression from permanent magnet supply concentration in Chinese processing facilities.
- CE marking conformity costs:The EU Machinery Directive mandates third-party assessment for safety circuits, extending time-to-market for non-European suppliers.
- Hydraulic system substitution ceiling:Low-rise commercial buildings in price-sensitive markets retain hydraulic installations where pit depth permits.
Strategic Opportunities
- Retrofit safety upgrade mandates:Japan's METI building codes create replacement demand for door locking mechanisms and overspeed governors in aging structures.
- Predictive maintenance convergence:IoT sensor integration with elevator control systems enables condition-based service contracts in premium commercial portfolios.
- Modular installation methods:Prefabricated elevator shaft systems reduce on-site labor requirements for German residential tower projects.
Industry Challenges
- Certified technician scarcity:Traction system commissioning requires specialized training that outpaces vocational program output in India's construction labor market.
- Legacy control integration:Modern destination dispatch systems face protocol incompatibility with 1990s-era relay logic in North American building retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Component Market |
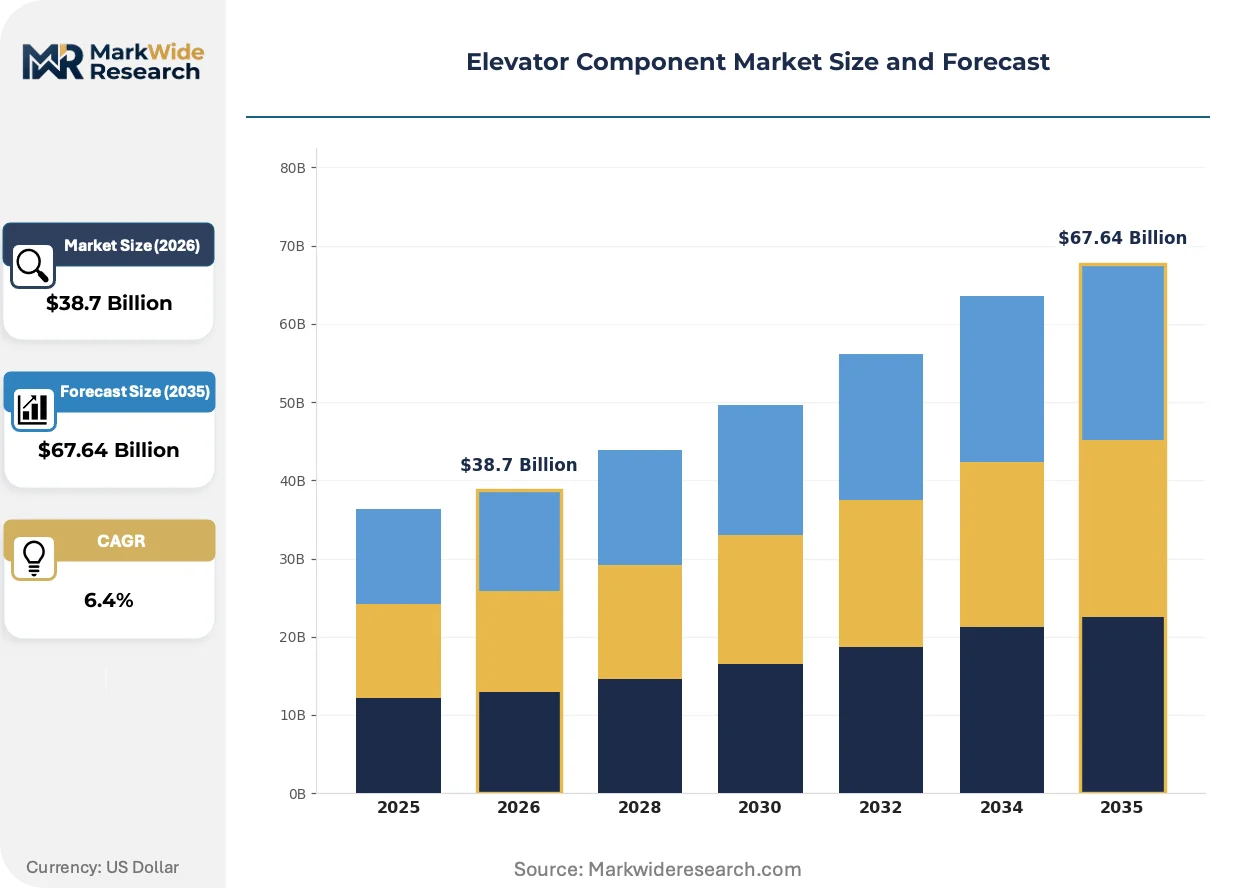
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Hoisting Machines, Safety Devices, Elevators Cars Technology: Hydraulic, Traction, Machine Room-Less, Vacuum End User: Residential Buildings, Commercial Offices, Hospitals, Industrial Facilities Installation Type: New Installations, Modernizations, Maintenance, Repairs |
| Companies Covered | Otis Elevator Company, KONE Corporation, Schindler Group, TK Elevator, Hitachi Ltd., Fujitec, Mitsubishi Electric Corporation, Hyundai Elevator Co. Ltd., Xizi Elevator Components Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Component Market Trends and Innovations
Digitalization of elevator subsystems is fragmenting traditional component boundaries, with software-defined safety functions and edge-computing controllers emerging as distinct value layers alongside mechanical assemblies.
Permanent magnet synchronous motor technology is decomposing the conventional separation between hoisting machine and control system vendors. Mid-rise residential developers in South Korea specify integrated motor-drive packages that compress installation timelines. This convergence is decomposing historical procurement patterns where mechanical and electrical subcontractors operated independently.
The EU's F-Gas Regulation is phasing out hydrofluorocarbon-based hydraulic fluids, compelling fluid formulation changes in remaining hydraulic installations. Component suppliers reformulate seal materials for compatibility with biodegradable alternatives. German and French elevator service networks face the steepest compliance retrofit obligations due to installed base age.
Building owners now unbundle long-term maintenance from initial equipment procurement, compressing manufacturer service contract attachment rates. Third-party maintenance specialists in Australia's commercial sector capture multi-brand service portfolios through standardized diagnostic tools. This unbundling is most visible in Sydney and Melbourne's Class A office markets where facility managers prioritize vendor flexibility over single-source accountability.
Elevator Component Market Segmentation
Elevator component procurement patterns diverge sharply across technical specifications and building typologies. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize R&D investment and channel configuration.
Product Type:
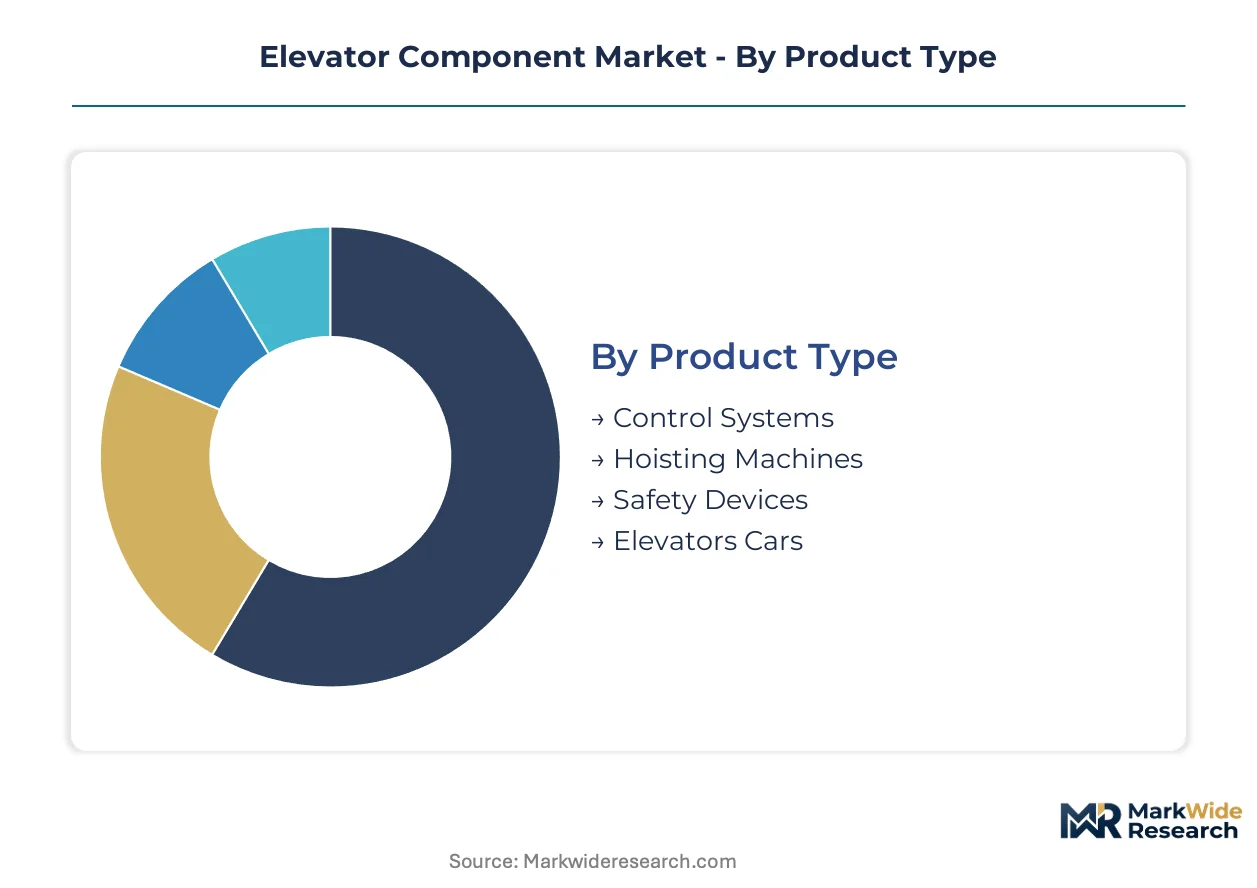
Control systems and safety devices command the deepest margin pools due to firmware complexity and certification barriers, while hoisting machines face sustained price pressure from magnetic core standardization.
- Control Systems:These units integrate microprocessor-based dispatch algorithms with destination selection protocols, managing traffic flow across multi-car banks. Demand concentrates in Southeast Asian hospital infrastructure where patient transport reliability mandates redundant controller architectures and real-time fault diagnostics.
- Safety Devices:Overspeed governors, door locking mechanisms, and emergency braking systems form the regulatory compliance layer of elevator assemblies. Japanese METI building codes drive replacement cycles in aging structures, creating sustained procurement volume for certified safety component manufacturers.
- Hoisting Machines:Permanent magnet synchronous motors and geared traction units translate electrical energy into mechanical lift force.
- Elevator Cars:Cab enclosures, door operators, and interior finishing assemblies complete the passenger interface.
The dominant share belongs to Control Systems, while Safety Devices is closing the gap fastest.
Technology:
Volume concentration follows building height restrictions and footprint constraints, with mid-rise residential specifications driving the steepest technology transitions.
- Machine Room-Less:Traction systems with compact permanent magnet motors eliminate overhead machine room requirements, reducing structural load and architectural interference. South Korean residential developers specify integrated motor-drive packages that compress installation timelines and enable smaller hoistway footprints.
- Traction:Conventional geared and gearless systems serve high-rise commercial towers requiring speeds above 2.5 meters per second.
- Hydraulic:Piston-driven systems retain cost advantages in low-rise commercial buildings where pit depth permits and speed requirements remain modest.
- Vacuum:Pneumatic tube systems address niche residential and scenic applications with limited travel distance.
Machine Room-Less configurations hold the largest installed base expansion, with Traction systems maintaining revenue leadership in premium commercial segments.
End User:
Building typology determines specification intensity, with healthcare and premium commercial assets demanding the highest component reliability grades.
- Hospitals:Patient transport elevators require advanced safety devices, destination control systems, and stretcher-compatible car dimensions. Southeast Asian healthcare infrastructure expansion specifies redundant braking systems and emergency power integration for critical vertical transport.
- Residential Buildings:High-rise clusters in Mumbai, Delhi, and Bangalore drive procurement volume for traction and machine room-less configurations.
- Commercial Offices:Class A facilities in Sydney and Melbourne prioritize destination dispatch and IoT-enabled predictive maintenance integration.
- Industrial Facilities:Freight elevators and material handling systems emphasize load capacity over passenger comfort specifications.
Residential Buildings account for the greatest unit volume, though Hospitals generate the highest revenue per installation.
Installation Type:
Service revenue stability varies dramatically across installation categories, with modernization cycles offering margin protection against new construction volatility.
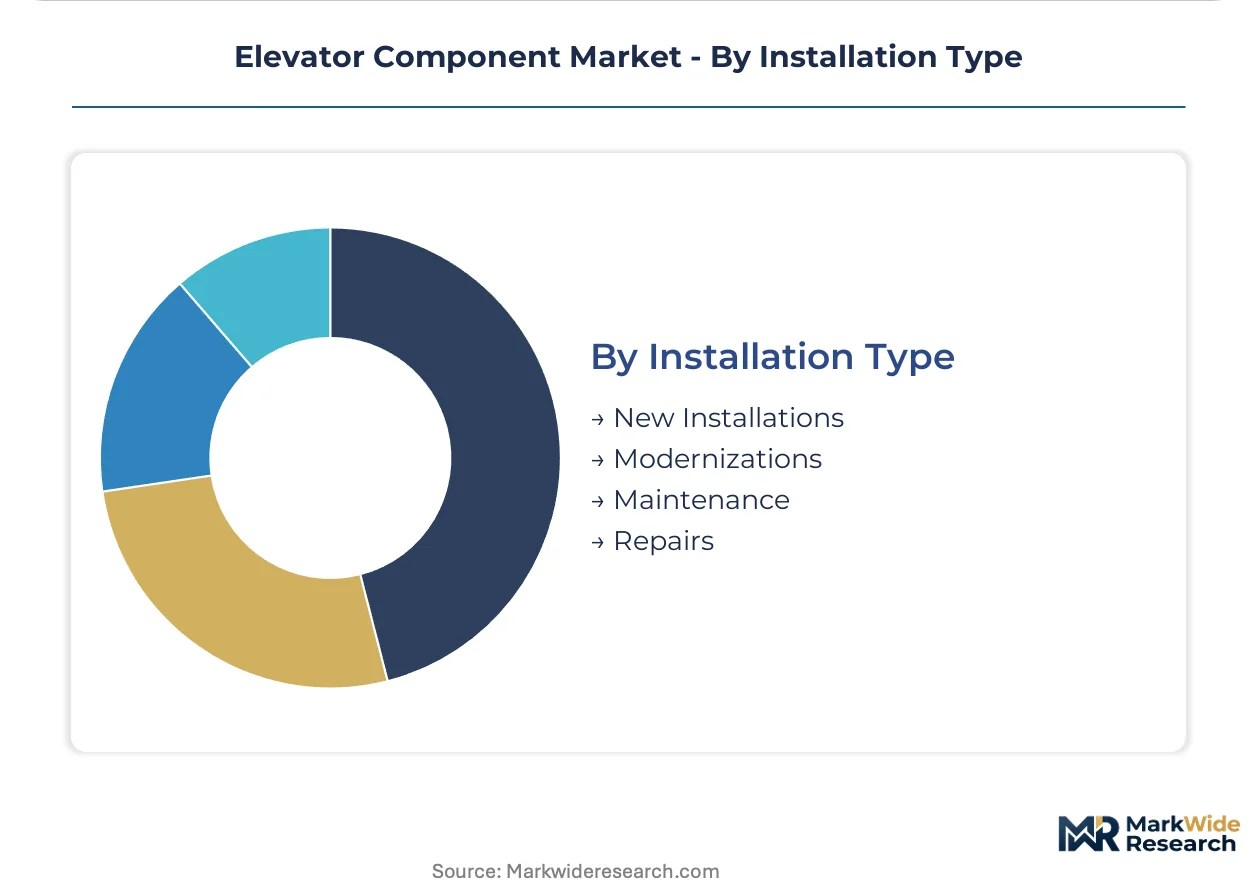
- Modernizations:Control system retrofits, safety upgrades, and car refurbishment extend equipment life in aging building stock. China's GB standard tightening accelerates replacement cycles for electromagnetic compatibility and energy efficiency compliance.
- New Installations:Greenfield construction projects specify complete subsystem packages from foundation to final inspection.
- Maintenance:Third-party service specialists in Australia's commercial sector capture multi-brand portfolios through standardized diagnostic platforms.
- Repairs:Break-fix interventions address component failures outside scheduled maintenance intervals.
New Installations dominate absolute revenue, while Modernizations is gaining share fastest as regulatory compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in elevator components tilt toward net-import dependence in Southeast Asian healthcare markets, while Chinese manufacturers leverage GB standard alignment to capture share across Belt and Road infrastructure corridors.
China
Urban hospital construction in Chengdu and Wuhan drives procurement of advanced safety devices and destination control systems. SAMR enforces tightening GB standards for electromagnetic compatibility and energy efficiency that accelerate replacement cycles in existing building stock. Component manufacturers cluster in the Yangtze River Delta, where machine room-less traction systems dominate export configurations.
India
High-rise residential towers in Mumbai, Delhi, and Bangalore generate concentrated demand for traction and machine room-less configurations. BIS certification requirements for elevator safety components create compliance barriers for non-domestic suppliers. The Delhi-NCR corridor anchors procurement volume, with local fabricators scaling permanent magnet synchronous motor production.
Japan
Aging building stock in Osaka and Nagoya triggers modernization cycles for door locking mechanisms and overspeed governors. METI building codes mandate retrofit safety upgrades that sustain replacement demand for certified component manufacturers. The Kanto region concentrates R&D activity in predictive maintenance integration.
Germany
Prefabricated elevator shaft systems reduce on-site labor requirements for residential tower projects in Berlin and Hamburg. The EU F-Gas Regulation phases out hydrofluorocarbon-based hydraulic fluids, compelling seal material reformulation. Bavaria and North Rhine-Westphalia host the densest concentration of service networks facing compliance retrofit obligations.
South Korea
Seoul Capital Area developers specify integrated motor-drive packages that compress installation timelines for mid-rise residential construction. MFDS-aligned safety protocols govern hospital elevator specifications in the Busan-Ulsan corridor. Domestic component suppliers leverage compact permanent magnet motor designs to displace conventional hydraulic installations.
Elevator Component Market Competitive Landscape
Concentration sits with integrated elevator manufacturers that maintain captive production of critical subsystems. The supply base separates into three strategic archetypes: full-system integrators controlling hoisting machine fabrication, component specialists focused on safety device certification, and regional fabricators serving modernization cycles. Competitive moves center on backward integration into permanent magnet motor production and strategic partnerships with prefabricated shaft system providers.
Within the integrated manufacturer tier, Otis Elevator Company, KONE Corporation, and Schindler Group exemplify divergent approaches to margin protection. Otis leverages in-house production of hoisting machines to sustain pricing control in high-rise commercial projects. KONE anchors its position through R&D intensity in machine room-less traction configurations. Schindler differentiates via channel control across European maintenance networks. Xizi Elevator Components Co. Ltd. occupies a position among Chinese specialists scaling export capacity for traction system subassemblies.
| Leading Market Players |
|---|
| Otis Elevator Company |
| KONE Corporation |
| Schindler Group |
| TK Elevator |
| Hitachi Ltd. |
| Fujitec |
| Mitsubishi Electric Corporation |
| Hyundai Elevator Co. Ltd. |
| Xizi Elevator Components Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day safety component lead times concentrate procurement leverage among GB-certified Chinese suppliers, compressing margin pools for non-aligned manufacturers while elevating pricing power for electromagnetic compatibility-compliant control system vendors. This inventory tightness feeds directly into project-based contract structures where hospital infrastructure buyers absorb premiums for certified subsystems.
Pricing Analysis
Configured-to-order pricing for machine room-less traction systems commands spreads of 35-50% above standard hoisting machine catalogs, with premium-mid-economy pricing differentiation anchored in CE marking tier and permanent magnet motor efficiency grade. Pricing pressure stems from copper and rare earth magnet volatility concentrated in Chinese processing facilities, eroding margins on standardized magnetic core designs. Healthcare facility buyers exhibit lowest price sensitivity due to patient transport reliability mandates, while Indian residential developers drive hardest bargain on volume-scale traction procurement.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam lanes elevates inbound logistics costs for European safety device distributors, compressing working capital cycles for CE marking-dependent suppliers. Permanent magnet synchronous motors draw from Chinese rare earth processing, Japanese magnetic steel, and German precision machining, with single-source vulnerability concentrated in dysprosium and terbium supply. Distribution runs through integrated manufacturer captive networks for high-rise commercial projects, while third-party specialists capture multi-brand service portfolios in Australian and Southeast Asian modernization cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine room-less traction penetration in mid-rise residential construction sits below 40% across price-sensitive markets, creating early-cycle expansion runway as footprint constraints tighten architect specifications and hydraulic substitution accelerates.
For Market Incumbents: Fortify backward integration into permanent magnet motor production to offset rare earth price volatility, while deepening channel control across European maintenance networks against third-party diagnostic platform entrants. Invest in GB standard pre-certification for electromagnetic compatibility subsystems ahead of SAMR enforcement waves. For New Entrants and Emerging Players: CE marking fast-track for safety circuits opens wedge positioning in German and French hydraulic modernization cycles driven by F-Gas Regulation compliance deadlines. Target India's BIS certification gap for traction system subassemblies, where domestic fabricators lag permanent magnet synchronous motor scale. Lead with prefabricated shaft system partnerships to compress on-site labor requirements for Berlin and Hamburg residential towers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across machine room-less traction sub-assemblies as integrated motor-drive packages standardize, favoring asset-light component specialists over full-system fabricators. Acquire predictive maintenance software layers with IoT sensor integration capabilities, as condition-based service contracts displace traditional maintenance attachment. Monitor CE marking conformity cost inflation as inflection indicator for non-European supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive supply of rare earth-dependent cores insulates margin from Chinese processing volatility. |
| GB Standard Pre-Certification Investment | SAMR electromagnetic compatibility alignment accelerates replacement cycle capture in Chengdu and Wuhan hospital builds. |
| Predictive Maintenance Platform Development | IoT sensor integration with control systems enables condition-based contracts in Sydney Class A office portfolios. |
| Prefabricated Shaft System Partnership | Modular installation methods reduce on-site labor for German residential tower projects facing technician scarcity. |
| Third-Party Diagnostic Tool Standardization | Multi-brand service capture in Australian commercial sector unbundles manufacturer maintenance attachment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging elevator OEM procurement directors, hospital facilities managers in Southeast Asian healthcare systems, and third-party maintenance specialists in Australian commercial portfolios. Secondary validation drew from SAMR GB standard filings, EU Machinery Directive conformity databases, BIS certification registries, and customs trade flow data for permanent magnet synchronous motor subassemblies. Bottom-up project pipeline analysis across Mumbai, Delhi, and Bangalore residential towers triangulated with top-down equipment stock estimates for Japanese METI modernization cycles.
Across the analysis window, volume and value outputs segmented by product type, technology configuration, end-user building typology, and installation category. Modeled dimensions included machine room-less versus traction versus hydraulic technology splits, hospital versus residential versus commercial office end-use concentration, and modernization versus new installation revenue mix. CAGRs derived from equipment stock depreciation curves, regulatory compliance deadline clustering, and urban hospital infrastructure expansion pipelines in Southeast Asian metropolitan clusters.
Underlying assumptions cover GB standard enforcement continuity, rare earth supply concentration persistence, and technician training program scaling in Indian construction labor markets, with deviation risk concentrated in CE marking conformity cost inflation and F-Gas Regulation phase-out acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Autonomous Warehouse Equipment Market