
 Global FRP Rebar Market | 2026-2036
Global FRP Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
Global FRP Rebar Market Analysis
ACI 440 certification for FRP reinforcement is redrawing competitive boundaries across the supply base. Pultron Composites leverages its New Zealand manufacturing base to sustain export volumes into Australian infrastructure programs. Owens Corning anchors North American supply through integrated glass fiber production and captive resin formulation. Schöck Bauteile GmbH differentiates via European technical approval holders and specialized structural connection expertise.
Fiber-reinforced polymer rebar comprises continuous glass, carbon, or basalt fibers embedded in a thermosetting vinyl ester or epoxy matrix, manufactured through pultrusion to achieve tensile strengths exceeding 110 ksi while remaining electromagnetically transparent and one-quarter the weight of steel. Glass FRP dominates volume due to cost positioning in highway barriers and parking structures, while carbon FRP commands premium placement in pre-stressed concrete bridge elements where modulus requirements are stringent. Marine applications represent the fastest-expanding demand pool as salt-water corrosion destroys conventional rebar within fifteen years of installation.
ASTM D7957 governs dimensional tolerances and mechanical property testing in the United States, while the EU Green Deal and associated CSRD reporting obligations pressure construction firms to document embodied carbon reductions from corrosion-free material selections. Japan's METI has incorporated FRP reinforcement standards into seismic retrofit guidelines for public buildings. Stakeholders must monitor how evolving EPD certification requirements and procurement rules from infrastructure agencies in Germany, Japan, and the United States alter specification gatekeeping before committing capacity expansion plans.
Market Dynamics
Corrosion-resistant material mandates in marine construction codes are displacing conventional steel specifications and redrawing competitive boundaries across the supply base. Government agencies in coastal regions are accelerating bridge deck rehabilitation programs, creating sustained demand pull for fiber-reinforced polymer alternatives that outlast traditional reinforcement in chloride environments.
Growth Catalysts
- ACI 440 Certification:North American infrastructure agencies now require this standard for public bridge projects, opening specification pathways previously blocked to composite materials.
- EU Green Deal:CSRD reporting obligations pressure construction firms to document embodied carbon reductions from corrosion-free material selections in marine environments.
- Japan Seismic Retrofits:METI has incorporated FRP reinforcement standards into public building earthquake resilience guidelines, creating mandatory replacement demand.
Market Restraints
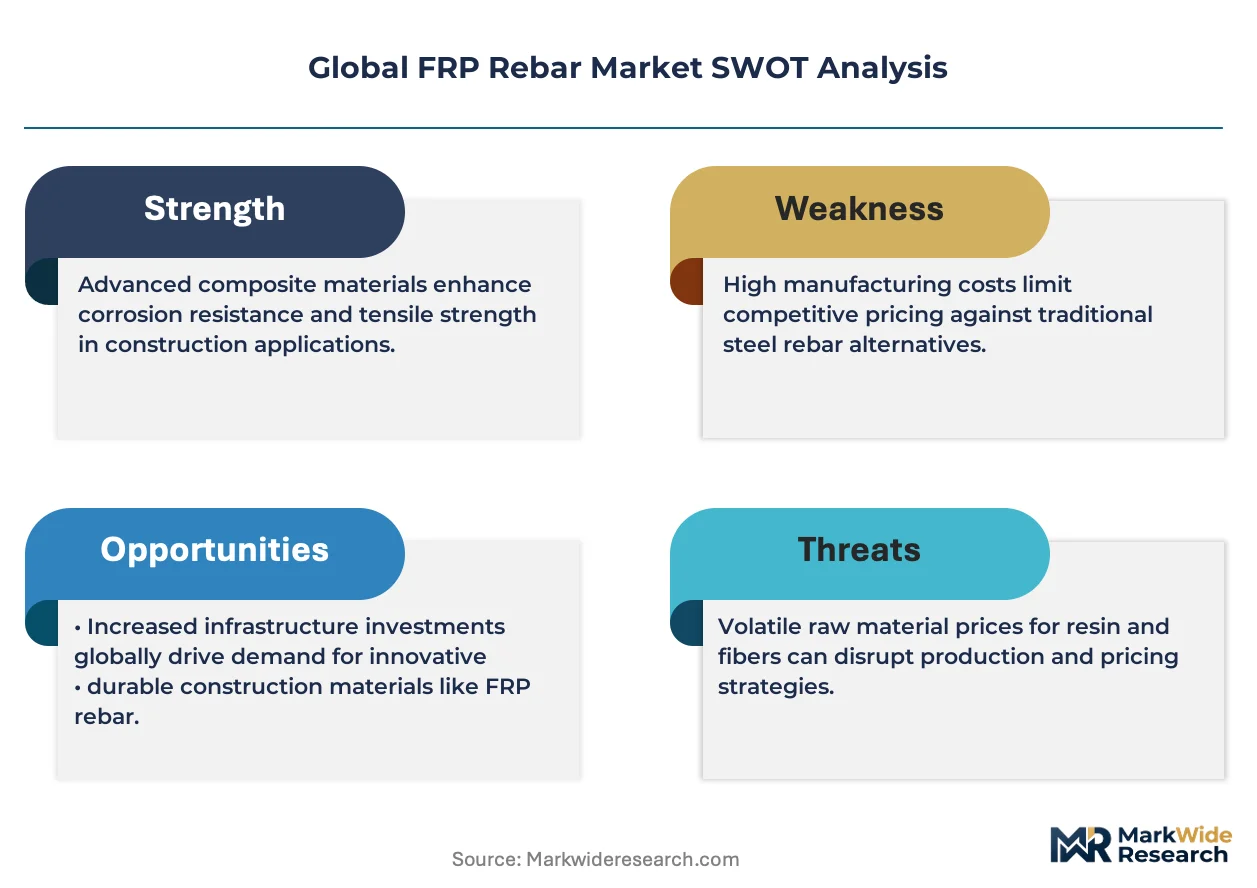
- Vinyl Ester Resin Volatility:Petrochemical feedstock price swings compress margins for pultrusion manufacturers dependent on thermoset matrix systems.
- Carbon Fiber Supply Concentration:Asian precursor production dominates, exposing Western fabricators to geopolitical disruption risk and import dependency.
- ASTM D7957 Testing Burden:Dimensional tolerance verification and mechanical property documentation requirements extend qualification timelines for new market entrants.
Strategic Opportunities
- India Coastal Infrastructure:BIS standards development for FRP reinforcement in port construction creates early-mover advantage before specification lock-in.
- Hybrid Steel-FRP Systems:Structural engineers are designing composite reinforcement cages that combine electromagnetic transparency with conventional steel moment capacity.
- Direct Agency Contracting:State departments of transportation in the United States are bypassing traditional distributor networks for high-volume highway barrier procurements.
Industry Challenges
- EPD Certification Timelines:Third-party environmental product declaration verification for EU Green Deal compliance consumes 8-14 months, delaying project eligibility.
- Design Engineer Familiarity Gap:Structural engineering curricula emphasize steel and concrete, leaving practicing professionals unprepared for anisotropic composite behavior modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FRP Rebar Market |
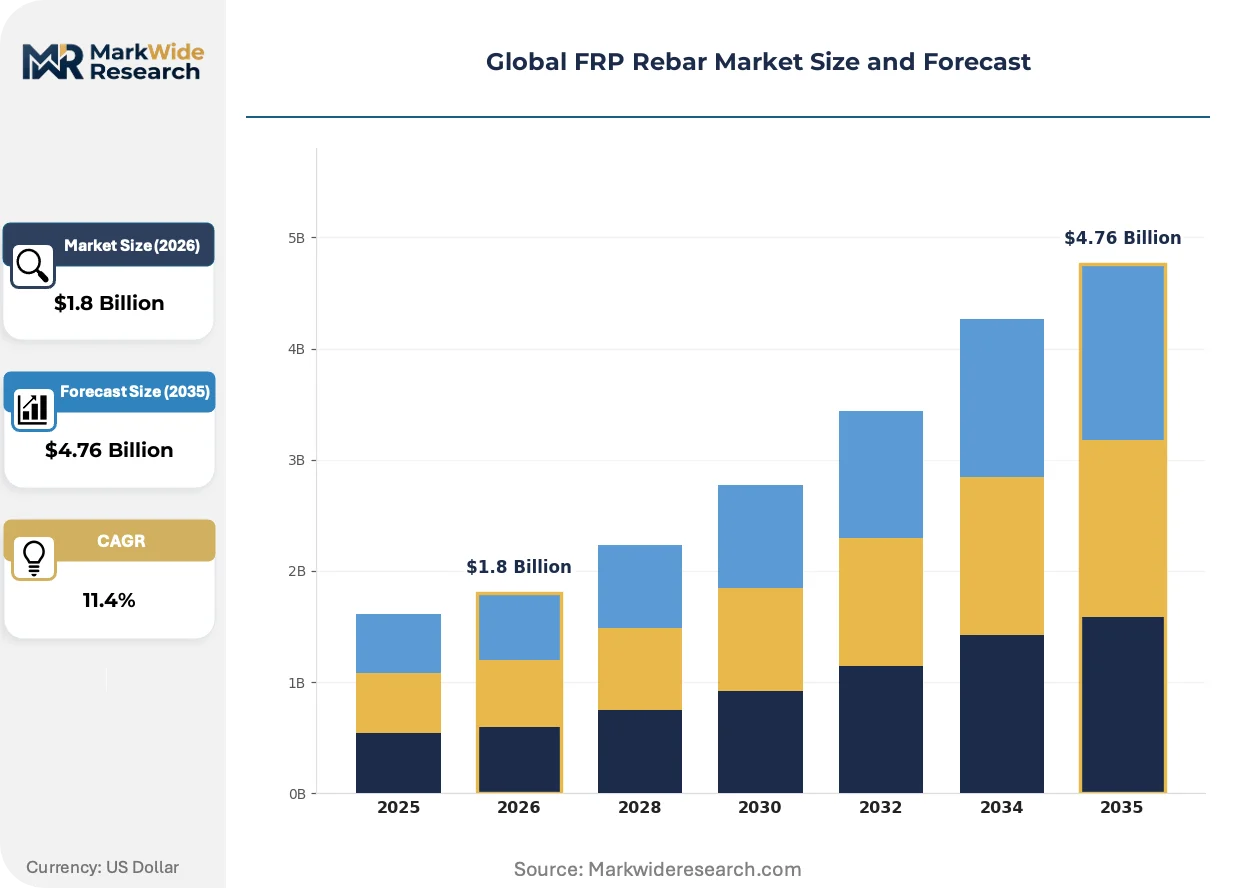
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass FRP, Carbon FRP, Basalt FRP, Hybrid FRP Application: Construction, Infrastructure, Transportation, Marine End User: Contractors, Engineers, Construction Firms, Government Agencies Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Dextra Group, Pultron Composites, Schöck Bauteile GmbH, Pultrall Inc., Kodiak Fiberglass Rebar, Owens Corning, Aslan FRP, Neuvokas Corporation, Röchling Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FRP Rebar Market Emerging Trajectories
Material science advances and code development cycles are converging to expand addressable applications beyond traditional corrosion replacement scenarios. Specification gatekeeping is loosening as performance data accumulates from multi-decade installations.
Basalt fiber reinforcement is fragmenting the glass-dominated volume segment by offering intermediate modulus properties at cost positions below carbon fiber. German highway authorities are specifying basalt FRP for noise barrier foundations where alkali resistance exceeds glass capabilities. The technology is fragmenting procurement patterns as engineers specify hybrid reinforcement schedules rather than material-class substitutions.
REACH authorization requirements for styrene emissions in vinyl ester resin production are forcing formulation shifts toward low-V epoxy alternatives in European manufacturing. Pultruders in Germany and the Netherlands are retooling lines to handle higher-viscosity thermoset systems. Marine construction specifications in the Baltic region are most affected, with contractors demanding pre-certified low-emission rebar to satisfy environmental impact assessments.
Asset owner engineering departments are internalizing FRP specification expertise that previously resided with specialty consultants. United States state transportation agencies are hiring composite materials engineers to evaluate supplier submissions directly, compressing the traditional architect-engineer-broker chain. This concentration of technical judgment in public procurement offices is most visible in Florida and California coastal bridge programs.
Global FRP Rebar Market Segmentation
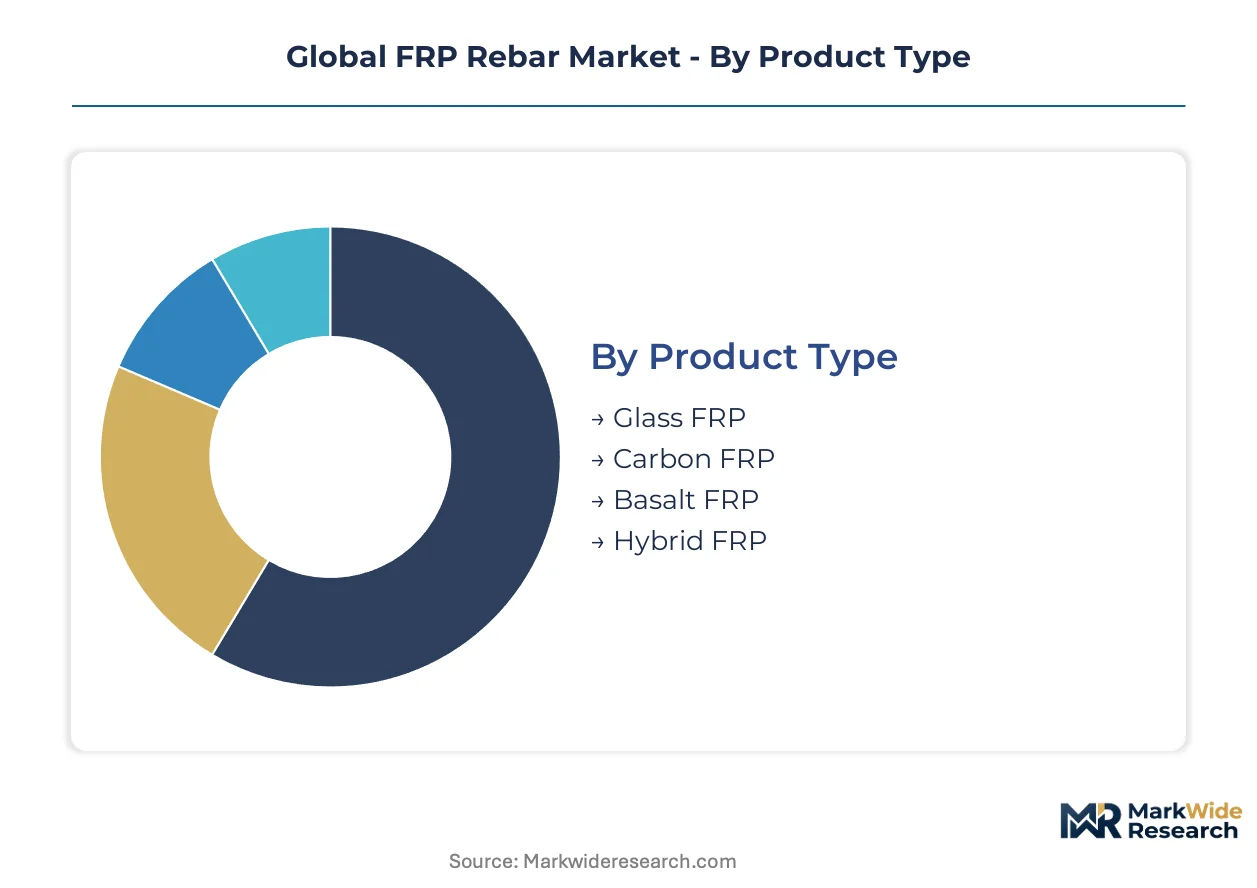
FRP rebar procurement patterns diverge sharply by material chemistry and project scale. Specification gatekeepers in public infrastructure agencies drive category prioritization differently than private construction portfolios.
Product Type:
Margin pools concentrate in carbon fiber formulations where modulus premiums justify 3-4x material cost multiples over glass alternatives.
- Glass FRP:Continuous E-glass or E-CR glass fibers in vinyl ester matrix dominate highway barrier and parking structure specifications. United States state DOTs specify glass FRP for electromagnetic transparency requirements in toll plaza foundations and intelligent transportation system embedments.
- Carbon FRP:PAN-based carbon fiber in epoxy matrix commands pre-stressed concrete bridge element placements where modulus exceeding 120 GPa is mandatory. Japanese METI seismic retrofit guidelines specify carbon FRP for column wrapping in public buildings where ductility demands exceed glass capabilities.
- Basalt FRP:Quarried basalt roving in thermoset matrix offers intermediate modulus at cost positions below carbon fiber. German highway authorities specify basalt for noise barrier foundations where alkali resistance exceeds glass performance.
- Hybrid FRP:Combined glass-carbon or basalt-carbon layups optimize cost-performance ratios in specialized structural cages.
Glass FRP holds installed capacity. Carbon FRP is rotating up the share rankings.
Application:
Volume concentrates in infrastructure replacement cycles where corrosion damage to steel has reached critical thresholds.
- Construction:Commercial and residential building foundations, swimming pool shells, and architectural precast elements specify FRP for electromagnetic neutrality. Florida and California coastal municipalities mandate FRP in public building foundations within chloride exposure zones.
- Infrastructure:Bridge deck overlays, tunnel linings, and water treatment facilities represent the largest addressable demand pool. United States federal highway programs in coastal states now require corrosion-resistant reinforcement in all substructure elements.
- Transportation:Airport runways, rail electrification corridors, and magnetic levitation guideways demand electromagnetically transparent reinforcement. Shanghai and Munich airport expansion projects specified carbon FRP for precision landing system interference elimination.
- Marine:Seawalls, jetties, and port infrastructure face the most aggressive chloride exposure. Baltic Sea port authorities in Poland and Sweden specify low-emission epoxy FRP to satisfy environmental impact assessments.
Infrastructure captures the majority of specification-driven volume. Marine is climbing the fastest as salt-water damage accelerates replacement cycles.
End User:
Procurement authority is concentrating in government technical offices that previously outsourced materials selection.
- Contractors:General and specialty contractors purchase FRP for design-build and hard-bid projects where specifications permit composite alternatives. Large infrastructure contractors in Texas and Florida maintain bonded inventory for emergency bridge repairs.
- Engineers:Structural design firms specify FRP in coastal and corrosive environments where lifecycle cost analysis favors non-metallic reinforcement. Engineering consultancies in Hamburg and Rotterdam have developed proprietary FRP design tools for marine infrastructure.
- Construction Firms:Integrated builders with in-house engineering capabilities optimize material selection across project portfolios. Japanese general contractors have established captive FRP supply relationships for METI-mandated seismic retrofits.
- Government Agencies:State and federal transportation departments are the fastest-expanding customer segment. United States DOTs in Florida, California, and New Jersey have hired composite materials engineers to evaluate supplier submissions directly.
Government Agencies are consolidating procurement authority. Engineers retain specification influence but face compressed review timelines.
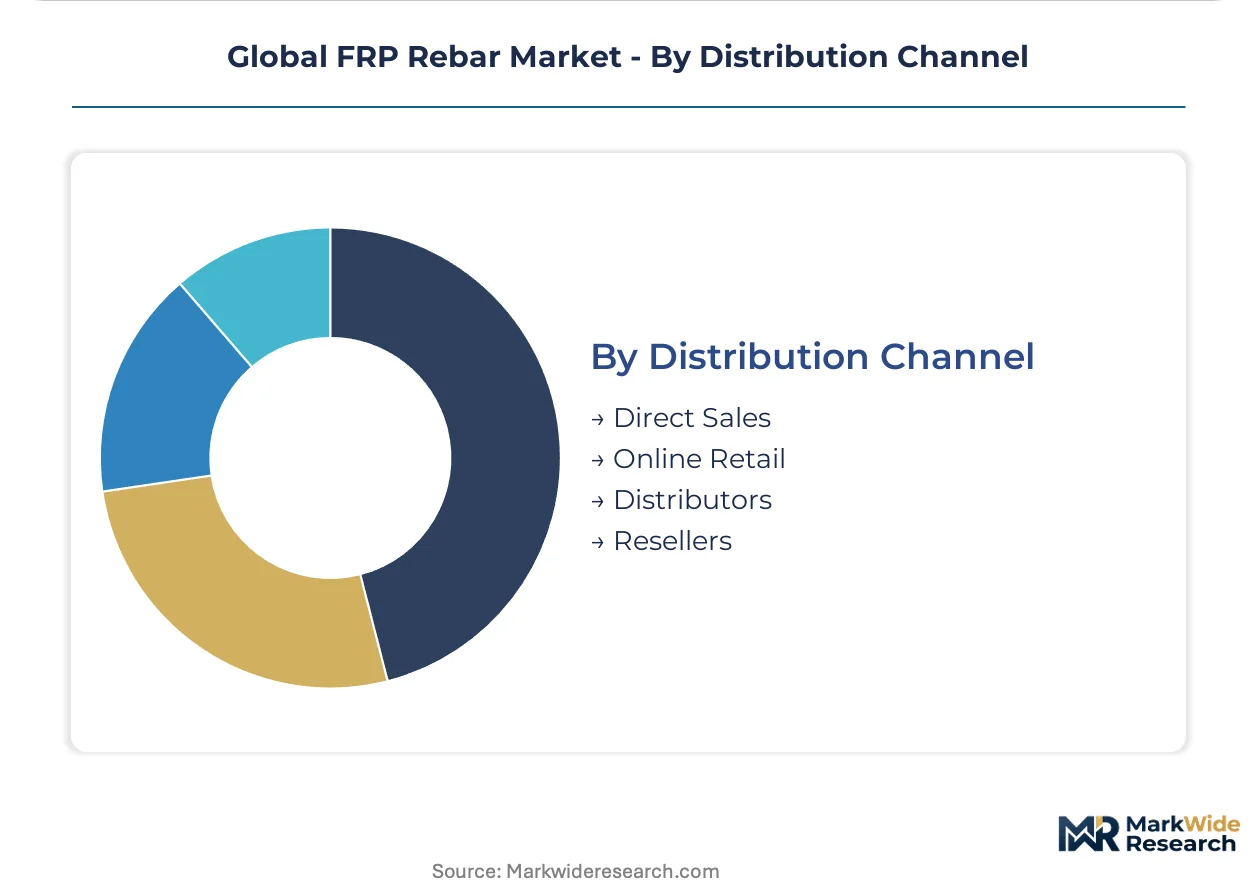
Distribution Channel:
Channel economics favor direct relationships as volume thresholds trigger agency bypass of traditional intermediaries.
- Direct Sales:Pultruders contract directly with state DOTs and federal infrastructure agencies for high-volume highway barrier and bridge deck programs. Owens Corning maintains dedicated account teams for United States transportation agency procurement offices.
- Online Retail:E-commerce platforms serve small contractors and repair specialists requiring cut-length FRP bar and custom fabrication. Alibaba and specialized construction material marketplaces list Chinese and Turkish FRP products for international shipment.
- Distributors:Regional construction supply houses stock standard diameters for immediate availability in metropolitan construction markets. Distributors in Sydney and Melbourne maintain inventory for Australian infrastructure agency call-off contracts.
- Resellers:Independent representatives aggregate demand from smaller engineering firms and municipal public works departments. Reseller networks dominate in Indian coastal states where BIS standards development is creating early specification opportunities.
Direct Sales captures the largest transaction values. Online Retail is expanding fastest among small-project segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Gate Bridge seismic retrofit program validates California's infrastructure replacement cycle. Chinese port expansion along the Yangtze River Delta consumes basalt FRP for chloride-resistant foundations. German noise barrier specifications underwrite European demand for alkali-resistant reinforcement.
United States
Florida Department of Transportation mandates FRP in all substructure elements within salt-water exposure zones. ACI 440 certification requirements now govern public bridge project specifications nationwide. State DOTs in California, New Jersey, and Texas maintain bonded inventory for emergency coastal repairs.
Germany
Federal highway authorities specify basalt FRP for noise barrier foundations where alkali resistance exceeds glass capabilities. REACH authorization for styrene emissions forces pultruders toward low-V epoxy alternatives. Manufacturing clusters in North Rhine-Westphalia retool lines for higher-viscosity thermoset systems.
China
Port construction along the Yangtze River Delta and Pearl River Delta accelerates specification development for chloride-resistant reinforcement. GB standards development for marine infrastructure creates procurement pathways for domestic fabricators. Shanghai airport expansion specified carbon FRP for precision landing system interference elimination.
Japan
METI incorporated FRP reinforcement standards into seismic retrofit guidelines for public buildings. Column wrapping specifications in Tokyo and Osaka demand carbon FRP where ductility requirements exceed glass capabilities. General contractors established captive supply relationships for mandated public building upgrades.
India
BIS standards development for FRP reinforcement in port construction creates early-mover advantage before specification lock-in. Coastal infrastructure programs in Gujarat and Maharashtra face aggressive salt-water corrosion cycles. Reseller networks aggregate demand from municipal public works departments in Kerala and Tamil Nadu.
Global FRP Rebar Market Vendor Landscape
Listed leaders compete with private specialists across certification access and resin formulation capabilities. The supply base fragments across integrated glass fiber producers, dedicated pultrusion fabricators, and regional construction material specialists. Three archetypes dominate: captive fiber-resin integrators, specification-focused engineering houses, and volume-driven highway barrier suppliers. Competitive moves concentrate on ACI 440 certification acquisition and direct state DOT contracting relationships.
Among New Zealand-based fabricators, Pultron Composites occupies a position exemplifying export-oriented supply architecture. Owens Corning represents the integrated fiber-resin archetype through captive glass production and matrix formulation. Schöck Bauteile GmbH anchors the European technical approval tier with specialized structural connection expertise.
| Leading Market Players |
|---|
| Dextra Group |
| Pultron Composites |
| Schöck Bauteile GmbH |
| Pultrall Inc. |
| Kodiak Fiberglass Rebar |
| Owens Corning |
| Aslan FRP |
| Neuvokas Corporation |
| Röchling Group |
| Others |
Supply Flow & Price Mechanics
Basalt fiber substitution for glass in German noise barrier foundations redraws procurement geography while compressing intermediate-tier pricing bands. State transportation agencies in Florida and California exploit this feedstock diversification to renegotiate long-term supply agreements.
Pricing Analysis
Volume-discount tiering structures separate carbon FRP pre-stressed bridge elements from glass FRP highway barriers and basalt FRP marine foundations. Price differentiation hinges on ACI 440 certification grade and resin formulation sophistication—low-V epoxy systems command premiums in Baltic marine contracts. Cost compression in glass FRP intensifies as Chinese pultruders expand export capacity into Australian infrastructure programs. Small contractors through online retail channels exhibit highest price sensitivity; government agencies with bonded inventory requirements show lowest.
Supply Chain Analysis
Inventory lead times stretch 8-14 months for EPD-certified product destined to EU Green Deal compliance. Geographic supply concentration centers on China for glass fiber precursor, Germany for basalt roving processing, and the United States for vinyl ester resin formulation. Raw material dependencies encompass PAN-based carbon fiber from Asian precursor producers, quarried basalt from Russian and Ukrainian deposits, and petrochemical-derived thermoset systems. Single-source vulnerability in carbon fiber precursor exposes Western fabricators to geopolitical disruption. Distribution runs through direct state DOT contracting for highway barrier volume, with regional distributors serving emergency repair call-offs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ACI 440 certification mandates constitute a regulatory inflection accelerating material substitution across North American public infrastructure. This disruption expands addressable demand pools beyond traditional corrosion replacement scenarios.
For Market Incumbents: Fortify specification gatekeeping through captive EPD certification capacity and direct agency engineering relationships. State DOTs in Florida and California are internalizing technical evaluation expertise—incumbents must embed composite materials engineers within procurement offices to defend position. Backward integration into vinyl ester resin formulation mitigates petrochemical feedstock volatility threatening margin stability.
For New Entrants and Emerging Players: Differentiate on low-emission epoxy formulations for Baltic Sea marine construction where REACH authorization pressures incumbent pultruders. India coastal infrastructure presents penetrable white space before BIS standards crystallize specification lock-in. Target reseller network aggregation in Gujarat and Maharashtra municipal public works departments as the go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed highway barrier specialists lacking carbon FRP modulus capabilities or METI seismic retrofit certification. Long-term viability favors integrated fiber-resin fabricators with agency direct contracting relationships. Watch Japanese general contractor captive supply relationship announcements as the inflection indicator for specification authority consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ACI 440 Certification Acquisition | Unlocks specification pathways for public bridge projects in Florida, California, and Texas DOT programs. |
| Backward Integration into Resin Formulation | Captures margin compression from vinyl ester petrochemical feedstock volatility affecting pultruders. |
| Direct State DOT Contracting Relationships | Bypasses distributor intermediaries for high-volume highway barrier and bridge deck procurements. |
| EPD Certification Pre-Positioning | Secures EU Green Deal eligibility for marine construction contracts in Poland and Sweden. |
| Hybrid FRP System Development | Addresses electromagnetic transparency requirements in Shanghai and Munich airport precision landing systems. |
Methodological Framework
Cross-validation between pultrusion plant manager interviews and customs trade data anchors the qualitative findings. Primary engagement encompassed composite materials engineers at state transportation agencies, procurement leads at German highway authorities, technical directors at marine construction firms, and resin formulation specialists at thermoset suppliers. Secondary sources incorporated ACI 440 certification registries, ASTM D7957 test documentation, EU EPD certification databases, and METI seismic retrofit guideline publications. Bottom-up capacity assessments triangulate against top-down infrastructure spending projections.
Sensitivity analysis around resin feedstock cost trajectories and certification timeline assumptions shapes the analytical framework. Segmentation dimensions encompass fiber chemistry tier, application exposure severity, end-user procurement authority, and regional regulatory cluster. CAGRs derive from infrastructure replacement cycle intensity and code adoption velocity. Carbon fiber supply concentration risk and REACH authorization timelines constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside ACI 440 certification expansion or EU Green Deal enforcement intensity would require recalibration. Forecasts reflect assumptions regarding infrastructure agency staffing for composite materials expertise and BIS standards development velocity in India. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Italy Cement Market
Building Materials
East Africa Cement Market
Building Materials
Steel Products Market
Building Materials
Roofing and Insulation Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Building and Construction Plastics Market
Building Materials
North America Architectural Coatings Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Basalt Rock Market
Building Materials
Bolt (Fastener) Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Exterior Doors Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Global Fiber Cement Siding Market