
 Fiber Optic Cable Materials Market | 2026-2036
Fiber Optic Cable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Cable Materials Market Intelligence
Buyer concentration is shifting as hyperscale data center operators consolidate procurement volumes while regional telecom providers fragment demand across specialized fiber grades. Corning Incorporated leverages vertical integration from preform to cable to sustain margin capture across the value chain. Prysmian Group anchors European supply through manufacturing scale and submarine cable specialization. Fujikura Ltd differentiates via polarization-maintaining fiber leadership for sensing and defense applications.
Fiber optic cable materials encompass the core, cladding, coating, and buffer compounds engineered to guide light with minimal attenuation, where pure silica cores achieve transmission losses below 0.2 dB/km at 1550 nm wavelength for long-haul telecommunication. The primary commercial purpose centers on replacing copper conductors with photonic transmission media that deliver higher bandwidth across intercontinental undersea links, metro networks, and intra-data center interconnects. Doped silica formulations dominate value pools due to erbium-doped amplifier compatibility and rare-earth integration for signal regeneration. Single mode construction leads volume deployment in submarine and long-distance terrestrial routes, while multimode fiber retains margin strength in short-reach data center networking where VCSEL economics govern transceiver selection.
FCC broadband deployment mandates in the United States accelerate fiber-to-the-premises material consumption, while EU Green Deal circularity requirements under REACH and RoHS constrain halogenated coating chemistries and drive bio-based buffer development. China's MIIT issues GB standards for bend-insensitive fiber that reshape domestic product specifications and import eligibility. Japan's METI promotes photonics fusion initiatives that expand fiber deployment beyond telecom into automotive lidar and medical imaging. Stakeholders must monitor evolving national broadband subsidy programs and carbon-border adjustment mechanisms that will reshape material sourcing geography and qualification timelines.
Market Dynamics
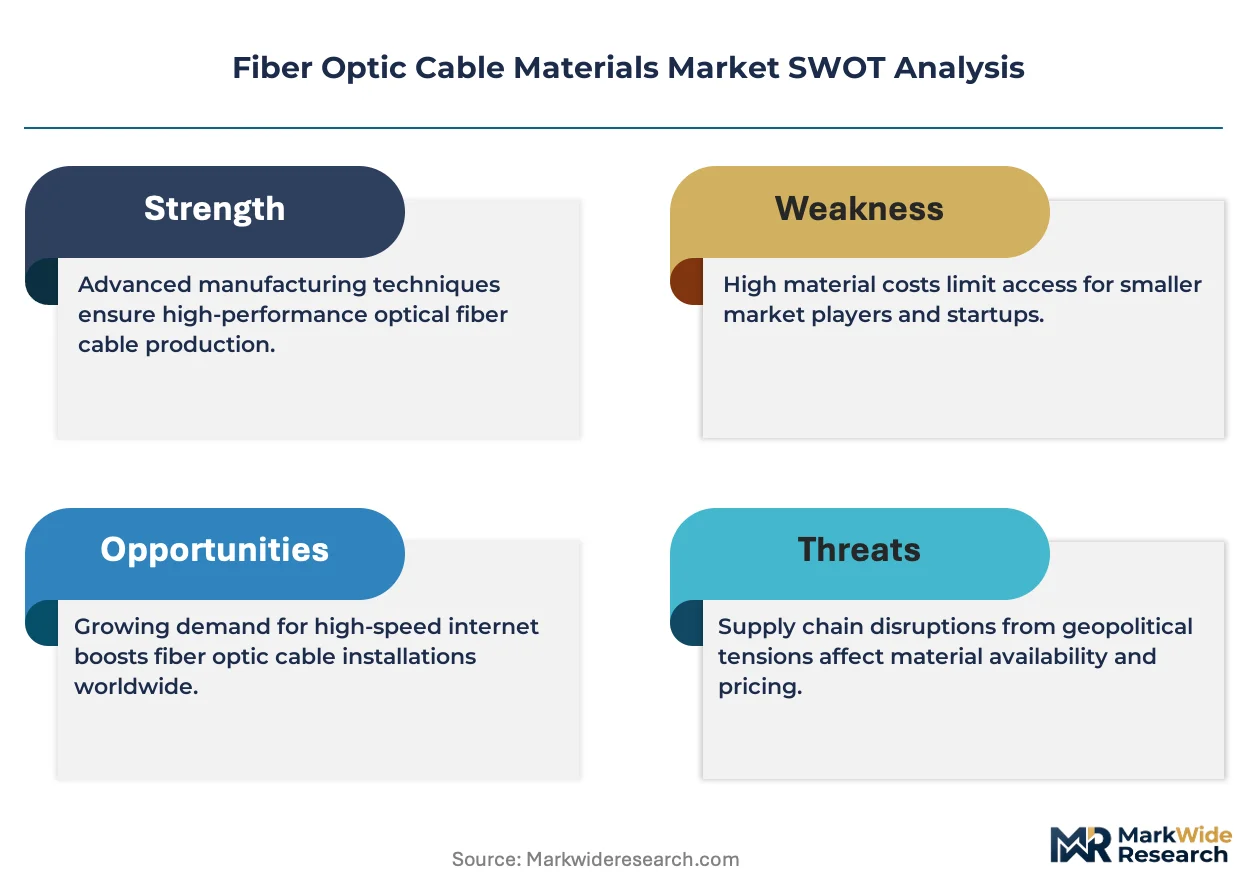
Hyperscale data center operators are consolidating procurement volumes while demanding bend-insensitive, low-attenuation fiber grades, compressing supplier margins and forcing material specialization across the value chain.
Growth Catalysts
- FCC Broadband Deployment Mandates:The United States regulator's funding programs accelerate fiber-to-the-premises construction, pulling preform and coating material demand through domestic cable manufacturers.
- Data Center Interconnect Scaling:Hyperscale cloud providers deploy multimode fiber for intra-facility links, driving volume consumption of graded-index core formulations optimized for VCSEL transmission economics.
- China's Dual Carbon Goals:MIIT's GB standards for energy-efficient manufacturing push domestic producers toward low-loss silica processes that reduce signal regeneration requirements across long-haul routes.
Market Restraints
- High-Purity Silica Feedstock Concentration:Synthetic silica precursor supply clusters in East Asian chemical processing hubs, exposing cable manufacturers to input cost volatility and geographic concentration risk.
- EU REACH Chemical Restrictions:The European regulation's evolving substance restrictions constrain halogenated buffer compound formulations, forcing reformulation investments without immediate cost recovery mechanisms.
- Copper Cable Residual Cost Advantage:Short-reach enterprise networking retains copper Cat 8 deployment for 25 Gbps links, limiting fiber penetration in price-sensitive building infrastructure segments.
Strategic Opportunities
- Automotive Lidar Integration:Japan's METI photonics fusion initiative expands polarization-maintaining fiber deployment into automotive sensing, creating new demand pools beyond traditional telecom applications.
- Submarine Cable Renewal Cycles:Transoceanic route upgrades toward 400 Gbps+ coherent transmission create replacement demand for ultra-low-loss single-mode fiber with enhanced cladding designs.
- India's BharatNet Expansion:The national rural broadband program generates volume demand for cost-optimized fiber grades, opening white space for manufacturers with scaled coating and buffer production capabilities.
Industry Challenges
- Specialized Preform Engineering Talent:Modified chemical vapor deposition and outside vapor deposition process expertise concentrates among veteran technicians, constraining capacity expansion timelines for new entrants.
- Multi-Jurisdiction Certification Complexity:Simultaneous compliance with FCC broadband standards, EU REACH substance restrictions, and China's GB bend-insensitivity specifications extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Cable Materials Market |
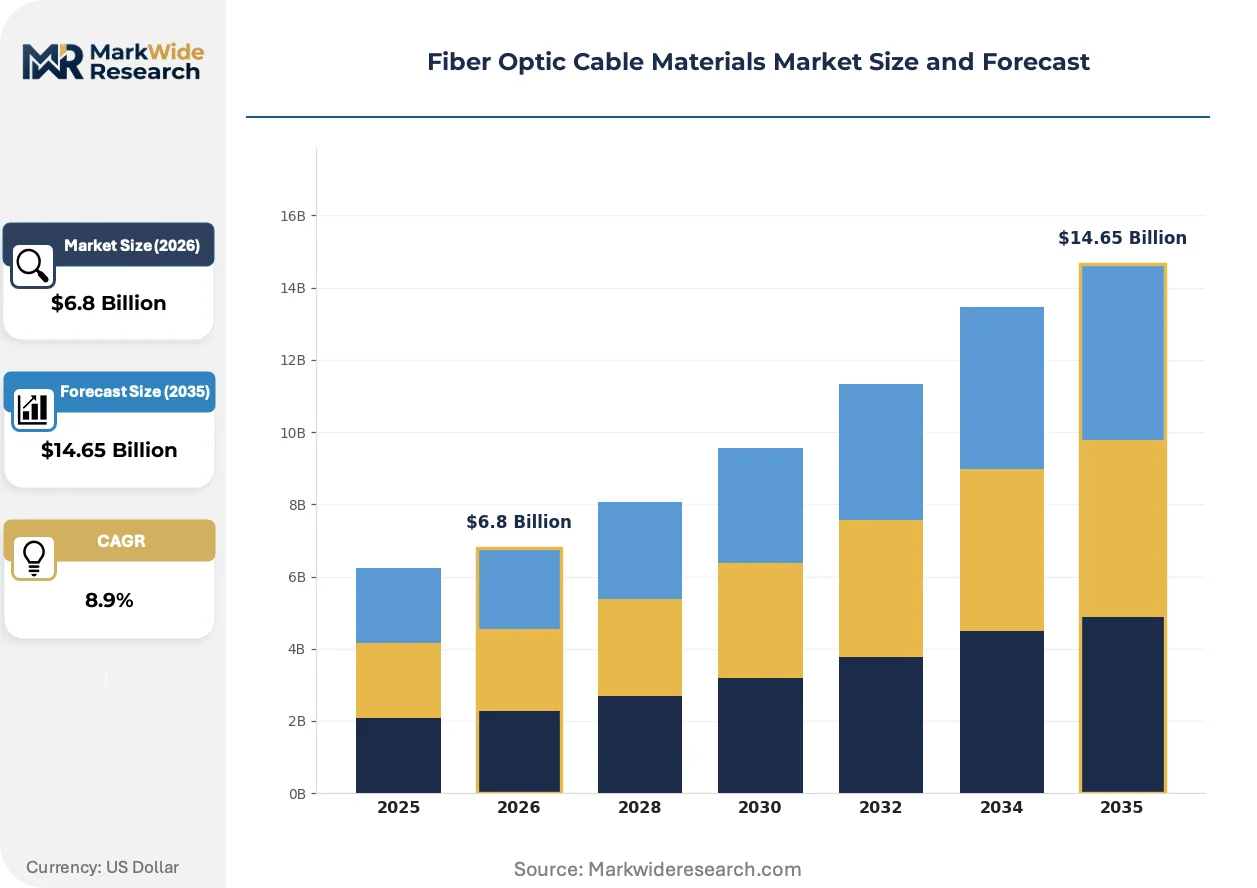
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.65 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Pure Silica, Doped Silica, Plastic Optical Fiber, Low-Loss Glass, Fluoride Glass Fiber Construction: Single Mode, Multimode, Polarization Maintaining, Graded Index, Step Index Application: Telecommunication, Data Center Networking, Military Communications, Aerospace, Undersea Transmission End User: Network Providers, Defense Agencies, Data Center Operators, Aircraft Manufacturers, Subsea Operators |
| Companies Covered | Corning Incorporated, Prysmian Group, Fujikura Ltd, Sumitomo Electric Industries, Furukawa Electric Co Ltd, Yangtze Optical Fibre and Cable, Sterlite Technologies Ltd, Nexans, Hengtong Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Cable Materials Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are simultaneously pushing fiber optic cable formulations toward higher purity and sustainable buffer alternatives, reshaping supplier R&D priorities.
Hollow-core fiber is rewriting transmission physics by guiding light through air rather than glass, achieving attenuation below 0.2 dB/km with reduced nonlinear effects. Hyperscale operators are piloting this technology for data center interconnects exceeding 10 kilometers. The structural consequence is compressing demand for conventional doped silica in latency-sensitive applications.
REACH and RoHS amendments are prohibiting halogenated flame retardants in cable jacketing compounds, forcing European manufacturers toward bio-based polyamide buffer materials. Industrial consequence includes reformulation costs and supply chain requalification. Submarine cable producers serving EU-flagged vessels face the most acute compliance pressure, accelerating partnerships with bio-polymer specialists.
Consolidated procurement by hyperscale operators is fragmenting the supplier base into tiered qualification pools, where direct relationships with cloud architects displace traditional distribution channels. Equipment manufacturers and integrators are losing intermediary margin capture. This pattern is most visible in Ashburn, Virginia and Frankfurt data center clusters where direct material sourcing now dominates.
Fiber Optic Cable Materials Market Segmentation
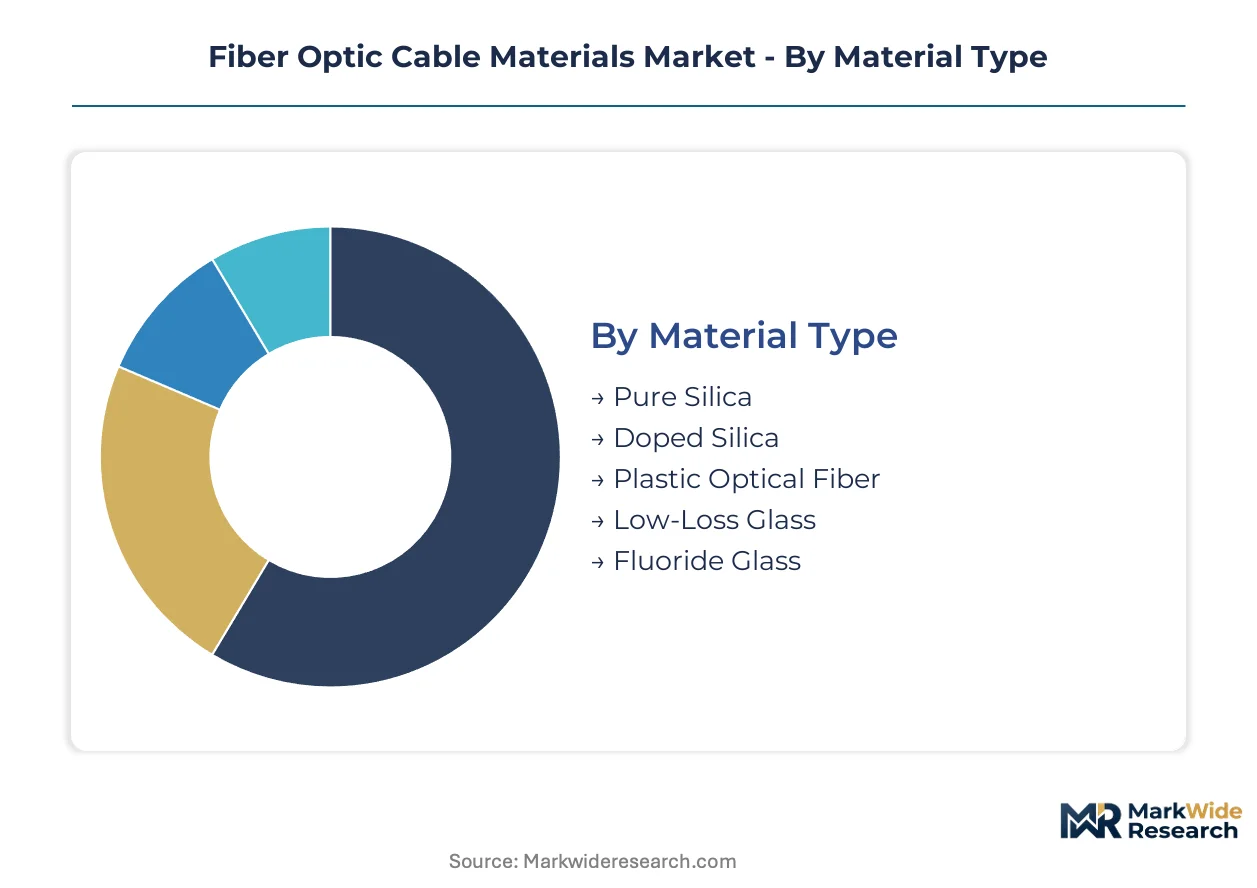
Material selection dictates transmission performance, thermal tolerance, and cost structure across fiber optic cable manufacturing. Construction geometry determines modal dispersion characteristics and deployment economics. Application-specific requirements reshape formulation priorities and certification pathways.
Material Type:
Purity levels and dopant chemistry define attenuation coefficients, splice loss budgets, and amplifier compatibility across transmission architectures.
- Doped Silica:Erbium and germanium dopants enable optical amplification and refractive index engineering for single-mode cores. Demand concentrates in transoceanic submarine cables where signal regeneration spacing drives total system economics.
- Pure Silica:Ultra-high-purity synthetic quartz achieves sub-0.2 dB/km attenuation at 1550 nm through elimination of hydroxyl impurities. Deployment clusters in China and Japan for long-haul terrestrial routes under MIIT and METI efficiency mandates.
- Plastic Optical Fiber:Polymethyl methacrylate cores tolerate tight bend radii for automotive infotainment and consumer electronics. Limited to short-reach applications due to higher intrinsic loss.
- Low-Loss Glass:Specialized borosilicate formulations bridge performance gaps between silica and polymer alternatives. Niche deployment in medical imaging and industrial sensing.
- Fluoride Glass:Heavy metal fluoride compositions enable mid-infrared transmission for spectroscopic and defense applications. Manufacturing complexity constrains volume scaling.
Mature deployment sits with doped silica. Newer deployment is concentrated in pure silica formulations serving China's dual carbon infrastructure goals.
Fiber Construction:
Waveguide geometry determines modal count, dispersion properties, and transceiver pairing economics across distance requirements.
- Single Mode:8-10 micron cores eliminate modal dispersion for coherent transmission beyond 100 kilometers. Dominates submarine and intercity routes where Fujikura and Corning anchor supply.
- Multimode:50-62.5 micron cores support VCSEL-based transceivers at lower cost per gigabit for distances under 2 kilometers. Graded-index profiles optimize bandwidth for hyperscale data center interconnects in Ashburn and Frankfurt clusters.
- Polarization Maintaining:Stress-applying elements preserve polarization state for interferometric sensing and coherent detection. METI photonics fusion initiatives accelerate automotive lidar adoption in Japan.
- Graded Index:Parabolic refractive index profiles minimize intermodal dispersion for 10 Gbps+ short-reach links. Standardized in IEEE 802.3 for enterprise networking.
- Step Index:Uniform core-cladding interface simplifies manufacturing for plastic optical fiber and specialty sensing applications. Higher modal dispersion limits data rates.
Volume concentration follows multimode for data center economics. Performance leadership sits with single mode for distance-insensitive routes.
Application:
End-use environments impose mechanical, environmental, and regulatory constraints that reshape coating and buffer specifications.
- Data Center Networking:High-fiber-count ribbon cables with bend-insensitive coatings accommodate dense patching fields. Hyperscale operators in Northern Virginia and Frankfurt drive standardization of OM4 and OM5 multimode grades.
- Telecommunication:Outside plant cables require UV-resistant polyethylene jackets and moisture-blocking gel compounds. FCC broadband deployment mandates accelerate fiber-to-the-premises consumption across United States municipal networks.
- Undersea Transmission:Armored cables with copper power conductors and hermetic sealing withstand hydrostatic pressure at 6,000 meter depths. Prysmian and NEC dominate transoceanic route upgrades.
- Military Communications:Tactical cables prioritize crush resistance and rapid deployment mechanics over attenuation minimization. Defense procurement specifications constrain supplier qualification.
- Aerospace:Avionics harnesses demand flame-retardant, low-smoke jacketing per FAA and EASA airworthiness directives. Weight minimization drives fiber replacement of copper in fly-by-light architectures.
Revenue scale favors telecommunication infrastructure. Expansion velocity is steepest in data center networking where cloud capex cycles concentrate procurement.
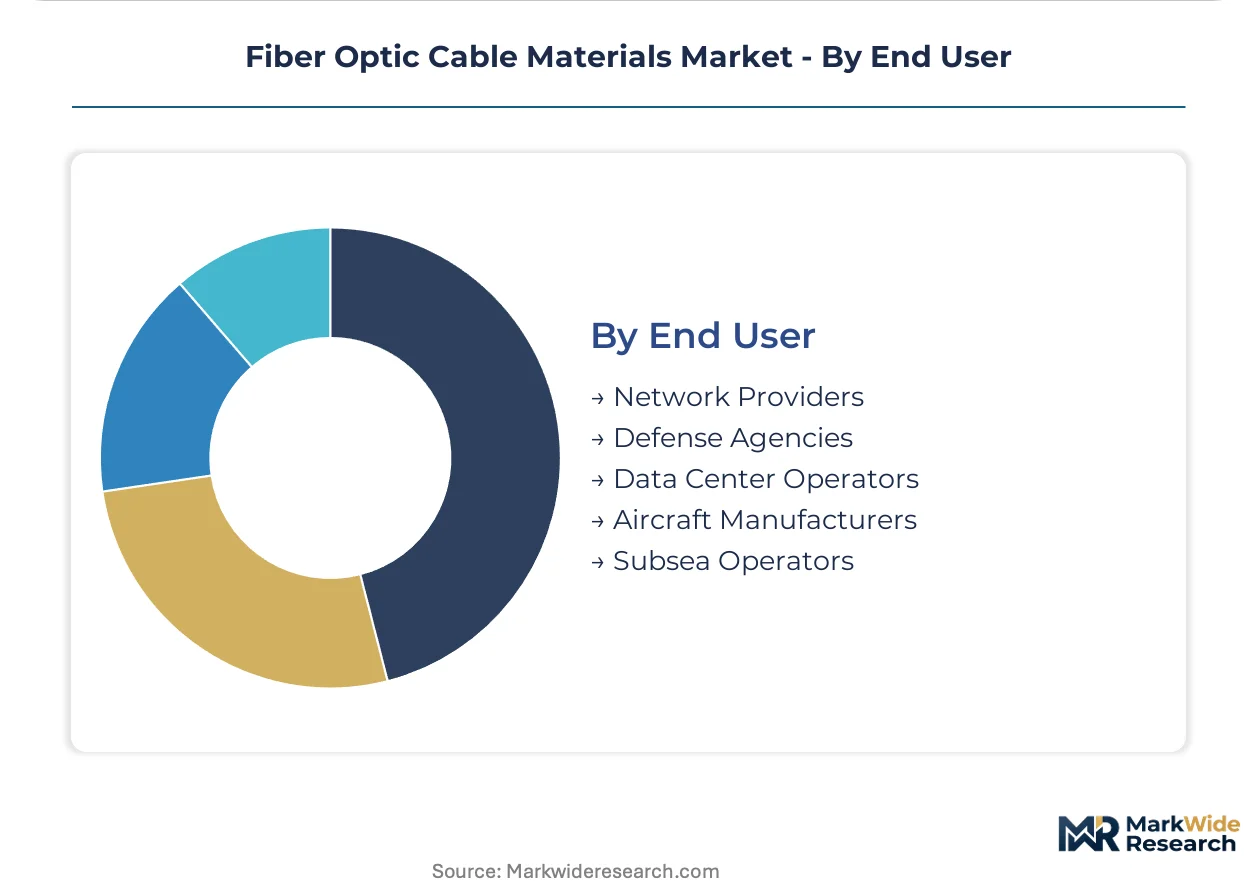
End User:
Procurement authority and technical specification ownership determine supplier engagement models and contract structures.
- Network Providers:Tier-1 telecoms and cable operators issue multi-year supply agreements with performance guarantees. Verizon and AT&T qualification programs span 18-24 months for new fiber grades.
- Data Center Operators:Hyperscale cloud architects specify cable assemblies directly, bypassing traditional distribution. Direct procurement compresses margin capture for intermediary integrators.
- Defense Agencies:Military procurement through defense logistics agencies imposes ITAR and country-of-origin restrictions. Sole-source justification requirements extend contract awards.
- Subsea Operators:Consortium structures for transoceanic cables distribute capex across multiple carriers. Google, Meta, and Microsoft participate directly in cable ownership.
- Aircraft Manufacturers:Boeing and Airbus specify fiber harnesses through tier-1 avionics suppliers. Certification reciprocity between FAA and EASA streamlines platform integration.
Procurement consolidation is most advanced among data center operators. Fragmentation persists in defense and aerospace segments where qualification barriers sustain specialized suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center procurement concentrates in Northern Virginia and Frankfurt, while submarine cable manufacturing clusters in Japan and Italy. China's domestic standards reshape import eligibility for silica preform suppliers. East Asian chemical processing hubs control synthetic feedstock supply.
United States
FCC broadband deployment mandates accelerate fiber-to-the-premises construction across municipal networks. The Infrastructure Investment and Jobs Act channels funding through state broadband offices. Northern Virginia's Ashburn data center cluster drives multimode fiber standardization for cloud interconnects.
China
MIIT's GB standards for bend-insensitive fiber reshape domestic product specifications and import eligibility. Dual carbon goals push manufacturers toward low-loss silica processes that reduce signal regeneration requirements. Yangtze River Delta manufacturing bases anchor domestic preform and cable production capacity.
Japan
METI photonics fusion initiatives expand fiber deployment into automotive lidar and medical imaging beyond traditional telecom. JIS standards govern polarization-maintaining fiber specifications for sensing applications. Chubu region hosts specialized coating compound development for high-reliability applications.
Germany
EU Green Deal circularity requirements under REACH and RoHS constrain halogenated coating chemistries and drive bio-based buffer development. ECHA substance restrictions force reformulation investments across cable jacketing compounds. Frankfurt's data center cluster concentrates hyperscale procurement volumes for European cloud infrastructure.
India
BharatNet rural broadband expansion generates volume demand for cost-optimized fiber grades. TRAI regulations shape domestic manufacturing incentives and import substitution policies. Gujarat and Maharashtra host emerging coating and buffer production facilities serving national network buildouts.
Fiber Optic Cable Materials Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty fiber niches including polarization-maintaining and hollow-core constructions. The supplier base organizes around three archetypes: integrated preform-to-cable manufacturers, specialized coating compound formulators, and regional cable assemblers. Consolidation pressures intensify as hyperscale operators consolidate procurement volumes and compress intermediary margins. Dominant competitive moves include backward integration into synthetic silica feedstock and strategic partnerships with bio-polymer specialists for REACH-compliant buffer materials.
Within the integrated manufacturing tier, Corning Incorporated and Prysmian Group exemplify scale-driven positions spanning preform engineering through cable assembly. Fujikura Ltd occupies a specialization anchor in polarization-maintaining fiber for sensing and defense applications. Yangtze Optical Fibre and Cable represents the domestic Chinese archetype, positioned within MIIT regulatory frameworks and dual carbon compliance requirements. These three entities collectively illustrate the geographic and capability segmentation shaping supplier qualification pools.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Fujikura Ltd |
| Sumitomo Electric Industries |
| Furukawa Electric Co Ltd |
| Yangtze Optical Fibre and Cable |
| Sterlite Technologies Ltd |
| Nexans |
| Hengtong Group |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap coating compound specialists in Japan and Germany anchor supply discipline through generational technical stewardship, while their concentrated ownership structures resist price-driven volume expansion that would erode formulation quality. This ownership pattern sustains premium pricing for specialized buffer materials even as hyperscale buyers consolidate procurement leverage.
Pricing Analysis
Volume concentrates in standard-grade multimode fiber for data center interconnects, while margins concentrate in polarization-maintaining and hollow-core specialty grades where Fujikura and emerging entrants command technical premiums. Price differentiation rests on certification tier—FCC broadband qualification for US telecom deployments versus MIIT GB standards for Chinese infrastructure—and volume scale, with hyperscale direct procurement compressing intermediary margins. Cost compression in standard single-mode grades is intensifying because Chinese domestic manufacturers are expanding low-loss silica capacity under dual carbon mandates. Data center operators exhibit lowest price sensitivity due to transceiver economics dominance, while BharatNet-style rural broadband programs in India show highest sensitivity to per-meter cable costs.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators and defense procurement agencies mandate qualification of at least two preform suppliers, fragmenting volume concentration despite geographic clustering. Synthetic silica feedstock concentrates in China, Japan, and South Korea, where chemical processing infrastructure draws from chlorosilane precursors and rare-earth dopant supply chains. Supply chain risk centers on single-source vulnerability for ultra-high-purity synthetic quartz used in submarine cable cores, with limited qualified suppliers outside East Asia. Distribution runs through direct procurement relationships with cloud architects for data center materials, while telecom infrastructure flows through cable manufacturers and systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized preform engineering talent scarcity props pricing power for incumbent manufacturers, as modified chemical vapor deposition expertise concentrates among veteran technicians with limited transferability. This bottleneck constrains capacity expansion timelines and sustains margin capture across the value chain.
For Market Incumbents: Deepen backward integration into synthetic silica feedstock to secure input cost stability against Yangtze River Delta supply volatility, while expanding captive coating compound production to capture REACH-driven bio-based buffer premiums. Hollow-core fiber pilots by hyperscale operators threaten conventional doped silica demand; defend through polarization-maintaining fiber specialization for automotive lidar and defense sensing applications where technical barriers sustain pricing. For New Entrants and Emerging Players: Launch via direct qualification with India's BharatNet program and state broadband offices under the US Infrastructure Investment and Jobs Act, where cost-optimized fiber grades face less stringent incumbent lock-in. Target submarine cable renewal cycles for 400 Gbps+ coherent transmission as the most penetrable segment, where ultra-low-loss single-mode demand outstrips qualified supplier capacity. Pursue partnerships with bio-polymer specialists to meet EU Green Deal circularity requirements without legacy reformulation burdens. For Investors and Strategic Acquirers: Hollow-core fiber achieving sub-0.2 dB/km attenuation in hyperscale pilot deployments is the leading indicator that latency-sensitive applications will fragment demand away from conventional silica formulations. Long-term viability favors suppliers with hollow-core manufacturing capability or polarization-maintaining specialization beyond commodity telecom. Acquisition targets should display modified chemical vapor deposition process expertise and established qualification with FCC, MIIT, or METI standards. Watch for GB standard updates from China's MIIT that restrict import eligibility as the signal for domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Silica Feedstock | Secures input supply against Yangtze River Delta concentration and price volatility. |
| Bio-Based Buffer Material Partnership | Addresses EU REACH and RoHS amendments prohibiting halogenated flame retardants in cable jacketing. |
| Polarization-Maintaining Fiber Capacity Expansion | Captures METI photonics fusion demand for automotive lidar and medical imaging beyond telecom. |
| Direct Hyperscale Procurement Qualification | Bypasses intermediary integrators in Ashburn and Frankfurt data center clusters to retain margin. |
| Hollow-Core Fiber Pilot Scaling | Positions for latency-sensitive data center interconnects exceeding 10 kilometers where air-guiding transmission reduces nonlinear effects. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with preform engineering directors, hyperscale data center procurement architects, coating compound R&D leads, and submarine cable project managers. FCC broadband deployment databases, MIIT GB standard documentation, METI photonics fusion program disclosures, and EU ECHA substance restriction registers provided secondary validation. Bottom-up fiber consumption estimates by application and geography triangulated against top-down cable manufacturer capacity assessments.
Granularity-level modeling disaggregated volume and value across material type, fiber construction, application, and end user dimensions, with additional segmentation by regulatory qualification tier. CAGRs derived through regression analysis of historical consumption patterns against broadband deployment schedules, data center capex cycles, and submarine cable renewal timelines. Forecast inputs incorporated hyperscale direct procurement share trajectories, REACH reformulation cost pass-through assumptions, and hollow-core fiber pilot-to-production scaling curves.
The model assumes a particular technology adoption path; alternative pathways for hollow-core fiber achieving commercial scale would alter the outlook for conventional doped silica demand. Forecasts reflect assumptions regarding MIIT dual carbon enforcement intensity, FCC broadband funding continuity, and EU Green Deal circularity timeline adherence. Deviation in hyperscale operator procurement consolidation velocity or submarine cable consortium structure would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Carrier Market
Cables
Mexico Wires and Cables Market
Cables
USB Cable Market
Cables
Asia-Pacific Premise Cable Market
Cables
Cable Flange Market
Cables
Japan Cables Market
Cables
Europe Wire and Cable Market
Cables
Premise Cable Market
Cables
Middle East Cable Market
Cables
Cable Trunking Market
Cables
Sensing Cable Market
Cables
HVDC Cables Market
Cables
Power Cable Accessories Market
Cables
Submarine Cable System Market
Cables
North America Coaxial Cable Market
Cables
Solar Cable Market