
 Power Cable Accessories Market | 2026-2036
Power Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Power Cable Accessories Market Outlook
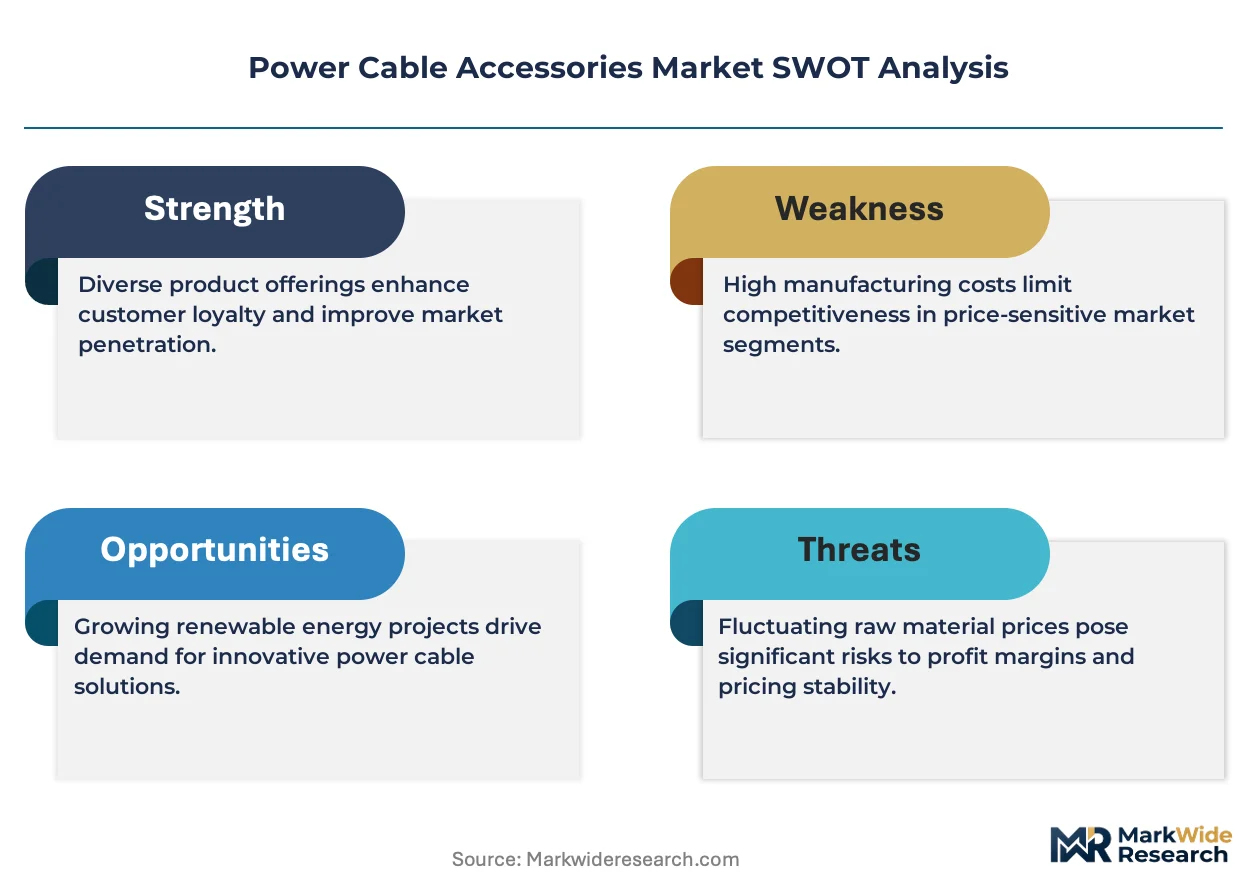
Single-source procurement for high-voltage terminations is shifting toward multi-source qualification programs as grid operators diversify supplier risk. Prysmian Group leverages backward integration into compound manufacturing to secure silicone and EPDM feedstock quality. Nexans anchors European submarine cable projects through its specialized jointing technology. TE Connectivity differentiates via sensor-embedded accessories that monitor partial discharge in real time.
Power cable accessories encompass joints, terminations, connectors, and sealing sleeves engineered to maintain electrical continuity, mechanical integrity, and environmental sealing across cable systems rated from low voltage through 500 kV. These components utilize cross-linked polyethylene, ethylene propylene rubber, or silicone compounds molded under controlled temperature and pressure cycles to achieve specified dielectric strength and thermal cycling performance. Joints dominate value pools in mature markets where underground network refurbishment cycles drive replacement demand, while terminations capture premium pricing in renewable energy installations exposed to harsh ambient conditions. Underground installation accessories represent the fastest-growing structural segment as urban densification mandates buried distribution corridors.
IEC 62271 and IEEE 62271 standards govern product certification across transmission utilities, with China's GB/T 12706 and India's IS 7098 creating parallel compliance pathways for regional tenders. The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants reshape material selection for European-specified sleeves and sealing systems. Stakeholders must monitor how national grid codes incorporate dynamic line rating requirements into accessory thermal performance specifications.
Market Dynamics
Cross-linked polyethylene insulation technology is displacing oil-filled cable designs across transmission networks, compressing jointing system lifecycles and forcing utilities to requalify accessory suppliers against revised thermal performance benchmarks.
Growth Catalysts
- China's ultra-high voltage grid buildout:State Grid Corporation of China mandates 800 kV and 1000 kV transmission corridors requiring specialized composite terminations and GIS bushings rated for extreme electrical stress.
- India's rural electrification programs:Saubhagya scheme and subsequent distribution strengthening initiatives drive volume demand for medium-voltage joints and heat-shrink sleeves in underground rural networks.
- EU F-Gas Regulation phase-down:Restrictions on sulfur hexafluoride in switchgear assemblies accelerate adoption of dry-type terminations and solid-insulation joints across European transmission utilities.
Market Restraints
- Silicone compound supply concentration:Specialty silicone elastomer production clusters in Germany and Japan, creating feedstock vulnerability for European and Asian accessory manufacturers.
- Copper and aluminum price volatility:Connector hardware represents 25-35% of accessory bill-of-materials, exposing margins to London Metal Exchange commodity swings.
- Extended type-test timelines:IEC 60840 and IEC 62067 qualification cycles exceed 18 months for 220 kV+ accessories, freezing supplier rotation and entrenching incumbent positions.
Strategic Opportunities
- Offshore wind inter-array cabling:Floating platform export cables require dynamic bend-resistant joints and marine-grade terminations with 40-year salt-water immersion ratings.
- India's smart city undergrounding mandates:Urban densification policies in Mumbai, Delhi, and Bangalore mandate buried 33 kV distribution, opening retrofit markets for cold-shrink and pre-molded jointing systems.
- Sensor-embedded condition monitoring:Integration of partial discharge sensors and fiber-optic temperature sensing into termination bodies enables predictive maintenance contracts.
Industry Challenges
- High-voltage jointing technician scarcity:Skilled craftspeople capable of executing 132 kV+ extruded cable joints number fewer than 2,000 globally, constraining installation throughput.
- Legacy oil-filled cable compatibility:Transition interfaces between paper-insulated and XLPE systems require bespoke transition joints with complex manufacturing tolerances.
- Multi-standard certification burden:Suppliers must simultaneously maintain IEC, IEEE, GB/T, and IS compliance for global tender participation, duplicating test expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Cable Accessories Market |
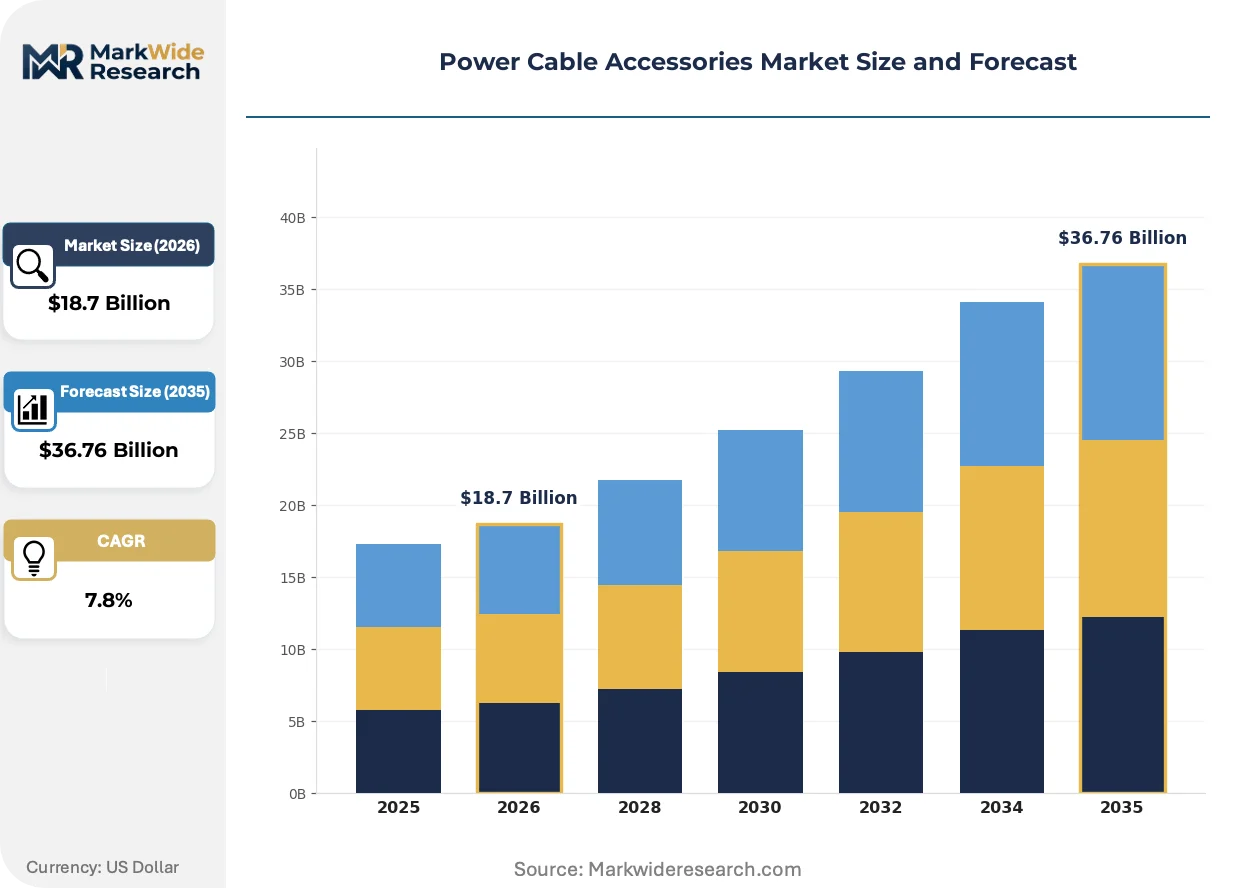
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminations, Joints, Connectors, Sleeves Installation Type: Indoor, Outdoor, Underground, Overhead End User: Utilities, Telecommunications, Manufacturing, Construction Application Area: Power Distribution, Renewable Energy, Industrial, Infrastructure |
| Companies Covered | ABB, LS Cable & System, Prysmian Group, Elsewedy Electric, Furukawa Electric, Nexans, NKT A/S, TE Connectivity, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Cable Accessories Market Strategic Shifts
Digitalization of grid infrastructure is rewriting accessory specifications, embedding intelligence into passive components and compressing the boundary between electrical hardware and monitoring systems.
Factory-pre-molded EPDM and silicone rubber joints with integrated stress-cone geometry are decentralizing field installation quality control. European utilities including TenneT and National Grid specify these units for 66 kV and 132 kV urban retrofit projects, eliminating dependence on ambient conditions during curing cycles. The technology is decentralizing the role of specialized jointing contractors toward general electrical installation crews.
REACH restrictions on halogenated flame retardants are forcing material reformulation across sealing sleeves and fire-stop systems. Compound manufacturers must substitute brominated additives with phosphorus-nitrogen intumescent systems, raising raw material costs and retooling extrusion lines. German TSOs and French distribution operators are absorbing these premiums to maintain CE marking compliance and avoid supply discontinuity.
Multi-source qualification programs are displacing single-source procurement for critical terminations. Grid operators in Italy, Spain, and the United Kingdom now mandate dual-approved suppliers for 220 kV+ projects, fragmenting volume concentration and compressing contract durations. This pattern is most visible in offshore wind connections where project finance covenants require supplier redundancy clauses.
Power Cable Accessories Market Segmentation
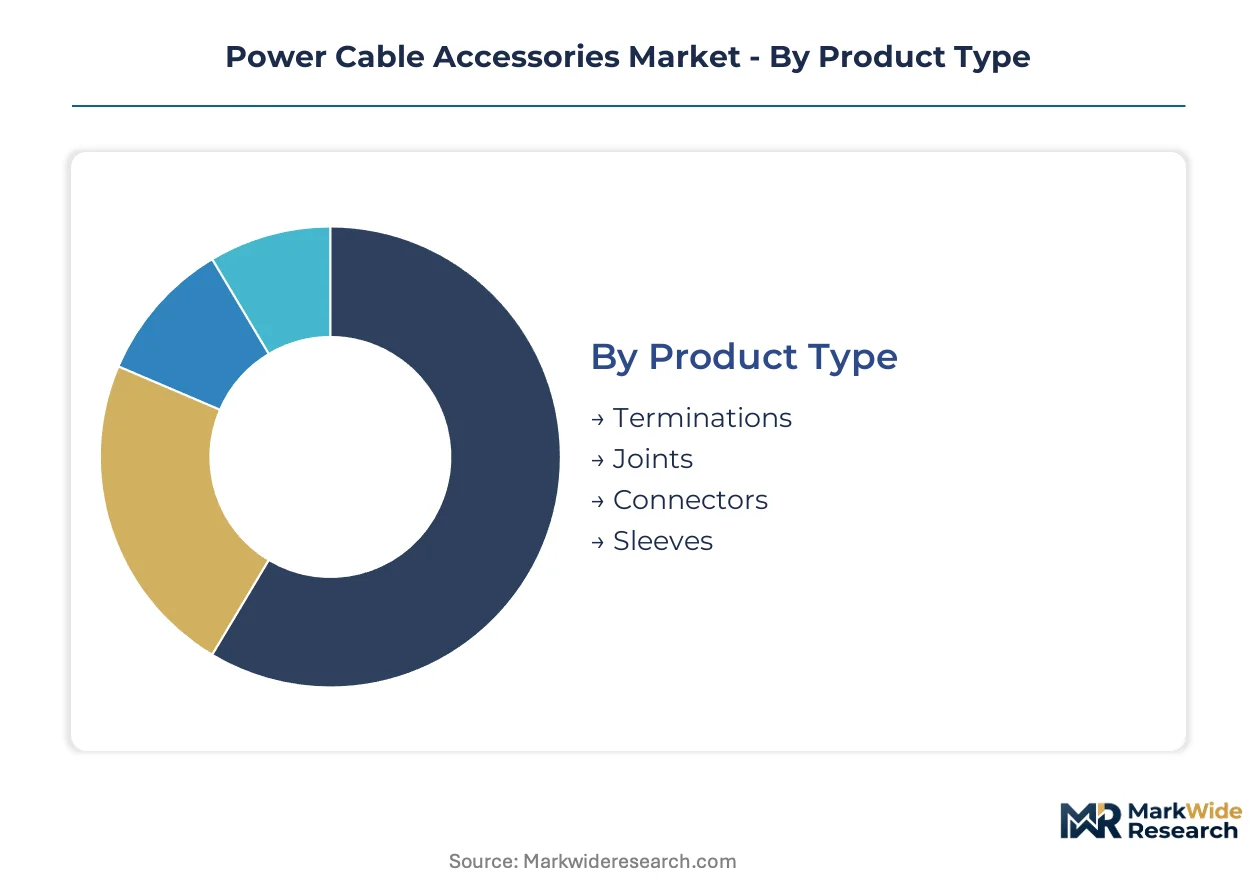
Power cable accessories serve radically different technical requirements across voltage classes and environmental exposures. Segmentation reveals which product configurations command premium positioning versus volume commoditization.
Product Type:
Standalone accessories dominate procurement for retrofit and repair scenarios, while embedded systems integrate factory-molded components into new cable manufacturing.
- Terminations:Composite or porcelain housings with stress-cone geometry manage electrical field distribution at cable endpoints. GIS bushings for 800 kV corridors in China absorb disproportionate engineering resources as State Grid Corporation pushes voltage ceilings.
- Joints:Factory-pre-molded EPDM and silicone units with integrated stress control replace field-cured tape systems. European utilities including TenneT specify these for 132 kV urban networks where installation windows are compressed.
- Connectors:Crimped or bolted metallic interfaces maintain electrical continuity across cable sections. Copper price volatility on the London Metal Exchange squeezes margins on these hardware-intensive components.
- Sleeves:Heat-shrink, cold-shrink, or wraparound sealing systems protect joints from moisture and mechanical damage. REACH restrictions on halogenated flame retardants force phosphorus-nitrogen formulations across European-specified units.
Volume placements concentrate in Joints; the faster expansion belongs to Terminations.
Installation Type:
Cost tiers separate standardized indoor fittings from engineered outdoor and subterranean systems requiring environmental hardening.
- Underground:Direct-buried or duct-bank accessories must withstand soil chemistry, groundwater, and thermal cycling. India's smart city mandates in Mumbai and Delhi mandate buried 33 kV distribution, opening retrofit markets for cold-shrink systems.
- Outdoor:Pollution-resistant terminations with silicone rubber housings serve exposed substation and overhead line transitions. Offshore wind platforms require marine-grade variants with 40-year salt-water immersion ratings.
- Indoor:Controlled-environment accessories face simpler thermal and dielectric specifications. Switchgear terminations in data center substations prioritize compact footprint over extreme weatherproofing.
- Overhead:Aerial bundled cable accessories integrate with messenger wire systems for rural distribution. India's Saubhagya rural electrification drives volume demand for medium-voltage overhead joints.
Cost premiums attach to Underground; Indoor commands the shallowest pricing.
End User:
Customer type determines specification stringency, with transmission utilities imposing multi-year qualification cycles that freeze out casual suppliers.
- Utilities:Grid operators mandate IEC 62271 or IEEE 62271 certification with type-test documentation exceeding 18 months for 220 kV+ accessories. Multi-source qualification programs now require dual-approved suppliers for critical terminations.
- Manufacturing:Industrial captive power systems specify medium-voltage accessories with shorter lead times and less onerous documentation. Automotive and semiconductor fabs prioritize delivery reliability over extreme voltage ratings.
- Construction:Building services contractors procure low-voltage sleeves and connectors through distributor channels. Fire-stop systems face evolving REACH restrictions on halogenated compounds.
- Telecommunications:Fiber-optic power cable hybrids require specialized grounding and surge protection accessories. 5G small cell densification drives demand for compact underground distribution fittings.
Contract durations stretch longest with Utilities; Construction offers the shortest sales cycles.
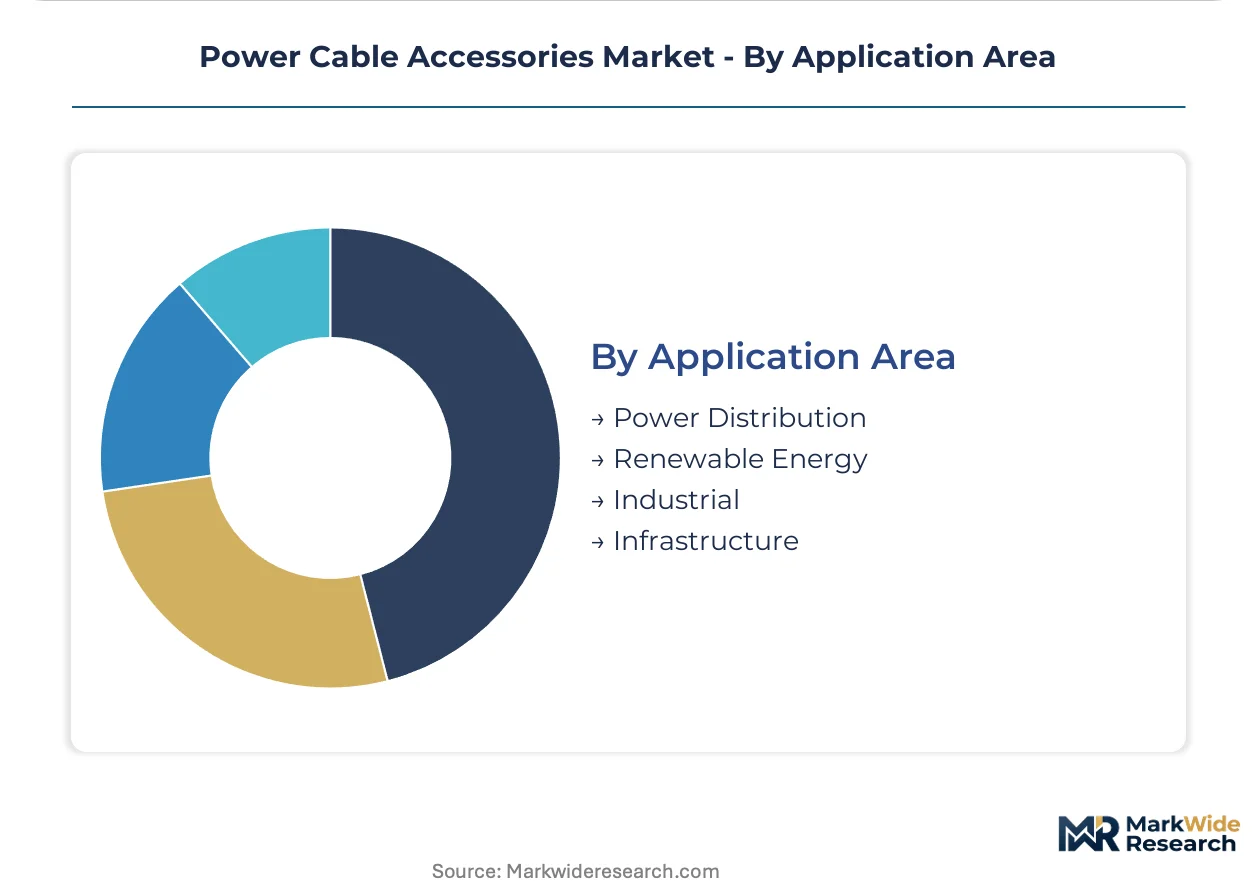
Application Area:
Maturity curves diverge sharply, with established distribution markets yielding to renewable energy's specification volatility.
- Power Distribution:Underground network refurbishment in mature European markets drives replacement demand for joints and terminations. Aging oil-filled cable transitions require bespoke XLPE-paper interface joints with complex manufacturing tolerances.
- Renewable Energy:Offshore wind inter-array cabling demands dynamic bend-resistant joints and floating platform export terminations. Sensor-embedded condition monitoring enables predictive maintenance contracts for remote assets.
- Industrial:Petrochemical and mining operations specify flame-retardant, oil-resistant accessories for hazardous zones. IECEx and ATEX certifications add compliance layers beyond standard utility specifications.
- Infrastructure:Rail electrification and airport power systems require vibration-resistant terminations and EMC-shielded connectors. High-speed rail corridors in China specify 27.5 kV accessories with enhanced mechanical durability.
Specification stability characterizes Power Distribution; Renewable Energy generates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty silicone elastomer production clusters in Germany and Japan anchor feedstock availability for European and Asian accessory manufacturers. These material concentrations shape regional supply security and qualification timelines across voltage classes.
China
State Grid Corporation mandates 800 kV and 1000 kV transmission corridors requiring specialized composite terminations. GB/T 12706 standards create parallel compliance pathways distinct from IEC certification. The Yangtze River Delta hosts manufacturing clusters producing GIS bushings for ultra-high voltage grid buildout.
Germany
TenneT and other transmission system operators specify factory-pre-molded EPDM joints for 132 kV urban retrofit projects. The EU F-Gas Regulation phase-down accelerates dry-type termination adoption. Bavaria-based compound manufacturers supply silicone feedstock to European accessory producers.
India
Saubhagya rural electrification drives volume demand for medium-voltage joints and heat-shrink sleeves. IS 7098 certification requirements govern regional tender participation. Mumbai and Delhi smart city mandates mandate buried 33 kV distribution, opening retrofit markets for cold-shrink systems.
United States
FERC interconnection standards influence transmission utility procurement specifications for 220 kV+ accessories. Multi-source qualification programs now require dual-approved suppliers for critical terminations. Texas and California grid operators lead underground network refurbishment cycles.
Japan
Specialty silicone production concentrates near Osaka and Nagoya, supplying premium feedstock for high-voltage applications. JIS standards create distinct certification requirements for domestic utilities. METI industrial policy supports advanced jointing technology development for export markets.
Power Cable Accessories Market Competitive Environment
Backward integration into compound manufacturing dominates the current landscape as suppliers secure silicone and EPDM feedstock quality. The market structures around three tiers: integrated material-to-accessory producers, specialized jointing technology firms, and regional hardware fabricators. Strategic archetypes include feedstock-secured volume players, marine-grade termination specialists, and sensor-embedded monitoring innovators. M&A activity and capacity expansion in high-voltage testing facilities represent the dominant competitive moves.
Among European-integrated producers, Prysmian Group and Nexans occupy positions anchoring submarine cable and specialized jointing technology respectively. TE Connectivity exemplifies the sensor-embedded monitoring archetype, representing real-time partial discharge integration. These three companies illustrate how geographic origin and structural suffixes map to distinct strategic positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| ABB |
| LS Cable & System |
| Prysmian Group |
| Elsewedy Electric |
| Furukawa Electric |
| Nexans |
| NKT A/S |
| TE Connectivity |
| Sumitomo Electric Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into compound manufacturing anchors supply security and pricing power for integrated producers controlling silicone and EPDM feedstock quality. Prysmian Group and Nexans leverage captive compound production to buffer margin erosion from London Metal Exchange commodity swings while commanding premium positioning for certified high-voltage terminations.
Pricing Analysis
Warranty and installation service bundling separates premium terminations from unbundled commodity joints in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62271 certification grade and volume scale, with 220 kV+ accessories carrying extended type-test documentation premiums. Pricing pressure stems from multi-source qualification programs fragmenting volume concentration and compressing contract durations. Construction contractors exhibit highest price sensitivity through distributor channels, while transmission utilities prioritize qualification reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's GB/T 12706 procurement and India's IS 7098 tender requirements reshape sourcing patterns toward local manufacturing partnerships. Specialty silicone production clusters in Germany and Japan, with EPDM compounding concentrated in Bavaria and the US Gulf Coast, create geographic dependencies for European and Asian accessory producers. Raw material exposure centers on copper and aluminum connector hardware, sulfur-cured rubber compounds, and halogen-free flame retardant additives. Single-source vulnerability in specialty elastomer feedstock threatens supply continuity under REACH regulatory restrictions. Distribution runs through direct utility contracts for high-voltage accessories and electrical distributor networks for low-voltage construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around qualification-intensive incumbents as extended IEC 60840 type-test timelines exceeding eighteen months freeze out undercapitalized competitors.
For Market Incumbents: To counter multi-source procurement fragmentation, deepen captive supply of silicone compounds through backward integration into German and Japanese feedstock partnerships. Expand high-voltage testing facility capacity in Asia-Pacific to capture State Grid Corporation ultra-high voltage buildout demand. Secure dual-certification pathways across IEC and IEEE standards to maintain tender eligibility as grid operators diversify supplier risk. For New Entrants and Emerging Players: Enter via sensor-embedded condition monitoring accessories where TE Connectivity has established technical feasibility but market penetration remains shallow. Target India's rural electrification volume tier for medium-voltage joints and heat-shrink sleeves where IS 7098 certification barriers are lower than transmission-grade requirements. Pursue white-label manufacturing partnerships with European distributors seeking REACH-compliant alternatives to incumbent supply. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated cable manufacturers seeking accessory capabilities. Five-to-ten year viability favors compound-to-accessory integrated producers with secured silicone feedstock and established utility qualification records. Monitor offshore wind inter-array cabling contract awards as inflection signal for marine-grade termination demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Testing Facility Expansion | State Grid Corporation 800 kV+ procurement requires certified local testing infrastructure. |
| Sensor-Embedded Accessory Development | Real-time partial discharge monitoring enables predictive maintenance contract premiums. |
| Silicone Compound Backward Integration | Captive EPDM and silicone production buffers margin exposure to German-Japanese feedstock concentration. |
| Multi-Standard Certification Investment | Dual IEC and IEEE pathways maintain tender access as European utilities diversify supplier bases. |
| Marine-Grade Termination Specialization | Forty-year salt-water immersion ratings capture offshore wind inter-array cabling growth. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility procurement officers, high-voltage jointing contractors, compound manufacturing technical directors, and grid planning engineers at transmission system operators validated demand assumptions. IEC 62271 certification databases, FERC interconnection filings, and import-export statistics for silicone elastomer feedstocks provided quantitative benchmarks. Bottom-up segmentation modeling triangulated against top-down utility capex projections across voltage classes.
Granularity-level modeling addressed product type, installation environment, end-user category, and application area with regional regulatory cluster differentiation. CAGRs derived from utility infrastructure investment cycles, renewable energy interconnection timelines, and replacement demand curves for aging oil-filled cable networks. Cross-linked polyethylene displacement rates and rural electrification program execution pace informed volume assumptions across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility spikes and REACH regulatory acceleration. Projections reflect assumptions regarding technician training pipeline expansion, multi-source qualification program adoption rates, and offshore wind project finance closure velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Testers Market
Cables
Japan Cables Market
Cables
Twisted Pair Cable Market
Cables
Global Low Voltage Cable Market
Cables
HVDC Cables Market
Cables
Mineral Insulated (MI) Cable Market
Cables
North America Coaxial Cable Market
Cables
Underground Cable Market
Cables
Shipboard Cable Market
Cables
XLPE Cables Market
Cables
Electric Submersible Cables (ESP) Market
Cables
North America Patch Cable Market
Cables
Cable Detector Market
Cables
Cable Tags Market
Cables
Class 1E Electric Cables Market
Cables
Audio and Video Cables Market