
 Cable Flange Market | 2026-2036
Cable Flange Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Flange Market Outlook
Preventive maintenance contracts and condition-monitoring subscriptions is restructuring how cable flange vendors capture lifetime value from industrial buyers. Roxtec International AB leverages its modular sealing platform to anchor long-term service agreements across marine and energy infrastructure. igus GmbH sustains differentiation through polymer flange innovations that reduce wear-based replacement cycles. Lorom Industrial Co., Ltd. competes on manufacturing scale in custom electromagnetic shielding configurations for medical device OEMs.
A cable flange is a mechanical sealing and retention component that secures electrical or fiber-optic cables through enclosure walls, typically manufactured with specified ingress protection ratings and material grades matched to environmental exposure. Stainless steel variants dominate heavy-industrial and marine installations where salt spray and chemical exposure demand corrosion resistance, while aluminum flanges gain share in weight-sensitive transportation and aerospace cable routing applications. Custom flanges command premium positioning due to engineering-intensive prototyping and low-volume production economics, whereas standard screw-on configurations represent the mature volume pool where price competition intensifies among Asian contract manufacturers.
The American Bureau of Shipping and DNV classification societies enforce marine-grade sealing standards that dictate material selection and pressure-testing protocols for offshore cable penetrations. IEC 60529 ingress protection codes and NEMA enclosure ratings shape product development roadmaps for industrial equipment suppliers seeking cross-border equipment certification. Stakeholders must monitor how evolving EU Ecodesign requirements and emerging circular-economy material mandates recast supplier qualification criteria for European infrastructure projects.
Market Dynamics
Preventive maintenance contracts and condition-monitoring subscriptions are restructuring how cable flange vendors capture lifetime value from industrial buyers. The shift from transactional component sales to recurring service revenue models is compressing replacement cycles and locking in long-term supplier relationships across marine and energy infrastructure.
Growth Catalysts
- Offshore wind procurement:Developers in Germany's northern port industrial clusters are expanding orders for corrosion-resistant cable management systems. Bremen and Hamburg anchor this demand concentration.
- EU F-Gas Regulation:Tightening material compliance requirements for sealing components are forcing specification upgrades across marine installations. IEC 60092 standards reinforce this pressure.
- Polymer flange innovation:Advanced polymer formulations are reducing wear-based replacement cycles in dynamic cable routing applications. Transportation and aerospace OEMs prioritize weight savings.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin predictability for corrosion-resistant flange manufacturers. Marine-grade material sourcing faces periodic disruption.
- Custom prototyping economics:Engineering-intensive low-volume production of specialized electromagnetic shielding configurations carries prohibitive unit costs. Medical device OEMs absorb these premiums selectively.
- Aluminum substitution ceiling:Salt spray exposure limits aluminum flange penetration in offshore environments despite weight advantages. IEC 60529 ingress protection testing validates material boundaries.
Strategic Opportunities
- Modular sealing platform expansion:Service agreement anchoring across marine infrastructure creates recurring revenue streams. Long-term contracts displace spot purchasing in port modernization projects.
- Electromagnetic shielding medical devices:Custom configurations for diagnostic imaging equipment represent underpenetrated specification territory. OEM qualification cycles favor early platform investment.
- Circular-economy material mandates:Evolving EU Ecodesign requirements recast supplier qualification criteria for European infrastructure projects. Recyclable polymer formulations gain specification preference.
Industry Challenges
- Marine certification timeline compression:American Bureau of Shipping and DNV classification pressure-testing protocols extend product validation cycles. Offshore project deadlines strain documentation throughput.
- Cross-border equipment certification complexity:Harmonizing IEC 60529 ingress protection codes with NEMA enclosure ratings demands duplicate testing investment. Multi-jurisdiction suppliers face qualification cost stacking.
- Legacy system integration friction:Retrofit flange installations in existing industrial enclosures encounter dimensional standard mismatches. Field adaptation erodes modular platform efficiency claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Flange Market |
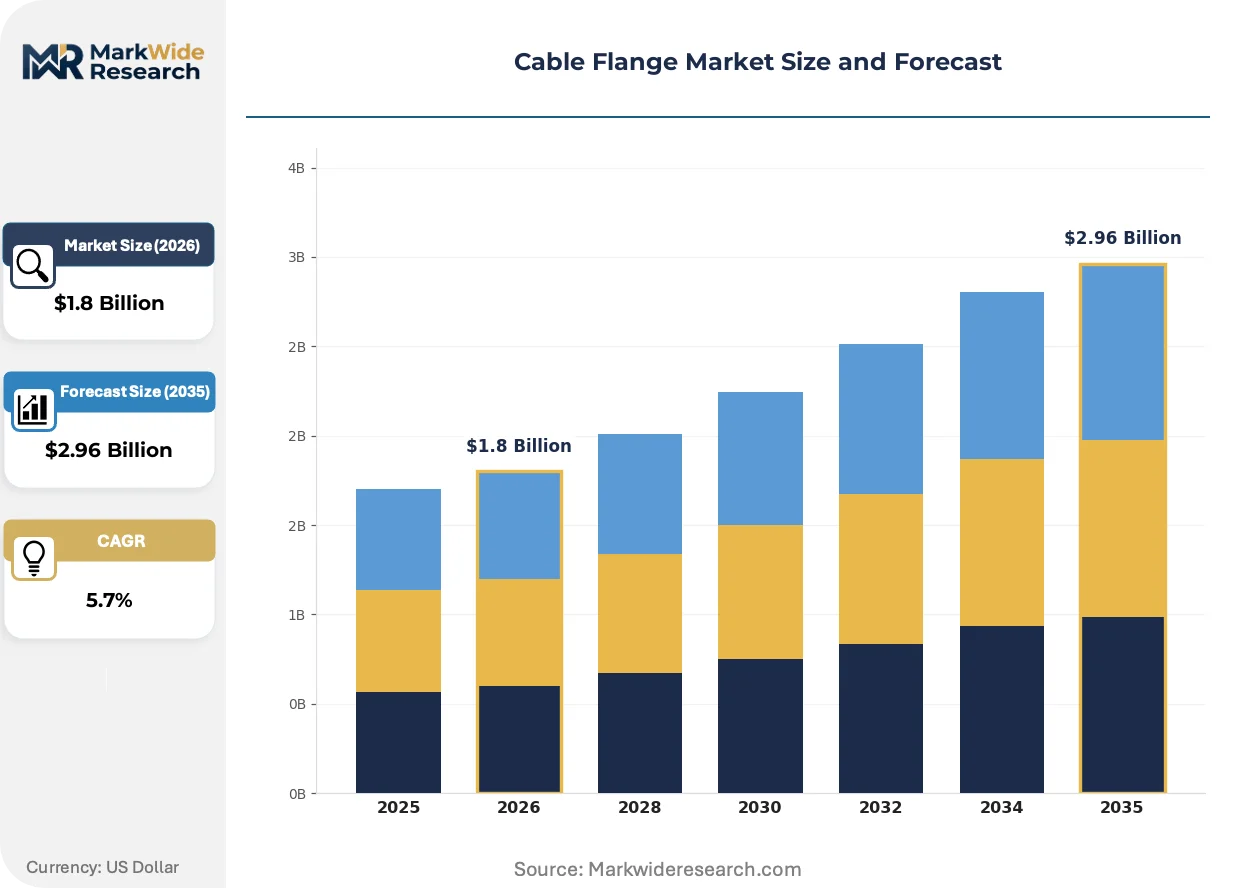
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flanges, Custom Flanges, Adapter Flanges, Blind Flanges Material: Stainless Steel, Aluminum, PVC, Copper Connection Type: Screw-On, Welded, Snap-On, Quick Release Application: Industrial Equipment, Marine Applications, Telecommunications, Transportation |
| Companies Covered | Lorom Industrial Co., Ltd., National Wire & Cable Corporation, Haynes International, Inc., Affinity Medical Technologies, LLC, Hitachi, Ltd., Sealcon, igus GmbH, Binder-USA, LP, Roxtec International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Flange Market Strategic Shifts
Smart sealing technologies and predictive maintenance integration are transforming cable flange from passive hardware into active infrastructure monitoring nodes. Material science advances and regulatory tightening are simultaneously reshaping specification requirements and supplier qualification barriers.
Polymer composite flange systems with embedded fiber-optic strain sensors are converging with industrial IoT architectures to enable real-time cable tension monitoring. Offshore wind farm operators in the North Sea are piloting these configurations for predictive maintenance scheduling. The technology is converging with SCADA platforms to compress fault detection response times from days to hours.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are eliminating legacy elastomer compounds from marine sealing applications. Compounders must reformulate halogenated material portfolios ahead of sunset dates. German and Dutch shipyards now specify fluorine-free alternatives in newbuild contracts to preempt compliance exposure.
Buyer consolidation among offshore wind developers is concentrating procurement authority with fewer engineering-procurement-construction contractors. Tier-one EPCs now mandate multi-year service bundling with component supply. Denmark and the United Kingdom exhibit the most advanced contract structures, with performance guarantees replacing conventional warranty terms.
Cable Flange Market Segmentation
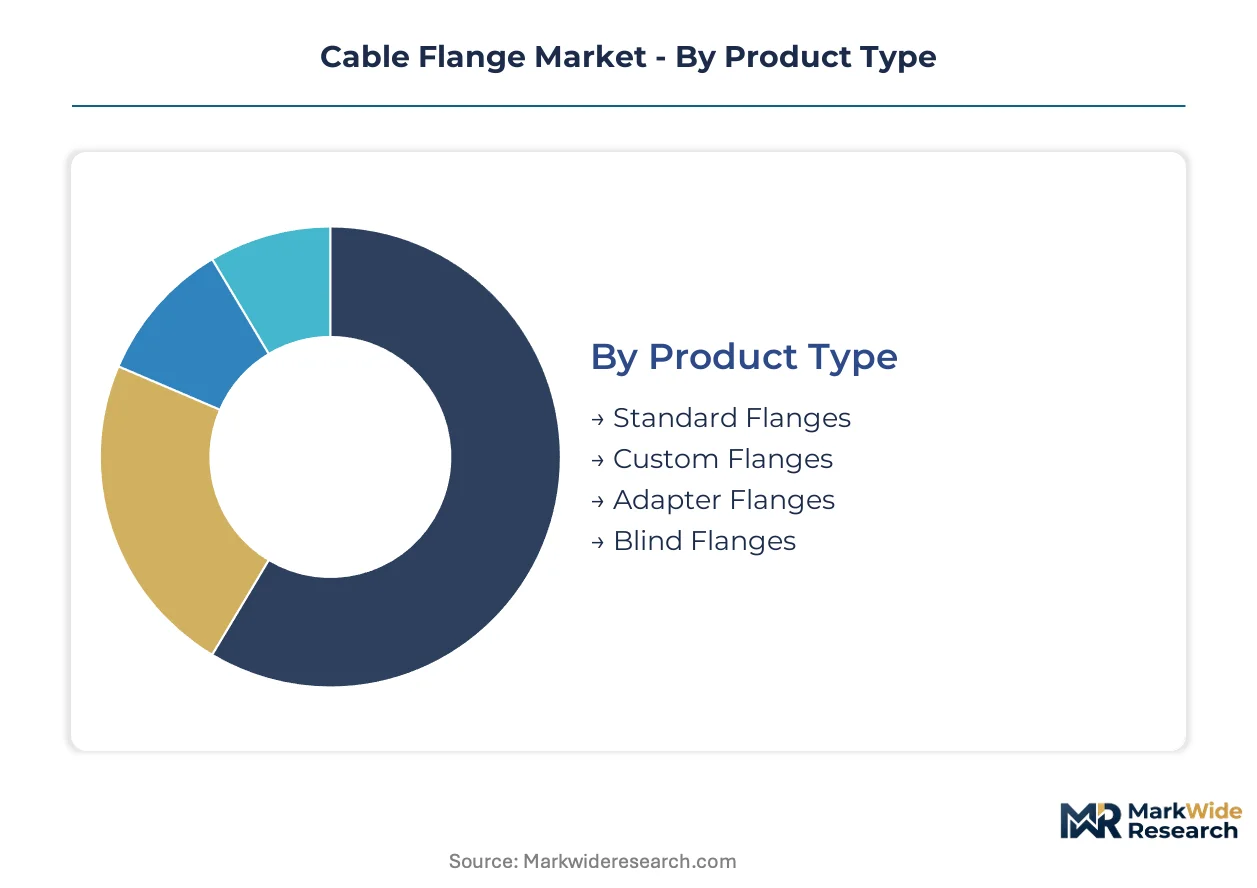
Cable flange procurement patterns diverge sharply between specification-driven marine projects and volume-driven industrial equipment retrofits. Understanding these segment boundaries clarifies where modular platforms compete against custom engineering economics.
Product Type:
Standard flanges dominate standalone installations where off-the-shelf IP ratings suffice, while custom variants embed into complex enclosure architectures demanding site-specific sealing geometries.
- Standard Flanges:Pre-engineered screw-on configurations with fixed IP65/IP67 ratings serve industrial equipment OEMs seeking procurement efficiency. German port infrastructure contractors in Bremen and Hamburg specify these for routine cable management in warehouse automation and shore power systems. IEC 60529 certification harmonization reduces cross-border qualification costs.
- Custom Flanges:Engineering-intensive prototypes accommodate non-standard penetration geometries in medical imaging equipment and defense enclosures. Low-volume production economics concentrate demand with specialized compounders capable of rapid elastomer formulation iteration. REACH substance restrictions force material requalification cycles that extend validation timelines.
- Adapter Flanges:Bridge legacy enclosure threads to modern sealing standards, enabling field retrofit without full panel replacement. Demand clusters in North Sea offshore wind repowering projects.
- Blind Flanges:Seal unused penetration points during enclosure commissioning or future expansion planning. Marine classification societies mandate pressure-testing documentation for temporary sealing applications.
Standard flanges lead volumes today; custom flanges are gaining share fastest in medical and defense specification territories.
Material:
Material selection maps directly to environmental exposure severity, with corrosion resistance premiums separating marine-grade procurement from weight-optimized transportation applications.
- Stainless Steel:Austenitic grades 316L and 904L deliver salt spray resistance for offshore wind monopile cable penetrations. Nickel and chromium price volatility compress margin predictability for European fabricators serving North Sea developers. DNV pressure-testing protocols validate weld integrity for subsea installations.
- Aluminum:6061-T6 and 7075 alloys reduce mass in aerospace cable routing and electric vehicle charging infrastructure. Salt spray exposure limits penetration in marine environments despite weight advantages. Transportation OEMs in Germany and the Netherlands prioritize aluminum for rooftop solar integration systems.
- PVC:Cost-effective polymer formulations serve indoor telecommunications enclosures with minimal chemical exposure. EU F-Gas Regulation phase-downs are eliminating halogenated additive packages.
- Copper:Electromagnetic shielding properties satisfy medical device and military specification requirements. Beryllium-free alternatives gain preference under evolving occupational safety directives.
Stainless steel commands revenue concentration; aluminum is expanding most quickly in electrified transportation platforms.
Connection Type:
Installation labor economics and field service accessibility determine connection architecture preference across infrastructure lifecycles.
- Screw-On:Threaded metal-to-metal sealing dominates industrial equipment where maintenance access permits tool-based disassembly. Mature volume pool attracts Asian contract manufacturer competition. NEMA enclosure rating compliance enables North American market entry.
- Welded:Permanent metallurgical bonding satisfies marine classification society requirements for pressure-rated bulkhead penetrations. American Bureau of Shipping documentation extends fabrication timelines. Offshore wind developers accept these constraints for structural integrity assurance.
- Snap-On:Tool-free installation accelerates telecommunications field deployment in fiber-to-the-premises rollouts. Polymer retention clips degrade under UV exposure in outdoor applications.
- Quick Release:Lever-actuated mechanisms enable rapid cable swap-out in broadcast equipment and mobile medical imaging systems. Premium positioning reflects precision machining requirements.
Screw-on configurations anchor volume leadership; quick release is climbing the fastest in mobile equipment segments.
Application:
End-use environmental severity creates specification tiering that separates commodity procurement from performance-guaranteed service contracting.
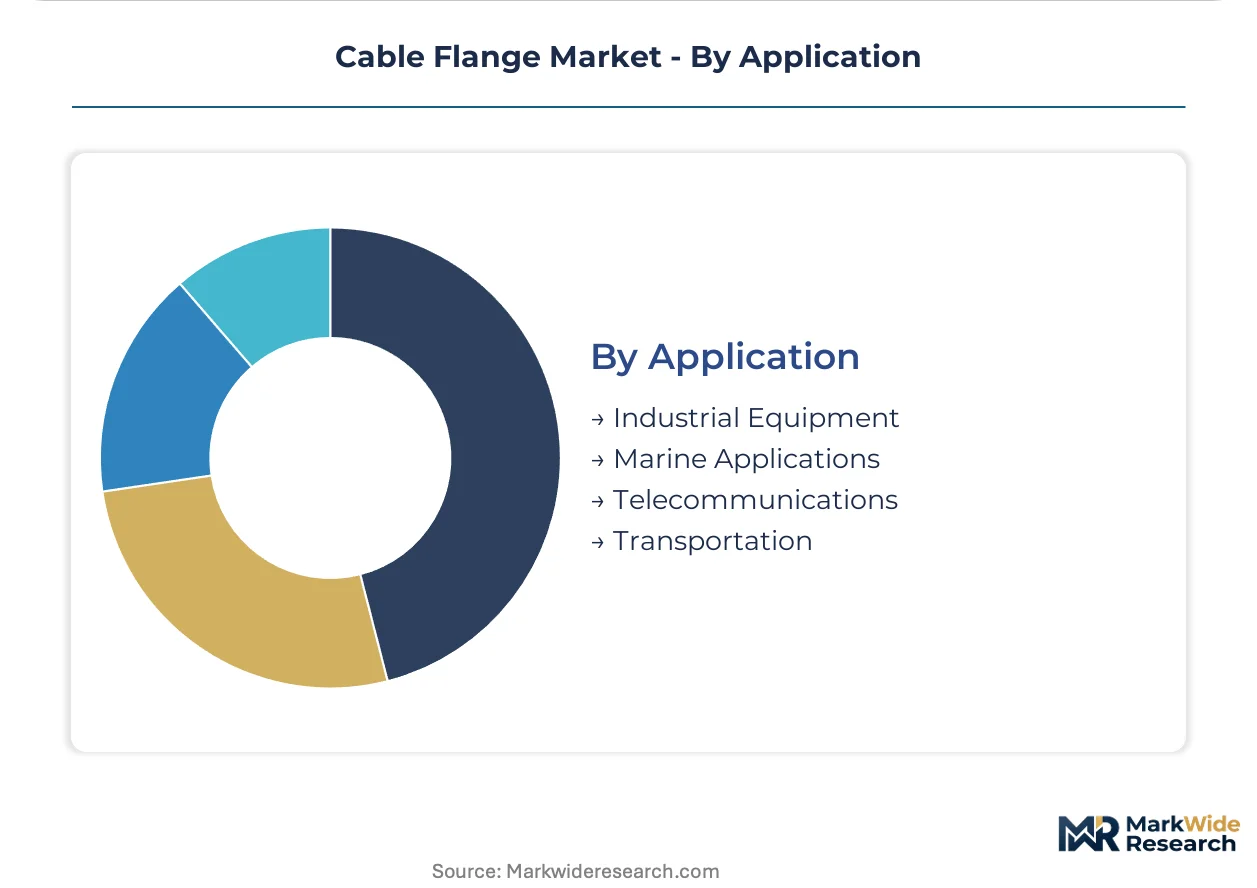
- Marine Applications:Subsea cable penetrations and topside equipment sealing demand the highest material grades and classification documentation. German and Danish offshore wind developers bundle multi-year service agreements with component supply. IEC 60092 standards dictate elastomer compound selection for salt spray resistance.
- Industrial Equipment:Factory automation and process control enclosures drive standard flange volume with moderate IP rating requirements. Preventive maintenance subscriptions are restructuring supplier-buyer relationships toward recurring revenue models.
- Telecommunications:Data center fiber management and 5G small cell enclosures prioritize density and tool-free installation speed. Copper EMI shielding specifications differentiate enterprise from consumer-grade deployments.
- Transportation:Aerospace cable routing and rail electrification systems trade corrosion resistance for weight reduction. Aluminum flange penetration accelerates in electric vehicle battery enclosure applications.
Industrial equipment leads absolute volumes; marine applications show the steepest expansion trajectory driven by offshore wind procurement concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's northern port clusters command premium procurement volumes for marine-grade cable flanges, while China's Yangtze River Delta manufacturing bases dominate standard component export flows. This divergence between specification-heavy European demand and scale-driven Asian supply defines regional competitive positioning.
Germany
Offshore wind developers in Bremen and Hamburg anchor North Sea cable penetration procurement. EU F-Gas Regulation phase-downs force elastomer compound reformulation across German shipyards. The Hamburg industrial cluster concentrates multi-year service bundling contracts with Tier-one EPC contractors.
China
Yangtze River Delta fabricators supply screw-on standard flanges for global industrial equipment OEMs. GB standards and IEC certification harmonization reduce export qualification friction. Shanghai port infrastructure expansion drives domestic marine sealing demand alongside export manufacturing.
United States
Gulf Coast offshore energy projects and data center construction sustain corrosion-resistant and telecommunications flange procurement. NEMA enclosure rating compliance enables cross-border equipment certification with Canadian markets. Houston anchors petrochemical cable management specification authority.
Denmark
Ørsted-led offshore wind consolidation concentrates procurement with engineering-procurement-construction contractors demanding performance guarantees. IEC 60092 marine standards dictate material selection for North Sea installations. Copenhagen industrial planners specify multi-year service agreements replacing conventional warranties.
Japan
Chubu/Nagoya aerospace cable routing and Kanto rail electrification prioritize aluminum flange weight reduction. METI industrial standards shape polymer formulation requirements for transportation applications. Osaka Bay manufacturing clusters export precision-machined quick-release configurations for broadcast equipment.
Cable Flange Market Competitive Environment
Top-tier vendors anchor premium specification territories, while mid-scale fabricators compete on standard component volumes. Market structure tilts toward consolidation in marine and medical segments where certification barriers concentrate procurement authority. Three archetypes dominate: modular sealing platform operators, polymer innovation specialists, and scale-driven custom electromagnetic shielding manufacturers. Competitive moves center on multi-year service contract anchoring and recyclable material formulation ahead of EU Ecodes mandates.
Among European sealing specialists, Roxtec International AB and igus GmbH occupy differentiated positions within the premium tier. Roxtec exemplifies the modular platform archetype through its service agreement anchoring across marine infrastructure. Igus represents polymer-based innovation vectors that reduce replacement cycle frequency in dynamic applications. Lorom Industrial Co., Ltd. anchors the custom manufacturing segment, exemplifying scale-driven positioning in specialized electromagnetic configurations.
| Leading Market Players |
|---|
| Lorom Industrial Co., Ltd. |
| National Wire & Cable Corporation |
| Haynes International, Inc. |
| Affinity Medical Technologies, LLC |
| Hitachi, Ltd. |
| Sealcon |
| igus GmbH |
| Binder-USA, LP |
| Roxtec International AB |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium price index volatility cascades through marine-grade stainless steel procurement into three-tier pricing stratification across corrosion-resistant, standard industrial, and economy polymer configurations. German fabricators serving North Sea offshore wind developers absorb input cost swings through long-term service bundling, while Asian contract manufacturers competing on screw-on standard volumes face margin compression from spot-market metal purchasing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard screw-on configurations, intensifying competition in the mature volume pool where NEMA enclosure rating compliance enables North American market entry. Premium-mid-economy pricing differentiation separates DNV-certified marine-grade welded flanges with multi-year performance guarantees from tool-free snap-on telecommunications variants. Cost compression in standard aluminum transportation flanges is intensifying because electric vehicle OEMs prioritize weight reduction over corrosion resistance. Medical device OEMs exhibit least price sensitivity for custom electromagnetic shielding configurations, while warehouse automation contractors in Bremen and Hamburg demonstrate highest sensitivity to standard flange unit costs.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore anchor hub-and-spoke patterns for marine-grade component fulfillment to offshore wind project sites. Manufacturing concentrates in Germany, China, and Japan, with German fabricators specializing in classification-documented welded configurations and Yangtze River Delta producers dominating screw-on export volumes. Raw material sourcing draws from nickel mines in Indonesia, chromium from South Africa, and specialty polymer compounds from German chemical clusters. Single-source vulnerability around marine-grade elastomer formulation creates exposure as EU F-Gas Regulation phase-downs eliminate legacy halogenated compounds. Distribution runs through Tier-one EPC contractor procurement platforms that bundle multi-year service agreements with component supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable flange market operates as a regulatory compounder where EU F-Gas Regulation phase-down schedules and IEC 60092 marine standard revisions continuously recast supplier qualification barriers, forcing material reformulation investments that favor incumbent platform operators with established certification documentation.
For Market Incumbents: Deploy modular sealing platform expansion as the primary lever to anchor recurring service revenue across marine infrastructure modernization. Backward integration into specialty polymer compounding secures supply continuity ahead of REACH substance restriction sunset dates. Counter aluminum flange substitution threats in transportation applications by emphasizing IEC 60529 ingress protection validation that salt spray exposure limits cannot satisfy.
For New Entrants and Emerging Players: Predictive maintenance sensor integration represents the most penetrable technology-first wedge for challenging established marine service contracts. Target medical device electromagnetic shielding configurations where OEM qualification cycles favor early platform investment and engineering-intensive prototyping economics deter volume competitors. Pursue direct engagement with German port industrial clusters around Bremen and Hamburg, where shore power system expansion creates specification white space outside incumbent EPC relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with polymer innovation specialists possessing recyclable formulation capabilities ahead of EU Ecodesign circular-economy mandates. Five-to-ten year viability favors vendors with demonstrated marine classification society documentation throughput rather than pure-play standard component scale. Monitor DNV and American Bureau of Shipping certification timeline compression as the critical inflection signal—accelerated validation cycles would disadvantage documentation-heavy incumbents and favor agile compounders.
| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Polymer Formulation Development | EU Ecodesign requirements recast supplier qualification criteria for European infrastructure projects. |
| Marine Classification Society Pre-Certification | DNV pressure-testing protocol completion compresses offshore project bid response timelines. |
| Multi-Year Service Agreement Structuring | Danish and UK offshore wind developers mandate performance guarantees replacing conventional warranty terms. |
| Electromagnetic Shielding Platform Investment | Medical imaging OEM qualification cycles favor early entrants in diagnostic equipment specification territory. |
| Regional Distribution Hub Establishment | Rotterdam and Singapore marine logistics nodes reduce field service response times for North Sea installations. |
Study Parameters
Coverage spans Germany, China, the United States, Denmark, and Japan, with primary inputs from each market's offshore wind developers, marine classification surveyors, industrial equipment procurement teams, and polymer compound technical directors. Secondary validation draws from IEC standard revision documentation, EU regulatory filing databases, customs trade flow records, and SEC filings from listed industrial component suppliers. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling addresses product type, material grade, connection architecture, and application severity tier at the country-cluster level. CAGRs derive from segment-level volume and value trajectory analysis incorporating raw material price index sensitivity and regulatory compliance cost stacking. Industry-specific forecast inputs include offshore wind installation pipeline databases and marine newbuild contract award tracking.
The model holds under stable regulatory phase-down schedules and consistent classification society documentation requirements; deviation in EU F-Gas Regulation enforcement timing or IEC 60092 revision scope would shift material substitution trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Trunking Market
Cables
SATA Power Cable Market
Cables
Copper Cable Market
Cables
GCC Cable Accessories Market
Cables
Magnetic Charging Cable Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Global Industrial Automation Cable Market
Cables
India Wire and Cable Market
Cables
Mexico Wires and Cables Market
Cables
Multicore Cables Market
Cables
USB Cable Market
Cables
Fiber Optic Cable Materials Market
Cables
Copper Stranded Wire Market
Cables
Cable Material Market
Cables
Military Cable Market
Cables
Twisted Pair Cable Market