
 Europe Wire and Cable Market | 2026-2036
Europe Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wire and Cable Market Insights
Capital-intensity divergence between integrated compound producers and cable assemblers is redrawing competitive boundaries across the European wire and cable sector. Prysmian S.p.A. leverages its vertical grip on optical fiber preform manufacturing to dominate subsea and high-voltage land cable tenders. Nexans S.A. anchors its position through dedicated R&D centers in France and Norway focused on superconducting and fire-resistant formulations. NKT A/S specializes in extruded high-voltage direct-current systems, giving it concentrated exposure to North Sea offshore wind interconnectors.
Wire and cable denotes electrically conductive assemblies comprising metallic conductors—typically copper or aluminum—with insulating and shielding layers engineered for voltage ratings from millivolt signal transmission to 500 kV power distribution. Manufacturing integrates continuous casting, wire drawing, and polymer extrusion to achieve specified dielectric strength, thermal endurance, and mechanical flexibility for energy transmission, data communication, or control signaling. Power cable commands the largest value pool, particularly XLPE-insulated medium- and high-voltage designs serving utility grid reinforcement. Communication cable is displacing legacy copper networks as fiber-to-the-premises mandates spread across EU member states. Specialty cable, including fire-resistant and halogen-free variants, captures premium pricing in rail, marine, and nuclear applications where REACH and CPR compliance thresholds are strictest.
CE marking under the Construction Products Regulation and EU Green Deal electrification targets are tightening material traceability and recyclability requirements across the value chain. ECHA REACH restrictions on lead stabilizers and short-chain chlorinated paraffins are accelerating PVC reformulation toward calcium-zinc or mixed-metal heat stabilizer systems. The EU F-Gas Regulation and impending CSRD disclosure obligations will force cable makers to document embodied carbon and fluorinated gas content in cross-linked insulation processes. Stakeholders must weigh stranded asset risk in conventional thermoplastic extrusion lines against capital commitments to bio-based and chemically recyclable polymer platforms.
Market Dynamics
The EU Green Deal's electrification mandates and F-Gas Regulation phase-down are forcing immediate material transitions across European cable manufacturing, compressing reformulation timelines for insulation compounds while offshore wind procurement accelerates demand for high-voltage submarine systems.
Growth Catalysts
- Renewable interconnection mandates:Germany and Scandinavia are accelerating procurement of high-voltage submarine and underground power cables to link offshore wind farms with onshore grids.
- REACH chemical restrictions:ECHA restrictions on lead stabilizers and short-chain chlorinated paraffins are accelerating PVC reformulation toward calcium-zinc heat stabilizer systems that command premium positioning.
- Data center fiber deployments:Fiber-to-the-premises mandates across EU member states are displacing legacy copper networks in France, Germany, and Italy.
Market Restraints
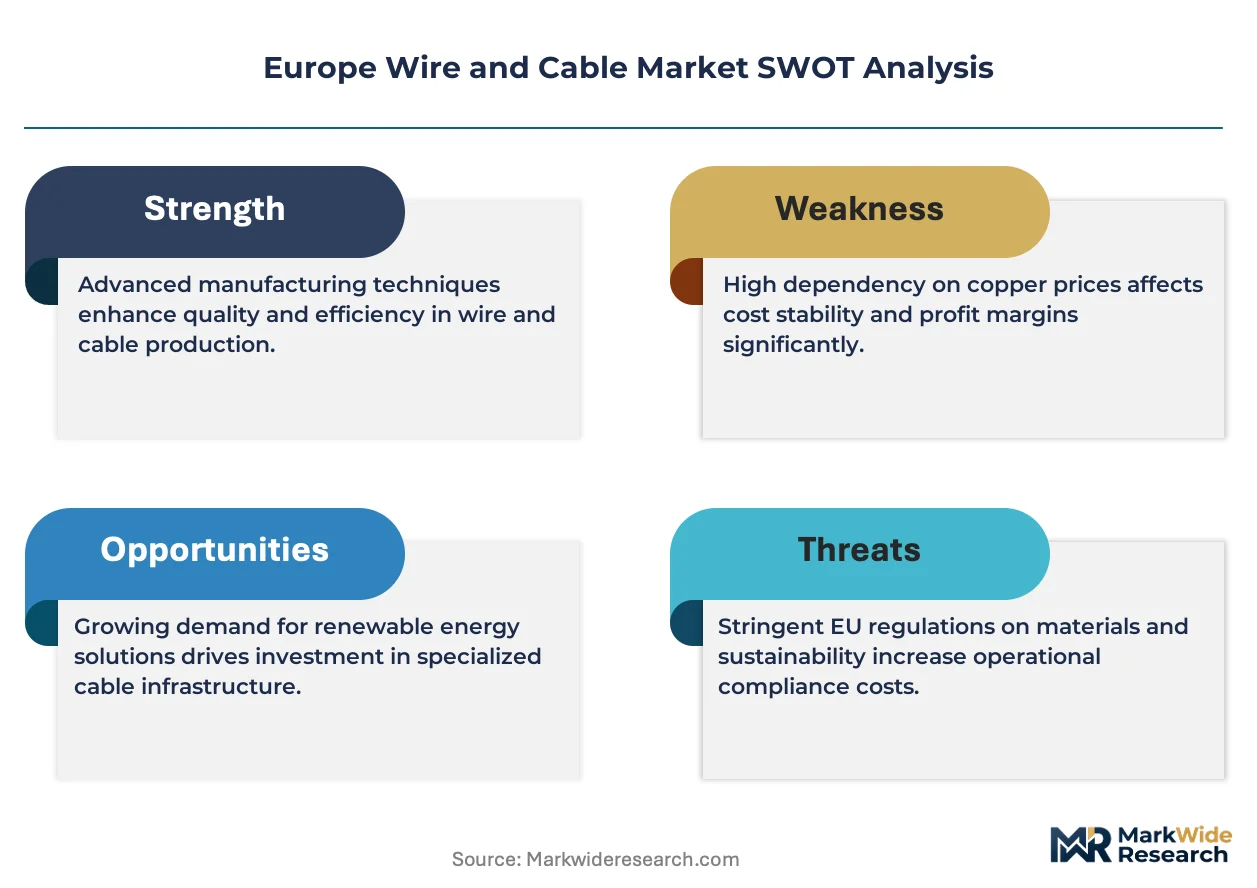
- Copper price volatility:London Metal Exchange copper pricing swings compress margin visibility for cable assemblers lacking backward integration into metal casting.
- Compound supply concentration:Integrated polymer producers in Germany and Benelux control specialty low-smoke zero-halogen formulations, creating procurement bottlenecks for mid-tier cable manufacturers.
- Cross-linked polyethylene technical ceiling:XLPE insulation faces dielectric strength limitations above 500 kV, constraining ultra-high-voltage land cable development without alternative materials.
Strategic Opportunities
- Polish and Romanian grid modernization:EU cohesion funds are channeling infrastructure investment into Central and Eastern European markets where cable stock remains below Western European density.
- CSRD disclosure tailwinds:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for cable makers documenting embodied carbon and fluorinated gas content in cross-linked processes.
- Superconducting-cryogenic convergence:Hybrid systems combining high-temperature superconducting tapes with conventional copper stabilizers are opening urban retrofit applications where right-of-way constraints block conventional high-voltage corridors.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for REACH-compliant halogen-free compounds concentrates among retiring specialists in Lyon and Leverkusen industrial clusters.
- CE marking timeline compression:Construction Products Regulation certification for fire-resistant rail cables now requires 14-18 month test cycles, delaying project-specific tenders.
- Legacy extrusion asset stranding:Conventional thermoplastic lines face accelerated obsolescence as bio-based and chemically recyclable polymer platforms require capital commitments exceeding mid-cap balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wire and Cable Market |
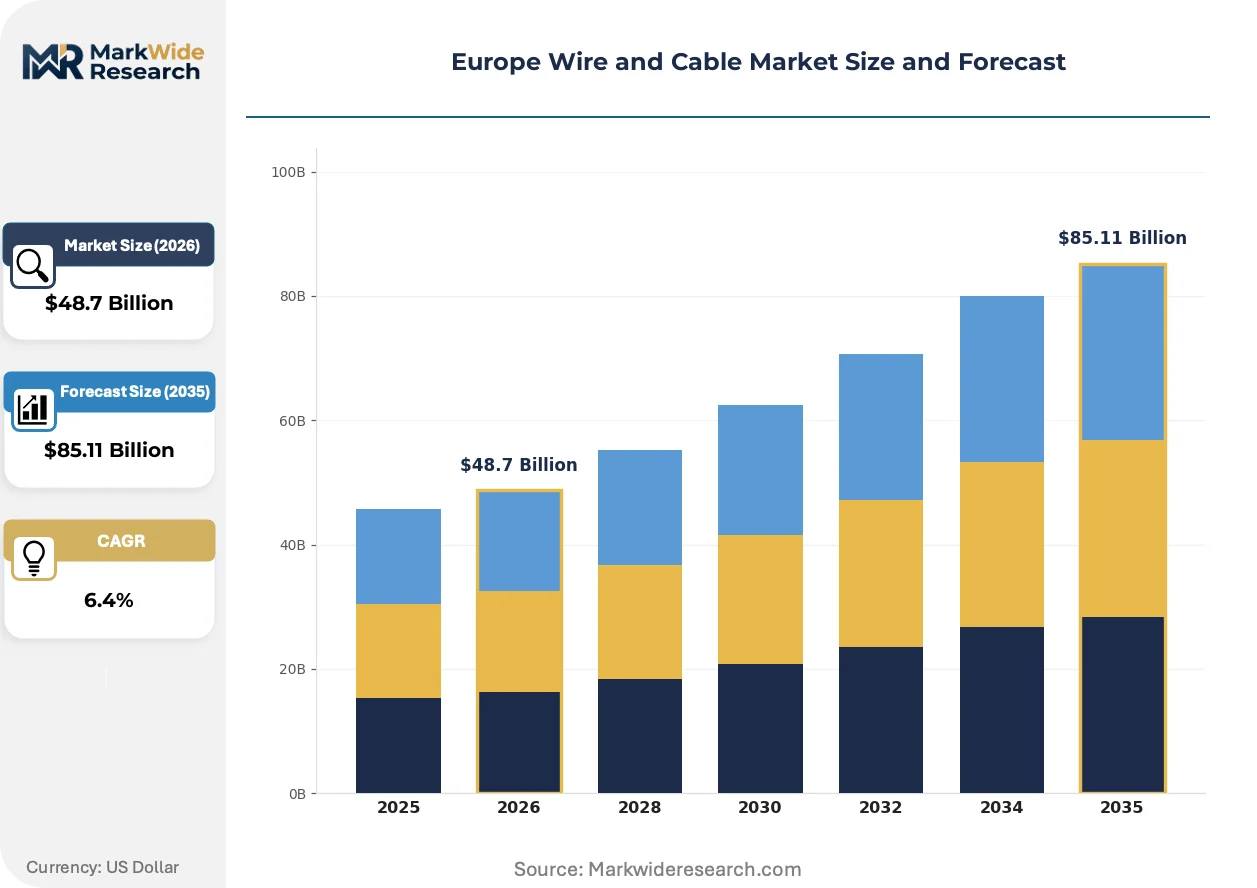
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cable, Communication Cable, Control Cable, Specialty Cable Insulation Material: XLPE, PVC, Rubber, Polyethylene End User: Construction, Automotive, Telecommunications, Energy Connection Type: Crimped, Soldered, Plug-in, Others |
| Companies Covered | Prysmian S.p.A., Nexans S.A., NKT A/S, Leoni AG, TELE-FONIKA Kable S.A., TE Connectivity Ltd., British Cables Company, Lapp Group, Belden Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wire and Cable Market Trends and Innovations
Active material science breakthroughs and regulatory disclosure mandates are compressing product development cycles across European cable manufacturing, while procurement centralization by utility buyers is rewriting competitive access rules.
Silicone rubber insulation is miniaturizing conductor bundles in automotive wiring harnesses without sacrificing thermal endurance. German OEMs are adopting 0.13 mm² cross-section designs for 48V mild-hybrid architectures, reducing copper mass per vehicle by 15-20 percent. This miniaturization is compressing the addressable market for traditional PVC automotive grades while expanding premium compound demand.
The EU F-Gas Regulation is banning hydrofluorocarbon blowing agents in cross-linked polyethylene manufacturing by 2027. Cable extruders are retrofitting nitrogen-injection systems or switching to azodicarbonamide alternatives, adding 8-12 percent to insulation line capital costs. Medium-voltage utility cable producers in France and Norway face the steepest compliance curves due to existing fluorinated gas inventory commitments.
Centralized procurement consortia among North Sea offshore wind developers are consolidating cable tender volumes into multi-year framework agreements. Tier-1 utilities are bypassing distribution intermediaries to negotiate directly with compound-integrated manufacturers, compressing channel margins and freezing out non-vertically integrated assemblers. This concentration is most visible in German and Danish offshore lease rounds where single-source supplier requirements dominate technical specifications.
Europe Wire and Cable Market Segmentation
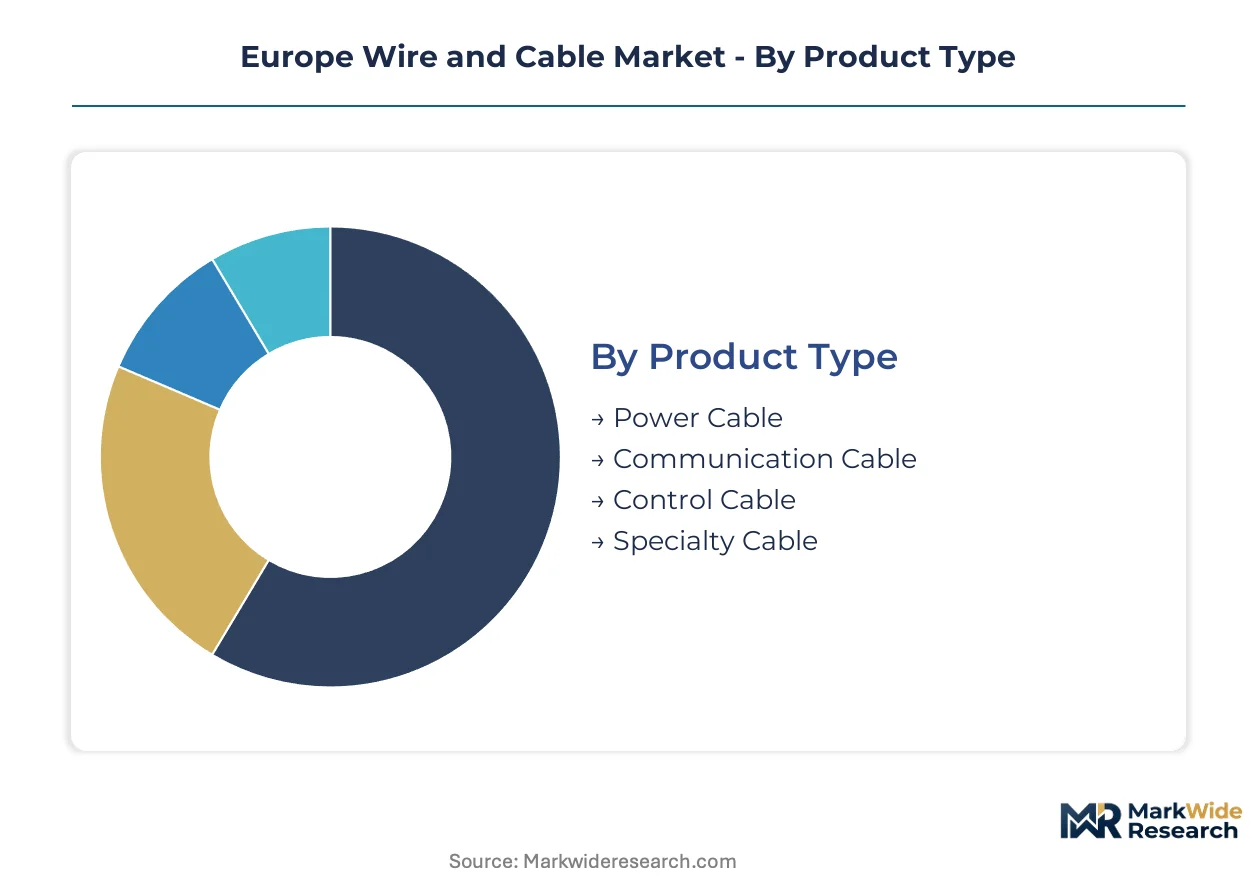
Segmentation in the European wire and cable market reveals how regulatory pressure and electrification mandates are fragmenting demand across incompatible material specifications. Voltage rating, insulation chemistry, and end-use certification requirements now dictate supplier access more than volume scale alone.
Product Type:
Power cable faces the strongest substitution pressure from high-voltage direct-current alternatives and superconducting systems in offshore wind interconnectors.
- Power Cable:XLPE-insulated medium- and high-voltage designs dominate utility grid reinforcement across Germany and Scandinavia. German transmission system operators are procuring 320 kV submarine systems for North Sea wind farm connections under centralized framework agreements.
- Communication Cable:Single-mode fiber displaces copper twisted-pair in France, Germany, and Italy as EU member states enforce fiber-to-the-premises mandates. Data center hyperscalers in Frankfurt and Amsterdam are driving ribbon fiber demand for 400G/800G switching architectures.
- Control Cable:Multi-conductor flexible assemblies serve factory automation and process instrumentation. REACH-compliant halogen-free variants command premium positioning in rail and nuclear applications.
- Specialty Cable:Fire-resistant and cryogenic-rated formulations address marine, aerospace, and superconducting hybrid systems. Prysmian and Nexans concentrate R&D for 500 kV+ land cable alternatives here.
Power cable retains volume leadership; communication cable holds the steepest expansion curve.
Insulation Material:
Material cost tiers separate premium compound-integrated manufacturers from commodity assemblers dependent on merchant polymer supply.
- XLPE:Cross-linked polyethylene delivers dielectric strength up to 500 kV for land and submarine transmission. Nitrogen-injection extrusion retrofits are spreading as the EU F-Gas Regulation phases out hydrofluorocarbon blowing agents.
- PVC:Thermoplastic formulations face ECHA REACH restrictions on lead stabilizers and short-chain chlorinated paraffins. Calcium-zinc and mixed-metal heat stabilizer systems are displacing legacy compounds in building wire applications.
- Rubber:Ethylene-propylene and silicone rubber grades serve mobile equipment and automotive wiring harnesses. German OEMs specify 0.13 mm² silicone-insulated conductors for 48V mild-hybrid architectures.
- Polyethylene:Linear low-density variants address low-voltage signal transmission and data communication. Compounding expertise concentrates in Benelux and German industrial clusters.
XLPE captures the highest value-per-ton; rubber formulations are climbing fastest on automotive electrification.
End User:
Customer procurement maturity separates long-term framework agreements from spot-market purchasing.
- Construction:Building wire and low-voltage power distribution serve residential and commercial development. CE marking under the Construction Products Regulation mandates 14-18 month fire-resistance certification cycles for rail and high-rise applications.
- Automotive:Wiring harnesses for internal combustion, hybrid, and battery-electric platforms drive copper demand. French and German OEMs are consolidating supplier panels to tier-1 harness assemblers with captive compound capabilities.
- Telecommunications:Fiber optic and copper data cables support broadband expansion and 5G backhaul. EU cohesion funds are channeling investment into Polish and Romanian network densification.
- Energy:Utility transmission, distribution, and renewable interconnection absorb high-voltage submarine and land cable output. North Sea offshore wind developers are consolidating tender volumes into multi-year direct negotiations with integrated manufacturers.
Energy commands the largest project scale; telecommunications delivers the most consistent volume growth.
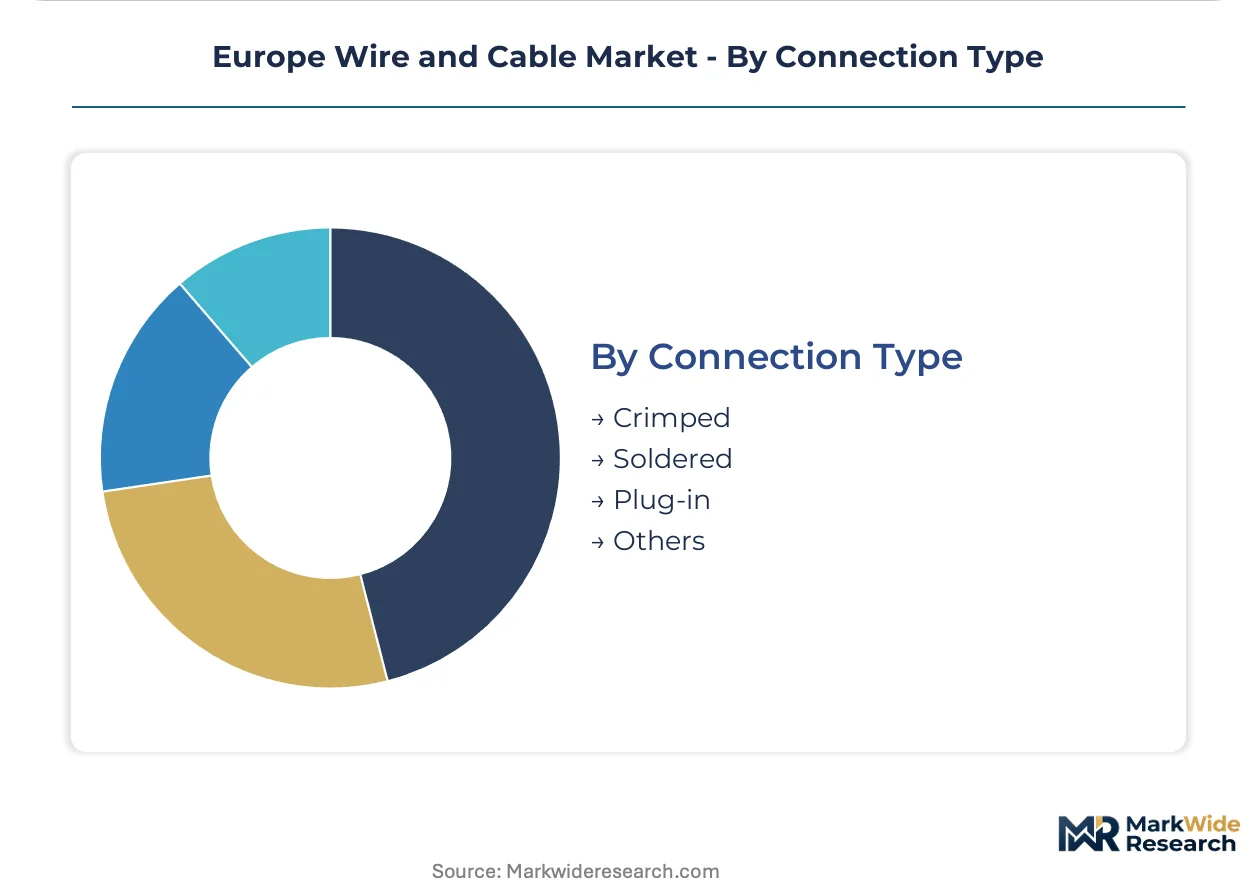
Connection Type:
Application-specific reliability requirements dictate termination technology selection across voltage classes.
- Crimped:Compression terminals dominate power cable joints and automotive harness connections. Tooling standardization varies between German DIN and French NFC specifications.
- Soldered:Tin-lead and lead-free alloys serve fine-pitch electronics and control signal integrity. REACH restrictions are accelerating transition to silver-bearing and copper-tin formulations.
- Plug-in:Modular connectors address data center fiber patching and industrial fieldbus applications. MPO/MTP multifiber push-on interfaces are standardizing at 16-fiber and 32-fiber densities.
- Others:Welded, clamped, and spring-force terminations serve specialty rail and marine applications. Custom specifications concentrate in Scandinavian and Alpine tunnel projects.
Crimped connections retain installation volume; plug-in interfaces are expanding most quickly on data center fiber density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across European wire and cable markets. Germany and Scandinavia concentrate procurement on high-voltage submarine systems for offshore wind, while France and Italy prioritize automotive harness upgrades and data center fiber.
Germany
Transmission system operators procure 320 kV submarine cables for North Sea wind farm connections under centralized framework agreements. The EU Green Deal electrification mandates accelerate grid reinforcement timelines. Industrial clusters in North Rhine-Westphalia and Bavaria host compound-integrated manufacturers with captive polymer formulation capabilities.
France
Automotive OEMs consolidate supplier panels for 48V mild-hybrid wiring harnesses with silicone-insulated miniaturized conductors. ECHA REACH restrictions on lead stabilizers force PVC reformulation toward calcium-zinc systems. The Lyon industrial corridor retains concentrated expertise in halogen-free compound chemistry for rail and nuclear applications.
Italy
Fiber-to-the-premises mandates displace legacy copper networks in urban broadband expansion. CE marking under the Construction Products Regulation imposes 14-18 month fire-resistance certification cycles for building wire. Manufacturing concentrates in Lombardy and Piedmont, with cable assemblers serving Mediterranean submarine interconnector projects.
Poland
EU cohesion funds channel infrastructure investment into grid modernization where cable stock remains below Western European density. The national energy regulator accelerates transmission network upgrades to integrate renewable generation. Industrial zones around Warsaw and Katowice attract mid-tier cable manufacturers seeking proximity to Central European construction markets.
Netherlands
Data center hyperscalers in Amsterdam drive ribbon fiber demand for 400G/800G switching architectures. The F-Gas Regulation phases out hydrofluorocarbon blowing agents in cross-linked polyethylene manufacturing by 2027. The Rotterdam-Antwerp chemical corridor supplies specialty low-smoke zero-halogen formulations to integrated cable producers.
Europe Wire and Cable Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European wire and cable manufacturing. The upper tier commands direct procurement relationships with North Sea offshore wind developers and German transmission operators. Mid-tier assemblers face procurement bottlenecks for REACH-compliant compounds controlled by integrated polymer producers. Strategic moves concentrate on backward integration into optical fiber preform manufacturing and nitrogen-injection extrusion retrofits for F-Gas compliance.
Among Italy-based manufacturers, Prysmian S.p.A. exemplifies the vertically integrated archetype with captive control over upstream material production. France's Nexans S.A. and Denmark's NKT A/S occupy positions within the high-voltage specialist tier, representing geographic concentration of submarine and extruded direct-current system expertise around North Sea renewable interconnection corridors.
| Leading Market Players |
|---|
| Prysmian S.p.A. |
| Nexans S.A. |
| NKT A/S |
| Leoni AG |
| TELE-FONIKA Kable S.A. |
| TE Connectivity Ltd. |
| British Cables Company |
| Lapp Group |
| Belden Inc. |
| Others |
Pricing and Supply Chain Analysis
Multi-year framework agreements between North Sea offshore wind developers and integrated cable manufacturers lock in both copper supply access and price visibility across volatile London Metal Exchange cycles. These contracts compress margin risk for compound-integrated producers while freezing out mid-tier assemblers lacking backward integration into polymer formulation or metal casting.
Pricing Analysis
After-sales service contracts for submarine cable installation and maintenance drive lifetime value for integrated manufacturers serving utility transmission operators. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant halogen-free formulations from legacy PVC building wire and commodity copper conductors. Cost compression in standard-grade power cable is intensifying because merchant polymer producers in Germany and Benelux control specialty low-smoke zero-halogen formulations. Data center hyperscalers exhibit lowest price sensitivity due to fiber density requirements for 400G switching architectures, while residential construction contractors face acute margin pressure on CE-marked building wire.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for copper cathode shipments from Chilean and Peruvian mining operations. Manufacturing gravity centers on Germany, Italy, and France, where industrial clusters host integrated compound producers with captive polymer formulation capabilities. Raw material dependencies rest on London Metal Exchange copper pricing, optical fiber preform supply, and specialty halogen-free resin formulations. Single-source vulnerability concentrates in German and Benelux polymer producers controlling REACH-compliant heat stabilizer systems. Distribution runs through direct procurement consortia among North Sea offshore wind developers, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe wire and cable market functions as a defensive-moat sector where regulatory entrenchment through CE marking and REACH compliance creates durable barriers against commodity assemblers. Switching costs for utility transmission operators concentrate procurement relationships among vertically integrated manufacturers with captive compound capabilities.
For Market Incumbents: Shield market position by accelerating nitrogen-injection extrusion retrofits ahead of EU F-Gas Regulation phase-down deadlines for hydrofluorocarbon blowing agents. Consolidate polymer formulation expertise in Lyon and Leverkusen industrial clusters before specialist retirements erode halogen-free compound capabilities. Capacity addition in Poland and Romania captures EU cohesion fund flows for grid modernization where cable stock remains below Western European density. For New Entrants and Emerging Players: CE marking fast-track for fire-resistant rail cables opens procurement access despite 14-18 month certification cycles delaying incumbent tenders. Target Polish and Romanian transmission network upgrades where EU cohesion funds channel infrastructure investment and mid-tier cable stock lags Western density. White-space opportunity concentrates in automotive wiring harness miniaturization for 48V mild-hybrid architectures requiring silicone-insulated 0.13 mm² conductors. Go-to-market angle: partner with German OEM supplier panels seeking second-source harness assemblers with captive compound capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with backward integration into optical fiber preform production and captive halogen-free polymer formulation. Long-term viability over the next decade hinges on exposure to North Sea offshore wind interconnector procurement and data center fiber density upgrades. Acquisition target archetype: mid-tier cable assemblers in Central Europe with stranded thermoplastic extrusion assets convertible to bio-based polymer platforms. Signal to watch: centralized procurement consortia consolidating tender volumes into multi-year direct negotiations with compound-integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive supply of REACH-compliant halogen-free compounds insulates against German-Benelux procurement bottlenecks. |
| Nitrogen-Injection Extrusion Retrofit | F-Gas Regulation compliance for cross-linked polyethylene manufacturing avoids hydrofluorocarbon blowing agent phase-out. |
| Long-term Framework Agreement | Direct procurement relationships with North Sea offshore wind developers lock in copper price visibility and volume commitments. |
| CE Marking Certification Investment | Fire-resistant rail cable approval opens access to German and Scandinavian tunnel projects with 14-18 month test cycles. |
| Geographic Expansion into Central Europe | Polish and Romanian grid modernization captures EU cohesion fund infrastructure investment below Western cable density. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and utility procurement disclosures across the European cable manufacturing sector. Primary interviews engaged transmission system operator procurement officers, polymer formulation chemists in Lyon and Leverkusen industrial clusters, and data center hyperscaler infrastructure planners. Secondary validation drew from ECHA REACH restriction updates, EU Green Deal electrification mandate documentation, and North Sea offshore wind lease round technical specifications. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators for copper demand and grid investment flows.
Segmentation dimensions modeled span voltage rating, insulation chemistry, end-use certification requirements, and connection type across the projection horizon. Voltage classes separate power, communication, control, and specialty cable demand pools. Insulation materials track XLPE, PVC, rubber, and polyethylene formulation shifts under regulatory pressure. End-use segmentation captures construction, automotive, telecommunications, and energy procurement maturity differences. CAGRs were derived from elasticity modeling against copper price volatility and offshore wind capacity deployment schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal electrification investment and F-Gas Regulation enforcement timelines; material deviation would warrant model refresh. Specific risk factors include accelerated stranded asset obsolescence in conventional thermoplastic extrusion lines and polymer chemist scarcity eroding REACH-compliant formulation capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Cable Blowing Equipment Market
Cables
Cable Detector Market
Cables
GCC Cable Accessories Market
Cables
Anti-Static Space Wires Market
Cables
SATA Power Cable Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
USB Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Polyurethane Cable Market
Cables
India Wire and Cable Market
Cables
Power and Control Cable Market
Cables
XLPE Cables Market
Cables
Ethernet Converters Market
Cables
Europe Cable Joints Market
Cables
Underground Cable Market
Cables
North America Copper Wire and Cable Market