
 Japan Cables Market | 2026-2036
Japan Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cables Market Insights
Multi-source procurement for specialized conductor alloys and optical fiber preforms is pivoting toward domestic-Japanese supply partnerships as trade friction elevates inventory risk. Sumitomo Electric Industries leverages captive refining and drawing capabilities to secure rare-earth-doped fiber supply chains. Fujikura anchors its position through deep R&D spending on ultra-low-attenuation single-mode fibers for submarine systems. Furukawa Electric competes via integrated copper smelting-to-cable operations that buffer metal price volatility.
Japan cables encompass insulated electrical conductors and optical waveguides engineered to JIS C 3605 and JIS C 6802 standards, with power cables rated up to 275 kV cross-linked polyethylene insulation and fiber optic cables achieving attenuation below 0.18 dB/km at 1550 nm, serving electricity distribution and photonic data transport across archipelago geography. Fiber optic cables command premium margins in the telecommunications application segment as NTT and regional carriers replace legacy copper with 10G-PON backbones. Power cables dominate value contribution within the renewable energy application segment, driven by offshore wind interconnection mandates and grid reinforcement for solar farms in Kyushu and Tohoku. Underground installation type faces escalating trenching and right-of-way costs, pushing innovation in slim-profile high-amperage designs.
METI enforces the Electricity Business Act and Industrial Safety and Health Act, mandating fire-resistant sheathing and quake-resistant cable routing in commercial and infrastructure projects. JIS standards, administered by the Japanese Industrial Standards Committee, define mechanical and electrical performance thresholds that exclude uncertified imports from public procurement. PMDA oversight of medical device cabling adds a secondary compliance layer for healthcare-sector suppliers. Stakeholders must monitor METI's forthcoming updates to grid codes for distributed energy resources, as these will dictate conductor sizing and smart-meter communication cable specifications across Japan's ten utility service territories.
Market Dynamics
Grid decentralization and offshore wind interconnection mandates are restructuring procurement volumes across Japan's cable value chain, forcing manufacturers to reconfigure capacity between high-voltage submarine systems and metropolitan fiber backbones.
Growth Catalysts
- Offshore wind mandates:METI's renewable energy targets require high-voltage submarine cables for inter-island transmission, concentrating demand in Kyushu and Tohoku coastal zones.
- GX League decarbonization:Corporate carbon-neutrality commitments under METI's GX initiative are accelerating low-loss cabling deployment in smart building retrofits and EV charging infrastructure.
- Data center cluster densification:Tokyo's cloud computing hub expansion is pulling multi-fiber ribbon cables and ultra-low-attenuation single-mode fiber into Kanto region distribution networks.
Market Restraints
- Copper price volatility:Integrated smelting operations at major Japanese manufacturers partially buffer metal cost swings, but spot market exposure remains for mid-tier extruders.
- Rare-earth fiber preform concentration:Doped optical fiber supply chains depend on limited domestic refining capacity, elevating inventory risk during trade friction episodes.
- JIS certification barriers:Public procurement exclusion of uncertified imports protects incumbent suppliers but constrains price competition in municipal infrastructure projects.
Strategic Opportunities
- Quake-resistant routing standards:METI's forthcoming updates to grid codes for distributed energy resources will mandate new conductor specifications across Japan's ten utility territories.
- Medical device cabling:PMDA oversight of healthcare-grade interconnects creates a premium segment for sterilization-resistant fiber and power cable assemblies.
- Submarine system upgrades:NTT and regional carriers' 10G-PON backbone replacement cycles are expanding addressable market for ultra-low-attenuation fiber in coastal prefectures.
Industry Challenges
- Specialized alloy metallurgy talent:Rare-earth doping expertise for optical fiber preforms concentrates at a handful of national university laboratories and captive R&D centers.
- Right-of-way cost escalation:Underground installation trenching expenses in dense urban corridors are compressing margins on conventional high-amperage designs.
- Legacy copper migration complexity:Regional carriers face integration friction when overlaying fiber networks onto existing duct infrastructure in aging metropolitan districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cables Market |
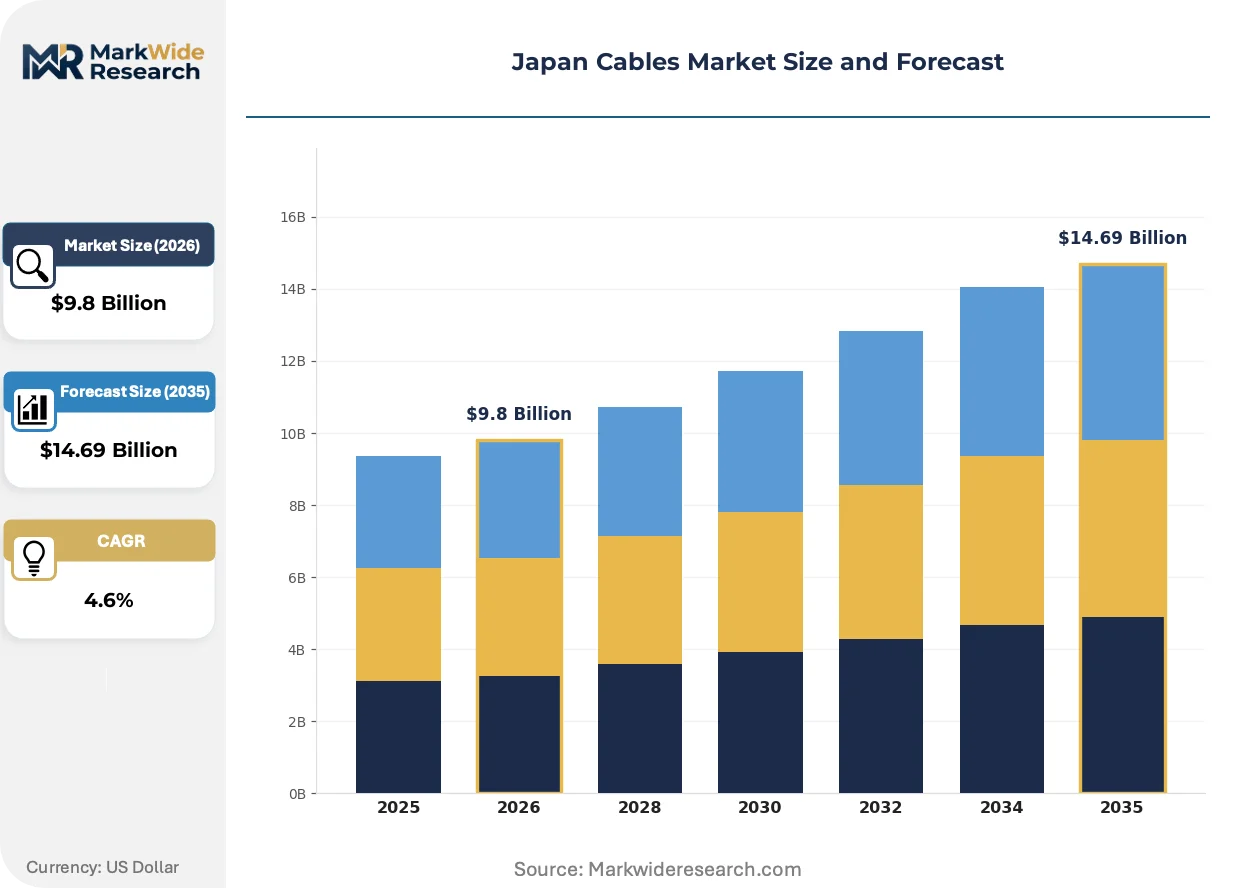
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cables, Coaxial Cables, Twisted Pair Cables, Power Cables Application: Telecommunications, Data Transmission, Industrial Automation, Renewable Energy End User: Telecom Providers, Government, Construction Firms, Utilities Installation Type: Onshore, Underground, Aerial, Indoor |
| Companies Covered | Sumitomo Electric Industries, Fujikura, Furukawa Electric, Prysmian Group, Nexans, LS Cable & System, Southwire Company, Corning, Finisar Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cables Market Trends and Innovations
Material science advances and regulatory tightening are converging to redefine performance benchmarks across power transmission and photonic data transport, with sustainability credentials now embedded in procurement scoring.
Silicon carbide (SiC) power electronics integration is expanding into high-voltage cable terminations and converter stations, enabling slimmer conductor profiles without amperage sacrifice. Renewable developers in Kyushu are specifying SiC-compatible 275 kV cross-linked polyethylene systems for offshore wind interconnections. This technology is expanding into land-based substation upgrades as utilities face right-of-way constraints in dense corridors.
METI's Industrial Safety and Health Act amendments are tightening fire-resistant sheathing requirements for commercial buildings and transit infrastructure. Manufacturers must reformulate halogen-free compounds to meet elevated smoke-density thresholds while maintaining mechanical flexibility. Healthcare and railway sectors face the steepest compliance timelines, with hospital retrofit deadlines preceding general commercial mandates by eighteen months.
Consolidated sourcing through domestic-Japanese supply partnerships is displacing multi-country alloy and preform procurement. Tier-one contractors now require documented rare-earth traceability and captive refining verification before qualifying suppliers. This pattern is most visible in Tokyo-Yokohama data center projects, where ESG disclosure requirements have elevated supply chain transparency above landed cost in vendor selection algorithms.
Japan Cables Market Segmentation
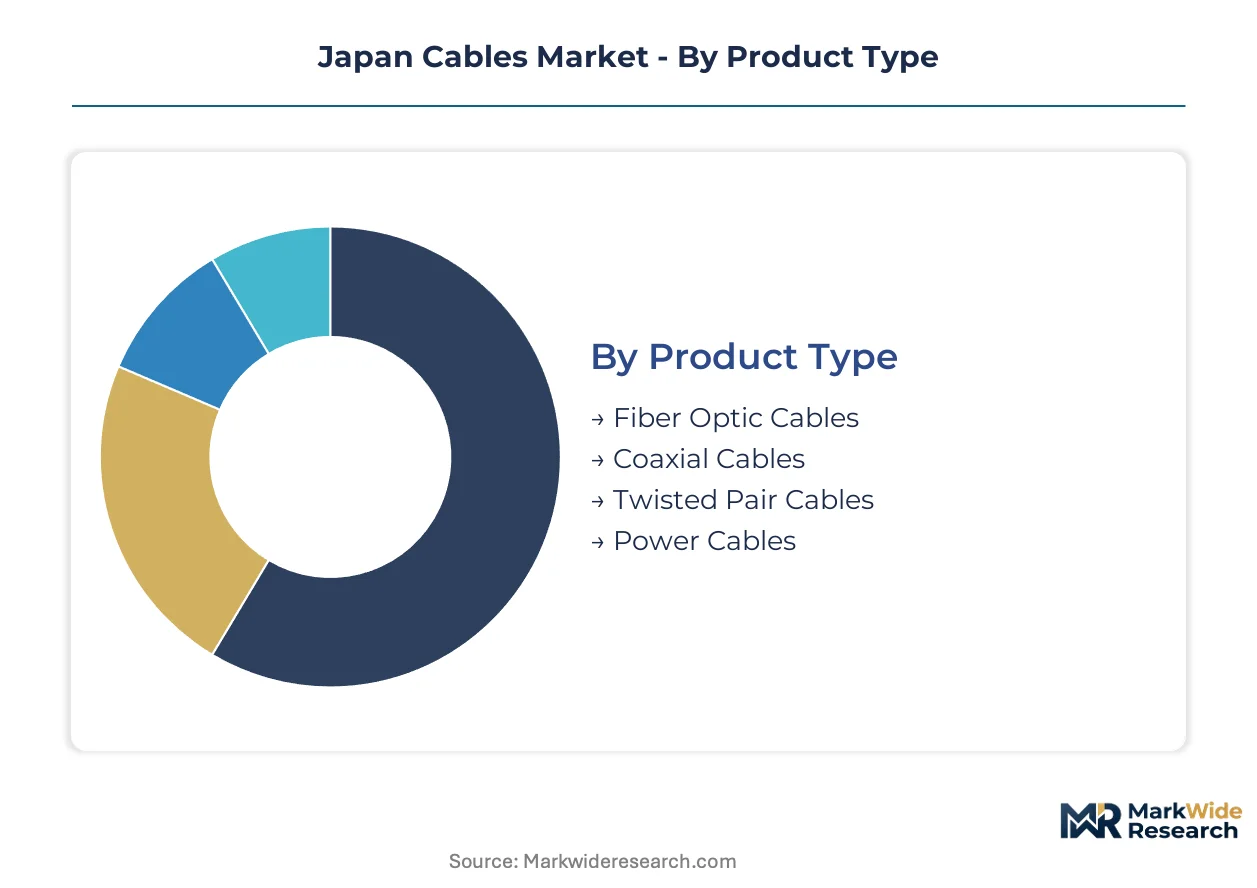
Japan's cable market segments reflect divergent engineering requirements across archipelago geography and regulatory jurisdictions. Product specifications vary sharply between metropolitan fiber densification and offshore wind interconnection projects.
Product Type:
Standardization dominates fiber and power cable production, while coaxial and twisted pair lines retain customization for legacy industrial retrofits.
- Fiber Optic Cables:Silica-based waveguides achieving attenuation below 0.18 dB/km at 1550 nm wavelength, with single-mode variants specified for NTT's 10G-PON backbone upgrades across Kanto data center clusters. Demand concentrates in ribbon cable formats for high-density metropolitan ducts.
- Power Cables:Cross-linked polyethylene insulated conductors rated up to 275 kV, engineered for METI's offshore wind interconnection mandates in Kyushu and Tohoku coastal zones. Aluminum and copper conductor alloys face divergent procurement patterns based on grid code conductor sizing requirements.
- Coaxial Cables:Copper-core shielded conductors for legacy RF signal distribution, retaining niche demand in broadcast infrastructure and closed-circuit systems.
- Twisted Pair Cables:Copper conductor pairs for industrial control networks and building automation, specified under JIS C 3605 for fire-resistant sheathing compliance.
Most installed capacity flows through Power Cables. Expansion is steepest in Fiber Optic Cables.
Application:
Volume concentrates in telecommunications infrastructure, while margin premiums attach to renewable energy and industrial automation segments.
- Telecommunications:Backbone and access network cabling for NTT and regional carriers replacing legacy copper with fiber-to-the-home architectures. Tokyo-Yokohama corridor drives multi-fiber ribbon procurement volumes.
- Renewable Energy:High-voltage submarine and land-based systems for offshore wind farm grid connection, governed by METI's carbon-neutrality roadmap and GX League procurement standards. Kyushu prefecture leads installation density.
- Data Transmission:Data center interconnect and enterprise networking cables, with ultra-low-attenuation single-mode fiber commanding premium positioning.
- Industrial Automation:Machine-to-machine cabling for smart factory deployments, requiring quake-resistant routing and electromagnetic interference shielding under Industrial Safety and Health Act amendments.
Telecommunications absorbs the largest share of current procurement. Renewable Energy is climbing the fastest.
End User:
Procurement scale separates utility and telecom providers from project-based construction and government segments.
- Telecom Providers:NTT and regional carriers dominate fiber optic volume, with 10G-PON replacement cycles driving specifications for ultra-low-attenuation submarine and terrestrial systems.
- Utilities:Ten regional utility service territories procure high-voltage power cables under METI grid code jurisdiction, with distributed energy resource integration mandates reshaping conductor requirements.
- Government:Municipal infrastructure projects bound by JIS certification requirements and public procurement exclusion of uncertified imports.
- Construction Firms:Commercial building and transit infrastructure contractors facing compressed timelines for fire-resistant sheathing compliance under amended Industrial Safety and Health Act provisions.
Utilities command the heaviest procurement volumes. Telecom Providers are gaining share fastest.
Installation Type:
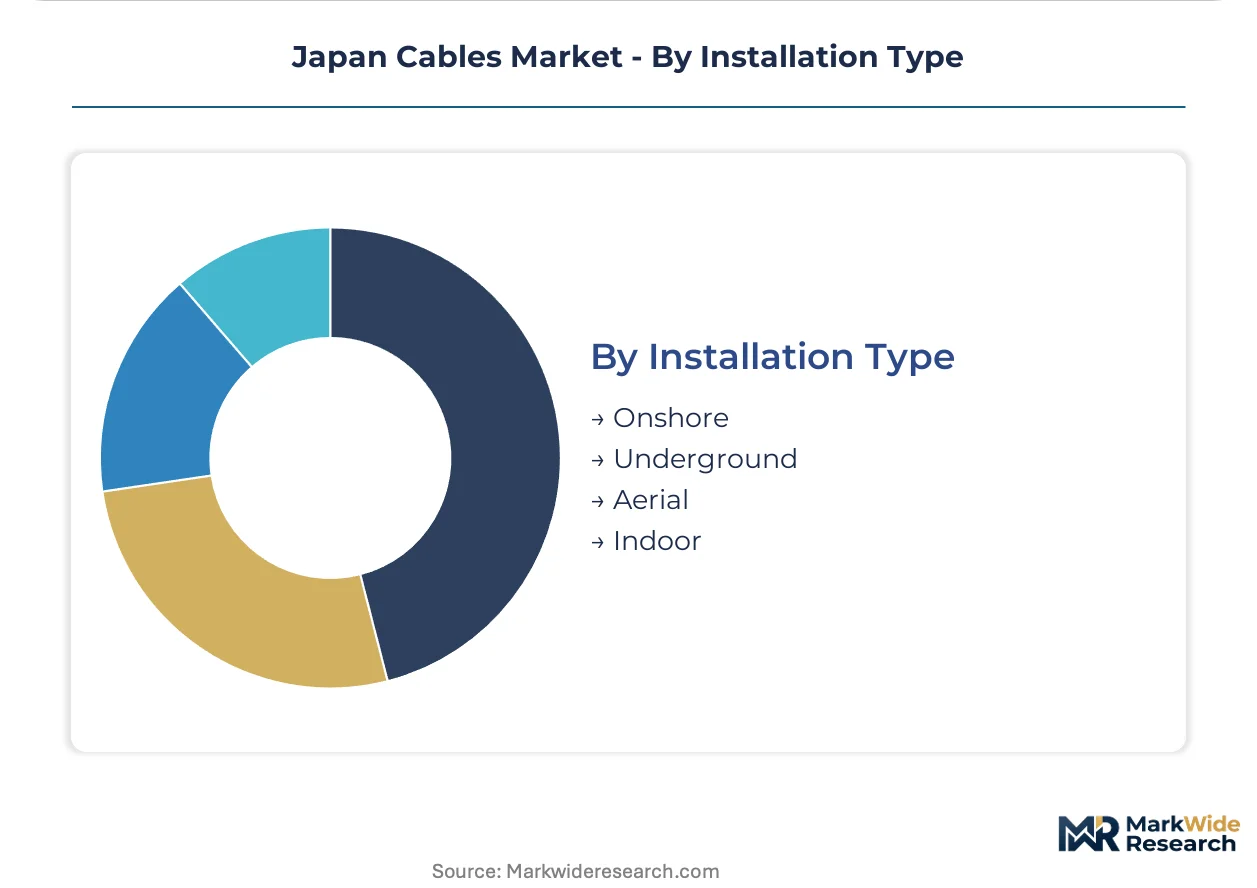
Right-of-way economics favor aerial and indoor methods, while technical requirements push underground and onshore submarine deployment.
- Underground:Trench-laid power and fiber systems in dense urban corridors, facing escalating land acquisition costs that compress margins on conventional high-amperage designs.
- Onshore:Land-based submarine cable landing stations and converter platforms for offshore wind interconnection, specifying SiC-compatible termination hardware.
- Aerial:Pole-mounted fiber and power distribution in rural Tohoku and Hokkaido prefectures, leveraging existing utility infrastructure.
- Indoor:Building-grade cabling for smart grid retrofits and EV charging infrastructure under GX League decarbonization procurement guidelines.
Underground methods carry the largest installed base. Onshore installations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo-Yokohama's data center corridor and industrial belt generates the heaviest cable procurement volumes in Japan, with metropolitan fiber densification and power grid reinforcement projects concentrating demand across the Kanto region.
Kanto
NTT's 10G-PON backbone upgrades and smart building retrofits under METI's GX League initiative drive multi-fiber ribbon and low-loss power cable procurement. The Industrial Safety and Health Act mandates fire-resistant sheathing for commercial projects in Tokyo's dense urban core. Yokohama's industrial corridor anchors high-voltage submarine cable landing stations for offshore wind interconnection.
Kansai
Osaka's manufacturing base and Kyoto's precision equipment sector sustain demand for industrial automation cabling with quake-resistant routing specifications. METI's carbon-neutrality roadmap accelerates EV charging infrastructure deployment across commercial districts. The Osaka-Kobe industrial zone concentrates procurement of electromagnetic interference-shielded cables for smart factory networks.
Kyushu
Offshore wind farm interconnection mandates under renewable energy targets position Kyushu as the fastest-growing region for high-voltage submarine cable demand. The Electricity Business Act governs grid connection standards for distributed energy resources. Fukuoka's port facilities and coastal landing stations anchor submarine system converter platform construction.
Tohoku
Rural aerial fiber deployment and coastal wind farm projects split procurement between pole-mounted distribution and submarine interconnection systems. Post-disaster grid resilience investments under METI jurisdiction drive quake-resistant cable routing specifications. Sendai's reconstruction corridor and coastal prefectures concentrate renewable energy transmission infrastructure.
Chubu
Nagoya's automotive and aerospace manufacturing clusters sustain demand for high-temperature resistant industrial cabling. The PMDA's medical device oversight creates a premium segment for sterilization-resistant interconnects in healthcare equipment manufacturing. Toyota's supplier ecosystem anchors specialized cable assembly procurement for robotics and automation systems.
Japan Cables Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized alloy and preform niches. The vendor base clusters around integrated metal refining operations and captive optical fiber drawing capabilities. Three archetypes dominate: integrated conglomerates with smelting-to-cable operations, specialist fiber preform manufacturers, and regional extruders serving municipal infrastructure. Capacity reconfiguration between submarine systems and metropolitan fiber backbones represents the primary competitive maneuver, alongside domestic supply partnership consolidation to mitigate trade friction exposure.
Among Japan-based integrated producers, Sumitomo Electric Industries, Fujikura, and Furukawa Electric exemplify the captive refining archetype. These conglomerates occupy positions defined by backward integration into rare-earth-doped fiber supply chains and copper smelting operations that buffer metal price volatility. Their market presence anchors the premium tier for ultra-low-attenuation submarine fiber and 275 kV cross-linked polyethylene power systems.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Fujikura |
| Furukawa Electric |
| Prysmian Group |
| Nexans |
| LS Cable & System |
| Southwire Company |
| Corning |
| Finisar Corporation |
| Others |
Pricing and Supply Chain Analysis
Utility procurement officers at Japan's ten regional power companies anchor contract-based pricing for high-voltage submarine cables, locking in multi-year offtake agreements that buffer spot copper volatility while compressing margins for mid-tier extruders locked into spot market exposure.
Pricing Analysis
Copper and rare-earth preform costs pass through to end buyers via indexed contract adjustments, with integrated smelting operations at Sumitomo Electric and Furukawa Electric capturing margin insulation unavailable to non-integrated competitors. Price differentiation hinges on JIS certification tier and volume scale, with public procurement mandates excluding uncertified imports entirely. Pricing pressure intensifies in standard-grade power cables as regional extruders compete for municipal infrastructure contracts with limited technical differentiation. Construction firms exhibit highest price sensitivity due to fixed-bid project structures, while telecom providers absorb premium positioning for ultra-low-attenuation fiber.
Supply Chain Analysis
Direct-to-utility channels handle high-voltage submarine cable demand, with project-based contracting dominating renewable energy interconnection procurement. Geographic supply concentration rests in Japan, China, and South Korea for rare-earth-doped fiber preforms and copper cathode refining. Raw material dependencies center on copper cathodes, optical fiber preforms, and halogen-free compound sheathing resins. Tariff exposure on Chinese rare-earth imports elevates inventory risk for non-integrated manufacturers. Distribution runs through authorized distributors for municipal projects and direct sales teams for utility-scale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's cables market functions as a geographic-arbitrage play where domestic-Japanese supply partnerships command premium positioning against import-dependent competitors facing elevated trade friction exposure.
For Market Incumbents: Hedge copper price volatility through backward integration into smelting operations or long-term cathode offtake agreements with Australian and Chilean miners. Defend market position by deepening captive rare-earth fiber preform capabilities before METI's forthcoming grid code updates reshape conductor specifications. Prioritize certification maintenance across JIS C 3605 and JIS C 6802 tiers to preserve public procurement eligibility. For New Entrants and Emerging Players: Begin with medical device cabling segments under PMDA oversight, where sterilization-resistant fiber assemblies command premium margins with lower capital barriers than submarine system manufacturing. Target healthcare equipment suppliers in Chubu's Nagoya corridor as the most penetrable geography. Pursue qualification partnerships with established Japanese distributors to bypass JIS certification timelines. For Investors and Strategic Acquirers: Industrial conglomerates with captive refining assets are the most active acquirer in this space, seeking optical fiber preform specialists to secure supply chain control. Long-term viability favors integrated operations with demonstrated rare-earth traceability and quake-resistant routing R&D capabilities. Monitor METI's distributed energy resource grid code revisions as the critical signal for conductor specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive preform supply secures fiber margins against trade friction with China. |
| JIS Certification Investment | Mandatory compliance unlocks public procurement across municipal infrastructure projects. |
| Quake-Resistant Routing R&D | METI's forthcoming grid codes will mandate new conductor specifications nationwide. |
| Medical Device Cabling Qualification | PMDA oversight creates premium segment with sterilization-resistant assembly requirements. |
| Domestic Supply Partnership Consolidation | ESG disclosure requirements elevate supply chain transparency above landed cost in vendor selection. |
Research Methodology
Multiple input streams — executive interviews with cable manufacturing plant managers, utility procurement directors, and telecom network engineers; secondary validation through METI regulatory filings, JIS committee documentation, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Primary fieldwork engaged distribution channel partners and EPC contractors active in offshore wind interconnection projects. Secondary sources included Electricity Business Act amendments, Industrial Safety and Health Act provisions, and regional utility capex disclosures.
Historical shipment data was cross-referenced against panel input from cable industry technical directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user category, and installation method. CAGRs were derived from slope analysis of normalized historical trends adjusted for regulatory inflection points. Forecast inputs incorporated METI's carbon-neutrality roadmap milestones and NTT's 10G-PON deployment schedules.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting rare-earth import flows, force majeure events disrupting submarine cable laying operations, and accelerated substitution by wireless transmission technologies. Forecasts reflect base-case assumptions regarding regulatory timeline adherence and commodity price band stability. Periodic stress-testing of base assumptions is recommended given concentrated supply chain dependencies and evolving grid code requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Asia-Pacific Cable Joints Market
Cables
Copper Stranded Wire Market
Cables
North America Coaxial Cable Market
Cables
XLPE Cables Market
Cables
Submarine Cables Market
Cables
Class 1E Electric Cables Market
Cables
Copper Cabling Systems Market
Cables
Cable Assembly Market
Cables
Mexico Wires and Cables Market
Cables
FFC/FPC Jumper Cables Market
Cables
North America Patch Cable Market
Cables
Patch Cable Market
Cables
Instrumentation Cables Market
Cables
Cable Fault Locator Market
Cables
UK Cables Market
Cables
Twisted Pair Cable Market