
 Middle East Cable Market | 2026-2036
Middle East Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Cable Market Analysis
High-voltage direct current transmission technology is narrowing the efficiency gap between offshore renewable installations and onshore grid interconnections across the Arabian Peninsula. Ducab leverages backward integration into copper rod production to secure raw material throughput for Gulf utility tenders. Elsewedy Electric anchors its position through integrated EPC capabilities that bundle cable supply with substation construction. Prysmian Group competes on submarine cable expertise for inter-island and cross-border links.
Middle East cables are engineered conductors comprising metallic cores—copper or aluminum—insulated with cross-linked polyethylene or fire-retardant compounds, designed to transmit electrical power or optical signals across temperatures exceeding 90°C in desert environments. Fiber optic segments lead value contribution as Gulf states deploy 5G backhaul and smart grid monitoring networks. Underground installation categories command premium positioning due to urban densification in Dubai and Riyadh, where aerial routing faces right-of-way constraints. Power distribution end-use absorbs the largest volume share, though industrial segments in Jubail and Yanbu drive specialized armored cable requirements.
Saudi Standards, Metrology and Quality Organization (SASO) and UAE's Emirates Authority for Standardization and Metrology (ESMA) enforce fire-performance and low-smoke specifications that filter substandard imports from Asian suppliers. Gulf Cooperation Council harmonization initiatives are reducing technical barriers to cross-border cable trade. Stakeholders must monitor how carbon-border adjustment mechanisms and local content rules reshape sourcing economics for European and East Asian manufacturers serving regional tenders.
Market Dynamics
Renewable energy integration across Gulf utility grids is forcing rapid modernization of transmission infrastructure, with high-voltage direct current technology compressing project timelines for interconnection schemes.
Growth Catalysts
- Saudi Vision 2030 diversification mandates:Gigaproject developments in NEOM and the Red Sea are generating concentrated demand for fire-resistant medium-voltage distribution networks.
- Cross-linked polyethylene insulation advances:Desert-rated compounds rated above 90°C continuous operation are expanding service life expectations for underground installations in Dubai and Riyadh.
- UAE net-zero commitments:Emirates Authority for Standardization and Metrology specifications for halogen-free cables are filtering procurement standards across data center clusters.
Market Restraints
- Copper price volatility:Raw material swings compress margin predictability for manufacturers lacking backward integration into rod production.
- Asian import competition:Substandard cable shipments from unverified suppliers create price pressure at the low-specification end of the Gulf market.
- Right-of-way constraints:Aerial routing limitations in dense urban cores of Doha and Manama force costly underground conversion of existing networks.
Strategic Opportunities
- Qatar industrial zone expansion:Ras Laffan and Mesaieed petrochemical complexes are driving specialized armored cable requirements for hazardous environment installations.
- 5G backhaul fiber deployment:Smart grid monitoring convergence with telecommunications infrastructure is creating hybrid fiber-power specification demand.
- Gulf Cooperation Council harmonization:Technical barrier reduction initiatives are opening cross-border tender participation for certified regional manufacturers.
Industry Challenges
- Fire-performance certification timelines:SASO and ESMA testing protocols create extended approval cycles for new product introductions.
- HVDC integration complexity:Legacy alternating current substations require costly retrofitting to accommodate direct current interconnection schemes.
- Specialized installation workforce scarcity:Desert-rated cable jointing and termination skills remain concentrated among a limited contractor base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Cable Market |
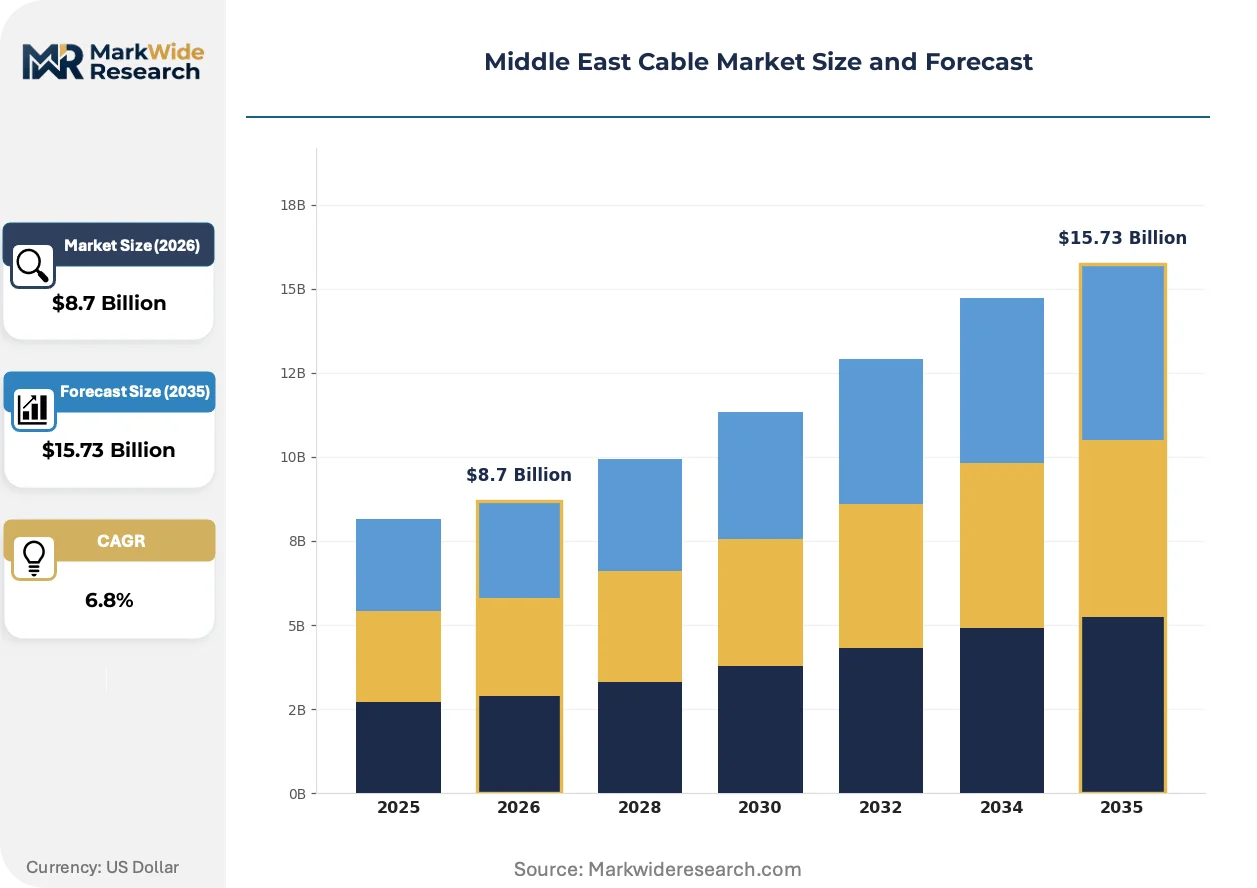
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Coaxial, Twisted Pair, Armored Installation Type: Underground, Overhead, Submarine, Aerial End User: Telecommunications, Power Distribution, Industrial, Residential Material: Copper, Aluminum, Polyvinyl Chloride, Others |
| Companies Covered | Oman Cables Industry, Bahra Electric, Ducab, Nexans, Prysmian Group, Saudi Cable Company, Elsewedy Electric, Alfanar, Riyadh Cables Group Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Cable Market Emerging Trajectories
Material science advances and procurement model evolution are compressing traditional specification cycles across Middle East cable markets. Three developments merit particular attention.
Extruded high-density polyethylene submarine cable sheathing is rendering obsolete traditional lead-sheathed designs for inter-island and offshore wind connections. Saudi Aramco and ADNOC procurement teams are specifying the lighter alternative for Red Sea and Arabian Gulf subsea links. The shift is compressing installation vessel day-rates and expanding route feasibility for longer crossings.
Emirates Authority for Standardization and Metrology fire-performance protocols are mandating low-smoke zero-halogen specifications for all high-occupancy buildings above twelve stories. The regulation forces reformulation of legacy PVC-insulated inventories across UAE distributor networks. Hospital and metro segments are absorbing premium positioning for certified product lines.
Integrated EPC contracting is consolidating cable procurement with substation construction across Saudi gigaproject tenders. Single-source accountability is displacing fragmented multi-vendor sourcing that separated material supply from installation warranty. NEOM and Red Sea Development Company packages exemplify the bundling pattern.
Middle East Cable Market Segmentation
Cable specification divergence across Middle East infrastructure projects demands granular segmentation. Procurement teams in Saudi Arabia and the UAE now source by installation environment and fire-performance tier rather than conducting commodity purchases.
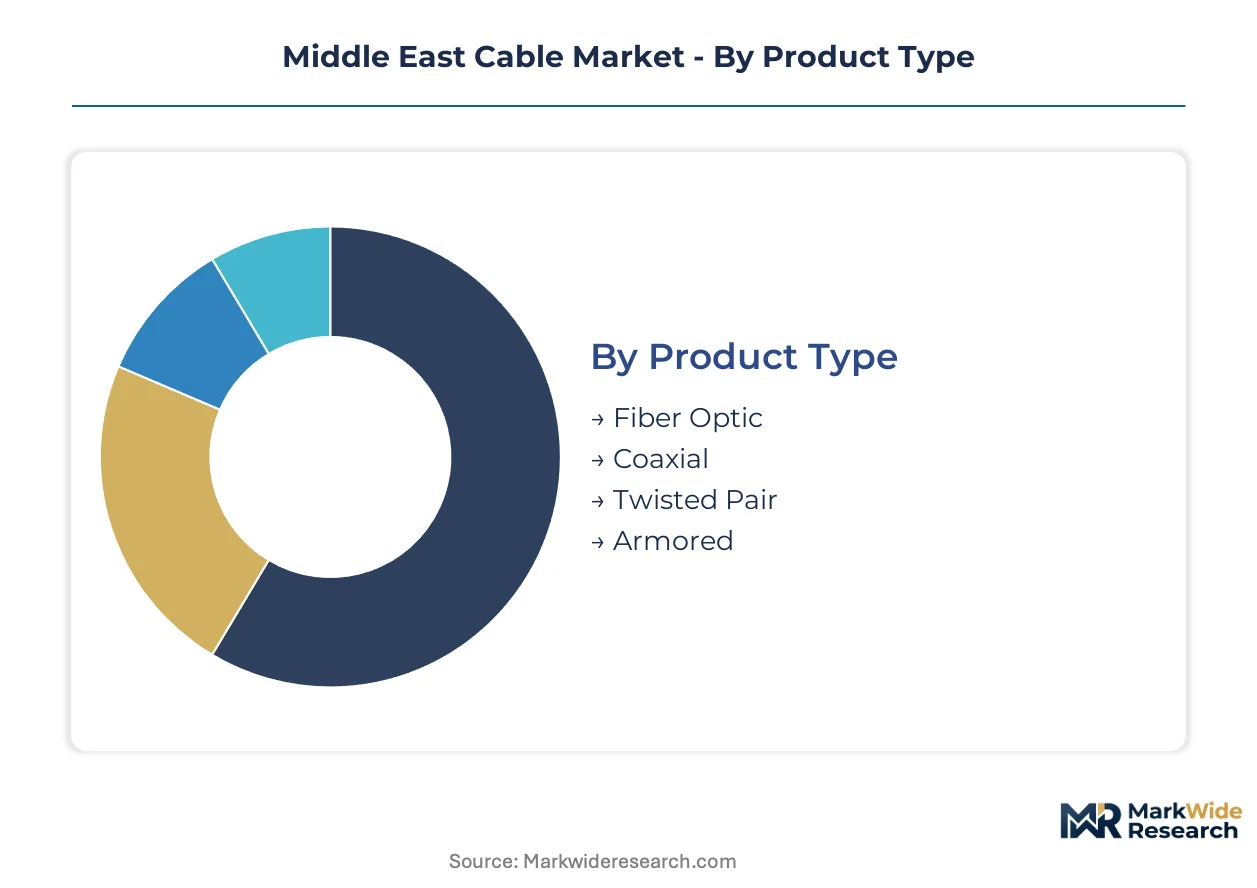
Product Type:
Application requirements dictate product selection across transmission, distribution, and signal-carrying functions.
- Fiber Optic:Glass-core silica fibers sheathed in polyethylene buffer tubes transmit terabit-scale data streams. 5G backhaul buildouts in Dubai Internet City and Riyadh's King Abdullah Financial District are absorbing ribbon cable and loose tube configurations for high-fiber-count deployments.
- Coaxial:Copper conductors with dielectric insulation and braided shielding maintain signal integrity across radio frequency applications. Legacy CATV networks in Kuwait and Bahrain continue phased upgrades while hybrid fiber-coaxial architectures persist in multi-dwelling installations.
- Twisted Pair:Insulated copper conductors in helical arrangements cancel electromagnetic interference for structured cabling. Commercial building automation in Doha's Lusail district specifies Category 6A and above for Power over Ethernet lighting and HVAC control integration.
- Armored:Steel wire or tape reinforcement protects against mechanical damage and rodent intrusion. Petrochemical facilities in Jubail Industrial City mandate interlocked armor for cable tray routing through corrosive process areas.
Fiber optic holds installed capacity. Armored is rotating up the share rankings.
Installation Type:
Geography and urban density determine routing methodology across the Arabian Peninsula.
- Underground:Direct-buried or duct-laid cables with water-blocking compounds and reinforced jackets withstand soil thermal resistivity. Riyadh's metro expansion and Dubai's district cooling networks are trenching medium-voltage feeders beneath congested arterial roads.
- Submarine:Polyethylene-sheathed designs with metallic armor and fiber optic elements bridge maritime distances. Inter-island links between Abu Dhabi's offshore artificial islands and cross-border Red Sea connections are specifying extruded HDPE alternatives to lead sheathing.
- Overhead:Aerial bundled conductors and messenger-supported designs span transmission corridors across desert terrain. Rural electrification in Oman's interior governorates employs spacer cable systems to reduce right-of-way width.
- Aerial:Pole-mounted distribution cables with weather-resistant jackets serve last-mile connectivity. Manama's historic districts face height restrictions that constrain aerial routing despite lower capital cost.
Underground dominates urban procurement. Submarine is climbing the fastest as offshore renewable interconnection scales.
End User:
Customer-type segmentation reveals divergent specification priorities across sectors.
- Power Distribution:Utility-scale transmission and distribution infrastructure carries bulk electricity across voltage classes from 11kV to 400kV. Saudi Electricity Company and Abu Dhabi Transmission and Despatch Company tenders specify XLPE-insulated designs for grid reinforcement and renewable integration.
- Industrial:Heavy manufacturing, petrochemical, and mining operations require specialized cable performance under mechanical and chemical stress. Ras Laffan and Mesaieed complexes in Qatar specify fire-resistant and mud-resistant armored constructions for hazardous area classification.
- Telecommunications:Fixed and mobile network operators deploy copper and fiber infrastructure for voice, data, and video services. Etisalat and stc Group data center interconnects are driving ribbon fiber and high-density copper trunking demand.
- Residential:Single-family and multi-unit housing developments specify standard power and communication cabling. NEOM's The Line and Red Sea Project developments are mandating halogen-free low-smoke specifications for all residential vertical construction.
Power distribution commands volume leadership. Industrial is gaining share fastest on petrochemical expansion.
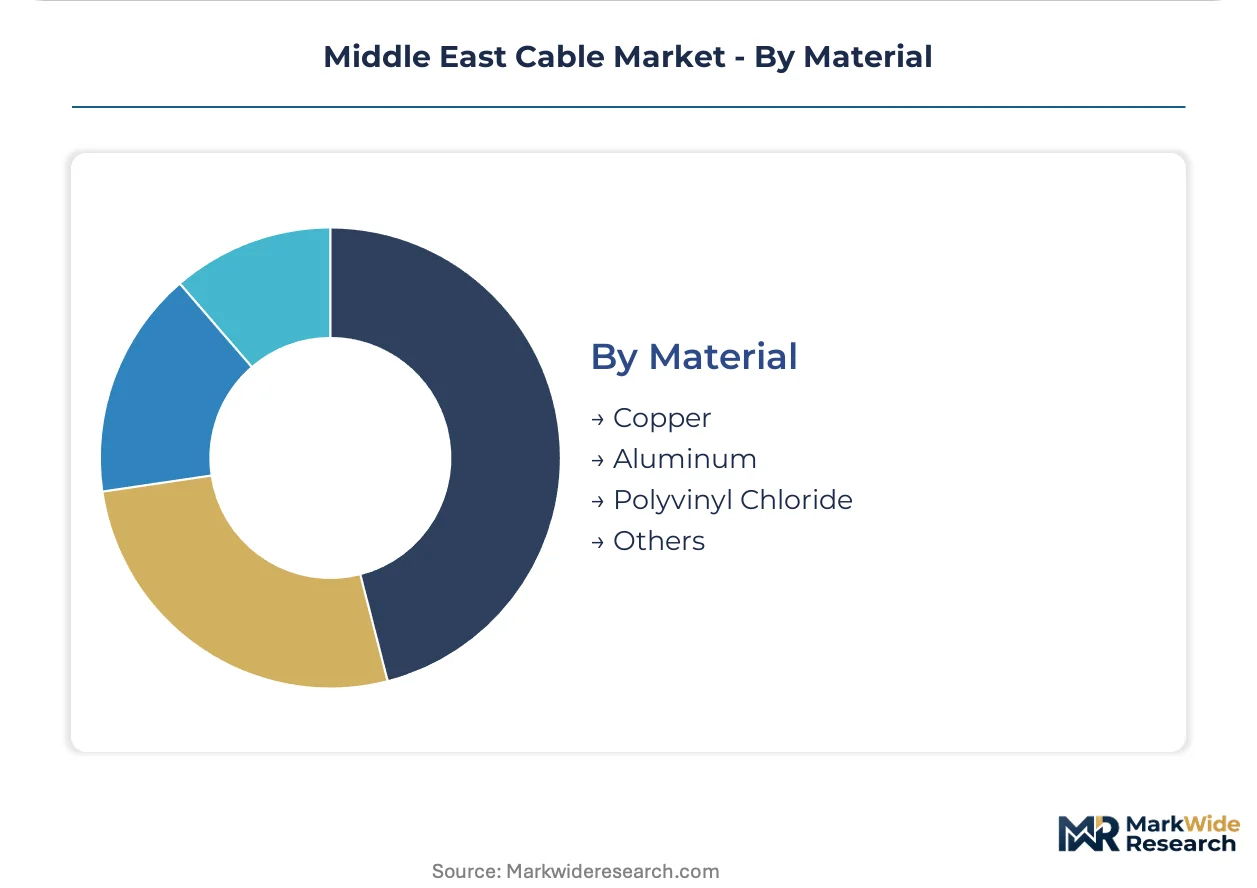
Material:
Cost tier and performance requirements segment raw material selection across conductor and insulation systems.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades deliver superior ampacity and corrosion resistance. Ducab's captive rod production in Abu Dhabi secures throughput for Gulf utility tenders despite London Metal Exchange volatility.
- Aluminum:Lightweight alloy conductors with steel core reinforcement reduce sag and structural loading for long-span transmission. 500kV overhead lines across Saudi Arabia's Empty Quarter employ aluminum conductor steel-reinforced designs for cost-optimized bulk power transfer.
- Polyvinyl Chloride:Plasticized and unplasticized formulations provide economical insulation and sheathing for general-purpose applications. SASO and ESMA fire-performance protocols are displacing legacy PVC in high-occupancy buildings above twelve stories.
- Others:Cross-linked polyethylene, ethylene propylene rubber, and low-smoke zero-halogen compounds address specialized thermal and safety requirements. Dubai Metro and Doha Metro rolling stock specifications mandate silicone-insulated cables for elevated temperature tolerance.
Copper retains premium positioning. Aluminum is rotating up the share rankings on transmission cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper rod shipments from UAE-based producers supply gigaproject contractors across the Arabian Peninsula, while Saudi-manufactured high-voltage cables feed cross-border grid interconnections into Jordan and Egypt.
Saudi Arabia
NEOM and Red Sea Development Company tenders are absorbing fire-resistant medium-voltage cable volumes for linear city construction. SASO mandates halogen-free specifications for all high-occupancy buildings above twelve stories. Riyadh's metro expansion and King Abdullah Financial District are trenching underground distribution networks beneath congested arterial corridors.
United Arab Emirates
Etisalat and du 5G backhaul deployments are driving ribbon fiber demand for data center interconnects. ESMA fire-performance protocols are filtering substandard imports from Asian suppliers. Dubai Internet City and Abu Dhabi's Masdar City are specifying low-smoke zero-halogen cables for smart grid monitoring integration.
Qatar
Ras Laffan and Mesaieed petrochemical complexes are generating specialized armored cable requirements for hazardous environment installations. Qatar General Electricity and Water Corporation tenders specify mud-resistant constructions for offshore platform links. Doha's Lusail district is deploying Category 6A twisted pair infrastructure for building automation systems.
Kuwait
Ministry of Electricity and Water grid reinforcement projects are procuring XLPE-insulated transmission cables for renewable integration. Kuwait Authority for Partnership Projects is bundling cable supply with substation EPC contracts. Al-Zour refinery and South Al-Mutlaa residential city are driving dual demand for industrial armored and halogen-free residential specifications.
Oman
Rural electrification in interior governorates employs aluminum conductor steel-reinforced designs for cost-optimized bulk power transfer across desert terrain. Oman Cables Industry capacity expansion targets export positioning into East African markets. Duqm Special Economic Zone and Salalah port modernization are absorbing submarine cable assemblies for inter-island links.
Middle East Cable Market Vendor Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive copper rod production and bundled EPC capabilities. Three strategic archetypes dominate: Gulf-based producers with backward integration into raw materials, European specialists with submarine cable expertise, and Egyptian contractors with integrated construction bundling. Competitive moves center on capacity expansion for gigaproject throughput and strategic partnerships for HVDC technology licensing.
Among UAE-based producers, Ducab exemplifies the backward-integrated archetype with captive copper rod supply, while Elsewedy Electric anchors the bundled EPC contractor tier. Prysmian Group represents European submarine specialization for offshore interconnections. These three occupy distinct competitive positions without direct overlap in core capability sets.
| Leading Market Players |
|---|
| Oman Cables Industry |
| Bahra Electric |
| Ducab |
| Nexans |
| Prysmian Group |
| Saudi Cable Company |
| Elsewedy Electric |
| Alfanar |
| Riyadh Cables Group Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Asian cable manufacturing is compressing margin structures for Gulf-based producers while simultaneously creating procurement leverage for Saudi and UAE utility buyers negotiating long-term offtake agreements. This utilization imbalance rewards backward-integrated manufacturers with captive copper rod supply while forcing merchant producers toward price-competitive standard-specification segments.
Pricing Analysis
Current-generation XLPE-insulated medium-voltage cables command substantial premia over prior-generation PVC designs, while next-generation halogen-free low-smoke compounds are establishing new price ceilings in high-occupancy building specifications. Pricing stratifies across premium, standard, and economy tiers based on fire-performance certification grade and volume scale. Cost compression in the standard tier is intensifying because Asian import competition floods the low-specification end of the market. Industrial petrochemical buyers exhibit lowest price sensitivity due to hazardous-area certification requirements, while residential developers in secondary Gulf markets remain most price-sensitive.
Supply Chain Analysis
Export control regimes on high-voltage direct current converter technology limit technology transfer to Gulf manufacturing facilities, constraining localization of advanced transmission cable production. Geographic supply concentration centers on China for copper rod and insulated wire, South Korea for specialty compounds, and Germany for HVDC submarine cable engineering. Raw material dependencies rest on Chilean copper cathode, Qatari liquefied natural gas for compound manufacturing energy feedstock, and Saudi petrochemical derivatives for polyethylene insulation. Single-source vulnerability in specialty compound formulation creates supply chain risk. Distribution runs through authorized distributor networks serving contractor and utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the Middle East cable market as gigaproject procurement unbundles from legacy utility frameworks, creating specialized niches for fire-performance-certified and submarine-capable manufacturers. NEOM and Red Sea Development Company tender structures reward single-source accountability over fragmented multi-vendor sourcing.
For Market Incumbents: Pre-empt Asian import encroachment by accelerating SASO and ESMA certification timelines for next-generation halogen-free product lines. Defensive consolidation through captive copper rod capacity expansion in Abu Dhabi and Jeddah industrial zones protects margin structures against London Metal Exchange volatility. Threat substitution from unverified Asian suppliers necessitates channel control investments with authorized distributor exclusivity arrangements. For New Entrants and Emerging Players: Qatar's Ras Laffan and Mesaieed petrochemical complexes represent underpenetrated demand for mud-resistant armored cable specifications. White-space targets include hybrid fiber-power cable for 5G-smart grid convergence and extruded HDPE submarine sheathing for Red Sea inter-island links. Go-to-market angle should emphasize EPC bundling partnerships with Saudi and UAE construction consortiums lacking integrated electrical installation capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated regional manufacturers with captive raw material supply and established Gulf utility relationships. Long-term viability over the coming decade hinges on HVDC technology licensing access and gigaproject order book depth. Acquisition target archetype: mid-cap cable producers with dormant fire-performance certification pipelines. Signal to watch is SASO approval cycle acceleration for low-smoke zero-halogen formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Ducab's captive Abu Dhabi smelter secures raw material throughput for Gulf utility tenders. |
| HVDC Technology Licensing Agreement | European submarine specialists enable Gulf manufacturers to bid cross-border grid interconnection schemes. |
| Fire-Performance Certification Acceleration | SASO and ESMA fast-track approval compresses product introduction timelines for halogen-free specifications. |
| Integrated EPC Contracting Capability | Elsewedy Electric bundles cable supply with substation construction for NEOM single-source accountability. |
| Submarine Cable Capacity Expansion | Extruded HDPE sheathing investments target Red Sea and Arabian Gulf offshore renewable connections. |
Methodological Framework
Desk research of customs trade databases, utility procurement registries, and standards body technical publications preceded structured interviews with cable procurement officers at Saudi Electricity Company and Abu Dhabi Transmission and Despatch Company, EPC project directors at NEOM and Red Sea Development Company, compound formulation specialists at Ducab and Saudi Cable Company, and distributor network managers across Dubai and Riyadh. Secondary validation drew from SASO technical regulations, ESMA product conformity schemes, Gulf Cooperation Council technical barrier reduction initiatives, and London Metal Exchange copper price series. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated against manufacturer capacity utilization disclosures.
Assumptions held fixed across the modeling period include continued Gulf Cooperation Council customs union enforcement, stable copper-aluminum price ratio bands, and persistent SASO-ESMA regulatory harmonization trajectory. Variables tested across sensitivity scenarios encompass gigaproject execution pace, HVDC interconnection project approval timelines, and Asian import penetration rates. Segmentation dimensions modeled span product type, installation environment, end-user sector, and conductor material composition. CAGRs were derived from regression-weighted historical shipment data and project-backed forward demand curves. Industry-specific forecast inputs include Saudi Vision 2030 capital commitment schedules and UAE net-zero pathway grid reinforcement targets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese manufacturers or accelerated European HVDC technology licensing to Gulf joint ventures would shift outcomes. Material shifts in copper price volatility regimes, gigaproject suspension or restructuring, or Gulf Cooperation Council tariff reconfiguration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Electric Vehicle Cables Market
Cables
Downhole Cables Market
Cables
Cable Testing Market
Cables
Submarine Cables Market
Cables
Cable Market
Cables
Cable Trunking Market
Cables
High-Temperature Superconducting Cables Market
Cables
Mexico Wires and Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Low-Temperature Cable Market
Cables
Patch Cable Market
Cables
Power Cable Accessories Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market