
 SATCOM Transceivers Market | 2026-2036
SATCOM Transceivers Market Size, Share, and Industry Trends Forecast 2026-2036
SATCOM Transceivers Market Analytics
The performance gap between radiation-hardened military-grade transceivers and commercial off-the-shelf units is realigning procurement strategies across satellite ground segment vendors. AnaCom, Inc. leverages its heritage in high-frequency block upconverters for defense applications. ACORDE Technologies S.A. specializes in compact frequency converters for airborne and maritime platforms. Comtech EF Data Corporation dominates commercial communication channels with scalable power amplifier architectures.
SATCOM transceivers are radio frequency subsystems that convert intermediate frequency signals to microwave bands for satellite uplink and downlink, typically operating across C, Ku, Ka, and X-band spectra with noise figures below 1.5 dB in low-noise block configurations. These devices enable bidirectional communication between earth stations and orbital assets for voice, data, and video transmission. Military communication applications anchor premium pricing through hardened specifications and sovereign security requirements, while commercial communication segments extend volume scale via standardized Ku and Ka-band terminals. Digital and beamforming technologies displace legacy analog architectures in next-generation phased array terminals, though hybrid architectures persist in retrofit installations where backward compatibility governs procurement.
The U.S. Federal Communications Commission governs spectrum allocation and equipment authorization for commercial SATCOM terminals, while the European Space Agency coordinates procurement standards for ground segment interoperability across member states. Japan's Ministry of Economy, Trade and Industry (METI) directs national space industrial policy through JIS standards alignment and domestic manufacturing incentives. Stakeholders must weigh sovereign supply chain requirements against commercial scale economics when positioning transceiver portfolios across defense and telecommunications verticals.
Market Dynamics
Defense procurement offices and commercial constellation operators are simultaneously demanding multi-orbit terminals capable of seamless LEO-to-GEO handoff, forcing transceiver vendors to abandon single-band architectures and absorb substantial R&D overhead before volume economics materialize.
Growth Catalysts
- Ka-band spectrum liberalization:The U.S. Federal Communications Commission's streamlined equipment authorization for non-geostationary satellite systems accelerates terminal deployment for broadband service providers seeking high-throughput connectivity.
- Maritime connectivity mandates:International Maritime Organization safety regulations now require redundant satellite links for vessel tracking and crew welfare, expanding addressable hardware demand across commercial shipping fleets.
- Software-defined radio architectures:Reconfigurable baseband processing enables single transceiver platforms to serve multiple orbital regimes, reducing unit economics for ground segment operators managing mixed constellations.
Market Restraints
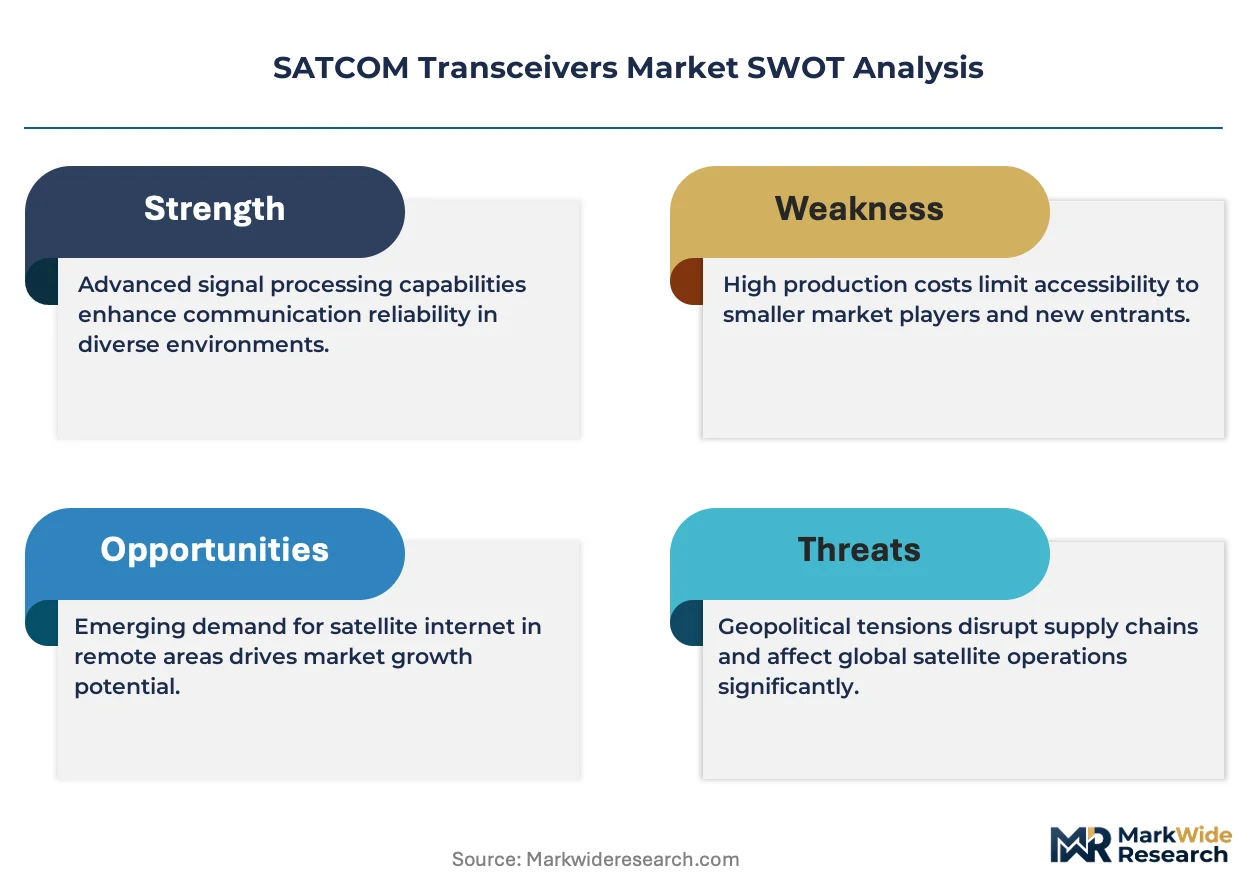
- Gallium nitride substrate scarcity:Defense-prioritized foundry capacity at U.S. and Japanese semiconductor fabs limits commercial access to high-efficiency power amplifier components.
- ITAR-controlled component dependency:U.S. State Department export restrictions on radiation-hardened integrated circuits fragment supply chains for non-U.S. system integrators.
- Thermal management complexity:High-power Ka-band operation in compact form factors exceeds passive cooling limits, forcing expensive active thermal solutions or derated performance specifications.
Strategic Opportunities
- African terrestrial backhaul substitution:National telecom regulators in Nigeria and Kenya are licensing satellite service providers to bypass fiber deployment gaps in rural infrastructure.
- LEO constellation terminal standardization:European Space Agency procurement frameworks are converging on interoperable reference designs, enabling multi-vendor competition for ground segment contracts.
- Hybrid RF-optical payloads:Converged transceiver architectures combining radio frequency and free-space optical links address emerging demand from scientific and intelligence community users requiring low-probability-of-intercept transmission.
Industry Challenges
- Microwave engineering talent scarcity:Specialized expertise in millimeter-wave circuit design concentrates at a handful of defense contractors and university research centers, constraining vendor scaling.
- Multi-orbit certification timelines:Simultaneous FCC, ETSI, and national type-approval processes for terminals operating across LEO, MEO, and GEO orbits extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SATCOM Transceivers Market |
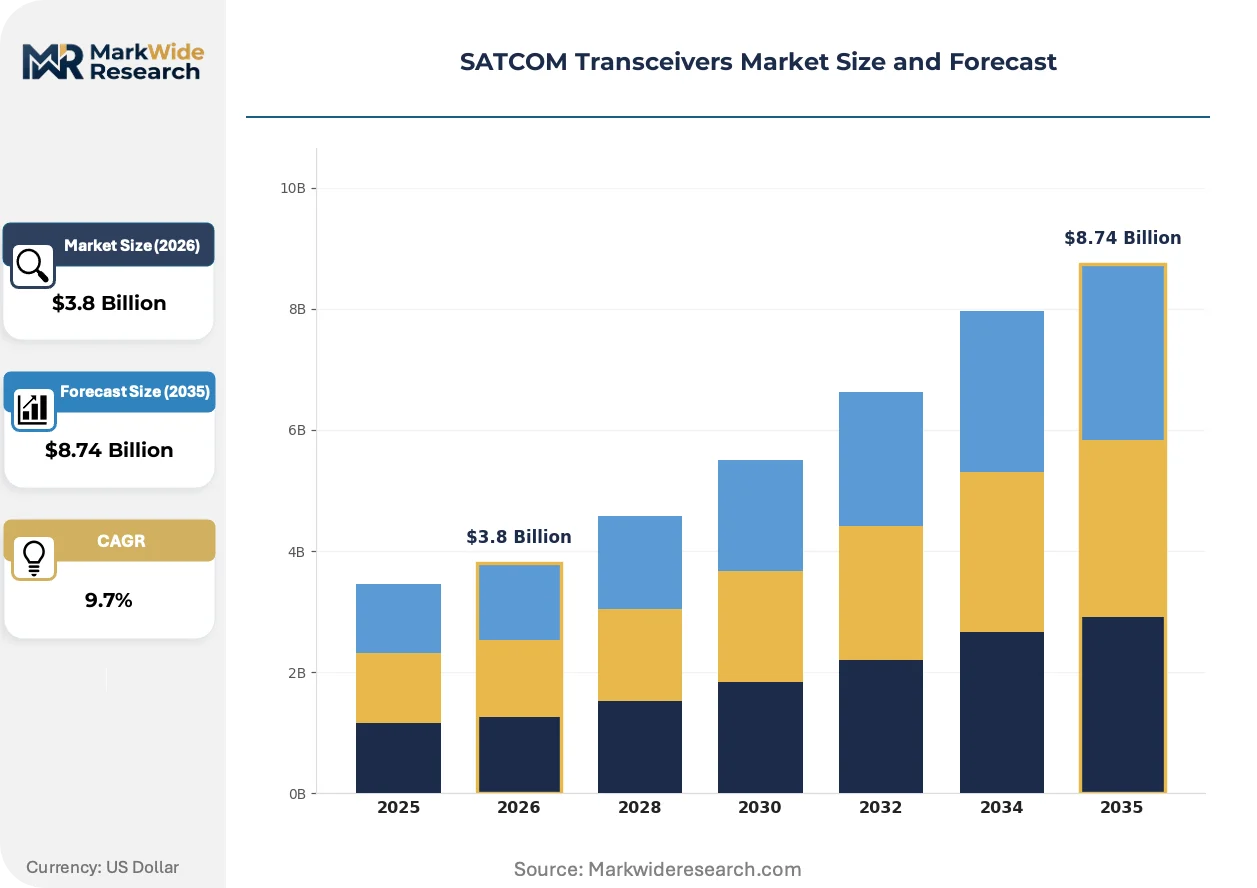
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Upconverter, Low Noise Block, Power Amplifier, Frequency Converter Application: Military Communication, Commercial Communication, Broadcasting, Remote Sensing Technology: Analog, Digital, Hybrid, Beamforming End User: Defense Sector, Telecommunications, Space Agencies, Research Institutions |
| Companies Covered | AnaCom, Inc., ACORDE Technologies S.A., Advantech Wireless Technologies, Inc., Comtech EF Data Corporation, ND SatCom GmbH, CPI International Inc, REMEC Broadband Wireless Networks LLC, Arralis Ltd., Amplus Communication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SATCOM Transceivers Market Evolving Landscape
Digital beamforming and solid-state power amplification are converging to eliminate mechanically steered antenna platforms, compressing terminal size and maintenance requirements while expanding addressable mobility applications.
Gallium nitride monolithic microwave integrated circuits are overtaking gallium arsenide legacy devices in high-power amplifier stages. Military airborne terminals and maritime stabilized platforms are adopting GaN MMICs for their superior power-added efficiency and thermal performance. This transition is compressing amplifier module count and cooling system mass in next-generation phased array designs.
The European Space Agency's Ground Segment Reference Architecture mandates interoperability protocols for multi-vendor terminal integration across member state procurement programs. Industrial consequence includes mandatory software interface standardization that prevents proprietary lock-in. Prime contractors in Germany, France, and Italy are restructuring subsystem sourcing to accommodate open-architecture compliance.
Consolidated procurement by mega-constellation operators is displacing fragmented service-provider purchasing patterns. SpaceX and Amazon's Project Kuiper are negotiating multi-year volume commitments directly with transceiver manufacturers, bypassing traditional systems integrator channels. This concentration is most visible in U.S. and European ground segment contracts where operator-owned terminal fleets now exceed third-party hardware deployment.
SATCOM Transceivers Market Segmentation
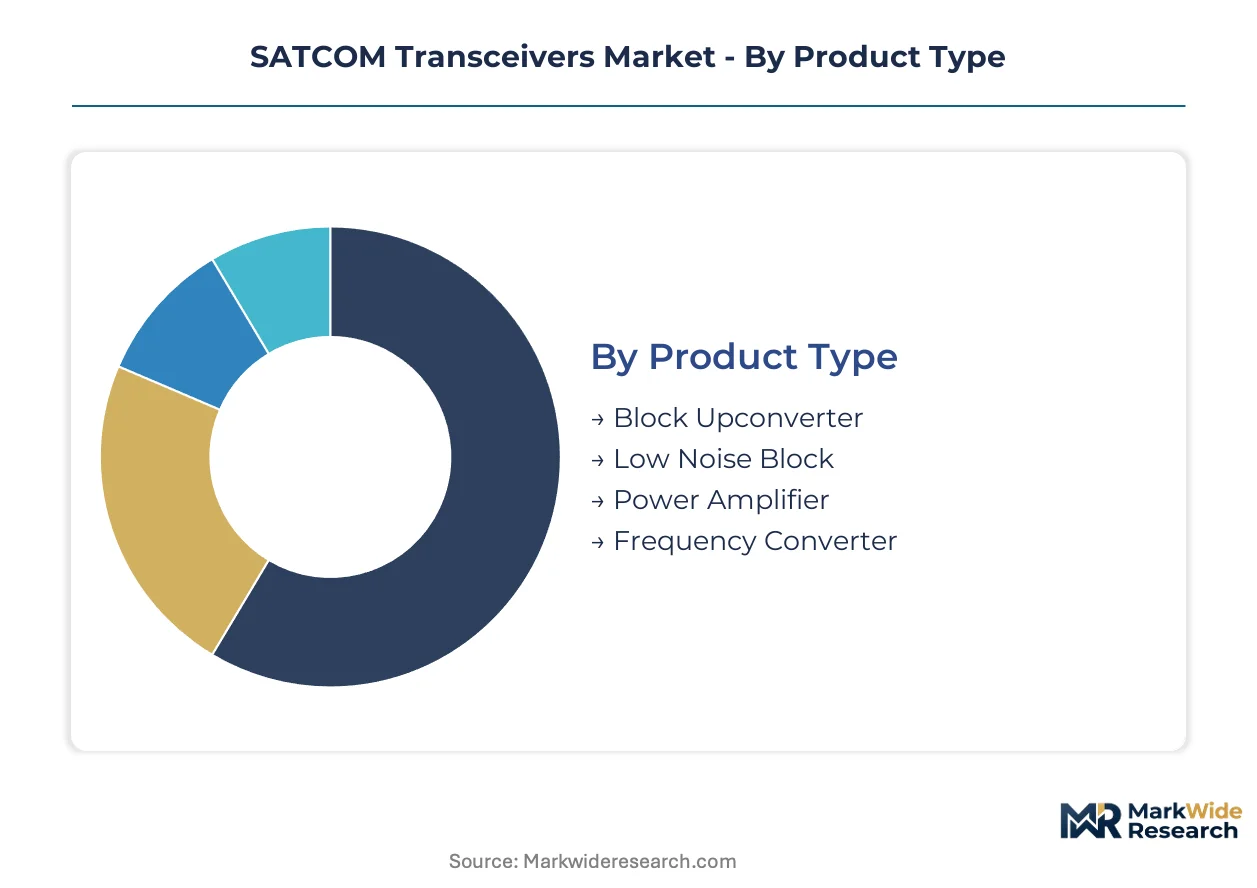
SATCOM transceiver segmentation reveals how procurement patterns split between hardened defense specifications and volume commercial terminals. Product architecture, frequency band, and end-use certification requirements create distinct commercial lanes with divergent margin structures and customer concentration.
Product Type:
Customization intensity spans from fully configurable military-grade units to standardized commercial modules, with integration complexity driving vendor specialization decisions.
- Block Upconverter:Frequency translation modules convert intermediate frequency signals to microwave bands for satellite uplink. Defense procurement offices in the United States prioritize radiation-hardened variants with integrated filtering for electronic warfare resilience.
- Power Amplifier:Solid-state and traveling-wave tube architectures deliver output power from watts to kilowatts for link budget requirements. Gallium nitride monolithic microwave integrated circuits are displacing gallium arsenide in Ka-band terminals where thermal efficiency governs form factor constraints.
- Low Noise Block:Downconverter assemblies with noise figures below 1.5 dB enable weak signal reception from geostationary and low-earth orbit assets.
- Frequency Converter:Broadband translation subsystems support multi-band terminals operating across C, Ku, Ka, and X-band spectra.
Most installed capacity flows through Power Amplifier segments. Expansion is steepest in Block Upconverter configurations for multi-orbit military terminals.
Application:
End-use diversity stretches from sovereign security programs with single-source procurement to commercial service providers negotiating multi-year volume commitments.
- Military Communication:Hardened transceivers with anti-jam waveforms and low-probability-of-intercept modes anchor premium pricing tiers. The U.S. Department of Defense and European defense ministries mandate ITAR-controlled component traceability and domestic foundry sourcing for strategic satellite uplink infrastructure.
- Commercial Communication:Standardized Ku and Ka-band terminals serve broadband service providers and maritime connectivity operators. SpaceX and Amazon's Project Kuiper are consolidating procurement through direct manufacturer negotiations, bypassing traditional systems integrator channels.
- Broadcasting:High-power amplifiers and redundant upconverter chains support television and radio distribution networks.
- Remote Sensing:Precision frequency stability and phase noise specifications enable synthetic aperture radar and earth observation downlink applications.
Commercial Communication carries the largest installed base. Military Communication is gaining share fastest as defense ministries modernize satellite uplink infrastructure.
Technology:
Architecture maturity ranges from legacy analog implementations to software-defined platforms requiring substantial firmware development investment.
- Digital:Software-defined radio architectures with reconfigurable baseband processing enable single hardware platforms to serve multiple orbital regimes and waveform standards. Ground segment operators managing mixed LEO, MEO, and GEO constellations favor digital implementations for operational flexibility.
- Beamforming:Phased array antennas with solid-state power amplification eliminate mechanical steering mechanisms, compressing terminal size for airborne and maritime mobility applications. Digital beamforming converges with gallium nitride MMICs to reduce cooling system mass in next-generation designs.
- Analog:Legacy architectures persist in retrofit installations where backward compatibility governs procurement decisions.
- Hybrid:Mixed-signal implementations bridge analog RF front-ends with digital baseband processing for cost-sensitive deployments.
Analog systems retain the deepest installed base. Beamforming is climbing the fastest as mobility applications demand electronically steered apertures.
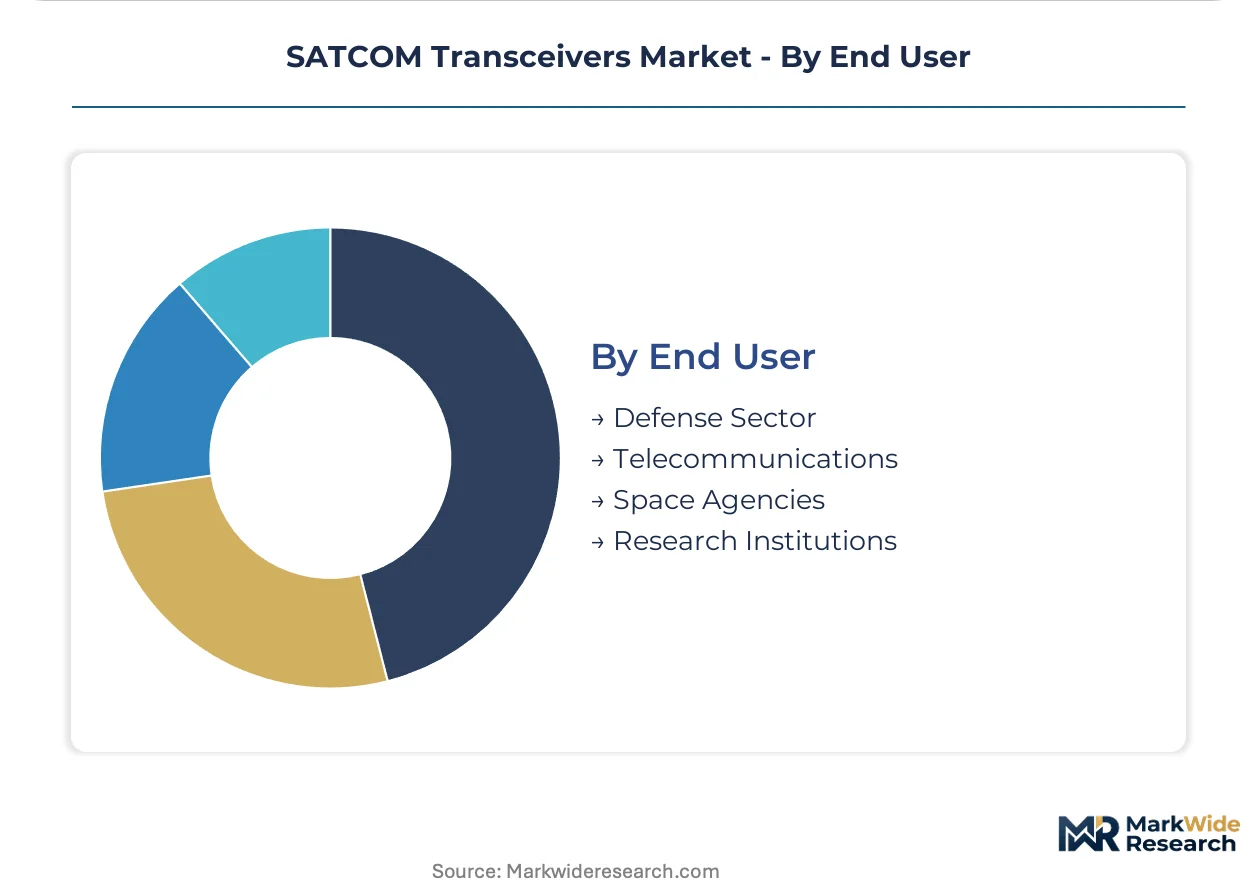
End User:
Customer concentration varies from fragmented research procurement to consolidated telecommunications operator spending with multi-year visibility.
- Defense Sector:Sovereign security requirements mandate domestic manufacturing, radiation-hardened specifications, and secure supply chain certification. The U.S. State Department's ITAR restrictions fragment procurement for non-U.S. system integrators seeking comparable performance tiers.
- Telecommunications:National telecom regulators in Nigeria and Kenya are licensing satellite service providers to bypass fiber deployment gaps, expanding addressable hardware demand for rural backhaul substitution.
- Space Agencies:European Space Agency procurement frameworks mandate interoperability protocols and open-architecture software interfaces across member state ground segment programs.
- Research Institutions:Scientific and intelligence community users require hybrid RF-optical payloads for low-probability-of-intercept transmission in experimental configurations.
Telecommunications accounts for the largest installed capacity. Defense Sector is expanding most quickly as ministries prioritize sovereign satellite infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains deeper sovereign satellite infrastructure commitments than Japan, though both nations channel procurement through distinct regulatory frameworks governing spectrum allocation and domestic manufacturing incentives.
United States
The U.S. Department of Defense accelerates hardened transceiver procurement for multi-orbit military terminals while SpaceX and Amazon's Project Kuiper consolidate ground segment contracts through direct manufacturer negotiations. The Federal Communications Commission streamlines equipment authorization for non-geostationary satellite systems under Ka-band spectrum liberalization policies. Industrial activity concentrates in California and Colorado aerospace corridors where defense primes and commercial constellation operators co-locate engineering talent.
Germany
German defense ministries prioritize sovereign satellite uplink infrastructure modernization through radiation-hardened procurement specifications. The European Space Agency coordinates procurement standards for ground segment interoperability across member states, mandating open-architecture software interfaces. Bavaria and North Rhine-Westphalia host subsystem vendors restructuring sourcing to accommodate ESA compliance requirements for multi-vendor terminal integration.
Japan
Japan's Ministry of Economy, Trade and Industry directs national space industrial policy through JIS standards alignment and domestic manufacturing incentives for satellite ground segment hardware. METI procurement frameworks emphasize backward compatibility with legacy analog architectures in retrofit installations. Tokyo and Nagoya industrial clusters concentrate microwave engineering expertise for millimeter-wave circuit design in next-generation phased array terminals.
United Kingdom
UK defense procurement offices demand ITAR-controlled component traceability for strategic satellite infrastructure while commercial operators seek multi-orbit terminal capabilities. National telecom regulators license satellite service providers to address rural connectivity gaps bypassing fiber deployment limitations. Harwell Space Cluster and Surrey research corridors anchor scientific and intelligence community demand for hybrid RF-optical payload configurations.
France
French aerospace primes secure ESA ground segment contracts requiring interoperability protocols across European member state procurement programs. The country's national space regulator enforces equipment authorization standards converging with ETSI type-approval processes for terminals operating across LEO, MEO, and GEO orbits. Toulouse and Paris-Saclay aerospace clusters concentrate digital beamforming and solid-state power amplification engineering for electronically steered aperture designs.
SATCOM Transceivers Market Competitive Landscape
Top-tier vendors anchor defense and commercial communication channels with hardened specifications and scalable power amplifier architectures, while mid-tier specialists occupy frequency converter and compact airborne platform niches. The vendor base organizes across three strategic archetypes: defense heritage contractors with radiation-hardened product lines, commercial volume manufacturers serving mega-constellation operators, and subsystem specialists focused on block upconverter and low-noise block configurations. Competitive positioning depends on multi-orbit certification capabilities and gallium nitride monolithic microwave integrated circuit integration. Momentum concentrates through direct procurement negotiations with constellation operators and strategic partnerships bridging analog legacy and digital beamforming transitions.
Within the defense heritage tier, AnaCom, Inc. and CPI International Inc exemplify vendors leveraging high-frequency block upconverter expertise for military applications. ACORDE Technologies S.A. occupies a specialist position among compact frequency converter providers for airborne and maritime platforms. Comtech EF Data Corporation anchors the commercial communication vector with scalable power amplifier architectures serving broadband service providers. These three companies represent distinct competitive positioning strategies: sovereign security procurement, mobility platform specialization, and commercial volume scale.
| Leading Market Players |
|---|
| AnaCom, Inc. |
| ACORDE Technologies S.A. |
| Advantech Wireless Technologies, Inc. |
| Comtech EF Data Corporation |
| ND SatCom GmbH |
| CPI International Inc |
| REMEC Broadband Wireless Networks LLC |
| Arralis Ltd. |
| Amplus Communication |
| Others |
Value Network & Pricing Analysis
Gallium nitride wafer pricing indices cascade through SATCOM transceiver manufacturing tiers, compressing margins for commercial-grade power amplifier suppliers while defense contractors with captive foundry access preserve premium pricing power through ITAR-controlled component scarcity.
Pricing Analysis
Capacity additions in Japan and the United States are reshaping price floors for gallium nitride monolithic microwave integrated circuits, yet defense-prioritized foundry allocations sustain premium tiers for radiation-hardened specifications. Pricing stratifies across ITAR-certified military-grade, ESA-compliant commercial, and unlicensed economy terminals based on certification burden and thermal performance thresholds. Cost compression in commercial Ku-band modules intensifies as SpaceX and Amazon consolidate procurement through direct manufacturer negotiations. Commercial telecommunications operators exhibit highest price sensitivity, while defense ministries accept 3-5x premiums for sovereign supply chain traceability.
Supply Chain Analysis
Freight costs for precision microwave components from Japanese semiconductor fabs to European integration facilities have stabilized, though air-cargo premiums for ITAR-controlled integrated circuits persist. Manufacturing concentrates in the United States, Japan, and Germany where defense primes and commercial constellation operators co-locate engineering talent. Raw material dependencies center on gallium nitride substrates, aluminum nitride thermal management components, and radiation-hardened silicon germanium semiconductors. Single-source vulnerability at U.S. and Japanese foundries fragments procurement for non-U.S. system integrators. Distribution runs through prime contractor channels for military applications and direct OEM negotiations for mega-constellation terminal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SATCOM transceivers market functions as a geographic-arbitrage play where U.S. ITAR restrictions and Japanese METI domestic manufacturing incentives create 40-60% cost differentials for equivalent performance tiers across procurement jurisdictions.
For Market Incumbents: Hedge gallium nitride substrate scarcity through long-term offtake agreements with Japanese foundries or backward integration into thermal management component production. Defend margin position by accelerating multi-orbit certification timelines before ESA interoperability mandates commoditize open-architecture interfaces. Channel control through direct procurement relationships with SpaceX and Amazon insulates against systems integrator displacement. For New Entrants and Emerging Players: Capture African terrestrial backhaul substitution opportunities in Nigeria and Kenya where national telecom regulators license satellite providers to bypass fiber deployment gaps. Target compact frequency converter niches for airborne and maritime platforms where ACORDE Technologies S.A. heritage creates specialist positioning precedent. Go-to-market leverage rests on ESA open-architecture compliance as mandatory procurement filter across European member state programs. For Investors and Strategic Acquirers: Consolidation pressure builds where microwave engineering talent scarcity constrains vendor scaling and multi-orbit certification overhead eliminates sub-scale competitors. Long-term viability favors prime contractors with captive defense procurement relationships and gallium nitride MMIC integration capabilities. Acquisition target archetype: mid-tier block upconverter specialists with ESA compliance infrastructure and proven airborne platform qualification. Signal to watch: European Space Agency procurement framework adoption rates as interoperability mandate inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride MMIC Integration | GaN monolithic microwave integrated circuits displace gallium arsenide legacy devices in Ka-band power amplifier stages. |
| Multi-Orbit Certification Investment | Simultaneous FCC, ETSI, and national type-approval processes compress product launch cycles for LEO-to-GEO terminals. |
| Direct Constellation Procurement | SpaceX and Amazon negotiate multi-year volume commitments bypassing traditional systems integrator channels. |
| ESA Open-Architecture Compliance | European Space Agency mandates software interface standardization preventing proprietary lock-in across member states. |
| ITAR-Controlled Supply Chain Certification | U.S. State Department export restrictions fragment procurement for non-U.S. integrators seeking hardened performance tiers. |
Research Methodology
Multiple input streams — defense procurement officer interviews, commercial constellation operator technical assessments, and semiconductor foundry capacity disclosures — were reconciled against secondary validation from FCC equipment authorization databases, ESA procurement framework documents, and METI industrial policy filings. Primary fieldwork engaged satellite ground segment engineering directors, military communications procurement leads, and microwave component distribution channel managers. Secondary sources encompassed customs trade data for gallium nitride substrate flows, SEC 10-K disclosures from listed aerospace primes, and national space agency budget appropriations. Bottom-up terminal deployment estimates and top-down addressable market sizing were triangulated for convergence.
Historical shipment data across C, Ku, Ka, and X-band frequency configurations were cross-referenced against panel input from subsystem vendors and prime contractors to anchor growth trajectory assumptions throughout the forecast period. Segmentation modeling incorporated product type architecture, application certification requirements, technology maturity, and end-user procurement concentration. CAGRs were derived from unit economics analysis of gallium nitride MMIC cost curves and multi-orbit terminal adoption rates. Industry-specific forecast inputs included ESA interoperability mandate implementation timelines and ITAR-controlled component availability constraints.
Defense budget reallocation, commercial constellation launch delays, and gallium nitride foundry capacity expansion are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented procurement patterns and regulatory implementation schedules without contingency for geopolitical disruption or technology substitution. Stakeholders should weight assumptions against their own operating context and sovereign supply chain exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market