
 Submarine Cable System Market | 2026-2036
Submarine Cable System Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Cable System Market Analysis
Market Context
The EU Green Deal is pivoting submarine cable procurement toward lower-carbon installation methods and marine ecosystem assessments. NEC Corporation leverages its integrated marine survey capabilities to pre-empt regulatory compliance costs. Alcatel Submarine Networks anchors European supply through its Calais manufacturing base and deep-water installation fleet. SubCom, LLC competes on trans-Pacific route density where latency-sensitive cloud traffic concentrates.
Technical Definition and Segment Structure
A submarine cable system comprises fiber optic, copper, or hybrid conductor bundles sheathed in polyethylene and steel armor, laid across ocean floors by specialized vessels to transmit telecommunications and data signals between land-based stations. Fiber optic segments dominate long-haul routes due to terabit-scale capacity and minimal signal attenuation over transoceanic distances. Military application demand is accelerating as sovereign nations prioritize secure undersea communication networks independent of commercial infrastructure. Amplifier segments concentrate margin pools because erbium-doped fiber repeaters require precision manufacturing and proprietary power-feeding architectures.
Regulatory Framework
The International Cable Protection Committee coordinates with national regulators including the FCC in the United States and France's ANSN to establish cable corridor protections and landing station permitting timelines. ECHA's REACH framework governs submarine cable sheath polymer composition, restricting certain flame retardants and plasticizers in European waters. Stakeholders must monitor evolving seabed mining regulations that could restrict cable routing through polymetallic nodule zones in the Pacific Clarion-Clipperton Zone.
Market Dynamics
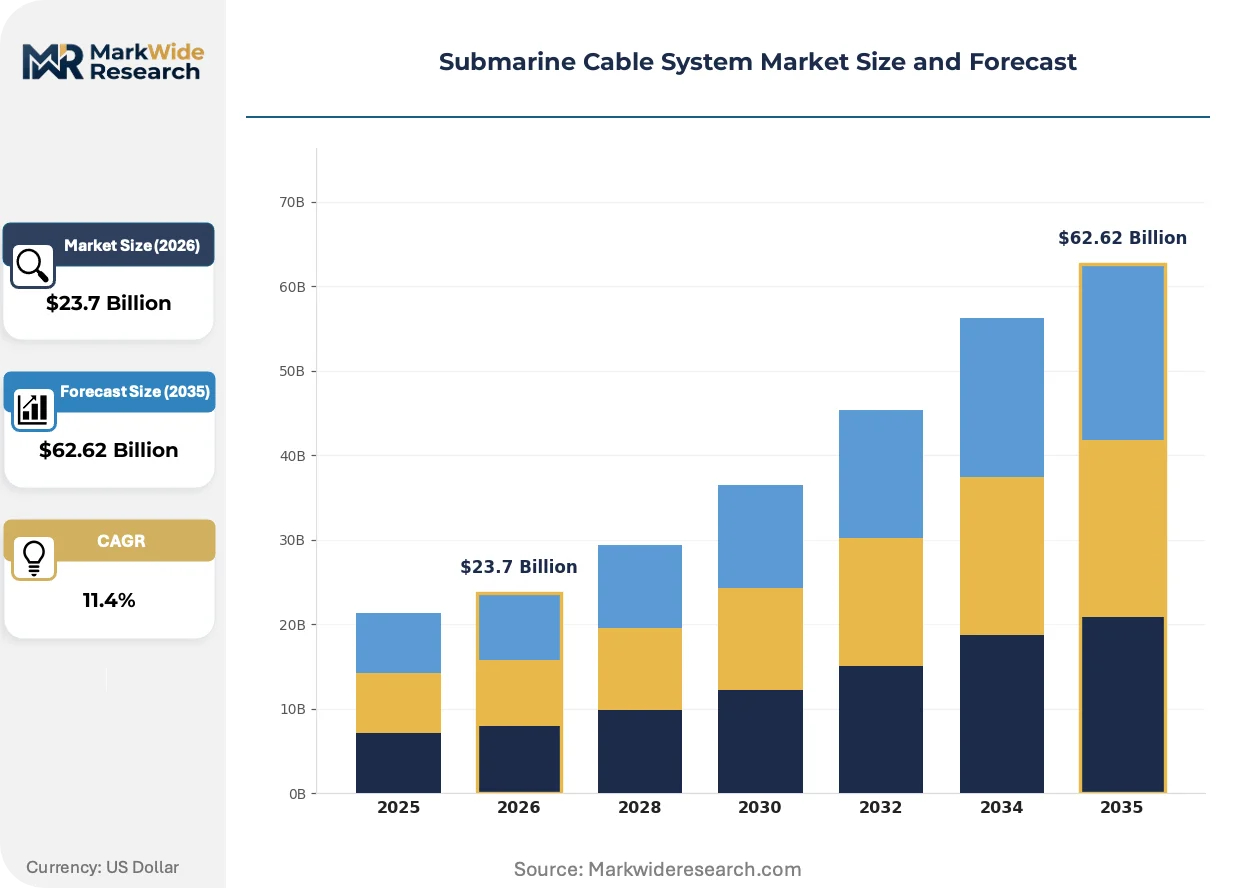
The submarine cable system market is experiencing structural pressure from hyperscaler-driven capacity expansion, as cloud service providers commission dedicated fiber pairs to support AI training clusters and data sovereignty mandates across multiple jurisdictions.
Growth Catalysts
- EU Green Deal procurement mandates:European cable tenders now require environmental impact assessments and low-carbon installation methods, accelerating demand for marine survey integration and vessel emission controls.
- Hyperscaler AI infrastructure buildouts:Cloud providers are contracting for multi-terabit capacity on trans-Pacific and Atlantic routes to interconnect distributed GPU clusters for generative AI workloads.
- Fiber optic technology maturation:Space-division multiplexing and advanced modulation formats are pushing per-fiber-pair capacity past 25 terabits, reducing unit transmission costs for long-haul routes.
Market Restraints
- Specialized vessel supply concentration:Cable-laying ship availability is constrained to fewer than 60 vessels worldwide, with booking lead times extending 18-24 months for deep-water installation campaigns.
- Copper and steel armor input volatility:Submarine cable sheathing relies on high-grade steel wire and copper conductors subject to commodity price swings and mill capacity allocation.
- Seabed mining regulatory friction:Emerging restrictions on polymetallic nodule extraction in the Clarion-Clipperton Zone threaten to eliminate preferred cable corridors through Pacific high-capacity routes.
Strategic Opportunities
- Underpenetrated African coastal connectivity:East and West African landing points remain underserved relative to traffic growth, creating demand for new cable systems linking Mombasa, Lagos, and Cape Town to European and Asian hubs.
- Arctic route activation:Melting ice conditions are opening seasonal installation windows for trans-Arctic cables connecting Northern Europe to East Asia via reduced latency paths.
- Power cable hybridization:Convergence of fiber optic telecommunications with subsea power transmission for offshore wind interconnectors creates bundled procurement opportunities with European energy utilities.
Industry Challenges
- Marine survey and route engineering talent scarcity:Specialized hydrographers and geotechnical seabed analysts command premium compensation, constraining project velocity for new cable consortia.
- Permitting timeline unpredictability:Coastal state landing station approvals vary from 12 to 48 months depending on local environmental review processes and indigenous consultation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Cable System Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Copper, Hybrid, Amplifiers Application: Telecommunication, Data Transmission, Military, Research Installation: Submarine, Terrestrial, Nearshore, Offshore End User: Government, Telecom Operators, Enterprises, Academic Institutions |
| Companies Covered | NEC Corporation, Hengtong Group, Alcatel Submarine Networks, LS Cable & System, NKT, Prysmian S.p.A, Nexans, ZTT International, SubCom, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Cable System Market Emerging Trajectories
Submarine cable architecture is pivoting toward software-defined capacity allocation and open cable specifications, decoupling wet plant infrastructure from terminal equipment procurement and enabling more flexible bandwidth trading between consortium members.
Space-division multiplexing with multi-core fiber is unifying previously separate capacity expansion strategies by enabling parallel transmission paths within a single cable sheath. Subsea operators are deploying this technology on high-density trans-Atlantic routes where duct space constraints limit new cable laying. The approach is compressing the traditional cycle of parallel cable builds by extending existing infrastructure lifecycles through fiber count multiplication rather than new system deployment.
France's ANSN and the FCC have tightened cable corridor protection zones around existing infrastructure, mandating wider exclusion buffers for fishing and anchoring activities in designated subsea zones. These rules are forcing rerouting of planned systems through longer, more expensive paths or requiring enhanced armoring specifications. The Atlantic and Mediterranean routes face the most significant constraint adjustments, with operators negotiating bilateral agreements to harmonize protection standards across national exclusive economic zones.
Consortium-based procurement is fragmenting as hyperscalers bypass traditional carrier alliances to commission private cable pairs with dedicated ownership structures. This pattern is visible most acutely on transpacific routes where content providers now directly contract system capacity rather than purchasing IP transit from tier-one carriers. The shift is concentrating ownership of newest-generation cable assets among a handful of technology firms while relegating traditional telecom operators to minority stakes and landing station operations.
Submarine Cable System Market Segmentation
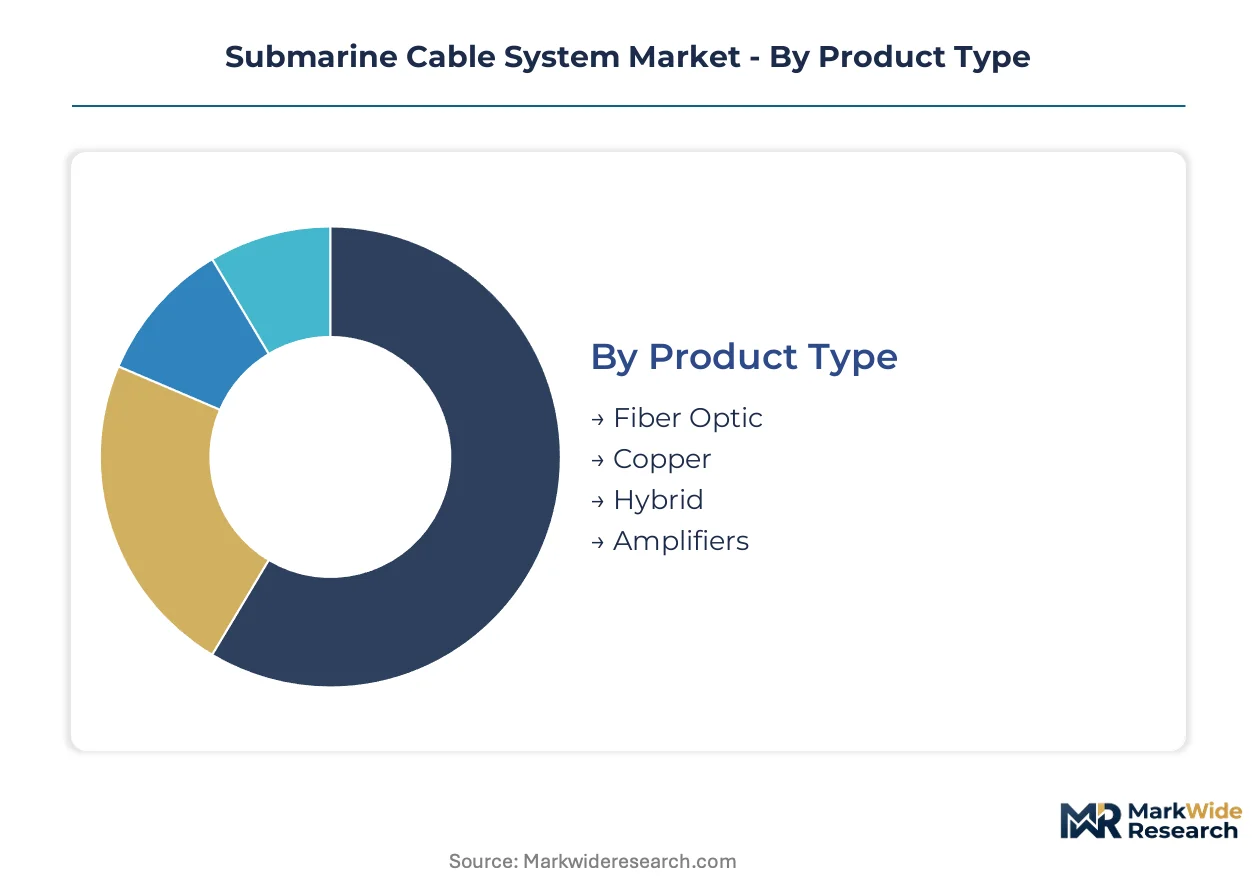
Submarine cable procurement decisions cascade through multiple technical and commercial dimensions. Operators weight capacity density against route flexibility, while regulatory pressures reshape installation method preferences across jurisdictions.
Product Type:
Fiber optic systems command premium pricing for transoceanic routes, while copper retains volume presence in legacy coastal networks and specialized power-feeding applications.
- Fiber Optic:Multi-core sheaths with space-division multiplexing enable terabit-scale transmission across Pacific and Atlantic corridors. Singapore, the United States, and France anchor demand as hyperscalers commission dedicated fiber pairs for AI training clusters.
- Amplifiers:Erbium-doped fiber repeaters with proprietary power-feeding architectures concentrate margin pools due to precision manufacturing requirements. Deep-water installation campaigns on trans-Pacific routes drive procurement volume for these components.
- Copper:Legacy conductor technology persists in coastal power-feeding segments and military hardened circuits where electromagnetic resilience outweighs bandwidth density.
- Hybrid:Bundled fiber-copper configurations serve nearshore utility corridors where simultaneous telecommunications and subsea power transmission create procurement efficiencies.
Today's leader: Fiber Optic. Tomorrow's challenger: Amplifiers.
Application:
Commercial data transmission generates the majority of route kilometers, though military specifications command higher unit margins and stricter domestic content requirements.
- Telecommunication:Carrier consortium traffic aggregation across transoceanic corridors, with capacity allocation shifting from wholesale IP transit toward direct hyperscaler leasing structures.
- Data Transmission:Cloud provider backbone interconnects supporting distributed GPU clusters for generative AI workloads, with Singapore-United States-France forming the primary demand triangle.
- Military:Sovereign secure networks independent of commercial infrastructure, with hardened armoring and encrypted terminal specifications mandated by national defense procurement offices.
- Research:Oceanographic sensor integration and climate monitoring arrays, particularly along Pacific routes traversing the Clarion-Clipperton Zone.
Data Transmission applications are expanding most quickly as AI infrastructure buildouts accelerate.
Installation:
Water depth and seabed geology determine vessel selection and route engineering complexity, with deep-water campaigns concentrating among specialized fleet operators.
- Submarine:Full ocean-depth laying operations requiring cable ships with dynamic positioning and plough burial capabilities for corridor protection.
- Nearshore:Shallow-water landing zone preparation with directional drilling and horizontal boring for beach manhole connectivity.
- Offshore:Platform-to-platform links and wind farm interconnector bundles, particularly in North Sea and Baltic developments.
- Terrestrial:Landing station backhaul extensions and cross-border terrestrial segments completing end-to-end circuits.
Submarine installation maintains the steepest expansion trajectory as new transoceanic systems enter survey phases.
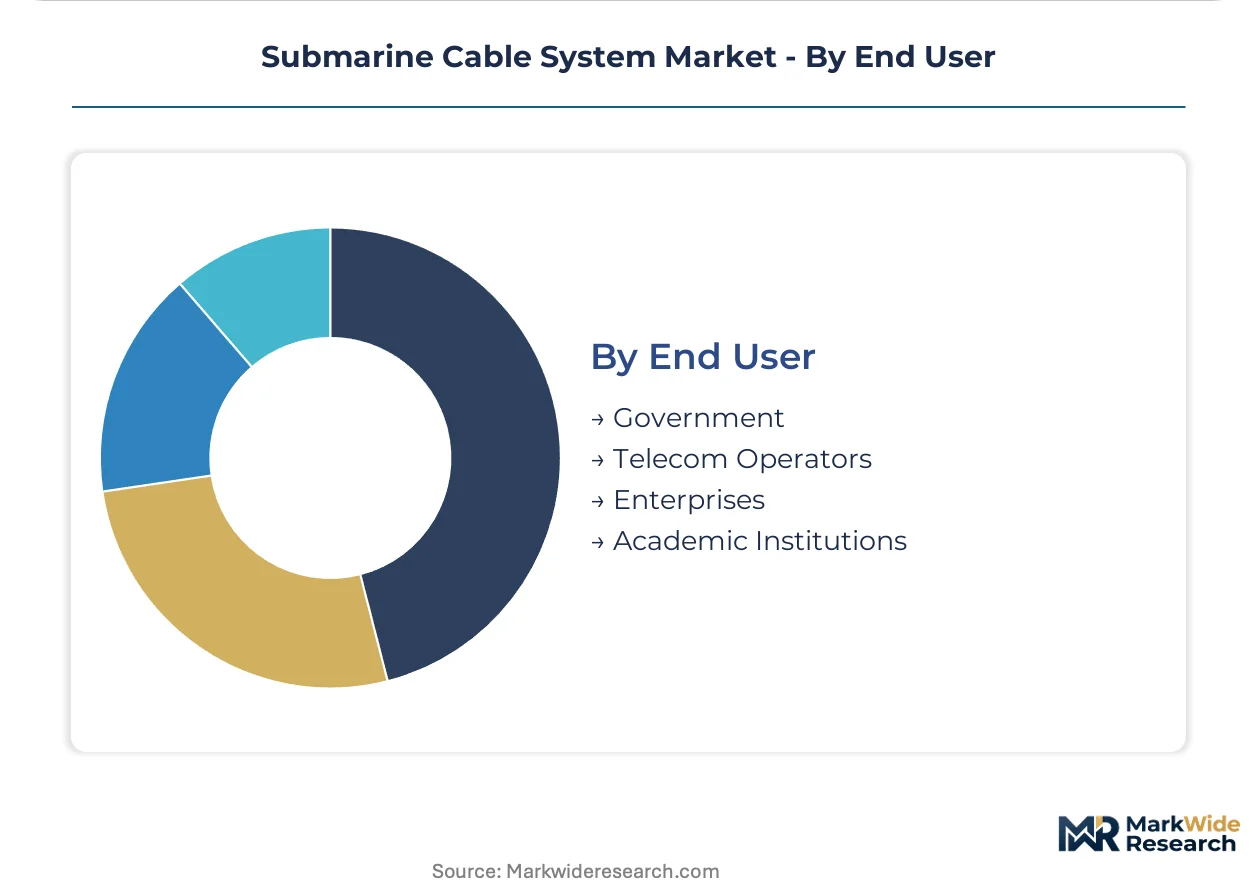
End User:
Government and enterprise procurement patterns diverge sharply on ownership structure, with sovereign networks favoring dedicated assets and commercial operators preferring consortium participation.
- Telecom Operators:Traditional carrier consortia with declining ownership shares as hyperscalers bypass wholesale arrangements for direct cable pair acquisition.
- Government:Defense and diplomatic networks with mandatory domestic landing stations and restricted foreign equipment sourcing under national security frameworks.
- Enterprises:Financial services and cloud infrastructure firms contracting private capacity on newest-generation systems, particularly across Atlantic and Pacific routes.
- Academic Institutions:Research and education network participation in consortium cables with preferential pricing for non-commercial traffic.
Enterprises are gaining share fastest as direct procurement displaces traditional carrier intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable industry traces its commercial origins to trans-Atlantic telegraph networks laid from the United Kingdom in the 1850s, with modern fiber optic infrastructure scaling through landing stations in Singapore, the United States, and France.
United States
Hyperscalers operating from Virginia and Oregon data centers are commissioning dedicated fiber pairs on transpacific routes. The FCC mandates cable corridor protection zones with exclusion buffers for fishing and anchoring activities. Miami and Los Angeles anchor landing station concentration as cloud providers bypass traditional carrier consortia for direct capacity ownership.
Singapore
The city-state functions as the primary interconnection hub for Southeast Asian traffic aggregation and AI workload distribution. Singapore's Infocomm Media Development Authority coordinates landing station permitting with marine environmental assessments. Tuas and Changi North house expanding cable landing facilities serving distributed GPU clusters across the region.
France
ANSN regulatory frameworks enforce seabed protection standards that reroute planned systems through longer paths. The EU Green Deal pressures cable tenders toward low-carbon installation methods and marine ecosystem assessments. Calais manufacturing and Marseille landing infrastructure anchor European supply chain integration.
Japan
METI prioritizes secure undersea communication networks independent of commercial infrastructure for sovereign defense requirements. Chubu and Kanto regions concentrate marine survey capabilities and precision manufacturing of erbium-doped fiber repeaters. Tokyo Bay landing stations serve as critical nodes for transpacific latency-sensitive traffic.
United Kingdom
Historical cable landing sites in Cornwall and Scotland retain infrastructure significance for trans-Atlantic route diversity. The UK Maritime and Coastguard Agency coordinates with the International Cable Protection Committee on seabed corridor designation. London financial services firms contract private capacity on newest-generation systems, displacing traditional carrier intermediation.
Submarine Cable System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across installation capability and marine survey integration. The market structure consolidates around specialized cable-laying vessel operators and integrated system providers with deep-water fleet access. Three archetypes dominate: Japanese and European integrated manufacturers with full marine capabilities, Chinese and Korean cable specialists with cost-optimized production, and pure-play installation contractors with chartered vessel networks. Competitive dynamics center on vessel booking lead time reduction and strategic partnerships with hyperscaler consortia.
Within the integrated manufacturer tier, NEC Corporation and Alcatel Submarine Networks exemplify archetypes combining marine survey capabilities with manufacturing depth. SubCom, LLC occupies a position representing specialized installation expertise on transpacific route density. Hengtong Group and ZTT International anchor the Chinese specialist segment with volume production positioning.
| Leading Market Players |
|---|
| NEC Corporation |
| Hengtong Group |
| Alcatel Submarine Networks |
| LS Cable & System |
| NKT |
| Prysmian S.p.A |
| Nexans |
| ZTT International |
| SubCom, LLC |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal procurement mandates gate qualified supply access for submarine cable manufacturers while simultaneously stratifying pricing tiers based on environmental compliance depth. Cable tenders requiring marine ecosystem assessments and low-carbon installation methods concentrate premium pricing power among integrated operators with in-house survey capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates submarine cable procurement, with differentiation driven by fiber pair count and vessel emission certification grade. Price compression intensifies in the standard tier as Chinese manufacturers expand capacity for nearshore applications. Hyperscalers commissioning dedicated AI infrastructure exhibit the lowest price sensitivity, while regional telecom consortia negotiate aggressively on legacy route replacements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for fiber optic cable systems, with manufacturing concentrated in France, Japan, and China. High-grade steel wire and copper conductors for cable armoring draw from specialized metallurgical suppliers in Germany and South Korea. Single-source vulnerability persists for erbium-doped fiber repeaters where Japanese precision manufacturers anchor global amplifier supply. Distribution runs through consortium procurement structures for transoceanic routes and direct bilateral contracts for private cable pairs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
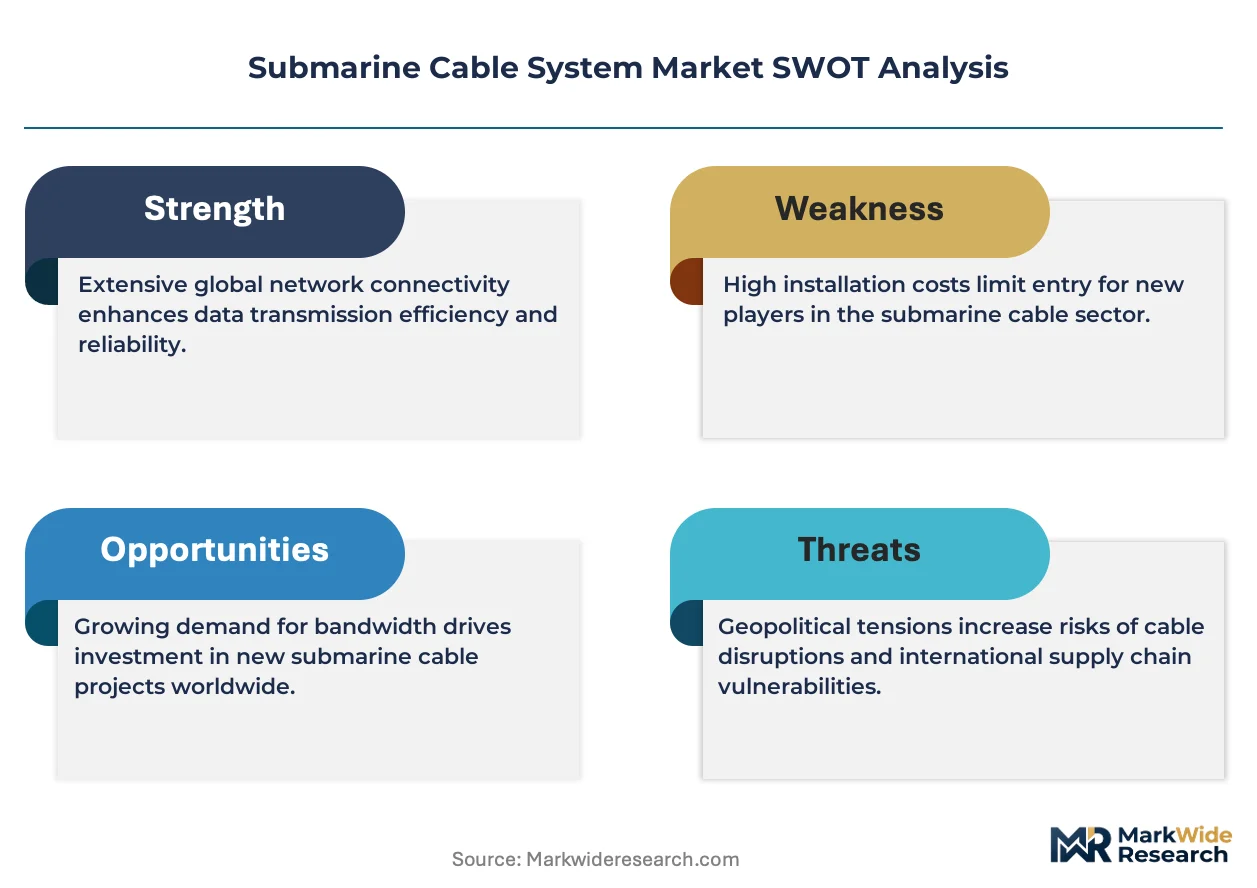
Submarine cable deployment functions as a geographic-arbitrage play where vessel availability in the Atlantic commands premium rates against Pacific route oversupply, and EU environmental compliance costs diverge sharply from Asian installation economics.
For Market Incumbents: Deepen marine survey integration to preempt regulatory compliance costs under France's ANSN and the FCC's expanding corridor protection zones. Anchor capacity allocation through long-term vessel charter agreements to neutralize the threat of 18-24 month booking lead times. Prioritize backward integration into erbium-doped fiber repeater manufacturing where precision requirements sustain margin pools.
For New Entrants and Emerging Players: Space-division multiplexing with multi-core fiber offers a technology-first wedge against established single-fiber architectures. Target East and West African coastal connectivity where landing point density remains below traffic growth curves. Pursue power cable hybridization opportunities with European offshore wind developers as a bundled procurement entry point.
For Investors and Strategic Acquirers: Roll-up economics work for specialized cable-laying vessel operators because fleet scarcity concentrates bargaining power across the analysis window. Target acquisition profiles should emphasize contractors with dynamic positioning capabilities and plough burial equipment. Watch seabed mining regulatory developments in the Clarion-Clipperton Zone as an inflection indicator for Pacific route engineering costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Marine Survey Integration | NEC Corporation's in-house hydrographic capabilities preempt ANSN compliance costs for European tenders. |
| Vessel Fleet Expansion | SubCom, LLC's deep-water installation fleet captures transpacific route density where latency-sensitive cloud traffic concentrates. |
| Multi-Core Fiber Deployment | Space-division multiplexing extends existing cable lifecycles through fiber count multiplication rather than new system builds. |
| Arctic Route Activation | Seasonal installation windows for trans-Arctic cables connect Northern Europe to East Asia via reduced latency paths. |
| Power Cable Hybridization | Convergence with subsea power transmission for offshore wind creates bundled procurement opportunities with European utilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cable system procurement officers, marine survey hydrographers, vessel fleet managers, and regulatory affairs leads at national landing station authorities with secondary validation. Secondary sources included FCC cable landing license filings, ANSN seabed protection zone designations, International Cable Protection Committee route databases, and hyperscaler capital expenditure disclosures. Bottom-up project pipelines and top-down traffic demand models triangulated volume estimates.
Historical reference periods anchored the forecast window to observed installation campaign cycles and fiber pair activation timelines across the projection horizon. Segmentation dimensions modeled encompassed product type, application, installation depth, and end-user procurement structure. CAGRs derived from capacity-weighted route economics and hyperscaler contract visibility. Industry-specific inputs included vessel booking lead time trajectories and polymetallic nodule zone regulatory friction indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to seabed mining restrictions and Arctic ice condition variability. Periodic stress-testing of base assumptions is recommended given permitting timeline unpredictability and specialized talent scarcity in geotechnical seabed analysis.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Network Cable Tester Market
Cables
Global Cable Gland Market
Cables
Magnetic Charging Cable Market
Cables
Audio and Video Cables Market
Cables
Active Optical Cable Market
Cables
Medium Voltage Cables Market
Cables
Cable Lugs Market
Cables
Submarine Optical Fiber Cables Market
Cables
Instrumentation Cables Market
Cables
Cable Assembly Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
GCC Cable Accessories Market
Cables
Wire and Cable Materials Market
Cables
Global Cable Tie Market
Cables
Cable Trunking Market