
 Interface Transceiver Market | 2026-2036
Interface Transceiver Market Size, Share, and Industry Trends Forecast 2026-2036
Interface Transceiver Market Foresight
Aftermarket service revenue for legacy transceiver modules is fragmenting as cloud providers shift toward disposable high-speed optics and vendor-managed inventory programs. Cisco Systems leverages its installed base of routing platforms to sustain recurring service contracts across enterprise data centers. Broadcom anchors its position through captive silicon design for next-generation SerDes architectures. Sumitomo Electric Industries specializes in vertical-cavity surface-emitting laser arrays that dominate short-reach optical links inside hyperscale facilities.
An interface transceiver is a mixed-signal electro-optical or RF subsystem that converts parallel electrical data streams into serialized transmitted signals and recovers incoming signals through clock-data recovery circuits, typically operating at line rates from 25 Gbps to 1.6 Tbps depending on the protocol standard. Its primary commercial purpose is enabling high-bandwidth, low-latency interconnects between switches, servers, and optical transport equipment across distributed computing infrastructure. Optical transceivers carry the dominant share of value as 400G and 800G pluggable formats displace copper in data center spine-leaf architectures. Ethernet transceivers are growing fastest among product types as IEEE 802.3 standards push beyond 100 Gbps per lane. Fiber optic technology commands premium positioning for distances exceeding 500 meters, while active optical cable assemblies capture cost-sensitive rack-scale deployments.
FCC equipment authorization rules govern RF transceiver emissions in the United States, while the EU Green Deal and RoHS directives restrict hazardous substances in optical module housings sold across Europe. China's MIIT enforces domestic GB standards for transceiver interoperability that favor local suppliers in government and telecom tenders. NMPA-equivalent equipment certification in China plus REACH substance disclosures in Europe collectively raise compliance costs for multinational vendors. Stakeholders must monitor divergence between IEEE electrical specifications and regional interoperability mandates when allocating R&D across product generations.
Market Dynamics
The migration from 400G to 800G and 1.6T Ethernet standards is compressing product lifecycles and forcing simultaneous investment in multiple speed grades across the supply base.
Growth Catalysts
- Hyperscale data center buildouts:Cloud providers in the United States, China, and Germany are expanding domestic infrastructure at unprecedented scale, driving procurement of high-speed optical transceivers for spine-leaf architectures.
- IEEE 802.3 standard advancement:The standards body's push beyond 100 Gbps per lane is enabling next-generation pluggable formats that displace copper interconnects in rack-scale deployments.
- RoHS and EU Green Deal compliance:European hazardous substance restrictions are accelerating module redesigns toward recyclable housings and reduced material intensity, creating upgrade cycles across installed bases.
Market Restraints
- Indium phosphide supply concentration:Laser chip fabrication depends on a limited supplier base concentrated in East Asian foundries, exposing procurement to geopolitical friction and capacity constraints.
- MIIT interoperability mandates:China's GB standards for transceiver certification create regional testing burdens that fragment product SKUs and extend time-to-market for multinational vendors.
- Copper active optical cables:Cost-sensitive rack-scale deployments below 10 meters increasingly substitute copper AOCs for optical transceivers, compressing addressable volume in hyperscale facilities.
Strategic Opportunities
- Co-packaged optics convergence:The integration of silicon photonics with switch ASICs is collapsing distance requirements and enabling new form factors for AI training clusters.
- Vendor-managed inventory programs:Cloud providers are outsourcing module lifecycle management to original manufacturers, creating recurring revenue streams and deeper customer captivity.
- Short-reach VCSEL arrays:Vertical-cavity surface-emitting laser technology optimized for sub-100-meter links inside hyperscale facilities represents underpenetrated white space distinct from long-haul coherent optics.
Industry Challenges
- SerDes architecture talent scarcity:Design of 112 Gbps and 224 Gbps serializer-deserializer circuits requires specialized mixed-signal expertise concentrated at a handful of semiconductor firms.
- FCC equipment authorization timelines:RF transceiver variants face extended certification cycles that misalign with hyperscaler procurement calendars, forcing inventory pre-positioning and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interface Transceiver Market |
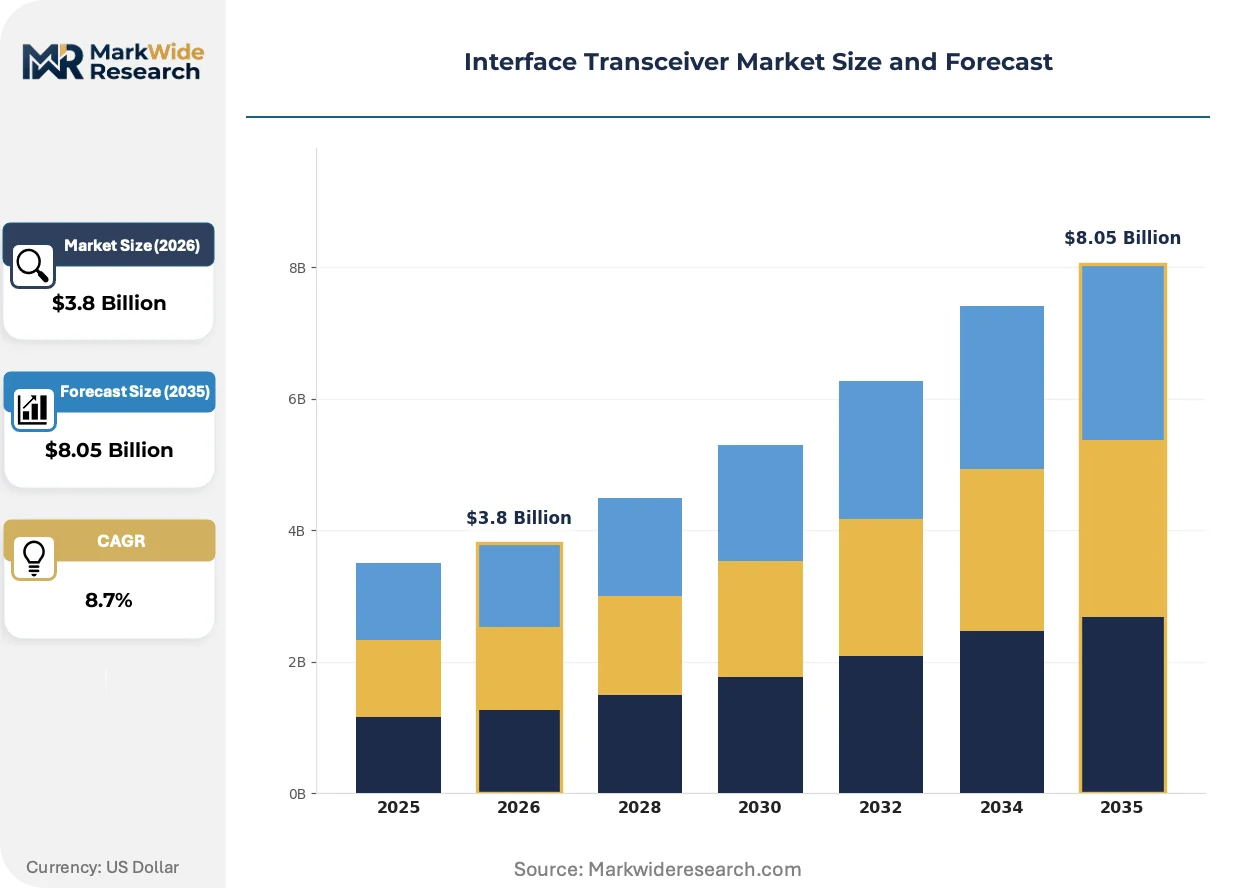
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethernet Transceiver, Optical Transceiver, Coaxial Transceiver, Wireless Transceiver Application: Data Centers, Telecommunications, Broadcast, Automotive Technology: Active Optical Cable, Fiber Optic, SerDes, RF End User: Telecom Operators, Cloud Providers, Enterprises, Educational Institutions |
| Companies Covered | Coherent Corp., Cisco Systems, Inc., Broadcom Inc., Lumentum Holdings Inc., Accelink Technologies Co. Ltd., INNOLIGHT, Sumitomo Electric Industries, Ltd., Hisense Broadband, Inc., Fujitsu Optical Components Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interface Transceiver Market Shifts & Advancements
Optical transceiver architecture is undergoing fundamental restructuring as electrical and optical domains merge, with implications for power density, thermal management, and supplier specialization.
Linear drive optics is collapsing the traditional DSP-based retiming architecture by eliminating power-hungry digital signal processors from the signal path. Hyperscalers deploying AI training clusters are piloting linear pluggable optics for 800G links to reduce module power consumption below 10 watts. This compression of the optical-electrical boundary is enabling denser switch faceplates and extending the viability of copper backplanes.
REACH substance disclosure requirements in Europe are forcing material transparency across multi-tier supply chains for optical module housings. The regulation's industrial consequence is a shift toward halogen-free substrates and recyclable metal enclosures that comply with extended producer responsibility frameworks. Transceiver vendors serving European data center operators are now pre-certifying modules against RoHS and REACH simultaneously to avoid SKU proliferation.
Disposable module economics is displacing traditional repair-and-return service models as cloud providers prioritize operational simplicity over asset longevity. Enterprise data centers and telecom central offices still maintain service contracts, but hyperscale buyers treat 400G and 800G optics as consumables with 3-5 year replacement cycles. This behavioral divergence is most visible in the United States, where Amazon Web Services, Microsoft Azure, and Google Cloud operate at sufficient scale to justify vendor-managed inventory and just-in-time module replacement programs.
Interface Transceiver Market Segmentation
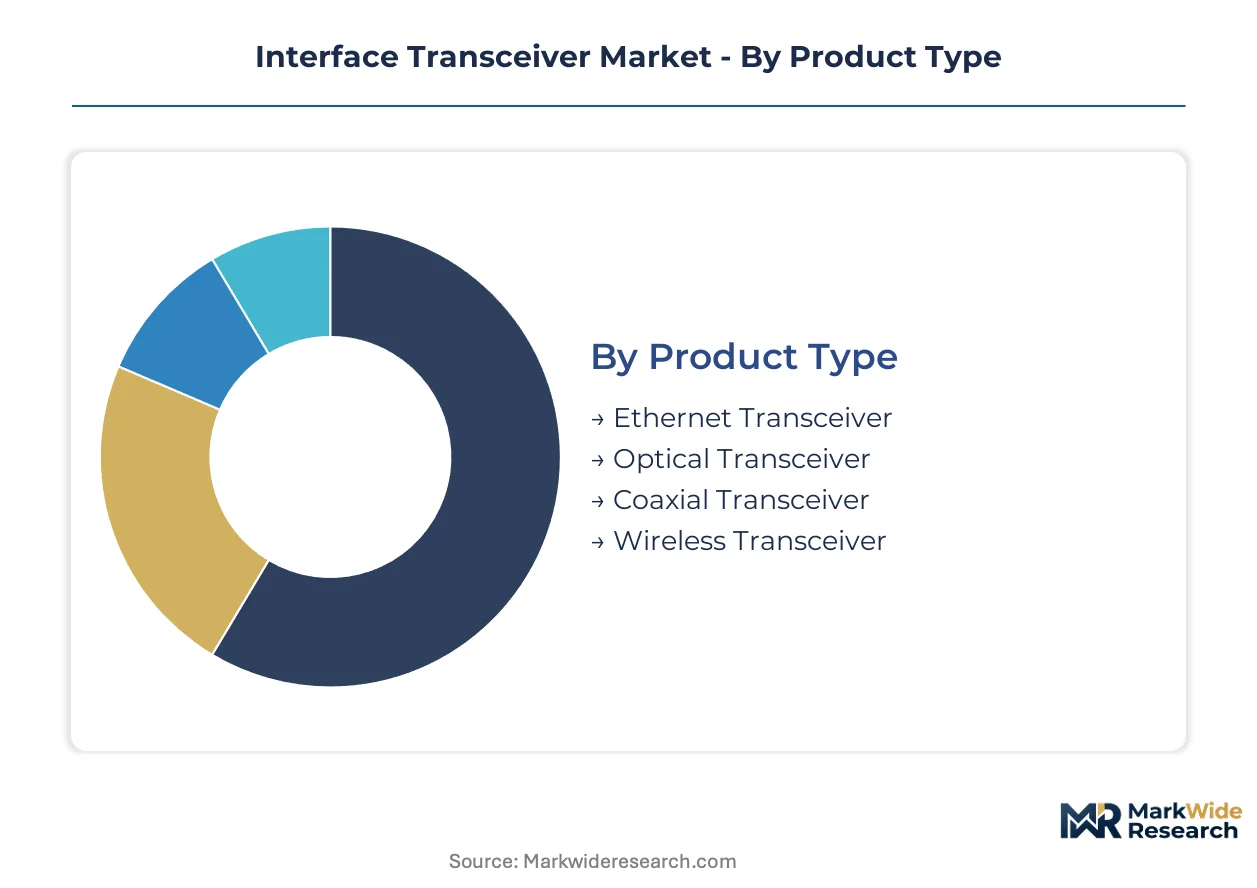
Interface transceiver segmentation reveals how architectural choices in speed, distance, and power consumption map onto distinct procurement patterns across computing infrastructure. Buyers optimize module selection against rack density constraints, protocol standards, and total cost of ownership across replacement cycles.
Product Type:
Mature copper-based formats coexist with emerging pluggable optics as data centers navigate multi-speed upgrade timelines.
- Optical Transceiver:Pluggable modules convert electrical signals to light using laser diodes or photodetectors, with 400G and 800G QSFP-DD and OSFP formats displacing legacy 100G installations. Hyperscale facilities in the United States and China are standardizing on optical spine-leaf architectures that demand these modules in volume, though indium phosphide laser supply concentration creates procurement risk.
- Ethernet Transceiver:IEEE 802.3-compliant devices handle serialized data transmission across twisted-pair copper or fiber, with 112 Gbps PAM4 signaling enabling 800G aggregate throughput. Cloud providers deploying AI training clusters are driving the fastest procurement velocity for these devices as they replace copper direct-attach cables in rack-scale interconnects.
- Coaxial Transceiver:RF-over-coax modules maintain relevance in legacy broadcast headends and cable access networks.
- Wireless Transceiver:Millimeter-wave and sub-6 GHz units serve 5G fronthaul and specialized industrial applications.
Optical Transceiver handles the majority of throughput; Ethernet Transceiver is expanding most quickly on share.
Application:
Volume concentrates in facilities with the highest port density requirements, while emerging use cases test module reliability under environmental stress.
- Data Centers:Hyperscale computing facilities deploy transceivers across spine, leaf, and server-facing tiers, with power budgets below 15 watts per module becoming mandatory for thermal management at 51.2 Tbps switch capacities. Buildouts by Amazon Web Services, Microsoft Azure, and Google Cloud in Virginia, Oregon, and Iowa are concentrating North American demand for 800G pluggable optics.
- Telecommunications:Carrier networks utilize coherent optical transceivers for metro and long-haul transport, with 400G ZR and ZR+ pluggable formats collapsing the traditional transponder/muxponder architecture. China's three state-owned operators are deploying these modules in provincial backbones under MIIT interoperability mandates that favor domestic certification.
- Broadcast:Professional video applications require SDI-over-fiber transceivers with deterministic latency for live production.
- Automotive:In-vehicle Ethernet and sensor fusion networks are piloting automotive-grade optical transceivers for autonomous driving compute platforms.
Data Centers absorb the dominant procurement volume; Automotive is climbing the fastest as a share of emerging applications.
Technology:
Signal conditioning approaches differentiate cost structures and deployment distances across computing environments.
- Fiber Optic:Laser-based transmission through single-mode or multimode fiber enables distances from 100 meters to 80 kilometers depending on wavelength and modulation format. European data center operators in Frankfurt and Amsterdam are prioritizing fiber deployments to meet EU Green Deal energy efficiency targets for network infrastructure.
- SerDes:Serializer-deserializer circuits at 56 Gbps, 112 Gbps, and emerging 224 Gbps lane rates constitute the electrical backbone of all high-speed transceivers, with Broadcom and Marvell dominating IP availability for these mixed-signal designs. Talent scarcity for 224 Gbps architecture development is constraining supplier roadmaps industry-wide.
- Active Optical Cable:Transceiver-integrated cable assemblies simplify procurement for rack-scale deployments under 10 meters, though hyperscalers are shifting toward discrete pluggable modules for inventory flexibility.
- RF:Radio frequency transceivers for wireless backhaul and fronthaul face extended FCC equipment authorization timelines that misalign with carrier procurement calendars.
SerDes architecture underpins every high-speed format; Fiber Optic commands the steepest expansion trajectory as distances stretch and power budgets tighten.
End User:
Procurement sophistication varies dramatically between volume buyers optimizing for total cost of ownership and price-sensitive adopters with intermittent refresh cycles.
- Cloud Providers:Hyperscale operators treat 400G and 800G transceivers as consumables with 3-5 year replacement cycles, outsourcing inventory management to original manufacturers through vendor-managed programs. Operational simplicity outweighs asset longevity for these buyers, who represent the highest absolute volume and most aggressive speed-grade migration.
- Telecom Operators:State-owned and competitive carriers maintain longer asset lifecycles and still demand repair-and-return service contracts, particularly in European and Asian markets with established central office infrastructure. NMPA-equivalent certification requirements in China fragment product SKUs for multinational vendors serving these operators.
- Enterprises:Private data centers and colocation users exhibit heterogeneous procurement patterns mixing legacy 10G/25G installations with selective 100G/400G upgrades.
- Educational Institutions:Research universities and campus networks represent sporadic demand concentrated in high-performance computing interconnects.
Cloud Providers dominate absolute volume; Enterprises are gaining share fastest as distributed edge computing expands module deployment beyond hyperscale facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: cloud providers in the United States treat high-speed optics as disposable consumables, while European telecom operators maintain longer asset lifecycles under repair-and-return contracts, and Chinese state-owned carriers enforce domestic certification regimes that reshape procurement flows.
United States
Hyperscale buildouts by Amazon Web Services, Microsoft Azure, and Google Cloud in Virginia, Oregon, and Iowa concentrate demand for 800G pluggable optics. FCC equipment authorization rules govern RF transceiver emissions, though extended certification cycles misalign with hyperscaler procurement calendars. The Dallas-Fort Worth metroplex anchors a growing cluster of data center construction driving module consumption.
China
MIIT enforces GB standards for transceiver interoperability that favor local suppliers in government and telecom tenders, fragmenting product SKUs for multinational vendors. The three state-owned operators deploy 400G ZR and ZR+ pluggable formats in provincial backbones under these mandates. Yangtze River Delta facilities in Shanghai and Suzhou concentrate domestic manufacturing capacity for laser chip packaging.
Germany
EU Green Deal energy efficiency targets and REACH substance disclosure requirements accelerate module redesigns toward recyclable housings. Frankfurt and Amsterdam data center operators prioritize fiber deployments to meet these regulatory thresholds. Bavaria's Munich-Ingolstadt corridor hosts specialized testing laboratories for RoHS and REACH pre-certification.
Japan
METI industrial policy supports domestic photonics manufacturing, with JIS standards creating baseline interoperability requirements for optical modules. Tokyo-Osaka corridor facilities maintain captive production of vertical-cavity surface-emitting laser arrays for short-reach applications. Kanagawa Prefecture concentrates precision optical component suppliers serving regional telecom infrastructure.
South Korea
MFDS-equivalent equipment certification and national broadband expansion programs sustain procurement of coherent optical transceivers for metro transport. Seoul Capital Area data center construction by Naver and Kakao drives 400G spine-leaf architecture deployment. Gyeonggi Province hosts assembly operations for pluggable module form factors.
Interface Transceiver Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around vertically integrated semiconductor designers holding SerDes IP, diversified optical component houses with captive laser fabrication, and specialized module assemblers serving cost-sensitive segments. Two strategic archetypes dominate: silicon photonics integrators collapsing optical-electrical boundaries, and pluggable format specialists optimizing for hyperscaler volume procurement. Competitive moves center on co-packaged optics convergence and vendor-managed inventory program expansion.
Among diversified optical component houses, Coherent Corp., Lumentum Holdings Inc., and Sumitomo Electric Industries, Ltd. occupy positions exemplifying vertical integration into laser chip fabrication. These entities represent the capability-concentrated tier where indium phosphide and gallium arsenide foundry access creates procurement leverage. Cisco Systems, Inc. and Broadcom Inc. anchor the semiconductor-integrated archetype, leveraging switch ASIC and routing platform installed bases to sustain module attach rates. The competitive dynamic between these tiers shapes pricing discipline and speed-grade migration timelines across 800G and 1.6T product generations.
| Leading Market Players |
|---|
| Coherent Corp. |
| Cisco Systems, Inc. |
| Broadcom Inc. |
| Lumentum Holdings Inc. |
| Accelink Technologies Co. Ltd. |
| INNOLIGHT |
| Sumitomo Electric Industries, Ltd. |
| Hisense Broadband, Inc. |
| Fujitsu Optical Components Limited |
| Others |
Supply & Pricing Matrix
Indium phosphide laser chip fabrication concentrates in East Asian foundries, anchoring margin capture upstream while module assemblers downstream face procurement leverage constraints and speed-grade migration pressure.
Pricing Analysis
Long-term offtake agreements dominate procurement between hyperscale cloud providers and captive silicon designers, though spot-market transactions persist for legacy 100G and 200G formats. Price differentiation rests on SerDes lane-rate capability and MIIT certification status for Chinese market access. Cost compression in 800G modules intensifies as Broadcom and Marvell license 112 Gbps IP more broadly. Cloud providers exhibit lowest price sensitivity given vendor-managed inventory programs, while enterprise data centers and educational institutions drive hardest bargain on per-unit economics.
Supply Chain Analysis
Extended payment terms from hyperscale buyers now stretch 90-120 days, forcing module assemblers to utilize supply-chain finance facilities anchored by receivables. Manufacturing concentrates in China, Japan, and the United States, with Yangtze River Delta facilities handling laser chip packaging and Kanagawa Prefecture supplying precision optical components. Production draws from indium phosphide wafers, ceramic submounts, and halogen-free PCB substrates. Single-source vulnerability runs through East Asian foundry capacity for 224 Gbps SerDes development. Distribution runs through direct OEM relationships and specialized photonics distributors serving telecom operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speed-grade fragmentation across 400G, 800G, and 1.6T migration timelines creates specialist niches for suppliers with targeted SerDes or laser capabilities rather than full-stack integration.
For Market Incumbents: Entrench position through backward integration into indium phosphide laser fabrication and captive 224 Gbps SerDes architecture development. Cisco Systems and Broadcom should deepen switch ASIC attach rates while Coherent Corp. and Lumentum secure long-term wafer supply agreements against foundry capacity constraints. Priority lever: vendor-managed inventory program expansion to lock hyperscale procurement calendars. For New Entrants and Emerging Players: Build out specialized capabilities in linear drive optics and co-packaged photonics for AI training cluster deployments, where architectural standards remain unsettled. Short-reach VCSEL arrays for sub-100-meter hyperscale links represent the most penetrable white space distinct from coherent long-haul dominance. Go-to-market angle: direct engineering engagement with cloud provider hardware teams bypassing traditional distribution. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated optical component houses with captive laser foundry access and established MIIT certification pathways for Chinese market participation. Long-term viability favors entities bridging silicon photonics integration with pluggable format expertise. Signal to watch: hyperscaler adoption timelines for linear pluggable optics versus traditional DSP-based architectures as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optics Convergence | Silicon photonics integration with switch ASICs collapses distance requirements for AI clusters. |
| Vendor-managed Inventory Program | Cloud providers outsource module lifecycle management to original manufacturers for operational simplicity. |
| Linear Drive Optics Pilot | Hyperscalers test DSP-free 800G modules to reduce power consumption below 10 watts. |
| REACH Pre-certification Investment | European data center operators demand simultaneous RoHS and REACH compliance to avoid SKU proliferation. |
| 224 Gbps SerDes Architecture Development | Talent scarcity for next-generation mixed-signal design constrains supplier roadmaps industry-wide. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with optical module procurement managers at hyperscale cloud providers, SerDes design engineers at semiconductor firms, and telecom carrier network planners; alongside secondary validation through IEEE 802.3 standards documentation, FCC equipment authorization filings, MIIT GB standard publications, and hyperscaler capital expenditure disclosures. Bottom-up module shipment estimates triangulated against top-down infrastructure investment projections across data center and telecommunications applications.
Forecast inputs considered speed-grade migration timelines, power density constraints at 51.2 Tbps switch capacities, and regional regulatory divergence between IEEE electrical specifications and MIIT interoperability mandates. Segmentation dimensions modeled include product type, application, technology, and end-user procurement sophistication across the projection horizon. CAGRs derived from installed base replacement cycles and hyperscale buildout acceleration in Virginia, Oregon, and Iowa.
Stress conditions across indium phosphide supply concentration, FCC certification timeline extension, and copper AOC substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding standards ratification schedules and foundry capacity expansion. Macroeconomic contraction in cloud infrastructure investment, regulatory divergence in EU Green Deal implementation, or breakthrough in co-packaged optics adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Wireless Transmitter Chip Market