
 Solar Cable Market | 2026-2036
Solar Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cable Market Intelligence
The European Union's Green Deal, with its ambitious renewable energy targets, is expanding the addressable market for high-performance solar cables. This policy-driven demand creates a stable growth environment for specialized manufacturers. Prysmian Group leverages its extensive global manufacturing footprint to serve large utility-scale developers across multiple continents. In parallel, Lapp Group specializes in engineering durable, weather-resistant cable solutions designed specifically for harsh environmental conditions found in desert or coastal solar farms.
A solar cable is a specialized, interconnecting electrical wire designed specifically for use in photovoltaic power systems. These cables are engineered with materials like cross-linked polyethylene (XLPE) to provide exceptional UV resistance, high-temperature tolerance, and long-term durability against environmental stressors. Their primary purpose is to reliably transmit direct current from solar panels to inverters or combiner boxes with minimal energy loss. Utility-scale projects represent the largest application segment, driven by government-backed renewable energy programs. XLPE dominates material selection due to its superior insulation and safety characteristics for outdoor installations.
Compliance with stringent technical standards is fundamental to market access and product acceptance. Key frameworks include the International Electrotechnical Commission's IEC 62930 standard, various ISO quality management certifications, and installation guidelines within the US National Electrical Code (NEC). These regulations enforce strict criteria for material durability, fire safety, and electrical performance, ensuring system longevity and operational safety. Stakeholder decisions will center on navigating material cost volatility for copper and advanced polymers while meeting evolving performance benchmarks.
Market Dynamics
The global expansion of utility-scale solar infrastructure, driven by national decarbonization targets and energy security policies, represents the central force shaping the solar cable market. This creates a sustained, large-volume demand for specialized, high-performance interconnection components meeting stringent international standards.
Growth Catalysts
- Supportive Regulatory Frameworks:Policies like the EU Green Deal and China's dual carbon goals mandate significant increases in renewable energy capacity, creating a direct and predictable demand pipeline for all photovoltaic system components, including solar cables.
- Utility-Scale Project Expansion:The development of large-scale solar farms, which constitute the largest application segment, requires extensive lengths of durable, high-transmission-efficiency cables to connect vast arrays of panels to the power grid.
- Material Standardization:The widespread adoption of cross-linked polyethylene (XLPE) as the primary insulation material is driven by its proven performance in UV resistance and high-temperature tolerance, enhancing system safety and operational longevity.
Market Restraints
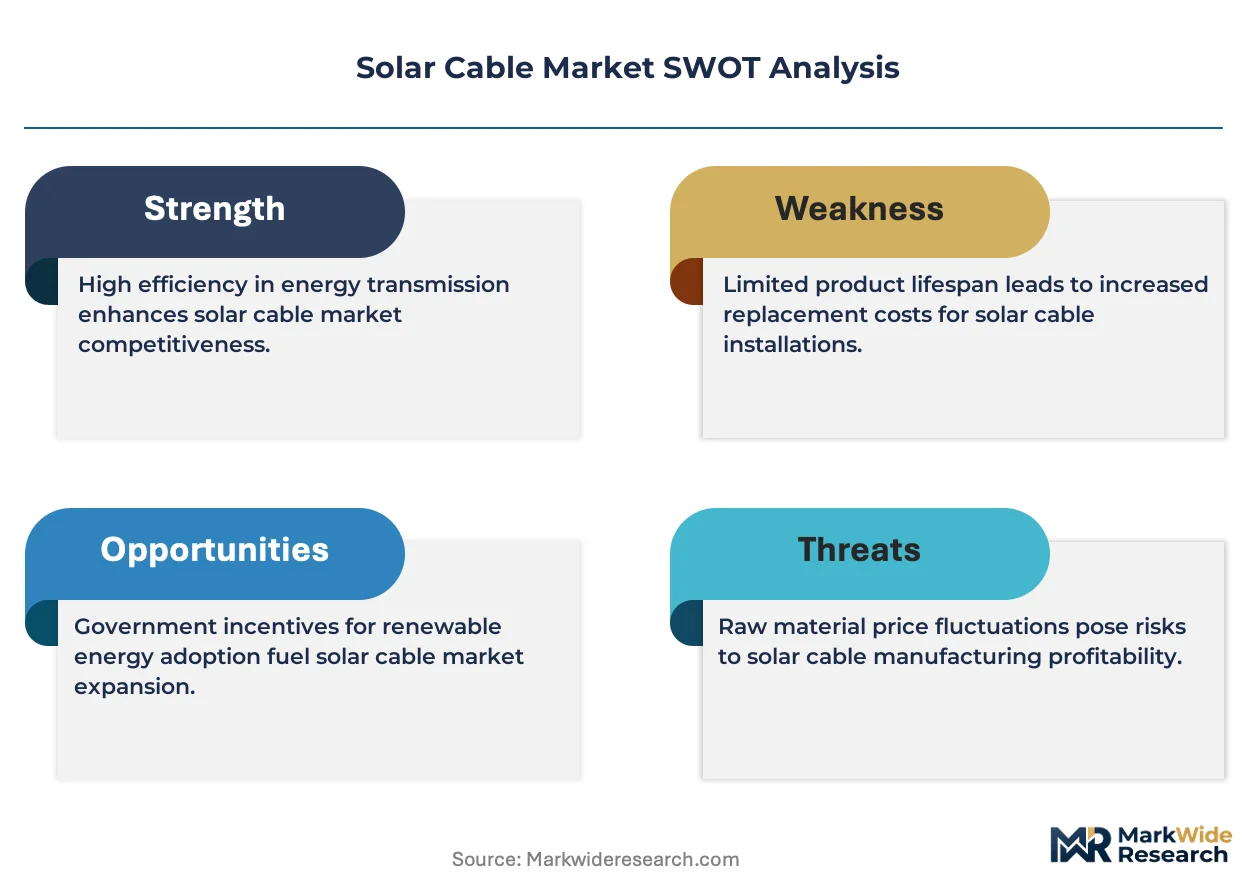
- Input Cost Volatility:The market is highly sensitive to price fluctuations in key raw materials, particularly copper for conductors and petroleum-derived polymers for insulation, which can compress manufacturer margins and impact project bidding prices.
- Technical Compliance Barriers:Adherence to rigorous and evolving technical standards, such as IEC 62930, requires significant investment in R&D and testing, creating a barrier to entry for smaller manufacturers lacking specialized expertise.
- Supply Chain Concentration:Geographic concentration in the manufacturing of raw materials and solar components, particularly in China, introduces risks related to geopolitical tensions, trade policy shifts, and potential logistical bottlenecks affecting global availability.
Strategic Opportunities
- Emerging Solar Geographies:Markets in Southeast Asia, the Middle East, and Africa are exhibiting nascent but rapid growth in solar installations, offering opportunities for suppliers to establish a foothold in regions with high solar irradiance and growing energy needs.
- Specialized Application Development:Innovations in floating solar farms and building-integrated photovoltaics (BIPV) create demand for cables with specialized properties, such as enhanced water resistance, greater flexibility, and unique aesthetic finishes.
- Alternative Conductor Materials:Research and development into copper-clad aluminum or advanced aluminum alloys present a significant opportunity to mitigate exposure to copper price volatility and potentially lower overall cable weight and cost.
Industry Challenges
- Evolving Compliance Demands:Manufacturers face the operational challenge of continuously tracking and adapting to frequent updates and regional variations in electrical codes and product safety standards, such as the US National Electrical Code (NEC).
- Counterfeit Product Risk:The prevalence of low-cost, non-compliant cables poses a substantial threat to system safety and performance, forcing legitimate manufacturers to invest in brand protection and supply chain authentication measures.
- Logistical Complexities:Managing the delivery of large, heavy cable drums to remote and often difficult-to-access utility-scale project sites requires sophisticated logistics planning and coordination to avoid costly installation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cable Market |
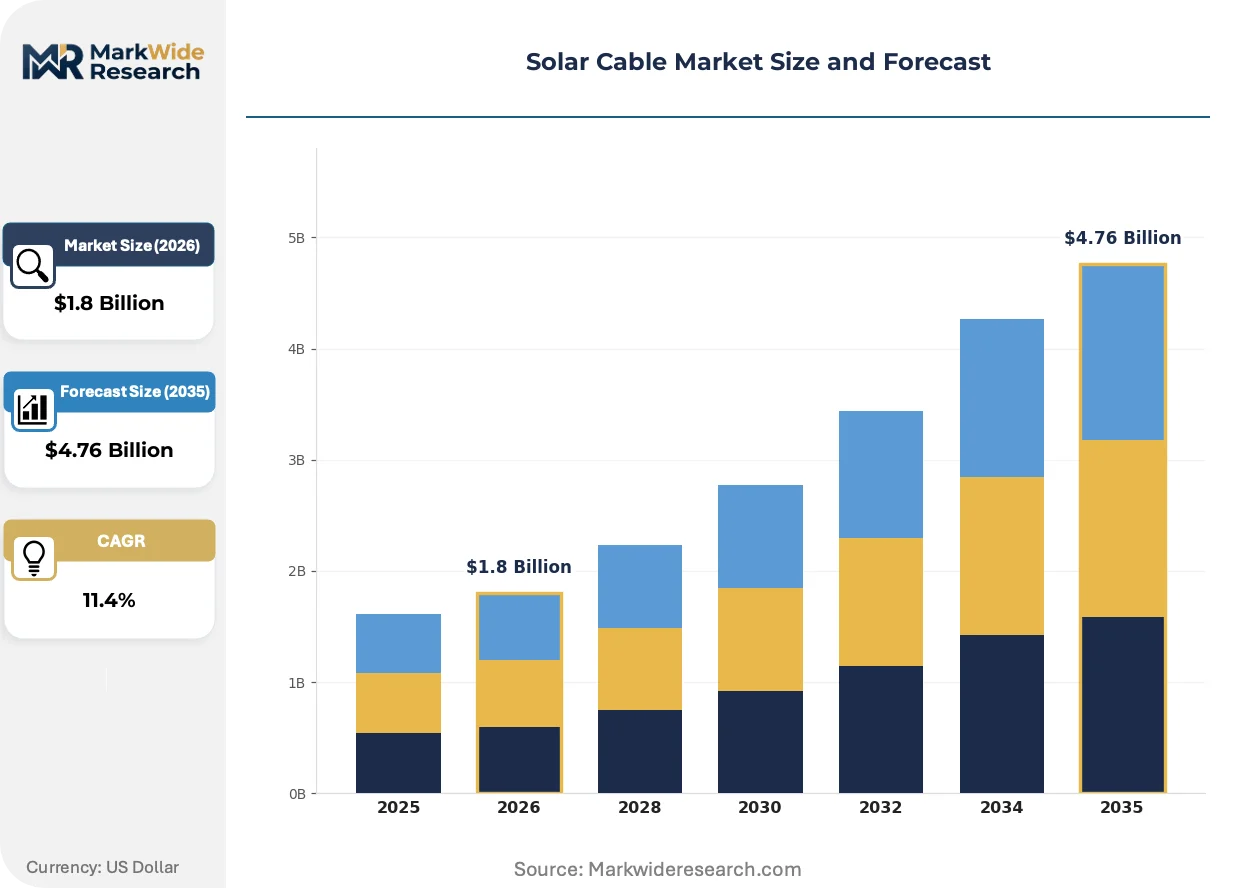
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cable, Connector Cable, Jumper Cable, Single Core Cable, Multi-Core Cable Material: Cross-Linked Polyethylene, Polyvinyl Chloride, Ethylene Propylene Rubber, Fluoropolymer, Silicone Rubber Application: Residential Installations, Commercial Power Systems, Utility-Scale Projects, Off-Grid Systems, Agricultural Power Solutions End User: Solar EPC Contractors, Power Generators, Renewable Energy Consultants, System Integrators, Installation Service Providers |
| Companies Covered | Lapp Group, SUNKEAN Cable, Prysmian Group, LS Cable & System, Shanghai Kuka Cable, Nexans, Belden, HELUKABEL, Southwire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cable Market Strategic Shifts & Innovations
Material science advancements and a global convergence on stricter safety protocols are defining the next generation of photovoltaic interconnection solutions. This evolution prioritizes long-term reliability and resilience in increasingly diverse and harsh operating environments, moving beyond basic power transmission.
Advanced polymer compounds, including enhanced XLPE and halogen-free flame-retardant (HFFR) formulations, provide superior fire safety and environmental compatibility. Utility-scale developers and commercial rooftop installers are increasingly specifying these materials to meet stringent building codes and mitigate operational risk. The market's focus on asset longevity and bankability is absorbing the higher upfront material cost, establishing these advanced polymers as a new performance benchmark.
The International Electrotechnical Commission's IEC 62930 standard is solidifying its position as the global baseline for PV cable design, testing, and safety. This framework harmonizes requirements for UV degradation, thermal endurance, and mechanical durability, compelling manufacturers to upgrade quality control and material specifications. This shift most directly affects suppliers targeting European and other developed markets, where certification to this standard is becoming a non-negotiable prerequisite for market access.
A significant behavioral shift among asset owners and EPCs involves prioritizing total cost of ownership and long-term energy yield over initial per-meter cable costs. This lifecycle-focused procurement model favors suppliers who provide verifiable performance data on durability, low electrical resistance, and degradation rates over decades. This trend is most pronounced within the competitive utility-scale solar segment, especially in geographies with mature project finance ecosystems.
Solar Cable Market Segmentation
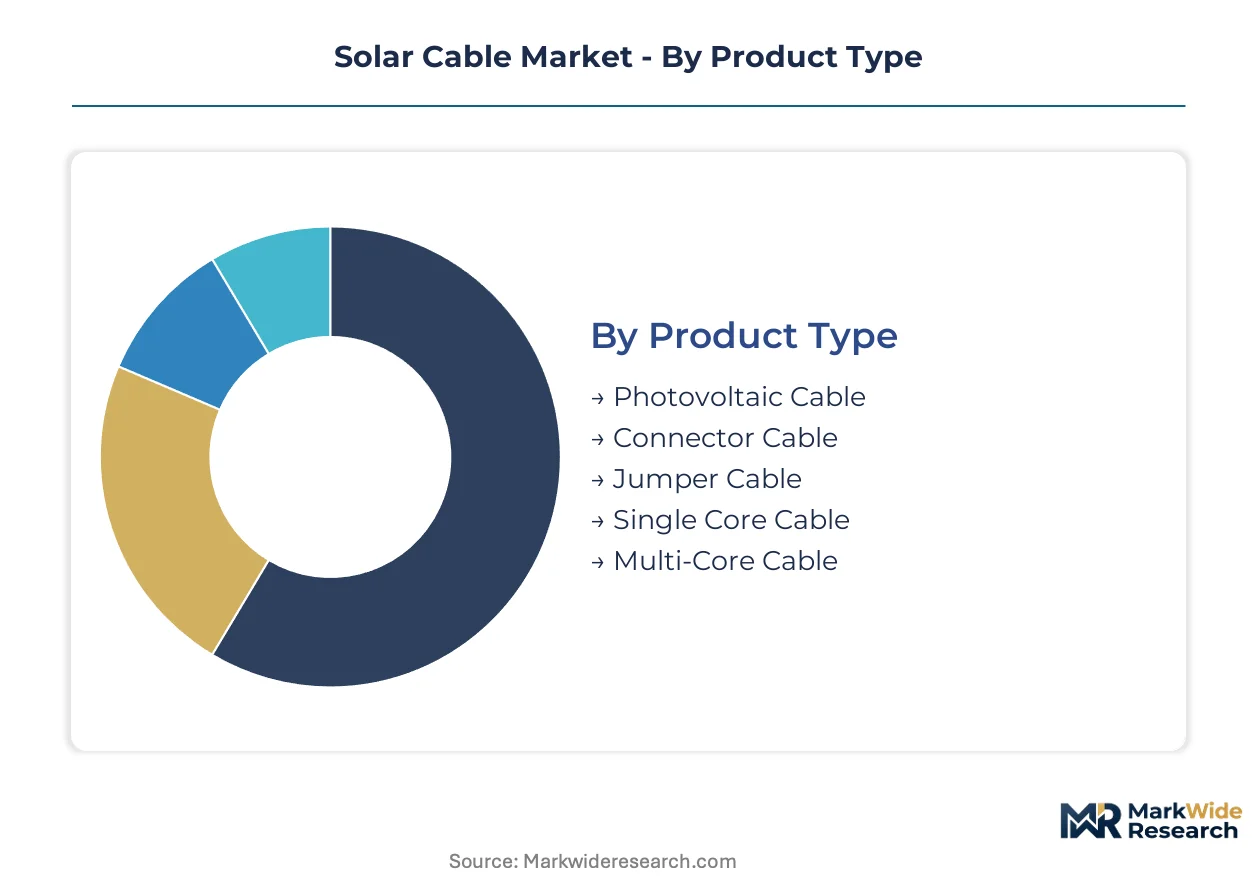
Market segmentation reveals distinct demand patterns and technical requirements across the solar cable industry. Understanding these categories is essential for manufacturers to align product development with specific application needs and regulatory mandates. This granular view enables targeted market penetration and optimizes supply chain strategies.
Product Type:
Compliance with stringent international and national standards dictates product development across different solar cable types.
- Photovoltaic Cable:Engineered to connect individual solar panels and strings, these cables must meet IEC 62930 and US NEC standards for UV resistance and temperature cycles. Demand concentrates in large utility-scale projects in China, where vast arrays require extensive, high-durability interconnections.
- Connector Cable:These specialized cables facilitate panel-to-panel or panel-to-combiner box connections, emphasizing robust, weather-sealed interfaces for reliable performance.
- Jumper Cable:Short, pre-assembled cables designed for quick, secure connections between adjacent components within a solar array, prioritizing ease of installation.
- Single Core Cable:These cables feature a single conductor, typically used for DC power transmission from combiner boxes to inverters, requiring high current capacity and excellent insulation. Demand is strong in European commercial rooftop installations, where compact designs and safety are paramount.
- Multi-Core Cable:Encompassing multiple insulated conductors within a single sheath, these cables often serve AC side connections or specialized control applications.
Leading the category by volume: Photovoltaic Cable. Growing fastest: Single Core Cable.
Material:
Material selection for solar cables often involves a trade-off between insulation performance, longevity, and overall cost considerations.
- Cross-Linked Polyethylene:XLPE is widely adopted for its superior thermal stability, UV resistance, and excellent electrical insulation properties, crucial for outdoor PV applications. Its demand is highest in regions with extreme temperatures like the Middle East, ensuring long operational lifespans.
- Polyvinyl Chloride:PVC offers cost-effectiveness and good flexibility, primarily used in less demanding indoor or protected short-run applications where UV exposure is minimal.
- Ethylene Propylene Rubber:EPR provides high flexibility and good temperature resistance, often specified for applications requiring dynamic movement or enhanced installation ease.
- Fluoropolymer:These advanced materials offer exceptional chemical resistance, high-temperature performance, and fire safety, making them ideal for specialized, high-reliability solar environments. Demand is increasing in building-integrated photovoltaics (BIPV) in Germany, where strict fire codes apply.
- Silicone Rubber:Silicone rubber cables maintain flexibility across a wide temperature range and possess good fire resistance, suitable for specific high-temperature or sensitive applications.
The selection of Cross-Linked Polyethylene dominates for its balanced performance, while Fluoropolymer cables are gaining share for niche, high-specification projects.
Application:
The volume of solar cable deployment varies significantly based on the scale and complexity of the photovoltaic installation.
- Residential Installations:These systems require cables suited for rooftop environments, often prioritizing ease of installation, compliance with local building codes, and aesthetic integration. Demand in Japan emphasizes compact, fire-resistant solutions for urban homes.
- Commercial Power Systems:Cables for commercial rooftops and ground-mounts handle moderate power levels, balancing durability with cost-efficiency for larger arrays.
- Utility-Scale Projects:Gigawatt-scale solar farms represent the largest segment, demanding vast quantities of high-voltage, durable cables capable of transmitting substantial power over long distances. Project developments in Australia drive extensive procurement for desert environments.
- Off-Grid Systems:Cables for remote power solutions emphasize robustness, reliability, and resistance to harsh environmental conditions without grid support.
- Agricultural Power Solutions:These applications require cables resistant to environmental factors like dust, moisture, and potential mechanical stress from farming equipment.
Margins are generally higher in Residential Installations due to specialized requirements, while Utility-Scale Projects drive volume-based pricing.
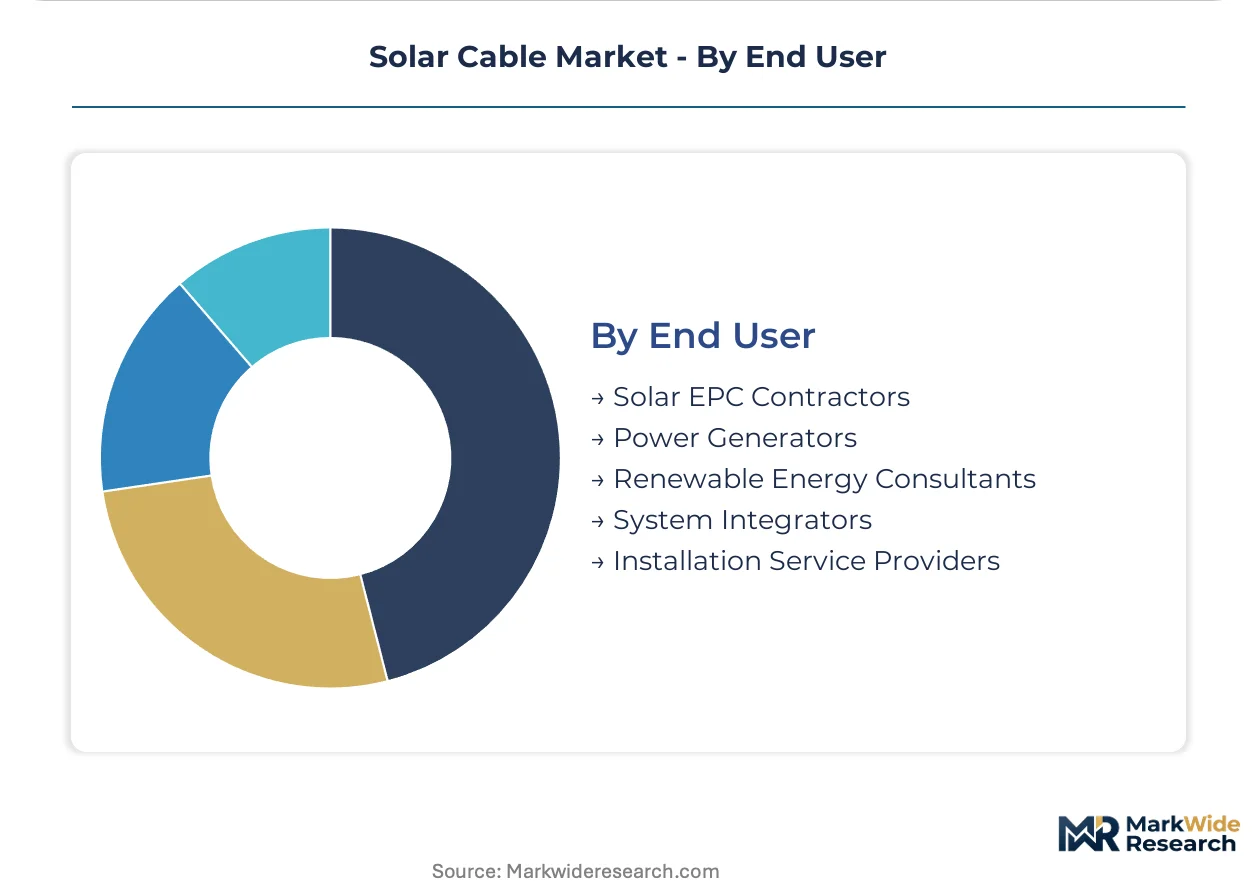
End User:
Different end-user categories exhibit distinct purchasing behaviors and technical specification requirements for solar cables.
- Solar EPC Contractors:EPCs procure cables in bulk for large-scale projects, prioritizing cost-effectiveness, timely delivery, and compliance with project-specific engineering standards. They drive significant demand for standardized, high-volume products in India.
- Power Generators:These entities focus on long-term reliability and performance, often specifying premium cables for their owned and operated solar assets to minimize downtime.
- Renewable Energy Consultants:Consultants influence cable specifications by recommending materials and types based on project design, regulatory compliance, and performance optimization.
- System Integrators:SIs combine various components into complete solar solutions, demanding flexible cable options that integrate seamlessly with diverse panel and inverter technologies. Demand from system integrators in the US focuses on NEC-compliant, easy-to-install solutions.
- Installation Service Providers:These providers purchase cables for smaller projects, valuing ease of handling, availability, and adherence to local electrical codes.
The most mature segment by procurement scale is Solar EPC Contractors, while System Integrators are expanding their influence on product choices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global solar cable market exhibits a clear divide between manufacturing hubs and high-consumption zones. Production capabilities for solar cables are heavily concentrated in specific industrial regions, while demand is geographically dispersed, driven by varying national energy policies. This dynamic creates complex supply chains balancing cost, compliance, and logistical efficiency.
China
China's immense utility-scale project expansion drives substantial demand for high-durability photovoltaic cables. The country's dual carbon goals mandate significant increases in renewable energy capacity across its vast landmass. Manufacturing clusters in the Yangtze River Delta produce high volumes of solar cables for both domestic and international utility-scale projects.
Germany
Germany's strong emphasis on renewable energy integration fuels demand for advanced solar cable solutions. The EU Green Deal and stringent building codes, like those for BIPV, shape product specifications. Bavarian industrial centers are increasingly specifying fluoropolymer cables for specialized, high-reliability solar environments.
United States
United States solar installations, particularly commercial and residential, require extensive lengths of compliant cables. Adherence to the US National Electrical Code (NEC) is a fundamental prerequisite for market access and product acceptance. System integrators in California focus on NEC-compliant, easy-to-install solutions for diverse rooftop and ground-mount projects.
India
India's ambitious renewable energy targets generate large-volume demand for standardized solar cables. The PLI scheme supports domestic manufacturing, influencing procurement patterns for PV components. Solar EPC contractors in Gujarat drive significant demand for high-volume products for new utility-scale solar farms.
Australia
Australia's abundant solar resources and large-scale project pipeline necessitate durable, high-performance solar cables. Government initiatives supporting renewable energy drive extensive procurement for vast desert environments. Utility-scale project developments in Queensland and New South Wales require cables capable of transmitting substantial power over long distances.
Solar Cable Market Key Industry Players
The competitive structure tilts toward a blend of established global conglomerates and specialized regional manufacturers. Market consolidation occurs among players with extensive global footprints and diverse product portfolios, serving multiple end-user segments. Strategic archetypes include large-scale integrated cable manufacturers, niche providers of specialized PV solutions, and cost-focused regional suppliers. Companies are pursuing strategic partnerships and capacity expansion to meet the growing demand from utility-scale projects and emerging solar geographies.
Among the global integrated cable manufacturers, Prysmian Group and Nexans exemplify companies with expansive international operations and broad product offerings. These entities anchor the premium segment, leveraging their extensive R&D capabilities and compliance with stringent international standards like IEC 62930. SUNKEAN Cable, a Chinese manufacturer, occupies a position among the specialized regional suppliers, focusing on cost-effective solutions for high-volume photovoltaic applications. These players collectively shape the market's technological trajectory and supply chain dynamics across various application segments.
| Leading Market Players |
|---|
| Lapp Group |
| SUNKEAN Cable |
| Prysmian Group |
| LS Cable & System |
| Shanghai Kuka Cable |
| Nexans |
| Belden |
| HELUKABEL |
| Southwire |
| Others |
Cost & Logistics Intelligence
Utility-scale EPC contractors primarily engage in project-based, contract-driven pricing for solar cables, which often ties to long-term raw material forecasts. This model is sensitive to input cost volatility, especially for copper and specialized polymers, directly impacting project profitability and procurement strategies.
Pricing Analysis
Margin compression across the solar cable market stems from intense competition among manufacturers and the fluctuating costs of raw materials. Pricing stratifies across premium, standard, and economy tiers, driven by factors like IEC 62930 certification, volume scale, and specialized geographic delivery costs for remote installations. Contract-based long-term offtake agreements dominate for large projects, providing some stability. Utility-scale EPCs exhibit high price sensitivity for bulk orders, while asset owners prioritize verifiable long-term performance data over initial per-meter costs.
Supply Chain Analysis
Logistical complexities and freight costs significantly influence solar cable supply, especially for heavy cable drums shipped to remote utility-scale sites. Supply concentration centers heavily on China for manufacturing, with key raw materials like copper and XLPE polymers sourced globally. Geopolitical tensions affecting manufacturing hubs or international shipping routes represent a structural supply chain risk. Distribution typically occurs through direct sales to large EPC contractors, complemented by specialized distributors serving smaller commercial and residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained story, where the limited global capacity for high-performance XLPE and fluoropolymer cable production props up pricing for specialized solutions.
For Market Incumbents: To counter the pervasive threat of counterfeit products and raw material price volatility, incumbents must deepen vertical integration into advanced polymer compounding. Investing in robust supply chain authentication technologies and expanding IEC 62930-compliant manufacturing capacity in emerging solar geographies like Southeast Asia will reinforce market leadership. Developing alternative conductor materials, such as copper-clad aluminum, offers a strategic hedge against copper price fluctuations.
For New Entrants and Emerging Players: Begin with targeting specialized application niches such as floating solar farms or building-integrated photovoltaics (BIPV) where specific performance requirements command higher margins. Focusing on compliance with stringent local standards, like the US National Electrical Code (NEC) for North American markets, provides a clear go-to-market angle. Emphasize innovative material solutions, such as enhanced water-resistant or halogen-free flame-retardant (HFFR) cables, to differentiate from commodity offerings.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized manufacturers with strong R&D capabilities in advanced materials within stable regulatory environments like Germany. The long-term viability of the solar cable market is anchored by global decarbonization targets and the increasing emphasis on asset longevity. An acquisition target archetype includes mid-sized companies possessing proprietary polymer formulations or advanced testing certifications. The signal to watch is the accelerating adoption rate of high-performance, advanced polymer compounds in utility-scale projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Polymers | Increases supply of high-performance XLPE and fluoropolymer cables for specialized applications. |
| R&D in Alternative Conductor Materials | Mitigates exposure to copper price volatility, offering cost-effective solutions for EPC contractors. |
| Strengthened Supply Chain Authentication | Combats counterfeit products, ensuring system safety and protecting legitimate manufacturer brand equity. |
| Certification to IEC 62930 and NEC Standards | Guarantees market access and product acceptance in major solar installation geographies. |
| Geographic Manufacturing Footprint Diversification | Reduces geopolitical supply chain risks and improves logistics for global utility-scale projects. |
Research Approach
IEC 62930 standards, EU Green Deal policy documents, and national energy agency reports formed the secondary backbone for this solar cable market analysis. This foundational data was rigorously cross-referenced with primary insights from utility-scale EPC procurement managers, solar project developers, and cable material scientists. The research methodology employed a blend of bottom-up market sizing and top-down validation, incorporating insights from renewable energy consultants.
Historical trendline analysis established the baseline for the forecast framework, projecting growth patterns across the analysis window. The model integrated segmentation dimensions including product type, material, application, end-user, and regional deployment patterns. Compound annual growth rates were derived from an assessment of demand-side drivers, such as national decarbonization targets, and supply-side factors like raw material price forecasts and manufacturing capacity expansions.
Underlying measurement precision varies by segment; utility-scale projects and XLPE materials carry tighter precision than others. Forecasts reflect assumptions regarding evolving regulatory landscapes and technological advancements in cable design. Stakeholders should weight assumptions against their own operating context, considering specific risk factors like geopolitical shifts impacting supply chains or unexpected raw material price spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Power Cable Accessories Market
Cables
Cable Testing and Certification Market
Cables
Sensing Cable Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Cable Clamp Market
Cables
Global Low Voltage Cable Market
Cables
Ethernet Converters Market
Cables
Cable Racks Market
Cables
Latin America Wire and Cable Market
Cables
South Africa Wire and Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Cable Tray Market
Cables
Mexico Wires and Cables Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Cable Carrier Market
Cables
Submarine Cabling Systems Market