
 Infrared Filter Market | 2026-2036
Infrared Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Filter Market Foresight
Specialized thin-film coating engineers is rotating toward infrared filter manufacturers as semiconductor and defense sectors compete for the same photonics talent pool. Hoya Corporation leverages its century-long glass formulation heritage to sustain premium positioning in medical and aerospace qualification tiers. Schott AG anchors European supply through its certified melting operations in Mainz, while TDK Corporation competes in Asia-Pacific electronics channels with volume-scaled polymer-hybrid lines. Crystal-Optech differentiates via integrated design-to-coating workflows that shorten prototype cycles for Chinese thermal imaging OEMs.
An infrared filter selectively transmits or blocks specific wavelengths in the near-infrared to far-infrared spectrum, typically constructed from doped glass substrates or dielectric thin-film stacks deposited through ion-assisted deposition or sputtering processes, serving to isolate target spectral bands in thermal imaging systems, optical communication hardware, and analytical instruments. Bandpass filters command the deepest margin pools in military and medical applications where coating layer count exceeds one hundred and qualification cycles extend across multiple years. Thin film coatings represent the fastest-growing technology segment as deposition equipment makers improve uniformity control across larger substrate formats, while polymer filters occupy cost-sensitive consumer electronics tiers where transmission efficiency trade-offs are acceptable.
US ITAR export controls and FDA device classification requirements shape product development roadmaps for suppliers targeting defense and diagnostic imaging end users, while REACH substance restrictions in Europe constrain certain dopant chemistries in glass melting operations. China's GB standards for optoelectronic components and NMPA medical device registration rules create parallel compliance pathways for domestic market access. Stakeholders must monitor how dual-use technology trade policies and evolving automotive functional safety standards redirect qualification investments across regional manufacturing footprints.
Market Dynamics
Thin-film deposition equipment advances are fragmenting the supplier base by enabling new entrants to match legacy coating uniformity without decades of process know-how accumulation. Automotive OEMs now specify infrared filters directly rather than delegating to Tier-1 module integrators, compressing qualification timelines and reshaping volume allocation.
Growth Catalysts
- Thermal imaging in ADAS:Night vision mandates from NHTSA are pushing German and Japanese automakers to qualify dual-band filters for pedestrian detection systems.
- REACH substance restrictions:European constraints on certain dopant chemistries are accelerating dielectric thin-film substitution for doped glass in medical device applications.
- Ion-assisted deposition:Equipment makers in Japan and Germany are improving coating uniformity across 300mm substrates, enabling wafer-scale filter production for consumer electronics.
Market Restraints
- Raw material concentration:Germanium substrate supply concentrates among Chinese and Russian refiners, creating geopolitical exposure for far-infrared filter makers.
- ITAR compliance burden:US export controls extend qualification cycles for defense-qualified suppliers, freezing out mid-tier manufacturers from military revenue pools.
- Polymer substitution threat:Volume-scaled polymer-hybrid filters from Asia-Pacific electronics channels are capturing cost-sensitive consumer tiers where transmission efficiency trade-offs are acceptable.
Strategic Opportunities
- India defense modernization:Domestic thermal sight procurement under the Make in India initiative is creating captive demand for locally qualified filter suppliers.
- EU Green Deal incentives:Carbon-neutral manufacturing certifications are opening preferential procurement channels for European coating houses with renewable-powered deposition lines.
- Hyperspectral convergence:Integration of infrared filtering with computational imaging algorithms is enabling new agricultural and mineralogical survey applications.
Industry Challenges
- Photonics talent scarcity:Specialized thin-film coating engineers are rotating toward semiconductor lithography and defense primes, lengthening hiring cycles for filter manufacturers.
- Multi-year qualification timelines:FDA device classification and NMPA medical device registration rules extend development-to-revenue intervals beyond typical venture capital horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Filter Market |
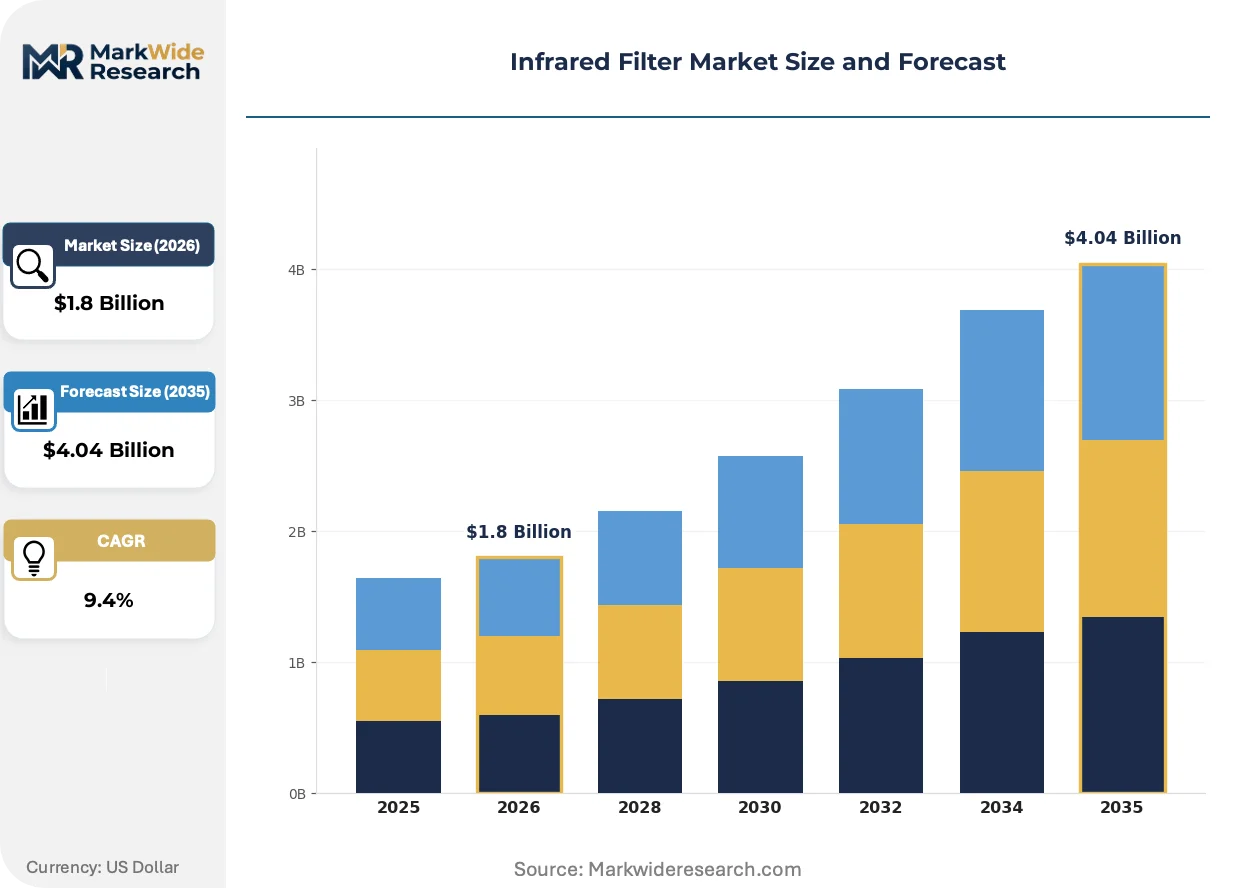
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandpass Filters, Longpass Filters, Shortpass Filters, Neutral Density Filters Application: Optical Communication, Thermal Imaging, Spectroscopy, Night Vision End User: Aerospace, Automotive, Electronics, Medical Technology: Thin Film Coatings, Polymer Filters, Glass Filters, Hybrid Filters |
| Companies Covered | Hubei Wufang Photoelectric, OPTRONTEC, Crystal-Optech, Hermosa Optics, Tanaka Engineering, TDK Corporation, Hoya Corporation, AGC, Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Filter Market Shifts & Advancements
Deposition technology democratization is compressing the traditional moat of process expertise that protected established coating houses. Equipment automation and metrology advances are enabling new entrants to achieve specification parity with shorter learning curves.
Atomic layer deposition for infrared optical coatings is fragmenting the competitive landscape by allowing precise thickness control at angstrom-scale resolution. Medical device manufacturers in Germany and Japan are adopting ALD-filtered detectors for diagnostic imaging systems requiring extreme spectral purity. The technology is fragmenting margin pools by reducing the minimum viable scale for premium filter production from dedicated coating lines to batch-processing equipment.
EU F-Gas Regulation phase-down schedules are constraining fluorinated precursor availability for plasma-enhanced chemical vapor deposition processes. Coating houses in Mainz and Jena are reformulating process chemistries to maintain production continuity under tightening substance restrictions. Military and aerospace filter suppliers face the steepest adaptation costs due to extended requalification protocols for changed material compositions.
Automotive OEMs are consolidating supplier relationships through direct filter specification rather than delegating to thermal camera module integrators. Tier-1 vision system suppliers in Stuttgart and Nagoya are losing procurement influence as vehicle manufacturers centralize optical component sourcing. This pattern is most pronounced in Germany where premium OEMs maintain captive optical engineering teams capable of validating coating designs internally.
Infrared Filter Market Segmentation
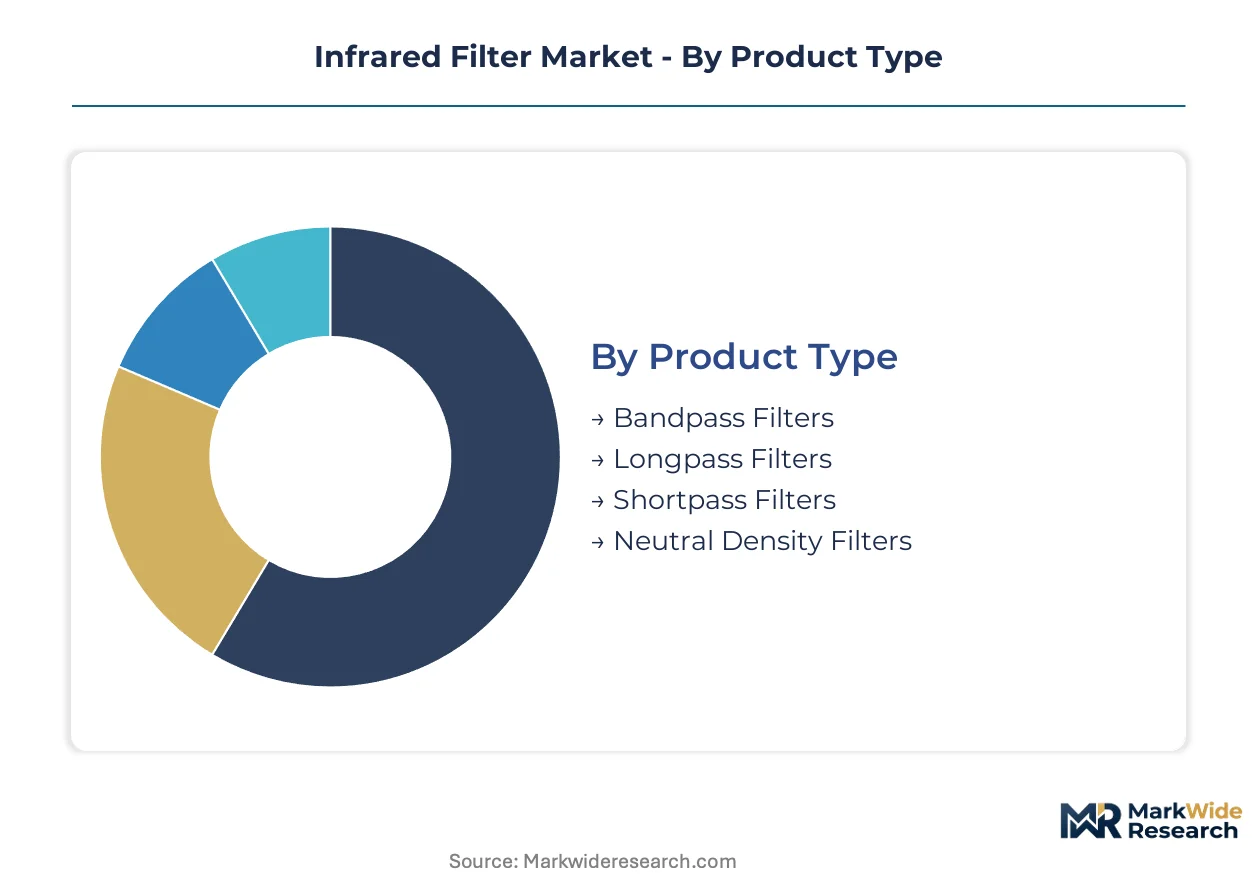
Infrared filter procurement channels diverge sharply by performance tier, with defense and medical buyers demanding qualification-heavy bandpass designs while consumer electronics flows favor polymer-hybrid volume contracts. Segment-specific coating technologies and substrate choices determine which suppliers can access each revenue pool.
Product Type:
Channel mix splits between direct OEM specification for high-layer-count designs and distributor-mediated flows for standard catalog parts, with defense primes and automotive Tier-1s controlling the premium procurement pathway.
- Bandpass Filters:Constructed from dielectric thin-film stacks exceeding one hundred layers, these isolate narrow spectral windows for thermal imaging and diagnostic applications. Demand concentrates in German automotive night vision programs and US defense thermal sight procurements where NHTSA pedestrian detection mandates and ITAR compliance requirements extend qualification cycles.
- Longpass Filters:Transmit wavelengths above a specified cutoff while attenuating shorter radiation, typically fabricated through ion-assisted deposition on germanium or silicon substrates. Japanese electronics OEMs and Chinese thermal camera manufacturers drive volume, with wafer-scale deposition equipment enabling cost compression for consumer-tier applications.
- Shortpass Filters:Block infrared transmission while passing visible light, serving sensor protection and color correction roles in imaging systems. German precision optics houses in Jena and Mainz dominate supply for industrial machine vision and laboratory instrumentation.
- Neutral Density Filters:Attenuate intensity uniformly across the infrared spectrum without altering spectral composition, finding use in laser power measurement and detector calibration. Scientific instrument manufacturers in Japan and Switzerland constitute the primary demand channel.
By volume, longpass filters lead through electronics sector absorption. By growth pace, bandpass designs are ahead on ADAS and defense thermal imaging expansion.
Application:
Cost tier stratification separates qualification-intensive defense and medical applications from price-sensitive consumer electronics deployments, with coating layer count and substrate material as the primary cost drivers.
- Thermal Imaging:Night vision systems for automotive ADAS and military platforms require dual-band filters with precise transmission characteristics across mid-wave and long-wave infrared. German OEMs in Stuttgart specify coatings directly, bypassing traditional Tier-1 module integrators and compressing supplier qualification timelines.
- Optical Communication:Datacenter interconnects and fiber optic networks deploy shortpass and bandpass designs for wavelength division multiplexing. Chinese equipment manufacturers and US cloud infrastructure deployers drive volume through polymer-hybrid filters where transmission efficiency trade-offs are acceptable.
- Spectroscopy:Analytical instruments for chemical composition and materials analysis demand extreme spectral purity with minimal out-of-band leakage. German and Japanese laboratory equipment manufacturers specify ALD-coated filters for pharmaceutical quality control and semiconductor metrology.
- Night Vision:Military thermal sights and surveillance systems combine longpass and bandpass architectures for all-weather target acquisition. ITAR-controlled US suppliers and emerging Indian domestic producers under Make in India initiatives compete for defense procurement contracts.
Thermal imaging commands the steepest margin tiers. Optical communication is climbing the fastest on datacenter buildout acceleration.
End User:
Customer type determines qualification burden and contract structure, with aerospace and medical buyers demanding multi-year validation cycles while automotive and electronics sectors prioritize volume scalability and cost reduction.
- Automotive:Night vision and pedestrian detection systems integrate infrared filters into forward-looking thermal cameras, with German and Japanese OEMs centralizing optical component sourcing away from Tier-1 integrators. Direct filter specification is reshaping supplier relationships and compressing development-to-production timelines.
- Aerospace:Satellite thermal imaging and aircraft enhanced vision systems require radiation-hardened coatings with extreme environmental durability. US ITAR regulations and European Space Agency qualification protocols create dual compliance pathways for suppliers seeking access to both markets.
- Medical:Diagnostic imaging and surgical navigation systems demand FDA and NMPA-registered filters with biocompatibility certification. German and Japanese device manufacturers specify premium bandpass designs for fluorescence imaging and optical coherence tomography applications.
- Electronics:Consumer thermal cameras, smartphones, and gaming peripherals absorb volume-scaled polymer and hybrid filters. Chinese OEMs and South Korean electronics conglomerates drive procurement through Asia-Pacific distribution channels with compressed lead times.
Electronics leads by unit volume. Automotive is gaining share fastest on ADAS penetration acceleration.
Technology:
Supply concentration clusters around deposition equipment access and process expertise, with thin-film coating houses in Germany and Japan defending premium positions against polymer-hybrid challengers from Asia-Pacific electronics channels.
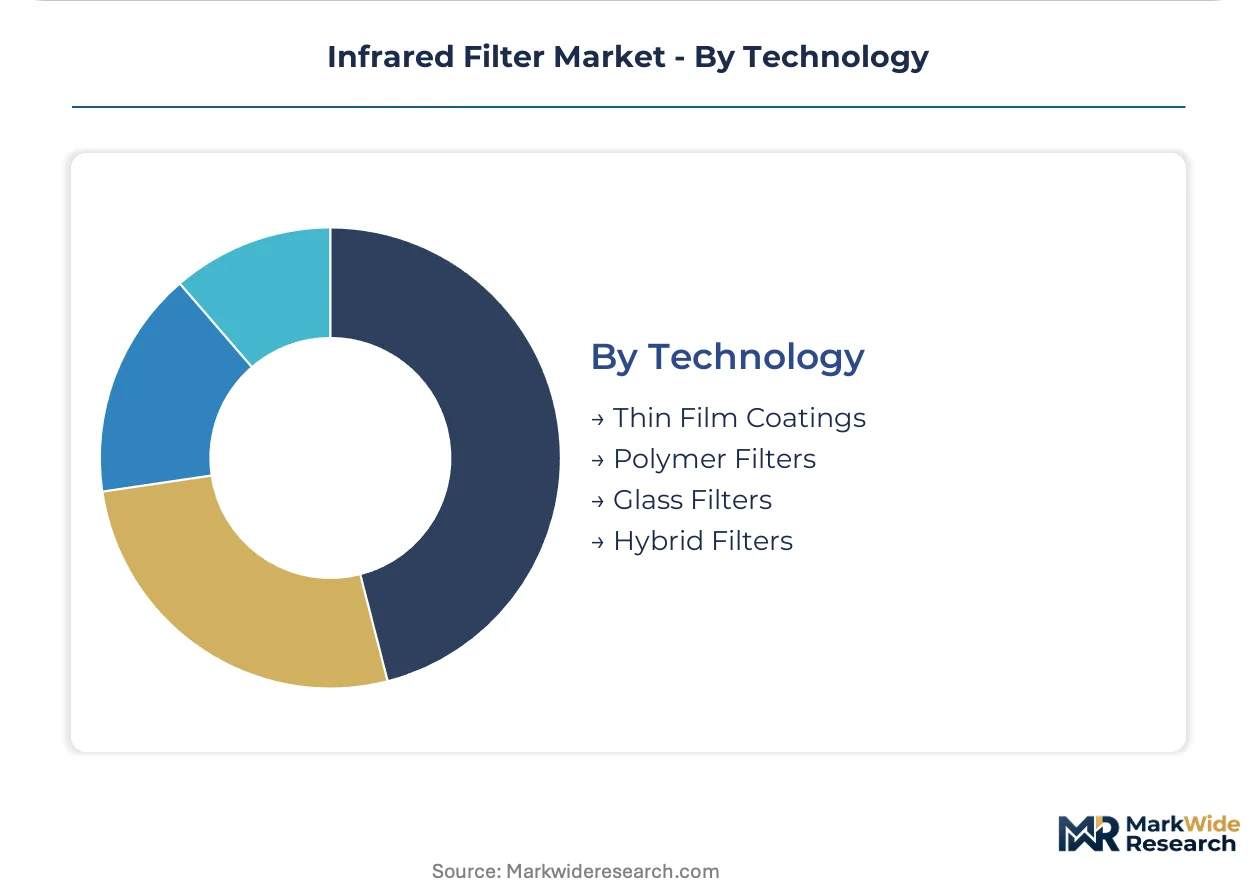
- Thin Film Coatings:Dielectric stacks deposited through ion-assisted deposition or sputtering deliver highest transmission efficiency and spectral selectivity. Equipment advances from Japanese and German makers are democratizing coating uniformity control, enabling new entrants to match legacy process expertise.
- Polymer Filters:Volume-scaled organic substrates with infrared-absorbing dyes serve cost-sensitive consumer applications. Chinese and South Korean electronics supply chains dominate manufacturing, capturing smartphone and peripheral demand where performance trade-offs are economically acceptable.
- Glass Filters:Doped substrates from certified melting operations provide environmental stability for aerospace and military applications. Schott AG's Mainz facility anchors European supply, with REACH substance restrictions accelerating dielectric substitution for certain dopant chemistries.
- Hybrid Filters:Combine polymer substrates with thin-film surface coatings to balance cost and performance for mid-tier industrial and automotive applications. Chinese thermal imaging OEMs favor integrated design-to-coating workflows that shorten prototype development cycles.
Glass filters retain the premium tier by qualification lock-in. Thin film coatings are expanding most quickly on deposition equipment democratization and wafer-scale format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs consume infrared filters for direct specification in night vision systems, while Chinese manufacturers absorb volume-scaled polymer-hybrid designs for consumer electronics, creating a demand-mix split between qualification-intensive and cost-sensitive procurement patterns.
United States
Defense thermal sight programs and FDA-regulated diagnostic imaging equipment drive premium bandpass filter demand. ITAR export controls extend supplier qualification cycles, freezing mid-tier manufacturers from military revenue pools. Boston-area precision optics clusters and Southern California aerospace suppliers concentrate coating expertise for satellite and aircraft applications.
Germany
Automotive OEMs in Stuttgart and Munich specify infrared filters directly for pedestrian detection systems, bypassing traditional Tier-1 integrators. REACH substance restrictions on dopant chemistries accelerate dielectric thin-film substitution for doped glass in medical devices. Mainz and Jena host certified melting operations and coating houses serving European defense and aerospace primes.
China
Domestic thermal imaging OEMs and consumer electronics manufacturers absorb longpass and polymer-hybrid filters at volume scale. GB standards for optoelectronic components and NMPA medical device registration rules create parallel compliance pathways for local market access. Yangtze River Delta and Pearl River Delta clusters concentrate wafer-scale deposition equipment and integrated design-to-coating workflows.
Japan
Electronics OEMs and precision instrument manufacturers drive demand for ion-assisted deposition equipment and ALD-coated filters. METI industrial policy supports photonics equipment makers improving coating uniformity across 300mm substrates. Nagoya and Osaka metropolitan areas host thin-film deposition technology suppliers and automotive vision system integrators.
India
Domestic thermal sight procurement under the Make in India initiative creates captive demand for locally qualified filter suppliers. DGFT import substitution policies and defense modernization budgets redirect qualification investments toward indigenous manufacturing. Bengaluru and Hyderabad defense corridors attract coating houses seeking military contract access.
Infrared Filter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with century-old glass formulators and electronics conglomerates defending premium positions against emerging coating houses enabled by deposition equipment democratization. Market structure stratifies across qualification-intensive defense-medical tiers and volume-scaled consumer electronics channels. Three archetypes dominate: heritage glass-melting operations with certified aerospace supply, Asia-Pacific electronics channels with polymer-hybrid scale, and integrated design-to-coating specialists compressing prototype cycles. Competitive moves concentrate on direct OEM specification capture and wafer-scale format adoption.
Within the heritage tier, Schott AG and Hoya Corporation exemplify long-established positioning through certified melting operations and glass formulation expertise. TDK Corporation represents the scale-driven electronics channel archetype. Crystal-Optech occupies a specialist position among Chinese-integrated design-to-coating workflows.
| Leading Market Players |
|---|
| Hubei Wufang Photoelectric |
| OPTRONTEC |
| Crystal-Optech |
| Hermosa Optics |
| Tanaka Engineering |
| TDK Corporation |
| Hoya Corporation |
| AGC |
| Schott AG |
| Others |
Supply & Pricing Matrix
Wafer-scale deposition equipment utilization above 80% in Japanese and German coating houses creates asymmetric cost structures that concentrate premium-tier supply among heritage operators while compressing price floors for mid-tier polymer-hybrid alternatives. This scale divergence shapes procurement bifurcation: automotive OEMs and defense primes absorb qualification-intensive bandpass designs at stable contract values, while consumer electronics channels drive spot-market volatility for volume-scaled longpass and shortpass filters.
Pricing Analysis
Long-term offtake contracts dominate defense and medical procurement, with ITAR-qualified US suppliers and FDA-registered German manufacturers locking in multi-year pricing through dedicated capacity reservations. Price differentiation hinges on certification tier—REACH-compliant dielectric stacks command 40-60% premiums over standard coatings—and volume scale, with wafer-scale orders above 10,000 units triggering step-down pricing schedules. Pricing pressure stems from polymer-hybrid substitution in consumer electronics, where Chinese OEMs negotiate aggressive spot terms. Medical device manufacturers exhibit lowest price sensitivity due to extended requalification costs, while smartphone peripheral suppliers maximize cost compression.
Supply Chain Analysis
Germanium substrate refining concentrates among Chinese and Russian state-linked processors, creating single-source vulnerability for far-infrared filter makers dependent on 6N+ purity metal. Ion-assisted deposition equipment draws from Japanese and German precision machinery specialists, while dopant chemistries for glass melting rest on Belgian and Austrian specialty chemical suppliers. Tariff exposure intensifies as US-China dual-use technology controls disrupt substrate flows. Distribution runs through direct OEM specification for premium tiers, with catalog parts flowing via regional optics distributors in Stuttgart, Nagoya, and Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film coating engineering expertise has become the binding constraint across defense, semiconductor lithography, and medical device sectors, with hiring cycles extending 18-24 months for qualified deposition process leads. This capability scarcity elevates the strategic value of incumbent process know-how while complicating new entrant scaling timelines.
For Market Incumbents: Shield premium positioning by embedding coating engineers within automotive OEM optical validation teams in Stuttgart and Nagoya, compressing competitor access to specification channels. Accelerate backward integration into germanium substrate processing through offtake partnerships with Chinese refiners, reducing exposure to supply disruption. Defend against ALD-fragmentation by patenting proprietary layer-stack architectures for pedestrian detection filters. For New Entrants and Emerging Players: Anchor in India's Make in India defense procurement corridor, where domestic qualification requirements create protected demand for locally certified bandpass suppliers. Target hybrid filter production for Chinese thermal imaging OEMs seeking integrated design-to-coating workflows with sub-12-week prototype cycles. Pursue equipment-leasing partnerships with Japanese deposition machinery makers to bypass capital-intensive coating line ownership. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive glass-melting and coating capabilities, as deposition equipment democratization erodes pure-play coating house margins. Long-term viability rests on qualification lock-in duration—defense-aerospace certification cycles spanning 5-10 years create durable revenue visibility. Watch for NHTSA night vision mandate expansion as inflection signal for ADAS-filter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Specification Capture | Bypasses Tier-1 integrators in Stuttgart and Nagoya, securing volume allocation for ADAS programs. |
| Wafer-Scale Deposition Investment | Enables cost parity with polymer-hybrid alternatives in consumer electronics channels. |
| ALD Process Patenting | Creates IP moats against equipment-democratized new entrants in medical imaging tiers. |
| Germanium Substrate Integration | Reduces geopolitical exposure from Chinese and Russian refiner concentration. |
| EU Green Deal Certification | Opens preferential procurement channels for renewable-powered coating operations in Mainz. |
Research Methodology
Initial hypotheses were tested against primary input from thin-film coating process engineers, automotive OEM optical validation leads, defense procurement officers, and medical device regulatory affairs specialists, then refined through secondary validation against SEC filings of precision optics suppliers, ECHA REACH substance restriction updates, NHTSA pedestrian detection rulemaking dockets, and Japanese METI photonics equipment production statistics. Bottom-up demand modeling across filter product types, applications, and end-user segments was triangulated with top-down market sizing derived from deposition equipment installation records and substrate consumption data.
Variance decomposition across the projection horizon isolates volume drivers—ADAS penetration rates, defense modernization budgets, datacenter interconnect buildout—from pricing dynamics including raw material pass-through clauses and certification premium erosion. Segmentation dimensions span product architecture, coating technology, substrate material, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to equipment capacity expansion announcements and OEM qualification pipeline visibility. Industry-specific inputs include ion-assisted deposition uniformity improvement trajectories and REACH substance substitution timelines.
Decision-makers should treat outputs as directional under assumptions of stable dual-use technology trade policy and continued automotive night vision mandate expansion; material deviation would warrant model refresh. Specific risk factors include germanium supply disruption from geopolitical friction, ALD technology adoption acceleration compressing incumbent margins, and polymer-hybrid performance improvement eroding thin-film cost premiums. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and India defense import substitution policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Fiber-Optic Attenuator Market
Optical Components
US Optical Sensors Market
Optical Components
Faraday Rotator Market
Optical Components
Optical Film Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Europe Scintillator Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Optical Transceiver Market
Optical Components
Bio-Optics Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Fiber Optic Plates (FOP) Market