
 Asia-Pacific Premise Cable Market | 2026-2036
Asia-Pacific Premise Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Premise Cable Market Insights
Polyethylene jacketing is recalibrating cost-performance benchmarks for outdoor-rated premise cables across humid tropical climates. Furukawa Electric leverages its compound formulation expertise to sustain margin in Japanese infrastructure renewals. LS Cable & System anchors Korean supply through integrated copper smelting and extrusion capacity. CommScope Holding Company Inc. competes on scale in Australian data center interconnect projects, where lead times compress contract awards.
Premise cable denotes structured cabling installed within building boundaries or campus environments, typically comprising twisted-pair copper conductors with polyethylene or PVC insulation, fiber optic strands with acrylate buffer coatings, or coaxial constructions with braided shielding, engineered to distribute voice, data, and video signals across localized networks. Fiber optic cable segments command premium positioning as hyperscale facilities displace copper for backbone links exceeding 100 meters. Indoor installation types dominate volume in Japan and South Korea's dense urban cores, where building codes restrict plenum-rated combustible materials. Multi-pair cable retains steady replacement demand across India's commercial retrofit sector, though fiber-to-the-desk conversion narrows its growth trajectory.
China's MIIT enforces GB 50311 and GB 50312 standards for structured cabling design and verification, compelling foreign suppliers to certify through the country's national standardization body before project participation. Australia's ACMA cabling provider rules mandate technician licensing for all optical fiber and coaxial terminations, restricting market access to trained installation networks. India's BIS certification for fire-resistant cable jackets, aligned with CEA electrical safety directives, raises compliance costs for imported product lines. Stakeholders must weigh localization investments against certification burden as procurement specifications diverge across national standards regimes.
Market Dynamics
Hyperscale data center buildouts across Southeast Asia are compressing procurement cycles and forcing cable suppliers to pre-certify against divergent national standards before project bidding begins.
Growth Catalysts
- GB 50311/50312 Compliance Mandates:China's MIIT standards for structured cabling design and verification compel infrastructure upgrades in tier-one cities, locking in replacement demand for certified copper and fiber assemblies.
- Cloud Provider Facility Buildouts:Alibaba, Tencent, and ByteDance data center expansions along China's eastern seaboard require massive volumes of backbone fiber exceeding 100-meter copper limitations.
- India Smart Cities Mission:Urban infrastructure modernization directives mandate fire-resistant cable deployments across commercial and municipal buildings, tightening jacket specifications under CEA electrical safety alignment.
Market Restraints
- Copper Price Volatility:LME copper fluctuations directly compress extrusion margins for Korean and Chinese manufacturers lacking captive smelting capacity.
- Import Certification Burden:India's BIS fire-resistant jacket certification and Australia's ACMA technician licensing rules create 6-12 month market entry delays for non-local suppliers.
- Fiber-to-the-Desk Substitution:Single-mode fiber price erosion below $0.50 per meter in bulk contracts narrows multi-pair copper's addressable market in premium commercial retrofits.
Strategic Opportunities
- Indonesia Data Center Greenfield:Jakarta and Batam hyperscale projects lack established cabling vendor relationships, creating first-mover positioning for certified suppliers.
- Philippines Submarine Cable Landings:Domestic fiber backhaul buildouts from landing stations to metro cores require specialized armored premise cable for humid tropical coastal zones.
- Vietnam Industrial Zone Expansion:Northern manufacturing clusters near Hai Phong are mandating Category 8 copper for smart factory automation, ahead of regional adoption curves.
Industry Challenges
- Certified Technician Scarcity:Australia's ACMA licensing requirements for optical fiber terminations outstrip training program output, extending project timelines.
- Legacy Building Code Fragmentation:Japan's METI plenum-rated material restrictions, Korea's KTL fire standards, and China's GB combustibility tiers force SKU proliferation without harmonization.
- Pre-Installation Testing Complexity:GB 50312 verification protocols for insertion loss and return loss require specialized OTDR equipment rarely available through general electrical contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Premise Cable Market |
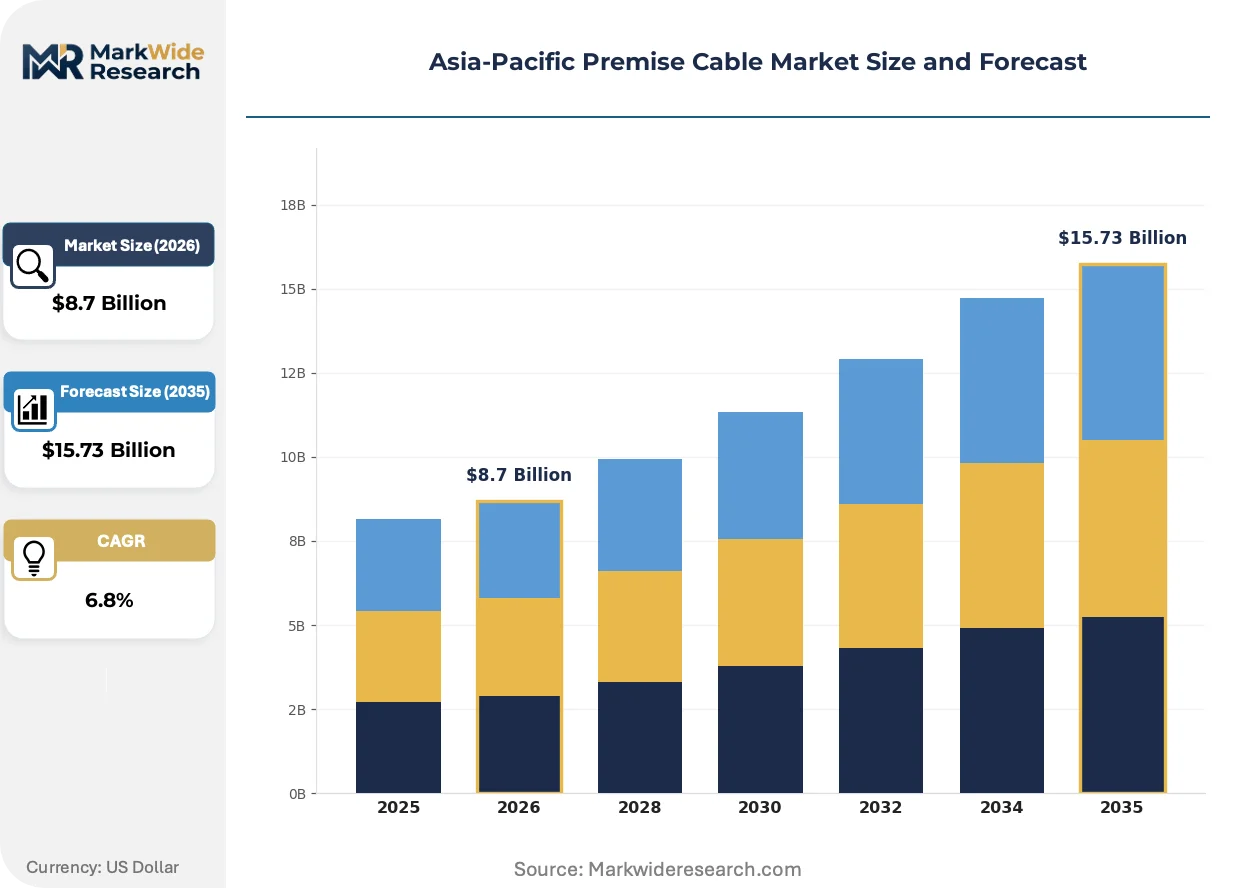
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Cable, Fiber Optic Cable, Coaxial Cable, Multi-Pair Cable Installation Type: Indoor, Outdoor, Aerial, Underground End User: Commercial, Residential, Industrial, Educational Usage: Networking, Telecommunications, CCTV, Data Transmission |
| Companies Covered | Furukawa Electric, Belden Inc., Prysmian Group, LS Cable & System, CommScope Holding Company Inc., Nexans, Sumitomo Electric, Hitachi Cable, Corning Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Premise Cable Market Trends and Innovations
Active optical cable assemblies and pre-terminated fiber solutions are compressing field installation labor content while raising factory precision requirements for Asia-Pacific suppliers.
Single-mode fiber with bend-insensitive coating is decentralizing data center top-of-rack architectures by eliminating traditional main distribution frame hierarchies. Hyperscale operators in Singapore and Sydney deploy direct server-to-switch links under 30 meters, bypassing structured cabling zones entirely. This topology shift is decentralizing procurement authority from facilities teams to server hardware buyers.
China's MIIT enforcement of GB 50311-2016 design standards and GB 50312-2016 verification protocols tightens documentation requirements for foreign suppliers seeking state-owned enterprise contracts. Compliance now demands third-party testing through the country's national standardization body, adding 8-14 weeks to qualification timelines. State-owned data center operators in Beijing and Shanghai are prioritizing pre-certified domestic suppliers to accelerate project approvals.
Direct procurement from cable manufacturers by hyperscale cloud operators is displacing traditional distribution through electrical wholesalers in Australia and Japan. Amazon Web Services and Google Cloud negotiate multi-year frame agreements specifying exact fiber counts, jacket compounds, and reel lengths delivered to construction sites. This channel compression is most visible in Sydney's Western Parkland City data center cluster, where distributor margins have compressed below 8 percent on fiber backbone contracts.
Asia-Pacific Premise Cable Market Segmentation
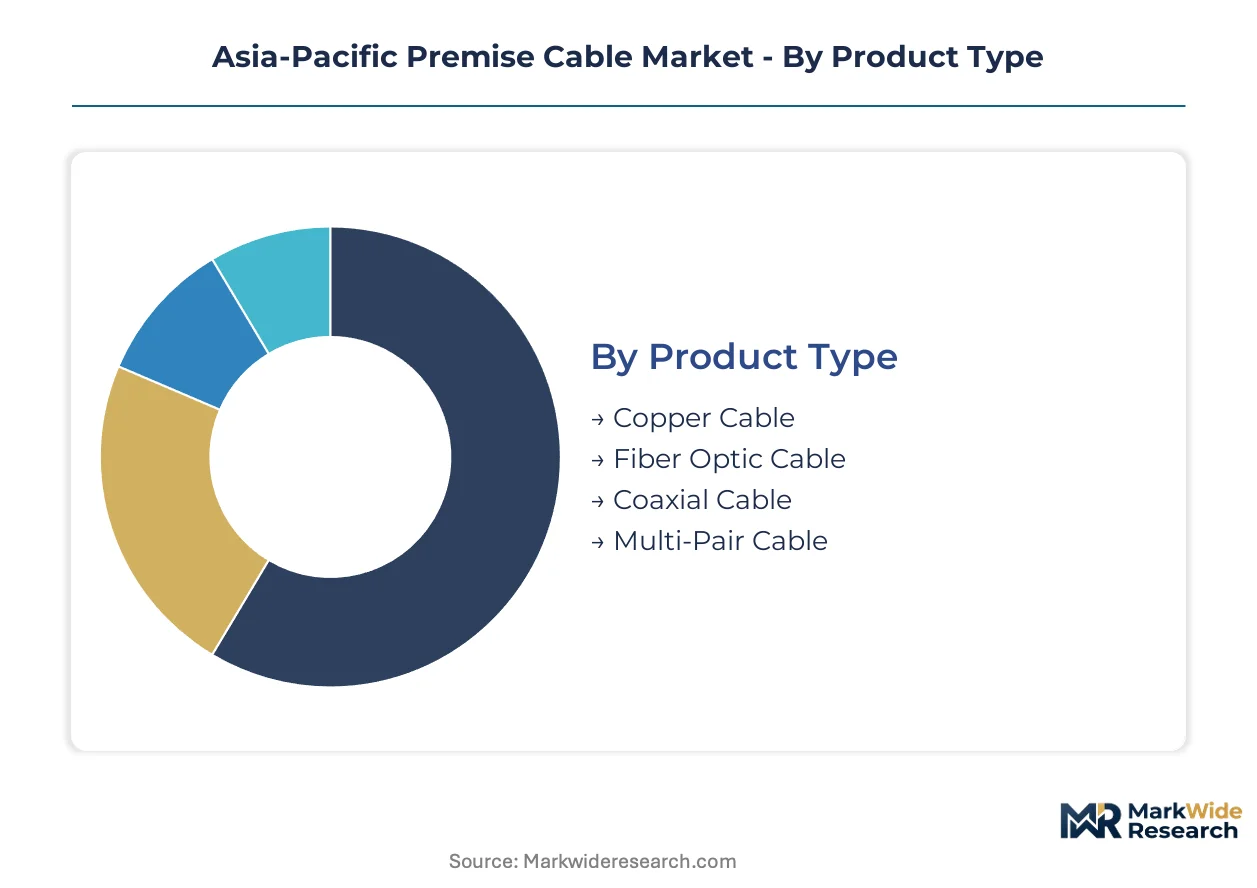
Premise cable procurement in Asia-Pacific splits sharply between commodity volume plays and specification-driven premium contracts. Understanding where each segment sits on this spectrum determines supplier positioning across China's state-owned data center builds, India's Smart Cities deployments, and Southeast Asian hyperscale greenfields.
Product Type:
Copper cable dominates raw volume across India's commercial retrofit sector and Vietnam's industrial zones, while fiber optic commands pricing power in backbone applications exceeding 100 meters.
- Copper Cable:Twisted-pair conductors with polyethylene or PVC insulation distribute voice and data signals across localized networks under 100 meters. Demand concentrates in India's commercial retrofit sector, where multi-pair Category 5e and 6 installations face narrowing growth trajectories from fiber substitution. Replacement cycles sustain volume despite price pressure.
- Fiber Optic Cable:Glass strands with acrylate buffer coatings transmit high-bandwidth signals across backbone links exceeding copper distance limitations. Cloud provider facility buildouts along China's eastern seaboard absorb massive single-mode volumes, with Alibaba and Tencent specifying exact fiber counts and jacket compounds in direct manufacturer negotiations.
- Coaxial Cable:Braided shielding constructions retain niche positioning in legacy CCTV and broadband distribution networks across older Japanese commercial buildings.
- Multi-Pair Cable:Bundled copper configurations serve telephone and low-speed data applications in India's municipal infrastructure and educational retrofits under Smart Cities Mission directives.
Today's leader: Copper cable. Tomorrow's challenger: Fiber optic cable.
Installation Type:
Indoor-rated products face stricter combustibility regulations than outdoor equivalents, with Japan's METI plenum restrictions and China's GB combustibility tiers forcing material specification divergence.
- Indoor:Plenum and riser-rated jackets meet building code restrictions on combustible materials in enclosed spaces. Japan and South Korea's dense urban cores generate concentrated demand, where fire-resistant specifications under BIS, KTL, and GB standards raise compliance costs for imported product lines.
- Outdoor:Polyethylene-jacketed constructions withstand moisture and UV exposure in humid tropical climates. Furukawa Electric's compound formulation expertise sustains margin in Japanese infrastructure renewals, while LS Cable & System anchors Korean supply through integrated extrusion capacity.
- Aerial:Self-supporting messenger wire configurations serve last-mile connectivity in Philippine and Indonesian archipelago deployments where underground trenching proves cost-prohibitive.
- Underground:Armored and gel-filled constructions protect against rodent damage and groundwater infiltration in Australian data center campus environments and Singapore's dense urban utility corridors.
Indoor installation generates premium pricing through certification burden; outdoor commands volume scale across Southeast Asian greenfield expansion.
End User:
Commercial and industrial buyers specify performance-grade cabling, while residential and educational procurement emphasizes cost minimization under public budget constraints.
- Commercial:Office buildings, retail centers, and hospitality venues demand Category 6A and fiber-to-the-desk configurations for high-density connectivity. Australia's ACMA licensing requirements for technician certification restrict installation networks, compressing procurement cycles for pre-qualified suppliers.
- Residential:Multi-dwelling unit deployments in China's tier-two cities and India's urban housing projects prioritize cost-optimized Category 5e copper over fiber deep penetration.
- Industrial:Smart factory automation in Vietnam's northern manufacturing clusters near Hai Phong is mandating Category 8 copper ahead of regional adoption curves, driven by precision timing requirements in automated production lines.
- Educational:Campus network modernizations under India's Smart Cities Mission and China's digital education initiatives absorb standardized copper volumes with limited fiber backbone penetration.
Commercial end-use anchors current revenue; industrial automation in Vietnam and Indonesia offers steepest expansion trajectory.
Usage:
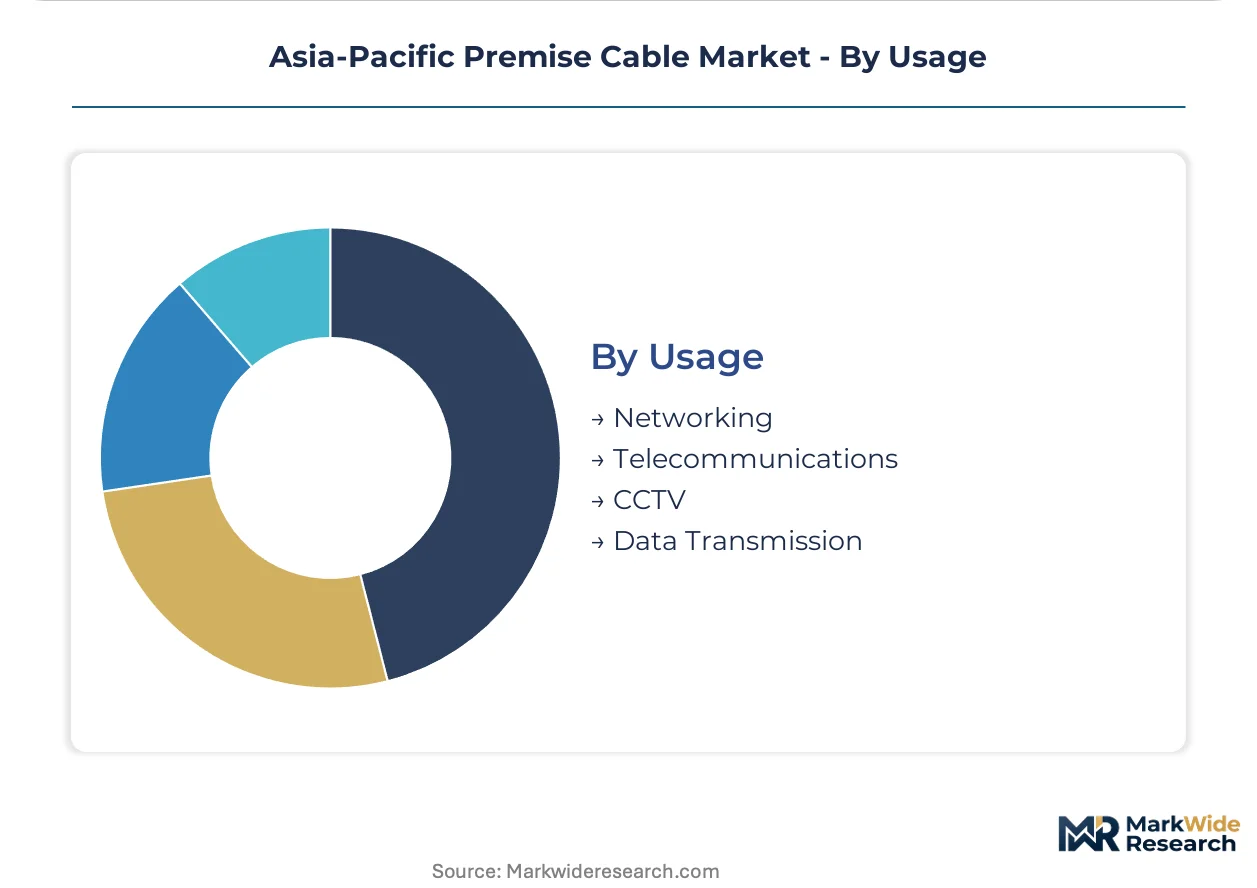
Networking and data transmission applications drive fiber backbone deployment, while telecommunications and CCTV retain copper dependency in legacy infrastructure zones.
- Networking:Local area distribution across enterprise campuses and data center server farms requires structured cabling hierarchies or direct top-of-rack fiber links. Hyperscale operators in Singapore and Sydney are bypassing traditional distribution frames entirely with active optical cable assemblies under 30 meters.
- Data Transmission:High-bandwidth backbone links between facilities and across metro cores command single-mode fiber with bend-insensitive coatings, eliminating traditional main distribution frame hierarchies in cloud provider architectures.
- Telecommunications:Voice-grade copper pairs sustain replacement demand in India's legacy PSTN infrastructure and Japan's aging building telephone systems.
- CCTV:Analog and IP surveillance networks in commercial and municipal security deployments absorb coaxial and twisted-pair volumes with limited fiber penetration except in campus backbone links.
Data transmission commands technology premium; networking volume is shifting toward direct server hardware procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern seaboard cities anchor Asia-Pacific premise cable demand through hyperscale data center construction. Cloud provider facility buildouts in Shanghai and Beijing absorb massive fiber volumes. National standards enforcement through MIIT locks in certified supplier relationships.
China
Alibaba, Tencent, and ByteDance drive backbone fiber consumption exceeding copper distance limitations. MIIT enforces GB 50311 and GB 50312 standards for structured cabling design and verification. State-owned data center operators in Beijing and Shanghai prioritize pre-certified domestic suppliers to accelerate project approvals.
Japan
Infrastructure renewals sustain replacement demand for polyethylene-jacketed outdoor cables. METI plenum-rated material restrictions tighten combustibility specifications in dense urban cores. Tokyo and Osaka building codes restrict installation networks to certified contractors.
India
Smart Cities Mission directives mandate fire-resistant cable deployments across commercial and municipal buildings. BIS certification for fire-resistant jackets raises compliance costs for imported product lines. Mumbai and Delhi commercial retrofits absorb multi-pair copper despite fiber substitution pressure.
Australia
Data center interconnect projects compress procurement cycles through direct manufacturer negotiations. ACMA cabling provider rules mandate technician licensing for optical fiber terminations. Sydney's Western Parkland City cluster sees distributor margins compress below eight percent on fiber backbone contracts.
South Korea
LS Cable & System anchors supply through integrated copper smelting and extrusion capacity. KTL fire standards force SKU proliferation without regional harmonization. Seoul's dense urban cores generate concentrated indoor-rated product demand under strict combustibility regulations.
Asia-Pacific Premise Cable Market Competitive Landscape
Global majors compete with regional champions across certification standards and installation network access. The vendor base splits between integrated manufacturers with captive raw material capacity and specification-driven specialists. Three archetypes dominate: Japanese compound formulation experts, Korean integrated smelter-extruders, and North American scale players. Capacity expansion and pre-certification against divergent national standards represent the dominant competitive moves.
Among Japanese manufacturers, Furukawa Electric exemplifies compound formulation expertise sustaining margin in infrastructure renewals. LS Cable & System represents the integrated archetype through captive copper processing. CommScope Holding Company Inc. occupies the scale-driven position in Australian data center interconnect procurement.
| Leading Market Players |
|---|
| Furukawa Electric |
| Belden Inc. |
| Prysmian Group |
| LS Cable & System |
| CommScope Holding Company Inc. |
| Nexans |
| Sumitomo Electric |
| Hitachi Cable |
| Corning Incorporated |
| Others |
Pricing and Supply Chain Analysis
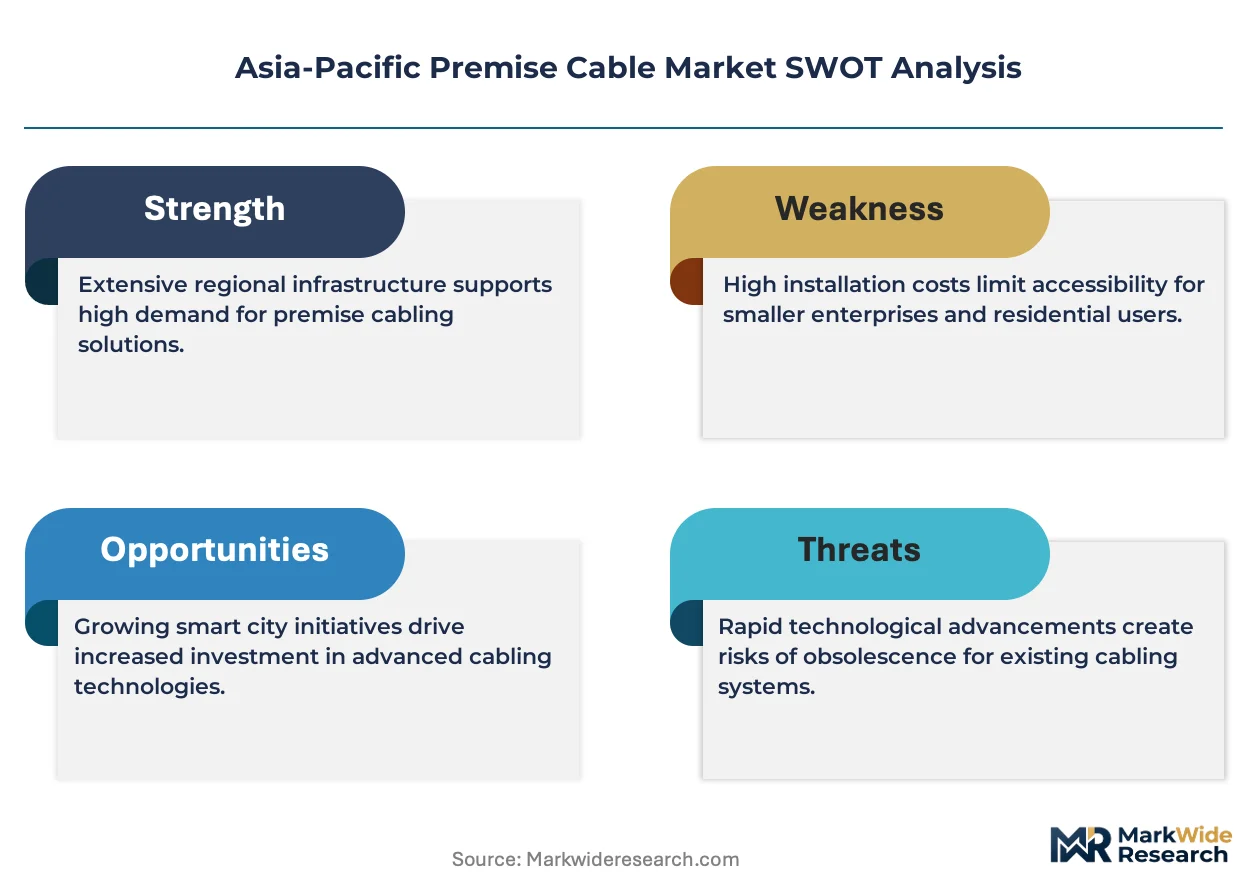
Hyperscale cloud operators' direct procurement mandates across China's eastern seaboard are forcing cable manufacturers to absorb certification costs upfront, compressing margins for non-integrated suppliers while rewarding those with captive compound formulation and extrusion capacity.
Pricing Analysis
LME copper volatility passes through directly to Korean and Chinese manufacturers lacking captive smelting operations, while integrated players buffer margin erosion. Pricing stratifies across MIIT-certified premium tiers, standard BIS-compliant grades, and economy copper volumes for residential retrofit. Cost compression in fiber backbone contracts runs through distributor channels as AWS and Google negotiate multi-year frame agreements. India's commercial retrofit sector exhibits highest price sensitivity; Australian data center operators show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
China's GB standards enforcement and India's BIS localization mandates are reshaping sourcing patterns, compelling foreign suppliers to establish domestic extrusion or forfeit state-owned enterprise contracts. Manufacturing concentrates in China, South Korea, and Japan, with raw material draws from Chilean copper cathode, Saudi petrochemical feedstock, and Japanese fluoropolymer resin. Single-source vulnerability sits with LME copper concentrate supply. Distribution runs through direct manufacturer negotiations with hyperscale operators, bypassing traditional electrical wholesalers in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific premise cable markets reward geographic arbitrage between China's certification-heavy state-owned data center procurement and Indonesia's greenfield hyperscale projects with relaxed vendor qualification timelines.
For Market Incumbents: Acquire certified installation network capacity in Australia and Japan to lock in ACMA and METI-compliant technician pools. Build backward integration into copper smelting or fluoropolymer compounding to defend margin against LME volatility and Furukawa Electric's formulation expertise. Pre-certify against GB 50311/50312, BIS fire-resistant jacket standards, and KTL combustibility tiers to compress 6-12 month qualification delays.
For New Entrants and Emerging Players: Begin with Indonesia's Jakarta and Batam hyperscale greenfields, where established cabling vendor relationships remain unformed and first-mover positioning is achievable. Target Philippine submarine cable landing backhaul builds requiring armored tropical-grade constructions. Pursue Vietnam's northern industrial zones mandating Category 8 copper for smart factory automation ahead of regional adoption curves. Lead with pre-terminated fiber solutions to reduce field labor dependency.
For Investors and Strategic Acquirers: Asymmetric upside sits with Japanese compound formulation specialists and Korean integrated smelter-extruders possessing captive raw material control. Long-term viability over the projection horizon hinges on certification breadth across divergent national standards regimes. Target acquisition archetype: mid-cap manufacturers with GB/BIS/ACMA pre-certification and direct hyperscale customer relationships. Watch for fiber-to-the-desk substitution inflection in India's premium commercial retrofit sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | MIIT GB 50311/50312 compliance unlocks state-owned data center procurement in Beijing and Shanghai. |
| Backward Integration into Copper Smelting | Captive cathode processing insulates LS Cable & System from LME volatility compressing extrusion margins. |
| Installation Network Acquisition | ACMA-licensed technician pools in Sydney compress project timelines for data center interconnect awards. |
| Pre-Terminated Fiber Capacity Expansion | Factory-precision assemblies reduce field labor content for hyperscale operators in Singapore and Sydney. |
| Greenfield Geographic Expansion | Jakarta and Batam hyperscale projects lack incumbent cabling relationships, enabling first-mover positioning. |
Research Methodology
Direct dialogue with data center facilities managers, structured cabling contractors, MIIT certification specialists, and copper procurement leads at Korean manufacturers grounded qualitative assessment, cross-referenced against customs trade databases, SEC filings from publicly listed cable producers, hyperscaler capex disclosures, and national standards body certification registries. Bottom-up volume estimates from individual project pipelines triangulated against top-down market sizing from regional construction forecasts.
Top-down regional demand modeling anchored the analytical framework, segmented by product type, installation environment, end-use sector, and application usage across the projection horizon. CAGRs derived from fitted growth curves incorporating cloud provider facility buildout timelines, Smart Cities Mission deployment schedules, and industrial automation adoption patterns. Modeled inputs included copper price trajectory assumptions, fiber substitution elasticity estimates, and national standards enforcement intensity indices.
Several conditions sit outside the modeled scope, including abrupt copper price spikes exceeding historical volatility bands, harmonization of APAC national standards regimes, and breakthrough wireless technologies displacing structured cabling entirely. Forecasts reflect documented assumptions about certification timeline stability and hyperscale construction continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Medium Voltage Cables Market
Cables
South Africa Wire and Cable Market
Cables
Hybrid Cables Market
Cables
Underground Cable Market
Cables
Cable Testers Market
Cables
Cable Testing Market
Cables
Fiber Optic Cable Accessories Market
Cables
Cable Market
Cables
SATA Power Cable Market
Cables
Solar Cable Market
Cables
Downhole Cables Market
Cables
Multicore Cables Market
Cables
United States Cable Accessories Market
Cables
Cable Management System Market
Cables
North America Patch Cable Market