
 Mexico Wires and Cables Market | 2026-2036
Mexico Wires and Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Wires and Cables Market Insights
Mexico's updated energy efficiency mandates under the Comisión Federal de Electricidad framework is recalibrating procurement standards for utility-grade conductors. Condumex leverages its integrated copper smelting and wire drawing operations to dominate domestic medium-voltage supply. Southwire Company anchors cross-border manufacturing through its Coahuila facility, sustaining cost advantages in building wire exports to the United States.
Wires and cables are electrically conductive assemblies comprising stranded or solid metallic cores—typically copper or aluminum—insulated with thermoplastic or cross-linked polymer compounds, engineered to transmit power or signals across rated voltage classes from sub-100V to 400 kV and above. Their primary purpose spans grid interconnection, building electrification, vehicle harnessing, and data transmission infrastructure. Low-voltage building wire occupies the largest volume share given Mexico's residential and commercial construction pipeline, while specialty wires for renewable energy applications represent the fastest-expanding margin pool as solar and wind projects multiply. Cross-linked polyethylene insulation commands preference over PVC in medium-voltage distribution due to superior thermal withstand and reduced dielectric losses.
The Comisión Nacional del Sistema de Ahorro para el Retiro oversees infrastructure investment standards that indirectly channel pension capital toward energy transmission buildouts, while NOM-001-SEDE electrical installation codes mandate conductor sizing and insulation grades for all new construction. BIS-aligned import testing protocols for Chinese and Korean cable shipments add compliance layers that favor producers with in-house certification laboratories. Stakeholders must monitor how nearshoring-driven industrial park expansions reshape regional demand patterns and whether domestic smelter capacity keeps pace with conductor alloy requirements.
Market Dynamics
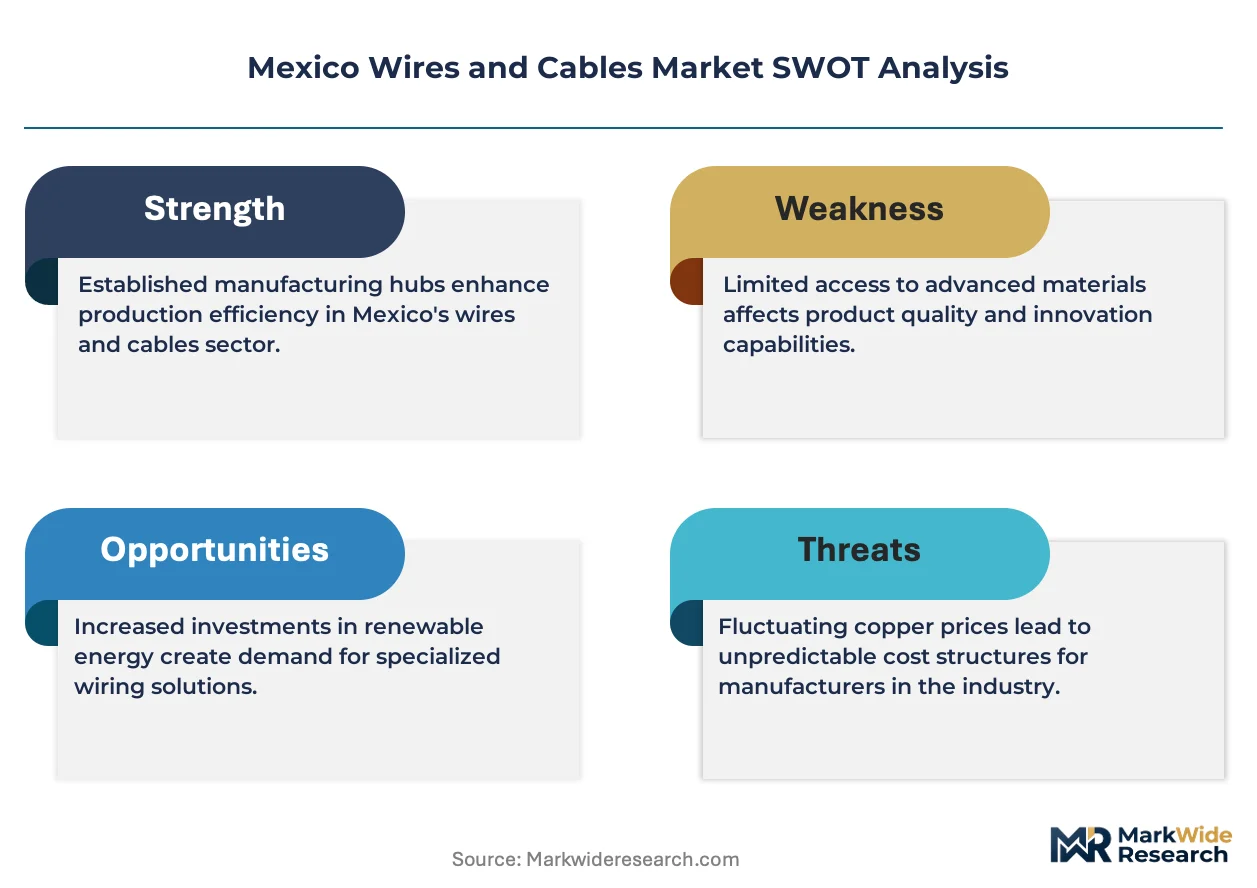
Nearshoring-driven industrial park expansions across northern Mexico are compressing procurement cycles for medium-voltage distribution infrastructure, forcing cable suppliers to co-locate extrusion and stranding capacity closer to automotive and electronics manufacturing clusters.
Growth Catalysts
- NOM-001-SEDE electrical codes:Updated conductor sizing mandates for all new commercial and residential construction are expanding specification-grade cable volumes in metropolitan zones.
- Automotive electrification:High-voltage cabling systems for electric vehicle powertrains are pulling specialized shielded conductor demand from maquiladora assembly plants in Nuevo León and Baja California.
- Copper smelter integration:Domestic cathode-to-wire drawing operations are shortening lead times for utility-grade procurement under CFE transmission buildout schedules.
Market Restraints
- Copper price volatility:London Metal Exchange cathode pricing swings transmit directly into conductor cost structures, compressing margins for distributors without hedging instruments.
- Import certification friction:BIS-aligned testing protocols for Asian cable shipments create 8-12 week customs delays that favor producers with in-house NOM certification laboratories.
- Aluminum substitution ceiling:Thermal expansion mismatches in medium-voltage splices limit aluminum conductor penetration despite 30% raw material cost advantages over copper.
Strategic Opportunities
- Yucatán Peninsula renewable clusters:Offshore wind and solar farm interconnection projects are opening specialty submarine and buried cable specifications underserved by incumbent suppliers.
- Cross-linked polyethylene convergence:XLPE insulation technology is displacing PVC in 15-35 kV distribution, creating margin pools for compounders with in-house silane grafting capability.
- Pension capital channeling:CONSAR infrastructure investment standards are directing retirement system flows toward transmission asset buildouts, lengthening contract tenors for qualified cable vendors.
Industry Challenges
- Medium-voltage splicing certification:CFE contractor qualification timelines stretch 14-18 months, throttling installation capacity expansion despite conductor availability.
- Legacy PVC compound requalification:NOM fire-resistance upgrades for building wire are forcing reformulation of stocked inventory, straining working capital for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Wires and Cables Market |
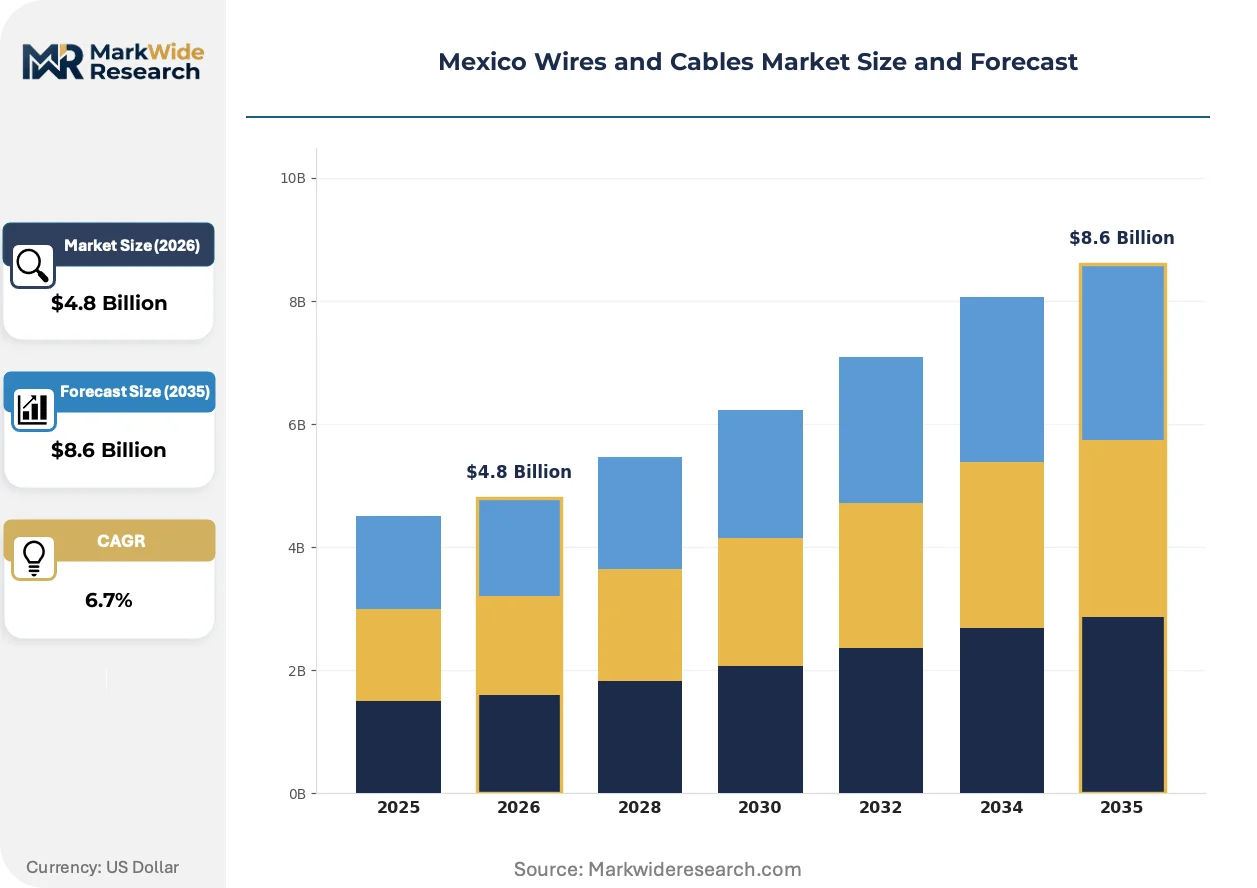
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Wires Insulation Material: Polyvinyl Chloride, Cross-Linked Polyethylene, Thermoplastic Elastomer, Rubber End User: Energy, Telecommunications, Construction, Automotive Application: Power Distribution, Communication, Building Wiring, Renewable Energy |
| Companies Covered | Condumex, Southwire Company, Furukawa Electric Mexico, Fujikura, TE Connectivity, Prysmian, Nexans, LS Cable & System, Belden, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Wires and Cables Market Trends and Innovations
Material science advances and procurement digitization are restructuring how conductor specifications are developed, tested, and contracted across Mexico's fragmented buyer base.
Silane-crosslinked polyethylene insulation is rewriting the economics of underground distribution networks. CFE distribution planners are specifying XLPE for 90% of new 23 kV feeder installations, displacing oil-impregnated paper and EPR alternatives. The technology is compressing maintenance intervals from 15 to 25 years while enabling 20% ampacity upgrades within existing duct banks.
Energy reform regulations under the SENER framework are mandating fire-resistance testing for all building wire deployed in high-occupancy structures. Manufacturers must now submit to NOM-001-SEDE third-party flame propagation protocols before commercialization. Low-smoke zero-halogen compounders are capturing specification share in Mexico City and Monterrey commercial high-rises where evacuation liability drives premium procurement.
Buyer concentration among industrial park developers is consolidating vendor panels and compressing qualification cycles. Developers in Tijuana and Ciudad Juárez are pre-approving cable suppliers for 3-year master service agreements, displacing project-by-project bidding. This shift is most visible in automotive supplier parks where just-in-time construction schedules leave no tolerance for material certification delays.
Mexico Wires and Cables Market Segmentation
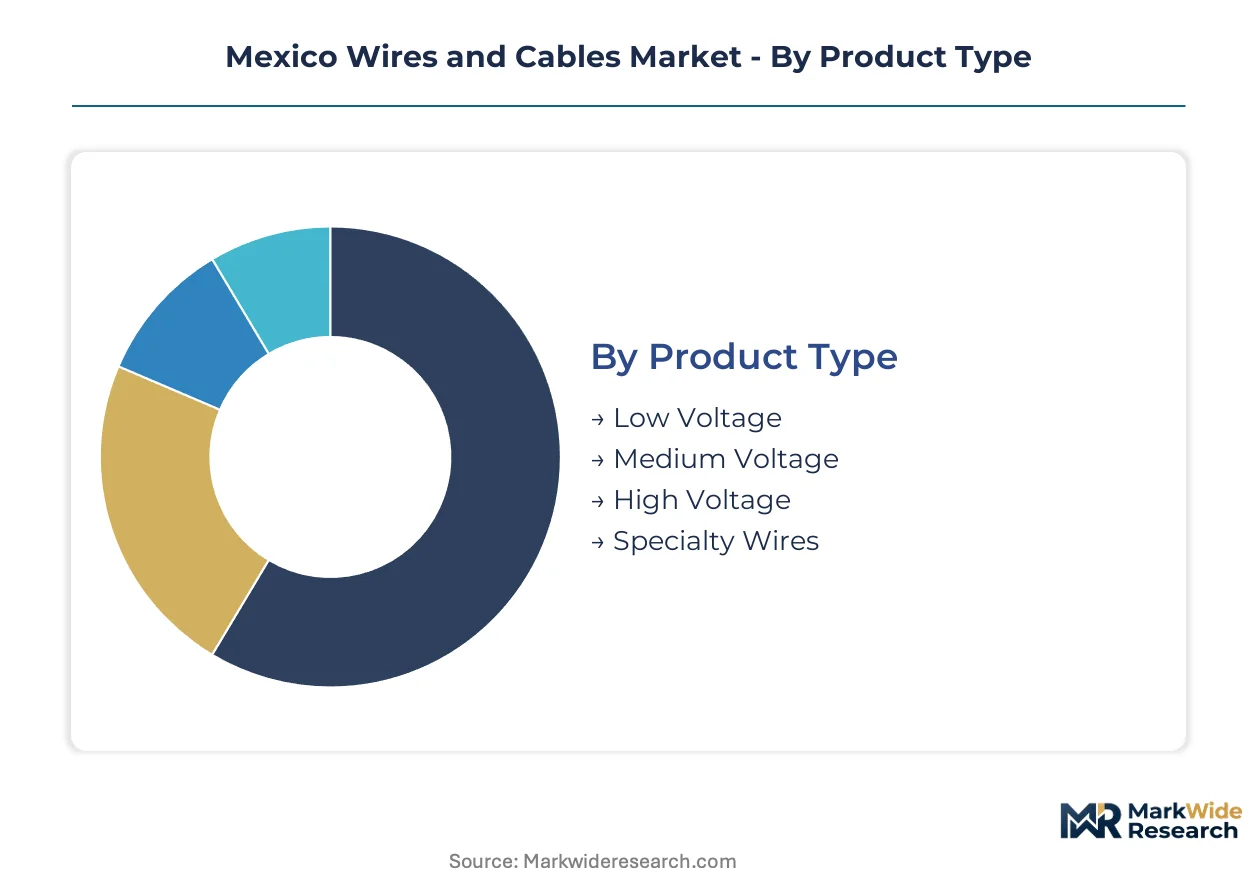
Segmentation in Mexico's wires and cables market reveals how voltage class, material chemistry, and end-use application create distinct procurement ecosystems with divergent qualification requirements and margin structures. Buyers prioritize different performance attributes depending on whether they serve CFE transmission schedules, automotive just-in-time assembly, or commercial construction codes.
Product Type:
Voltage classification separates buyers by project scale and regulatory scrutiny intensity.
- Low Voltage:Building wire and appliance cabling rated below 1 kV dominates residential and commercial construction volumes. Nuevo León and Jalisco metropolitan construction pipelines are pulling specification-grade THHN/THWN-2 conductors as NOM-001-SEDE electrical codes tighten conductor sizing mandates.
- Medium Voltage:Distribution-class cables from 1 kV to 35 kV serve CFE feeder networks and industrial park substations. Silane-crosslinked polyethylene insulation is displacing older technologies in 23 kV installations across the Yucatán Peninsula renewable interconnection clusters.
- High Voltage:Transmission cables above 35 kV require specialized extrusion and testing infrastructure.
- Specialty Wires:Automotive harnessing, submarine, and fire-resistant specifications command premium qualification cycles.
Low Voltage leads volumes today; Specialty Wires is gaining share fastest.
Insulation Material:
Material selection tracks thermal performance requirements and fire-resistance regulatory upgrades.
- Cross-Linked Polyethylene:Silane-grafted XLPE dominates medium-voltage underground distribution for its 90°C continuous rating and 25-year maintenance intervals. CFE planners specify XLPE for 90% of new 23 kV feeder installations.
- Polyvinyl Chloride:PVC compounds retain cost advantage in low-voltage building wire despite NOM fire-resistance reformulation mandates straining distributor working capital.
- Thermoplastic Elastomer:Flexible jacketing for automotive and robotics applications.
- Rubber:Heavy-duty portable cordage for mining and construction sites.
PVC commands the widest application base; XLPE is climbing the fastest on transmission-grade specifications.
End User:
Customer concentration determines contract structure and technical service intensity.
- Energy:CFE procurement anchors utility-grade conductor demand with 14-18 month contractor qualification timelines. Domestic cathode-to-wire integration shortens lead times for transmission buildout schedules.
- Automotive:Maquiladora assembly plants in Baja California and Nuevo León are pulling high-voltage shielded conductor demand for electrified powertrains.
- Construction:Commercial and residential developers in Monterrey and Mexico City drive building wire volumes.
- Telecommunications:Fiber-optic and copper data cabling for carrier infrastructure.
Energy sector procurement anchors absolute volumes; Automotive is expanding most quickly on nearshoring-driven capacity additions.
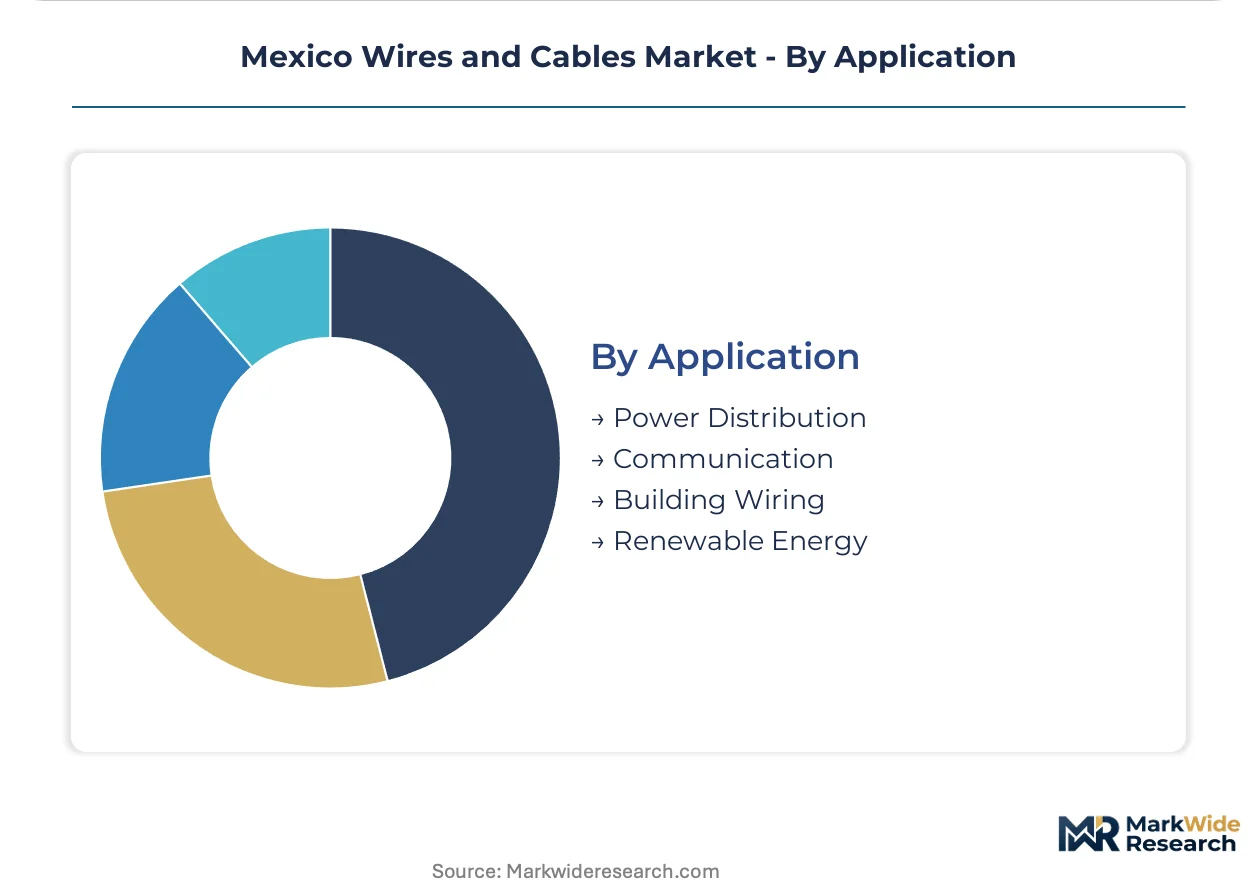
Application:
Application context dictates installation environment and regulatory compliance layers.
- Power Distribution:Grid interconnection and substation cabling spans all voltage classes with CFE specification dominance.
- Building Wiring:Low-voltage residential and commercial installations face NOM-001-SEDE flame propagation protocols.
- Renewable Energy:Solar farm DC cabling and wind turbine interconnection require UV-resistant and torsion-flexible specifications.
- Communication:Structured cabling and fiber infrastructure for data transmission networks.
Power Distribution holds the largest installed base; Renewable Energy shows the steepest expansion trajectory on Yucatán and Baja California project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper wire manufacturing first scaled in Mexico during the 1960s maquiladora boom, when US electronics and automotive firms established cross-border supply chains to leverage tariff advantages and proximity to Texas industrial corridors.
Nuevo León
Automotive electrification and data center construction are pulling medium-voltage cable demand across the Monterrey metropolitan zone. NOM-001-SEDE electrical codes mandate upgraded conductor specifications for all new industrial facilities. The Apodaca-Santa Catarina corridor hosts concentrated extrusion capacity serving Tesla's Gigafactory and tier-one supplier parks.
Baja California
Medical device and aerospace manufacturing clusters generate specialized coaxial and shielded cable procurement. Mexico's federal energy reform regulations require fire-resistant insulation grades for high-occupancy industrial structures. Tijuana and Mexicali maquiladoras source locally from cross-border wire drawing operations anchored in San Diego supply sheds.
Jalisco
Guadalajara's electronics manufacturing services sector consumes precision signal cabling for consumer device assembly. The state's environmental regulator enforces stricter volatile organic compound limits on PVC compounding than federal baselines. El Salto industrial parks concentrate automotive harness suppliers serving Nissan and Honda assembly plants.
Northern Border States
Chihuahua and Coahuila anchor cross-border manufacturing integration with Texas utility markets. CFE transmission buildouts through the Comisión Federal de Electricidad framework specify domestic cathode sourcing for reliability. Piedras Negras and Ciudad Juárez host Southwire's integrated wire drawing and insulation extrusion complex.
Yucatán Peninsula
Offshore wind and solar farm interconnection projects are opening specialty submarine and buried cable specifications. SENER renewable energy mandates require 35% local content in transmission infrastructure procurement. Mérida and Progreso industrial zones attract compounders with silane grafting capability for XLPE insulation.
Mexico Wires and Cables Market Competitive Landscape
Capital-heavy producers with integrated copper smelting compete with asset-light distributors focused on specification-grade procurement and logistics optimization. The market structures around three tiers: domestic integrated manufacturers with captive metal supply, cross-border multinationals leveraging US-Mexico-Canada Agreement tariff preferences, and regional distributors holding NOM certification laboratory relationships. Dominant competitive moves include backward integration into cathode sourcing and pre-approval contracting with industrial park developers for multi-year master service agreements.
Among domestic integrated producers, Condumex exemplifies the smelter-to-wire archetype with captive copper refining and medium-voltage extrusion capacity. Southwire Company anchors the cross-border multinational tier through its Coahuila manufacturing footprint and building wire export orientation to US construction markets. Furukawa Electric Mexico and Fujikura represent the precision-cable specialist segment serving automotive and telecommunications OEMs with shielded conductor specifications. TE Connectivity occupies a position bridging industrial connectivity and automotive electrification procurement channels.
| Leading Market Players |
|---|
| Condumex |
| Southwire Company |
| Furukawa Electric Mexico |
| Fujikura |
| TE Connectivity |
| Prysmian |
| Nexans |
| LS Cable & System |
| Belden |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap producers with multi-generational operational control dominate Mexico's wire and cable landscape, anchoring supply discipline through captive copper smelting while resisting price wars that erode long-term contract viability with CFE and industrial park developers.
Pricing Analysis
Three-tier pricing structure across NOM-certified premium, standard commercial, and economy-grade tiers separates specification-grade XLPE cables from commodity PVC building wire. Price differentiation hinges on certification laboratory access and cathode sourcing integration, with premium tiers capturing utility-grade procurement while economy segments face compression from unhedged copper volatility. Margins are tightening due to London Metal Exchange pricing swings that transmit directly into unintegrated distributor cost structures. Automotive harnessing buyers show least price sensitivity given just-in-time delivery penalties, while residential construction developers in Jalisco and Nuevo León negotiate hardest on volume.
Supply Chain Analysis
Cross-border freight costs from Texas and Arizona smelters into northern Mexico maquiladora clusters determine working capital cycles for building wire distributors. Raw material supply draws from Chilean cathode imports, domestic Sonora mining output, and US scrap copper flows, with conductor alloy formulation resting on silane compounder relationships in Coahuila and Nuevo León. Single-source vulnerability concentrates in XLPE resin supply from US Gulf Coast petrochemical complexes. Distribution runs through CFE-approved contractor networks for utility-grade procurement and industrial park developer panels for commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's wires and cables market compounds steadily on nearshoring-driven industrial park expansion, with automotive electrification and renewable interconnection projects providing durable demand anchors across the projection horizon.
For Market Incumbents: Lock in multi-year master service agreements with Tijuana and Ciudad Juárez industrial park developers before qualification cycles compress further. Defend against aluminum substitution threats by deepening silane-grafting capabilities for XLPE insulation that maintains thermal performance advantages in medium-voltage splices. Prioritize backward integration into cathode sourcing to hedge London Metal Exchange volatility that squeezes unintegrated competitors. For New Entrants and Emerging Players: Yucatán Peninsula offshore wind developers represent the most penetrable buyer archetype given underserved submarine cable specifications and SENER-mandated local content requirements. Target compounders with in-house certification laboratories to bypass 8-12 week customs delays that disadvantage Asian import competitors. Lead with XLPE insulation technology for 23 kV renewable interconnection clusters where incumbent suppliers lack dedicated capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors holding NOM certification relationships but lacking extrusion capacity, offering bolt-on acquisition targets for integrated manufacturers seeking channel control. Long-term viability frames around 5-10 year transmission asset buildouts under CONSAR-directed pension capital flows. Watch CFE contractor qualification timeline compression as the inflection signal—shortening 14-18 month cycles indicate installation capacity scarcity that favors pre-qualified cable vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cathode | Captive smelting operations insulate Condumex and Southwire from London Metal Exchange volatility that erodes distributor margins. |
| XLPE Silane Grafting Capacity Expansion | In-house compound production captures CFE specification shifts toward 23 kV cross-linked polyethylene distribution feeders. |
| NOM Certification Laboratory Investment | Third-party testing capability accelerates customs clearance for Asian import competitors facing BIS-aligned protocol delays. |
| Industrial Park Master Service Agreements | Three-year pre-approval contracts with Tijuana and Apodaca developers lock out project-by-project bidding competitors. |
| Yucatán Submarine Cable Specialization | Offshore wind interconnection specifications remain underserved by incumbent suppliers focused on terrestrial distribution. |
Research Methodology
Coverage spans Mexico's northern industrial corridor, central highlands manufacturing belt, and Yucatán Peninsula renewable zones, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged CFE procurement officers, industrial park developers, cable plant managers, and NOM certification laboratory directors. Secondary sources included SEC filings from cross-border manufacturers, Mexican customs trade databases, CFE transmission planning documents, and CONSAR infrastructure investment disclosures. Bottom-up volume modeling from extrusion capacity utilization and top-down macro calibration from construction and automotive production forecasts were reconciled.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with segmentation modeling across voltage class, insulation material chemistry, and end-use application. CAGRs derive from installed base replacement cycles, renewable energy capacity additions, and automotive electrification content-per-vehicle trajectories. Industry-specific inputs include CFE transmission buildout schedules, maquiladora employment and facility expansion data, and NOM-001-SEDE code revision implementation timelines.
Underlying measurement precision varies by segment; utility-grade medium-voltage specifications carry tighter precision than fragmented low-voltage building wire distribution. Forecasts reflect assumptions on copper price regime stability, nearshoring momentum sustainability, and CFE contractor qualification capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
South Africa Wire and Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Asia-Pacific Premise Cable Market
Cables
Cable Management System Market
Cables
Cable Racks Market
Cables
United States Cable Accessories Market
Cables
FFC/FPC Jumper Cables Market
Cables
HVDC Cables Market
Cables
Fiber Optic Cable Accessories Market
Cables
Copper Cable Market
Cables
Global Wires and Cables Market
Cables
Premise Cable Market
Cables
Low-Temperature Cable Market
Cables
India Wire and Cable Market
Cables
Cable Assembly Market
Cables
Magnetic Charging Cable Market