
 HVDC Cables Market | 2026-2036
HVDC Cables Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Cables Market Analysis
China's manufacturing base for extruded HVDC insulation is reconfiguring competitive dynamics in submarine cable supply. Prysmian Group leverages integrated compound-to-cable manufacturing to sustain margin control across long-distance interconnector projects. NKT anchors Nordic offshore wind demand through its specialized high-voltage DC factory in Karlskrona, Sweden. Hitachi Energy competes on converter-cable system integration, extending its reach beyond pure component supply into full turnkey offerings.
High-voltage direct current cables transmit electrical power using direct current at voltages typically exceeding 100 kV, employing extruded cross-linked polyethylene or mass-impregnated paper insulation to minimize losses over distances exceeding 600 kilometers where alternating current becomes uneconomical. Submarine installations command premium engineering requirements due to hydrostatic pressure, thermal cycling, and seabed anchoring constraints that drive specialized armoring and jointing solutions. Mass impregnated cables retain dominance in ultra-high-voltage submarine corridors where proven reliability outweighs extrusion technology advances, while solid extruded systems capture share in offshore wind export links up to 525 kV. Renewable integration applications concentrate demand growth as developers require dedicated HVDC export circuits from remote generation zones to load centers.
EU Green Deal carbon-neutrality mandates and F-Gas Regulation phase-downs shape insulation gas choices and cable system environmental compliance across European procurement. China's GB standards and MIIT industrial policy direct domestic capacity expansion toward 500 kV+ extruded cable qualification for offshore wind and cross-border interconnection. The US Department of Energy and FERC interstate transmission rules influence cost-recovery frameworks for multi-state HVDC corridor development. Stakeholders must weigh converter station interoperability against cable technology lock-in when committing to decades-long infrastructure contracts.
Market Dynamics
Converter-cable system integration is compressing project timelines and reshaping supplier relationships across long-distance interconnector and offshore wind corridors. Developers now bundle procurement decisions for submarine HVDC links with converter station technology, forcing cable manufacturers to extend engineering capabilities beyond pure component supply.
Growth Catalysts
- EU Green Deal carbon-neutrality mandates:The framework accelerates cross-border interconnector buildout across the continent, creating dedicated procurement pipelines for 525 kV extruded submarine systems connecting renewable zones to load centers.
- Offshore wind export circuits:Developers in the North Sea and Baltic regions require dedicated HVDC links from remote generation clusters, pulling specialized submarine cable capacity into multi-year order backlogs.
- Extruded cross-linked polyethylene insulation:Advances in 500 kV+ qualification are displacing mass-impregnated paper in medium-length submarine corridors, opening new technical specifications for solid-dielectric systems.
Market Restraints
- Copper and aluminum price volatility:Raw material swings compress manufacturing margins and complicate long-dated project bidding for submarine cable contracts with five-plus year delivery horizons.
- Specialized vessel scarcity:Cable-laying ship availability concentrates among Nordic and East Asian operators, creating installation bottlenecks that extend project schedules and inflate marine spread costs.
- F-Gas Regulation phase-downs:EU restrictions on synthetic insulation gases complicate gas-insulated cable system designs and force reformulation of existing product lines for European compliance.
Strategic Opportunities
- US Atlantic offshore wind pipeline:Bureau of Ocean Energy Management lease rounds are activating demand for first-mover submarine HVDC export links from Massachusetts to North Carolina wind zones.
- Converter-cable integration services:Full turnkey offerings that bundle extruded cable supply with voltage source converter technology capture premium positioning and multi-decade service contracts.
- Japan's METI renewable energy auctions:Feed-in-tariff mechanisms for remote island interconnection create specialized demand for mass-impregnated paper systems in seismic seabed conditions.
Industry Challenges
- Submarine jointing technician scarcity:Deep-water splice installation requires certified specialists with decade-plus experience, creating talent bottlenecks that constrain installation fleet expansion.
- Multi-standard certification timelines:Simultaneous qualification under IEC, GB, and CIGRE technical brochures extends product development cycles and delays market entry for new insulation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Cables Market |
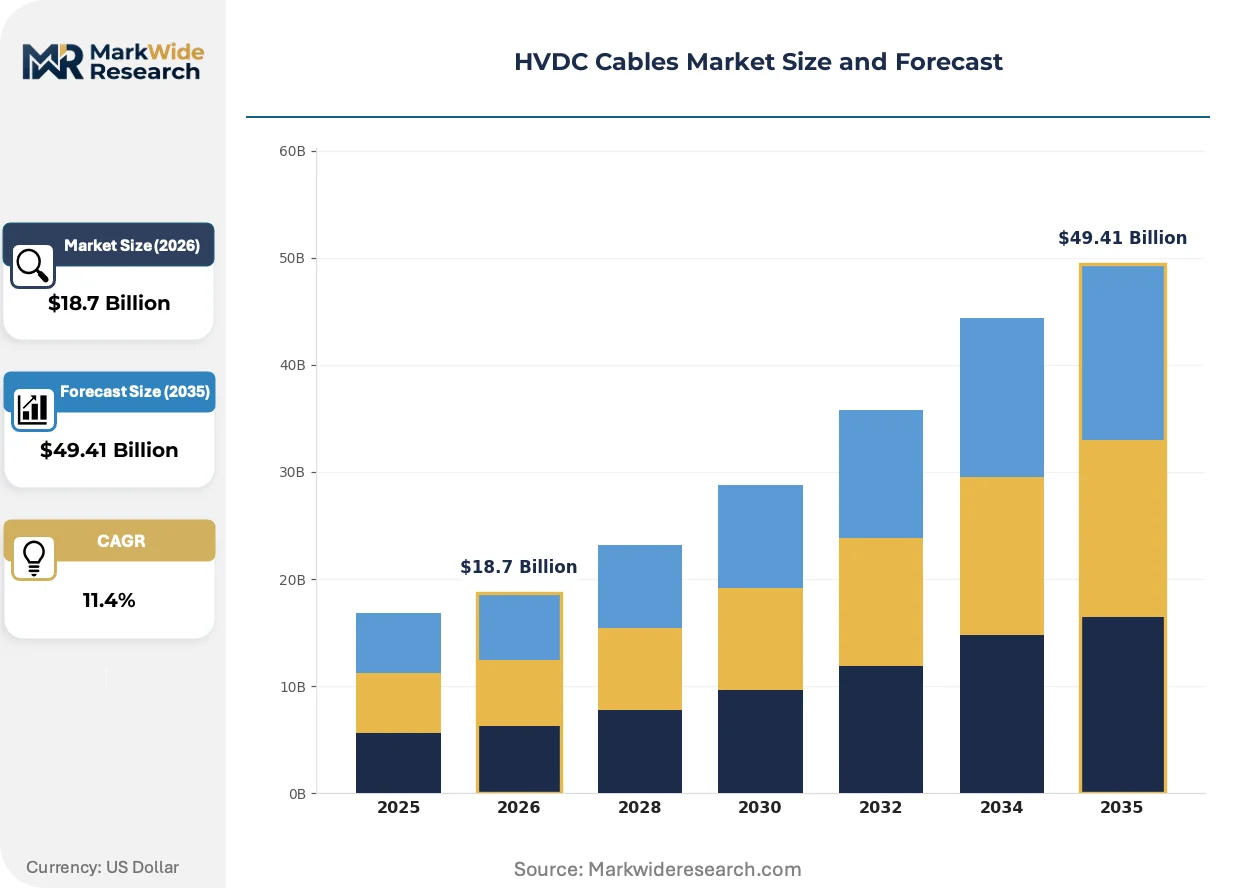
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Cables, Mass Impregnated Cables, Bundled Cables, Cable Accessories Application: Transmission, Interconnection, Renewable Integration, Power Supply End User: Utilities, Industrial Sector, Renewable Energy Providers, Offshore Wind Farms Installation Type: Underground, Submarine, Overhead, Hybrid Systems |
| Companies Covered | NKT, Hitachi Energy, Prysmian Group, Taihan Cable & Solution, Siemens Energy, Nexans, LS Cable & System, ZTT, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Cables Market Emerging Trajectories
Extruded insulation technology is hybridizing with conventional mass-impregnated designs, creating new system architectures that blend manufacturing scalability with proven submarine reliability. This technical convergence is compressing the traditional technology-choice timeline for project developers.
Extruded cross-linked polyethylene insulation is hybridizing with mass-impregnated paper in hybrid cable designs for medium-length submarine corridors. Offshore wind developers in the North Sea are piloting these configurations for 320 kV export links under 200 kilometers. The structural consequence is a compression of the traditional technology bifurcation, enabling manufacturers to standardize production lines across previously separate product categories.
The EU F-Gas Regulation is forcing reformulation of gas-insulated cable systems and accelerating solid-dielectric alternatives across European procurement specifications. Industrial consequence includes withdrawal of sulfur hexafluoride-dependent designs from tender processes and retooling of manufacturing lines toward dry-type insulation. Submarine interconnector projects in the Baltic and Mediterranean corridors are most affected, with developers rewriting technical specifications to exclude fluorinated gases entirely.
Buyer concentration among European offshore wind developers is consolidating procurement decisions into multi-project framework agreements that span five-year buildout schedules. Engineering-procurement-construction contractors are displacing standalone cable purchasing as the dominant channel, bundling submarine links with foundation and turbine supply. This pattern is most visible in German and Danish North Sea zones, where Orsted and RWE have centralized HVDC cable sourcing across their development portfolios.
HVDC Cables Market Segmentation
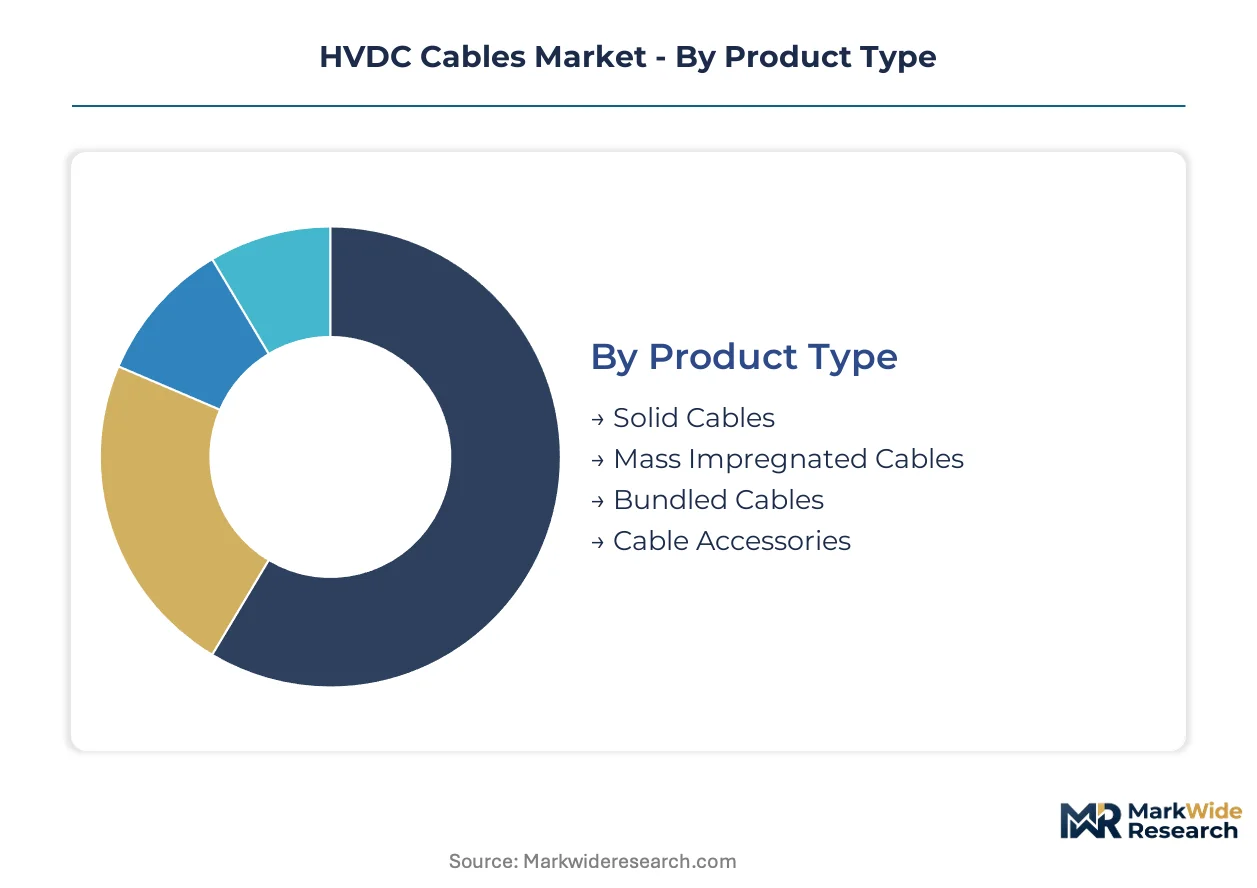
HVDC cable procurement decisions hinge on insulation technology, installation environment, and converter system compatibility. Each segmentation dimension carries distinct engineering specifications, regulatory requirements, and margin structures that shape supplier positioning across interconnector and offshore wind corridors.
Product Type:
Cost tier stratification separates mature mass-impregnated systems from emerging extruded alternatives, with bundled configurations occupying a mid-tier engineering position.
- Solid Cables:Extruded cross-linked polyethylene insulation dominates 320 kV to 525 kV submarine export links for offshore wind. European developers in the North Sea and Baltic corridors specify solid-dielectric systems for their manufacturing scalability and reduced environmental compliance burden under EU F-Gas Regulation phase-downs.
- Mass Impregnated Cables:Paper-oil composite insulation retains preference for ultra-high-voltage submarine corridors exceeding 600 kV where decades of operational data outweigh extrusion technology advances. Japan's METI renewable auctions specify mass-impregnated designs for seismic seabed conditions around remote island interconnections.
- Bundled Cables:Hybrid configurations combine extruded cores with mass-impregnated armoring for medium-length corridors under 200 kilometers, enabling manufacturers to standardize production lines across previously separate product categories.
- Cable Accessories:Jointing kits, terminations, and sealing systems command premium pricing due to submarine jointing technician scarcity and deep-water splice certification requirements.
Solid cables hold installed capacity. Mass impregnated cables are rotating up the share rankings in ultra-high-voltage corridors.
Application:
Volume concentration varies sharply by project type, with renewable integration pulling the steepest expansion trajectory while transmission applications mature.
- Transmission:Long-distance bulk power corridors exceeding 800 kilometers connect remote generation to load centers. China's GB standards and MIIT industrial policy direct domestic capacity expansion toward 500 kV+ extruded cable qualification for cross-border transmission.
- Interconnection:Cross-border submarine links between national grids require synchronized converter-cable system integration. EU Green Deal carbon-neutrality mandates accelerate interconnector buildout across the continent, creating dedicated procurement pipelines for 525 kV extruded submarine systems.
- Renewable Integration:Offshore wind export circuits from remote generation clusters to onshore substations. Bureau of Ocean Energy Management lease rounds in the US Atlantic activate demand for first-mover submarine HVDC export links from Massachusetts to North Carolina wind zones.
- Power Supply:Dedicated feed-in circuits for industrial loads and island grids with limited interconnection alternatives.
Transmission commands legacy capacity. Renewable integration is climbing the fastest as offshore wind developers scale procurement.
End User:
Customer type determines contract structure, with utilities favoring framework agreements and offshore wind developers driving turnkey integration demand.
- Utilities:Grid operators and transmission system operators procure through multi-year framework agreements spanning five-year buildout schedules. German and Danish North Sea zones show centralized HVDC cable sourcing across development portfolios.
- Industrial Sector:Mining, smelting, and petrochemical facilities require dedicated HVDC feeds for remote or high-load operations.
- Renewable Energy Providers:Solar and onshore wind developers seeking grid connection for remote generation assets.
- Offshore Wind Farms:Developers in the North Sea and Baltic regions require dedicated HVDC links from remote generation clusters, pulling specialized submarine cable capacity into multi-year order backlogs. Engineering-procurement-construction contractors bundle submarine links with foundation and turbine supply.
Utilities hold contract volume. Offshore wind farms are gaining share fastest through bundled procurement.
Installation Type:
Geography and seabed conditions dictate installation method, with submarine commanding premium engineering and overhead facing right-of-way constraints.
- Underground:Urban and suburban corridors where overhead routing is prohibited. Thermal cycling management and soil thermal resistivity govern cable sizing.
- Submarine:Hydrostatic pressure, thermal cycling, and seabed anchoring constraints drive specialized armoring and jointing solutions. Cable-laying ship availability concentrates among Nordic and East Asian operators, creating installation bottlenecks.
- Overhead:Limited HVDC application due to insulation and corona discharge challenges at direct current voltages; rare except for specialized test lines.
- Hybrid Systems:Combinations of submarine and underground segments for coastal interconnections, requiring transition jointing expertise at shoreline crossings.
Submarine installations dominate project value. Hybrid systems are expanding most quickly as coastal renewable zones multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes HVDC cables primarily for North Sea offshore wind export, while China deploys them for cross-border transmission corridors. The United States concentrates demand in Atlantic coastal lease zones. Japan maintains distinct preferences for seismic-resistant submarine systems.
China
Cross-border interconnection projects with Central Asia and Southeast Asia drive extruded cable procurement at 500 kV and above. MIIT industrial policy directs domestic manufacturers toward qualification for offshore wind and transmission applications. Yangtze River Delta cable producers are expanding capacity for 525 kV solid-dielectric systems targeting export markets.
Germany
North Sea offshore wind clusters require dedicated submarine HVDC links from remote generation zones to onshore substations. EU Green Deal carbon-neutrality mandates accelerate interconnector buildout across continental grids. Northern coastal regions host specialized cable-laying vessel operations serving Baltic and North Sea corridors.
United States
Bureau of Ocean Energy Management lease rounds from Massachusetts to North Carolina activate first-mover demand for submarine HVDC export infrastructure. FERC interstate transmission rules shape cost-recovery frameworks for multi-state corridor development. Atlantic coastal states are consolidating procurement through engineering-procurement-construction contractors bundling cable with foundation supply.
Japan
METI renewable energy auctions for remote island interconnection create specialized demand for mass-impregnated paper systems. Seismic seabed conditions around volcanic island chains favor proven submarine reliability over extrusion technology advances. Kyushu and Okinawa prefectures concentrate project development for geothermal and offshore wind integration.
United Kingdom
Offshore wind developers in Scottish and English waters scale procurement of 320 kV to 525 kV submarine export circuits. OFGEM regulatory frameworks govern revenue recovery for cross-border interconnectors to continental Europe. North Sea ports host jointing technician training programs addressing specialized workforce scarcity.
HVDC Cables Market Vendor Landscape
Capability concentration sits with integrated compound-to-cable manufacturers; scale advantage sits with diversified energy infrastructure conglomerates. The market structures around three tiers: pure-play submarine cable specialists, converter-cable system integrators, and diversified wire-and-cable manufacturers extending into high-voltage DC. Dominant competitive moves include backward integration into insulation compound production and strategic partnerships bundling cable supply with converter station technology.
Among European specialists, NKT and Prysmian Group occupy positions representing integrated manufacturing archetypes, while Hitachi Energy exemplifies the converter-cable system integration model. These three anchor the competitive landscape across long-distance interconnector and offshore wind corridors, with each representing distinct strategic postures toward turnkey service expansion versus component specialization.
| Leading Market Players |
|---|
| NKT |
| Hitachi Energy |
| Prysmian Group |
| Taihan Cable & Solution |
| Siemens Energy |
| Nexans |
| LS Cable & System |
| ZTT |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors global extruded HVDC cable capacity, translating concentrated polymer compound production into asymmetric pricing power for Chinese suppliers bidding European offshore wind tenders. Raw material volatility in copper and aluminum conductor markets feeds directly into contract escalation clauses, compressing margins for manufacturers without backward integration into insulation compound production.
Pricing Analysis
European-North Asian price spreads of 15-25 percent persist for 525 kV submarine systems, reflecting EU F-Gas Regulation compliance costs and specialized vessel mobilization premiums. Project-based long-term contracting dominates, with pricing stratifying across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in standard-tier extruded cables is intensifying because Chinese capacity additions outpace qualified installation fleet expansion. Offshore wind developers show highest price sensitivity, while national transmission system operators prioritize reliability over unit cost.
Supply Chain Analysis
Specialized cable-laying vessel operators in Norway, Denmark, and China hold concentrated installation capacity, creating bottlenecks that extend project delivery timelines. Manufacturing draws from copper cathode feedstock sourced from Chile and Indonesia, cross-linked polyethylene resin from South Korea and Saudi Arabia, and steel armoring wire from Japanese and German mills. Single-source vulnerability concentrates around qualified deep-water jointing technicians with decade-plus certification experience. Distribution runs through engineering-procurement-construction contractors bundling cable supply with converter station and foundation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC cable procurement sits at an inflection where EU Green Deal carbon-neutrality mandates are compressing decade-long infrastructure commitment windows. Converter-cable system integration is disrupting traditional component-supplier relationships across interconnector and offshore wind corridors.
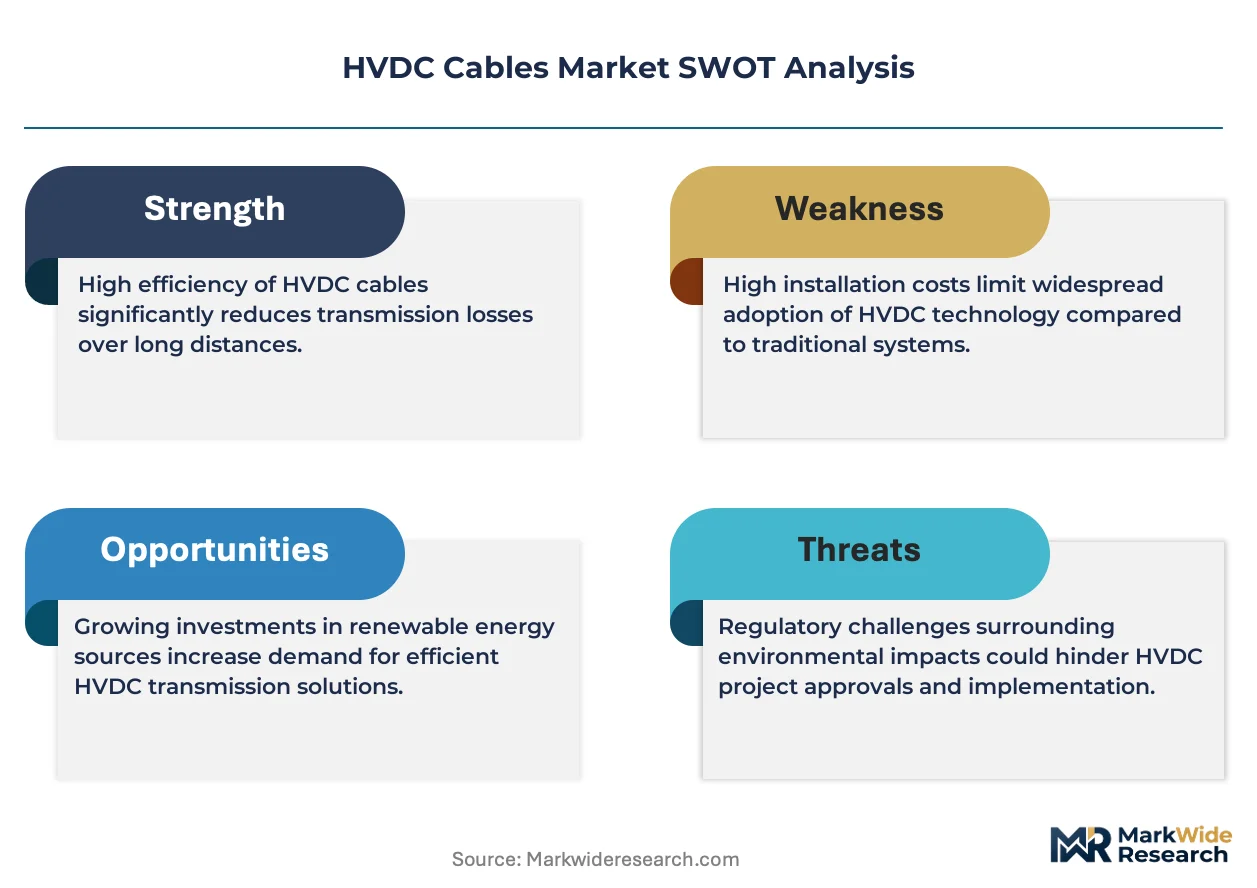
For Market Incumbents: Pre-empt margin erosion from Chinese extruded cable competition by deepening captive supply of cross-linked polyethylene compounds and securing multi-year vessel charter agreements. Converter station technology partnerships represent the priority lever for defending turnkey positioning against pure-play cable specialists.
For New Entrants and Emerging Players: Build out qualification capabilities for 500 kV+ solid-dielectric systems targeting US Atlantic offshore wind lease zones where domestic content preferences create protected procurement pools. Joint venture structures with established installation vessel operators offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-compounding play because submarine cable assets generate multi-decade contracted cash flows with inflation-linked tariffs. Acquisition targets should display integrated compound-to-cable manufacturing and converter station partnerships. Monitor Bureau of Ocean Energy Management lease round timing as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Yangtze River Delta producers are capturing margin from insulation resin supply. |
| Converter Station Technology Licensing | Hitachi Energy and Siemens Energy extend reach beyond component supply. |
| Specialized Vessel Fleet Expansion | Nordic operators address installation bottlenecks in North Sea corridors. |
| Multi-Standard Certification Investment | Simultaneous IEC, GB, and CIGRE qualification accelerates market entry. |
| Turnkey EPC Bundle Positioning | Orsted and RWE framework agreements favor integrated procurement channels. |
Methodological Framework
Cross-validation between primary fieldwork with cable manufacturers and secondary project databases anchors the qualitative findings. Interviews with EPC procurement directors, submarine cable project managers, converter station engineers, and offshore wind development executives combined with customs trade data, FERC interconnection filings, EU project development databases, and Bureau of Ocean Energy Management lease records. Bottom-up project pipeline aggregation and top-down regulatory mandate analysis provided triangulation.
Calibration against historical capacity utilization and installation fleet availability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include insulation technology type, installation environment, voltage class tier, converter system architecture, and regional regulatory cluster. CAGRs derived from project sanctioning timelines and manufacturing capacity expansion schedules, with specific inputs from copper price futures curves and specialized vessel orderbook data.
Sensitivities concentrate around raw material price volatility, vessel availability constraints, and multi-standard certification timeline extensions. Quarterly review of BOEM lease award announcements, EU Green Deal implementation guidance, and Chinese MIIT industrial policy directives is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
GCC Cable Accessories Market
Cables
Ethernet Converters Market
Cables
North America HVAC Cables Market
Cables
Underground Cable Market
Cables
Class 1E Electric Cables Market
Cables
Downhole Cables Market
Cables
SATA Power Cable Market
Cables
High Voltage Cable Termination Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Global Cable Tie Market
Cables
Cable Accessories Market
Cables
India Wire and Cable Market
Cables
EPR Cable Market
Cables
Wire and Cable Materials Market
Cables
Water Leak Sensing Cable Market
Cables
Aluminum Cable Market