
 Ferric Chloride Market | 2026-2036
Ferric Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Chloride Market Intelligence
The capability gap between integrated chemical production and specialized regional supply is redrawing the competitive landscape. Large-scale producers like BASF SE leverage their vast chemical synthesis infrastructure to achieve cost advantages in raw material supply. In contrast, specialists such as Kemira and Tessenderlo Group differentiate through application-specific formulations and localized service networks for municipal water clients. This creates distinct strategic pathways for market participants.
Ferric chloride is an inorganic compound, primarily produced as an aqueous solution (FeCl3) through the reaction of hydrochloric acid with iron. It functions as a highly effective coagulant and flocculant in industrial processes. The liquid form dominates the market due to its ease of handling in water treatment applications, which represents the largest segment. Conversely, the anhydrous powder and flake forms serve niche, higher-value uses such as an etching agent in electronics manufacturing and as a catalyst in chemical synthesis.
Market access and product standards are heavily influenced by environmental and chemical safety regulations. In the United States, the EPA sets limits for contaminants in drinking water, while in Europe, ECHA's REACH framework governs chemical registration and safety. China's Ministry of Ecology and Environment (MEE) imposes stringent discharge standards on industries, creating demand for effective treatment chemicals. Navigating these varied compliance requirements is critical for suppliers seeking to operate across different jurisdictions.
Market Dynamics
Tightening global water quality mandates are the central force shaping the market. This pressure from regulators like the US EPA and China's MEE creates non-discretionary demand for effective coagulants in wastewater treatment.
Growth Catalysts
- Regulatory Mandates:The EU's Urban Waste Water Treatment Directive drives ferric chloride use for phosphorus removal in municipal facilities.
- Industrial Pollution Control:China’s MEE enforcement pushes industrial zones to upgrade effluent treatment, creating demand from textiles and electronics.
- Performance Advantages:The chemical effectively removes diverse contaminants in various water conditions, outperforming alternatives like aluminum sulfate.
Market Restraints
- Feedstock Volatility:Pricing for hydrochloric acid, a primary raw material, is unstable due to its dependency on other chemical production cycles.
- Substitution Risk:Alternative coagulants like polyaluminium chloride (PAC) offer superior performance in specific pH ranges and produce less sludge.
- Logistical Hurdles:The corrosive nature of liquid ferric chloride requires specialized, costly storage and handling equipment, increasing total ownership costs.
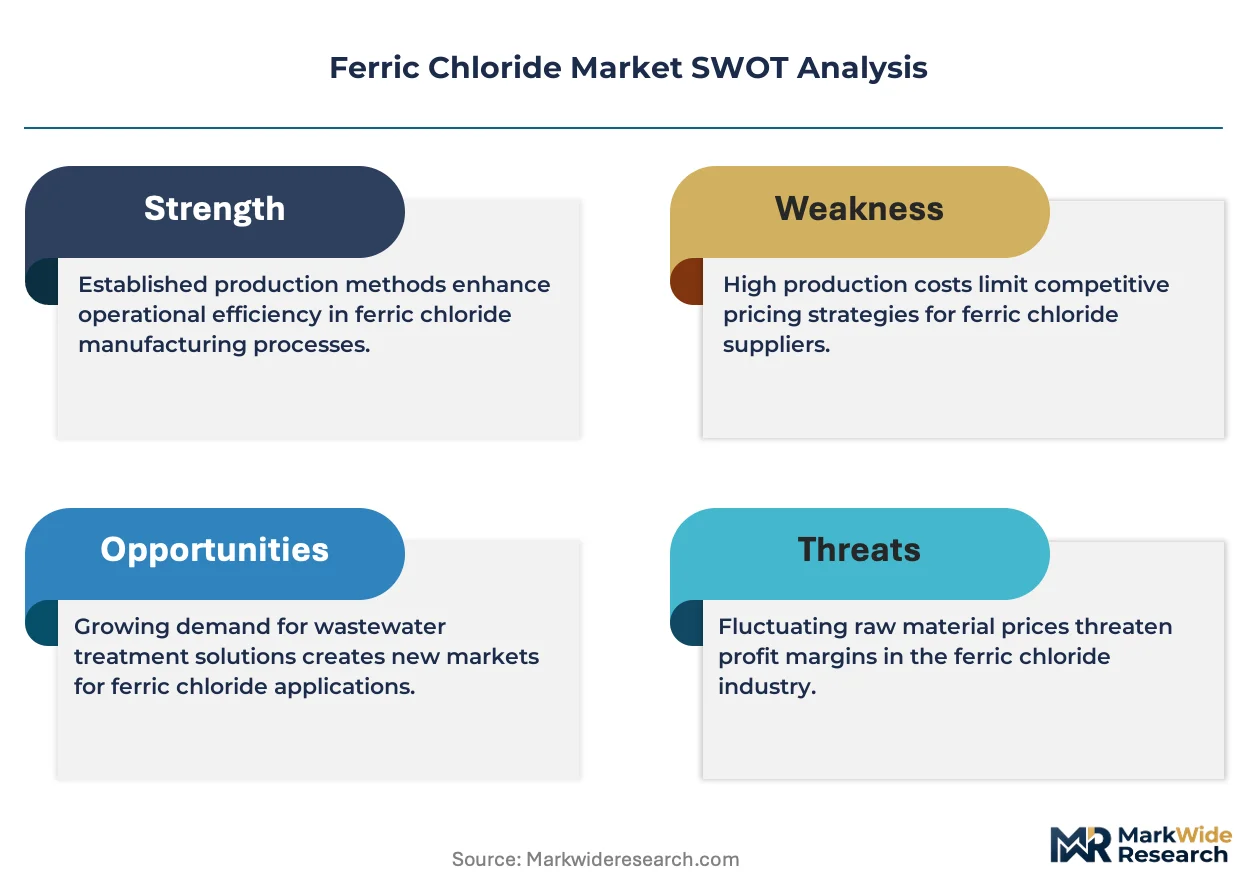
Strategic Opportunities
- Sludge Dewatering:Use in sludge treatment to reduce final disposal volume represents a value-added application for wastewater operators.
- Geographic Expansion:Underdeveloped water infrastructure in Southeast Asian nations like Vietnam presents greenfield market opportunities.
- High-Purity Grades:Developing formulations for electronics etching and chemical synthesis opens higher-margin, niche market segments.
Industry Challenges
- Compliance Complexity:Navigating the patchwork of chemical safety regulations, such as Europe's REACH framework, increases operational costs and delays market access.
- Infrastructure Investment:The high capital expenditure needed for regional liquid production and distribution hubs acts as a significant barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Chloride Market |
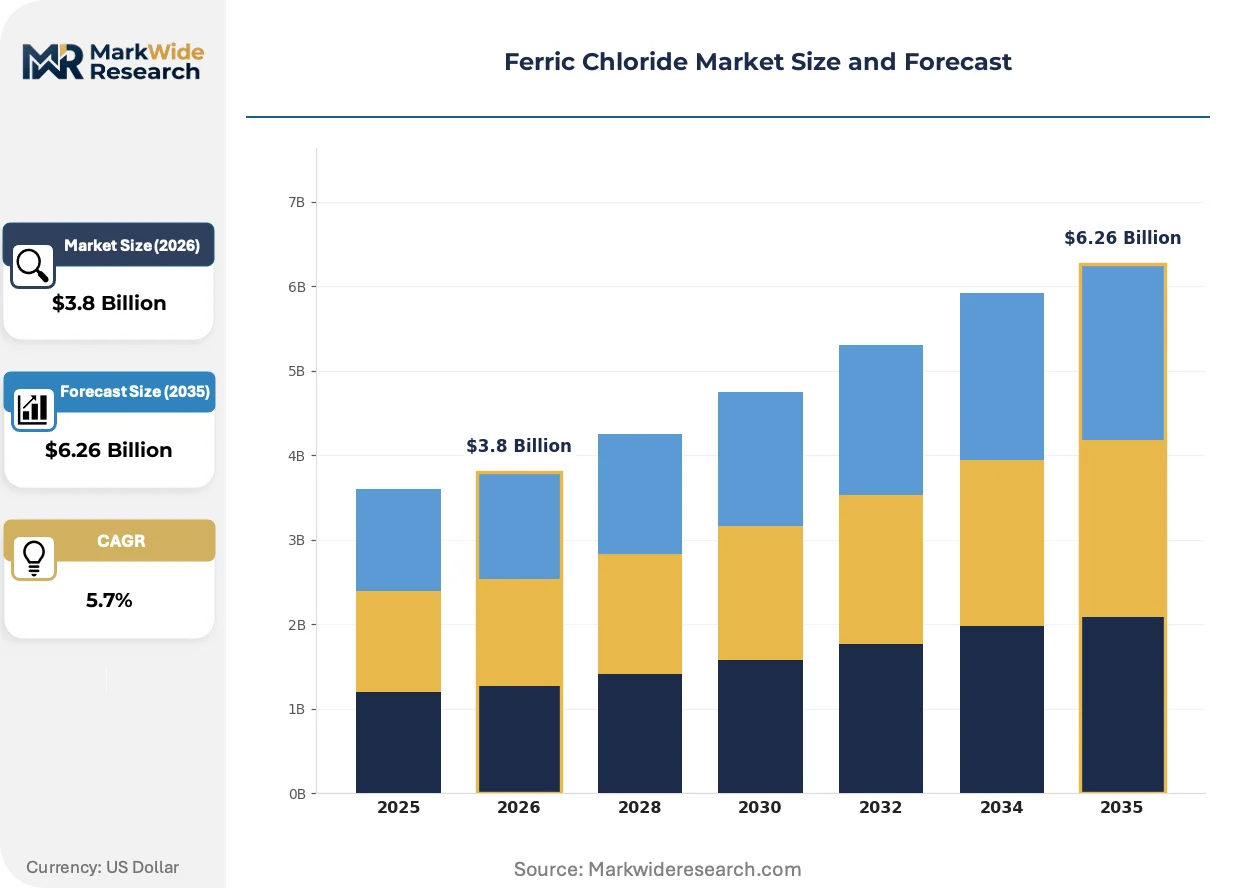
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Ferric Chloride, Solid Granules, Flake Form, Anhydrous Powder Application: Water Treatment, Etching Agent, Sewage Processing, Pigment Production, Catalyst Use End User Industry: Electronics Manufacturing, Chemical Processing Plants, Municipal Utilities, Metalworks, Textile Production Packaging Type: Drums, IBC Containers, Bags, Bulk Tankers, Plastic Containers |
| Companies Covered | PVS Chemicals, Chemifloc, Kemira, Sukha Chemical Industries, SIDRA Wasserchemie GmbH, BASF SE, Feralco AB, Saf Sulphur Company, Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Chloride Market Strategic Shifts & Innovations
Product development and service delivery models are diverging to address distinct market needs. This shift is driven by the dual pressures of achieving cost efficiency in bulk applications and providing specialized formulations for high-value segments.
High-purity anhydrous ferric chloride serves as a critical etching agent and a Lewis acid catalyst in organic synthesis. Its adoption is concentrated among specialized chemical and electronics firms seeking precise reaction control. The development of application-specific grades is fragmenting the market away from a single commodity into a portfolio of value-differentiated formulations.
China's Ministry of Ecology and Environment (MEE) has implemented stringent discharge standards for key industrial sectors. This forces factories, particularly in textiles and chemicals, to upgrade wastewater systems to comply with stricter limits. The industrial wastewater treatment segment is therefore seeing a mandatory shift toward more effective coagulants.
Municipal water utilities are moving toward long-term service and supply agreements. This model displaces spot-market procurement with contracts that include technical support and inventory management from specialized suppliers. The trend is most prominent in North America and Europe, where utilities prioritize operational reliability over raw chemical price.
Ferric Chloride Market Segmentation
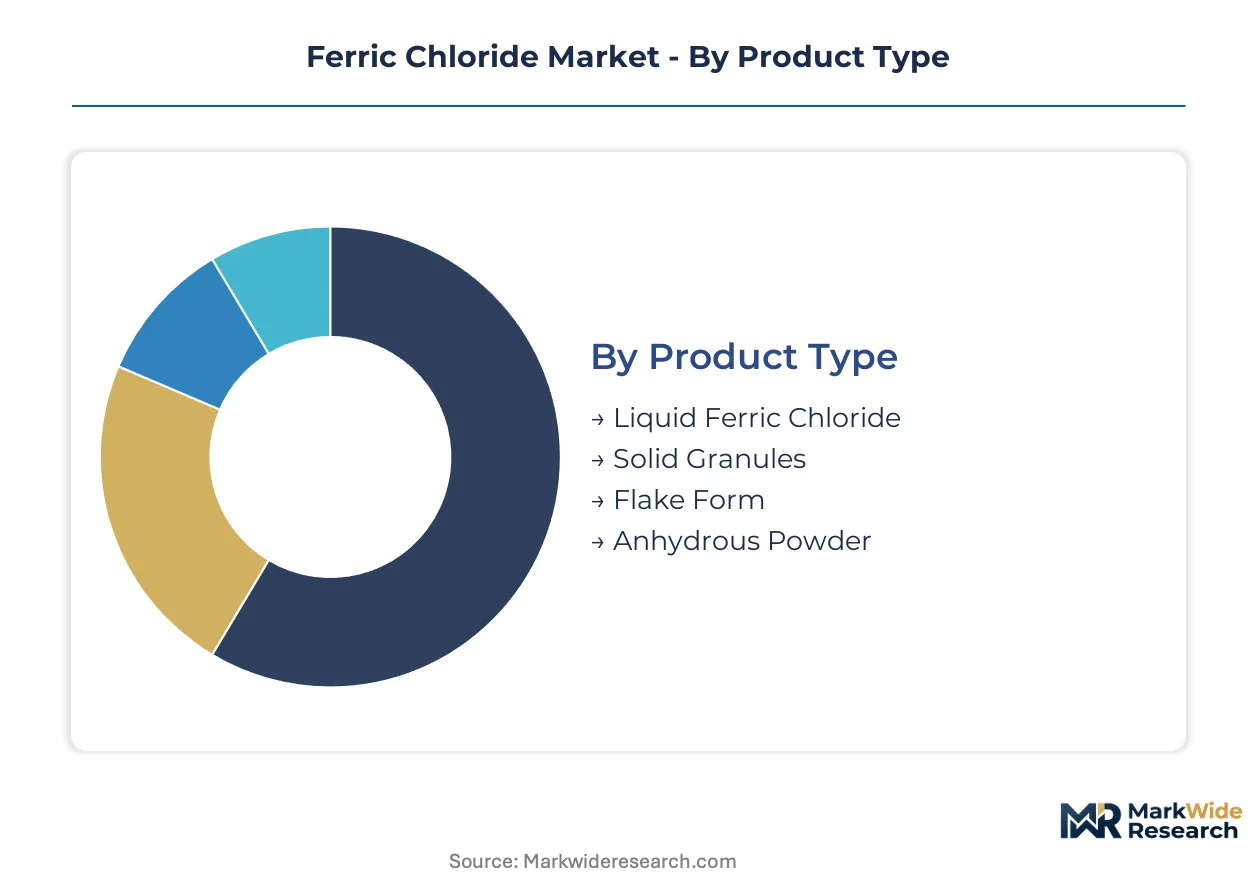
Ferric chloride market segmentation reveals distinct value propositions and operational complexities across its diverse uses. Understanding these segments helps market participants tailor product offerings and distribution strategies effectively. Varied forms and applications reflect specific industry requirements for purity, handling, and performance.
Product Type:
The product type segmentation delineates how different forms of ferric chloride are distributed and consumed across various regions.
- Liquid Ferric Chloride:This aqueous solution (35-42% FeCl3) is valued for its ease of dosing and mixing in large-scale operations. Demand concentrates in municipal water treatment facilities across North America and Europe for efficient coagulation.
- Solid Granules:Granular ferric chloride offers transport and storage stability advantages compared to liquid forms, particularly in remote locations or smaller industrial applications.
- Flake Form:Ferric chloride flakes are a solid, highly soluble form, often preferred for applications requiring precise dosage control or water addition at the point of use.
- Anhydrous Powder:This high-purity, solid form contains minimal water, crucial for moisture-sensitive reactions and precise etching processes. Its demand is strong in electronics manufacturing and advanced chemical synthesis.
Liquid Ferric Chloride commands the established base. The steepest expansion runs through Anhydrous Powder.
Application:
The application segment highlights the varied economic value and operational costs associated with ferric chloride across different industrial uses.
- Water Treatment:Ferric chloride serves as a primary coagulant, effectively removing suspended solids, phosphorus, and heavy metals from raw water sources. Widespread use in municipal facilities drives significant volume demand.
- Etching Agent:This application utilizes ferric chloride's corrosive properties for precise material removal in printed circuit boards and semiconductors. Electronics firms prioritize high-purity grades for controlled etching.
- Sewage Processing:Ferric chloride aids in wastewater treatment, facilitating pollutant removal and improving sludge dewatering efficiency for municipal plants.
- Pigment Production:The chemical acts as a precursor in iron-based pigment synthesis, contributing to color intensity and stability of various paints and coatings.
- Catalyst Use:Ferric chloride functions as a Lewis acid catalyst in organic synthesis reactions, enabling pharmaceutical and fine chemical production. This niche application demands high-purity anhydrous forms.
Water Treatment represents the largest volume application. Catalyst Use is climbing the fastest.
End User Industry:
The end user industry segmentation illustrates diverse operational requirements and consumption volumes across various sectors.
- Electronics Manufacturing:This sector utilizes high-purity ferric chloride as an etching agent for printed circuit boards and semiconductor components. Asian manufacturers are significant consumers due to production scale.
- Chemical Processing Plants:Ferric chloride serves as a catalyst or flocculant in various chemical synthesis processes, including pharmaceuticals and dyes.
- Municipal Utilities:These entities represent the largest consumers, employing ferric chloride for drinking water purification and wastewater treatment. Stricter regulations mandate its use for phosphorus removal.
- Metalworks:Ferric chloride is used in metal pickling baths, removing rust and scale from steel surfaces before further processing.
- Textile Production:The chemical finds use in textile dyeing and finishing processes as a mordant, enhancing color fastness.
Municipal Utilities drive foundational demand. Electronics Manufacturing is gaining share fastest.
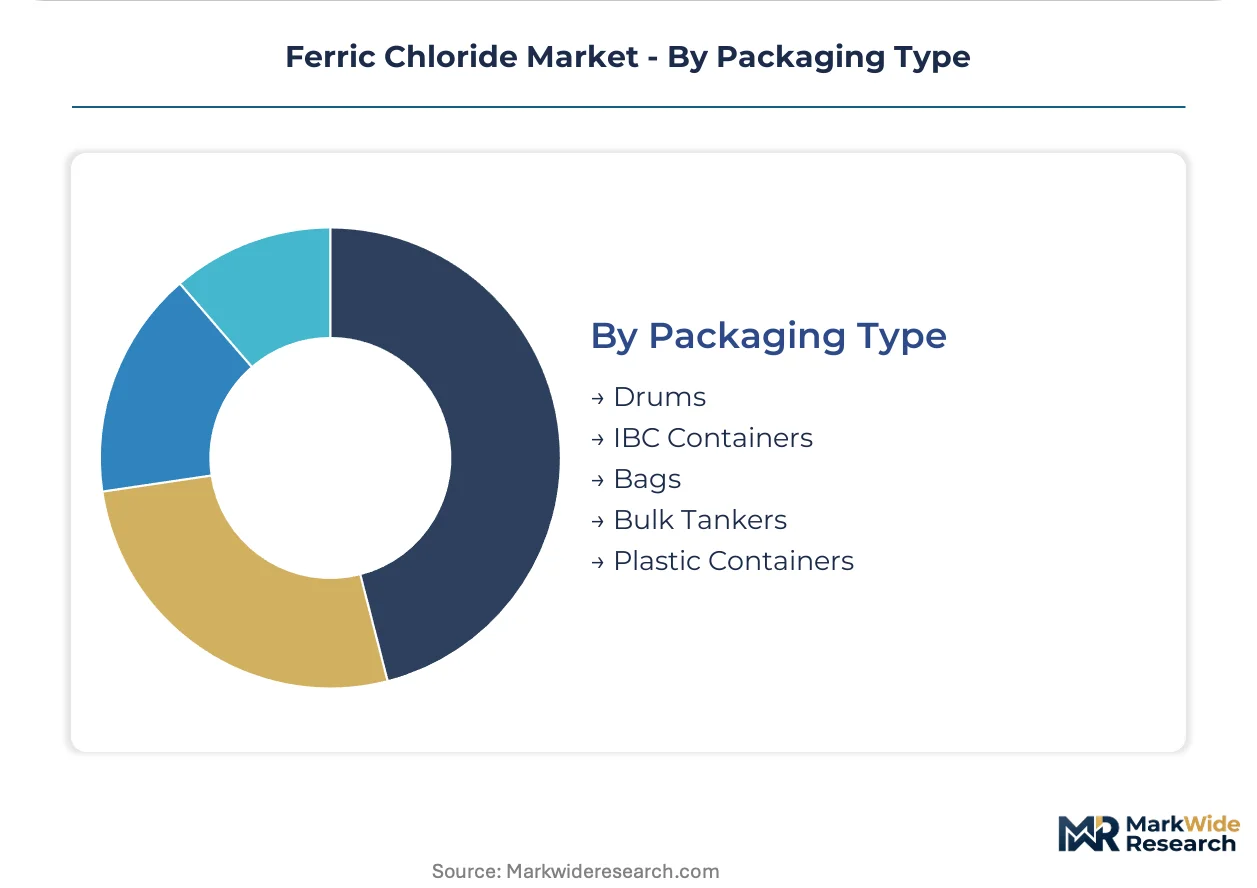
Packaging Type:
The packaging type segmentation reflects logistical efficiencies and safety requirements inherent in ferric chloride distribution.
- Drums:These 55-200 liter steel or plastic containers are used for moderate volume shipments, balancing transportability and corrosive liquid containment.
- IBC Containers:Intermediate Bulk Containers (IBCs), typically 1000-liter capacity, provide a cost-effective solution for transporting larger quantities than drums. They are common for municipal and mid-sized industrial users.
- Bags:This packaging is primarily for solid anhydrous powder or granules, offering efficient storage for dry ferric chloride products in niche applications.
- Bulk Tankers:Large road or rail tankers are employed for high-volume delivery of liquid ferric chloride to major industrial sites and municipal treatment plants. This method minimizes handling costs.
- Plastic Containers:Smaller plastic containers (1-25 liters) cater to laboratory use or specialized small-batch chemical synthesis, ensuring convenient handling.
Bulk Tankers handle the majority of large-volume shipments. Plastic Containers are expanding most quickly for smaller, specialized deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ferric chloride demand exhibits varied elasticity across global markets. Municipal water treatment facilities, driven by public health mandates, often demonstrate inelastic demand for coagulants. Industrial sectors with robust competition can display greater price sensitivity, influencing localized supply dynamics.
China
China's rapid industrialization fuels substantial demand for ferric chloride in wastewater treatment. The Ministry of Ecology and Environment (MEE) enforces stringent discharge standards, compelling industries to upgrade effluent processing. Industrial zones in the Yangtze River Delta heavily invest in advanced water purification systems.
United States
Consistent ferric chloride demand stems from US municipal utilities for drinking water purification. The US EPA's Safe Drinking Water Act regulates contaminant levels, requiring effective coagulation. Major metropolitan areas like New York continually upgrade water infrastructure to meet these standards.
Germany
German municipal facilities extensively utilize ferric chloride for phosphorus removal, adhering to strict EU directives like the Urban Waste Water Treatment Directive. This ensures high water quality across the country. Industrial centers in North Rhine-Westphalia also employ ferric chloride for treating complex chemical effluents.
Vietnam
Vietnam represents a greenfield opportunity for ferric chloride suppliers due to its expanding industrial base and developing water infrastructure. Government initiatives to improve environmental protection are driving investment in wastewater treatment plants. Industrial parks near Ho Chi Minh City prioritize new water treatment capacities.
India
India's burgeoning population and industrial growth generate significant demand for water treatment chemicals. The Central Pollution Control Board (CPCB) mandates effluent treatment for industrial units, particularly in textile hubs. Cities like Mumbai and Chennai are expanding municipal water and wastewater treatment facilities.
Ferric Chloride Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the ferric chloride market. This tiered structure sees large chemical conglomerates leveraging their raw material synthesis capabilities for cost advantages. Strategic archetypes include global bulk chemical producers, regional application specialists, and niche high-purity suppliers. Competitive moves focus on geographic expansion into emerging markets and developing application-specific formulations.
Within the global bulk chemical producer archetype, Germany-based BASF SE exemplifies extensive chemical synthesis infrastructure, enabling cost-efficient raw material supply across diverse regions. Finland-based Kemira represents a specialized player, focused on application-specific formulations and technical support for municipal water treatment clients. Similarly, Tessenderlo Group, operating from Belgium, occupies a position as a regional specialist, emphasizing localized service networks and tailored solutions for municipal clients across Europe.
| Leading Market Players |
|---|
| PVS Chemicals |
| Chemifloc |
| Kemira |
| Sukha Chemical Industries |
| SIDRA Wasserchemie GmbH |
| BASF SE |
| Feralco AB |
| Saf Sulphur Company |
| Tessenderlo Group |
Cost & Logistics Intelligence
Chemical synthesis scale economies in ferric chloride production drive supply concentration among integrated producers. These large-scale operations establish competitive price floors for bulk liquid forms.
Pricing Analysis
Specialized service and technical support offerings drive lifetime value for ferric chloride suppliers. The dominant pricing model for bulk liquid forms involves contract-based long-term offtake agreements with municipal utilities. Price differentiation stems from high-purity grades for electronics etching and localized service networks. Pricing softness reflects feedstock volatility for hydrochloric acid, impacting industrial buyers more than municipal facilities.
Supply Chain Analysis
China produces significant volumes of ferric chloride, alongside major European producers such as Germany and Finland. The supply chain primarily depends on hydrochloric acid and iron as key raw materials. Logistical hurdles for transporting corrosive liquid ferric chloride represent a structural risk, increasing handling costs. Distribution runs through bulk tankers for municipal utilities and large industrial sites, complemented by IBCs and drums for smaller-scale users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ferric chloride market offers a defensive-moat story, primarily due to regulatory entrenchment in municipal water treatment. Stricter environmental mandates ensure non-discretionary demand for effective coagulants.
For Market Incumbents: Fortify existing market share by securing long-term service and supply agreements with municipal utilities, particularly in North America and Europe. Expand regional liquid production and distribution hubs to mitigate logistical hurdles and counter feedstock volatility. Invest in R&D for high-purity grades to address the substitution risk from alternative coagulants in niche applications.
For New Entrants and Emerging Players: Anchor in greenfield market opportunities within developing water infrastructure, such as Vietnam. Target the sludge dewatering application segment, offering value-added solutions to wastewater operators. Focus on delivering localized service networks and tailored formulations for small to mid-sized industrial wastewater treatment plants, differentiating through technical expertise and supply reliability.
For Investors and Strategic Acquirers: Regional application specialists with strong municipal client relationships represent attractive acquisition targets. This market offers long-term viability, underpinned by non-discretionary demand from environmental regulations. Focus on entities with established localized service networks and application-specific formulation capabilities. A signal to watch is the consolidation trend among mid-sized players seeking to expand geographic reach or technical expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreements | Secures consistent revenue streams for suppliers and operational stability for municipal water utilities. |
| Capacity Expansion | Addresses growing demand in regions like China and India, driven by water quality mandates. |
| Green Manufacturing Transition | Improves sustainability profile and compliance with evolving EU environmental directives for chemical producers. |
| Joint Venture | Facilitates market access and localized distribution in emerging Southeast Asian nations. |
| High-Purity Grade R&D | Unlocks higher-margin segments like electronics etching and advanced chemical synthesis. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for this study, combining primary interviews with extensive secondary validation. Interviews included plant managers, procurement leads at municipal utilities, R&D directors in chemical synthesis, and environmental compliance officers. Secondary data sources comprised customs and trade statistics, China's MEE reports, US EPA guidelines, and Europe's ECHA REACH framework. This approach ensured robust bottom-up and top-down triangulation of market data.
Across the analysis window, the analytical framework modeled market dynamics using a multi-dimensional approach. Segmentation included product type, application, end-user industry, packaging type, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends, projected demand drivers, and expert consensus. Key inputs included water treatment infrastructure investment plans and raw material price forecasts.
Material uncertainties — including geopolitical shifts, unforeseen technological breakthroughs, or significant changes in environmental legislation — sit outside the modeled envelope. Forecasts reflect assumptions regarding these macro-environmental factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosphotungstic Acid Market
Chemicals
Paint Remover Market
Chemicals
Iso Nonanol Market
Chemicals
Sodium Methoxide Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Para Cresol Market
Chemicals
Egypt Acidulants Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
South America Construction Chemicals Market
Chemicals
Global Construction Chemical Market
Chemicals
Peracetic Acid Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Trimethylamine Market
Chemicals
Global Methylene Chloride Market
Chemicals
Bakers Ammonia Market