
 Phosphotungstic Acid Market | 2026-2036
Phosphotungstic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphotungstic Acid Market Analytics
Aftermarket technical service revenue for catalyst regeneration and reactivation is reshaping margin distribution in the phosphotungstic acid value chain. Merck KGaA leverages its analytical-grade certification network to command premium positioning in European diagnostics channels. TCI Chemicals anchors its competitive stance through deep specialization in crystalline-form custom synthesis for Japanese pharmaceutical clients. American Elements controls North American supply security through in-house tungsten sourcing and domestic manufacturing scale.
Phosphotungstic acid is a heteropoly acid with the formula H3PW12O40, typically supplied as a hydrate with molecular weights ranging from approximately 2880 g/mol for the anhydrous form to over 3000 g/mol for common hydrated grades; it functions primarily as a strong Brønsted acid and oxidation catalyst in organic synthesis, electron microscopy staining, and proton-conducting membrane applications. High-purity grades capture the dominant share of value owing to stringent pharmaceutical and diagnostic specifications, while analytical-grade volumes are expanding fastest in proteomics and histology workflows. Industrial-grade phosphotungstic acid faces margin compression from commoditization in bulk pigment manufacturing, though dispersant applications in specialty coatings retain above-average profitability.
EPA hazardous substance reporting requirements and OSHA permissible exposure limits govern U.S. handling and transport protocols, while REACH registration obligations in Europe restrict non-compliant imports and elevate documentation costs for distributors. China's SAMR enforces GB standards on chemical purity and labeling that foreign suppliers must satisfy for customs clearance. Stakeholders should monitor evolving dual-use chemical export controls and tungsten supply-chain traceability mandates that could reshape qualified supplier lists and regional sourcing strategies.
Market Dynamics
Specialty chemical manufacturers in China are expanding procurement of high-purity phosphotungstic acid grades for pharmaceutical catalysis, tightening specification requirements across import channels and reshaping competitive positioning in East Asian production clusters.
Growth Catalysts
- REACH compliance mandates:European importers now require full registration documentation, elevating qualified supplier lists and filtering out non-compliant traders from distribution channels.
- Proteomics workflow expansion:Diagnostic laboratories in Japan and South Korea are scaling analytical-grade volumes for histology and electron microscopy staining protocols.
- Tungsten supply traceability:China's GB standards for chemical purity and labeling are forcing foreign suppliers to upgrade quality systems for customs clearance.
Market Restraints
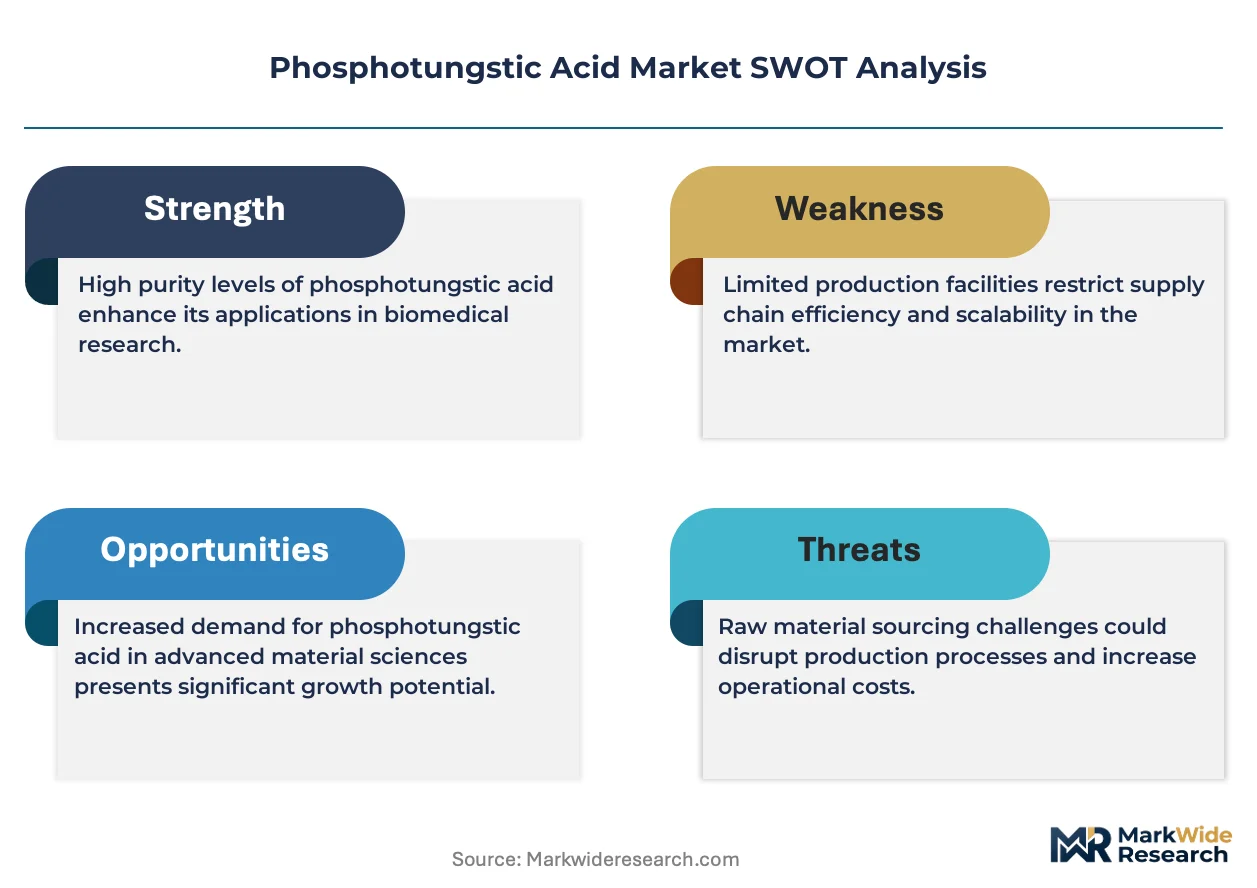
- Tungsten ore price volatility:Concentration of tungsten mining in Jiangxi and Hunan provinces exposes processors to input cost swings and export quota fluctuations.
- Substitution by phosphomolybdic acid:Pigment manufacturers in bulk coatings applications are switching to lower-cost heteropoly acids where staining precision is less critical.
- Dual-use chemical export controls:Stricter licensing requirements for tungsten compounds are extending lead times for cross-border shipments to qualified buyers.
Strategic Opportunities
- Proton-conducting membrane R&D:Fuel cell developers in Germany and Japan are testing phosphotungstic acid-doped polymers for elevated-temperature operation.
- Catalyst regeneration services:Aftermarket technical service revenue for reactivation is creating recurring revenue streams independent of virgin acid sales.
- Indian pharmaceutical manufacturing:CDSCO-registered active pharmaceutical ingredient producers are qualifying new heteropoly acid suppliers for oxidation catalysis steps.
Industry Challenges
- Analytical-grade certification timelines:ISO 17025 accreditation for pharmaceutical customers requires 12-18 month validation cycles that strain working capital.
- Crystalline form customization:Japanese pharmaceutical clients demand particle-size distributions that require dedicated reactor configurations and process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphotungstic Acid Market |
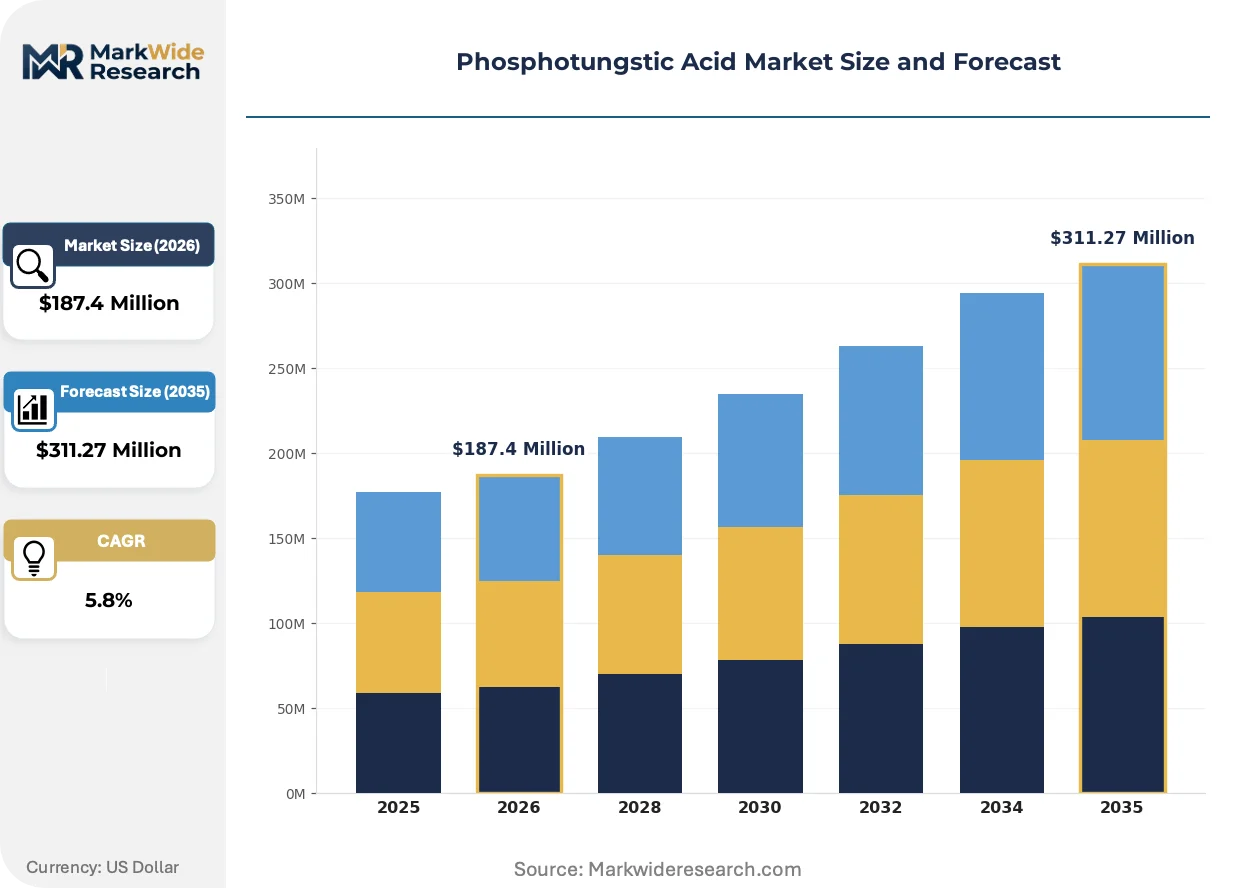
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity, Analytical Grade, Industrial Grade, Crystalline Application: Catalysis, Dispersant, Chemical Synthesis, Pigment End User: Pharmaceuticals, Chemicals, Research Laboratories, Diagnostics Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Merck KGaA, TCS Biosciences, Alfa Aesar, American Elements, Sigma-Aldrich, MP Biomedicals, Toronto Research Chemicals, Honeywell International Inc., TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphotungstic Acid Market Evolving Landscape
Workflow digitization in diagnostic laboratories and tightening purity mandates from pharmaceutical regulators are converging to reshape how phosphotungstic acid is specified, procured, and integrated into life-science supply chains.
Automated histology staining platforms are digitizing specimen preparation protocols in pathology laboratories. Diagnostic chains in the United States and Germany are adopting closed-system analyzers that require pre-certified reagent cartridges with validated lot traceability. This equipment is digitizing manual staining workflows and compressing demand for bulk analytical-grade powder formats in favor of unit-dose packaging with embedded RFID tracking.
China's SAMR enforcement of updated GB standards on chemical purity and hazardous substance labeling is extending documentation requirements to all import channels. Foreign suppliers must now submit third-party assay certificates and safety data sheets in Mandarin for customs clearance. Pharmaceutical-grade importers are responding by pre-qualifying domestic analytical laboratories for pre-shipment testing.
Consolidated procurement by multinational pharmaceutical manufacturers is displacing spot-market purchasing for high-purity grades. Merck KGaA and TCI Chemicals are securing multi-year supply agreements with Japanese and European drug developers that bundle technical service, reagent certification, and inventory management. This concentration is most visible in Basel and Shanghai, where global headquarters procurement teams are rationalizing qualified supplier lists to three to four certified vendors per region.
Phosphotungstic Acid Market Segmentation
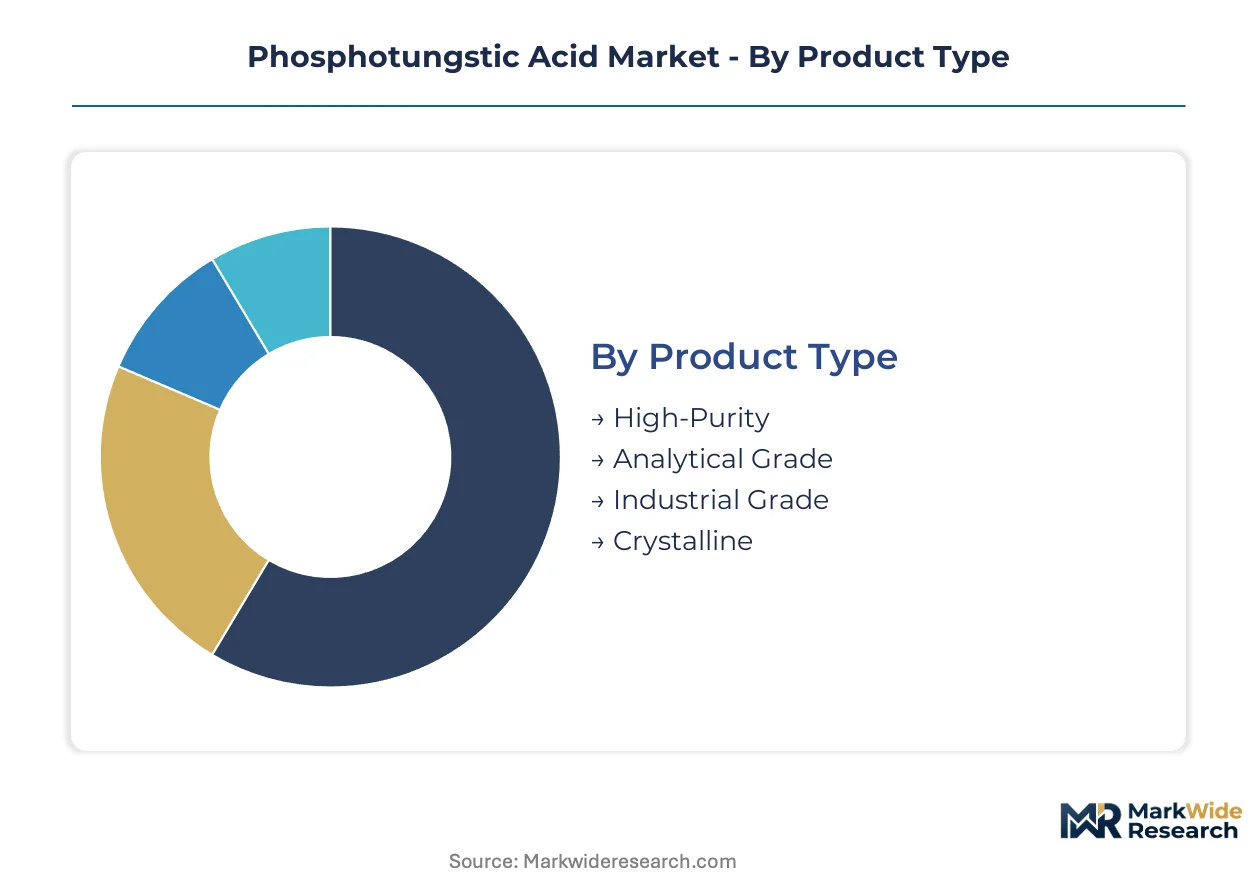
Phosphotungstic acid specifications vary dramatically across end-use requirements, with pharmaceutical catalysis demanding sub-ppm impurity thresholds while industrial pigment applications tolerate broader compositional ranges. Service intensity and technical support requirements differ sharply by segment, reshaping how suppliers configure their commercial organizations.
Product Type:
After-sales-service intensity varies dramatically across purity tiers, with pharmaceutical-grade customers demanding 12-18 month validation support and on-site technical assistance that industrial buyers rarely require.
- High-Purity:Sub-ppm metal impurity specifications with batch-specific certificates of analysis. Demand concentrates in Basel and Shanghai pharmaceutical clusters where CDSCO and EMA filings require documented supply chain traceability.
- Analytical Grade:ISO 17025-certified lots for diagnostic workflows with validated electron microscopy staining protocols. Japanese proteomics laboratories are scaling volumes fastest as automated histology platforms displace manual preparation methods.
- Industrial Grade:Commoditized hydrate forms for bulk pigment manufacturing facing margin compression from phosphomolybdic acid substitution.
- Crystalline:Custom particle-size distributions for pharmaceutical reactor feedstock requiring dedicated reactor configurations.
High-purity grades hold the largest share; momentum sits with analytical-grade formats as diagnostic automation accelerates.
Application:
Margin structures diverge sharply by application, with catalyst regeneration services capturing recurring revenue streams that pigment dispersant sales cannot match.
- Catalysis:Brønsted acid function in oxidation steps for active pharmaceutical ingredient synthesis. German and Japanese fuel cell developers are testing phosphotungstic acid-doped proton-conducting membranes for elevated-temperature operation.
- Dispersant:Specialty coatings applications retaining above-average profitability despite industrial-grade commoditization pressures elsewhere.
- Chemical Synthesis:Heteropoly acid catalysis for fine chemical intermediates with growing demand from Indian CDSCO-registered API producers.
- Pigment:Bulk manufacturing applications facing substitution risk where staining precision requirements are less critical.
Catalysis commands the dominant revenue position; steepest expansion trajectory belongs to proton-conducting membrane R&D applications.
End User:
Procurement consolidation patterns separate institutional buyers from fragmented research consumers, with multinational pharmaceutical headquarters rationalizing qualified supplier lists to three or four certified vendors per region.
- Pharmaceuticals:Multi-year supply agreements bundling technical service, reagent certification, and inventory management. REACH compliance documentation and Mandarin-language safety data sheets are now mandatory for customs clearance.
- Chemicals:Spot-market purchasing displaced by consolidated procurement with pre-qualified domestic analytical laboratories for pre-shipment testing.
- Research Laboratories:Unit-dose packaging with embedded RFID tracking replacing bulk powder formats as closed-system analyzers digitize specimen preparation.
- Diagnostics:Pre-certified reagent cartridges with validated lot traceability for automated histology staining platforms in US and German pathology chains.
Pharmaceuticals represent the largest end-use segment; diagnostic laboratories are gaining share fastest through workflow digitization.
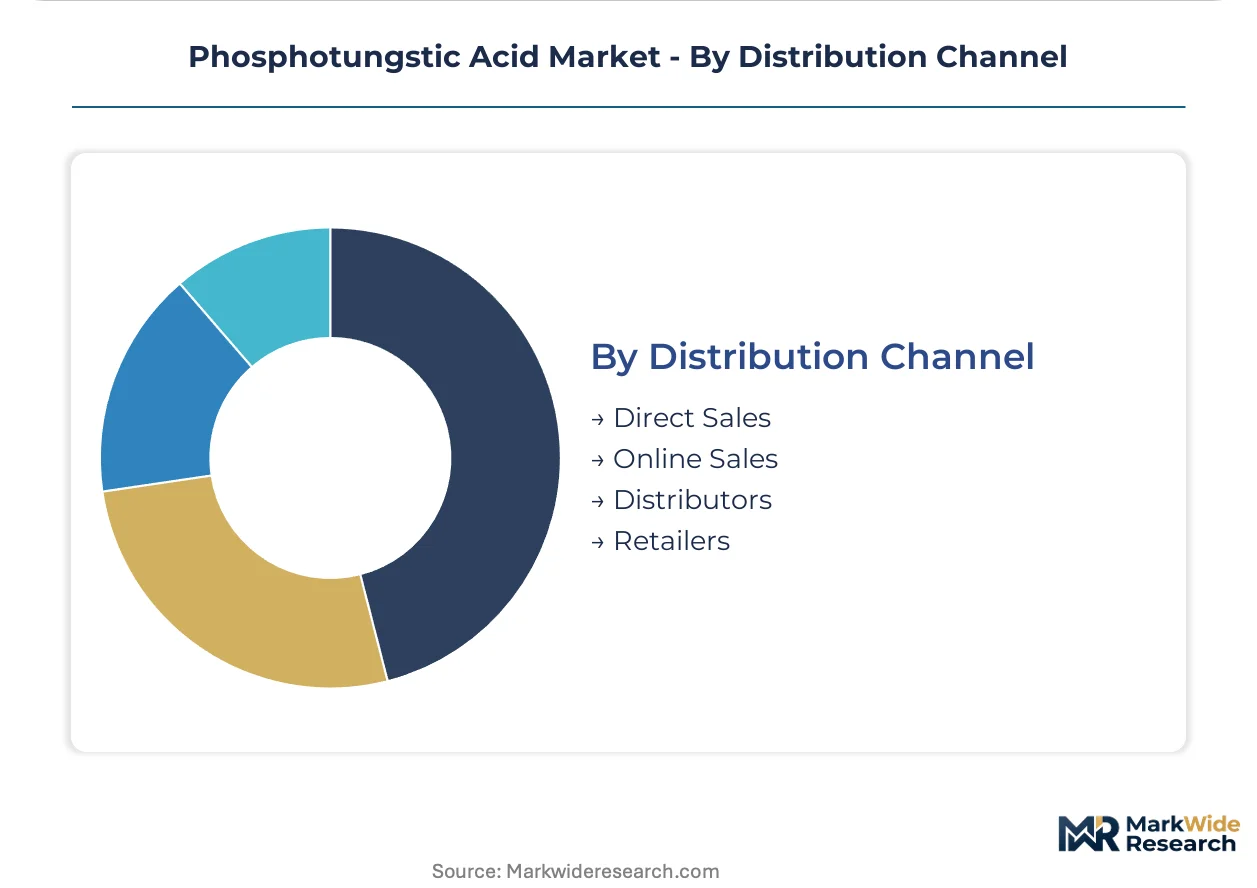
Distribution Channel:
Channel economics reflect documentation burden intensity, with REACH registration obligations and GB standard compliance elevating costs for non-direct routes.
- Direct Sales:Multi-year agreements with technical service bundling for pharmaceutical and diagnostic customers requiring validated supply chains.
- Distributors:Qualified supplier lists filtering out non-compliant traders as European importers demand full registration documentation.
- Online Sales:Research-grade volumes for proteomics and histology workflows with digitized procurement protocols.
- Retailers:Minimal presence limited to small-volume educational and institutional research supply.
Direct sales capture the dominant channel position; distributors are restructuring fastest to meet tightening import documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Japanese pharmaceutical buyers absorb premium pricing for validated supply chains, while Indian pigment manufacturers drive hard volume negotiations. Chinese procurement offices now demand Mandarin-language documentation as a non-negotiable entry condition.
United States
Diagnostic laboratory chains in Boston and San Diego are converting to automated histology platforms requiring pre-certified reagent cartridges. EPA hazardous substance reporting governs interstate transport and warehouse storage protocols. The Research Triangle Park cluster in North Carolina anchors contract research organization demand for analytical-grade heteropoly acids.
Germany
Fuel cell developers in Munich and Stuttgart are testing phosphotungstic acid-doped proton-conducting membranes for elevated-temperature vehicle applications. REACH registration obligations filter non-compliant traders from import channels. The BASF-Ludwigshafen chemical corridor maintains concentrated demand for catalyst regeneration services.
China
Specialty chemical manufacturers in Shanghai and Suzhou are expanding high-purity grade procurement for pharmaceutical catalysis steps. SAMR enforcement of updated GB standards mandates third-party assay certificates in Mandarin for customs clearance. The Yangtze River Delta production cluster is rationalizing qualified supplier lists to three certified vendors per compound class.
Japan
Proteomics laboratories in Osaka and Tokyo are scaling analytical-grade volumes for electron microscopy staining protocols. METI guidelines on chemical purity documentation align with PMDA pharmaceutical filing requirements. The Kansai pharmaceutical manufacturing belt demands crystalline-form custom synthesis with particle-size distributions requiring dedicated reactor configurations.
India
CDSCO-registered active pharmaceutical ingredient producers in Hyderabad and Ahmedabad are qualifying new heteropoly acid suppliers for oxidation catalysis. The country's national pharmaceutical regulator mandates documented supply chain traceability for import license renewal. The Gujarat chemical corridor is displacing spot-market purchasing with consolidated procurement through pre-qualified domestic analytical laboratories.
Phosphotungstic Acid Market Competitive Landscape
Vertically integrated tungsten processors and analytical-grade certification specialists split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: in-house tungsten miners controlling upstream raw material security, specialty chemical houses with ISO 17025-accredited quality systems, and regional distributors managing import documentation complexity. Competitive moves center on multi-year supply agreements bundling technical service and captive tungsten sourcing.
Within the certification-intensive tier, Merck KGaA exemplifies the European analytical-grade archetype through its quality system depth. TCI Chemicals occupies a parallel position in the Japanese market, representing crystalline-form specialization for pharmaceutical reactor feedstock. American Elements anchors North American supply security through domestic manufacturing scale and in-house tungsten control. These three patterns—European certification dominance, Japanese custom synthesis precision, and North American vertical supply security—define the competitive structure.
| Leading Market Players |
|---|
| Merck KGaA |
| TCS Biosciences |
| Alfa Aesar |
| American Elements |
| Sigma-Aldrich |
| MP Biomedicals |
| Toronto Research Chemicals |
| Honeywell International Inc. |
| TCI Chemicals |
| Others |
Value Network & Pricing Analysis
Tungsten ore price volatility in Jiangxi and Hunan provinces determines both the spread between pharmaceutical-grade premiums and industrial-grade commoditization and the geographic shape of qualified supplier networks. REACH documentation burdens and GB standard compliance costs further stratify pricing tiers while concentrating procurement through certified channels.
Pricing Analysis
Catalyst regeneration and reactivation service contracts drive lifetime value capture beyond virgin acid transactions. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and industrial-grade levels reflects certification depth and validation support intensity. Cost compression in industrial-grade hydrate forms is intensifying because phosphomolybdic acid substitution in bulk pigment applications eliminates pricing power. Indian pigment manufacturers exhibit highest price sensitivity while Japanese pharmaceutical buyers absorb premiums for validated supply chains.
Supply Chain Analysis
Tungsten concentrate feedstock draws from Chinese mining districts, North American in-house sourcing at American Elements, and spot-market procurement by European distributors. Sodium tungstate, phosphoric acid, and crystallization reagents constitute the critical input trinity. Single-source vulnerability concentrates in Jiangxi province ore processing. Distribution runs through direct technical-service agreements for pharmaceutical customers and qualified distributor networks managing REACH documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workflow digitization in diagnostic laboratories fragments procurement into pre-certified cartridge formats and bulk powder spot markets, creating distinct capability niches for certification specialists versus commodity processors.
For Market Incumbents: Pre-empt phosphomolybdic acid substitution in pigment applications by anchoring profitability in catalyst regeneration service contracts. Secure captive tungsten supply through backward integration into ore processing or long-term offtake agreements with Jiangxi concentrate producers. ISO 17025 accreditation investment defends pharmaceutical-grade positioning against emerging analytical-grade specialists. For New Entrants and Emerging Players: CDSCO-registered API producers in Hyderabad and Ahmedabad represent the most penetrable entry point for heteropoly acid qualification. Proton-conducting membrane R&D partnerships with German fuel cell developers offer technology-pull positioning distinct from commodity catalysis. Technical service bundling with domestic analytical laboratory pre-qualification addresses India's import documentation requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certification-intensive specialists with validated pharmaceutical supply chains. Acquisition targets should demonstrate ISO 17025 accreditation depth and multi-year supply agreements with Basel or Shanghai pharmaceutical clusters. Monitor CDSCO import license renewal timelines as inflection indicators for Indian market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Concentrate | Jiangxi province ore security insulates margin from export quota fluctuations. |
| ISO 17025 Accreditation Investment | Pharmaceutical customer validation cycles require certified quality system depth. |
| Catalyst Regeneration Service Launch | Recurring revenue streams decouple profitability from virgin acid volume. |
| Proton-Conducting Membrane R&D Partnership | German fuel cell developers test elevated-temperature polymer doping. |
| Pre-Qualified Domestic Laboratory Network | India's CDSCO mandates third-party assay for import license renewal. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical procurement directors, specialty chemical plant managers, diagnostic laboratory operations heads, and tungsten concentrate trading specialists. Secondary validation drew from customs/trade data, CDSCO import license filings, ECHA REACH registration databases, and SEC 10-K disclosures from listed chemical manufacturers. Bottom-up segment sizing triangulated against top-down industry association estimates.
Calibration against historical price series and volume trajectories anchored projections across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, crystalline form specification, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves adjusted for input cost elasticity. Tungsten ore price scenarios and REACH documentation cost inflation served as industry-specific forecast inputs.
Stress conditions across tungsten concentrate supply disruptions, phosphomolybdic acid substitution rates, and dual-use chemical export licensing delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and pharmaceutical outsourcing trends. Cross-checking against ECHA registration renewal timelines and CDSCO import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Allyl Chloride Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Calcium Hydroxide Market
Chemicals
Isoamyl Acetate Market
Chemicals
Laboratory Chemicals Market
Chemicals
Acid Anhydrides Market
Chemicals
Methanol Market
Chemicals
Chromium Trioxide Market
Chemicals
Mercuric Chloride Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Sulfur Chemicals Market
Chemicals
Periodic Acid Market
Chemicals
Methylamines Market
Chemicals
Japan Methanol Market
Chemicals
Global Construction Chemical Market