
 Pharmaceutical Suspension Market | 2026-2036
Pharmaceutical Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Suspension Market Analysis
Hospital procurement consolidation across integrated delivery networks is pivoting volume toward contract-manufactured suspensions with guaranteed supply continuity. AstraZeneca plc leverages its respiratory suspension portfolio to sustain formulary positioning in acute care settings. AbbVie Inc. anchors its immunology franchise through differentiated rheumatic suspension formulations. GlaxoSmithKline plc dominates pediatric antibiotic suspensions via established channel relationships with pharmacy chains.
Pharmaceutical suspensions are heterogeneous dispersions of insoluble drug particles in a liquid vehicle, typically stabilized by suspending agents such as xanthan gum or microcrystalline cellulose at particle sizes below 5 micrometers to ensure dose uniformity and syringeability. These formulations serve patients who cannot swallow solid dosage forms, including children, elderly individuals, and post-surgical populations. Oral suspensions command the largest volume share due to broad therapeutic applicability across infectious disease and gastroenterology indications, while injectable suspensions capture premium positioning in oncology and rheumatology where sustained-release depot formulations enable extended dosing intervals. Extended release formulations within the formulation dimension represent the fastest-expanding margin pool as patent-protected complex generics attract limited competition.
FDA bioequivalence guidelines for locally acting suspensions, EMA reflection papers on nanosuspension characterization, and USP general chapters on dissolution testing for suspensions collectively elevate technical barriers to generic entry. These frameworks compel manufacturers to invest in particle engineering and in vitro bioequivalence modeling before regulatory submission. Stakeholders must monitor evolving FDA guidance on complex generic suspensions to anticipate which therapeutic categories will face accelerated generic penetration versus prolonged exclusivity periods.
Market Dynamics
FDA bioequivalence standards for locally acting suspensions are forcing manufacturers to invest in particle engineering and in vitro modeling before regulatory submission, compressing margins for generic entrants while extending exclusivity windows for complex formulations.
Growth Catalysts
- Dysphagic Patient Prevalence:Hospital formularies in the United States increasingly mandate liquid alternatives for patients with swallowing disorders, expanding the addressable patient base for oral suspensions.
- Pediatric Formulary Expansion:EMA reflection papers on nanosuspension characterization are accelerating regulatory clarity for pediatric dosing, enabling faster development of age-appropriate formulations.
- Depot Formulation Demand:Rheumatology and oncology practices are adopting sustained-release injectable suspensions to extend dosing intervals and improve patient compliance.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for suspension-grade materials clusters in India and China, creating vulnerability to export restrictions or quality enforcement actions.
- Dissolution Testing Burden:USP general chapters on suspension dissolution require specialized apparatus and method development, extending analytical timelines and elevating development costs.
- Complex Generic Barriers:FDA bioequivalence guidelines for locally acting suspensions impose particle size distribution and polymorphism requirements that generic manufacturers struggle to replicate.
Strategic Opportunities
- Geriatric Home Care:Japan's aging population and community-based care expansion create demand for pre-filled oral syringes and unit-dose suspension packaging.
- Complex Generic White Space:Patent-protected extended-release suspension formulations face limited competition, offering margin pools for manufacturers with particle engineering capabilities.
- Contract Manufacturing Scale:Integrated delivery network procurement consolidation favors contract manufacturers with guaranteed supply continuity and regulatory track records.
Industry Challenges
- Particle Engineering Talent Scarcity:Formulation scientists with expertise in nanosuspension stabilization and controlled-release matrix design command premium compensation and limited availability.
- Multiparameter Bioequivalence:Demonstrating equivalence across particle size, polymorphism, and in vitro release profiles requires iterative method development and extended regulatory dialogue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Suspension Market |
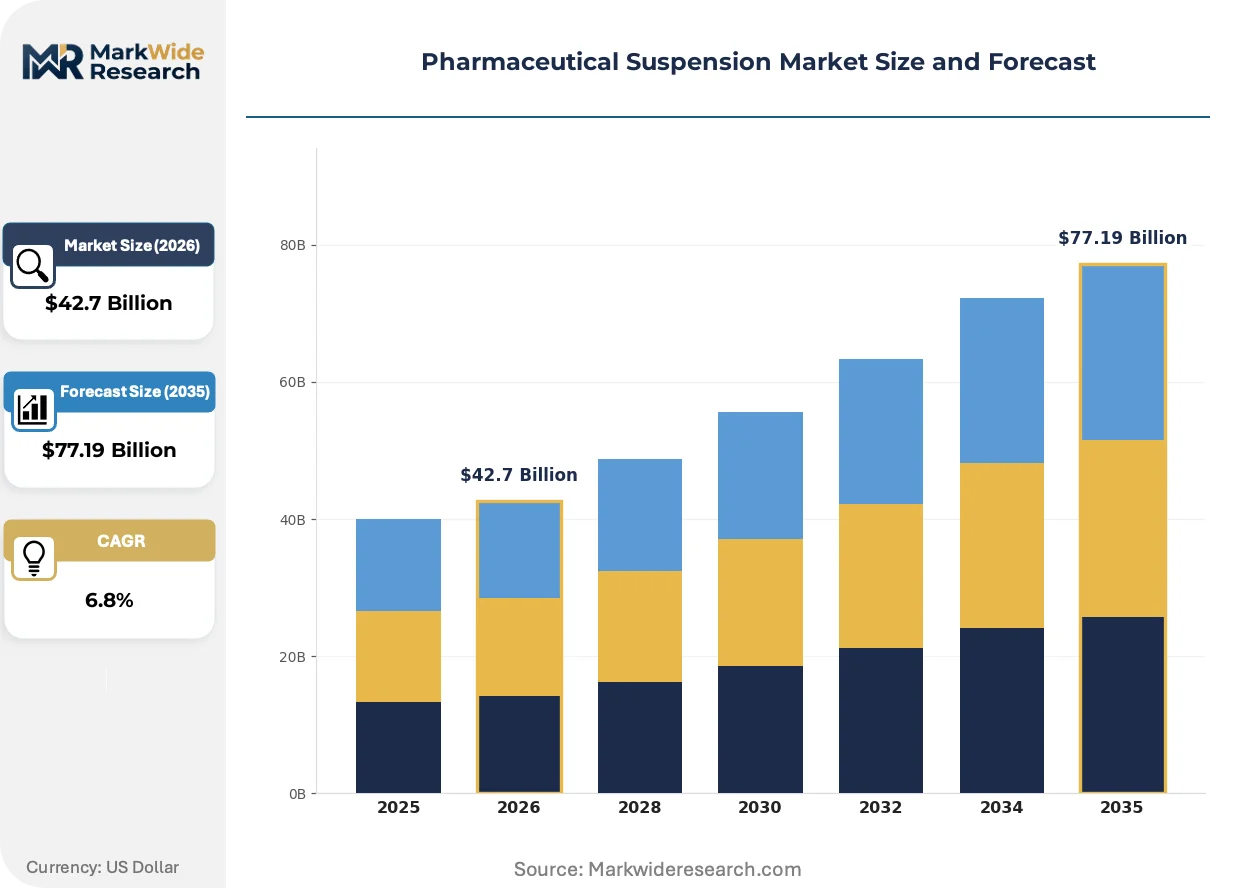
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Suspensions, Injectable Suspensions, Topical Suspensions, Ophthalmic Suspensions Therapy Area: Rheumatology, Oncology, Infectious Diseases, Gastroenterology End User: Hospitals, Pharmacies, Homecare, Research Laboratories Formulation: Stable Formulations, Extended Release, Immediate Release, Liquid Formulations |
| Companies Covered | AstraZeneca plc, Bristol Myers Squibb Company, AbbVie Inc., GlaxoSmithKline plc, Eli Lilly and Company, Amneal Pharmaceuticals LLC, Bayer AG, Johnson & Johnson, ANI Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Suspension Market Emerging Trajectories
Continuous manufacturing technologies are reshaping suspension production economics, while regulatory frameworks for complex generics evolve toward physiologically-based bioequivalence models. These forces are compressing development timelines for innovators and raising technical barriers for followers.
Hot-melt extrusion paired with nanosuspension stabilization is decentralizing production scale requirements for sustained-release formulations. Mid-size manufacturers in Germany and Switzerland are adopting modular continuous lines to produce clinical trial batches and niche commercial volumes without dedicated large-scale facilities. This technology is decentralizing capacity concentration that previously favored high-volume blockbusters.
EMA reflection papers on nanosuspension characterization are mandating orthogonal particle sizing methods and surface charge analysis for regulatory submissions. European manufacturers must now demonstrate batch-to-batch consistency across multiple analytical platforms before approval. Pediatric antibiotic suspensions face the steepest compliance burden, with sponsors investing in laser diffraction and nanoparticle tracking analysis capabilities.
Hospital procurement through integrated delivery networks is consolidating volume toward sole-source contracts with guaranteed supply continuity. Pharmacy chains are displacing independent distributors in pediatric suspension fulfillment, capturing volume through direct manufacturer relationships. This concentration is most visible in the United States, where three national pharmacy chains control the majority of pediatric antibiotic suspension dispensing.
Pharmaceutical Suspension Market Segmentation
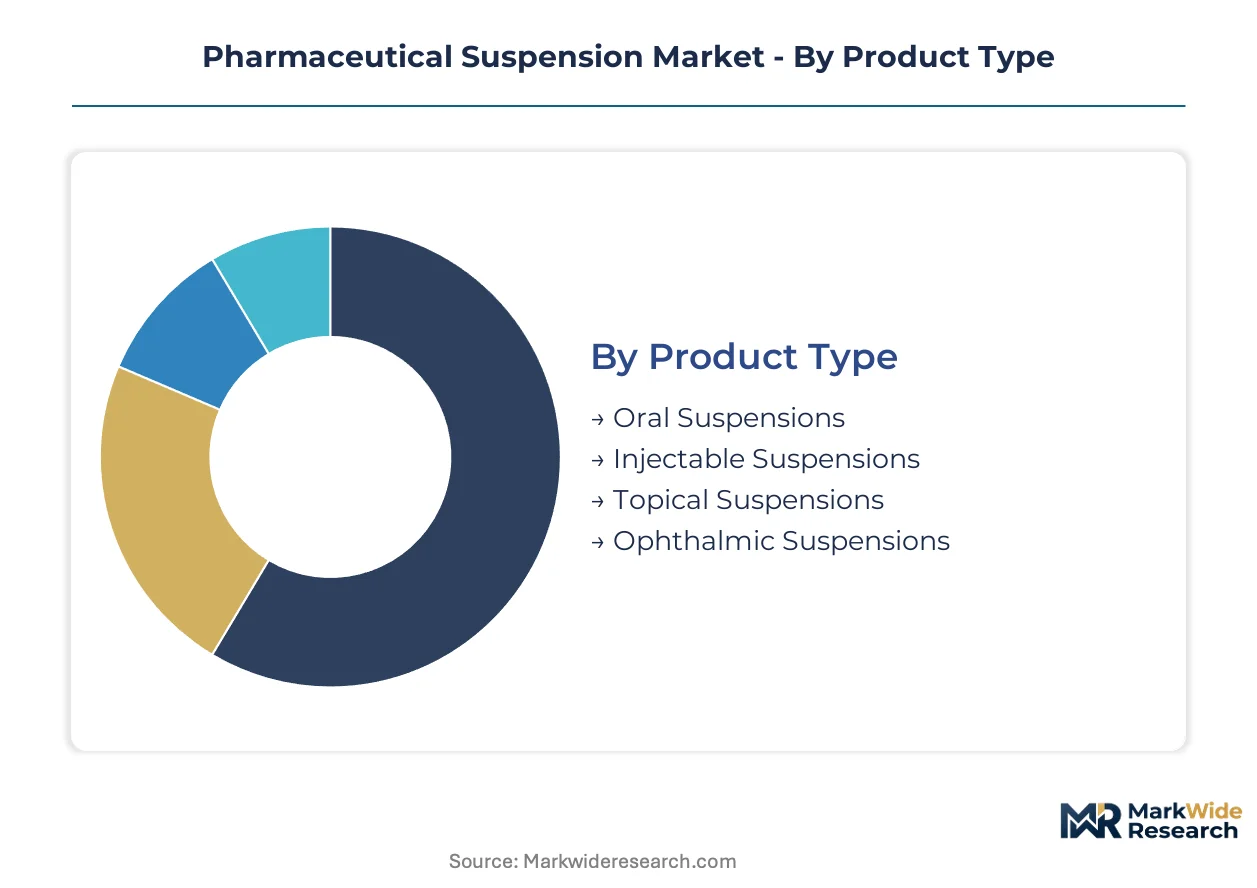
Segmentation in pharmaceutical suspensions reveals how formulation complexity, patient accessibility requirements, and therapeutic applications create distinct competitive arenas. Each dimension carries unique technical barriers, regulatory pathways, and margin structures that shape manufacturer positioning.
Product Type:
Buyers differentiate by route of administration complexity and the clinical settings where administration occurs.
- Oral Suspensions:Heterogeneous dispersions of insoluble drug particles in aqueous vehicles, stabilized by suspending agents such as xanthan gum or microcrystalline cellulose. Demand concentrates in United States hospital formularies serving dysphagic patients and pediatric populations, with pharmacy chains capturing dispensing volume through direct manufacturer relationships.
- Injectable Suspensions:Depot formulations enabling sustained drug release through particle size control and polymorphism engineering. Rheumatology and oncology practices in Japan and Germany are adopting these formulations to extend dosing intervals and improve patient compliance in chronic disease management.
- Topical Suspensions:Semi-solid preparations for dermatological delivery requiring viscosity modulation and skin permeation optimization.
- Ophthalmic Suspensions:Sterile particulate formulations demanding rigorous particle size control below 10 micrometers to prevent ocular irritation and ensure dose uniformity.
Volume sits with Oral Suspensions; growth tilts toward Injectable Suspensions.
Therapy Area:
Regulatory complexity and reimbursement intensity separate therapeutic categories by development timeline and commercial risk.
- Rheumatology:Sustained-release corticosteroid and biologic suspensions for intra-articular and intramuscular delivery. United States rheumatology practices are expanding depot formulation adoption to reduce injection frequency in osteoarthritis and inflammatory arthritis populations, with FDA bioequivalence standards for locally acting suspensions elevating generic barriers.
- Oncology:Cytotoxic and hormonal suspensions requiring sterile manufacturing and extended stability profiles. German oncology centers are integrating sustained-release formulations into supportive care protocols, driven by EMA reflection papers on nanosuspension characterization that clarify regulatory pathways.
- Infectious Diseases:Antibiotic suspensions dominating pediatric prescribing volumes with established pharmacokinetic profiles.
- Gastroenterology:Anti-inflammatory and acid-suppressing suspensions for patients with swallowing disorders or nasogastric tube dependence.
Revenue concentrates in Rheumatology; regulatory clarity is expanding fastest in Oncology.
End User:
Procurement scale and formulary control authority determine contract structures and supply assurance requirements.
- Hospitals:Integrated delivery networks in the United States are consolidating procurement toward sole-source contracts with guaranteed supply continuity, mandating liquid alternatives for dysphagic patients through formulary standardization.
- Pharmacies:Three national pharmacy chains control the majority of pediatric antibiotic suspension dispensing, displacing independent distributors through direct manufacturer relationships and inventory centralization.
- Homecare:Pre-filled oral syringes and unit-dose packaging for Japan's aging population and community-based care expansion.
- Research Laboratories:Clinical trial materials and comparator products for bioequivalence studies with specialized stability documentation.
Procurement volume clusters in Hospitals; channel expansion is accelerating most quickly in Homecare.
Formulation:
Release kinetics and manufacturing complexity create tiered margin pools with varying competitive intensity.
- Extended Release:Matrix-based or reservoir systems controlling drug dissolution through particle engineering and polymer selection. Patent-protected complex generics in this category face limited competition, attracting manufacturers with nanosuspension stabilization and controlled-release matrix design capabilities.
- Stable Formulations:Conventional suspensions with established excipient systems and validated manufacturing processes. Indian and Chinese API suppliers dominate active pharmaceutical ingredient sourcing for these formulations, creating concentration risk amid export restriction vulnerabilities.
- Immediate Release:Rapid-dissolution suspensions for acute symptom management with shorter development timelines.
- Liquid Formulations:Ready-to-use presentations eliminating reconstitution steps for pediatric and geriatric compliance.
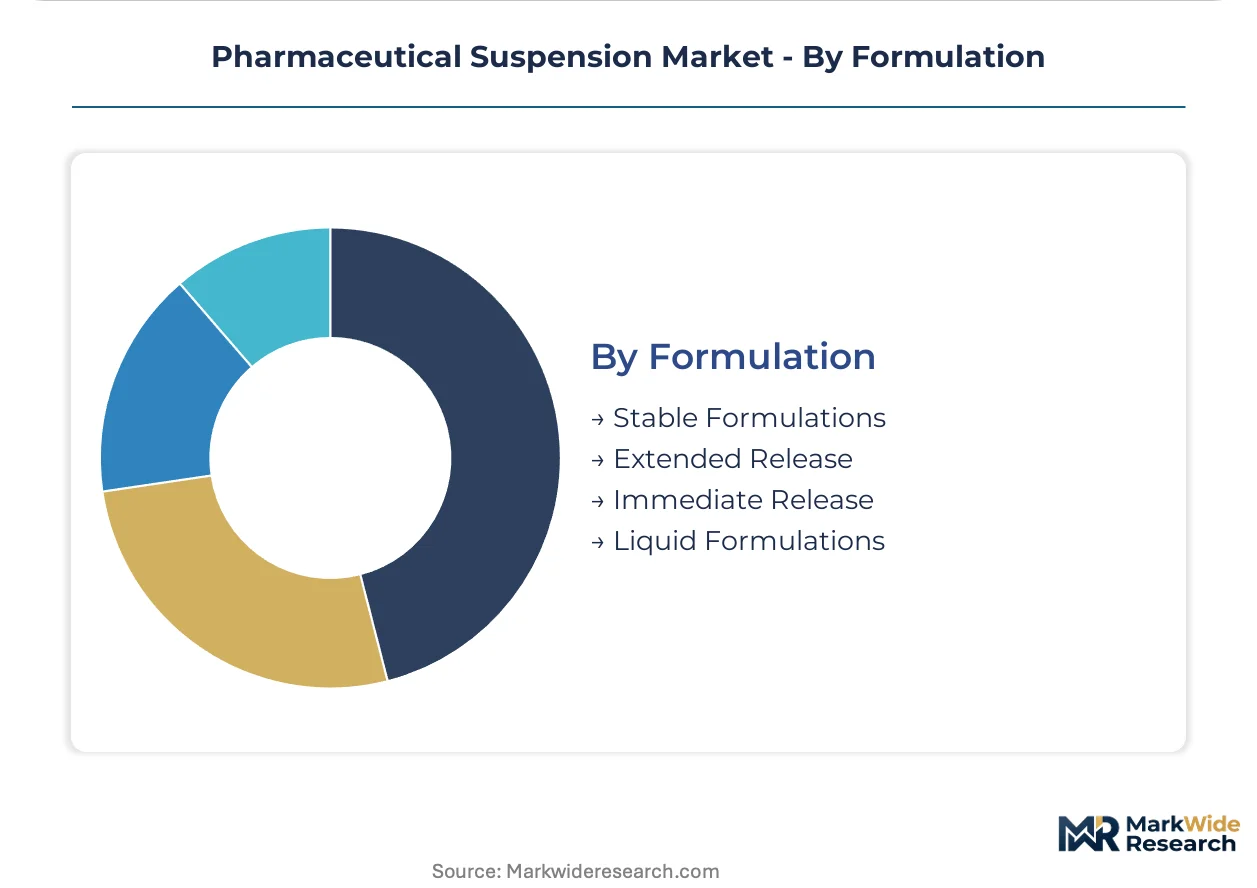
Unit economics favor Extended Release; development activity is concentrating fastest in Stable Formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital formulary consolidation in the United States concentrates procurement volume for oral suspensions, while Japan's geriatric care expansion and Germany's injectable depot adoption create complementary demand poles across three continents.
United States
Integrated delivery networks mandate liquid alternatives for dysphagic patients through standardized hospital formularies, expanding the addressable base for oral suspensions. FDA bioequivalence guidelines for locally acting suspensions elevate technical barriers for generic entrants. Three national pharmacy chains in the Northeast and Midwest control pediatric antibiotic suspension dispensing through direct manufacturer relationships.
Germany
Oncology centers in Bavaria and North Rhine-Westphalia integrate sustained-release injectable suspensions into supportive care protocols for chronic disease management. EMA reflection papers on nanosuspension characterization clarify regulatory pathways for complex generics. The Frankfurt-Rhine-Main pharmaceutical cluster hosts manufacturers adopting modular continuous manufacturing lines for clinical trial batches.
Japan
Community-based care expansion for the aging population drives demand for pre-filled oral syringes and unit-dose suspension packaging in Kanto and Kansai regions. METI guidelines on pharmaceutical manufacturing quality support domestic production of geriatric-friendly formulations. Osaka-based contract manufacturers scale capacity for homecare-directed packaging formats.
India
API sourcing for suspension-grade materials clusters in Gujarat and Maharashtra, creating supply concentration for global formulation manufacturers. CDSCO quality enforcement actions on export-oriented facilities intermittently disrupt supply continuity. Hyderabad's pharmaceutical corridor houses particle engineering specialists serving contract manufacturing demand from North American and European sponsors.
Switzerland
Mid-size manufacturers in Basel and Zurich adopt hot-melt extrusion paired with nanosuspension stabilization for niche commercial volumes and clinical trial materials. Swissmedic standards for complex generic suspensions align with EMA frameworks while permitting streamlined national pathways. The Basel biopharma cluster anchors European development of controlled-release matrix designs.
Pharmaceutical Suspension Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue complex generic white space through particle engineering capabilities. The market structures around three tiers: multinational innovators with respiratory and immunology franchises, regional specialists in pediatric antibiotics, and contract manufacturers serving integrated delivery network procurement. Competitive moves concentrate on supply continuity guarantees and regulatory track record accumulation rather than price aggression.
Among UK-based innovators, AstraZeneca plc and GlaxoSmithKline plc exemplify the formulary-anchored archetype through sustained hospital positioning. AbbVie Inc. represents the differentiated-rheumatic-suspension specialist tier. These three occupy positions defined by therapeutic focus breadth and acute care channel depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Bristol Myers Squibb Company |
| AbbVie Inc. |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Amneal Pharmaceuticals LLC |
| Bayer AG |
| Johnson & Johnson |
| ANI Pharmaceuticals Inc. |
| Others |
Supply Flow & Price Mechanics
Extended-release formulation premiums diverge sharply from commodity oral suspensions, with patent-protected complex generics commanding sustainable margins while standard antibiotic suspensions face cost compression from Indian and Chinese API oversupply. This bifurcation manifests in procurement patterns: hospital formularies negotiate sole-source contracts for depot formulations with guaranteed supply continuity, while pharmacy chains drive volume discounts on pediatric antibiotics through consolidated purchasing power.
Pricing Analysis
Volume concentrates in immediate-release oral suspensions where pharmacy chain consolidation intensifies price competition, while margins pool in extended-release injectable suspensions protected by FDA bioequivalence barriers. Price differentiation separates patent-protected depot formulations from commodity antibiotics, with certification tier and particle engineering capability determining premium capture. Pricing pressure stems from API oversupply in Gujarat and Maharashtra eroding margins on standard suspensions. Hospital procurement teams show lowest price sensitivity for dysphagic-patient formulations with guaranteed supply continuity.
Supply Chain Analysis
Freight costs for temperature-controlled suspension shipments amplify geographic sourcing advantages, favoring regional contract manufacturers over distant API suppliers. Active pharmaceutical ingredient production clusters in India and China, with formulation finishing distributed across Germany, Switzerland, and the United States. Suspension-grade excipients draw from cellulose suppliers in North America and xanthan gum producers in Asia. Single-source vulnerability concentrates in nanosuspension stabilization polymers. Distribution runs through integrated delivery networks for hospital formularies and direct manufacturer relationships for pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Particle engineering talent scarcity props pricing for complex generics, constraining supply expansion and sustaining exclusivity windows for manufacturers with proven nanosuspension capabilities.
For Market Incumbents: Extend formulary positioning through backward integration into API sourcing for suspension-grade materials, securing supply continuity guarantees that hospital procurement mandates. Invest in laser diffraction and nanoparticle tracking analysis capabilities to defend against emerging entrants lacking orthogonal characterization infrastructure. Deepen relationships with integrated delivery networks through sole-source contracting for extended-release depot formulations. For New Entrants and Emerging Players: Capture white space in geriatric homecare packaging by developing pre-filled oral syringe formats for Japan's community-based care expansion. Target complex generic extended-release suspensions where FDA bioequivalence guidelines limit follower competition. Pursue contract manufacturing partnerships with mid-size sponsors lacking particle engineering capabilities as the primary go-to-market pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational innovators seeking depot formulation capabilities, with IPO viability tethered to demonstration of sustained regulatory approval momentum. Long-term viability favors manufacturers with integrated particle engineering and continuous manufacturing infrastructure. Acquisition targets should show validated nanosuspension portfolios and hospital formulary anchoring. Watch EMA reflection paper implementation timelines as the signal for accelerated European complex generic penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Particle Engineering Capability Buildout | FDA bioequivalence standards for locally acting suspensions elevate technical barriers protecting margin pools. |
| Continuous Manufacturing Adoption | Modular production lines in Basel and Frankfurt-Rhine-Main decentralize scale requirements for niche volumes. |
| Hospital System Partnership | Integrated delivery network procurement consolidation favors suppliers with guaranteed supply continuity. |
| Regulatory Track Record Accumulation | EMA reflection papers on nanosuspension characterization mandate orthogonal analytical capabilities for approval. |
| Complex Generic Pipeline Expansion | Patent-protected extended-release formulations face limited competition from followers lacking particle engineering expertise. |
Methodological Framework
Multi-period observation of FDA approval timelines, EMA reflection paper implementation, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with formulation development executives, regulatory affairs leads, hospital procurement managers, and contract manufacturing officers. Secondary validation drew from FDA filings, EMA submission databases, USP general chapter revisions, and integrated delivery network contract announcements. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation converged on segment sizing.
Segment-weighting across formulation complexity, therapeutic application, and regional regulatory clusters shaped the analytical framework across the projection horizon. Dosage form, administration route, and patient population dimensions were modeled with CAGRs derived from historical approval velocity and formulary adoption curves. Forecast inputs included particle engineering talent pipeline constraints and API supply concentration metrics from Indian and Chinese export data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CDSCO quality enforcement actions and FDA guidance revisions on complex generic bioequivalence. Forecasts reflect documented assumptions about regulatory pathway stability and hospital procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market