
 South America Construction Chemicals Market | 2026-2036
South America Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Construction Chemicals Market Insights
Skilled formulator shortages across Brazil and Argentina is redrawing competitive boundaries for construction chemicals suppliers operating at scale. Sika AG leverages its São Paulo technical center to sustain localized admixture development for megaproject specifications. BASF SE anchors regional supply through captive production of acrylic-based additives at its Guarulhos complex. Votorantim Cimentos competes through backward integration into cement-compatible chemical blends distributed via its construction materials network.
Construction chemicals encompass admixtures, sealants, adhesives, and surface treatments formulated with polymers, surfactants, and mineral binders to modify concrete rheology, durability, or substrate bonding performance. These formulations serve primarily to extend structural service life and enable architectural designs exceeding native material limitations. Admixtures dominate value capture due to irreplaceability in high-strength concrete recipes for commercial infrastructure, while bio-based technology segments attract formulation investment as ANVISA and state environmental agencies tighten VOC thresholds. Sealants and adhesives occupy margin-intensive niches in industrial projects requiring chemical-resistant jointing systems.
ANVISA governs chemical substance registration and occupational exposure limits for construction chemical imports into Brazil. Argentina's Secretariat of Industry enforces IRAM standards for cement additive compatibility and performance labeling. Chile's Ministry of Housing and Urbanism mandates seismic-grade admixture certification for public infrastructure tenders. Stakeholders must monitor regulatory divergence across Mercosur members when standardizing product portfolios for cross-border project bids.
Market Dynamics
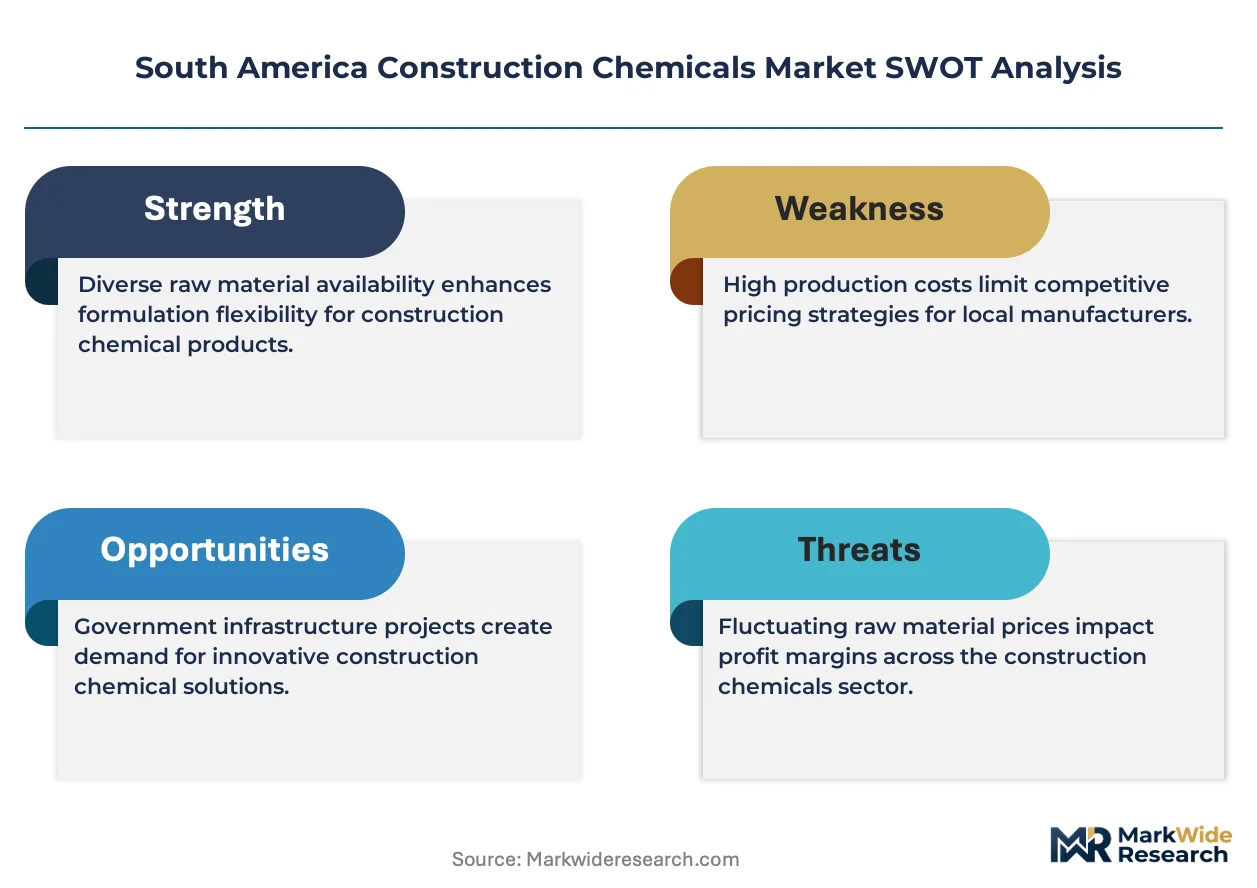
Brazil's ANVISA chemical substance registry overhaul is forcing construction chemicals suppliers to rebuild formulation compliance infrastructure from raw material sourcing through finished product labeling.
Growth Catalysts
- High-performance concrete specifications:Megaproject tenders across Brazil's southeast corridor now mandate superplasticizer inclusion for structural durability targets.
- ANVISA registration modernization:Streamlined import pathways for pre-approved polymer additives reduce time-to-market for foreign suppliers meeting occupational exposure standards.
- Seismic-grade certification mandates:Chile's Ministry of Housing and Urbanism requires admixture performance validation for public infrastructure, locking in premium formulation demand.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and naphthalene derivative prices swing with Brazilian refinery output disruptions.
- Import concentration risk:Specialty surfactants and performance polymers flow through Santos port, creating single-point vulnerability for inland distributors.
- Formulation complexity ceiling:Cement-compatible chemical blends face irreducible compatibility testing timelines that extend project bidding cycles.
Strategic Opportunities
- Argentina industrial corridor penetration:IRAM standards alignment creates cross-border product portability for Brazilian suppliers with existing compliance infrastructure.
- Bio-based surfactant convergence:ANVISA VOC threshold tightening intersects with state environmental agency mandates to open rapeseed-derived alternatives.
- Direct-to-contractor digital channels:Mid-size commercial builders in São Paulo state bypass traditional distributor markups through platform-based procurement.
Industry Challenges
- Rheology specialist scarcity:Brazilian universities graduate insufficient concrete admixture formulators to match rehabilitation program demand.
- Multi-jurisdiction certification lag:Mercosur regulatory divergence forces parallel testing protocols for products serving Brazil and Argentina.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Construction Chemicals Market |
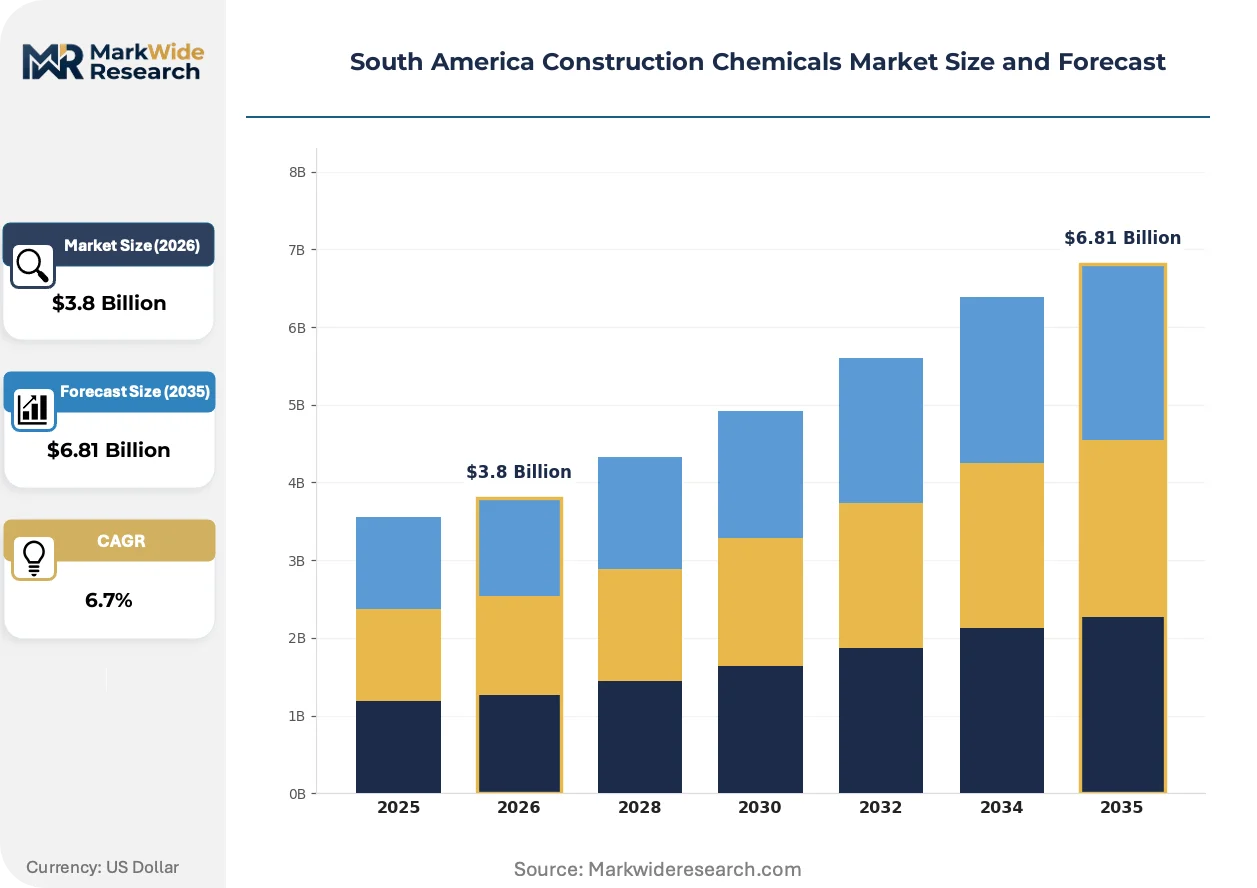
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Surface Treatment Application: Residential Buildings, Commercial Infrastructure, Industrial Projects, Road Construction End User: Contractors, Construction Companies, Architects, Engineers Technology: Polymerization, Pre-mixed, Dry Mortar, Bio-based |
| Companies Covered | Arkema, RPM International Inc, Sika AG, BASF SE, Henkel AG & Co KGaA, Saint-Gobain, CEMEX, Votorantim Cimentos, MAPEI S.p.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Construction Chemicals Market Trends and Innovations
Polymer chemistry advances and regulatory chemistry are compressing formulation development cycles while redrawing competitive boundaries between imported and locally compounded construction chemicals.
Polycarboxylate ether superplasticizers deliver slump retention and water reduction in high-strength concrete recipes. Infrastructure contractors across Minas Gerais state specify these additives for bridge deck pours requiring extended workability windows. The technology is miniaturizing batch-to-batch variability, enabling ready-mix suppliers to guarantee performance metrics previously reserved for precast specialists.
ANVISA's updated chemical substance registry requirements impose granular hazard classification and labeling obligations on imported additives. Formulation houses must rebuild documentation systems to trace component origins through multi-tier supply chains. Brazilian commercial infrastructure projects face extended material qualification timelines as foreign suppliers adapt submission protocols.
Performance-based procurement contracts displace specification-driven purchasing in São Paulo state megaprojects. Contractors now tender for guaranteed compressive strength and durability outcomes rather than prescribed admixture brands. This compresses supplier margins while rewarding formulators with captive testing capabilities and localized technical service teams.
South America Construction Chemicals Market Segmentation
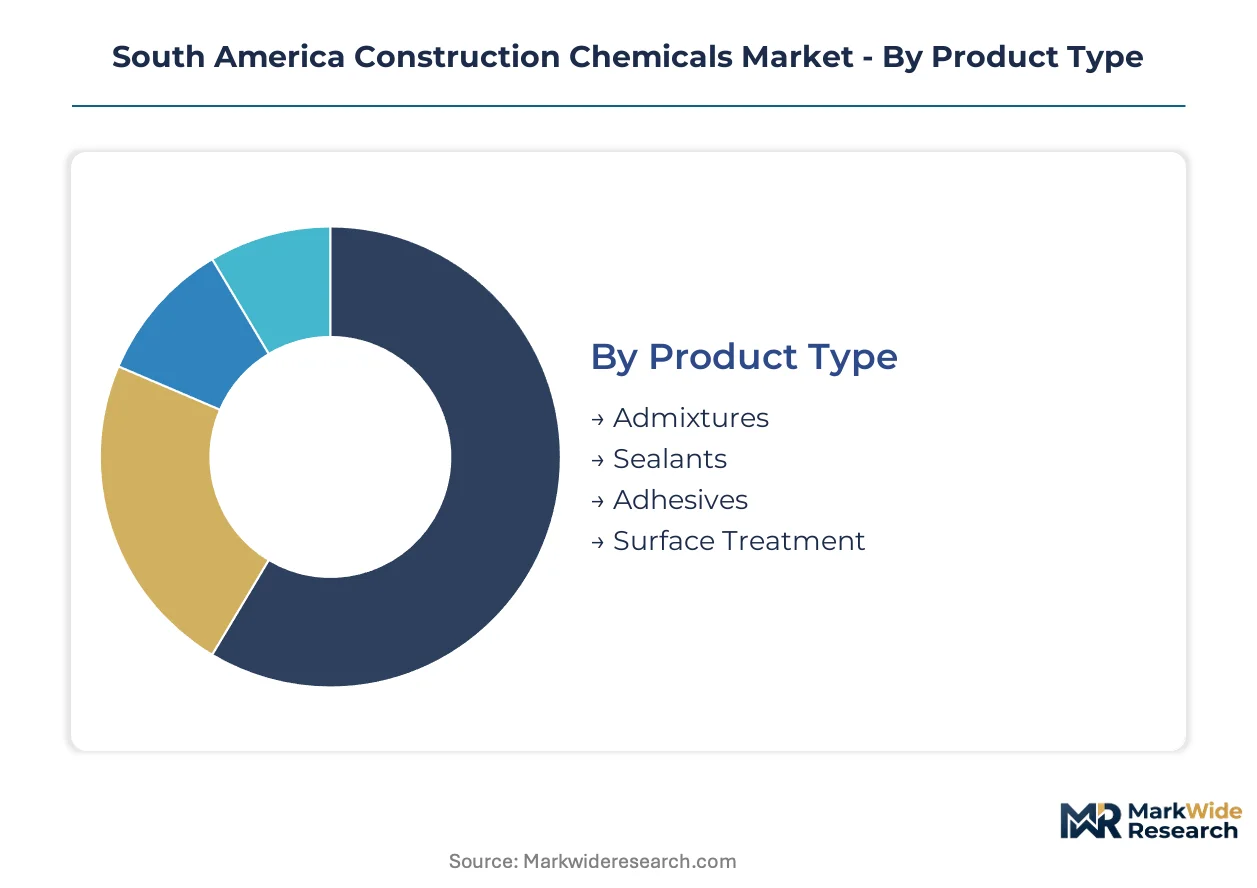
Segmentation reveals where specification power concentrates and which technology platforms face displacement risk from regulatory tightening. Product and technology categories show the sharpest divergence in substitution vulnerability across the South American market.
Product Type:
Admixtures face limited substitution threat due to irreplaceability in high-strength concrete formulations, while sealants and adhesives confront mounting pressure from mechanical fastening systems and prefabricated jointing solutions.
- Admixtures:Polycarboxylate ether and naphthalene-based formulations modify concrete rheology, water reduction, and slump retention. Demand concentrates in Brazil's southeast corridor for bridge deck pours and commercial high-rises requiring extended workability windows under ANVISA's updated substance registry protocols.
- Sealants:Polyurethane and silicone compounds provide chemical-resistant jointing for industrial containment structures. Procurement in Chile's mining belt specifies seismic-grade certified products under Ministry of Housing mandates, locking in premium formulation requirements despite higher unit costs versus conventional caulking.
- Adhesives:Acrylic and epoxy systems bond structural elements and flooring substrates across Argentine industrial corridors.
- Surface Treatment:Penetrating sealers and crystalline waterproofing compounds protect concrete substrates from chloride ingress in coastal Brazilian infrastructure.
Admixtures retain volume leadership; surface treatment holds the steepest expansion curve as rehabilitation programs accelerate specification of protective systems.
Application:
Commercial infrastructure commands the highest performance-grade chemical loading per square meter, while residential construction operates on thinner margins that compress supplier pricing power.
- Commercial Infrastructure:High-rise cores, parking structures, and facade systems require superplasticizer-dosed concrete achieving compressive strength targets exceeding standard mix designs. São Paulo state megaprojects now tender on guaranteed durability outcomes rather than prescribed admixture brands, shifting risk to suppliers with captive testing infrastructure.
- Industrial Projects:Mining facilities, petrochemical plants, and power generation stations specify chemical-resistant grouts, epoxy mortars, and acid-proof tile adhesives. Procurement in Minas Gerais and Chile's Atacama region prioritizes formulations validated under IRAM and seismic-grade certification protocols respectively.
- Residential Buildings:Standard-grade concrete modifiers and tile adhesives serve volume housing construction across Brazilian northeast states.
- Road Construction:Pavement sealers, curing compounds, and joint fillers protect highway infrastructure in Argentina's Ruta Nacional network.
Commercial infrastructure dominates value capture; industrial projects are climbing the fastest as extractive sector investment revives specification of chemical-resistant systems.
End User:
Contractors wield growing procurement autonomy through platform-based purchasing channels, while architects and engineers retain specification influence that shapes long-term formulation lock-in.
- Contractors:Ready-mix suppliers and specialty subcontractors across São Paulo state increasingly source admixtures through digital procurement platforms that bypass traditional distributor markups. Performance-based contracts transfer testing and compliance documentation burdens to chemical suppliers.
- Construction Companies:Large integrated builders with captive concrete batching operations negotiate direct supply agreements with formulators possessing localized technical service teams.
- Architects:Design specifications for exposed concrete finishes and waterproofing systems influence downstream chemical selection in premium commercial segments.
- Engineers:Structural and materials engineers validate admixture compatibility for high-strength and self-consolidating concrete applications in public infrastructure tenders.
Contractors control accelerating volume flows; construction companies maintain the tightest supplier relationships through multi-year framework agreements.
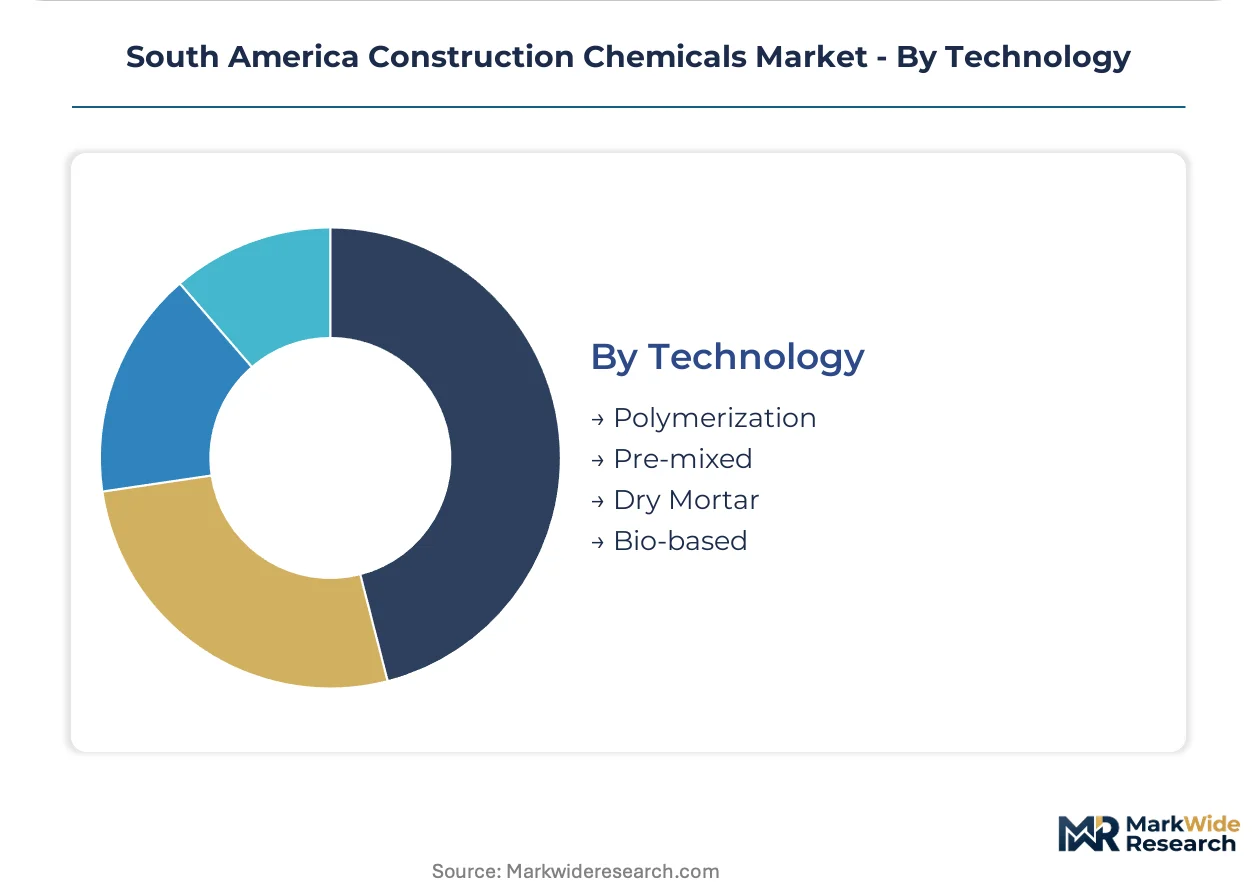
Technology:
Conventional polymerization platforms face regulatory pressure from bio-based alternatives as ANVISA and Brazilian state environmental agencies tighten VOC emission thresholds across manufacturing and application stages.
- Polymerization:In-situ acrylic and polyurethane systems deliver customizable cure profiles and chemical resistance for industrial jointing and coating applications. Argentine petrochemical corridor projects specify these technologies for tank lining and containment applications requiring IRAM-validated performance labeling.
- Bio-based:Rapeseed-derived surfactants and plant-oil modified polymers reduce hazardous substance classification burden under ANVISA's modernized registry. Formulation investment concentrates in Brazilian suppliers seeking streamlined import pathways and reduced occupational exposure compliance costs.
- Pre-mixed:Factory-blended grouts, repair mortars, and leveling compounds guarantee batch consistency for contractors lacking on-site quality control infrastructure.
- Dry Mortar:Cementitious powders with pre-dosed polymer modifiers require only water addition at point of use, simplifying logistics for remote construction sites.
Polymerization retains installed base dominance; bio-based formulations are gaining share fastest as regulatory chemistry compresses conventional formulation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's chemical substance registry overhaul anchors Brazil's regulatory framework for construction chemicals, reshaping import compliance costs across the continent's largest market. Argentina's IRAM standards and Chile's seismic-grade mandates create divergent certification requirements that fragment cross-border product portability. Procurement patterns concentrate in industrial corridors where infrastructure rehabilitation and extractive sector investment drive specification of high-performance admixtures.
Brazil
São Paulo state's megaproject pipeline mandates superplasticizer-dosed concrete for commercial high-rises and bridge decks. ANVISA's modernized registry imposes granular hazard classification on imported polymer additives, extending material qualification timelines for foreign suppliers. The southeast corridor spanning Rio de Janeiro and Minas Gerais concentrates demand for cement-compatible chemical blends serving infrastructure rehabilitation programs.
Argentina
Industrial corridor projects across Buenos Aires and Córdoba provinces specify IRAM-validated cement additives for petrochemical and mining facilities. The Secretariat of Industry enforces performance labeling standards that create cross-border friction for Brazilian suppliers seeking market entry. IRAM certification requirements lock in premium formulation demand for seismic-resistant concrete systems in public infrastructure tenders.
Chile
Mining investment revives specification of chemical-resistant grouts and epoxy mortars across the Atacama region. The Ministry of Housing and Urbanism mandates seismic-grade admixture certification for public infrastructure, filtering supplier participation through validated performance documentation. Santiago's commercial construction sector drives demand for crystalline waterproofing compounds protecting coastal concrete substrates from chloride ingress.
Colombia
Bogotá's infrastructure expansion programs accelerate procurement of concrete admixtures for tunnel lining and highway rehabilitation projects. National infrastructure agency requirements emphasize durability guarantees that shift testing burdens to chemical suppliers with captive laboratory capabilities. Antioquia's industrial clusters concentrate demand for tile adhesives and flooring systems serving commercial development.
Peru
Lima's coastal infrastructure faces accelerated specification of penetrating sealers and corrosion inhibitors addressing marine exposure conditions. Mining sector investment in the Andean highlands drives demand for high-strength concrete modifiers validated under national construction standards. Public-private partnership frameworks for transport infrastructure create bundled procurement opportunities for admixture suppliers with localized technical service presence.
South America Construction Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South America's construction chemicals market, with multinational chemical conglomerates and regional cement producers occupying distinct competitive positions. The upper tier combines captive polymer production with localized formulation capabilities, while mid-scale specialists compete through technical service density in specific sub-regions. Two strategic archetypes dominate: backward-integrated cement-chemical hybrids and imported-additive distributors rebuilding compliance infrastructure. Capacity expansion and regulatory certification acceleration represent the dominant competitive moves as suppliers adapt to ANVISA's documentation requirements.
Among European-based chemical conglomerates, Sika AG and BASF SE exemplify the integrated-leader archetype through localized production and technical center investments. Sika AG leverages its São Paulo technical center for admixture development targeting megaproject specifications, while BASF SE anchors regional supply through captive production at its Guarulhos complex. Votorantim Cimentos occupies a distinct position as a Brazil-based cement-chemical hybrid competing through backward integration into cement-compatible blends distributed via its construction materials network. These three entities represent contrasting strategic postures: foreign direct investment with localized R&D, captive manufacturing with regional supply security, and vertical integration leveraging downstream distribution control.
| Leading Market Players |
|---|
| Arkema |
| RPM International Inc |
| Sika AG |
| BASF SE |
| Henkel AG & Co KGaA |
| Saint-Gobain |
| CEMEX |
| Votorantim Cimentos |
| MAPEI S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Bio-based surfactant substitution for petroleum-derived polymers simultaneously redistributes raw material sourcing toward Brazilian agricultural processors and compresses formulation cost premiums previously commanded by imported synthetic additives under ANVISA's substance registry protocols.
Pricing Analysis
Price spreads between São Paulo and inland Brazilian states reach double-digit percentages due to Santos port logistics premiums and distributor markup layering. Three-tier pricing structure across premium, standard, and economy levels stratifies by ANVISA certification grade and seismic-grade validation status. Pricing pressure stems from performance-based procurement contracts transferring testing burdens to suppliers. Residential contractors in Brazil's northeast states exhibit highest price sensitivity, while Chilean mining operators accept premium tiers for seismic-certified formulations.
Supply Chain Analysis
Santos port congestion and container availability constraints on Asia-Brazil trade lanes elevate inbound logistics costs for specialty surfactants and polycarboxylate ether raw materials. Supply concentrates in Brazil, Germany, and China for polymer additives and surfactant intermediates. Raw material dependencies rest on acrylic monomers, naphthalene derivatives, and rapeseed oil feedstocks. Single-point vulnerability at Santos port creates structural risk for inland distributors serving Minas Gerais and São Paulo corridors. Distribution runs through construction materials networks anchored by cement producers and specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as ANVISA's registry overhaul and performance-based procurement fragment specification authority across contractors, engineers, and regional regulators, creating service and compliance niches for targeted entrants.
For Market Incumbents: Fortify technical service density in Brazil's southeast corridor where megaproject specifications concentrate. Expand captive testing infrastructure to absorb performance-guarantee risks from shifting procurement models. Deepen backward integration into bio-based surfactant supply to preempt ANVISA VOC threshold compliance cost escalation. For New Entrants and Emerging Players: Technical service gaps in Argentina's industrial corridor present accessible entry points where IRAM certification complexity deters smaller Brazilian suppliers. Target mid-size commercial builders in São Paulo state adopting platform-based procurement channels. Pursue direct-to-contractor digital distribution to bypass entrenched distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulators with captive laboratory infrastructure and multi-jurisdiction certification capabilities. Long-term viability hinges on regulatory chemistry adaptation capacity rather than commodity scale. Acquisition focus should center on Brazilian specialists with ANVISA submission expertise and localized technical teams. Monitor IRAM-ANVISA regulatory convergence negotiations as inflection signal for cross-border product portability economics.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Acceleration | Pre-approved polymer additive pathways reduce foreign supplier time-to-market against domestic competitors. |
| Backward Integration into Bio-based Feedstocks | Rapeseed-derived surfactant production secures streamlined import pathways under tightening VOC thresholds. |
| Technical Center Localization | São Paulo-based formulation development captures megaproject specifications requiring localized rheology support. |
| Platform-Based Distribution Partnership | Digital procurement channel access reaches mid-size contractors bypassing traditional distributor networks. |
| Seismic-Grade Certification Investment | Chile Ministry of Housing validation locks in premium positioning for mining and public infrastructure tenders. |
Research Methodology
A spread of perspectives from admixture formulators, ready-mix procurement managers, cement producer technical directors, and ANVISA regulatory consultants converged on the working assumptions shaping volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings of exposed chemical conglomerates, ANVISA substance registry documentation, and IRAM certification records. Bottom-up triangulation across product-grade consumption patterns and top-down cross-checks against cement production and construction output indices anchored the analytical framework.
Segmentation dimensions modeled include product type, application sector, end-user archetype, and technology platform across the projection horizon. CAGRs were derived from trend extrapolation of specification-grade adoption curves and regulatory-driven substitution elasticities. Forecast inputs incorporated petrochemical feedstock price volatility assumptions and infrastructure rehabilitation program commitment trajectories from national development bank disclosures.
Forecasts assume regulatory continuity in ANVISA's modernized registry and IRAM's cement additive standards; material policy shifts would require re-modeling of import compliance cost structures and cross-border product portability economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phenothiazine Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Sulfuric Acid Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Betaine Market
Chemicals
China Inorganic Iodide Market
Chemicals
Global Syringaldehyde Market
Chemicals
Sodium Azide Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Global Construction Chemical Market
Chemicals
Pyrogallol Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Cumene Market