
 Paint Remover Market | 2026-2036
Paint Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Remover Market Outlook
Modular packaging configurations are expanding buyer flexibility in the paint remover category. Henkel leverages its adhesive and surface chemistry heritage to sustain integrated stripper portfolios across professional and consumer channels. PPG Industries anchors industrial-grade removal systems through captive distribution to automotive refinish networks. Sherwin-Williams controls shelf positioning in North American retail through exclusive aerosol and bulk container formats.
Paint removers are formulated chemical systems designed to dissolve, soften, or mechanically lift cured coatings from substrates through solvent penetration, caustic saponification, enzymatic breakdown, or abrasive scouring action, typically operating within specific temperature ranges and dwell times to prevent substrate damage. Solvent-based formulations dominate volume in heavy industrial stripping where epoxy and polyurethane removal demands aggressive chemical action, though biochemical alternatives are capturing margin pools in furniture refinishing and heritage restoration segments where substrate preservation commands premium pricing. The construction end-user segment generates steady demand through infrastructure maintenance cycles, while DIY project applications are shifting toward smaller-format packaging as residential renovation activity channels buyers toward ready-to-use aerosol and bottle configurations.
EPA oversight of volatile organic compound emissions constrains solvent-based product formulations in the United States, while REACH chemical authorization requirements in Europe drive substitution toward caustic and biochemical alternatives. OSHA workplace exposure limits further shape industrial procurement standards for personal protective equipment compatibility and ventilation requirements. Stakeholders must monitor regulatory divergence between jurisdictions to align formulation portfolios with emerging compliance thresholds and anticipate where chemical restriction timelines will redirect demand toward next-generation stripping technologies.
Market Dynamics
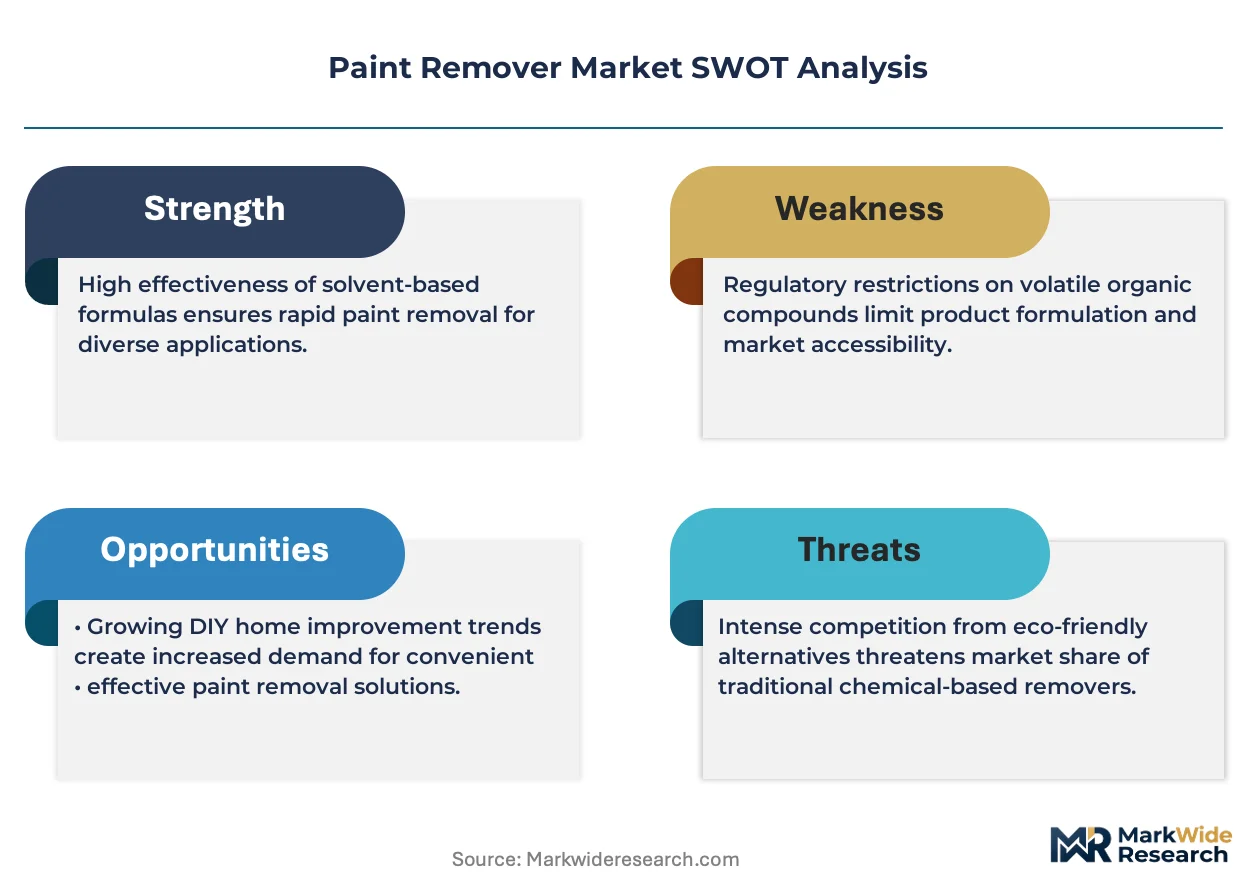
EPA solvent emission standards and REACH chemical authorization timelines are forcing simultaneous reformulation across North American and European supply chains, compressing product development cycles while opening margin pools for compliant alternatives.
Growth Catalysts
- Automotive refinishing demand:Collision repair networks in the United States are expanding throughput capacity as vehicle age extends coating maintenance cycles. EPA VOC regulations accelerate low-VOC stripper procurement.
- REACH chemical substitution:ECHA authorization requirements are redirecting industrial coating removal toward caustic-based and biochemical alternatives across German manufacturing clusters.
- Heritage restoration segment:Substrate-preserving enzymatic formulations capture premium pricing in furniture refinishing and architectural conservation where damage tolerance approaches zero.
Market Restraints
- Feedstock volatility:N-methyl-2-pyrrolidone and methylene chloride supply concentrates with Chinese petrochemical producers, exposing formulators to import tariff and shipping cost swings.
- Technical performance ceiling:Biochemical strippers face dwell-time and temperature limitations against catalyzed epoxy systems that demand aggressive solvent action.
- Regulatory fragmentation:Divergent OSHA workplace exposure limits and state-level chemical restriction timelines complicate national product line rationalization for North American suppliers.
Strategic Opportunities
- India industrial maintenance:BIS standards evolution and domestic manufacturing incentives under PLI schemes create entry pathways for compliant industrial-grade formulations.
- Aerosol convenience channel:Ready-to-use spray formats displace bulk chemical handling in residential renovation, capturing DIY buyers through home improvement retail.
- Enzyme-surfactant convergence:Formulation platforms combining proteolytic enzymes with biosurfactants open heritage restoration and precision electronics cleaning applications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in solvent-replacement chemistry and regulatory toxicology concentrates with aging technical workforces in Western Europe and the United States.
- Certification timeline compression:ECHA substance evaluation and EPA new chemical review periods extend 18-36 months, delaying commercialization of reformulated portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Remover Market |
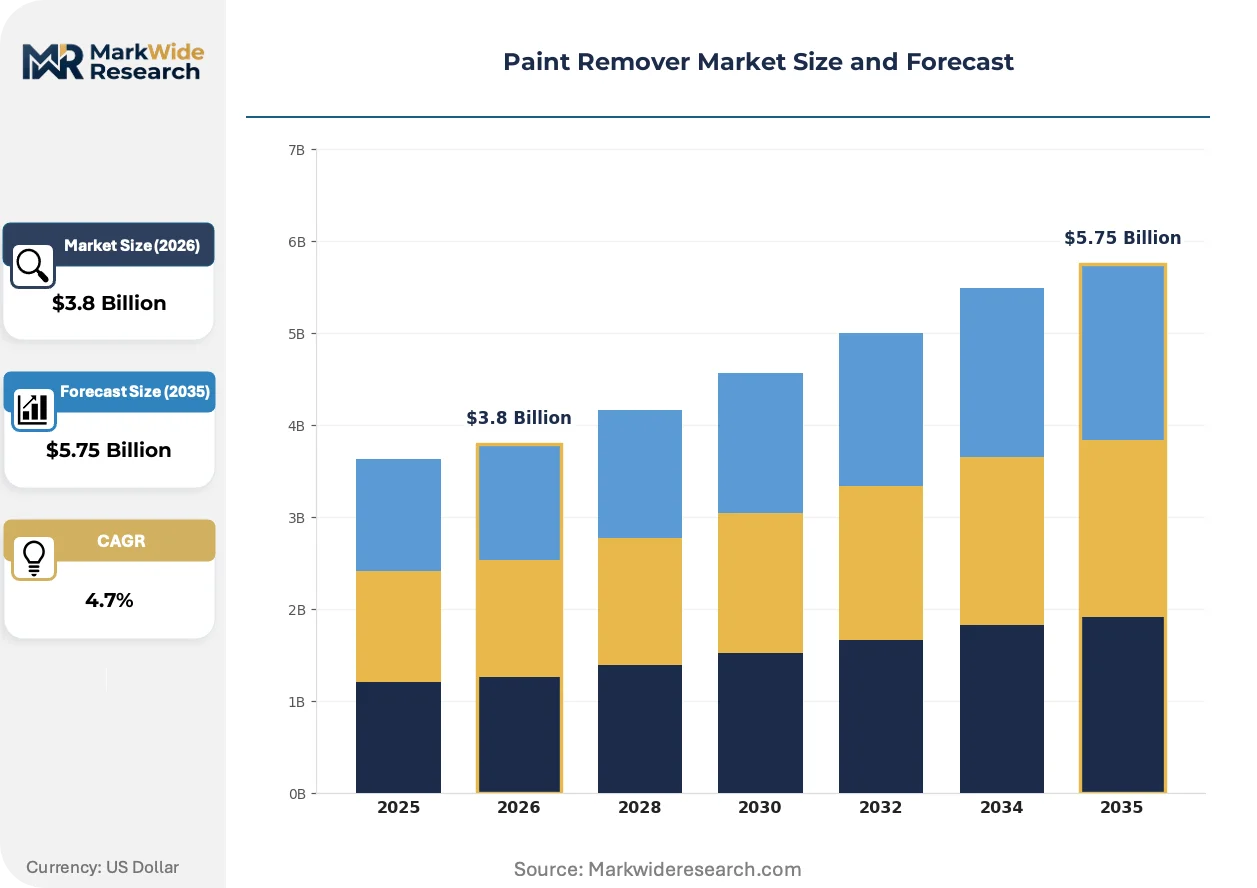
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Caustic-Based, Biochemical, Abrasive End User: Construction, Automotive Repair, Furniture Refinishing, Arts & Crafts Application: Residential Use, Industrial Use, Commercial Use, DIY Projects Packaging Type: Aerosol Cans, Tins, Bottles, Bulk Containers |
| Companies Covered | Henkel, RPM International, 3M, United Gilsonite Laboratories, Franmar Chemical, PPG Industries, Sherwin-Williams, Fiberlock Technologies, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Remover Market Strategic Shifts
Active ingredient platforms and delivery systems are diverging sharply between heavy industrial and precision restoration applications, with regulatory pressure acting as the primary sorting mechanism.
Biochemical stripping systems combining engineered enzymes with low-toxicity cosolvents are modularizing application protocols across furniture refinishing and heritage conservation segments. Master craftsmen and architectural conservators in Italy and France adopt these systems for gilded surface and veneered substrate work. The technology is modularizing service offerings by separating coating removal from substrate conditioning into discrete, billable process steps.
REACH authorization timelines and EPA risk evaluation mandates are compressing the commercial lifespan of methylene chloride and NMP-based formulations. Industrial buyers in Germany and the Netherlands face mandatory substitution planning for authorized substances. Automotive refinishing networks are responding by qualifying caustic paste and benzyl alcohol alternatives ahead of regulatory deadlines.
Project-scale purchasing is fragmenting as residential renovation buyers favor single-use aerosol and trigger-spray formats over bulk container procurement. Home improvement retail channels in the United States and United Kingdom expand shelf space for ready-to-use configurations. The shift compresses average transaction values while expanding addressable household penetration for maintenance-grade products.
Paint Remover Market Segmentation
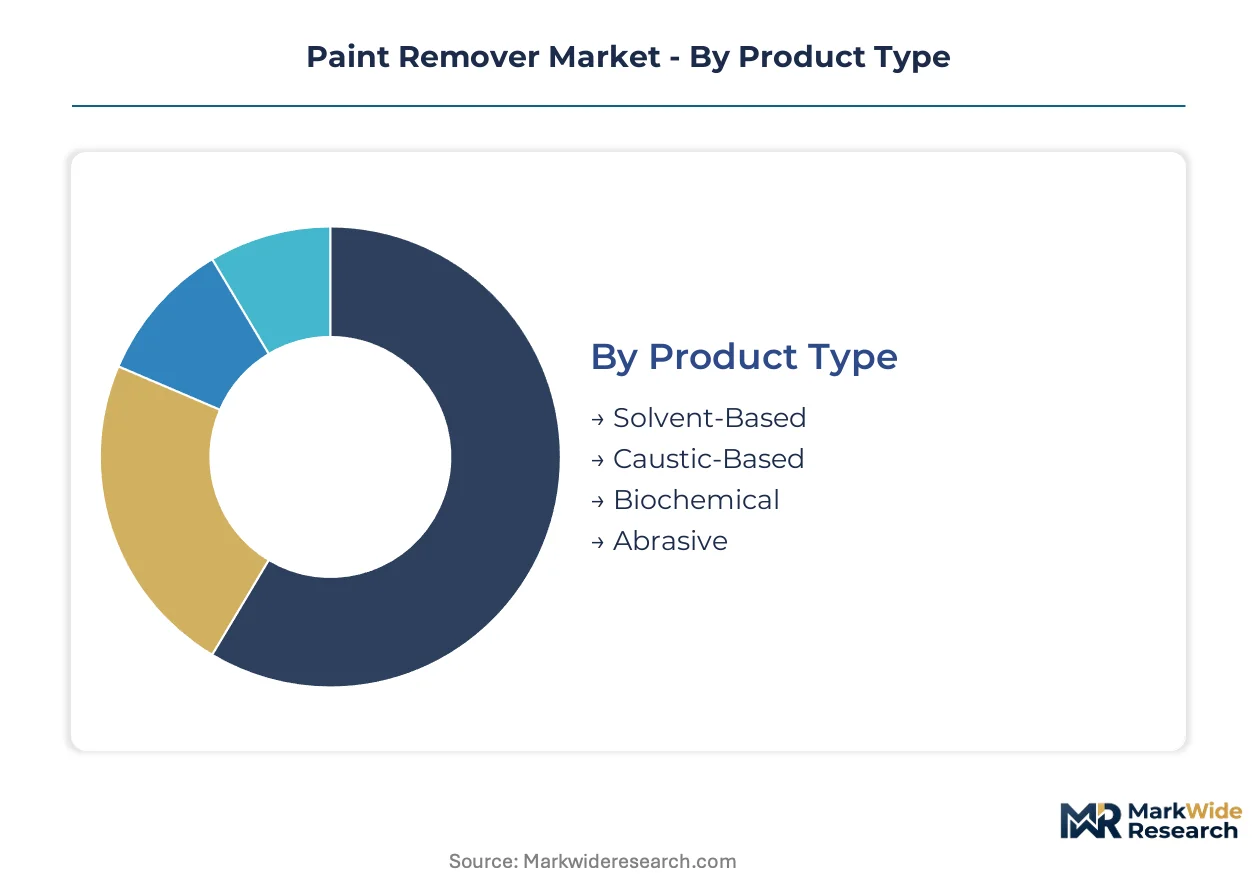
Formulation chemistry and packaging configuration determine margin capture across distinct use environments. Segmentation in this market separates high-volume industrial procurement from premium-priced precision applications where substrate preservation commands technical specification premiums.
Product Type:
Formulation platforms diverge sharply between aggressive industrial stripping and precision restoration where substrate damage tolerance approaches zero.
- Solvent-Based:N-methyl-2-pyrrolidone and methylene chloride formulations penetrate catalyzed epoxy and polyurethane systems through aggressive chemical action. Demand concentrates in United States automotive refinishing networks where EPA VOC regulations are accelerating procurement shifts toward compliant alternatives ahead of emission standard deadlines.
- Biochemical:Engineered enzyme systems combined with low-toxicity cosolvents modularize application protocols for furniture refinishing and heritage conservation. Master craftsmen in Italy and France adopt these platforms for gilded surface work where damage tolerance approaches zero and premium pricing reflects substrate preservation value.
- Caustic-Based:Saponification chemistry dominates German manufacturing clusters under REACH authorization timelines that redirect industrial coating removal from restricted solvents.
- Abrasive:Mechanical scouring systems serve heavy infrastructure maintenance where chemical residue prohibition excludes solvent or caustic alternatives.
Solvent-Based leads on scale; Biochemical leads on momentum.
End User:
Procurement patterns separate project-scale industrial buyers from residential consumers prioritizing convenience over unit economics.
- Automotive Repair:Collision repair networks in the United States extend throughput capacity as vehicle age expands coating maintenance cycles. EPA solvent emission standards compress product qualification timelines while opening margin pools for low-VOC alternatives.
- Construction:Infrastructure maintenance cycles generate steady demand through bridge, pipeline, and industrial facility recoating programs where specification compliance determines contractor eligibility.
- Furniture Refinishing:Heritage restoration specialists in France and Italy specify enzymatic systems for veneered substrate and gilded surface work.
- Arts & Crafts:Hobbyist buyers favor small-format retail configurations through home improvement channels.
Construction anchors volume procurement; Automotive Repair shows steepest regulatory-driven substitution activity.
Application:
Use environment dictates packaging format, dwell time tolerance, and technical performance thresholds.
- Industrial Use:Heavy stripping operations in German manufacturing clusters demand aggressive chemical action against catalyzed coating systems. REACH authorization requirements compress commercial lifespan of legacy formulations while accelerating qualification of caustic paste and benzyl alcohol alternatives.
- DIY Projects:Residential renovation buyers in the United States and United Kingdom shift procurement toward single-use aerosol and trigger-spray formats. Home improvement retail expands shelf space for ready-to-use configurations that displace bulk chemical handling.
- Residential Use:Maintenance-grade applications favor bottle and tin configurations for controlled application on architectural surfaces.
- Commercial Use:Contractor procurement balances unit economics against transport and storage efficiency for multi-site deployment.
Industrial Use commands specification premiums; DIY Projects expand addressable household penetration fastest.
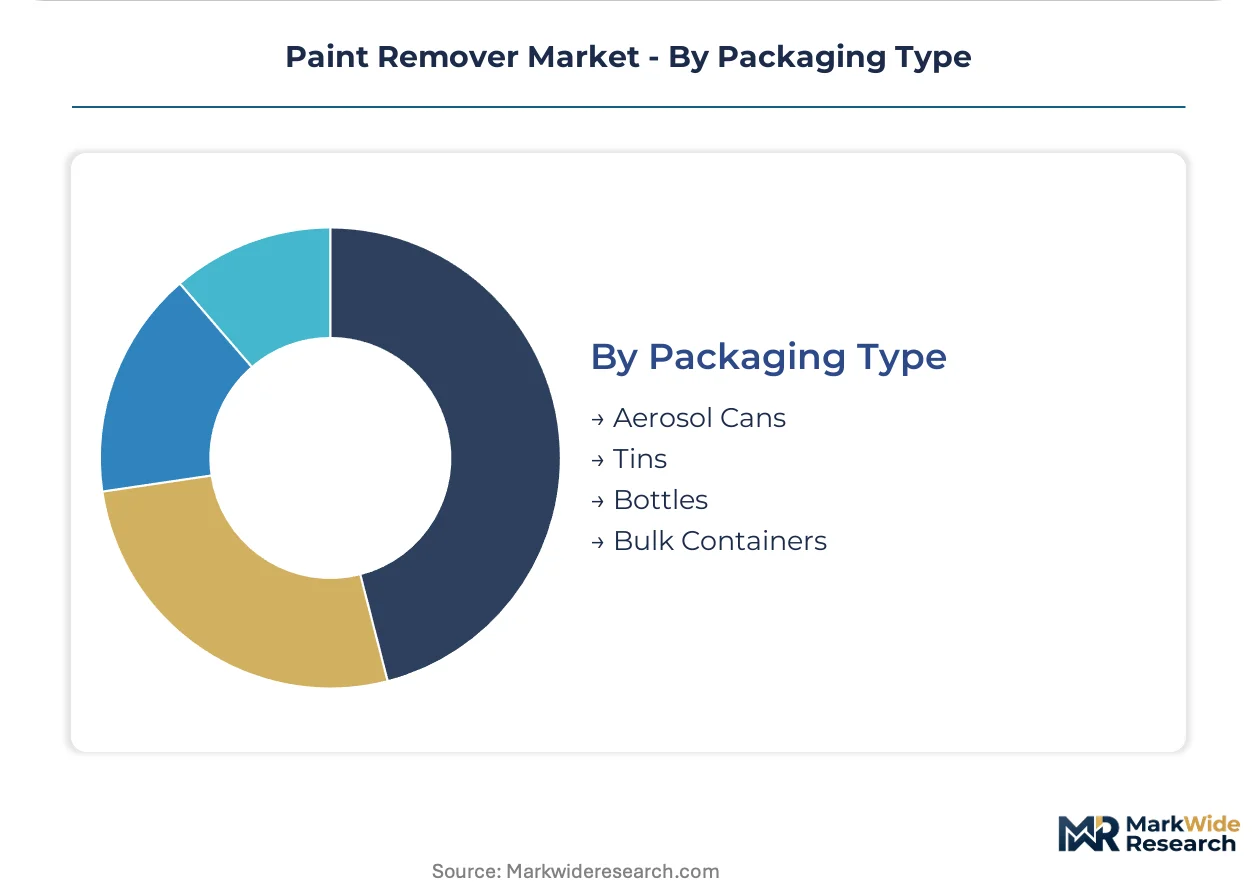
Packaging Type:
Container configuration directly determines channel placement and buyer accessibility across professional and consumer segments.
- Aerosol Cans:Ready-to-use spray formats capture residential renovation buyers through United States and United Kingdom home improvement retail. The shift compresses average transaction values while eliminating bulk chemical handling barriers for occasional-use consumers.
- Bulk Containers:Industrial buyers in German automotive refinishing networks optimize per-unit economics through volume procurement of caustic paste alternatives.
- Bottles:Trigger-spray and pour configurations serve maintenance-grade residential and commercial applications.
- Tins:Traditional metal containers retain position in professional refinishing channels for brush-applied paste formulations.
Bulk Containers dominate industrial procurement value; Aerosol Cans gain share fastest in consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paint remover chemistry scaled through German industrial clusters during the post-war reconstruction era, with solvent-based formulations dominating heavy manufacturing maintenance across the Ruhr Valley before environmental regulations forced geographic diversification of production and reformulation expertise.
United States
Automotive refinishing networks in Michigan, Ohio, and Texas extend throughput capacity as vehicle age expands coating maintenance cycles. EPA VOC emission standards compress product qualification timelines while accelerating procurement shifts toward low-VOC alternatives ahead of regulatory deadlines. Collision repair clusters in the Detroit metropolitan area qualify caustic paste and benzyl alcohol substitutes.
Germany
Industrial coating removal operations in North Rhine-Westphalia and Bavaria face mandatory substitution planning under ECHA REACH authorization timelines. Caustic-based saponification chemistry captures share from restricted solvent formulations across automotive manufacturing clusters. Stuttgart and Wolfsburg refinishing operations redirect procurement toward compliant alternatives ahead of chemical restriction deadlines.
China
Domestic manufacturing incentives and evolving GB standards create entry pathways for industrial-grade formulation suppliers serving infrastructure maintenance programs. N-methyl-2-pyrrolidone and methylene chloride feedstock supply concentrates with petrochemical producers in the Yangtze River Delta. Shanghai and Ningbo industrial zones expose formulators to import tariff and shipping cost volatility.
India
BIS standards evolution and PLI scheme incentives attract compliant industrial-grade formulation investment for domestic manufacturing maintenance. Construction and automotive refinishing demand concentrates in Maharashtra and Gujarat industrial corridors. Mumbai and Ahmedabad coating removal operations shift procurement toward specification-compliant products as certification requirements tighten.
France
Heritage restoration specialists in Paris and Lyon specify enzymatic systems for gilded surface and veneered substrate work where damage tolerance approaches zero. Architectural conservators adopt biochemical platforms that modularize coating removal from substrate conditioning. Île-de-France restoration workshops capture premium pricing through substrate preservation capabilities.
Paint Remover Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation chemistry sophistication and regulatory compliance certification. The vendor base separates into three tiers: integrated chemical conglomerates with adhesive and surface chemistry heritage, specialized coating companies with captive distribution to automotive refinish networks, and regional formulators serving price-sensitive industrial maintenance segments. Dominant competitive moves include portfolio diversification into low-VOC and biochemical alternatives and geographic expansion through home improvement retail shelf positioning.
Among integrated chemical conglomerates, Henkel and PPG Industries exemplify archetypes with adhesive and surface chemistry heritage and captive distribution to automotive refinish networks respectively. Sherwin-Williams occupies a position controlling North American retail shelf space through exclusive aerosol and bulk container formats. These three companies anchor tiered competitive positioning across professional and consumer channels.
| Leading Market Players |
|---|
| Henkel |
| RPM International |
| 3M |
| United Gilsonite Laboratories |
| Franmar Chemical |
| PPG Industries |
| Sherwin-Williams |
| Fiberlock Technologies |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
REACH authorization timelines and EPA solvent emission standards gate qualified supply access and premium-tier pricing power for compliant formulation portfolios. Buyers in Germany and the United States face compressed procurement timelines that reward suppliers with pre-qualified low-VOC and biochemical alternatives, while non-compliant producers absorb margin erosion through channel exclusion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage restoration enzymatic systems from industrial caustic pastes and commodity solvent-based strippers. Price differentiation rests on certification grade for REACH and EPA compliance plus volume scale for automotive refinish network procurement. Cost compression in solvent-based tiers is intensifying because feedstock volatility from Chinese N-methyl-2-pyrrolidone suppliers exposes margin structures. DIY residential buyers show highest price sensitivity through aerosol format purchasing, while architectural conservators in France absorb premium pricing for substrate-preserving enzymatic systems.
Supply Chain Analysis
Formulation chemist scarcity in Western Europe and the United States concentrates technical expertise with aging workforces in Stuttgart and Michigan industrial clusters. Raw material supply draws from Chinese petrochemical producers for methylene chloride and N-methyl-2-pyrrolidone, German specialty chemical manufacturers for caustic saponification agents, and French biotech suppliers for engineered enzymes. Single-source vulnerability in Chinese feedstock exposes formulators to import tariff and shipping cost swings. Distribution runs through captive automotive refinish networks for industrial buyers and home improvement retail for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paint remover market reads as a late-cycle quality story where automotive refinishing networks and heritage restoration specialists redirect procurement toward premium specifications that satisfy tightening EPA and REACH compliance thresholds.
For Market Incumbents: Extend low-VOC and biochemical formulation portfolios ahead of regulatory deadlines to preempt channel displacement from emerging specialty chemical entrants. Invest in REACH and EPA pre-certification to lock automotive refinish network specifications. Backward integration into enzyme supply partnerships with French biotech suppliers secures margin capture in heritage restoration segments.
For New Entrants and Emerging Players: Capture white-space in Indian industrial maintenance corridors where BIS standards evolution and PLI scheme incentives create entry pathways for compliant formulations. Target Maharashtra and Gujarat automotive refinishing clusters with specification-compliant caustic paste alternatives. Lead with technical service bundling that addresses formulation chemist scarcity among local distributors.
For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with captive distribution to automotive refinish networks because certification timeline compression and regulatory fragmentation favor scaled compliance infrastructure over fragmented local players. Target mid-cap specialists with REACH-authorized portfolios and established automotive OEM relationships. Watch ECHA substance evaluation acceleration as the inflection signal for substitution-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Supply | Captures margin in biochemical heritage restoration formulations where French biotech suppliers command premium positioning. |
| REACH Pre-Certification Investment | Locks German automotive manufacturing cluster procurement ahead of ECHA authorization deadline compression. |
| Aerosol Format Channel Expansion | Penetrates United States and United Kingdom home improvement retail where DIY buyers displace bulk chemical handling. |
| Joint Venture in Indian Industrial Corridors | Addresses BIS standards evolution and PLI scheme incentives in Maharashtra and Gujarat maintenance markets. |
| Long-Term Supply Agreement with Petrochemical Feedstock Producers | Hedges Chinese N-methyl-2-pyrrolidone and methylene chloride import tariff and shipping cost volatility exposure. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant managers at automotive refinishing networks, procurement leads at German manufacturing clusters, distribution channel partners in home improvement retail, and technical R&D directors at specialty chemical formulators. Secondary validation draws from EPA regulatory filings, ECHA authorization databases, customs and trade data for N-methyl-2-pyrrolidone and methylene chloride flows, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across formulation chemistry segments.
Rate-of-change decomposition separates volume growth from pricing dynamics and mix shift toward compliant alternatives across the analysis window. Segmentation dimensions include formulation chemistry platform, end-use industry vertical, packaging configuration, and regional regulatory cluster. CAGRs derive from regression analysis of historical substitution patterns and regulatory timeline impacts. Industry-specific forecast inputs incorporate ECHA substance evaluation schedules and EPA risk evaluation mandates.
Feedstock supply disruption, regulatory timeline acceleration, and formulation chemist attrition are the dominant revision risks that could compress or extend substitution trajectories. Forecasts reflect documented assumptions on REACH authorization enforcement consistency and EPA VOC standard implementation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Amine Oxide Market
Chemicals
North America Methanol Market
Chemicals
Acetic Ether Market
Chemicals
Malonic Acid Market
Chemicals
Glyoxylic Acid Market
Chemicals
Pentanedione Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Guaiacol Market
Chemicals
Benzhydrol Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Carbon Tetrabromide Market