
 Trimethylamine Market | 2026-2036
Trimethylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Trimethylamine Market Outlook
Long-term supply contracts with embedded price-adjustment clauses is repositioning how trimethylamine gets monetized, shifting value capture from spot transactions to predictable recurring revenue. BASF SE leverages its integrated methanol-to-amines platform to sustain cost leadership across European supply corridors. Alkyl Amines Chemicals Ltd. anchors its position through dedicated capacity serving India's pharmaceutical and agrochemical sectors. Mitsubishi Gas Chemical Company, Inc. dominates the high-purity reagent-grade segment through proprietary distillation technology.
Trimethylamine is a tertiary aliphatic amine with the formula N(CH₃)₃, typically produced via catalytic vapor-phase methanol-ammonia reaction over silica-alumina catalysts at elevated temperature and pressure, and it functions primarily as a chemical intermediate for choline chloride, quaternary ammonium compounds, and flotation reagents. Industrial grade commands the largest volume share due to bulk consumption in water treatment and polymer catalysts, while pharmaceutical grade captures the deepest margin pool as regulatory filing requirements restrict qualified supplier counts. The animal feed use case is expanding fastest as livestock producers substitute synthetic choline for natural sources to standardize nutrient profiles.
EPA oversight under the Toxic Substances Control Act shapes manufacturing facility permitting and emissions controls for US producers, while REACH registration mandates in Europe dictate substance dossier completeness for import and production volumes above one tonne annually. China's MEE enforces wastewater discharge standards that affect amine plant operating economics in the Yangtze River basin. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries are altering competitive positioning in cross-border trade flows.
Market Dynamics
Long-term supply contracts with embedded price-adjustment clauses are consolidating procurement power among large animal feed compounders, compressing spot market liquidity and favoring integrated methanol-amine producers with captive raw material access.
Growth Catalysts
- EPA emissions standards:Tighter Toxic Substances Control Act enforcement is accelerating facility upgrades that favor larger producers with capital reserves, concentrating compliant supply among integrated chemical manufacturers.
- Choline chloride demand:Livestock producers in China and India are standardizing synthetic choline inclusion rates in poultry and swine rations, creating predictable offtake volumes for trimethylamine derivatives.
- Silica-alumina catalyst advances:Improved vapor-phase methanol-ammonia reaction selectivity is lifting yields above legacy fixed-bed designs, lowering unit costs for industrial-grade material.
Market Restraints
- Methanol price volatility:Natural gas feedstock swings and Chinese coal-to-methanol capacity fluctuations transmit directly to trimethylamine cost structures, squeezing margin predictability for non-integrated producers.
- Yangtze River basin concentration:Over half of global merchant capacity sits within China's MEE wastewater enforcement zone, exposing supply chains to unilateral environmental shutdowns.
- Dimethylethanolamine substitution:Water treatment formulators are piloting quaternary ammonium alternatives with lower odor profiles, threatening industrial-grade volume in municipal applications.
Strategic Opportunities
- Pharmaceutical-grade qualification:REACH dossier completeness and FDA Type II Drug Master File pathways restrict qualified supplier counts, creating margin expansion for producers with regulatory filing capabilities.
- Flotation reagent expansion:Copper and molybdenum mining operations in Chile and Peru are increasing quaternary ammonium collector usage as ore grades decline, opening South American demand channels.
- EU Green Deal chemistry:Bio-based methanol certification pathways under the Renewable Energy Directive are enabling premium positioning for low-carbon trimethylamine in European personal care applications.
Industry Challenges
- Process safety engineering scarcity:Specialized expertise in high-pressure amine reactor design and HAZOP management is concentrated among retiring cohorts, constraining brownfield expansion timelines.
- REACH-only representative complexity:Non-European producers face extended substance dossier preparation timelines and legal entity registration costs, delaying market entry.
- Legacy distributed control system integration:Continuous vapor-phase reactors require real-time temperature and pressure monitoring that conflicts with analog instrumentation at older methanol-amine facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimethylamine Market |
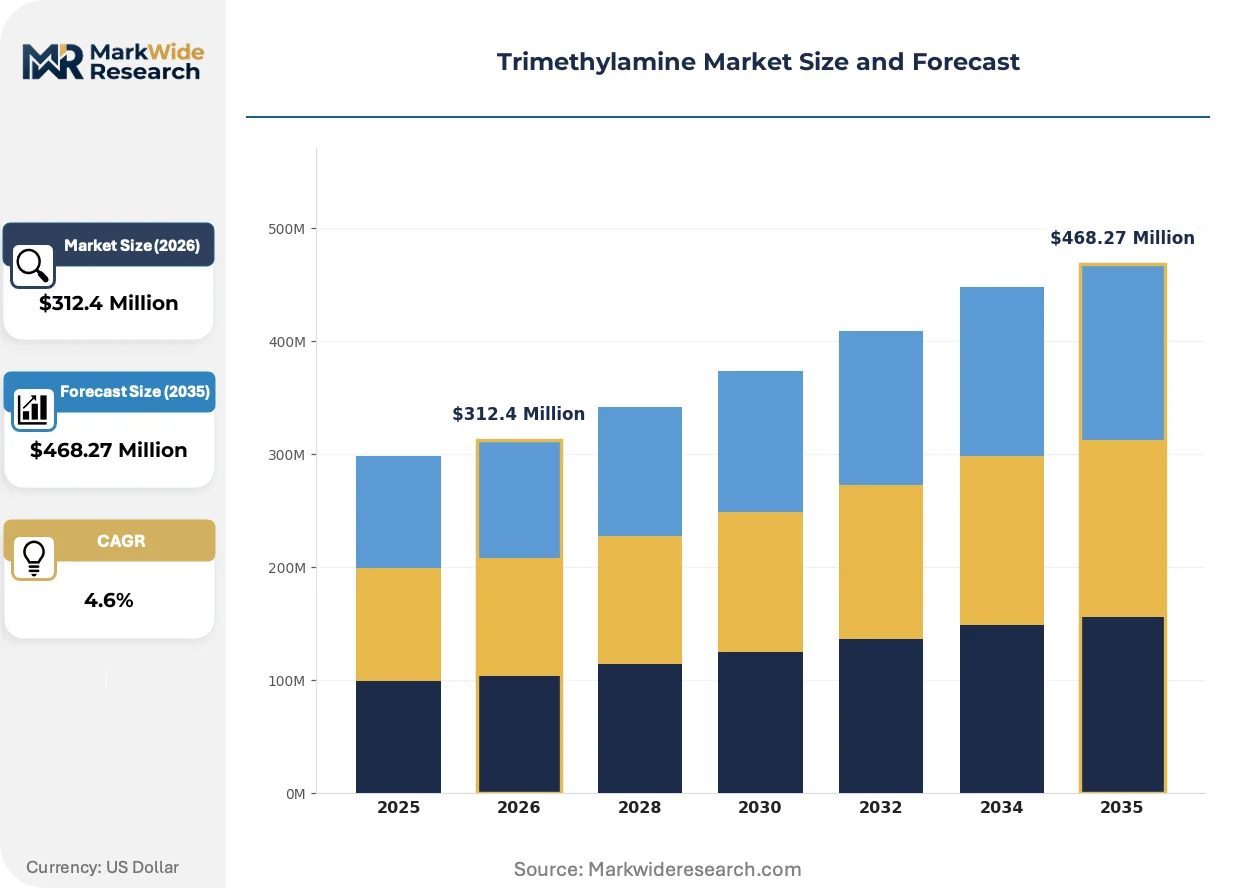
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $468.27 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Food Grade, Pharmaceutical Grade Use Case: Agriculture, Animal Feed, Chemicals, Pharmaceuticals End User: Agricultural Producers, Chemical Manufacturers, Pharmaceutical Companies, Food Industry Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Mitsubishi Gas Chemical Company, Inc., Alkyl Amines Chemicals Ltd., BASF SE, The Chemours Company, DuPont, Celanese Corporation, Balaji Amines Ltd., LOTTE Fine Chemical Co., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimethylamine Market Strategic Shifts
Membrane separation technology and predictive maintenance analytics are converging to reshape how trimethylamine purity grades are produced and certified, compressing the gap between industrial and pharmaceutical specifications.
Membrane pervaporation systems for water-amine separation are rewriting the economics of high-purity production. Pharmaceutical-grade buyers in Germany and Switzerland are qualifying membrane-refined material for quaternary ammonium synthesis, reducing reliance on energy-intensive azeotropic distillation. This technology is compressing capital requirements for grade-crossover, enabling mid-scale producers to contest reagent markets previously locked by proprietary distillation expertise.
REACH registration mandates under the EU's CLP Regulation are tightening substance dossier completeness requirements for import volumes above one tonne annually. Industrial-grade importers are consolidating supply relationships to reduce registration cost burdens per supplier, favoring larger European distributors with existing substance portfolios. Specialty chemical formulators in France and the Netherlands are responding by qualifying fewer, larger suppliers with full dossier coverage.
Livestock integrators are consolidating feed additive procurement through central purchasing cooperatives, unbundling traditional distributor markups. Poultry producers in China's Shandong and Henan provinces are negotiating direct choline chloride supply agreements with methanol-amine producers, bypassing regional chemical traders. This channel compression is most visible in bulk industrial-grade transactions where specification standardization enables direct matching.
Trimethylamine Market Segmentation
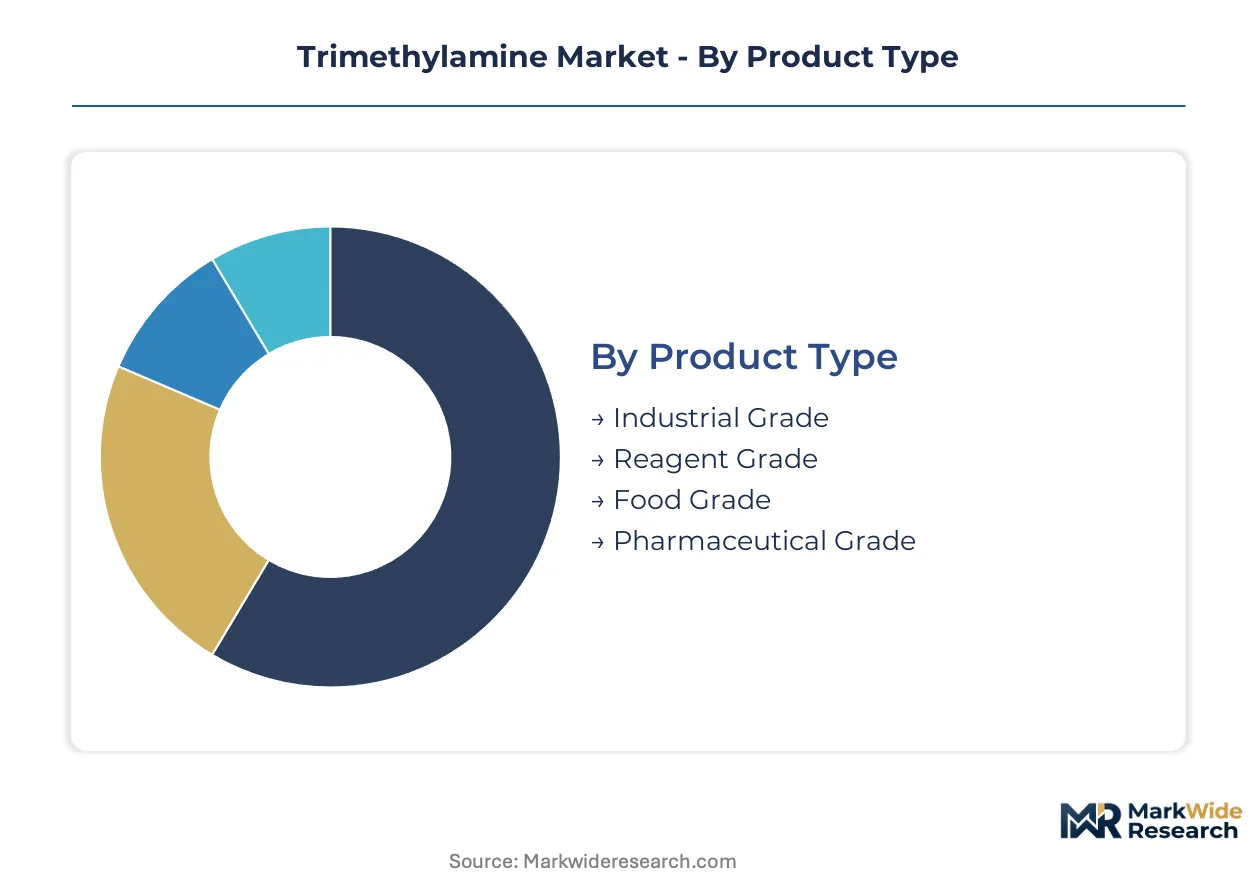
Trimethylamine segmentation reflects divergent purity requirements and regulatory exposure across derivative value chains. Specification tiers separate bulk industrial applications from filing-intensive pharmaceutical pathways.
Product Type:
Purity thresholds distinguish segments by contaminant limits and certification burden.
- Industrial Grade:Material with 70-99% purity serves water treatment polymerization and flotation reagent synthesis. Demand concentrates in China's Yangtze River basin chemical clusters where MEE wastewater standards shape plant operating economics.
- Reagent Grade:High-purity material meeting ACS specifications supports analytical chemistry and quaternary ammonium research. German and Swiss laboratory suppliers qualify membrane-refined sources, displacing legacy azeotropic distillation supply.
- Food Grade:Certified material for choline chloride feed additives complies with FDA food additive regulations and EFSA feed hygiene standards.
- Pharmaceutical Grade:USP/EP-compliant material requires FDA Type II Drug Master Files and REACH dossier completeness, restricting qualified supplier counts.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Use Case:
Application economics separate commodity derivative volumes from specialty chemical margins.
- Agriculture:Choline chloride for crop stress tolerance formulations drives seasonal procurement patterns tied to planting cycles in Brazil and Argentina.
- Animal Feed:Synthetic choline standardization in poultry and swine rations creates predictable offtake from Shandong and Henan province integrators.
- Chemicals:Quaternary ammonium compounds for biocides and phase transfer catalysis consume industrial-grade volumes in bulk.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and counterion chemistry demand reagent-grade material with batch-level documentation.
Volume leadership belongs to Chemicals. Steepest expansion trajectory is visible in Animal Feed.
End User:
Procurement sophistication varies by technical capability and regulatory filing requirements.
- Agricultural Producers:Large livestock integrators negotiate direct supply agreements, compressing traditional distributor markups.
- Chemical Manufacturers:Integrated methanol-amine producers with captive trimethylamine supply dominate bulk derivative production.
- Pharmaceutical Companies:Multinational drug manufacturers enforce supplier qualification protocols that exclude non-dossier-complete sources.
- Food Industry:Feed additive compounders require FAMI-QS certification and traceability documentation for choline chloride inclusion.
Contract consolidation is most advanced among Agricultural Producers. Qualification barriers are highest for Pharmaceutical Companies.
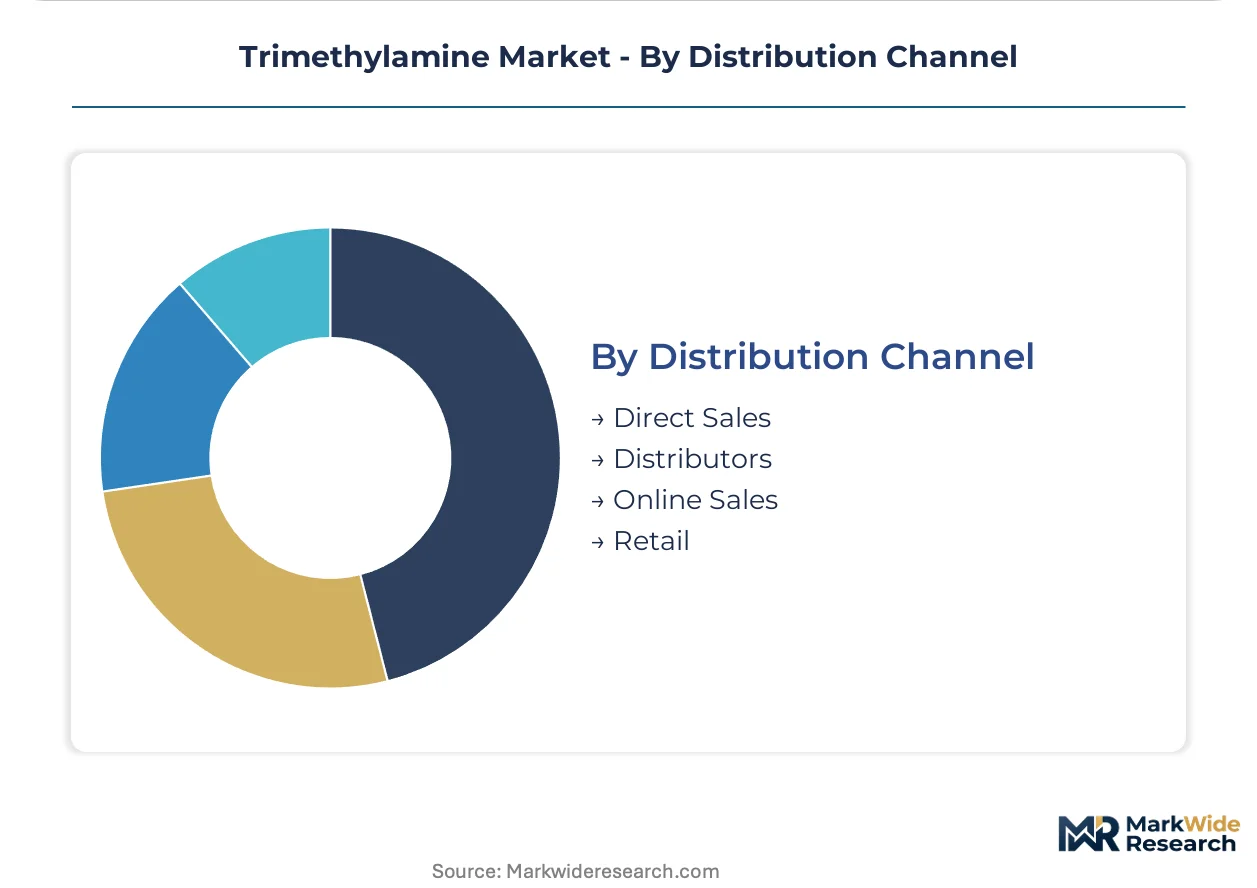
Distribution Channel:
Channel selection tracks shipment scale and technical service requirements.
- Direct Sales:Bulk industrial-grade contracts with embedded price-adjustment clauses bypass intermediary margins.
- Distributors:Regional chemical traders with REACH-only representative capabilities serve smaller European formulators.
- Online Sales:Reagent-grade material moves through laboratory supply platforms with certificate-of-analysis download functionality.
- Retail:Limited to specialty hobbyist and educational applications with minimal commercial significance.
Direct Sales commands the largest value flow. Distributors retain relevance where regulatory representation is required.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of industrial-grade material while consuming the majority for choline chloride derivatives. Germany and the United States import high-purity grades for pharmaceutical and specialty chemical applications. India is expanding captive capacity to serve its agrochemical sector.
China
Livestock integrators in Shandong and Henan provinces negotiate direct choline chloride supply agreements with methanol-amine producers. MEE wastewater discharge standards in the Yangtze River basin force operating adjustments at merchant plants. Chemical clusters in Jiangsu province concentrate over half of global merchant capacity.
Germany
Pharmaceutical-grade buyers in Germany and Switzerland qualify membrane-refined material for quaternary ammonium synthesis. REACH dossier completeness mandates under CLP Regulation restrict qualified supplier counts for import volumes above one tonne. The Rhine-Ruhr industrial corridor hosts distributors with existing substance portfolios covering industrial-grade offtake.
United States
EPA Toxic Substances Control Act enforcement accelerates facility upgrades that favor larger producers with capital reserves. FDA Type II Drug Master File requirements constrain qualified pharmaceutical-grade sources. Gulf Coast petrochemical complexes leverage integrated methanol supply for cost-competitive derivative production.
India
Agrochemical formulators expand captive trimethylamine consumption for quaternary ammonium biocide production. BIS quality standards and CDSCO filing requirements shape import substitution strategies. Gujarat and Maharashtra chemical parks anchor domestic capacity serving pharmaceutical and agricultural sectors.
Japan
Specialty chemical manufacturers import high-purity grades for electronic materials and phase transfer catalysis. METI chemical management policies and JIS standards govern substance handling protocols. Osaka-Kobe industrial zone maintains demand for reagent-grade material in analytical chemistry applications.
Trimethylamine Market Competitive Environment
Capital-heavy producers compete with asset-light formulators for margin capture in trimethylamine derivatives. The vendor base separates into three tiers: integrated petrochemical majors with captive methanol supply, regional amine specialists with dedicated derivative capacity, and merchant distributors with regulatory representation capabilities. Strategic moves concentrate on long-term supply contracting with embedded price-adjustment clauses and membrane technology licensing for grade-crossover.
Within the integrated petrochemical tier, BASF SE and Mitsubishi Gas Chemical Company, Inc. exemplify scale-driven positioning through methanol-to-amines platform control. Alkyl Amines Chemicals Ltd. represents the regional specialist archetype with India-focused capacity. These three entities occupy positions that span industrial-grade volume leadership and pharmaceutical-grade qualification barriers.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical Company, Inc. |
| Alkyl Amines Chemicals Ltd. |
| BASF SE |
| The Chemours Company |
| DuPont |
| Celanese Corporation |
| Balaji Amines Ltd. |
| LOTTE Fine Chemical Co. |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Livestock integrator procurement consolidation in China's Shandong and Henan provinces forces merchant producers toward long-term offtake contracts with embedded price-adjustment clauses, compressing spot market liquidity and anchoring industrial-grade pricing to methanol feedstock indices.
Pricing Analysis
Margin tightening in industrial-grade material reflects methanol feedstock volatility transmitted through non-integrated producers lacking captive natural gas or coal-to-methanol supply. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades separates qualified suppliers with REACH dossier completeness from commodity merchants. Cost-down pressure on industrial-grade volumes accelerates because water treatment formulators pilot dimethylethanolamine substitutes. Agricultural producers demonstrate highest price sensitivity through central purchasing cooperative leverage, while pharmaceutical companies accept premium positioning for USP/EP-certified material with batch documentation.
Supply Chain Analysis
Specialized expertise scarcity in high-pressure amine reactor design and HAZOP management constrains brownfield expansion timelines across Jiangsu province chemical clusters. Supply concentrates in China, Germany, and India, with over half of global merchant capacity sitting within China's MEE wastewater enforcement zone. Raw material dependencies draw from natural gas, coal-derived methanol, and ammonia feedstocks. Single-source vulnerability runs through Yangtze River basin environmental shutdown exposure. Distribution runs through direct bulk contracts for industrial-grade volumes and REACH-only representative distributors serving smaller European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
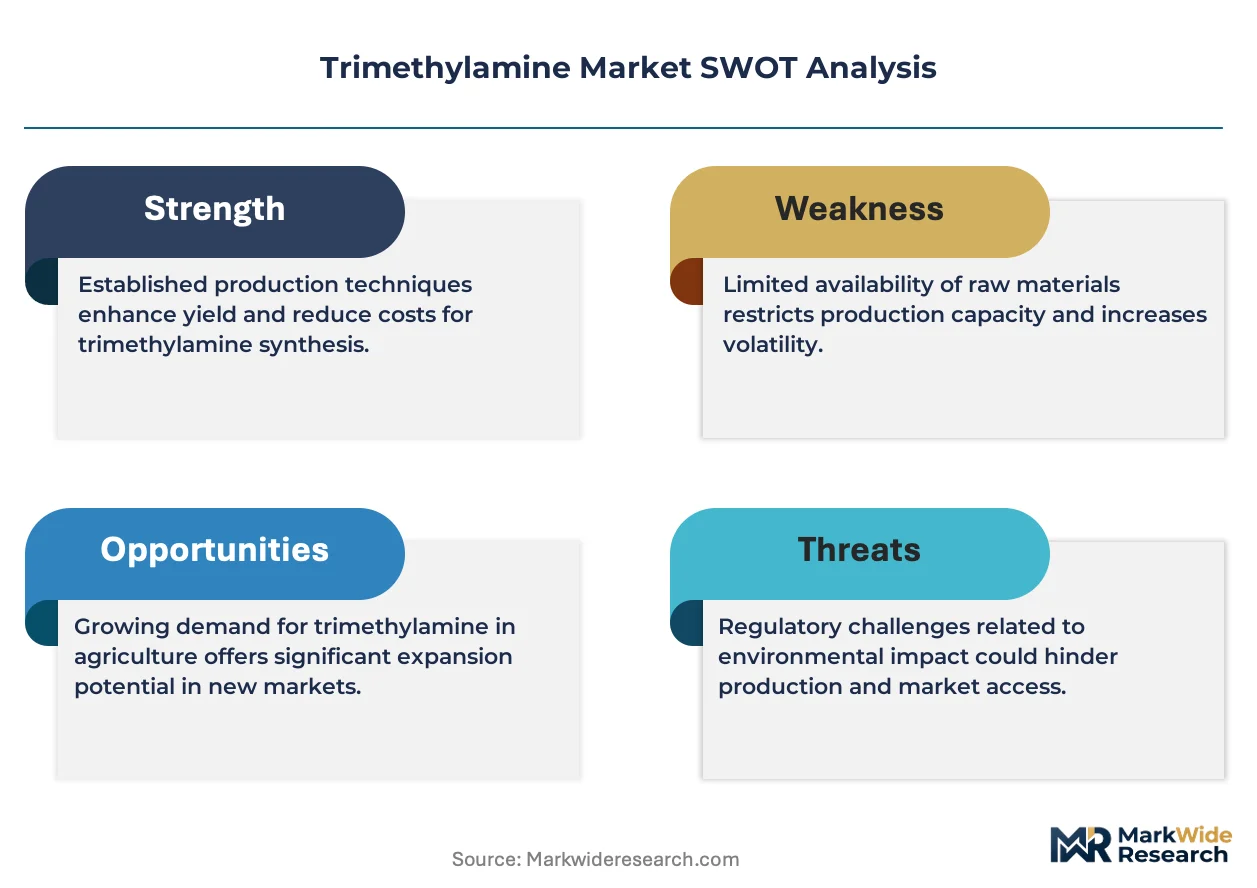
This market reads as supply-constrained through process safety engineering scarcity, with retiring cohort expertise propping pricing for qualified producers against unqualified expansion attempts.
For Market Incumbents: Hedge methanol feedstock exposure through backward integration into coal-to-methanol or natural gas supply in named geographies with stable energy policy. Defend pharmaceutical-grade margin position by accelerating membrane separation technology licensing to mid-scale competitors, preventing their independent qualification for reagent markets. Prioritize long-term supply agreements with embedded price-adjustment clauses over spot market participation as livestock integrator consolidation compresses distributor markups. For New Entrants and Emerging Players: Begin with pharmaceutical-grade qualification targeting German and Swiss laboratory suppliers displacing legacy azeotropic distillation sources. The most penetrable white-space sits in membrane-refined reagent-grade material for quaternary ammonium research applications. Pursue FAMI-QS certification for feed additive channel access, bypassing industrial-grade commodity competition concentrated in China's Yangtze River basin. For Investors and Strategic Acquirers: The window for entry favors regional amine specialists with dedicated derivative capacity and existing REACH dossier completeness. Long-term viability centers on producers with regulatory filing capabilities restricting qualified supplier counts in pharmaceutical-grade segments. Watch membrane separation technology adoption rates as the inflection signal for grade-crossover economics enabling mid-scale producer market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Captive feedstock access insulates margin from natural gas volatility in Germany and US Gulf Coast corridors. |
| Membrane Separation Technology Licensing | Enables mid-scale producers to contest reagent markets previously locked by Mitsubishi Gas Chemical distillation expertise. |
| REACH Dossier Completion Investment | Restricts qualified supplier counts for pharmaceutical-grade import volumes above one tonne annually under CLP Regulation mandates. |
| Long-term Supply Agreement Structuring | Embedded price-adjustment clauses with Shandong poultry producers compress spot market liquidity for integrated methanol-amine platforms. |
| Process Safety Engineering Capability Buildout | HAZOP management expertise scarcity constrains brownfield expansion timelines across Yangtze River basin chemical clusters. |
Study Parameters
Independent corroboration across plant managers at methanol-amine facilities, procurement leads at downstream choline chloride compounders, distribution channel partners with REACH-only representative capabilities, and technical R&D directors in quaternary ammonium synthesis underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and EPA TSCA enforcement disclosures. Bottom-up capacity assessments triangulate against top-down derivative demand modeling across animal feed, water treatment, and pharmaceutical applications.
Comparable-period anchoring to historical methanol-ammonia reaction yield improvements and silica-alumina catalyst deployment timelines establishes the forecast framework baseline. Segmentation dimensions span purity grade tier, end-use industry concentration, and regional production hub regulatory exposure. CAGRs derive from derivative demand elasticity modeling and capacity expansion announcement tracking. Industry-specific inputs include MEE wastewater enforcement intensity indices and livestock integrator procurement consolidation rates.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision through FDA Type II Drug Master File visibility than industrial-grade merchant trade estimates. Forecasts reflect assumptions around membrane separation technology adoption curves and REACH registration cost burden consolidation. Material deviation in Yangtze River basin environmental enforcement intensity or methanol feedstock price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tributyl Phosphate Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Aluminum Chemicals Market
Chemicals
Glycerol Carbonate Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Allyl Alcohol Market
Chemicals
Pentanedione Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Whitening Ingredients Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Diphenylamine (DPA) Market