
 Global Methylene Chloride Market | 2026-2036
Global Methylene Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methylene Chloride Market Foresight
Pharmaceutical manufacturing is pivoting toward higher-purity solvent grades as batch consistency requirements tighten across GMP-certified facilities. Dow Chemical Company leverages its integrated chlor-alkali network to sustain cost-competitive supply chains for methylene chloride feedstock. Gujarat Alkalies & Chemicals Ltd. anchors regional supply across South Asian pharmaceutical corridors with dedicated production lines for laboratory-grade material.
Methylene chloride, also known as dichloromethane, is a volatile organochlorine compound with the chemical formula CH₂Cl₂ and a boiling point of 39.6°C, produced primarily through methane chlorination or methanol hydrochlorination processes. Its primary industrial purpose centers on non-flammable solvent applications requiring rapid evaporation rates, particularly in paint stripping formulations and pharmaceutical extraction protocols. Industrial grade material dominates volume flows into paint removal and metal cleaning applications where cost sensitivity outweighs purity premiums, while pharmaceutical grade commands concentrated margin pools amid batch certification requirements from FDA and EMA inspectors. Chemical synthesis applications are expanding fastest among end-use categories as Asian producers scale fluorocarbon and polycarbonate intermediate manufacturing.
EPA restrictions on consumer paint stripper formulations and REACH registration requirements under ECHA oversight are redirecting demand toward industrial and pharmaceutical channels with established exposure controls. OSHA permissible exposure limits and China's MEE enforcement on volatile organic compound emissions are reshaping plant-level abatement investments and regional sourcing patterns. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate grade-mix shifts and capacity relocation decisions.
Market Dynamics
Regulatory divergence between industrial and pharmaceutical-grade specifications is fragmenting supply chains, forcing producers to maintain parallel certification tracks for EPA-compliant paint strippers versus FDA-validated solvent batches.
Growth Catalysts
- Pharmaceutical solvent mandates:FDA and EMA purity requirements for generic drug manufacturing are pulling laboratory-grade methylene chloride into GMP-certified facilities across India and China.
- Fluorocarbon intermediate demand:Chemical synthesis applications in Asian fluoropolymer production are accelerating feedstock consumption for refrigerant and aerosol propellant precursors.
- Paint stripping industrialization:EPA restrictions on consumer formulations are redirecting volume toward controlled industrial stripping operations with established exposure monitoring protocols.
Market Restraints
- Feedstock chlorine cost volatility:Integrated chlor-alkali economics tie methylene chloride margins to caustic soda and chlorine market swings, compressing producer flexibility during energy price spikes.
- Substitution pressure from N-methyl-2-pyrrolidone:Electronics cleaning and coating applications are migrating toward less regulated polar aprotic solvents with lower toxicity profiles.
- REACH registration friction:ECHA authorization requirements for dichloromethane are elevating compliance costs for EU-based formulators and limiting new market entry.
Strategic Opportunities
- Pharmaceutical corridor expansion:Underpenetrated generic API manufacturing clusters in Vietnam and Indonesia offer white-space positioning for laboratory-grade supply partnerships.
- Closed-loop solvent recovery:On-site distillation and recycling systems at metal finishing plants are creating service-based revenue streams beyond commodity chemical sales.
- China dual carbon alignment:MEE enforcement on VOC emissions is accelerating demand for abatement-integrated solvent systems with carbon accounting documentation.
Industry Challenges
- Analytical chemist scarcity:Batch certification for pharmaceutical-grade material requires specialized chromatography expertise that concentrates in established manufacturing hubs, constraining quality team scaling.
- Legacy equipment retrofit costs:Industrial stripping operations face capital intensity for ventilation and vapor recovery upgrades to meet tightening OSHA permissible exposure limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methylene Chloride Market |
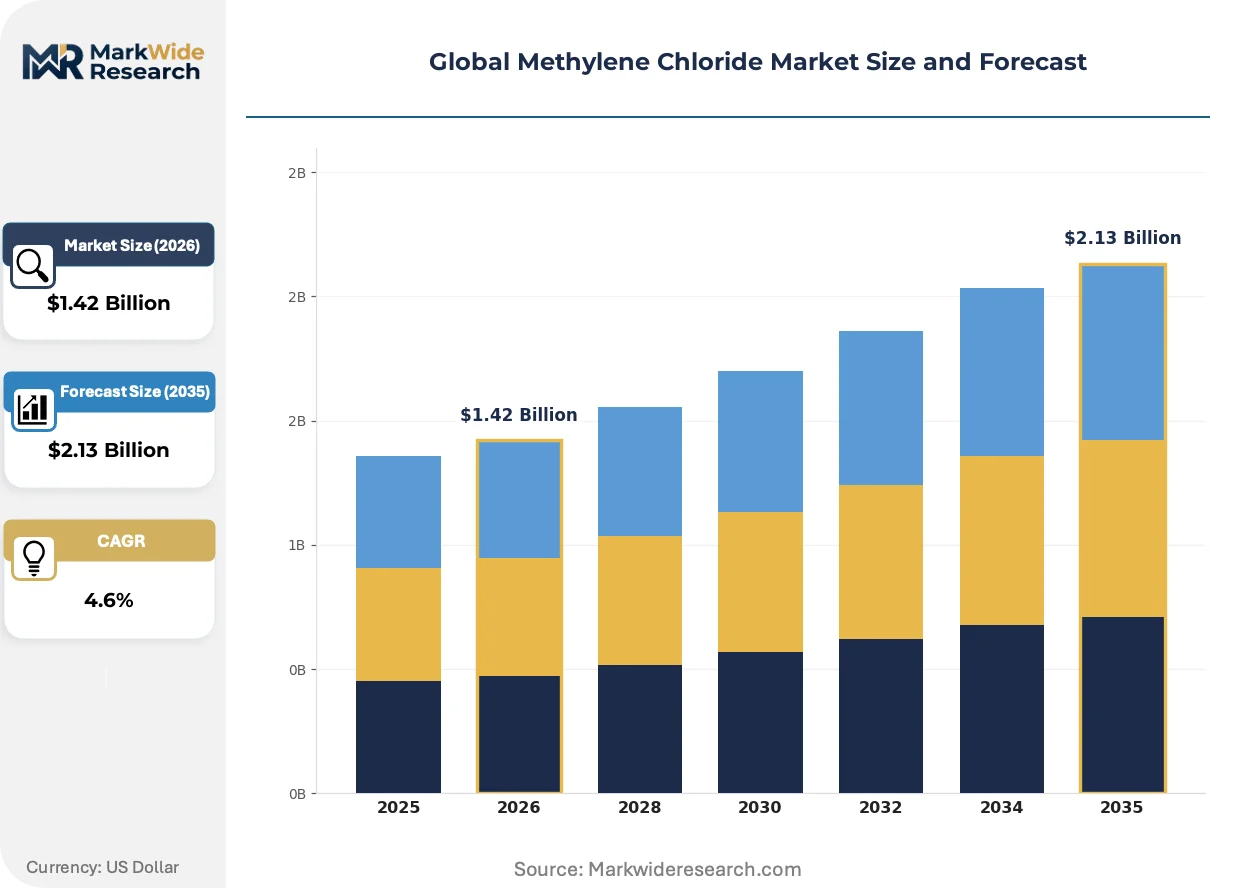
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Food Grade, Pharmaceutical Grade Application: Paint Removal, Pharmaceutical Manufacturing, Metal Cleaning, Adhesives Production, Chemical Synthesis End Use Industry: Pharmaceutical Companies, Chemical Manufacturers, Electronics Fabricators, Printing Firms, Consumer Goods Producers Packaging Type: Drums, Bulk Containers, Cylinders, Intermediate Bulk Containers |
| Companies Covered | AkzoNobel N.V., Dow Chemical Company, Eastman Chemical Company, Olin Corporation, Shin-Etsu Chemical Co., Ltd., Occidental Petroleum Corporation, KEM ONE, Gujarat Alkalies & Chemicals Ltd., Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methylene Chloride Market Shifts & Advancements
Process intensification and regulatory technology are converging to reshape how methylene chloride moves from chlor-alkali feedstock through validated pharmaceutical batches to controlled industrial applications.
Membrane-based chlor-alkali cell technology is expanding into methylene chloride production networks, replacing mercury and diaphragm processes with ion-exchange membrane electrolysis that cuts energy intensity and enables tighter chlorine purity control. Indian and Chinese chlorinated solvent producers are retrofitting membrane cells at accelerating pace. This diffusion is compressing the cost gap between integrated and merchant chlorine sourcing across Asian supply corridors.
REACH authorization timelines under ECHA oversight are forcing EU-based formulators to document substitution feasibility for dichloromethane in paint stripping and adhesive applications. Industrial end-users are responding with exposure-control investments rather than material switches, preserving methylene chloride share in professional metal cleaning while consumer markets contract. The regulatory friction is most acute in German automotive refinishing clusters where technical performance requirements resist NMP or benzyl alcohol alternatives.
Certificate-of-analysis-driven procurement now dominates pharmaceutical-grade solvent contracting, with buyers demanding lot-specific GC-MS purity data and chain-of-custody documentation before release to GMP suites. This specification escalation is displacing spot-market purchasing in generic API manufacturing and concentrating volume with producers maintaining dedicated pharmaceutical production lines. The behavioral shift is most visible across Indian pharmaceutical corridors where CDSCO inspection readiness has become a non-negotiable supplier selection criterion.
Global Methylene Chloride Market Segmentation
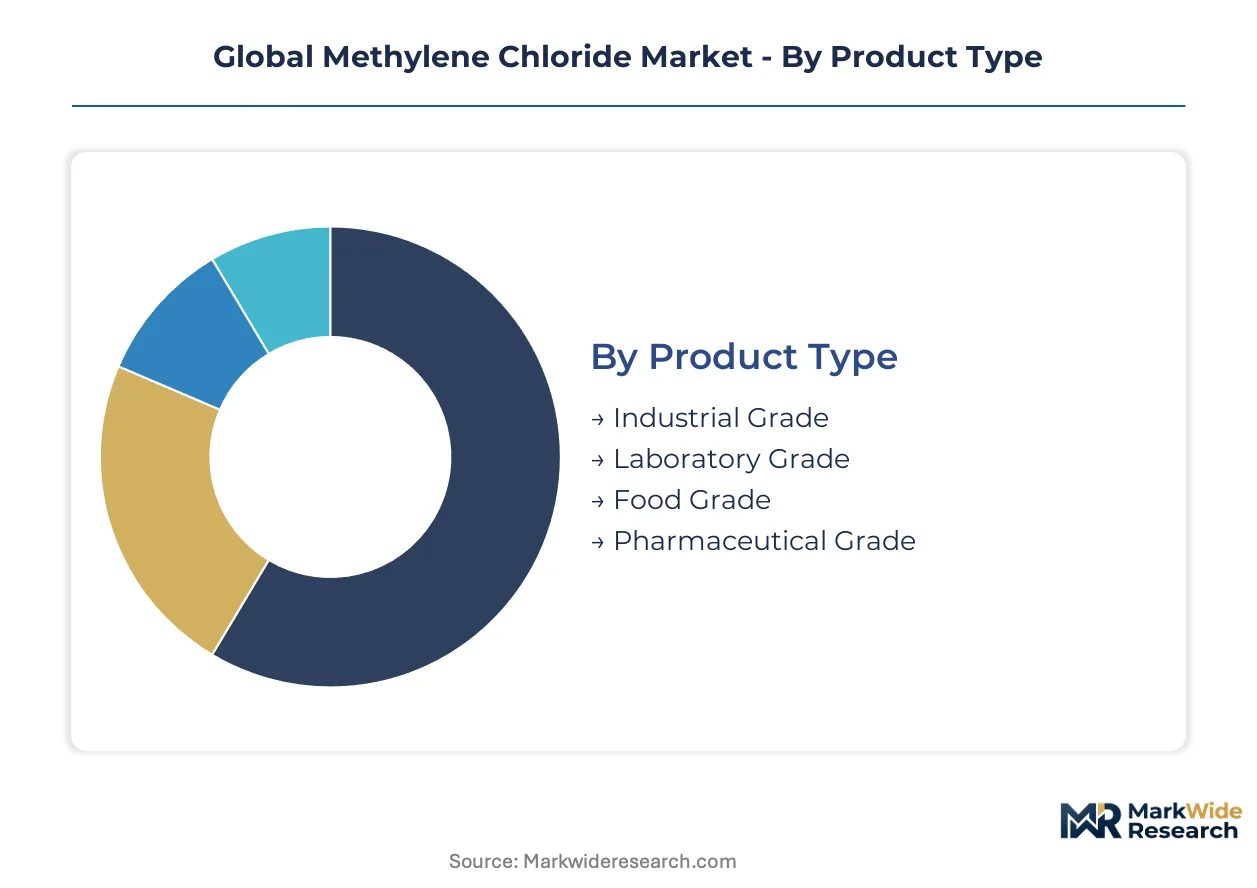
Grade purity thresholds and regulatory certification requirements split buyer procurement patterns across methylene chloride supply chains. Application-specific solvent performance demands further fragment sourcing strategies between high-throughput industrial operations and validated pharmaceutical production environments.
Product Type:
Buyers differentiate primarily by contamination tolerance and batch documentation burden.
- Industrial Grade:Contains higher residual acidity and water content acceptable for paint stripping and degreasing operations. Volume concentrates in Chinese and Indian metal finishing clusters where OSHA-style exposure controls remain unevenly enforced.
- Laboratory Grade:Specifications demand sub-ppm impurity profiles validated through gas chromatography. Pharmaceutical corridors in Hyderabad and Shanghai pull this material into GMP-certified synthesis suites under FDA and CDSCO inspection protocols.
- Food Grade:Meets extraction solvent standards for decaffeination and hop processing with documented residue limits.
- Pharmaceutical Grade:Carries the most stringent certification requirements including endotoxin testing and ICH Q3C residual solvent compliance.
Industrial Grade leads volumes today; Laboratory Grade is gaining share fastest.
Application:
End-use performance requirements determine whether buyers prioritize evaporation speed, solvency power, or regulatory defensibility.
- Paint Removal:EPA restrictions on consumer formulations have collapsed retail demand while preserving industrial stripping volumes. Professional refinishing operations in Germany and the US now dominate this channel with mandated vapor recovery systems.
- Pharmaceutical Manufacturing:Extraction and crystallization protocols in generic API production require validated solvent batches with certificate-of-analysis documentation. Indian CDSCO inspections have made supplier qualification non-negotiable.
- Metal Cleaning:Precision degreasing for aerospace and automotive components favors methylene chloride's non-flammability profile over aqueous alternatives.
- Adhesives Production:Solvent-based formulation lines in packaging and footwear manufacturing consume consistent industrial-grade volumes.
- Chemical Synthesis:Fluorocarbon intermediate production across Chinese chemical parks drives feedstock consumption for refrigerant and propellant precursors.
Paint Removal retains installed base dominance; Chemical Synthesis shows the steepest expansion trajectory.
End Use Industry:
Regulatory exposure and technical specification intensity vary sharply across buyer categories.
- Pharmaceutical Companies:GMP certification mandates and FDA pre-approval inspection readiness define procurement criteria. Laboratory-grade supply partnerships in Ahmedabad and Suzhou command premium positioning.
- Chemical Manufacturers:Integrated chlor-alkali operators and merchant solvent blenders purchase industrial-grade material for downstream fluoropolymer and polycarbonate intermediate production.
- Electronics Fabricators:Precision cleaning applications face substitution pressure from N-methyl-2-pyrrolidone in semiconductor and display manufacturing.
- Printing Firms:Flexographic and gravure ink formulation consumes moderate solvent volumes with moderate purity requirements.
- Consumer Goods Producers:Aerosol propellant and adhesive applications face regulatory headwinds in EU and North American markets.
Chemical Manufacturers anchor current demand; Pharmaceutical Companies are pulling volume growth fastest.
Packaging Type:
Logistics economics and handling safety protocols shape container selection across buyer scales.
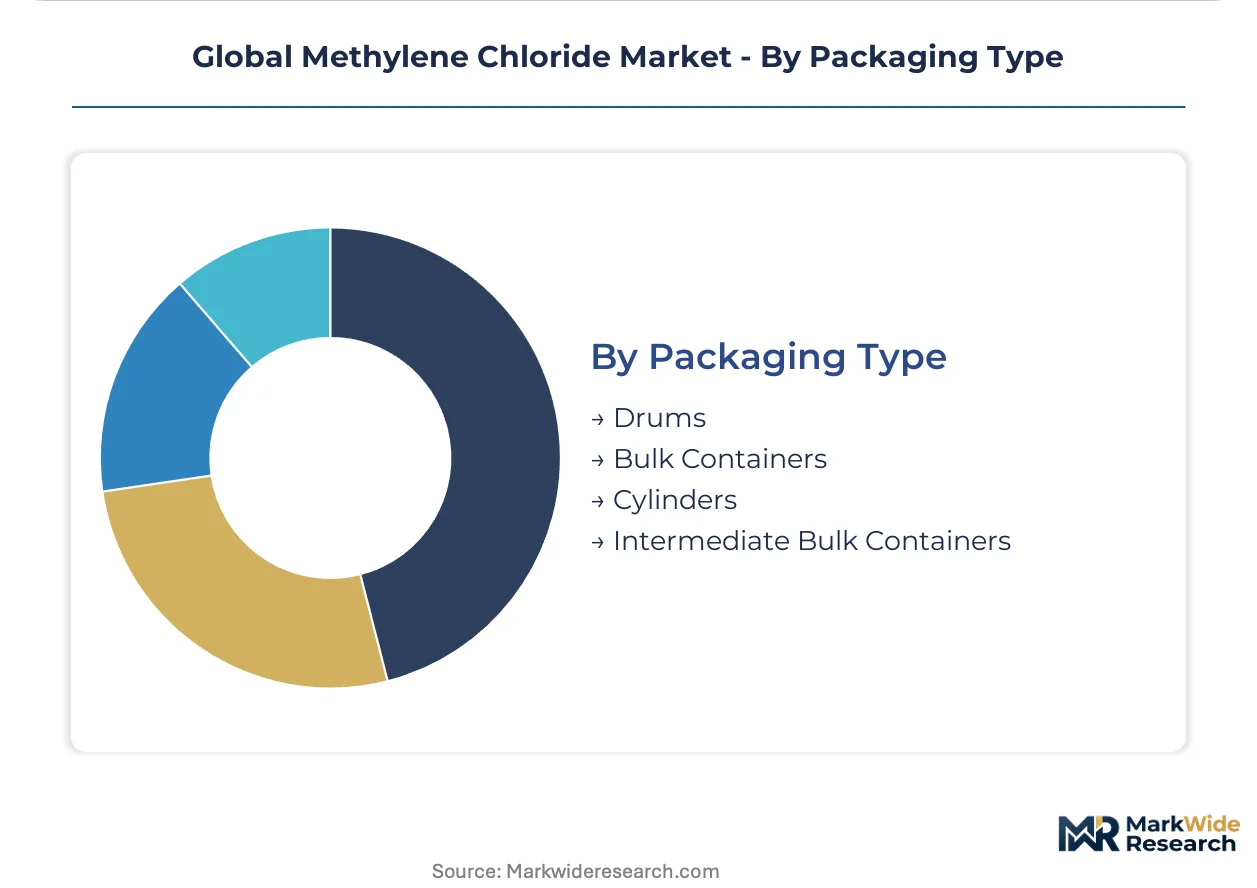
- Drums:Standard 200-liter steel drums serve mid-scale pharmaceutical and chemical operations requiring frequent batch turnover and manageable inventory exposure.
- Bulk Containers:Tank trucks and railcars feed high-throughput paint stripping and metal cleaning facilities with dedicated unloading infrastructure.
- Cylinders:Pressurized delivery suits aerosol propellant charging operations and specialized extraction equipment.
- Intermediate Bulk Containers:Flexible and rigid IBC formats bridge drum and bulk economics for regional chemical distributors serving fragmented end-user bases.
Bulk Containers dominate tonnage flows; Intermediate Bulk Containers are expanding most quickly among smaller formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting methylene chloride production toward jurisdictions where chlorine feedstock costs and environmental compliance burdens create measurable cost-of-compliance gaps. Producers are relocating capacity to exploit these divergences while maintaining pharmaceutical-grade certification for regulated end-markets.
China
Fluorocarbon intermediate manufacturing and chlor-alkali integration dominate methylene chloride consumption. MEE enforcement on VOC emissions is accelerating abatement-integrated solvent system adoption across chemical parks in Jiangsu and Shandong provinces. The Yangtze River Delta concentration of fluoropolymer producers anchors regional feedstock demand for refrigerant precursors.
United States
Industrial paint stripping operations with mandated vapor recovery systems sustain volume flows after EPA retail formulation bans collapsed consumer demand. OSHA permissible exposure limit compliance drives capital deployment in ventilation upgrades across automotive refinishing clusters in Michigan and Ohio. Dow Chemical's integrated chlor-alkali network on the Gulf Coast secures cost-competitive feedstock positioning.
Germany
REACH authorization requirements under ECHA oversight elevate compliance costs for dichloromethane formulators serving automotive and aerospace metal cleaning applications. Technical performance requirements in German refinishing clusters resist N-methyl-2-pyrrolidone substitution despite regulatory pressure. The North Rhine-Westphalia chemical corridor maintains specialized production lines for industrial-grade material.
India
Generic API manufacturing expansion in Hyderabad and Ahmedabad is pulling laboratory-grade methylene chloride into GMP-certified facilities under CDSCO inspection protocols. Domestic chlor-alkali capacity expansion in Gujarat is compressing import dependence for feedstock supply. Gujarat Alkalies & Chemicals anchors regional pharmaceutical-grade production with dedicated certification tracks.
Japan
Precision electronics cleaning applications face substitution pressure from polar aprotic solvents with lower toxicity profiles. METI industrial chemical regulations maintain stringent exposure control mandates for methylene chloride handling in semiconductor fabrication. The Osaka-Kobe manufacturing belt concentrates specialized solvent recovery system deployment for cost containment.
Global Methylene Chloride Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated chlor-alkali operators scale membrane cell retrofits to capture energy efficiency gains. The vendor base concentrates around three tiers: multinational chemical conglomerates with captive chlorine supply, regional specialists serving pharmaceutical corridors with dedicated certification infrastructure, and merchant blenders dependent on spot chlorine markets. Strategic archetypes include backward-integrated feedstock controllers, laboratory-grade certification specialists, and industrial-grade volume suppliers. Geographic expansion into underpenetrated generic API manufacturing clusters and technology licensing for closed-loop solvent recovery systems represent the dominant competitive moves.
Among multinational chemical conglomerates, Dow Chemical Company and Eastman Chemical Company exemplify the backward-integrated archetype with captive chlor-alkali positioning. Gujarat Alkalies & Chemicals Ltd. occupies a specialist role within South Asian pharmaceutical supply corridors. Shin-Etsu Chemical Co., Ltd. and Tokuyama Corporation represent Japanese producers navigating electronics cleaning substitution pressure through precision-grade positioning.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Dow Chemical Company |
| Eastman Chemical Company |
| Olin Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Occidental Petroleum Corporation |
| KEM ONE |
| Gujarat Alkalies & Chemicals Ltd. |
| Tokuyama Corporation |
| Others |
Supply & Pricing Matrix
Membrane cell retrofits across Asian chlor-alkali networks are compressing energy intensity and chlorine purity variance simultaneously, concentrating cost advantage with integrated producers while fragmenting merchant feedstock economics. This technology diffusion is reshaping margin pools across pharmaceutical-grade and industrial-grade tiers as certification burdens diverge.
Pricing Analysis
Distributor margins on laboratory-grade material absorb the heaviest documentation burden, with certificate-of-analysis validation and chain-of-custody tracking adding 15-25% markup layers before GMP suite delivery. Three-tier pricing structure across pharmaceutical, laboratory, and industrial grades reflects certification intensity rather than manufacturing cost alone. Price differentiation centers on endotoxin testing and ICH Q3C compliance overhead for pharmaceutical batches versus residual acidity tolerance for paint stripping supply. Cost compression in industrial-grade channels is intensifying because membrane cell diffusion in China and India is expanding low-cost supply availability. Metal finishing clusters in Shandong and Gujarat remain most price-sensitive, while FDA-inspected API manufacturers in Hyderabad and Suzhou absorb premium positioning with limited substitution options.
Supply Chain Analysis
Solvent recovery and distillation returns from metal finishing plants are creating closed-loop feedstock streams that bypass virgin chlor-alkali sourcing entirely. Primary production concentrates in China, India, and the United States, with Jiangsu and Gujarat anchoring Asian supply and Gulf Coast integrated operators sustaining North American flows. Feedstock draws from caustic soda and chlorine co-production economics, with merchant methanol and hydrochloric acid inputs creating secondary dependency layers. Single-source vulnerability concentrates in membrane cell technology licensors and specialized chromatography equipment for batch certification. Distribution runs through regional chemical distributors serving fragmented pharmaceutical corridors, with bulk tanker and railcar flows dominating high-volume industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where chlorine feedstock cost differentials between membrane-retrofitted Chinese chlor-alkali networks and legacy European mercury-cell operations create 20-30% cost-of-compliance gaps for pharmaceutical-grade certification.
For Market Incumbents: Cement backward integration into membrane cell technology to lock in chlorine cost advantage before merchant feedstock economics deteriorate further. Expand dedicated pharmaceutical production lines in Ahmedabad and Suzhou corridors where CDSCO and FDA inspection readiness commands supplier stickiness. Defend against N-methyl-2-pyrrolidone substitution in electronics cleaning by emphasizing non-flammability performance in aerospace metal finishing specifications. For New Entrants and Emerging Players: Closed-loop solvent recovery systems offer a technology-first wedge into industrial stripping operations facing OSHA ventilation upgrade mandates. Target Vietnamese and Indonesian generic API manufacturing clusters where laboratory-grade supply partnerships remain underpenetrated and GMP certification demand is accelerating. Pursue service-based revenue models charging per-liter-recovered rather than commodity chemical margins. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chemical distributors with pharmaceutical-grade certification infrastructure but limited geographic reach. Long-term viability hinges on regulatory divergence persistence between EPA/REACH restriction trajectories and Asian enforcement gaps. Watch for MEE enforcement intensity in Chinese chemical parks as the inflection signal for capacity relocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | Energy intensity reduction at Jiangsu and Shandong chlor-alkali facilities compresses feedstock cost curves. |
| Pharmaceutical Corridor Expansion | Dedicated production lines in Hyderabad and Ahmedabad capture CDSCO inspection-ready supplier positioning. |
| Closed-Loop Solvent Recovery | On-site distillation systems at metal finishing plants create recurring service revenue beyond commodity sales. |
| REACH Authorization Compliance | ECHA documentation requirements preserve methylene chloride share in German automotive refinishing against NMP substitution. |
| Dual Carbon Alignment | MEE-compliant abatement-integrated solvent systems with carbon accounting documentation unlock Chinese chemical park access. |
Research Methodology
Bottom-up pharmaceutical and chemical synthesis modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated solvent producers, procurement leads at generic API manufacturers, distribution channel partners in Indian pharmaceutical corridors, and technical R&D directors at fluoropolymer operations were cross-validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and EPA enforcement action databases.
Historical trendline analysis across grade-tier consumption patterns, end-use industry growth trajectories, and regional production hub expansion informed the projection framework. Segmentation dimensions modeled include grade purity tier, end-use industry application, packaging format logistics economics, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization trajectories across the projection horizon, with fluorocarbon intermediate demand and pharmaceutical solvent mandates serving as primary forecast inputs.
The model holds under sustained regulatory divergence between EPA/REACH restriction enforcement and Asian VOC compliance trajectories; deviation in MEE enforcement intensity or membrane cell technology diffusion rates would shift capacity relocation timing and margin pool distribution. Practitioners should monitor CDSCO inspection protocol tightening and ECHA authorization timeline extensions for early signals of pharmaceutical-grade supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Photographic Chemicals Market
Chemicals
Fluorochemicals Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Cumene Market
Chemicals
Tromethamine Market
Chemicals
Iscotrizinol Market
Chemicals
Isoamyl Acetate Market
Chemicals
Barbituric Acid Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Betaine Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Paint Stripper Market