
 Peracetic Acid Market | 2026-2036
Peracetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Peracetic Acid Market Analysis
China is fragmenting peracetic acid production capacity as regional chemical parks add hydrogen peroxide and acetic acid derivative lines. Evonik Industries leverages its integrated peroxide backbone to sustain supply security across European food and healthcare channels. Solvay anchors North American demand through specialized stabilized formulations for cold aseptic filling operations.
Peracetic acid is an organic peroxide formed from the equilibrium reaction of hydrogen peroxide and acetic acid, typically manufactured at concentrations between 5% and 15% with sulfuric acid catalysis and stabilized using phosphonates or phosphates to control decomposition. It functions as a broad-spectrum antimicrobial agent effective against bacteria, viruses, spores, and biofilms at low temperatures, making it indispensable for cold sanitization in food processing, beverage bottling, and medical device disinfection where heat-based sterilization would damage substrates. Liquid formulations dominate commercial supply due to easier dosing and blending flexibility, though stabilized concentrates are gaining traction in automated CIP systems where extended shelf stability reduces operational complexity. Food Processing applications lead volume consumption, while Water Treatment represents the fastest-expanding segment as utilities adopt peracetic acid for secondary disinfection to replace chlorine derivatives in effluent discharge.
EPA registration under FIFRA governs antimicrobial claims in the United States, requiring extensive efficacy data that extends product development timelines and raises barriers for new entrants seeking market access. ECHA enforces REACH restrictions on peroxide transport classifications and storage thresholds across Europe, pushing manufacturers toward on-site generation systems that reduce hazardous material logistics. FDA food contact notifications shape formulation purity requirements for equipment sanitation in dairy and meat processing facilities. Stakeholders must monitor evolving state-level discharge limits for peroxide residuals, as tighter effluent standards in key manufacturing states could shift procurement toward lower-concentration, higher-frequency dosing protocols.
Market Dynamics
Food processing facilities in Germany, the United States, and Japan are consolidating cold-chain sanitation contracts around stabilized peracetic acid formulations, compressing supplier margins while elevating purity thresholds demanded by centralized procurement teams.
Growth Catalysts
- Cold aseptic filling mandates:Beverage bottlers in Germany and France are retrofitting lines for peracetic acid-based sterilization to eliminate heat damage to sensitive packaging substrates.
- REACH transport reclassification:ECHA restrictions on concentrated peroxide shipments are accelerating on-site generation system deployments across European dairy processing clusters.
- Hydrogen peroxide feedstock expansion:Regional chemical parks in China are adding derivative capacity that lowers input costs for peracetic acid manufacturers serving Asian food exporters.
Market Restraints
- Acetic acid price volatility:Petrochemical feedstock fluctuations directly compress formulation margins for producers lacking backward integration into acetic acid supply.
- EPA registration timelines:FIFRA antimicrobial claim approvals require 18-24 month efficacy studies that delay new entrant market access and entrench incumbent positions.
- Quaternary ammonium substitution:QAC-based sanitizers retain cost advantages in ambient-temperature cleaning applications where cold sterilization is not mandatory.
Strategic Opportunities
- Japanese pharmaceutical disinfection:PMDA guidance on medical device sterilization is opening peracetic acid penetration in endoscope reprocessing where glutaraldehyde faces phase-out pressure.
- US state-level effluent mandates:California and New York are tightening peroxide residual discharge limits, creating demand for lower-concentration, higher-frequency dosing protocols.
- On-site generation convergence:Integration of electrochemical hydrogen peroxide synthesis with acetic acid blending is digitizing supply security for remote food processing facilities.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in phosphonate stabilization chemistry for extended-shelf concentrates is concentrated among aging technical workforces in German and Swiss chemical clusters.
- Legacy CIP system incompatibility:Retrofitting automated clean-in-place infrastructure for peracetic acid compatibility requires stainless steel grade verification and sensor recalibration that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peracetic Acid Market |
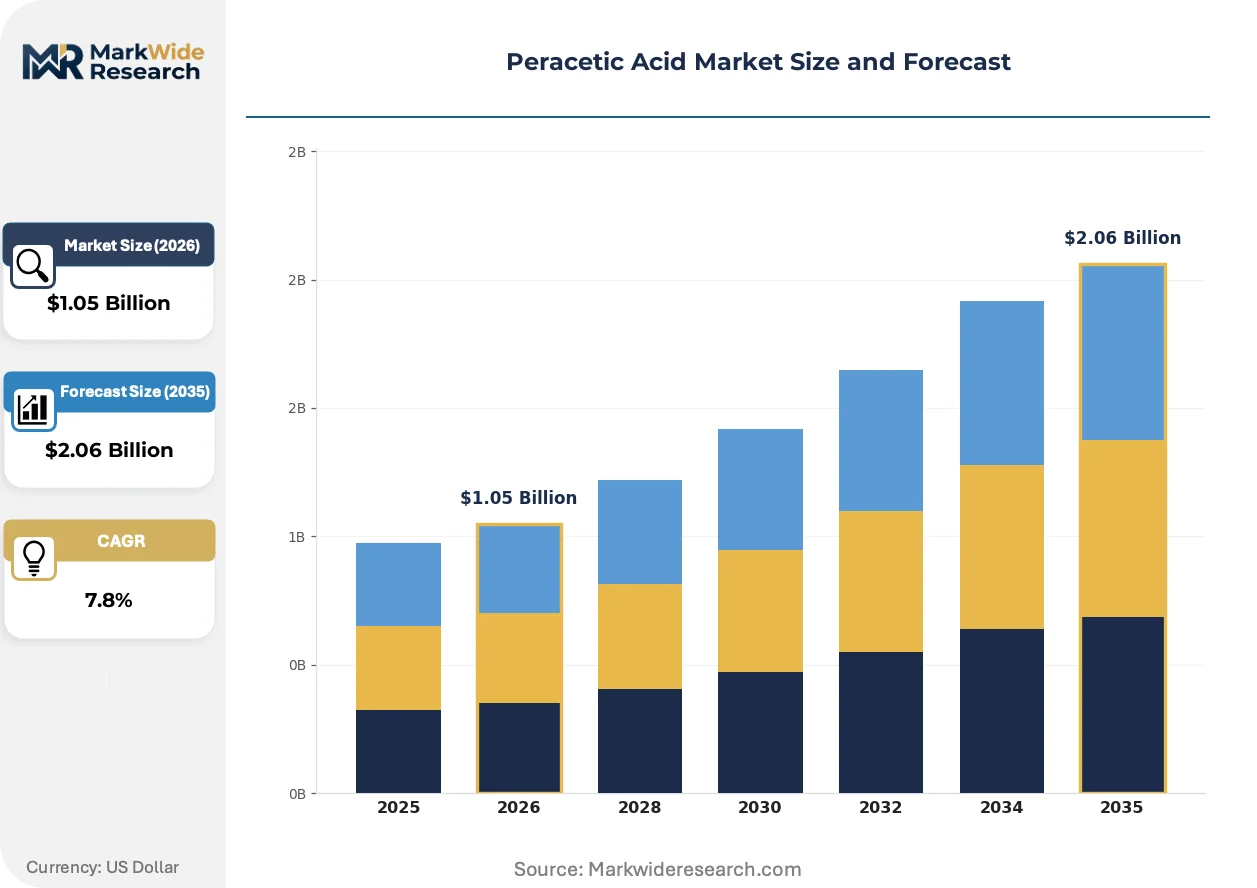
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Concentrate, Stabilized Application: Food Processing, Water Treatment, Agriculture, Healthcare End User: Food Industry, Chemical Manufacturing, Waste Management, Pharmaceutical Distribution Channel: Online Sales, Direct Sales, Wholesale, Retail |
| Companies Covered | Evonik Industries, Solvay, Ecolab, Kemira, Enviro Tech Chemical Services, Mitsubishi Gas Chemical Company, FMC Corporation, LANXESS, Christeyns, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peracetic Acid Market Emerging Trajectories
Peracetic acid supply chains are bifurcating between bulk stabilized concentrates for centralized food processors and modular on-site generation units for distributed beverage and healthcare facilities seeking hazardous material logistics reduction.
Electrochemical hydrogen peroxide synthesis is digitizing feedstock security for peracetic acid manufacturers. German chemical parks are piloting membrane-cell technology that produces hydrogen peroxide on demand from water and electricity, eliminating transport of concentrated peroxide precursors. Food processors in Bavaria and Baden-Württemberg are adopting these integrated systems to satisfy ECHA storage threshold restrictions while maintaining sterilization throughput.
EPA's emerging contaminants monitoring framework is tightening effluent scrutiny for peroxide residuals in food processing discharge. The agency's expanded analytical methods for downstream water body detection are forcing dairy and meat processors to validate degradation kinetics before permit renewal. Facilities in Wisconsin and Idaho are investing in quenching systems that accelerate peracetic acid decomposition to meet state-level receiving water standards.
Centralized procurement teams at multinational food conglomerates are consolidating sanitation chemical contracts around full-service sterilization programs rather than commodity chemical purchasing. Technical service bundling—encompassing dosing equipment, efficacy validation, and regulatory documentation—is displacing spot-market peracetic acid transactions. This shift is most pronounced in German and Dutch dairy cooperatives where sustainability reporting requirements favor single-supplier accountability for chemical usage and discharge metrics.
Peracetic Acid Market Segmentation
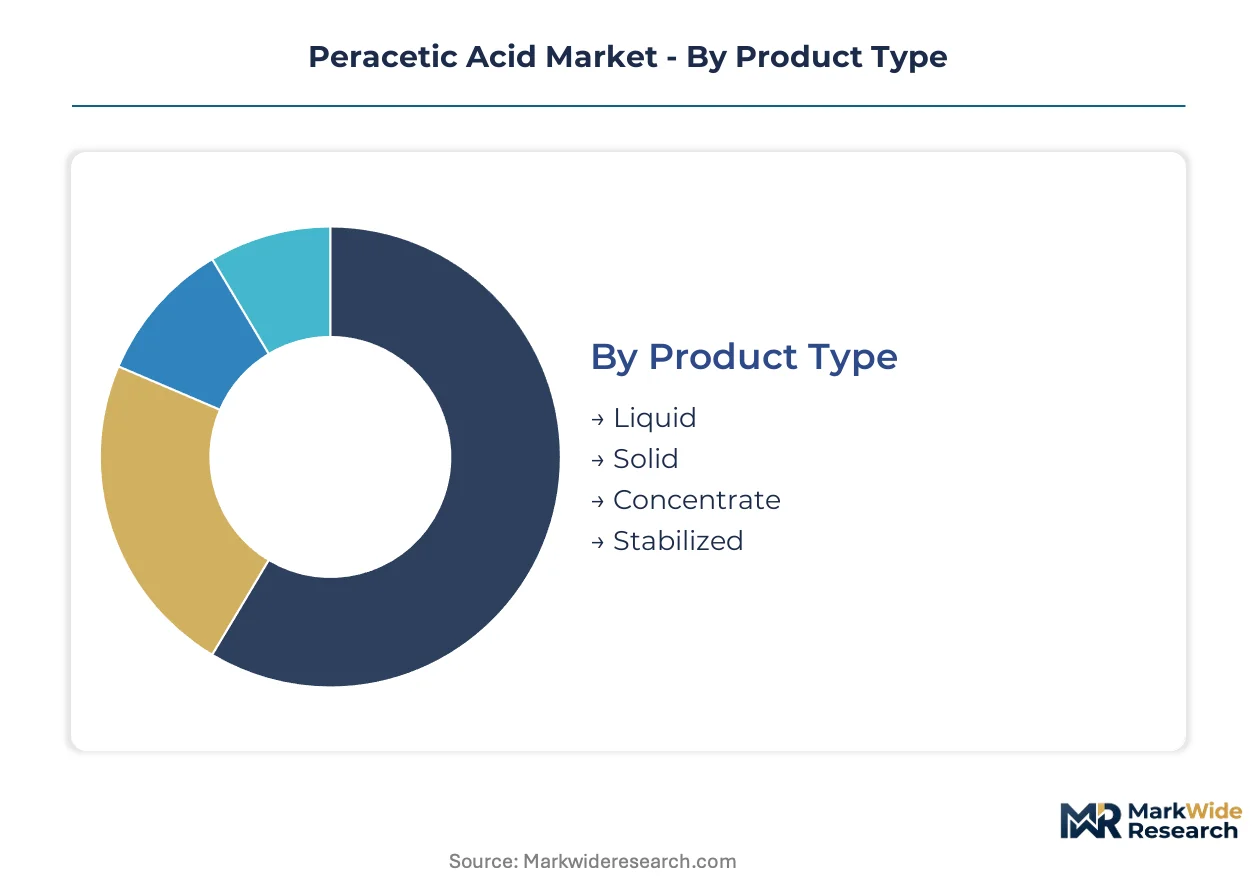
Peracetic acid formulations vary sharply in stability, concentration, and handling requirements across use cases. Food processors, wastewater utilities, and healthcare facilities each impose distinct purity thresholds and dosing protocols that reshape product specifications.
Product Type:
Liquid concentrates and stabilized variants span the use-case spectrum from bulk cold-chain sanitation to precision medical device sterilization.
- Liquid:Standard aqueous solutions dominate commercial supply due to easier dosing and blending flexibility. Dairy cooperatives in Germany and beverage bottlers in France favor liquid formats for automated CIP systems where flow-rate precision controls sterilization efficacy.
- Stabilized:Phosphonate-extended shelf formulations command premium positioning in centralized procurement contracts. Extended stability reduces operational complexity for remote food processing facilities facing ECHA transport restrictions on concentrated peroxide shipments.
- Concentrate:High-strength formulations serve bulk industrial users with on-site dilution infrastructure.
- Solid:Tablet and powder formats address specialized logistics constraints in remote agricultural applications.
Established volume favors Liquid; emerging adoption favors Stabilized.
Application:
Cost tier separation distinguishes commodity sanitation from regulated healthcare sterilization where purity documentation commands price premiums.
- Food Processing:Cold-chain sanitation for dairy, meat, and beverage applications constitutes the dominant volume segment. Low-temperature antimicrobial efficacy against biofilms and spores drives specification at German and US processing facilities where heat sterilization would damage product integrity.
- Water Treatment:Secondary disinfection for municipal and industrial effluent is expanding most quickly as utilities replace chlorine derivatives to meet tightened discharge standards. California and New York state-level peroxide residual limits are accelerating validation of degradation kinetics before permit renewal.
- Healthcare:Medical device sterilization and endoscope reprocessing face PMDA guidance shifts away from glutaraldehyde in Japanese facilities.
- Agriculture:Crop protection and equipment sanitation serve seasonal demand patterns with lower regulatory stringency.
Food Processing anchors current procurement spend; Water Treatment shows the steepest expansion trajectory.
End User:
Customer type fragmentation separates centralized chemical buyers from distributed facilities requiring technical service bundling.
- Food Industry:Multinational conglomerates and dairy cooperatives are consolidating sanitation contracts around full-service sterilization programs. Sustainability reporting requirements in Germany and the Netherlands favor single-supplier accountability for chemical usage metrics.
- Waste Management:Municipal utilities and industrial treatment plants specify peracetic acid for odor control and secondary disinfection compliance.
- Chemical Manufacturing:Captive consumption and merchant sales of derivative formulations serve downstream blending operations.
- Pharmaceutical:Sterile manufacturing and cleanroom protocols impose the most stringent purity documentation requirements.
Procurement concentration favors Food Industry; regulatory tailwinds favor Pharmaceutical.
Distribution Channel:
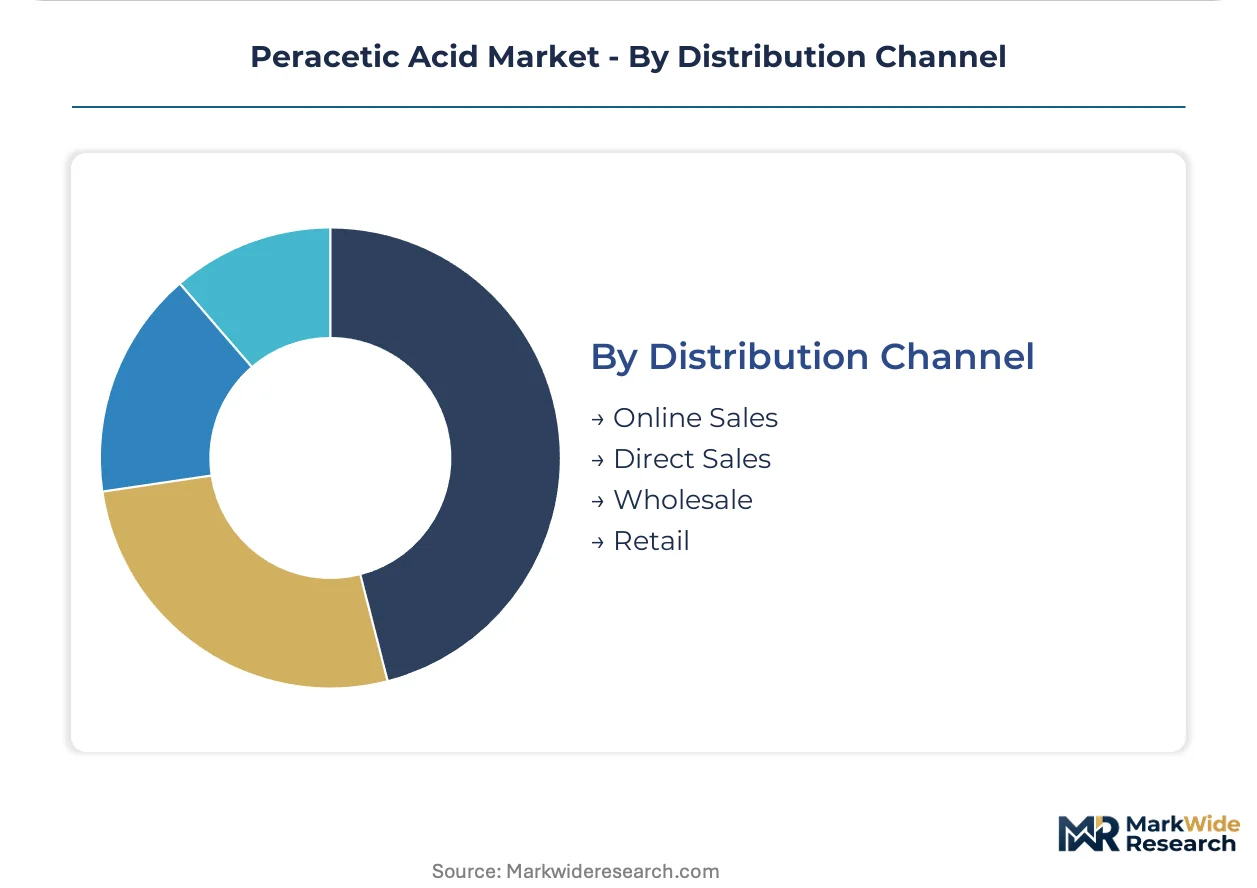
Supply chain configuration separates spot-market commodity transactions from integrated equipment-and-chemical service models.
- Direct Sales:Technical service bundling—encompassing dosing equipment, efficacy validation, and regulatory documentation—is displacing arm's-length chemical purchasing. Bavarian food processors adopt integrated systems combining electrochemical hydrogen peroxide synthesis with acetic acid blending.
- Wholesale:Bulk concentrate distribution serves mid-scale processors lacking dedicated chemical management infrastructure.
- Online Sales:Standardized low-concentration formulations address small-scale agricultural and facility maintenance buyers.
- Retail:Consumer-scale packaging captures minimal share in professional-dominated end markets.
Margin capture favors Direct Sales; volume accessibility favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration requirements under FIFRA anchor the United States as the regulatory benchmark for antimicrobial efficacy validation, while ECHA's REACH transport classifications reshape supply chain configurations across European chemical parks.
United States
Cold aseptic filling retrofits at beverage bottlers in Wisconsin and Idaho drive stabilized formulation demand. EPA's emerging contaminants monitoring framework tightens peroxide residual scrutiny in dairy and meat processing discharge. Facilities in the Great Lakes region invest in quenching systems to accelerate degradation kinetics before permit renewal.
Germany
Centralized procurement teams at dairy cooperatives in Bavaria and Baden-Württemberg consolidate sanitation contracts around full-service sterilization programs. ECHA storage threshold restrictions on concentrated peroxide shipments accelerate on-site generation deployments. Chemical parks in the Rhine-Ruhr region pilot membrane-cell electrochemical hydrogen peroxide synthesis to eliminate precursor transport.
China
Regional chemical parks add hydrogen peroxide and acetic acid derivative lines to serve Asian food exporters. The country's national chemical safety regulator enforces stricter peroxide transport classifications for inter-provincial shipments. Processing clusters in Shandong and Jiangsu provinces integrate backward into captive acetic acid supply to compress formulation margins.
Japan
PMDA guidance on medical device sterilization opens peracetic acid penetration in endoscope reprocessing where glutaraldehyde faces phase-out pressure. METI industrial standards shape purity documentation requirements for pharmaceutical cleanroom protocols. Manufacturing concentrations in the Kansai region around Osaka anchor healthcare sterilization demand validation.
France
Beverage bottlers in the Île-de-France and Auvergne-Rhône-Alpes regions retrofit lines for peracetic acid-based sterilization to protect sensitive packaging substrates. EU Green Deal effluent standards tighten receiving water quality thresholds for food processing discharge. Dairy cooperatives in Normandy adopt technical service bundling to satisfy sustainability reporting requirements for chemical usage metrics.
Peracetic Acid Market Vendor Landscape
Integrated peroxide backbone operators and specialized stabilized formulation suppliers split the market between feedstock security and application-specific performance. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with captive hydrogen peroxide supply, regional blending specialists with technical service bundling capabilities, and electrochemical technology providers enabling on-site generation systems. Dominant competitive moves include backward integration into acetic acid feedstock and geographic expansion through technical service partnerships with centralized procurement teams.
Among German-based chemical conglomerates, Evonik Industries exemplifies the integrated peroxide backbone archetype, while Solvay anchors the specialized stabilized formulation tier for North American cold aseptic filling operations. Kemira represents the regional technical service bundling model, particularly in European dairy processing clusters where ECHA transport restrictions favor localized supply security.
| Leading Market Players |
|---|
| Evonik Industries |
| Solvay |
| Ecolab |
| Kemira |
| Enviro Tech Chemical Services |
| Mitsubishi Gas Chemical Company |
| FMC Corporation |
| LANXESS |
| Christeyns |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr chemical corridor freight costs compress formulation margins for European peracetic acid producers while simultaneously enabling premium pricing for stabilized concentrates delivered to Bavarian dairy cooperatives facing ECHA transport restrictions. This logistics tension concentrates pricing power among integrated hydrogen peroxide operators and fragments procurement options for remote food processors.
Pricing Analysis
Price spreads between German stabilized concentrates and Chinese commodity-grade formulations reflect purity documentation tiers and cold-chain certification requirements. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates healthcare sterilization premiums from beverage bottling contracts. Cost compression in standard liquid formulations is intensifying because acetic acid feedstock volatility squeezes non-integrated blenders. Mid-scale wastewater utilities exhibit highest price sensitivity due to chlorine substitution economics, while pharmaceutical cleanroom protocols tolerate premium positioning.
Supply Chain Analysis
Tariff exposure between China and key food-exporting nations dominates supply chain risk planning for Asian peracetic acid manufacturers. Production gravity centers on Germany, China, and the United States, with hydrogen peroxide and acetic acid feedstock dependencies drawing from regional chemical park infrastructure. Single-source vulnerability in phosphonate stabilization chemistry concentrates among aging technical workforces in German and Swiss clusters. Distribution runs through direct technical service bundling for multinational food conglomerates and wholesale concentrate channels for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peracetic acid market fragmentation creates entry niches as centralized procurement teams disaggregate commodity chemical purchasing from full-service sterilization programs. This demand-side shift opens specialized positioning for electrochemical technology providers and regional technical service bundlers.
For Market Incumbents: Insulate formulation margins through captive acetic acid supply and phosphonate stabilization chemistry expertise concentration. Backward integration into hydrogen peroxide feedstock secures cost position against Chinese chemical park expansion. Priority investment targets automated CIP system compatibility certification to entrench switching costs at dairy cooperatives consolidating sanitation contracts.
For New Entrants and Emerging Players: Japanese pharmaceutical disinfection represents underpenetrated white space as PMDA guidance phases out glutaraldehyde in endoscope reprocessing. On-site generation system deployment for remote beverage facilities facing ECHA storage thresholds offers second entry vector. Go-to-market positioning emphasizes digitized supply security through electrochemical hydrogen peroxide synthesis integration.
For Investors and Strategic Acquirers: Regional blending specialists with technical service bundling capabilities anchor acquisition interest as procurement consolidation elevates single-supplier accountability models. Long-term viability frames around regulatory tailwinds for cold sterilization replacing heat-based methods across food and healthcare channels. Signal to monitor: California and New York state-level effluent mandate acceleration driving lower-concentration, higher-frequency dosing protocol adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive feedstock supply compresses formulation margins against volatile petrochemical pricing. |
| On-Site Generation System Deployment | Electrochemical hydrogen peroxide synthesis eliminates ECHA transport restriction exposure for remote processors. |
| Technical Service Bundling Expansion | Integrated dosing equipment and efficacy validation contracts displace spot-market chemical transactions. |
| Pharmaceutical-Grade Certification Investment | PMDA and FDA purity documentation opens healthcare sterilization premium pricing tiers. |
| Geographic Expansion Through Partnership | Collaboration with centralized procurement teams at multinational food conglomerates accelerates contract consolidation capture. |
Methodological Framework
A standing panel of plant managers at German dairy cooperatives, procurement leads at US beverage bottlers, technical R&D directors at hydrogen peroxide manufacturers, and EHS compliance officers at wastewater utilities provided ongoing calibration. Primary interviews combined with secondary validation from EPA FIFRA registration databases, ECHA REACH substance dossiers, FDA food contact notification filings, and customs trade data. Bottom-up facility-level consumption estimates triangulated against top-down chemical park production capacity assessments.
Scenario-bracketing framed projections across regulatory acceleration and feedstock volatility pathways. Segmentation dimensions modeled include product concentration tier, application end-use, and regional regulatory cluster. CAGRs derived from weighted average of demand-side procurement surveys and supply-side capacity expansion announcements. Forecast inputs incorporated ECHA transport reclassification timing and state-level effluent mandate progression.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrochemical technology providers or acetic acid producers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Flame Retardants Chemicals Market
Chemicals
Welding Chemicals Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
HATU Market
Chemicals
Potassium Alum Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Pinoxaden Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Nonanoic Acid Market
Chemicals
Immunochemicals Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
RDX and HMX Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Hydroxyzine Imine Market
Chemicals
China Methanol Market