
 Global Construction Chemical Market | 2026-2036
Global Construction Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Chemical Market Foresight
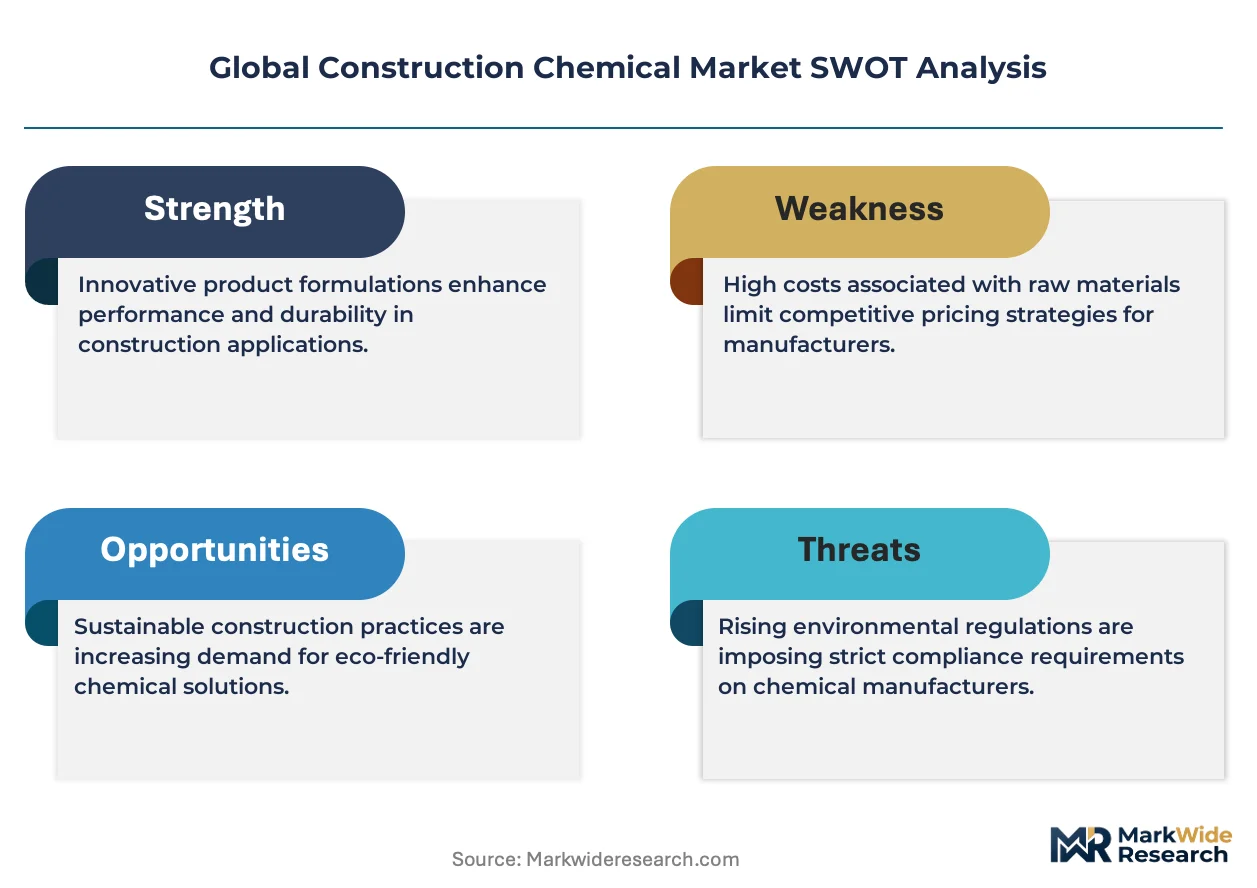
The EU Green Deal's embodied carbon thresholds is restructuring procurement criteria for public infrastructure across member states. Sika AG leverages its vertically integrated polymer supply to pre-certify products against emerging carbon budgets. BASF SE anchors its position through R&D intensity in polycarboxylate ether superplasticizers. MAPEI S.p.A. competes on geographic dominance across Mediterranean markets with localized blending capacity.
Construction chemicals encompass admixtures, sealants, coatings, and repair compounds formulated with polymer binders, mineral fillers, and performance additives to modify concrete rheology, durability, and curing kinetics. These formulations serve primarily to extend service life of reinforced concrete structures exposed to chloride ingress, freeze-thaw cycling, and chemical attack. Concrete admixtures command the largest value pool due to their ubiquity in ready-mix and precast operations, while waterproofing chemicals register the fastest structural expansion as below-grade construction intensifies in flood-prone urban corridors. Tile adhesives occupy a mature margin segment where formulation differentiation centers on open-time and shear-strength specifications.
The US EPA regulates volatile organic compound emissions from coating applications, while India's BIS mandates IS 9103 conformance for concrete admixture performance. China's MEE enforces GB standards on hazardous substance limits in construction materials. Stakeholders must monitor how cascading carbon disclosure rules from the EU CSRD reshape specification power across the contractor-developer interface.
Market Dynamics
Polymer-modified binder substitution in highway infrastructure is compressing specification cycles and forcing reformulation investments across admixture portfolios. The EU Green Deal's embodied carbon thresholds now function as procurement gatekeepers for public tenders.
Growth Catalysts
- EU Green Deal procurement mandates:Member states now embed embodied carbon thresholds into infrastructure tender criteria, redirecting volume toward low-carbon admixture suppliers with pre-certified environmental product declarations.
- Below-grade waterproofing intensity:Urban flood-risk corridors in coastal megacities are mandating comprehensive substructure protection, expanding specification of crystalline and membrane-based waterproofing systems.
- Polymer-modified asphalt substitution:Highway authorities are displacing conventional bitumen with elastomer-modified binders to extend pavement service life under heavy axle loads and thermal cycling stress.
Market Restraints
- Petrochemical feedstock volatility:Styrene-butadiene and ethylene-vinyl acetate prices swing with crude oil benchmarks, compressing margin predictability for polymer-dependent waterproofing and adhesive formulations.
- China supply concentration:Bulk production of polycarboxylate ether superplasticizers and redispersible polymer powders clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for global formulators.
- Substitution by geopolymer cements:Alkali-activated binders are displacing Portland-based systems in select precast applications, threatening volume in traditional concrete admixture categories.
Strategic Opportunities
- India's smart city infrastructure pipeline:Municipal corporations in Mumbai, Delhi, and Bangalore are specifying high-performance admixtures for metro rail and flood-resilient housing stock.
- Carbon-capture concrete admixtures:Mineralization technologies that sequester CO2 during curing are converging with voluntary carbon credit markets, creating premium pricing architecture.
- Direct-to-contractor digital platforms:E-procurement channels are disintermediating traditional distributor networks for standardized repair mortar and tile adhesive SKUs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology modification and compatibility testing for polycarboxylate ether systems is concentrated among retiring technical specialists in European and Japanese laboratories.
- EPD certification timelines:Third-party verification of environmental product declarations under ISO 14025 protocols extends 12-18 months, delaying qualification for EU public procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Chemical Market |
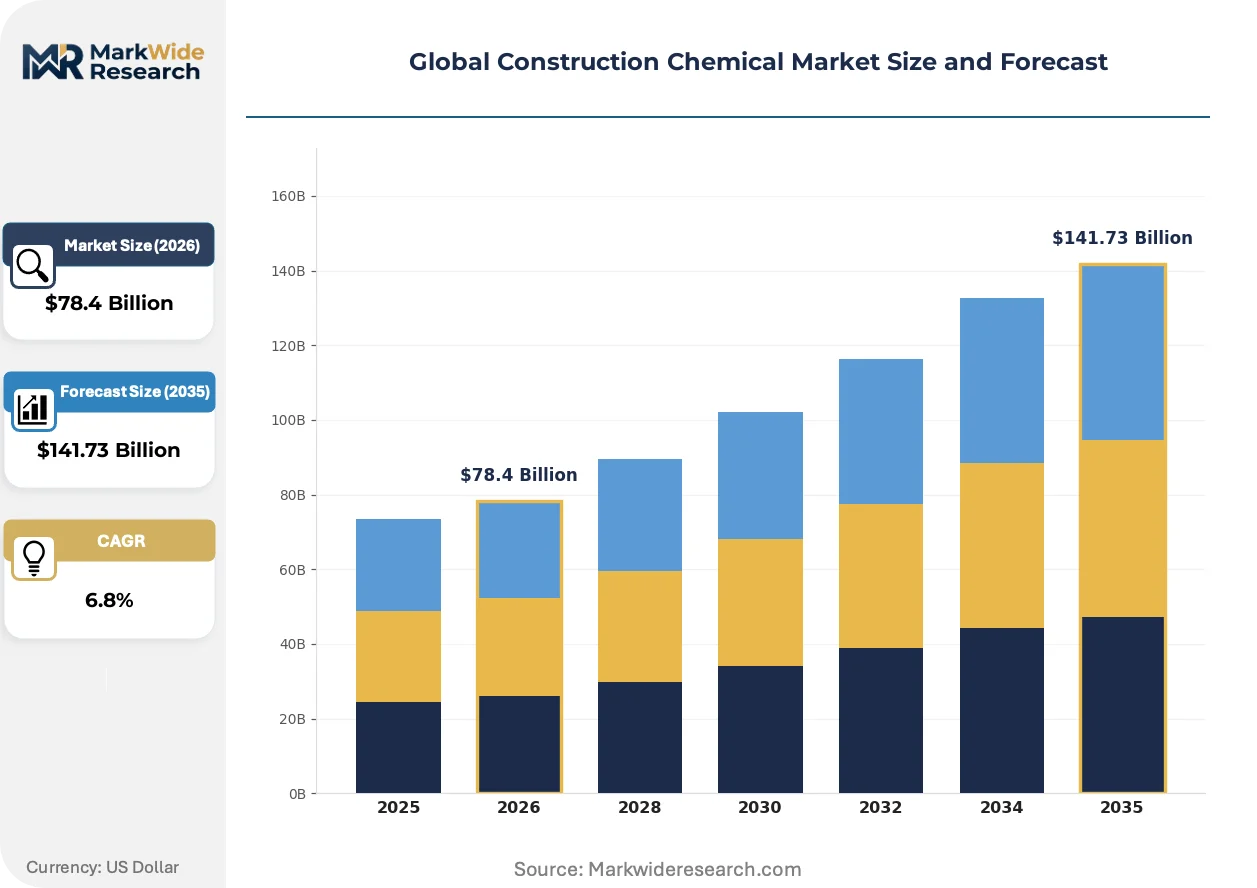
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Admixtures, Waterproofing Chemicals, Surface Treatment Chemicals, Repair & Restoration Chemicals, Tile Adhesives, Grouts Technology: Polycarboxylate Ether, Silane & Siloxane, Epoxy, Polyurethane, Acrylic Polymers, Cementitious Application: Bridges, Dams, Commercial Buildings, Highways, Tunnels, Water Treatment Plants End User: General Contractors, Specialty Contractors, Facility Managers, Real Estate Developers, Architectural Firms, Engineering Consultants |
| Companies Covered | Sika AG, BASF SE, Henkel AG & Co. KGaA, MAPEI S.p.A., RPM International Inc., Arkema SA, Fosroc International Limited, Ashland Global Holdings Inc., Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Chemical Market Shifts & Advancements
Digital formulation tools and bio-based feedstocks are compressing development cycles while regulatory carbon accounting is embedding itself into product specifications. Three active shifts are restructuring competitive advantage.
Self-healing concrete admixtures containing encapsulated bacteria or vascular networks are converging with lifecycle cost contracting models for marine and tunnel infrastructure. Port authorities in the Netherlands and Denmark are piloting these systems for chloride-exposed substructures. The technology is compressing maintenance liability windows from decades to years in performance-guaranteed contracts.
REACH authorization requirements for microplastic additives are forcing reformulation of conventional sealants and coatings across European manufacturing. Formulators are displacing synthetic microspheres with cellulose-derived alternatives in waterproofing membranes. The construction chemicals segment faces the steepest compliance burden among building material categories due to polymer loading densities.
Integrated project delivery contracts are consolidating specification authority into engineering-procurement-construction consortiums rather than fragmented subcontractor decisions. This concentration is compressing supplier qualification lists to three-to-five approved vendors per product category. The shift is most visible in German and French infrastructure megaprojects where alliance contracting has become mandatory for public works above threshold values.
Global Construction Chemical Market Segmentation
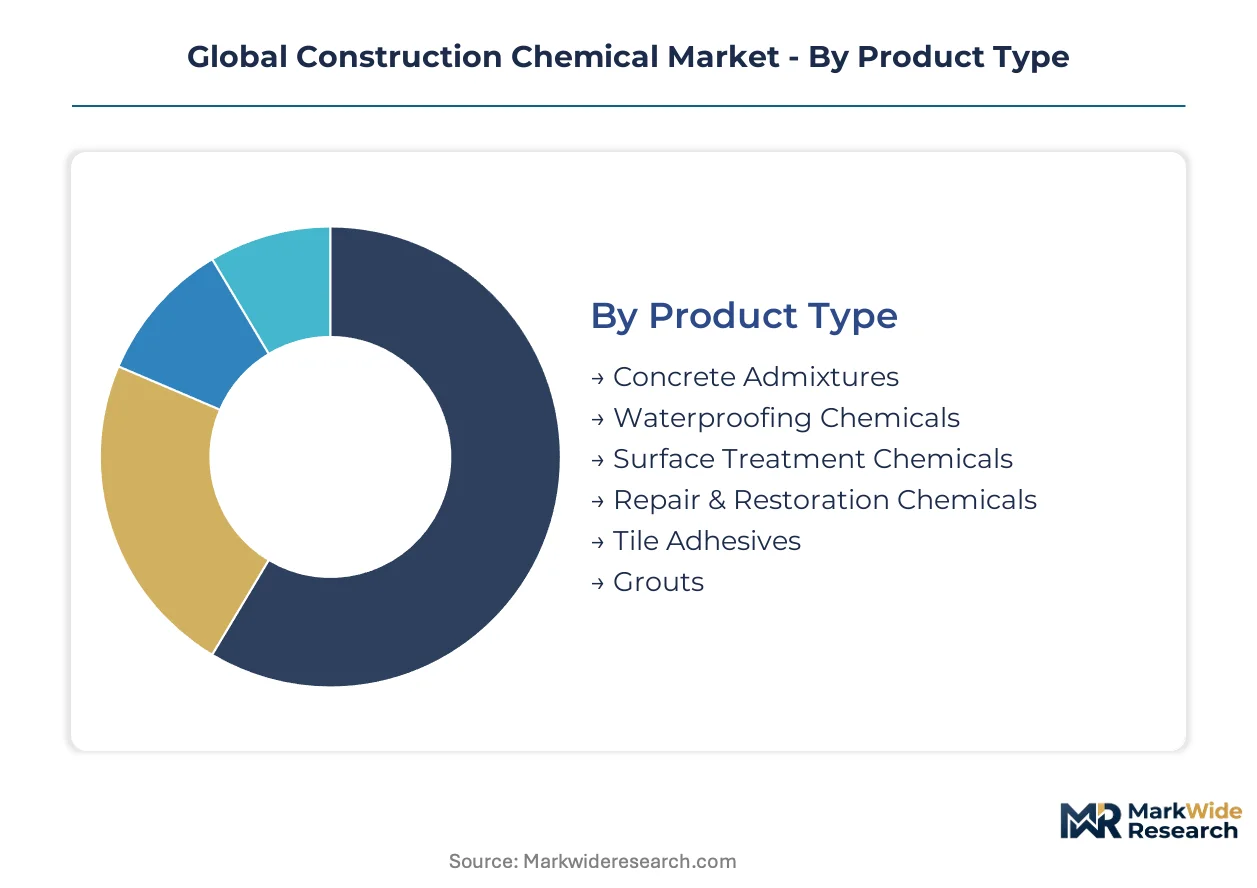
Segmentation in construction chemicals reveals how formulation complexity, specification authority, and project scale fragment value capture across the supply chain. Product categories diverge sharply in margin structure and capital requirements, while end-user concentration determines pricing power and contract tenure.
Product Type:
Capital intensity escalates from commodity blending operations to polymer synthesis and specialized rheology modification systems.
- Concrete Admixtures:Polycarboxylate ether and lignosulfonate formulations modify slump retention and early strength development in ready-mix and precast concrete. Demand concentrates in China's megacity infrastructure corridors and India's smart city pipelines, where specification engineers prioritize chloride resistance and pumpability over unit cost.
- Waterproofing Chemicals:Crystalline admixtures, bituminous membranes, and elastomeric coatings protect substructures from hydrostatic pressure and vapor transmission. Below-grade construction in flood-prone coastal cities—Mumbai, Jakarta, Miami—drives specification of integral crystalline systems that self-seal capillary cracks.
- Surface Treatment Chemicals:Curing compounds and densifiers for hardened concrete surfaces.
- Repair & Restoration Chemicals:Structural mortars, injection resins, and corrosion inhibitors for deteriorated reinforced concrete.
- Tile Adhesives:Cementitious and polymer-modified thin-set and thick-bed formulations for ceramic and stone installation.
- Grouts:Non-shrink and epoxy-based systems for machinery baseplates, anchor bolts, and precision alignment.
Most installed capacity flows through Concrete Admixtures. Expansion is steepest in Waterproofing Chemicals.
Technology:
Patent density and R&D spend cluster around polymer architectures that enable superplasticizing efficiency and durability enhancement.
- Polycarboxylate Ether:Comb-like copolymers with polyethylene glycol side chains deliver high-range water reduction at low dosages, enabling self-consolidating concrete and ultra-high-performance mixes. German and Japanese formulators dominate patent estates, while Chinese producers in Shandong province supply bulk powder to regional blenders.
- Silane & Siloxane:Small-molecule penetrants and oligomeric resins impart hydrophobicity to masonry and concrete substrates without surface film formation. Historic building restoration in Italy and heritage infrastructure protection in the UK sustain premium pricing for breathable, UV-stable formulations.
- Epoxy:Two-component thermosetting systems for high-bond repair mortars and chemical-resistant coatings.
- Polyurethane:Flexible membranes, sealants, and injection foams for dynamic crack bridging and waterproofing.
- Acrylic Polymers:Styrene-acrylic and pure acrylic dispersions for decorative coatings and tile adhesive modification.
- Cementitious:Portland-based systems with crystalline or pozzolanic additives for passive waterproofing and repair.
Polycarboxylate Ether commands the highest technical margins. Silane & Siloxane applications are climbing the fastest in heritage and coastal specifications.
Application:
Project scale and durability exposure dictate formulation performance tiers and supplier qualification requirements.
- Commercial Buildings:High-rise concrete cores, post-tensioned slabs, and facade systems demand admixtures for pumpability, shrinkage control, and finish quality. Specification authority sits with engineering-procurement-construction consortiums in German and French alliance contracts, compressing approved vendor lists to three-to-five suppliers per category.
- Highways:Polymer-modified asphalt binders and concrete pavement overlays face extreme thermal cycling and heavy axle loading. US state DOTs and India's NHAI are displacing conventional bitumen with SBS-modified and EVA-modified systems to extend resurfacing intervals.
- Bridges:Marine exposure and de-icing salt attack drive specification of corrosion-inhibiting admixtures and cathodic protection systems.
- Dams:Mass concrete placements require retarders, pozzolans, and cooling systems to control thermal cracking in large lifts.
- Tunnels:Shotcrete accelerators, waterproofing membranes, and segment gasket adhesives for underground excavation support.
- Water Treatment Plants:Chemical-resistant coatings and potable-water-certified linings for containment structures.
Commercial Buildings absorb the largest admixture volumes. Highways are gaining share fastest as polymer-modified binder substitution accelerates.
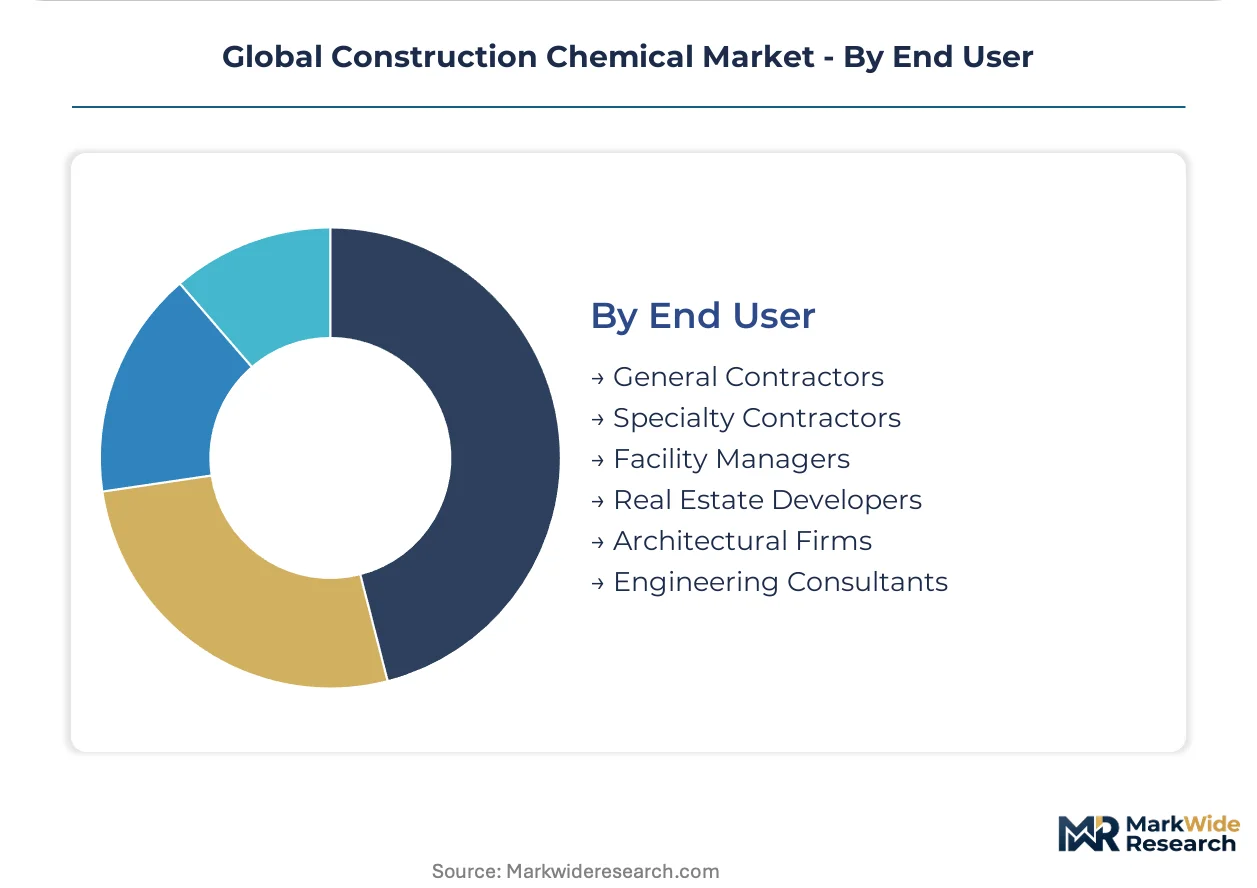
End User:
Procurement sophistication and technical staffing determine whether specifications favor performance-tested brands or commodity alternatives.
- General Contractors:Volume purchasers of standardized admixtures and repair mortars through distributor networks or emerging direct-to-contractor digital platforms. Margin pressure is acute as project delivery methods consolidate buying power into fewer decision-makers.
- Specialty Contractors:Waterproofing applicators, concrete restoration firms, and flooring installers with formulation-specific expertise and brand loyalty. These users drive specification of application-critical products like crystalline waterproofing and self-leveling underlayments.
- Facility Managers:Maintenance-phase purchasers of repair compounds and protective coatings for asset life extension.
- Real Estate Developers:Early-phase influencers on green building certification and embodied carbon targets.
- Architectural Firms:Aesthetic and durability specifiers for exposed concrete and protective coatings.
- Engineering Consultants:Performance-based specification writers for public infrastructure tenders.
General Contractors channel the highest transaction volumes. Specialty Contractors are expanding fastest as technical application requirements fragment the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with polycarboxylate ether expertise concentrate in German industrial clusters and Japanese technical centers, anchoring innovation capacity for high-performance admixtures.
China
Shandong and Jiangsu provinces host bulk manufacturing of polycarboxylate ether superplasticizers and redispersible polymer powders. The Ministry of Ecology and Environment enforces GB standards on hazardous substance limits in construction materials. Tianjin and Shanghai serve as export hubs where domestic producers supply regional blenders across Southeast Asia.
Germany
Ruhr industrial corridors and Bavarian chemical parks sustain Europe's densest concentration of construction chemical R&D. The EU Green Deal's embodied carbon thresholds now gate public infrastructure tenders, favoring suppliers with pre-certified environmental product declarations. Frankfurt and Stuttgart anchor specification authority for alliance-contracted megaprojects.
India
Mumbai, Delhi, and Bangalore municipal corporations specify high-performance admixtures for metro rail and flood-resilient housing stock. The Bureau of Indian Standards mandates IS 9103 conformance for concrete admixture performance. Gujarat and Maharashtra industrial zones attract capacity expansion from multinational formulators seeking proximity to smart city infrastructure pipelines.
United States
State DOTs displace conventional bitumen with SBS-modified and EVA-modified binders to extend highway resurfacing intervals. The EPA regulates volatile organic compound emissions from coating applications. Texas and California infrastructure budgets channel the largest admixture volumes for commercial high-rise and transportation projects.
United Arab Emirates
Dubai and Abu Dhabi developers specify crystalline waterproofing systems for below-grade construction in coastal flood-risk zones. MOHAP oversees construction material safety standards for building envelope applications. Jebel Ali industrial zones concentrate blending capacity serving Gulf Cooperation Council megaproject pipelines.
Global Construction Chemical Market Competitive Landscape
The competitive structure tilts toward vertically integrated polymer suppliers with captive raw material positions. Tier-one specialists with in-house superplasticizer synthesis coexist alongside regional blenders dependent on imported powder intermediates. Two strategic archetypes dominate: diversified chemical conglomerates leveraging backward integration into petrochemical feedstocks, and focused admixture specialists competing on formulation service intensity. Capacity expansion and environmental product declaration pre-certification represent the dominant competitive moves as EU procurement gates tighten.
Among Swiss-headquartered specialists, Sika AG exemplifies the integrated polymer supply archetype. BASF SE anchors the diversified chemical conglomerate tier with German corporate roots. MAPEI S.p.A. occupies a position within the Mediterranean-focused formulation specialist segment.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Henkel AG & Co. KGaA |
| MAPEI S.p.A. |
| RPM International Inc. |
| Arkema SA |
| Fosroc International Limited |
| Ashland Global Holdings Inc. |
| Evonik Industries |
| Others |
Supply & Pricing Matrix
Formulation chemists with polycarboxylate ether expertise concentrate in German industrial clusters and Japanese technical centers, anchoring labor-cost differentials that widen pricing-tier spreads between premium superplasticizer formulations and commodity-blended alternatives. These regional skill premiums compress margins for regional blenders dependent on imported powder intermediates while rewarding vertically integrated suppliers with captive technical staff.
Pricing Analysis
Bundled technical service contracts separate premium-tier suppliers from unbundled commodity transactions in spot markets. Three-tier pricing structure across premium, standard, and economy levels reflects EPD certification status and polymer synthesis depth as primary differentiation drivers. Price erosion runs through economy-tier concrete admixtures as Chinese powder exports flood Southeast Asian blending operations. General contractors demonstrate highest price sensitivity through digital procurement platforms, while specialty waterproofing applicators absorb premium markups for application-critical crystalline systems.
Supply Chain Analysis
Single-source vulnerability sits with Shandong and Jiangsu provinces for bulk polycarboxylate ether superplasticizers and redispersible polymer powders. Raw material flows draw from ethylene-vinyl acetate feedstocks tethered to crude oil benchmarks and styrene-butadiene rubber anchored in petrochemical complexes. Tariff exposure on Chinese chemical exports threatens margin stability for European formulators lacking backward integration. Distribution runs through regional blending facilities serving ready-mix concrete plants and precast yards, with direct-to-contractor digital channels disintermediating traditional distributor networks for standardized repair mortar SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Construction Chemical Market functions as a regulatory compounder where EU Green Deal embodied carbon thresholds are restructuring procurement gatekeeping across public infrastructure tenders. This regulatory milestone concentrates specification authority and redirects volume toward pre-certified low-carbon admixture suppliers.
For Market Incumbents: Deploy EPD pre-certification investments to lock in EU public procurement qualification ahead of cascading carbon disclosure rules from the CSRD. Sika AG and BASF SE anchor positions through backward integration into polymer synthesis and R&D intensity in polycarboxylate ether systems, but geopolymer cement substitution threatens Portland-based admixture volumes. Capacity addition in Gujarat and Maharashtra industrial zones captures proximity to India's smart city infrastructure pipelines while defending against formulation chemist scarcity concentrated among retiring European and Japanese specialists. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable channel wedge for standardized tile adhesive and repair mortar SKUs where brand loyalty remains undeveloped. Carbon-capture concrete admixtures converging with voluntary carbon credit markets present white-space opportunity for mineralization technology specialists. Target Mumbai, Delhi, and Bangalore municipal corporations specifying high-performance admixtures for metro rail and flood-resilient housing stock, leveraging technical service intensity to differentiate against commodity powder blenders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders dependent on imported Chinese powder intermediates, vulnerable to petrochemical feedstock volatility and single-source supply concentration. Long-term viability over the next decade hinges on securing captive polymer synthesis capacity or proprietary formulation expertise in rheology modification. Watch EPD certification timelines extending 12-18 months under ISO 14025 protocols as the inflection signal for qualification bottlenecks in EU public procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Pre-Certification Investment | ISO 14025 verification gates EU Green Deal public tender eligibility for low-carbon admixture suppliers. |
| Backward Integration into Polymer Synthesis | Captive ethylene-vinyl acetate production insulates margin predictability from crude oil benchmark swings. |
| Capacity Expansion in Gujarat Industrial Zones | Proximity to Mumbai and Delhi smart city pipelines captures specification authority for high-performance admixtures. |
| Direct-to-Contractor Digital Platform Launch | E-procurement channels disintermediate distributor networks for standardized repair mortar and tile adhesive SKUs. |
| Carbon-Capture Admixture Development | Mineralization technologies sequestering CO2 during curing converge with voluntary carbon credit markets for premium pricing. |
Research Methodology
Bottom-up ready-mix and precast concrete modeling reconciled against top-down polymer feedstock tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement leads at multinational contractors, distribution channel partners, and technical R&D directors at admixture suppliers combined with secondary validation from customs and trade data, SEC 10-K filings, Bureau of Indian Standards conformance records, and EU CSRD disclosure frameworks. Triangulation across these sources anchors volume and value estimates.
Input-output matrices mapping polycarboxylate ether consumption to ready-mix concrete production across China's megacity infrastructure corridors and India's smart city pipelines structure the forecast framework. Segmentation dimensions span product type, polymer architecture, application exposure, and end-user procurement sophistication across the projection horizon. CAGRs derive from regression analysis against highway infrastructure budgets, below-grade construction permits in flood-prone coastal cities, and polymer-modified asphalt substitution rates.
Revisions become necessary when EU member states accelerate embodied carbon threshold enforcement, when Chinese environmental regulators tighten GB standards on hazardous substance limits, or when geopolymer cement displacement accelerates beyond precast into ready-mix applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
United Kingdom Methanol Market
Chemicals
Global Chiral Chemicals Market
Chemicals
N-Propanol Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Aluminum Phosphide Market
Chemicals
Cyclopentylamine Market
Chemicals
De-Icing Agents Market
Chemicals
Guaiacol Market
Chemicals
Cumene Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Household Insecticides Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Global Syringaldehyde Market
Chemicals
Italy Laboratory Chemicals Market