
 Paraphenylenediamine (PPD) Market | 2026-2036
Paraphenylenediamine (PPD) Market Size, Share, and Industry Trends Forecast 2026-2036
Paraphenylenediamine (PPD) Market Analytics
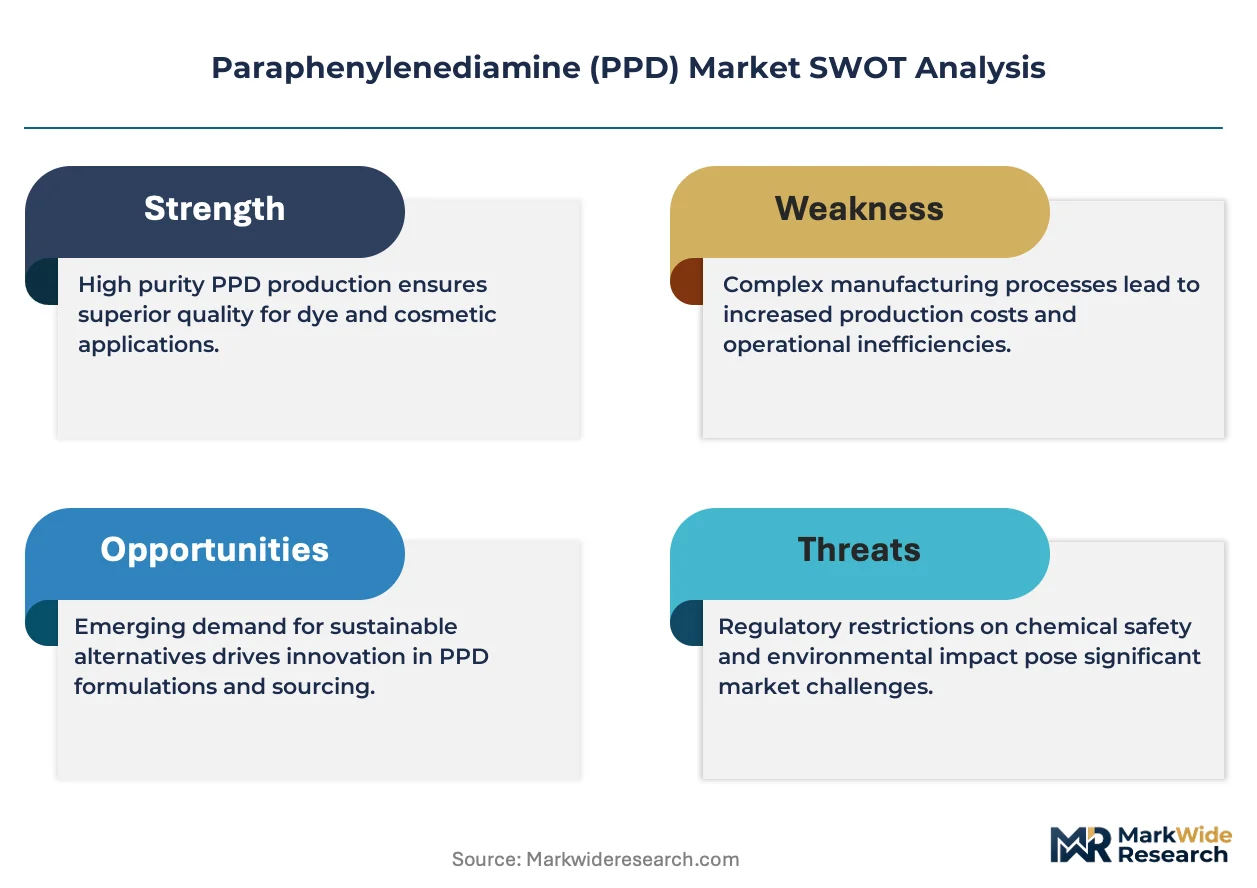
Software-defined color matching and digital shade libraries are expanding how dye suppliers monetize PPD-based formulations. DuPont de Nemours Inc. leverages its polymer science heritage to develop controlled-release PPD systems for reduced skin sensitization. Lanxess AG anchors European supply through its specialty chemicals infrastructure and REACH-compliant production protocols. Zhejiang Longsheng Group dominates Asian dye intermediate output through backward integration into nitrobenzene and aniline feedstocks.
Paraphenylenediamine is an aromatic diamine with the molecular formula C₆H₈N₂, synthesized primarily through catalytic hydrogenation of p-nitroaniline or reduction of p-dinitrobenzene, and functions as a critical oxidative coupling agent in permanent hair colorants and polyurethane curing systems. The hair dyes product category leads value generation due to premium consumer willingness to pay for gray coverage and fashion shades, while industrial dyes sustain volume throughput from textile manufacturing clusters. Paints and coatings applications represent the fastest-growing application segment as automotive OEMs adopt high-performance polyurea coatings for corrosion resistance. Powder form dominates industrial procurement due to extended shelf stability and precise dosing in automated batching systems.
EPA oversees PPD under the Toxic Substances Control Act, requiring pre-manufacture notifications for new chemical modifications, while ECHA classifies PPD as a skin sensitizer under REACH restriction proposals, directly limiting concentrations in cosmetic formulations. China's MEE enforces wastewater discharge standards on aniline derivative plants, elevating compliance costs for domestic producers. Stakeholders must monitor evolving dermatological safety thresholds and regional substitution mandates for p-aminophenol alternatives.
Market Dynamics
REACH restriction proposals on skin sensitizers are compressing permissible PPD concentrations in cosmetic formulations, forcing reformulation cycles across European hair dye manufacturers while simultaneously elevating compliance costs for Asian exporters serving EU markets.
Growth Catalysts
- Gray coverage demand:Aging demographics in Germany and Japan sustain premium hair colorant consumption, with salon-grade oxidative dyes commanding sustained volume commitments from professional beauty distributors.
- REACH-compliant production:Specialty chemical infrastructure investments in Belgium and the Netherlands enable continued EU market access for purified PPD grades, preserving revenue streams for compliant suppliers.
- Polyurea coatings adoption:Automotive OEMs in Michigan and Stuttgart deploy high-performance corrosion-resistant finishes, expanding PPD-derived curing agent consumption in protective coating systems.
Market Restraints
- Aniline feedstock volatility:Nitrobenzene price swings tied to benzene naphtha spreads compress margin predictability for PPD manufacturers dependent on petrochemical value chains.
- Substitution pressure:p-Aminophenol alternatives gain traction in semi-permanent dye formulations, threatening volume displacement in consumer hair colorant segments.
- Concentrated Asian supply:Zhejiang and Jiangsu provinces control over 60% of global dye intermediate output, creating geographic vulnerability for European and North American formulators.
Strategic Opportunities
- Controlled-release systems:Encapsulation technologies reducing dermal penetration open premium positioning for hypoallergenic hair dye lines targeting sensitized consumer cohorts.
- Indian manufacturing expansion:Gujarat and Maharashtra chemical corridors offer cost-competitive production bases with improving environmental compliance infrastructure for export-oriented PPD plants.
- Digital shade matching:AI-driven color formulation platforms enable dye suppliers to monetize precision PPD dosing as a subscription service to salon chains.
Industry Challenges
- Toxicologist recruitment:Dermal safety assessment expertise scarcity delays reformulation timelines for brands navigating ECHA restriction compliance.
- Legacy batch system integration:Automated powder dosing equipment requires capital retrofitting at mid-scale dye houses, creating competitive asymmetry against integrated majors.
- Cross-border waste discharge:MEE wastewater standards for aniline derivatives impose treatment cost burdens on Chinese producers serving export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraphenylenediamine (PPD) Market |
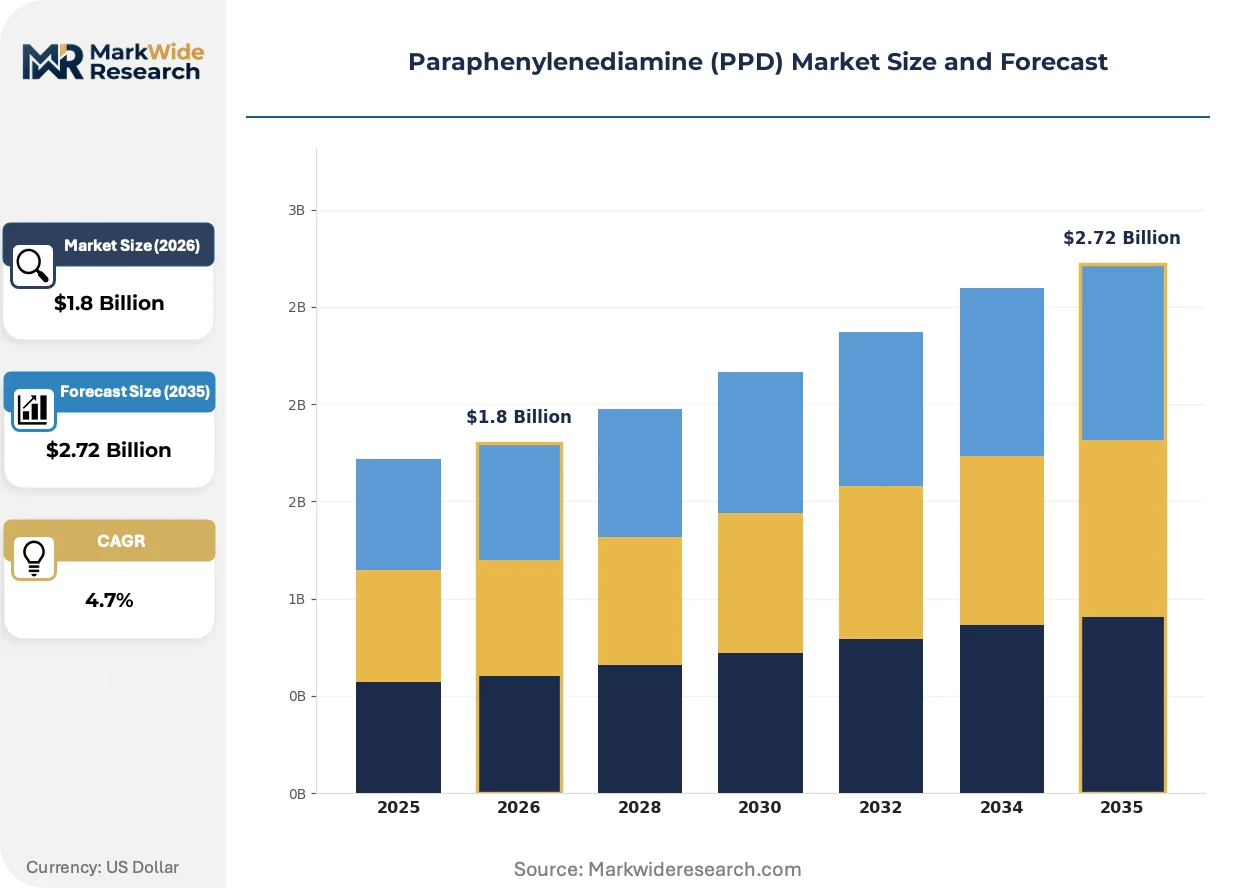
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dyes, Textile Dyes, Industrial Dyes, Cosmetics Application: Personal Care, Textile Manufacturing, Paints & Coatings, Printing Inks End Use Industry: Cosmetic, Textile, Automotive, Electronics Form: Liquid, Powder, Gel, Granule |
| Companies Covered | DuPont de Nemours Inc., Lanxess AG, Chizhou Fangda Science and Technology Co., Ltd., Zhejiang Longsheng Group, Chemstar, Jay Organics, Alxa League Lixin Chemical, BASF, Aarti Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraphenylenediamine (PPD) Market Evolving Landscape
Software-defined manufacturing and precision dosing technologies are redrawing competitive boundaries between commodity intermediate suppliers and formulation-integrated service providers.
Microencapsulation technology is decentralizing PPD delivery architecture in cosmetic applications. Shell-core particle systems isolate the oxidative coupler until activation, enabling beauty brands to market reduced-sensitivity claims. L'Oréal and Henkel pilot lines in France and Germany are scaling these systems for 2025 salon launches. This decentralization of risk management from raw material specification to delivery mechanism is compressing traditional purity-based pricing premiums.
ECHA's proposed Annex XVII restriction on skin sensitizers in rinse-off and leave-on products is forcing concentration caps below current industry standards. The regulation triggers reformulation investments exceeding €50 million across European hair dye portfolios. Professional salon channels face the steepest compliance burden, as consumer retail lines pivot faster to pre-mixed, lower-PPD alternatives.
Direct-to-salon distribution platforms are disintermediating regional chemical distributors in North American professional beauty markets. Schwarzkopf and Wella parent entities now ship concentrated oxidative dye bases directly to licensed stylists, bypassing wholesale markups. This channel compression is most visible in California and Texas metropolitan corridors, where consolidated salon chains negotiate volume contracts bypassing traditional procurement hierarchies.
Paraphenylenediamine (PPD) Market Segmentation
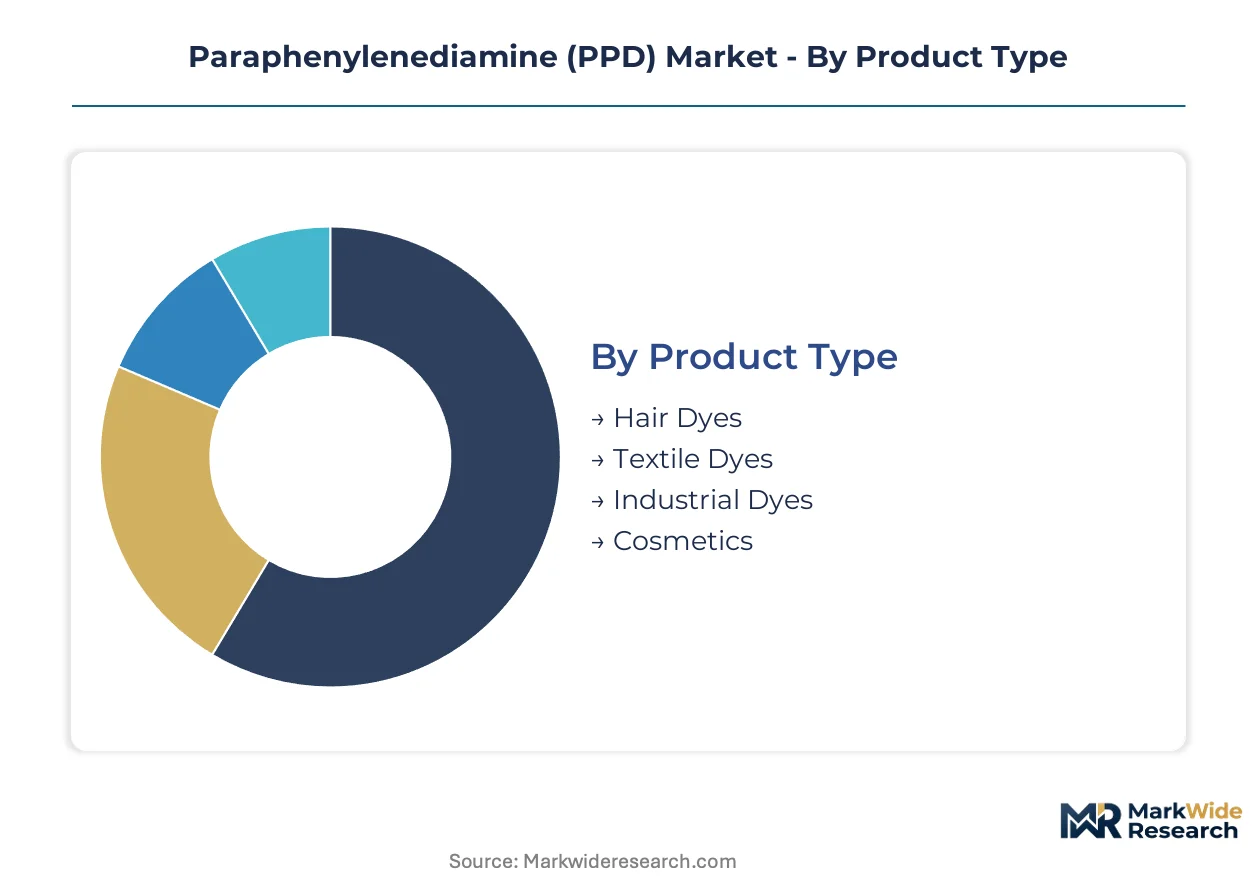
PPD's functional versatility across oxidative coupling, polyurethane curing, and colorant applications creates distinct value pools. Each segment carries unique purity specifications, regulatory thresholds, and customer procurement patterns that shape supplier positioning.
Product Type:
Technical grade differentiation separates cosmetic-grade from industrial-grade specifications, with purity thresholds determining addressable end-use markets.
- Hair Dyes:Cosmetic-grade PPD at 99.5%+ purity serves oxidative coupling in permanent colorants. Gray coverage demand in Germany and Japan sustains premium procurement contracts from salon distributors. REACH concentration caps force reformulation investments across European portfolios.
- Textile Dyes:Intermediate purity grades (98-99%) feed azo dye synthesis for polyester and cotton substrates. Zhejiang province manufacturing clusters absorb volume throughput through backward integration into aniline feedstocks.
- Industrial Dyes:Standard grades serve leather tanning and paper coloring applications with lower sensitivity thresholds.
- Cosmetics:Ultra-pure grades (<100 ppm heavy metals) comply with EU 1223/2009 cosmetic regulation for direct skin contact formulations.
Hair Dyes leads on scale; Cosmetics leads on momentum.
Application:
End-use performance requirements range from dermal safety in personal contact to chemical resistance in protective coatings.
- Personal Care:Hair colorants and cosmetic formulations demand batch-level toxicological documentation. ECHA skin sensitizer classifications compress permissible concentrations, triggering substitution trials with p-aminophenol alternatives.
- Textile Manufacturing:Fiber dyeing and printing operations consume volume grades through automated dosing systems. Gujarat chemical corridors in India expand capacity to serve export-oriented garment producers.
- Paints & Coatings:Polyurea curing agents for automotive corrosion protection command specification-grade premiums. Stuttgart and Michigan OEMs specify high-performance finishes with PPD-derived hardeners.
- Printing Inks:Pigment dispersion applications utilize lower-purity grades for packaging and publication substrates.
Textile Manufacturing dominates volume absorption; Paints & Coatings shows steepest expansion trajectory.
End Use Industry:
Customer procurement sophistication spans from beauty brand toxicological audits to automotive tier-one specification lock-ins.
- Cosmetic:L'Oréal and Henkel parent entities enforce supplier qualification protocols exceeding baseline REACH compliance. Microencapsulation pilots in France and Germany shift value capture toward delivery mechanism innovation.
- Textile:Integrated dye houses in Jiangsu province leverage captive nitrobenzene capacity to compress intermediate costs. MEE wastewater discharge standards elevate treatment capital burdens.
- Automotive:OEM specification systems lock in curing agent suppliers through multi-year coating platform approvals.
- Electronics:Printed circuit board and semiconductor packaging applications utilize high-purity grades for specialized polymer systems.
Cosmetic commands specification premiums; Automotive locks in longest contract tenures.
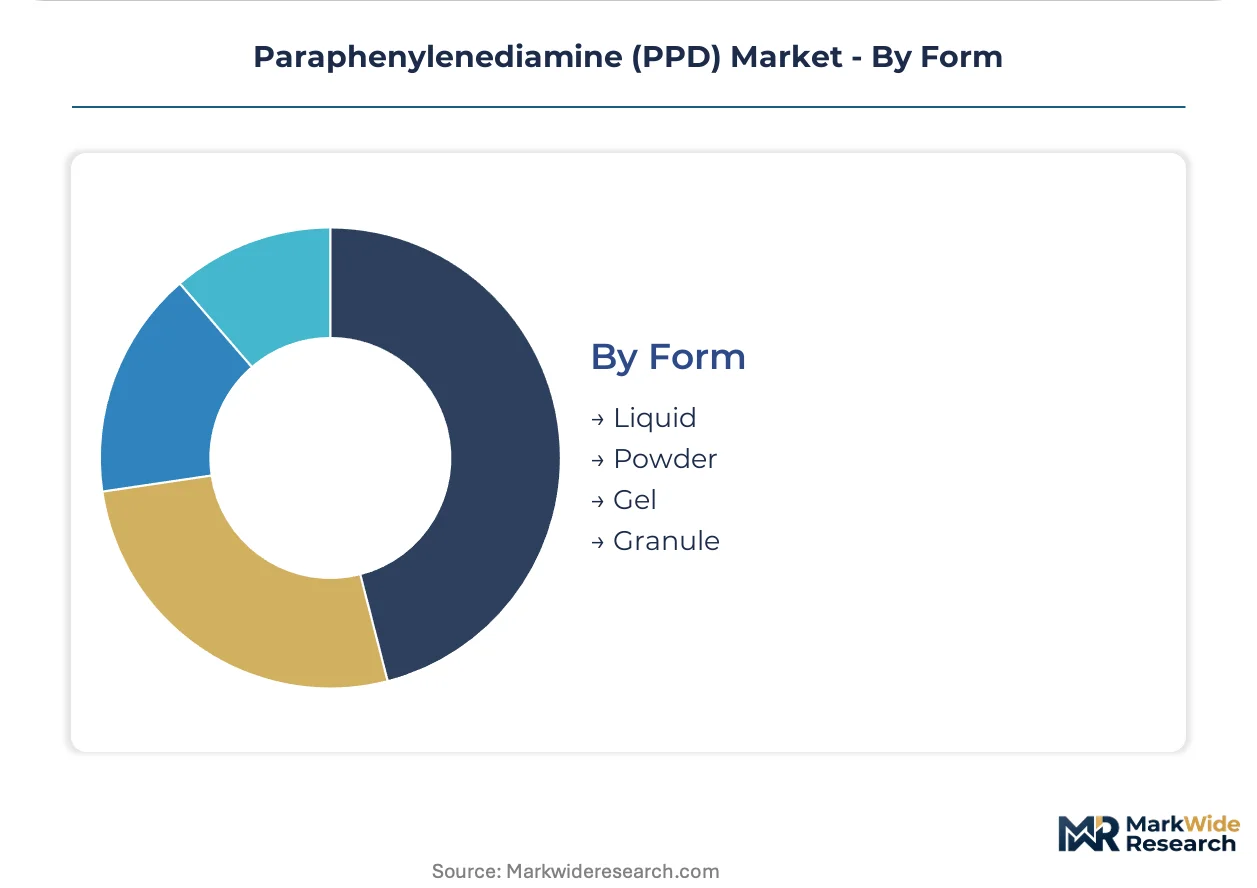
Form:
Physical state determines handling infrastructure, shelf stability, and dosing precision across customer operations.
- Liquid:Pre-dissolved solutions enable direct metered addition in continuous dyeing lines. California and Texas salon chains prefer concentrate formats for direct-to-stylist distribution models.
- Powder:Crystalline form dominates industrial procurement with extended storage stability and precise gravimetric dosing in automated batching systems.
- Gel:Viscous suspensions target professional beauty channels with reduced dust exposure during handling.
- Granule:Agglomerated particles balance flowability with reduced caking in humid climates.
Powder leads on industrial adoption; Liquid gains share fastest in professional beauty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates PPD manufacturing throughput while Germany sustains the strictest purity requirements for cosmetic-grade imports, creating divergent compliance burdens across supplier bases.
China
Zhejiang and Jiangsu provinces absorb over sixty percent of global dye intermediate output through captive nitrobenzene and aniline production. MEE wastewater discharge standards for aniline derivatives impose treatment capital burdens on export-oriented plants. The Yangtze River Delta chemical corridor concentrates backward-integrated PPD capacity serving textile and hair dye formulators.
Germany
Stuttgart automotive OEMs specify PPD-derived polyurea curing agents for corrosion-resistant coating platforms. ECHA REACH restriction proposals on skin sensitizers force reformulation investments exceeding fifty million euros across domestic hair dye portfolios. The North Rhine-Westphalia specialty chemicals belt anchors EU-compliant production infrastructure for purified grades.
United States
Michigan automotive assembly plants drive specification-grade demand for high-performance coating hardeners. EPA Toxic Substances Control Act oversight requires pre-manufacture notifications for modified PPD chemistries. California and Texas metropolitan salon chains accelerate direct-to-stylist distribution models for concentrated oxidative dye bases.
India
Gujarat and Maharashtra chemical corridors expand cost-competitive PPD capacity with improving environmental compliance infrastructure. BIS certification requirements for chemical intermediates shape export qualification protocols. The Mumbai-Pune industrial belt attracts dye intermediate investments targeting European and North American cosmetic formulators.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas sustain premium salon-grade oxidative dye consumption for gray coverage. METI chemical substance management frameworks align with REACH-equivalent safety thresholds for cosmetic applications. The Kansai region hosts formulation R&D facilities piloting microencapsulation technologies for reduced-sensitivity hair colorants.
Paraphenylenediamine (PPD) Market Competitive Landscape
Top-tier vendors anchor integrated specialty chemical platforms, while mid-scale regional producers compete on feedstock proximity and batch flexibility. The vendor base stratifies across three tiers: multinational chemical conglomerates with REACH-compliant infrastructure, Asian dye intermediate specialists with captive aniline supply, and regional formulators serving localized beauty markets. Two dominant competitive moves define current positioning: backward integration into nitrobenzene feedstocks to compress intermediate costs, and encapsulation technology licensing to capture premium positioning in hypoallergenic cosmetic lines.
Within the multinational tier, DuPont de Nemours Inc. and Lanxess AG occupy positions defined by polymer science heritage and European regulatory compliance infrastructure. Zhejiang Longsheng Group exemplifies the Asian specialist archetype through its dominance of nitrobenzene-to-dye-intermediate integration. These three entities collectively represent the structural poles of the competitive landscape: REACH-compliant Western supply, scale-driven Asian manufacturing, and technology-differentiated formulation services.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| Lanxess AG |
| Chizhou Fangda Science and Technology Co., Ltd. |
| Zhejiang Longsheng Group |
| Chemstar |
| Jay Organics |
| Alxa League Lixin Chemical |
| BASF |
| Aarti Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Captive nitrobenzene-to-aniline integration in Zhejiang and Jiangsu provinces anchors both supply security and pricing power for Asian PPD manufacturers serving export markets. This upstream control compresses feedstock cost volatility while enabling volume-based price aggression against European specialty chemical competitors facing REACH compliance burdens.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for technical-grade PPD serving textile dye formulators. Three-tier pricing structure across cosmetic-grade, industrial-grade, and technical-grade purity levels separates premium REACH-compliant supply from standard Asian export grades. Price differentiation hinges on ECHA skin sensitizer certification and volume scale commitments from automotive OEM coating programs. Cost compression in industrial grades is intensifying because of nitrobenzene feedstock volatility tied to benzene-naphtha spreads. Small-batch cosmetic formulators exhibit highest price sensitivity; automotive tier-one suppliers show least sensitivity due to specification lock-ins.
Supply Chain Analysis
Skilled toxicologist and process chemist availability in Germany and Belgium underpins REACH-compliant purification capacity. Supply concentrates in China, India, and Germany, with Zhejiang province controlling captive aniline feedstock production. PPD manufacturing draws from nitrobenzene, aniline, and hydrogen feedstocks. Single-source vulnerability runs through concentrated Zhejiang intermediate output. Distribution runs through direct-to-salon platforms in North America and specialty chemical distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA's proposed Annex XVII skin sensitizer restrictions force sustained reformulation investment cycles across European cosmetic portfolios.
For Market Incumbents: Lock in multi-year coating platform approvals with Stuttgart and Michigan automotive OEMs before specification windows close. Deepen backward integration into nitrobenzene feedstocks in Zhejiang to defend margin position against Indian capacity additions. Prioritize microencapsulation R&D licensing to capture premium positioning as p-aminophenol substitution pressure intensifies in hair dye formulations. For New Entrants and Emerging Players: Mid-scale Indian cosmetic formulators seeking REACH-compliant PPD grades represent an underserved buyer archetype bypassed by multinational distributors. Gujarat chemical corridors offer lowest-cost production bases with improving environmental compliance infrastructure. Target direct-to-salon distribution partnerships in California and Texas metropolitan markets to bypass entrenched wholesale hierarchies. For Investors and Strategic Acquirers: Roll-up economics work for European REACH-compliant specialty chemical assets because ECHA concentration caps create insurmountable compliance barriers for new entrants. Five-to-ten year viability hinges on backward-integrated Asian producers acquiring toxicological documentation capabilities. Monitor ECHA restriction proposal implementation timelines as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Zhejiang producers compress intermediate costs through captive aniline feedstock supply. |
| Microencapsulation Technology Licensing | L'Oréal and Henkel pilots in France validate reduced-sensitivity delivery systems for salon launch. |
| REACH-Compliant Capacity Expansion | Belgium and Netherlands infrastructure investments preserve EU market access for purified grades. |
| Direct-to-Salon Distribution Platform | Schwarzkopf and Wella parent entities bypass wholesale markups in California and Texas corridors. |
| Gujarat Manufacturing Footprint | Maharashtra chemical corridors attract export-oriented investments targeting European cosmetic formulators. |
Research Methodology
Direct dialogue with plant managers at nitrobenzene facilities, procurement leads at downstream dye houses, REACH compliance officers, and salon distribution channel partners grounded qualitative assessment. Secondary validation drew from ECHA restriction proposal documentation, MEE wastewater discharge standards, customs trade data for aniline derivatives, and SEC filings from listed chemical conglomerates. Bottom-up and top-down triangulation cross-checked capacity announcements against import-export flow patterns.
Bottom-up modeling aggregated segment-level volume assumptions across hair dye, textile, and coating applications; top-down analysis cross-referenced against aggregate chemical intermediate consumption trends. Segmentation dimensions included purity grade tier, end-use industry, physical form, and regional production hub. CAGRs were derived from slope analysis of historical consumption patterns adjusted for regulatory intervention timelines. Forecast inputs incorporated automotive OEM coating specification cycles and salon channel inventory dynamics.
Underlying measurement precision varies by segment; cosmetic-grade PPD carries tighter precision than industrial dye intermediates given toxicological documentation requirements. Forecasts reflect assumptions about ECHA restriction implementation timelines and MEE enforcement intensity. Material deviation in benzene-naphtha spreads or ECHA concentration cap finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Pyrimidine Market
Chemicals
Acetic Ether Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Methylamines Market
Chemicals
Lime Sulfur Market
Chemicals
Nonaisoprenol Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Detergent Alcohols Market
Chemicals
Isopropanolamine Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Copper Oxychloride Market
Chemicals
Natural Fatty Alcohols Market