
 Egypt Acidulants Market | 2026-2036
Egypt Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Acidulants Market Foresight
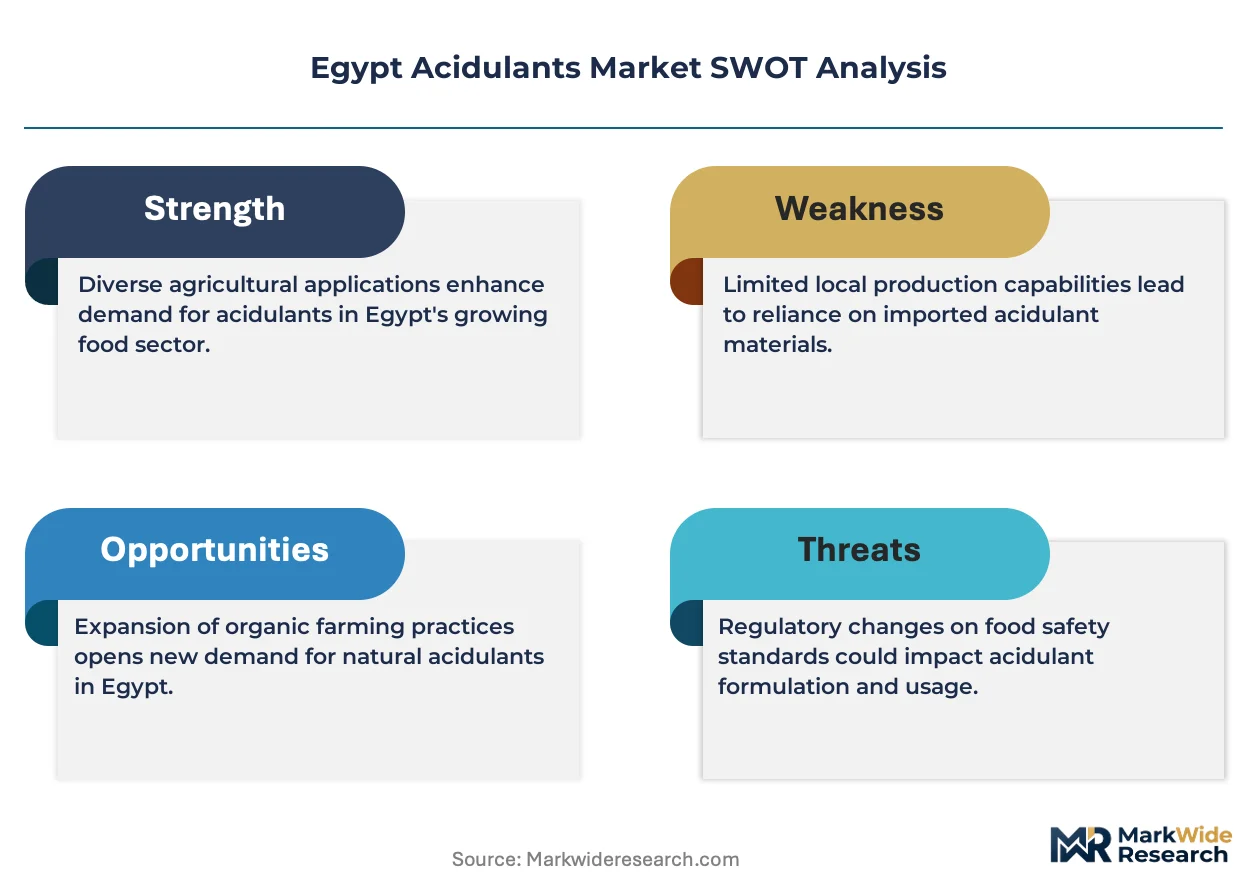
Clean-label fermentation technology is reshaping how acidulants are produced for Egyptian food processors. Cargill Incorporated leverages its biotechnology platforms to supply citric acid variants with reduced chemical processing residues. Tate & Lyle PLC anchors the premium acidulant segment through specialized buffer systems for carbonated beverages. El Badramany dominates local distribution networks, sustaining cost-competitive supply to mid-tier dairy manufacturers across Upper Egypt.
Acidulants are organic or inorganic compounds that impart tartness, control pH, and preserve shelf stability in formulated products, typically manufactured through submerged fermentation of carbohydrate substrates or chemical synthesis with purity grades ranging from food-grade to pharmaceutical-grade specifications. Citric acid leads Egyptian consumption by volume due to its versatility across soft drinks, jams, and confectionery, while lactic acid represents the fastest-expanding category as clean-label demand from food manufacturers intensifies. Phosphoric acid maintains entrenched positions in cola-type beverages though faces substitution pressure from malic acid in reduced-sugar formulations targeting health-conscious consumers.
Egypt's national food safety authority and the Egyptian Organization for Standardization enforce additive purity benchmarks aligned with Codex Alimentarius principles, compelling importers to submit batch certificates of analysis for acidulant shipments. The country's Ministry of Trade and Industry applies local content requirements to certain processed food categories, indirectly steering acidulant procurement toward suppliers with regional blending or repackaging facilities. Stakeholders must monitor evolving enforcement patterns around additive maximum limits and traceability documentation to preempt supply disruptions.
Market Dynamics
Clean-label fermentation technology is compressing traditional chemical synthesis margins across Egyptian acidulant supply chains, forcing processors to retool production lines or cede share to biotech-enabled competitors.
Growth Catalysts
- EFSA-aligned additive purity mandates:Egypt's national food safety authority now enforces Codex-aligned batch certification requirements, compelling importers to upgrade documentation systems and locking out informal suppliers.
- Carbonated beverage formulation intensity:Cairo-based soft drink manufacturers are expanding production capacity, pulling citric acid and phosphoric acid volumes through dedicated supply agreements with Delta-region distributors.
- Clean-label lactic acid fermentation:Dairy processors in Alexandria and Giza are substituting synthetic acidulants with fermentation-derived alternatives to meet retailer clean-label specifications.
Market Restraints
- Molasses feedstock price volatility:Submerged fermentation of citric acid depends on sugar beet molasses subject to Egyptian agricultural subsidy fluctuations and import parity pricing swings.
- Import concentration in Port Said and Alexandria:Over 70% of acidulant shipments clear through two customs zones, creating bottleneck exposure during inspection backlogs or foreign exchange clearance delays.
- Phosphoric acid substitution pressure:Malic acid and citric acid blends are displacing orthophosphoric acid in reduced-sugar cola formulations, eroding entrenched supplier positions.
Strategic Opportunities
- Upper Egypt dairy corridor penetration:Minya and Assiut governorates host underdeveloped processed cheese and yogurt manufacturing clusters with minimal local acidulant blending capacity.
- Biotech-accelerated fermentation platforms:CRISPR-enhanced Aspergillus niger strains are cutting citric acid production cycles by 30%, enabling cost-competitive supply to mid-tier Egyptian food processors.
- Direct-to-processor digital procurement:B2B platforms are disintermediating traditional Cairo-based chemical distributors, allowing manufacturers in 10th of Ramadan City to source acidulants with real-time price transparency.
Industry Challenges
- Fermentation technician scarcity:Egyptian universities produce insufficient industrial microbiologists trained in submerged culture optimization, forcing processors to recruit from pharmaceutical sectors at premium wages.
- EFSA batch certification timeline compression:Import clearance now requires 14-21 additional days for additive purity verification, straining just-in-time inventory systems at beverage bottling plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Acidulants Market |
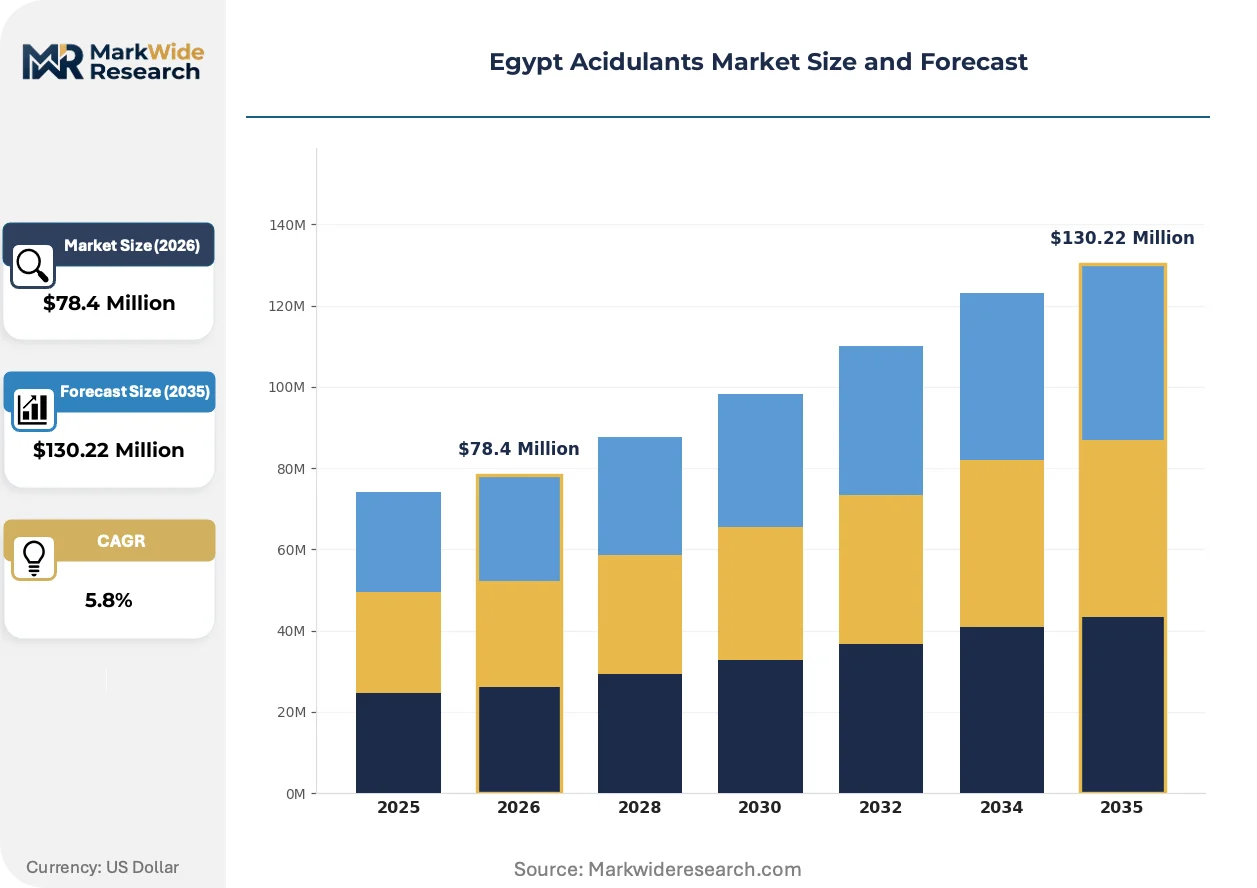
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Phosphoric Acid, Malic Acid Application: Food & Beverage, Pharmaceuticals, Personal Care, Agriculture Form: Liquid, Powder, Granular, Spray-Dried End User: Food Manufacturers, Cosmetic Companies, Nutraceuticals, Agricultural Distributors |
| Companies Covered | Tate & Lyle PLC, NAMAA Egypt, Archer Daniels Midland Company, Univar Solutions Inc, El Badramany, Cargill Incorporated, BASF SE, DuPont Nutrition & Biosciences, Brenntag AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Acidulants Market Shifts & Advancements
Fermentation biotechnology and digital supply chain tools are restructuring how Egyptian food manufacturers source, specify, and integrate acidulants into formulated products.
Precision fermentation using metabolically engineered yeast strains is virtualizing traditional citric acid manufacturing. Alexandria-based dairy and beverage processors are piloting these biocatalysts to reduce chemical processing residues in final formulations. The technology is virtualizing capital-intensive extraction infrastructure, enabling smaller Egyptian manufacturers to access pharmaceutical-grade acidulant purity without backward integration into fermentation assets.
Egypt's updated consumer protection standards now mandate front-of-pack additive disclosure aligned with Codex Alimentarius principles. This regulatory compression is forcing reformulation across processed juice and confectionery segments. Manufacturers in Greater Cairo are responding by accelerating clean-label acidulant substitutions ahead of enforcement phase-in deadlines.
Buyer concentration among Egyptian multinational beverage bottlers is compressing supplier negotiation cycles from annual to quarterly frameworks. Tier-1 processors in 6th of October City now demand dynamic pricing clauses tied to molasses futures indices. This behavioral shift is most visible in phosphoric acid procurement, where legacy distributors are losing share to integrated suppliers with captive fermentation and hedging capabilities.
Egypt Acidulants Market Segmentation
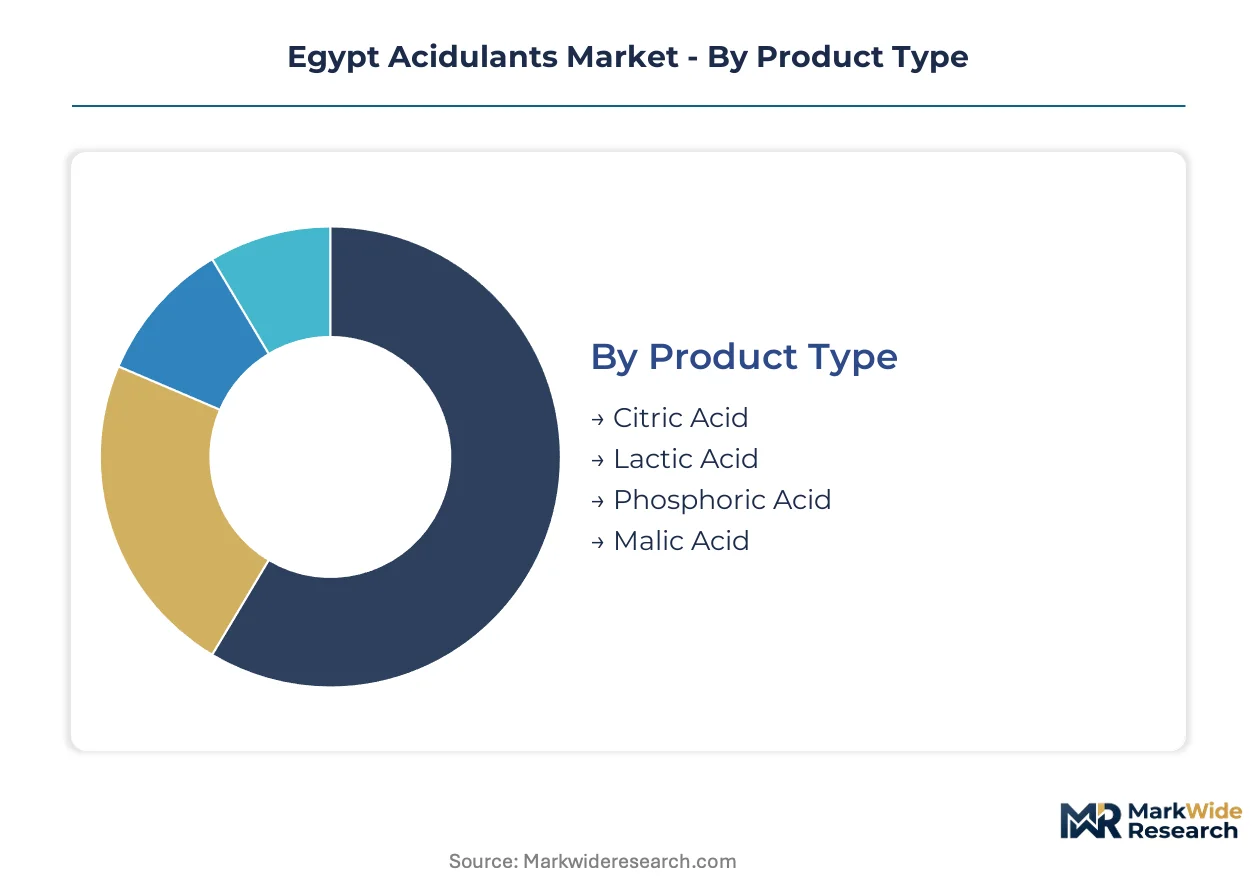
Acidulant procurement patterns across Egyptian food and industrial sectors fragment sharply by technical specification, application intensity, and downstream customer sophistication. Understanding these segment boundaries reveals where margin compression and substitution threats concentrate most acutely.
Product Type:
Mature commodity grades dominate volume flows while fermentation-derived alternatives reshape competitive positioning.
- Citric Acid:Manufactured through submerged fermentation of Aspergillus niger on carbohydrate substrates, this tricarboxylic acid delivers pH reduction and chelation across soft drinks, jams, and confectionery. Cairo-based bottlers in 6th of October City pull the heaviest volumes through dedicated supply agreements with Delta-region distributors.
- Lactic Acid:Fermentation-derived from Lactobacillus strains on sucrose or glucose, this alpha-hydroxy acid offers milder tartness and clean-label positioning. Dairy processors in Alexandria and Giza are accelerating substitution away from synthetic alternatives to meet retailer specifications.
- Phosphoric Acid:Orthophosphoric acid synthesized via wet-process phosphate rock treatment maintains entrenched positions in cola-type beverages.
- Malic Acid:Dicarboxylic acid from maleic anhydride hydration or fermentation routes displaces phosphoric acid in reduced-sugar formulations.
Citric acid handles the majority of throughput; lactic acid is the fastest mover on share.
Application:
End-use concentration varies dramatically by regulatory scrutiny and formulation complexity.
- Food & Beverage:Carbonated soft drinks, processed juices, dairy products, and confectionery absorb the dominant share of Egyptian acidulant consumption. Greater Cairo and Alexandria manufacturing clusters drive specification intensity.
- Pharmaceuticals:Buffer systems and excipient applications demand pharmaceutical-grade purity with EFSA-aligned batch certification.
- Personal Care:pH adjustment in cosmetics and toiletries represents a specialized niche with distinct purity requirements.
- Agriculture:Fertilizer and feed additive applications operate on cost-driven procurement with minimal specification differentiation.
Food and beverage commands absolute volume leadership; pharmaceuticals expands most quickly on specification premium capture.
Form:
Physical state selection tracks directly against handling infrastructure and dissolution kinetics requirements.
- Liquid:Ready-to-dose aqueous solutions eliminate dissolution steps at beverage bottling plants. 10th of Ramadan City processors favor liquid citric acid for continuous production lines.
- Powder:Free-flowing crystalline grades offer storage stability and precise metering for dry-blend applications. Confectionery manufacturers in Giza prefer powder forms for hard candy acid sanding.
- Granular:Intermediate particle size reduces dusting while maintaining rapid solubility.
- Spray-Dried:Agglomerated particles enhance flowability for automated handling systems.
Powder formats retain the broadest installed base; liquid forms are climbing the fastest on operational efficiency demands.
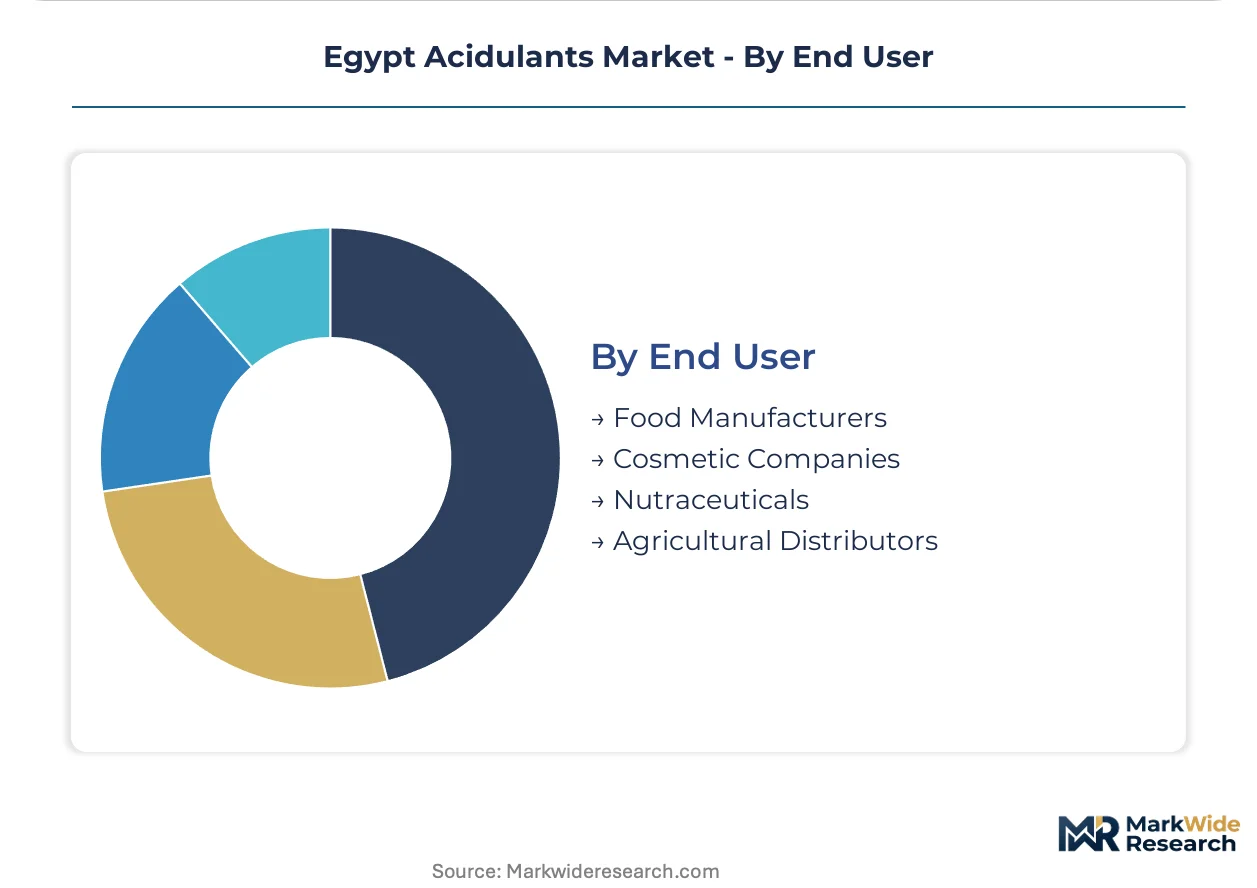
End User:
Customer sophistication tiers separate specification-heavy multinationals from price-sensitive regional processors.
- Food Manufacturers:Multinational bottlers and domestic dairy processors in Cairo, Alexandria, and Delta governorates anchor demand. These buyers enforce quarterly pricing frameworks and dynamic clauses tied to molasses futures indices.
- Cosmetic Companies:Personal care formulators in 10th of Ramadan City industrial zones require cosmetic-grade acidulants with enhanced heavy metal controls.
- Nutraceuticals:Dietary supplement manufacturers represent an emerging specification segment with pharmaceutical-grade purity demands.
- Agricultural Distributors:Bulk fertilizer blenders in Upper Egypt operate on minimal margin, prioritizing cost over technical service.
Food manufacturers absorb the dominant procurement volume; nutraceuticals shows the steepest expansion trajectory on health-product positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational beverage bottlers and domestic dairy processors in Greater Cairo, Alexandria, and the Nile Delta drive the majority of Egyptian acidulant procurement. These buyers enforce quarterly pricing frameworks and dynamic clauses tied to molasses futures indices. Geographic concentration creates distinct operational profiles across Egypt's major industrial corridors.
Greater Cairo
Carbonated soft drink manufacturers in 6th of October City and 10th of Ramadan City pull the heaviest citric acid and phosphoric acid volumes. Egypt's national food safety authority enforces EFSA-aligned batch certification requirements, compelling importers to upgrade documentation systems. Cairo-based processors favor liquid citric acid for continuous production lines.
Alexandria
Dairy processors in this Mediterranean port city are accelerating fermentation-derived lactic acid substitution to meet retailer clean-label specifications. The Egyptian Organization for Standardization mandates additive purity benchmarks aligned with Codex Alimentarius principles. Alexandria's industrial zones host cosmetic-grade acidulant demand from personal care formulators requiring enhanced heavy metal controls.
Nile Delta Governorates
Processed juice and confectionery manufacturers in Sharqia, Dakahlia, and Gharbia absorb significant powder-grade citric acid volumes. Local content requirements from the Ministry of Trade and Industry indirectly steer procurement toward suppliers with regional blending facilities. Delta-region distributors maintain dedicated supply agreements with Cairo-based bottlers.
Upper Egypt
Minya and Assiut governorates host underdeveloped processed cheese and yogurt manufacturing clusters with minimal local acidulant blending capacity. Molasses feedstock price volatility from sugar beet agricultural subsidy fluctuations particularly impacts this region's cost structure. El Badramany dominates distribution networks here, sustaining cost-competitive supply to mid-tier dairy manufacturers.
Egypt Acidulants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Egyptian acidulant supply chains. The market structures around three tiers: multinational biotechnology platforms with fermentation assets, regional distributors with customs clearance expertise, and local repackagers serving price-sensitive agricultural segments. Strategic moves concentrate on backward integration into molasses sourcing and digital procurement platform deployment.
Among biotechnology-enabled suppliers, Cargill Incorporated and Tate & Lyle PLC exemplify the premium-tier archetype through specialized buffer systems and reduced-chemical processing variants. El Badramany occupies a distinct position anchoring local distribution networks across Upper Egypt. These three represent contrasting competitive approaches: global fermentation platforms versus regional logistics control versus sub-regional cost positioning.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| NAMAA Egypt |
| Archer Daniels Midland Company |
| Univar Solutions Inc |
| El Badramany |
| Cargill Incorporated |
| BASF SE |
| DuPont Nutrition & Biosciences |
| Brenntag AG |
| Others |
Supply & Pricing Matrix
Chinese fermentation-grade citric acid capacity anchors Egyptian import pricing, compressing margin pools at Alexandria and Port Said customs clearance tiers while elevating returns for Delta-region distributors with captive blending operations. Molasses futures indexation in quarterly supply agreements transfers agricultural volatility directly to Cairo-based beverage bottlers.
Pricing Analysis
Cost-plus contracts with molasses futures indexation dominate procurement frameworks between Delta-region distributors and Greater Cairo bottlers. Price differentiation rests on EFSA-aligned batch certification grade and volume scale, with pharmaceutical-grade citric acid commanding substantial premiums over food-grade alternatives. Pricing pressure stems from malic acid substitution in reduced-sugar formulations, eroding phosphoric acid contract values. Mid-tier dairy manufacturers in Upper Egypt exhibit highest price sensitivity, while multinational beverage bottlers in 6th of October City prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and Egypt dominates supply chain risk calculus for acidulant importers. Manufacturing concentrates in China, Belgium, and Thailand, with fermentation assets drawing from sugar beet molasses, phosphate rock, and corn-derived glucose feedstocks. Single-source vulnerability concentrates in Port Said and Alexandria customs zones, where inspection backlogs cascade through just-in-time beverage production schedules. Distribution runs through Cairo-based chemical distributors with customs clearance expertise, though B2B platforms are disintermediating traditional channel tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational beverage bottlers in Greater Cairo and Alexandria, compressing supplier negotiation cycles and forcing acidulant vendors into quarterly pricing frameworks with dynamic indexation clauses.
For Market Incumbents: Harden fermentation technician retention through pharmaceutical-sector recruitment partnerships and captive training academies, as industrial microbiologist scarcity threatens production cycle optimization. Deepen backward integration into sugar beet molasses sourcing to offset Egyptian agricultural subsidy fluctuations and secure cost-competitive feedstock supply. For New Entrants and Emerging Players: Pursue direct-to-processor digital procurement platforms targeting 10th of Ramadan City manufacturers, disintermediating legacy Cairo distributors with real-time price transparency. White-space concentration sits in Upper Egypt dairy corridors, where Minya and Assiut processed cheese clusters lack local acidulant blending capacity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional distributors holding customs clearance expertise and Delta-region logistics networks. Long-term viability favors biotechnology platforms with CRISPR-enhanced fermentation capabilities over commodity chemical synthesis operations. Watch for EFSA enforcement phase-in deadlines as inflection indicators for clean-label acidulant substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Captive sugar beet supply hedges Egyptian agricultural subsidy volatility for fermentation operations. |
| CRISPR-Enhanced Fermentation Platform Deployment | Metabolically engineered Aspergillus niger strains cut citric acid production cycles by 30%. |
| EFSA-Aligned Batch Certification Investment | Pharmaceutical-grade purity capabilities unlock premium pricing from Alexandria dairy processors. |
| Direct-to-Processor Digital Procurement Launch | B2B platforms bypass Cairo distributor margins for 10th of Ramadan City manufacturers. |
| Upper Egypt Distribution Network Expansion | Minya and Assiut dairy corridor penetration captures underdeveloped processed cheese acidulant demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, EFSA regulatory filings, and Egyptian Organization for Standardization additive purity benchmarks. Primary interviews engaged fermentation plant managers, procurement leads at Cairo-based beverage bottlers, Delta-region distribution channel partners, and technical R&D directors at biotechnology platforms. Secondary sources included customs clearance records, Codex Alimentarius documentation, and Egyptian Ministry of Trade local content requirement circulars. Bottom-up volume modeling triangulated against top-down expenditure analysis across food and beverage, pharmaceutical, and agricultural end-use segments.
Forecast inputs span acidulant grade tier, end-use industry application intensity, packaging format preference, and regional production hub concentration across Greater Cairo, Alexandria, Nile Delta, and Upper Egypt corridors. CAGRs derived from segment-level growth trajectory analysis incorporating molasses feedstock price elasticity, EFSA enforcement intensity, and clean-label substitution velocity. Industry-specific inputs included fermentation technology adoption curves and digital procurement platform penetration rates among mid-tier manufacturers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fermentation platforms or accelerated EFSA certification timeline compression would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Pinoxaden Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Spirodiclofen Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Paint Remover Market
Chemicals
Paint Stripper Market
Chemicals
Betaine Market
Chemicals
Sodium Methoxide Market
Chemicals
Welding Chemicals Market
Chemicals
Etidronic Acid Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Deicing Fluid Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Hydrogen Fluoride Pyridine Market