
 Ferric Oxide Market | 2026-2036
Ferric Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Oxide Market Analysis
Chinese ferric oxide producers is rebalancing capacity toward higher-purity grades after environmental inspections tightened discharge limits. Huntsman International LLC leverages backward integration into titanium dioxide co-production to secure feedstock cost advantages. LANXESS AG anchors its European position through REACH-registered pigment lines with full traceability documentation. Cathay Industries competes from a Shanghai manufacturing base that supplies both domestic coatings formulators and export markets.
Ferric oxide, an iron(III) oxide with the chemical formula Fe₂O₃, occurs naturally as hematite or is synthesized through controlled precipitation and calcination routes yielding particle sizes from sub-micron to coarse granules. The material serves primarily as a colorant and UV stabilizer across paints, construction materials, and plastic compounds where opacity and thermal stability matter. Red iron oxide dominates product type revenue due to its prevalence in architectural coatings and concrete coloring, while nano grade formulations command premium positioning in cosmetics and specialty electronics applications. Micronized grade supply concentrates among European and Japanese producers who serve pharmaceutical tablet coating and food-contact plastics with tight particle distribution specifications.
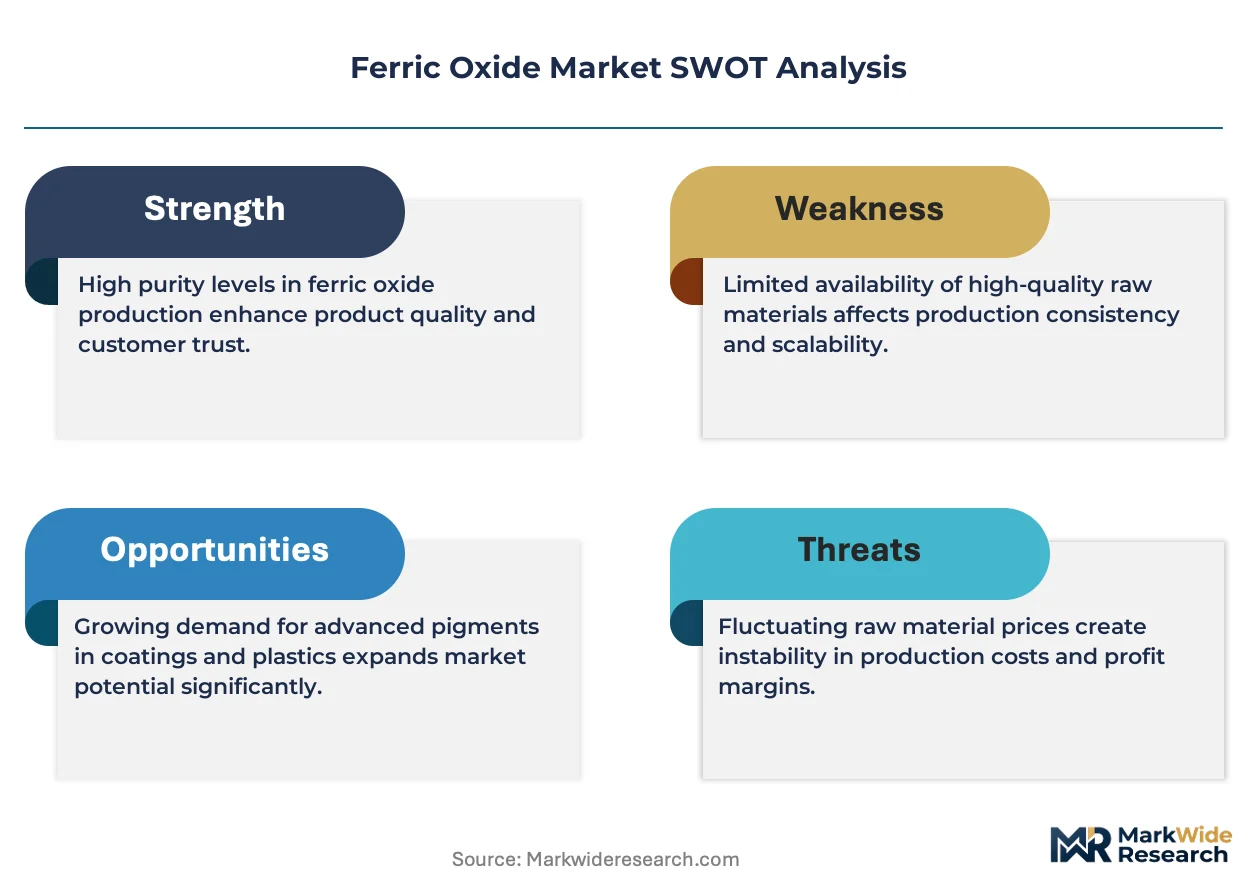
REACH registration requirements in Europe, administered by ECHA, mandate full toxicological dossiers for ferric oxide pigments used in consumer-facing coatings and cosmetics. The US EPA oversees air emissions from calcination furnaces under the National Emission Standards for Hazardous Air Pollutants, raising capital costs for domestic thermal processing expansions. China's MEE enforces wastewater discharge limits on hematite beneficiation and precipitation facilities in Hebei and Shandong provinces. Stakeholders must monitor how evolving purity standards in pharmaceutical and food-contact applications reshape grade premiums and supplier qualification timelines.
Market Dynamics
Environmental compliance tightening in China and Europe is forcing ferric oxide producers to reconfigure calcination and precipitation assets toward higher-purity output, compressing legacy capacity and redrawing supplier qualification timelines for coatings and cosmetics formulators.
Growth Catalysts
- Construction coatings demand:Architectural paint formulators in China and India are absorbing expanded red iron oxide volumes as urban housing stock and infrastructure investment accelerates.
- REACH registration requirements:ECHA-mandated toxicological dossiers for consumer-facing pigments are locking in qualified European suppliers and raising barriers to unregistered imports.
- Nano-grade synthesis advances:Controlled precipitation methods yielding sub-100 nanometer particles are opening cosmetic and electronics applications with premium pricing power.
Market Restraints
- Iron ore feedstock volatility:Hematite beneficiation costs fluctuate with seaborne iron ore pricing, squeezing margin stability for non-integrated pigment producers.
- Hebei-Shandong supply concentration:Environmental inspections concentrated in these two provinces periodically shutter precipitation capacity, injecting volume uncertainty into export markets.
- Titanium dioxide substitution:TiO₂ white pigments capture share in high-opacity architectural applications where ferric oxide red tones are not specification-critical.
Strategic Opportunities
- Pharmaceutical tablet coating:Micronized grades with tight particle distribution specifications remain underpenetrated by Chinese suppliers, leaving margin capture potential for European and Japanese producers.
- UV stabilization in plastics:Food-contact compliance certification for ferric oxide colorants is displacing heavy metal alternatives in European packaging regulations.
- Direct procurement platforms:Coatings formulators are bypassing distributor tiers to contract directly with precipitation facilities, compressing channel margins and accelerating qualification data exchange.
Industry Challenges
- Calcination furnace emissions compliance:US EPA NESHAP standards for hazardous air pollutants require continuous monitoring retrofits, extending capital deployment timelines for domestic thermal processing expansions.
- REACH dossier maintenance:ECHA substance evaluation cycles demand updated toxicological studies, consuming technical regulatory affairs bandwidth at mid-scale pigment houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Oxide Market |
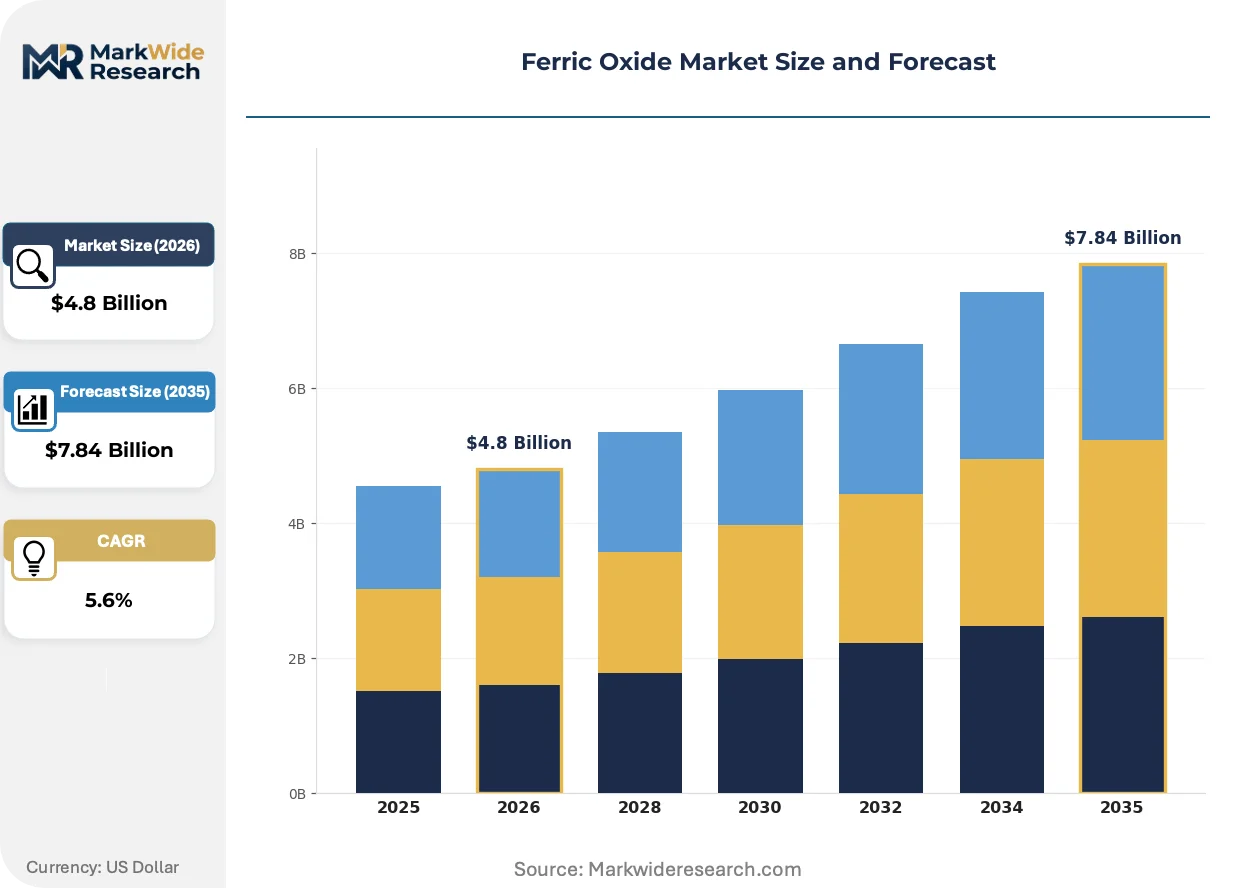
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Iron Oxide, Yellow Iron Oxide, Black Iron Oxide, Brown Iron Oxide Application: Coatings, Construction, Plastics, Cosmetics Grade: Commercial Grade, Micronized Grade, Nano Grade, Specialty Grade End User: Manufacturing, Chemicals, Paints & Coatings, Pharmaceuticals |
| Companies Covered | Huntsman International LLC, Kronos International, Inc., LANXESS AG, Applied Minerals Inc., Titan Kogyo, Ltd., BASF SE, Hunan Sanhuan Pigment Co., Ltd, Toda Kogyo Corporation, Cathay Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Oxide Market Emerging Trajectories
Particle engineering and regulatory data transparency are compressing traditional grade hierarchies, enabling synthetic precipitated oxides to capture share from natural hematite derivatives in performance-sensitive applications.
Surface-modified nano-ferric oxides with silane coupling agent treatments are overtaking uncoated precipitated grades in automotive refinish coatings, where dispersion stability and gloss retention determine formulation selection. Tier-one automotive paint suppliers in Germany and Japan have accelerated qualification of these engineered particles. The technology is overtaking legacy micronized natural oxides in premium segment specifications, compressing price premiums for basic precipitated material.
ECHA's 2023 updated guidance on nanomaterial registration obligations is extending dossier requirements to surface-treated ferric oxide particles below 100 nanometers. Pigment houses must now submit enhanced exposure assessments and lifecycle data for cosmetics and sunscreen applications. European cosmetic formulators are responding by consolidating supplier bases to pre-registered nano-grade sources with existing toxicological packages.
Coatings manufacturers are unbundling after-sales technical service from pigment procurement contracts, shifting to fee-based color matching and dispersion consulting. This pattern is most visible in North American architectural coatings, where formulators have built in-house application laboratories. The service unbundling is compressing traditional supplier value-added bundles and exposing bare pigment pricing to sharper procurement comparison.
Ferric Oxide Market Segmentation
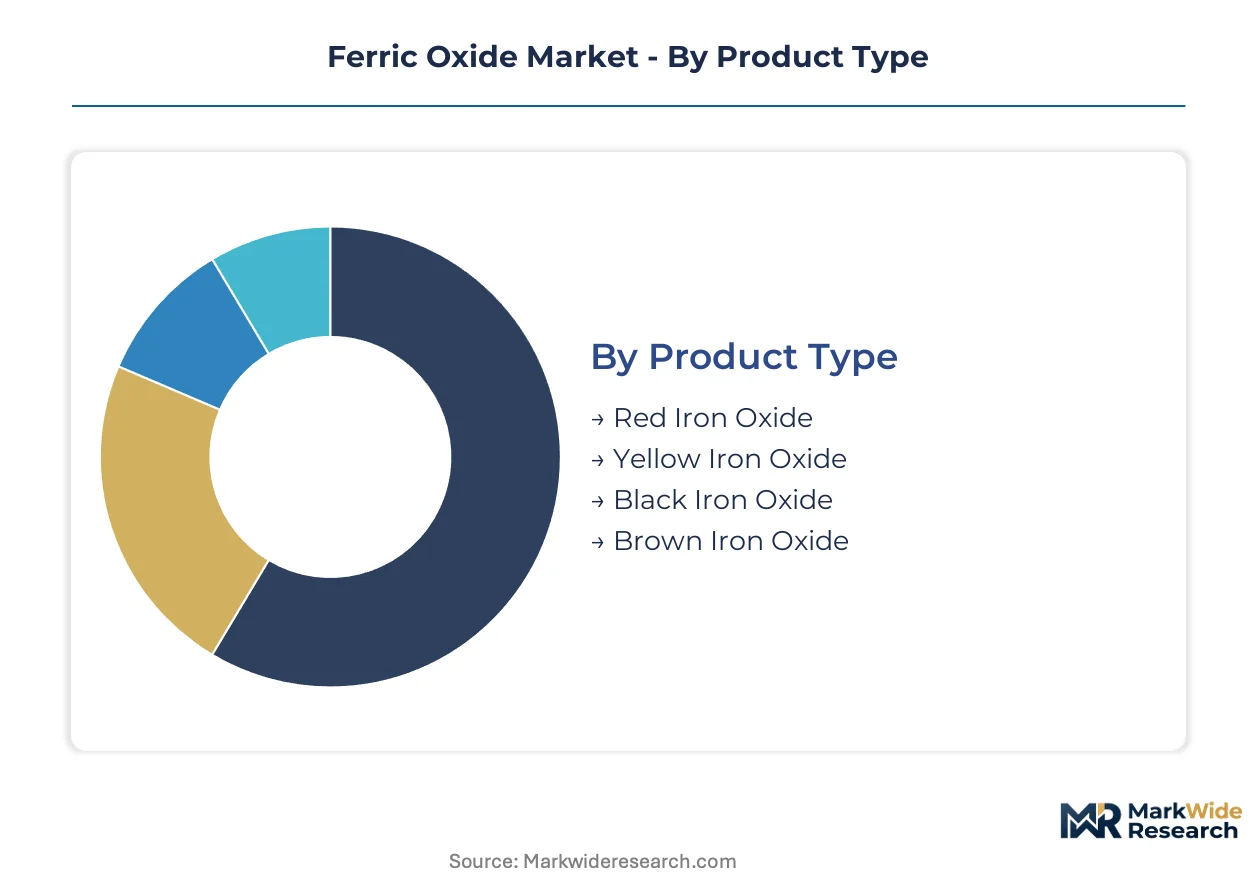
Product differentiation in ferric oxide hinges on particle engineering precision and regulatory compliance tiering. Formulators select grades based on opacity requirements, thermal stability thresholds, and end-use certification demands.
Product Type:
Color chemistry and crystal structure determine performance in specific coating systems and construction materials.
- Red Iron Oxide:Alpha-Fe₂O₃ hematite structure delivers superior UV absorption and thermal stability in architectural coatings. Demand concentrates in China's construction sector as urban housing stock expansion drives concrete coloring and protective paint formulations. REACH-registered suppliers capture premium positioning in European decorative coatings.
- Yellow Iron Oxide:Goethite-based α-FeOOH provides bright, clean yellow tones with lower tinting strength than red variants. Italian and German coatings formulators specify yellow grades for heritage restoration and terracotta-effect finishes where color consistency matters.
- Black Iron Oxide:Magnetite Fe₃O₄ offers magnetic properties alongside coloration, serving specialty electronics and magnetic recording media. Japanese producers dominate micronized black oxide supply for ferrite manufacturing.
- Brown Iron Oxide:Blended or co-precipitated compositions bridge red and yellow color spaces. Wood stain manufacturers in North America specify brown grades for exterior decking and fencing applications.
Mature deployment sits with Red Iron Oxide. Newer deployment is concentrated in Black Iron Oxide for electronics applications.
Application:
End-use specifications reshape particle size distribution requirements and purity thresholds across consumption channels.
- Coatings:Architectural, automotive, and industrial paint systems absorb the largest ferric oxide volumes. German automotive refinish suppliers specify surface-modified nano-grades for gloss retention. Waterborne architectural coatings in India drive commercial-grade red oxide consumption.
- Construction:Concrete coloring, paving stones, and roofing tiles demand coarse, cost-optimized grades with consistent dispersibility. Brazilian and Mexican infrastructure projects specify iron oxide pigments for aesthetic concrete finishes.
- Plastics:Polyolefin and PVC compounding requires heat-stable grades with low heavy metal content. Food-contact certification under EU regulations displaces cadmium and lead alternatives in European packaging.
- Cosmetics:Sunscreen and color cosmetic applications mandate nano-grade particles below 100 nanometers with full ECHA registration. French and Italian cosmetic houses consolidate supplier bases to pre-registered sources.
Volume leadership resides with Coatings. Steepest expansion trajectory belongs to Cosmetics as nano-grade registration barriers concentrate qualified supply.
Grade:
Purity tiering separates commodity precipitation output from precision-engineered particles for regulated applications.
- Commercial Grade:Standard precipitated or natural hematite oxides serve cost-sensitive construction and general industrial coatings. Hebei and Shandong precipitation facilities supply China's domestic coatings base.
- Micronized Grade:Tight particle distribution specifications enable pharmaceutical tablet coating and food-contact plastics. European and Japanese producers maintain capability scarcity in sub-5-micron controlled grinding.
- Nano Grade:Sub-100 nanometer particles synthesized through controlled precipitation open cosmetics and electronics applications. ECHA's nanomaterial registration obligations extend dossier requirements to surface-treated variants.
- Specialty Grade:Surface-modified, heat-treated, or chemically purified oxides meet military, aerospace, or medical device specifications. US and German specialty chemical houses dominate this tier.
Supply concentration weights toward Commercial Grade. Margin capture potential concentrates in Specialty Grade for qualified applications.
End User:
Procurement sophistication varies sharply across customer categories, from specification-driven pharmaceutical houses to price-sensitive construction material producers.
- Manufacturing:Cement, ceramics, and building materials producers purchase bulk commercial grades through distributor channels. Direct procurement platforms are compressing traditional distributor margins.
- Chemicals:Intermediates and catalyst manufacturers specify technical grades with controlled surface area and reactivity. German chemical clusters source through qualified European pigment houses.
- Paints & Coatings:Formulators drive grade innovation through qualification protocols and color matching requirements. North American architectural coatings producers have unbundled technical service from pigment procurement.
- Pharmaceuticals:Tablet coating and capsule coloration demand micronized grades with full pharmacopoeial compliance. CDSCO and FDA inspections tighten impurity documentation for Indian and US drug manufacturers.
Established demand anchors in Paints & Coatings. Emerging qualification intensity concentrates in Pharmaceuticals as purity documentation requirements escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematite deposits in Western Australia and beneficiation corridors in China's Hebei province anchor raw-material availability for ferric oxide synthesis. Processing capacity clusters near these feedstock nodes, with regulatory frameworks in consuming markets reshaping trade flows and grade specifications.
China
Construction coatings formulators in Shanghai and Guangzhou absorb expanded red iron oxide volumes as urban housing stock accelerates. MEE wastewater discharge limits on precipitation facilities in Hebei and Shandong provinces periodically shutter capacity, injecting volume uncertainty into export markets. The Yangtze River Delta concentrates domestic pigment manufacturing that supplies both local coatings producers and seaborne shipments.
Germany
Automotive refinish suppliers in Stuttgart and Munich specify surface-modified nano-grades for gloss retention and dispersion stability. ECHA REACH registration requirements lock in qualified European suppliers and raise barriers to unregistered imports. The Rhine-Ruhr industrial corridor anchors LANXESS AG's pigment operations with full traceability documentation.
United States
Architectural coatings producers in the Midwest and Southeast drive commercial-grade consumption for concrete coloring and protective paints. EPA NESHAP standards for hazardous air pollutants from calcination furnaces require continuous monitoring retrofits, extending capital deployment timelines for thermal processing expansions. The Gulf Coast petrochemical corridor hosts backward-integrated titanium dioxide co-production that secures feedstock cost advantages.
India
Waterborne architectural coatings in Maharashtra and Gujarat absorb expanded red oxide volumes as infrastructure investment accelerates. CDSCO inspections tighten impurity documentation for pharmaceutical tablet coating applications, reshaping supplier qualification timelines. The Mumbai-Pune industrial belt concentrates coatings formulators building in-house application laboratories.
Japan
Cosmetic houses in Tokyo and Osaka consolidate supplier bases to pre-registered nano-grade sources with existing ECHA toxicological packages. METI standards for particle engineering precision in electronics applications command premium positioning. The Kansai region dominates micronized black oxide supply for ferrite manufacturing.
Ferric Oxide Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance tiers and feedstock integration depth. The vendor base stratifies between REACH-registered European houses, backward-integrated titanium dioxide producers, and Chinese precipitation specialists serving cost-sensitive construction markets. Three archetypes dominate: vertically integrated chemical conglomerates with captive feedstock, mid-scale pigment houses with regional regulatory registrations, and commodity precipitation operators concentrated in Hebei-Shandong corridors. Competitive moves center on M&A for regulatory dossier portfolios and capacity expansion toward pharmaceutical-grade micronized output.
Within the vertically integrated tier, Huntsman International LLC and LANXESS AG exemplify contrasting geographic anchors. Huntsman leverages North American titanium dioxide co-production infrastructure, while LANXESS occupies a position defined by European regulatory compliance depth. Among Asia-Pacific specialists, Cathay Industries represents the Shanghai-based manufacturing archetype that supplies both domestic coatings formulators and export markets. These three entities illustrate how feedstock access and registration status combine to determine competitive positioning.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Kronos International, Inc. |
| LANXESS AG |
| Applied Minerals Inc. |
| Titan Kogyo, Ltd. |
| BASF SE |
| Hunan Sanhuan Pigment Co., Ltd |
| Toda Kogyo Corporation |
| Cathay Industries |
| Others |
Supply Flow & Price Mechanics
Hematite feedstock costs from Western Australian mines cascade through three pricing tiers before reaching coatings formulators, with calcination energy expenses and REACH dossier maintenance costs stratifying final pigment quotations across European, Chinese, and Indian supply corridors.
Pricing Analysis
After-sales technical service unbundling from pigment procurement contracts is compressing traditional value-added bundles and exposing bare pigment pricing to sharper procurement comparison. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered nano grades for cosmetics from commercial precipitated oxides for construction and unregistered commodity material. Pricing pressure stems from titanium dioxide substitution in high-opacity architectural applications where red iron oxide tones are not specification-critical. Construction material producers exhibit highest price sensitivity, while pharmaceutical tablet coating houses prioritize pharmacopoeial compliance over unit cost.
Supply Chain Analysis
Skilled chemical process engineers in Germany's Rhine-Ruhr corridor and Japan's Kansai region command wage premiums that sustain micronized grade capability scarcity. Supply concentrates in China's Hebei-Shandong precipitation belt, Germany's automotive coatings corridor, and Japan's electronics materials sector. Raw material dependencies encompass Western Australian hematite, sulfuric acid for precipitation chemistry, and natural gas for calcination furnaces. Single-source vulnerability concentrates in Hebei-Shandong environmental inspection cycles that periodically shutter precipitation capacity. Distribution runs through direct procurement platforms that bypass distributor tiers and accelerate qualification data exchange.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into titanium dioxide co-production to secure feedstock cost advantages and lock in margin stability against iron ore price volatility.
For Market Incumbents: Acquire REACH dossier portfolios to defend European market access against unregistered import competition. Expand micronized grade capacity in Japan or Germany to capture pharmaceutical tablet coating margins before Chinese suppliers close the capability gap. Titanium dioxide substitution in architectural coatings threatens volume in red iron oxide's core segment. Backward integration into hematite beneficiation or captive titanium dioxide co-production secures feedstock cost control. For New Entrants and Emerging Players: ECHA nanomaterial registration obligations in Europe open a window for qualified nano-grade suppliers to consolidate cosmetic house supplier bases. Target underpenetrated pharmaceutical tablet coating segments in India where CDSCO inspections are tightening impurity documentation requirements. Partner with coatings formulators building in-house application laboratories to embed technical service relationships before procurement unbundling completes. For Investors and Strategic Acquirers: MEE wastewater discharge enforcement intensity in Hebei is the leading indicator that Chinese supply consolidation will accelerate and export volume uncertainty will persist. Mid-scale pigment houses with existing REACH registrations and traceability documentation represent prime acquisition targets. Watch for environmental inspection campaign announcements that trigger capacity shutdowns and price spikes in export markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Titanium dioxide co-production secures feedstock cost advantages against iron ore volatility. |
| REACH Dossier Acquisition | Registered pigment lines with full traceability documentation lock in European market access. |
| Micronized Capacity Expansion | Sub-5-micron controlled grinding capability captures pharmaceutical coating margin premiums. |
| Direct Procurement Platform | Bypassing distributor tiers compresses channel margins and accelerates qualification data exchange. |
| Nano-Grade Registration | ECHA-compliant toxicological packages open cosmetics and electronics premium positioning. |
Methodological Framework
Independent corroboration across procurement leads at coatings formulators, plant managers at precipitation facilities, and regulatory affairs directors at pigment houses underwrites the qualitative findings. Primary interviews with technical R&D directors, distribution channel partners, and downstream OEM procurement teams combined with secondary validation from customs/trade data, SEC 10-K filings, and ECHA registration databases. Bottom-up volume estimates triangulate against top-down market sizing across grade tiers and end-use industries.
Rate-of-change decomposition separates volume growth from price realization across the analysis window. Segmentation dimensions modeled include product type, application channel, grade tier, and regional production hub. CAGRs derive from regression analysis against construction activity indices, coatings production data, and pharmaceutical formulation trends. Forecast inputs incorporate environmental inspection frequency in Hebei-Shandong and REACH evaluation cycle timelines.
Caveats apply where MEE enforcement intensity, ECHA substance evaluation outcomes, or titanium dioxide substitution rates could materially shift the outlook. Forecasts reflect assumptions about regulatory continuity and feedstock price stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Power Plant Chemicals Market
Chemicals
Para Cresol Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Paint Stripper Market
Chemicals
Bakers Ammonia Market
Chemicals
N-Propanol Market
Chemicals
Sodium Azide Market
Chemicals
Canada Methanol Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Triethanolamine Market
Chemicals
Hydrazine Market
Chemicals
Chemical Distribution Market
Chemicals
Global Glycol Ether Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Calcium Borate Market