
 Bakers Ammonia Market | 2026-2036
Bakers Ammonia Market Size, Share, and Industry Trends Forecast 2026-2036
Bakers Ammonia Market Analytics
Synthetic cream of tartar is decoupling from traditional bakers ammonia formulations in premium biscuit manufacturing, altering leavening cost structures across European and North American plants. CF Industries Holdings leverages its nitrogen platform to sustain feedstock advantages in ammonia carbonate production. Yara International anchors its position through integrated ammonia operations spanning fertilizer and food-grade derivatives. OCI Global differentiates via specialized purification capacity serving confectionery clients.
Bakers ammonia—chemically ammonium carbonate—decomposes at 58°C into ammonia, carbon dioxide, and water vapor, leaving no residual salt and imparting the characteristic crisp texture to Dutch speculaas and Scandinavian Christmas cookies. Powdered product type leads volume shipments due to superior shelf stability and dosing precision in automated bakery lines. End use in confectionery represents the fastest-expanding segment as Asian manufacturers adopt European-style crisp biscuit formats. Distribution through wholesale channels captures the dominant margin pool by bypassing retail markup for industrial-scale buyers.
The FDA governs ammonium carbonate as a GRAS substance under 21 CFR 184.1137, while the EU EFSA monitors maximum residue levels through Regulation 1333/2008 on food additives. REACH compliance in Europe and evolving EPA reporting thresholds for ammonia derivatives in the United States shape formulation transparency and import documentation burdens. Stakeholders must track regulatory divergence between jurisdictions to optimize multi-plant formulation strategies and avoid reformulation costs.
Market Dynamics
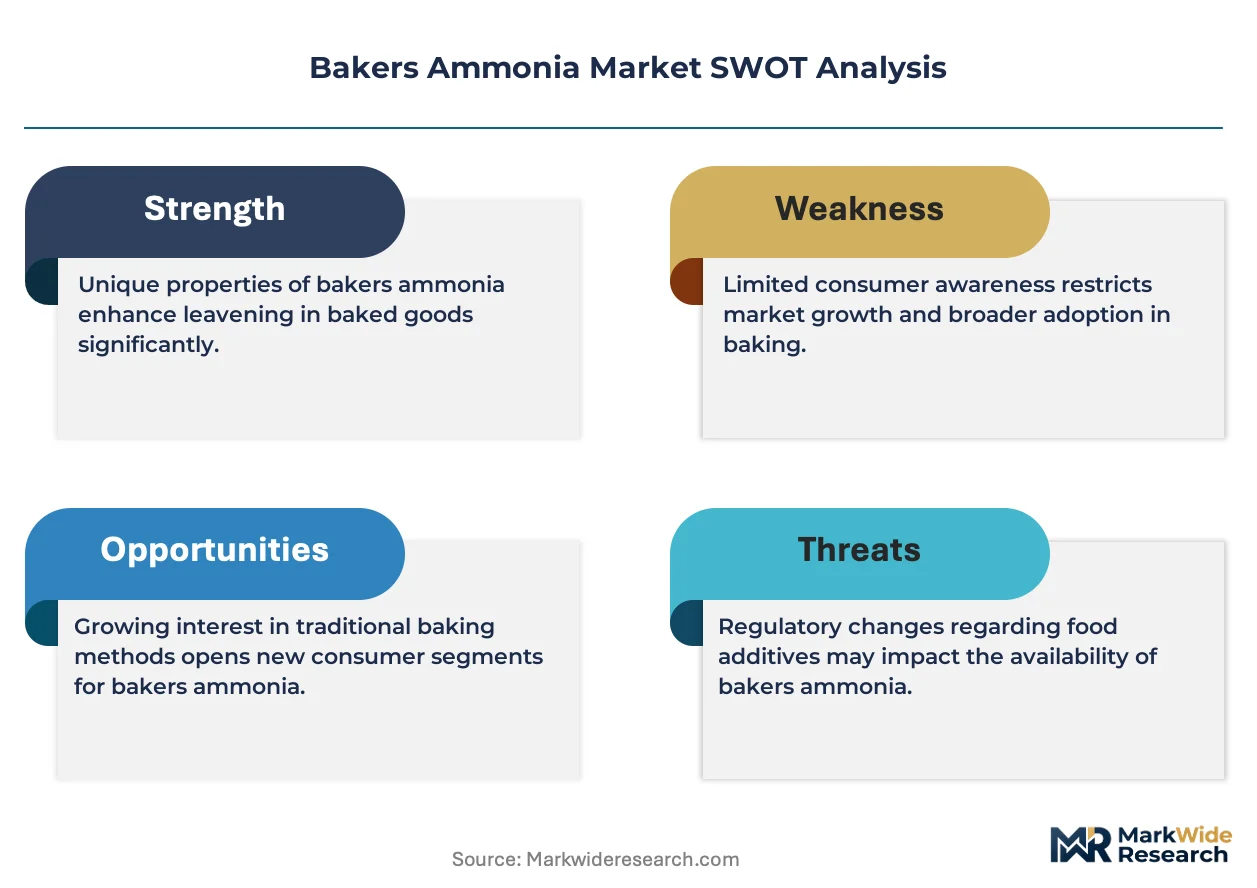
Clean-label formulation mandates across Western Europe are forcing industrial bakeries to abandon synthetic leavening salts, redirecting procurement toward ammonium carbonate as the sole GRAS-compliant crisping agent for heritage biscuit formats. This regulatory compression is concentrating demand among ammonia producers with food-grade purification capabilities.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework's 2030 reduction mandates for synthetic food additives accelerate replacement of aluminum-based leavening phosphates with ammonium carbonate in Dutch and German industrial bakeries.
- Asian confectionery manufacturers:Adoption of European-style crisp biscuit formats in South Korea and Japan creates new demand for bakers ammonia in automated wafer and speculaas production lines.
- Powdered product type shelf stability:Superior dosing precision in high-speed automated bakery equipment reduces waste and labor calibration costs versus crystalline ammonium carbonate alternatives.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis depends on Haber-Bosch process inputs, exposing carbonate producers to European TTF benchmark price swings that compress margin predictability.
- REACH documentation burdens:ECHA registration requirements for ammonia derivatives impose fixed compliance costs that disproportionately burden small-batch artisan suppliers.
- Synthetic cream of tartar substitution:Premium biscuit manufacturers in North America are reformulating with potassium bitartrate blends that mimic bakers ammonia texture without ammonia odor risks.
Strategic Opportunities
- India's organized bakery sector:FSSAI clean-label guidance and expanding modern trade retail create first-mover advantage for ammonium carbonate distribution through Mumbai and Bangalore industrial corridors.
- Carbon capture integration:Food-grade CO2 sourcing from ammonia plant carbon capture installations aligns with EU ETS incentive structures for low-carbonate production.
- Direct-to-artisan digital channels:Specialty ingredient platforms bypass wholesale markup structures to capture margin from small-batch Scandinavian and Alpine heritage bakers.
Industry Challenges
- Food-grade certification timelines:EFSA novel food consultations and FDA GRAS affirmation processes extend time-to-market for purified ammonia derivatives by 18-24 months.
- Legacy equipment incompatibility:Automated dosing systems calibrated for sodium bicarbonate require retooling to handle ammonium carbonate hygroscopicity and sublimation behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakers Ammonia Market |
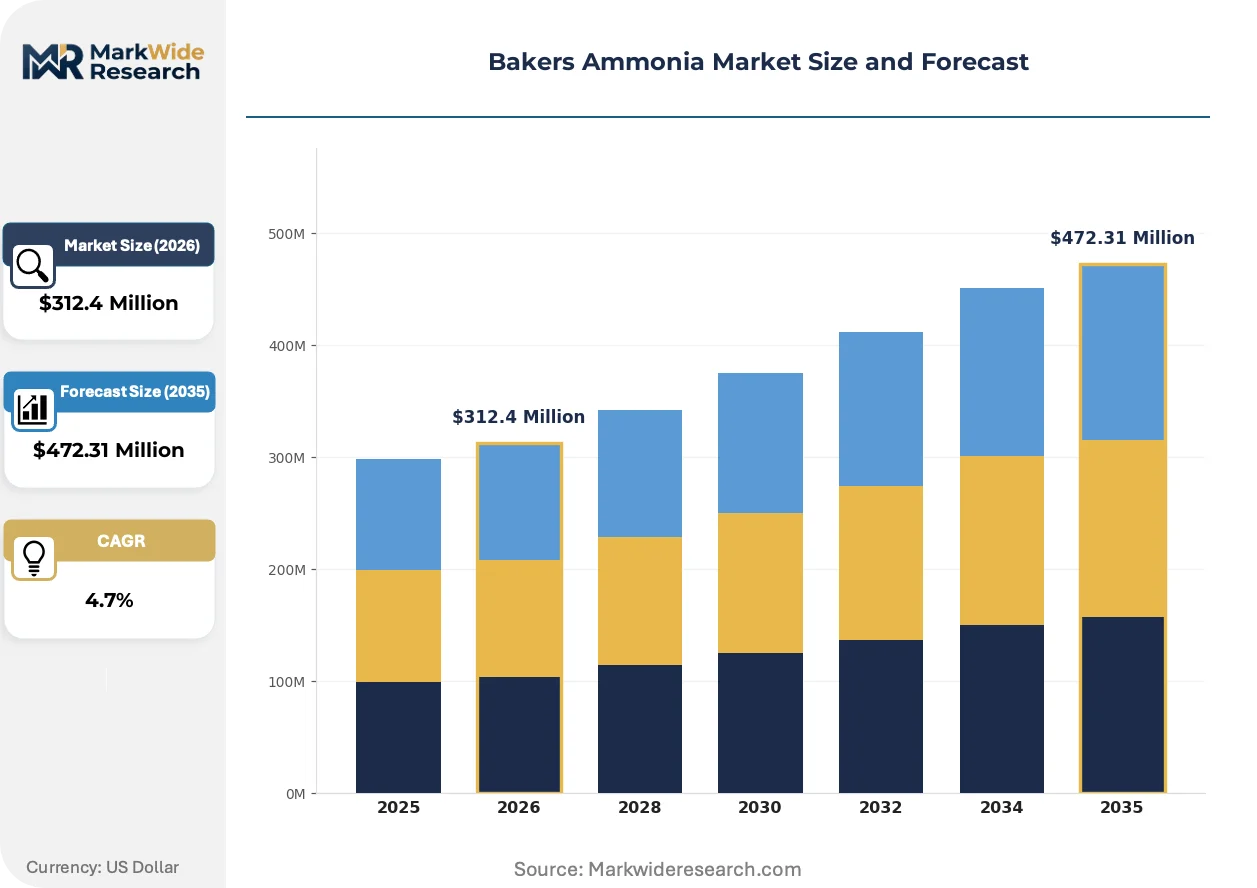
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Liquid, Semi-solid End Use: Baking, Confectionery, Snack Foods, Meat Processing Distribution Channel: Online Retail, Supermarkets, Food Service, Wholesale Packaging Type: Bags, Containers, Pouches, Drums |
| Companies Covered | CF Industries Holdings, Inc., Yara International ASA, OCI Global, BASF SE, Nutrien, Saudi Basic Industries Corporation, Qatar Fertiliser Company, Koch Fertilizer, LLC, CSBP Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakers Ammonia Market Evolving Landscape
Reformulation chemistry and process control systems are converging to preserve bakers ammonia's unique thermal decomposition properties while eliminating handling hazards that have constrained its adoption in modern plant environments.
Microencapsulation technology is integrating ammonium carbonate within lipid or polymer shells that delay sublimation until target baking temperatures. Industrial biscuit manufacturers in Germany's Ruhr baking corridor are piloting these systems to enable year-round storage stability without climate-controlled warehousing. The technology is integrating precision thermal release profiles that match automated oven zone temperatures, compressing variability in finished product texture.
REACH Regulation 2023 amendments on ammonia derivative classification are forcing importers to submit extended safety data sheets for ammonium carbonate shipments into EU member states. Industrial users must now document workplace exposure controls and environmental release estimates that previously applied only to fertilizer-grade ammonia. Confectionery segment buyers are responding by consolidating supplier relationships with integrated ammonia producers possessing in-house regulatory affairs capabilities.
Heritage bakery procurement patterns are fragmenting away from consolidated wholesale distributors toward specialty chemical direct sourcing. Small-batch speculaas and springerle producers in Belgium and the Netherlands are establishing direct supply agreements with ammonia purification specialists, bypassing regional ingredient distributors that previously captured 35-40 point margins. This channel disintermediation is most visible in Flanders and Limburg provinces where artisan guilds coordinate collective purchasing to meet minimum order thresholds for food-grade railcar deliveries.
Bakers Ammonia Market Segmentation
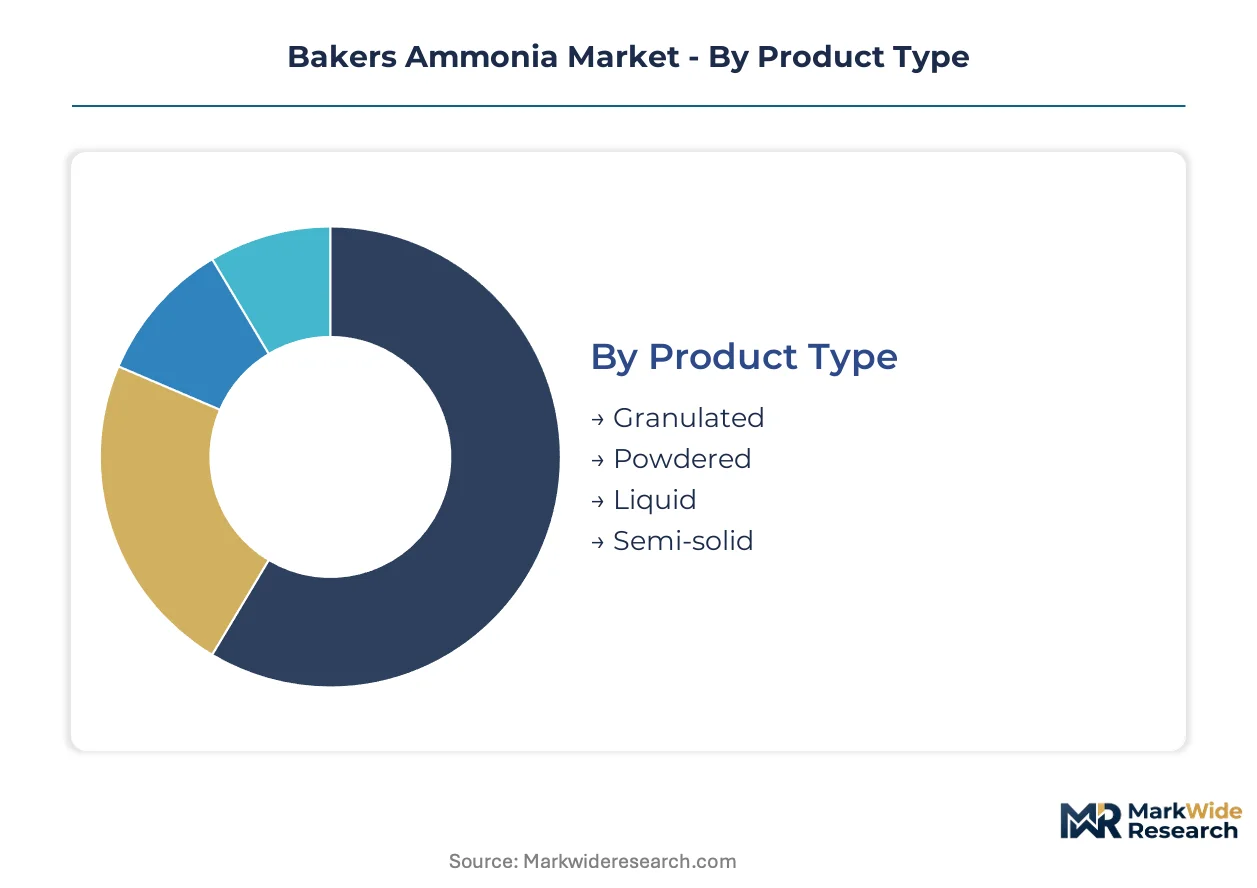
Bakers ammonia segments by physical form, application, and channel reflect divergent margin structures and technical requirements. Powdered formats command automated bakery premiums while liquid variants serve specialized meat curing operations. Channel choice determines regulatory documentation burdens and minimum order economics.
Product Type:
Powdered formats dominate volume shipments due to superior flow characteristics in high-speed dosing equipment, while granulated variants capture premium positioning in artisan heritage applications.
- Powdered:Ammonium carbonate ground to 100-200 mesh enables precise volumetric feeding in Dutch and German industrial biscuit lines. German Ruhr corridor bakeries specify this grade for automated speculaas production where dosing tolerance below 2% controls texture uniformity.
- Granulated:Crystalline ammonium carbonate with 2-4mm particle size resists caking during ambient storage. Belgian artisan guilds in Flanders and Limburg provinces prefer this format for small-batch springerle where manual scaling tolerates slower dissolution kinetics.
- Liquid:Aqueous ammonium carbonate solutions serve industrial meat processors requiring controlled pH elevation in cured product emulsions.
- Semi-solid:Paste concentrates find niche use in mobile bakery operations where water addition flexibility matters more than shelf stability.
Mature deployment sits with Powdered formats in automated European biscuit plants. Newer deployment is concentrated in Semi-solid formats for emerging mobile and field bakery concepts.
End Use:
Application segmentation tracks divergent thermal processing requirements and regulatory classification thresholds across food manufacturing categories.
- Baking:Heritage crisp biscuit formats—Dutch speculaas, Scandinavian Christmas cookies, German springerle—depend on ammonium carbonate's 58°C decomposition threshold leaving zero residual salt. Industrial bakeries in Germany's North Rhine-Westphalia corridor specify food-grade purity above 99% for consistent CO2 release profiles.
- Confectionery:Asian wafer manufacturers in South Korea and Japan are adopting European crisp formats, creating demand for ammonium carbonate in automated wafer baking tunnels where rapid ammonia venting requires engineered extraction systems.
- Snack Foods:Extruded savory applications use ammonium carbonate as a secondary leavening agent where alkaline residues from sodium bicarbonate would distort flavor profiles.
- Meat Processing:Cured meat emulsions employ ammonium carbonate as a pH modifier where rapid decomposition during thermal processing eliminates residual alkalinity concerns.
Established penetration sits with Baking applications in Western European heritage formats. Steepest expansion trajectory is occurring in Confectionery as Asian manufacturers replicate European crisp biscuit architectures.
Distribution Channel:
Channel selection determines margin capture, regulatory documentation intensity, and minimum viable order quantities for ammonium carbonate procurement.
- Wholesale:Industrial-scale buyers bypass retail markup through direct railcar and bulk truck deliveries. Integrated ammonia producers with food-grade purification capacity dominate this channel, offering consolidated REACH documentation and certificate of analysis packages.
- Online Retail:Specialty ingredient platforms serve small-batch artisan bakers with sub-tonne order quantities. Belgian and Dutch heritage guilds coordinate collective purchasing through these channels to meet minimum thresholds for food-grade certification.
- Supermarkets:Consumer-packaged formats in 100-500g containers reach home bakers seeking authentic speculaas recipes, though shelf space constraints limit SKU proliferation.
- Food Service:Restaurant and hotel bakery operations procure through broadline distributors where ammonium carbonate appears within consolidated leavening ingredient portfolios.
Margin concentration sits with Wholesale channels serving industrial biscuit manufacturers. Channel fragmentation is accelerating in Online Retail as artisan guilds disintermediate regional ingredient distributors.
Packaging Type:
Packaging selection balances hygroscopicity protection, handling automation compatibility, and regulatory labeling requirements for ammonia derivative classification.
- Bags:Multi-wall paper bags with polyethylene liners provide cost-efficient containment for powdered ammonium carbonate in automated bakery ingredient handling systems.
- Drums:Steel drums with sealed lids protect granulated formats from moisture ingress during extended storage in variable-climate warehouse environments.
- Containers:Rigid plastic containers serve liquid and semi-solid formats where spill containment and stack stability override unit cost minimization.
- Pouches:Flexible pouches with high-barrier laminates target artisan and retail segments where resealability and shelf presentation matter.
Industrial standardization sits with Bags and Drums in automated bakery supply chains. Format experimentation is concentrated in Pouches for direct-to-artisan digital channels seeking differentiation through packaging convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial baking corridors in Germany concentrate bakers ammonia procurement volumes, while Asian confectionery manufacturers accelerate adoption of European crisp biscuit formats. Regulatory divergence between FDA GRAS affirmation and EFSA additive classifications shapes multi-plant formulation strategies. Clean-label mandates in Western Europe redirect procurement toward ammonium carbonate as heritage biscuit producers abandon synthetic leavening salts.
Germany
Ruhr corridor industrial bakeries drive powdered ammonium carbonate consumption for automated speculaas production lines. EU Green Deal chemical sustainability targets accelerate replacement of aluminum-based leavening phosphates in North Rhine-Westphalia facilities. Cologne-Düsseldorf industrial zones concentrate food-grade purification capacity among integrated ammonia producers.
Netherlands
Heritage speculaas and springerle producers in Flanders and Limburg provinces sustain granulated format demand for small-batch artisan applications. REACH Regulation 2023 amendments impose extended safety data sheet requirements on ammonia derivative imports. Belgian-Dutch border regions witness channel disintermediation as artisan guilds coordinate direct railcar purchasing.
United States
Premium biscuit manufacturers in Pennsylvania and Wisconsin test potassium bitartrate blends as synthetic cream of tartar substitutes. FDA GRAS status under 21 CFR 184.1137 governs ammonium carbonate use, while evolving EPA reporting thresholds shape import documentation. Midwest industrial baking clusters calibrate automated dosing systems for sodium bicarbonate compatibility.
South Korea
Wafer manufacturers adopt European crisp biscuit architectures, creating demand for ammonium carbonate in automated baking tunnels. MFDS food additive regulations govern maximum residue levels in confectionery applications. Seoul-Incheon industrial corridors engineer ammonia extraction systems for rapid venting during thermal processing.
India
FSSAI clean-label guidance drives organized bakery sector interest in heritage leavening agents. Mumbai and Bangalore industrial corridors present first-mover distribution opportunities for food-grade ammonium carbonate. Maharashtra and Karnataka state regulators align with central guidance on synthetic additive reduction timelines.
Bakers Ammonia Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated ammonia producers capturing industrial-scale procurement through consolidated REACH documentation. The vendor base organizes around three archetypes: nitrogen platform operators with food-grade purification capabilities, regional fertilizer-grade suppliers attempting downstream qualification, and specialty chemical distributors serving artisan channels. Consolidation pressures concentrate among ammonia producers possessing in-house regulatory affairs capacity. Competitive moves center on carbon capture integration for food-grade CO2 sourcing and direct-to-artisan digital channel establishment.
Within the nitrogen platform tier, CF Industries Holdings, Inc., Yara International ASA, and OCI Global exemplify the integrated archetype. CF Industries anchors North American positioning through its nitrogen platform infrastructure. Yara International ASA represents European integrated operations spanning fertilizer and food-grade derivative production. OCI Global occupies specialized purification capacity serving confectionery segment requirements. These three companies illustrate how feedstock control and regulatory compliance capabilities determine competitive positioning in food-grade ammonium carbonate supply.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Yara International ASA |
| OCI Global |
| BASF SE |
| Nutrien |
| Saudi Basic Industries Corporation |
| Qatar Fertiliser Company |
| Koch Fertilizer, LLC |
| CSBP Limited |
| Others |
Value Network & Pricing Analysis
Clean-label procurement mandates in Western Europe are compressing supplier qualification timelines and forcing ammonia carbonate producers to absorb REACH documentation costs into contract pricing. This demand-side pressure concentrates purchasing power among integrated nitrogen platforms with in-house regulatory affairs capacity.
Pricing Analysis
Volume-mass industrial contracts capture thin margins against food-grade certification premiums, while artisan-channel granulated formats sustain three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EFSA purity certification tier and railcar delivery scale. Cost compression in standard-grade powdered formats is intensifying because natural gas feedstock volatility transfers directly from TTF benchmarks. Small-batch heritage bakers in Belgium and the Netherlands exhibit highest price sensitivity; automated German biscuit plants prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EU industrial bakeries mandate qualification of at least two food-grade purification specialists per procurement category. Supply concentrates in Germany, the Netherlands, and Norway among integrated ammonia producers drawing from natural gas and captured CO2 feedstocks. Raw material dependencies rest on Haber-Bosch synthesis inputs, food-grade carbon dioxide sourcing, and specialized desiccant packaging. Single-source vulnerability persists for REACH-compliant documentation bundles. Distribution runs through railcar and bulk truck direct delivery to automated bakery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology is displacing legacy ammonium carbonate handling systems in automated European biscuit plants, creating transition-phase arbitrage for suppliers with precision thermal-release capabilities.
For Market Incumbents: Lock in artisan-channel relationships through direct-to-guild digital platforms before specialty chemical distributors consolidate collective purchasing power in Flanders and Limburg. Prioritize backward integration into carbon capture installations to secure food-grade CO2 supply and align with EU ETS incentive structures. Synthetic cream of tartar substitution in North American premium biscuit manufacturing represents the core demand threat. For New Entrants and Emerging Players: Launch via online retail specialty ingredient platforms serving sub-tonne order quantities from Mumbai and Bangalore industrial corridors where FSSAI clean-label guidance is redirecting procurement. India's organized bakery sector offers the most penetrable geography. Target confectionery segment expansion in South Korea and Japan through engineered ammonia extraction system partnerships. For Investors and Strategic Acquirers: The window for entry favors integrated nitrogen platforms with existing food-grade purification infrastructure over greenfield purification investments. Long-term viability hinges on carbon capture integration and regulatory affairs capacity consolidation. Watch for EFSA novel food consultation backlogs as inflection indicator for time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Food-grade CO2 sourcing from ammonia plant capture aligns with EU ETS incentive structures. |
| Microencapsulation Technology Deployment | Precision thermal-release profiles match automated oven zone temperatures in German Ruhr corridor. |
| Direct-to-Artisan Digital Channel Establishment | Specialty platforms bypass wholesale markup to capture margin from Belgian heritage guilds. |
| REACH Documentation Consolidation | In-house regulatory affairs capacity secures industrial-scale procurement from EU bakeries. |
| India Distribution Corridor Buildout | Mumbai and Bangalore industrial zones present first-mover advantage under FSSAI guidance. |
Research Methodology
Independent corroboration across plant managers at German industrial bakeries, procurement leads at Dutch speculaas manufacturers, and ammonia purification specialists underwrites the qualitative findings. Primary interviews with distribution channel partners and technical R&D directors at nitrogen platform operators combined with secondary validation from customs/trade data, Cefic chemical industry reports, and SEC 10-K filings. Bottom-up volume modeling and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical ammonia derivative pricing and industrial bakery output volumes established the forecast baseline. The analytical framework segments by physical form, end-use application, and distribution channel across the projection horizon, with additional modeling of certification-grade tier and regional production hub concentration. CAGRs derive from regression against nitrogen platform capacity utilization and clean-label regulatory adoption curves. Feedstock cost volatility and REACH amendment implementation timelines serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for microencapsulation thermal-release systems would alter the outlook. Forecasts reflect assumptions about EFSA consultation timelines, natural gas benchmark stability, and Asian confectionery format adoption rates. Deviation in EU Green Deal chemical sustainability target acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Potassium Fluoride Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Linear Mercaptans Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Global Construction Chemical Market
Chemicals
Methanol Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Tromethamine Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Sodium Cyanide Market
Chemicals
Calcium Hydride Market