
 Tin Chloride Market | 2026-2036
Tin Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Tin Chloride Market Outlook
Electronics plating houses are unwinding legacy procurement from generalist chemical distributors. Yunnan Tin Group leverages captive tin metal supply to dominate anhydrous feedstock production. TIB Chemicals AG anchors European supply through specialized pharmaceutical-grade purification. Merck KGaA differentiates via ultra-high-purity specifications for semiconductor etching applications.
Tin chloride denotes tin halide compounds—principally SnCl₂ and SnCl₄—manufactured via direct chlorination of tin metal or reduction of tin oxide with hydrochloric acid, with purity grades spanning technical to electronic grade. The primary commercial purpose centers on electroplating fluxes, polymerization catalysts, and reducing agents in organic synthesis. Tin(IV) chloride leads product type revenue due to its irreplaceable role in CVD precursors for transparent conductive oxides, while tin(II) chloride records faster growth from resurgent pharmaceutical reducing-agent demand. Application segmentation shows electronics commanding the dominant margin pool, whereas water treatment represents a volume-stable but price-competitive segment.
EPA regulations under the Toxic Substances Control Act constrain domestic manufacturing emissions, while REACH registration in Europe mandates full toxicological dossiers for import authorization. China's MEE enforces wastewater discharge limits that elevate compliance costs for hydrated product facilities. Stakeholders must monitor evolving semiconductor material purity thresholds and dual-use export control expansions affecting tin precursor shipments.
Market Dynamics
Electronics plating houses are unwinding legacy procurement from generalist chemical distributors and contracting directly with specialized tin chloride refiners to secure electronic-grade purity certificates required by semiconductor OEMs.
Growth Catalysts
- Semiconductor CVD precursor demand:Tin(IV) chloride serves as an irreplaceable feedstock for indium tin oxide deposition in display manufacturing, with display panel fabs expanding capacity in China and South Korea.
- REACH registration completion:Full toxicological dossier authorization under ECHA rules has stabilized European import volumes for pharmaceutical-grade applications.
- Printed circuit board surface treatment:High-density interconnect PCB manufacturing is consuming larger tin chloride volumes for electroless tin plating processes.
Market Restraints
- Tin metal price volatility:London Metal Exchange tin pricing swings directly compress hydrated product margins for non-integrated producers.
- Yunnan supply concentration:Captive tin metal supply in southwestern China creates asymmetric feedstock access for domestic anhydrous producers versus importers.
- Phosphorus-based reducing agent substitution:Pharmaceutical formulators are piloting hypophosphite alternatives to tin(II) chloride in certain organic synthesis routes.
Strategic Opportunities
- Indian electronics manufacturing:Production-linked incentive schemes for semiconductor and PCB fabrication are creating new tin chloride demand centers in Gujarat and Tamil Nadu.
- Battery-grade tin precursor qualification:Sodium-ion battery anode developers are evaluating tin chloride-derived materials for next-generation energy storage.
- Direct refiner-to-fab contracting:Bypassing traditional chemical distribution layers allows purity certification co-development with semiconductor material engineers.
Industry Challenges
- Semiconductor purity threshold escalation:Sub-ppb metallic impurity specifications for 3nm node etching precursors require capital-intensive purification infrastructure.
- Dual-use export control navigation:Expanding precursor chemical shipment licensing under multilateral frameworks complicates cross-border logistics planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tin Chloride Market |
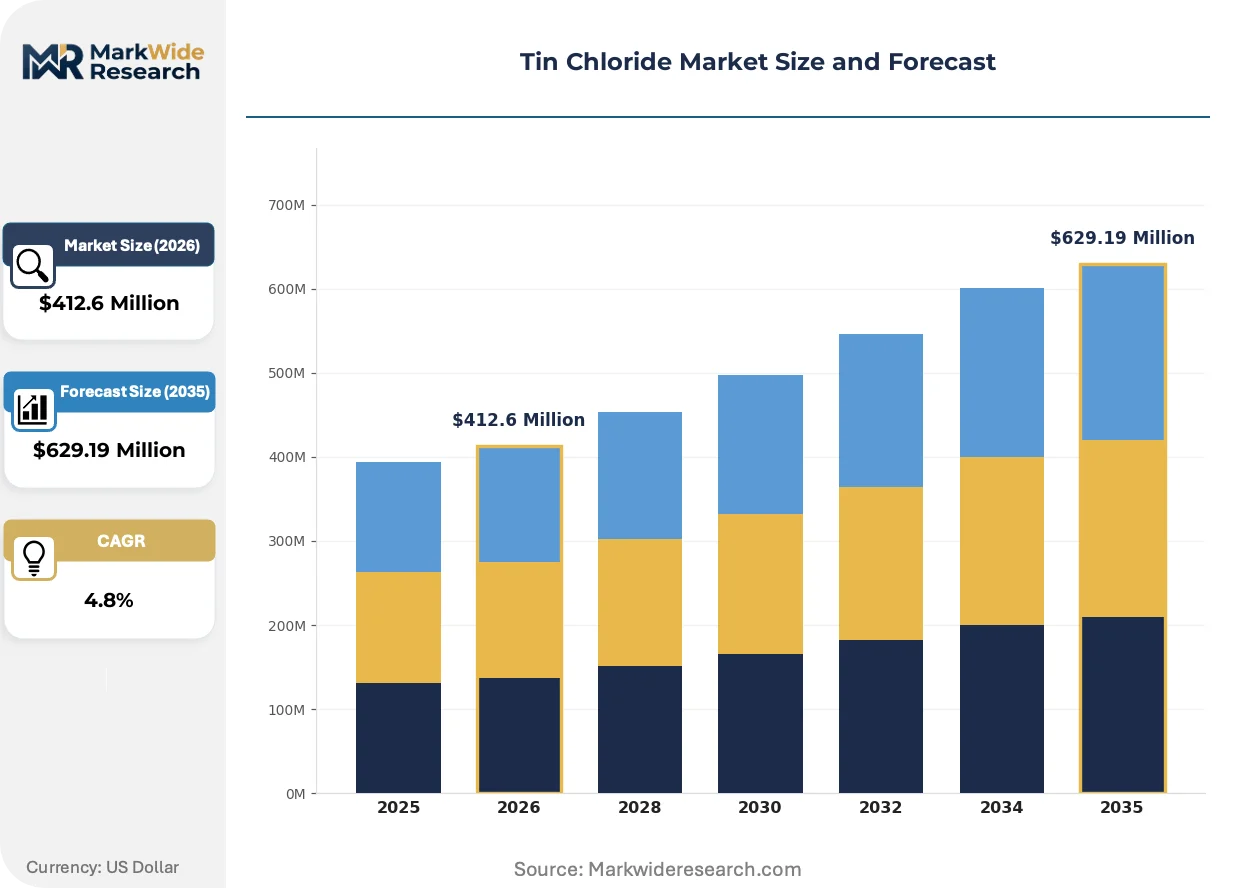
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Tin Chloride, Hydrated Tin Chloride, Tin(II) Chloride, Tin(IV) Chloride Application: Chemical Synthesis, Electronics, Food Preservation, Textile Industry End Use Industry: Pharmaceuticals, Agriculture, Manufacturing, Water Treatment Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Yunnan Tin Group, Mason Corporation, Showa America, TIB Chemicals AG, Merck KGaA, Alfa Aesar, Gulbrandsen, Liuzhou China Tin Group, William Blythe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tin Chloride Market Strategic Shifts
Continuous purification technologies are displacing batch crystallization methods, while regulatory dossier requirements and procurement model restructuring are simultaneously reshaping competitive positioning across the value chain.
Gas-phase purification is fragmenting traditional liquid-phase crystallization dominance in electronic-grade tin chloride production. Semiconductor material engineers at advanced node fabs are specifying vapor-deposited feedstocks to eliminate particulate contamination risks. This technology shift is fragmenting the supplier base between integrated metal-to-precursor refiners and standalone chemical processors lacking vapor-phase capabilities.
REACH authorization requirements for tin chloride intermediates are tightening toxicological data obligations across European chemical supply chains. ECHA's evolving substance evaluation criteria are extending registration timelines for new market entrants. Specialty chemical distributors with incomplete dossiers are retreating from pharmaceutical-grade segments, ceding share to fully registered direct manufacturers.
Long-term contracting is displacing spot market purchasing for high-purity tin chloride volumes. Display panel manufacturers in South Korea and Taiwan are locking in multi-year supply agreements with specified purity tiers and volume flexibility clauses. This behavioral shift is most visible in the transparent conductive oxide precursor segment, where foundry-grade specifications now travel with dedicated supply chain audits.
Tin Chloride Market Segmentation
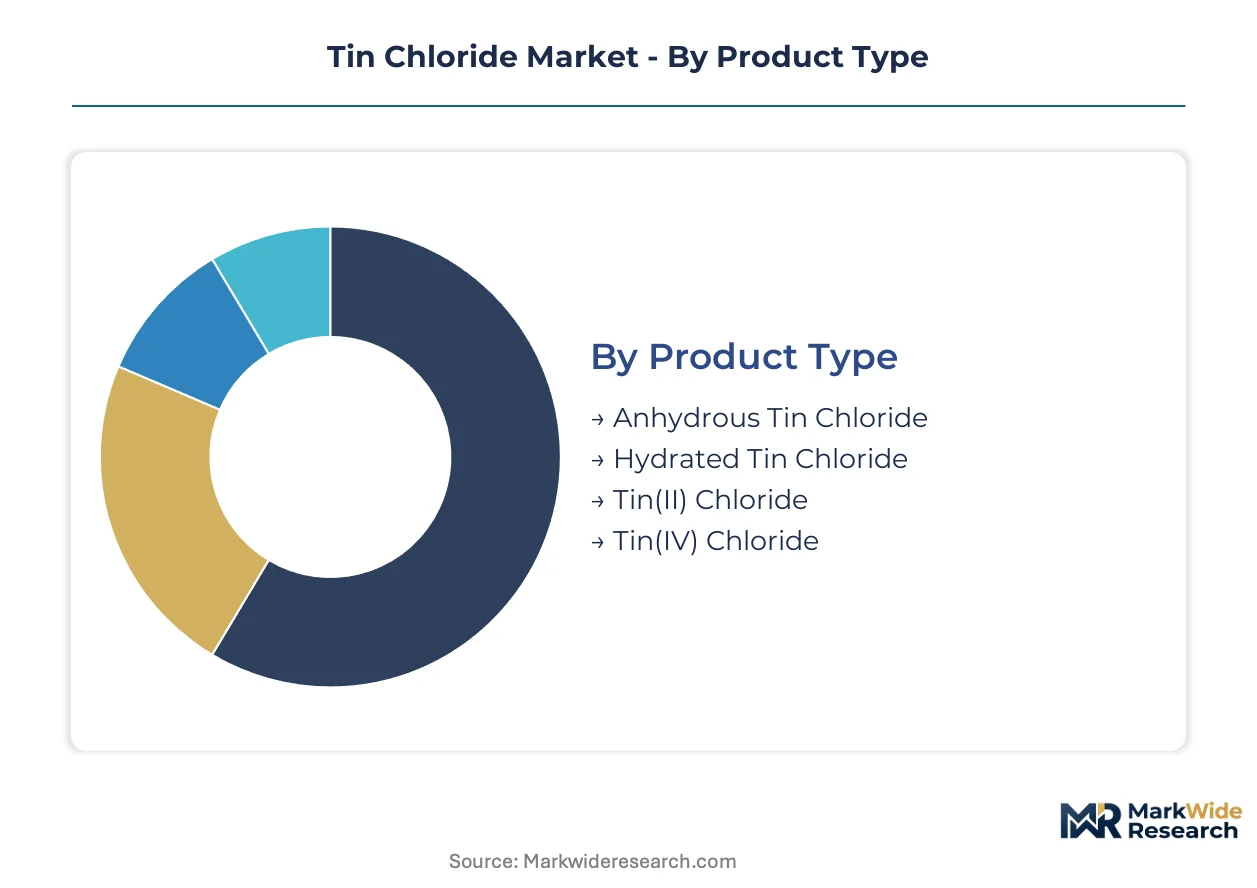
Margin concentration in tin chloride markets tracks purity gradients and captive supply chains rather than volume throughput. Electronics-grade specifications command pricing multiples over technical grades, while direct refiner relationships are displacing traditional distributor intermediation.
Product Type:
Anhydrous grades concentrate the highest margin pools due to semiconductor precursor specifications and energy-intensive dehydration requirements.
- Anhydrous Tin Chloride:Manufactured via direct chlorination of tin metal followed by fractional distillation, achieving moisture content below 50 ppm. Display panel fabs in South Korea and Taiwan specify anhydrous SnCl₄ for indium tin oxide CVD processes, with purity certificates now requiring sub-ppb metallic impurity thresholds.
- Tin(IV) Chloride:The tetravalent halide serves as the dominant feedstock for transparent conductive oxide deposition in flat-panel display manufacturing. Chinese display cluster expansion around Hefei and Chengdu is absorbing expanding volumes of vapor-phase purified material.
- Hydrated Tin Chloride:Crystalline pentahydrate and dihydrate forms serve electroplating flux and textile mordant applications. Technical-grade specifications dominate water treatment procurement in India and Southeast Asia.
- Tin(II) Chloride:The divalent salt functions as a reducing agent in pharmaceutical organic synthesis and polymerization catalysis. Resurgent demand from generic API manufacturers in Gujarat and Tamil Nadu is tightening pharmaceutical-grade supply.
Tin(IV) chloride holds installed capacity. Tin(II) chloride is rotating up the share rankings.
Application:
Electronics applications extract the steepest value per kilogram through purity-linked pricing tiers, while food preservation operates on commodity chemical economics.
- Electronics:Encompasses printed circuit board electroless tin plating, semiconductor etchant formulation, and transparent conductive oxide precursor supply. High-density interconnect PCB manufacturing in Taiwan and South Korea consumes expanding tin chloride volumes for surface finishing.
- Chemical Synthesis:Tin(II) chloride reduction protocols support pharmaceutical intermediate production and organic transformations. ECHA REACH authorization requirements are constraining European supply chain participation to fully registered direct manufacturers.
- Textile Industry:Tin chloride mordants fix dyes to natural fibers in traditional weaving clusters. Indian textile processing centers around Surat and Tiruppur maintain steady technical-grade consumption.
- Food Preservation:Stannous chloride serves as an antioxidant in canned goods under FDA and EFSA food additive specifications. Volume demand concentrates in mass-market packaging applications with minimal purity premium capture.
Electronics commands margin concentration. Chemical synthesis is climbing the fastest.
End Use Industry:
Pharmaceutical procurement operates on batch certification requirements that filter out non-registered suppliers, while water treatment purchases on delivered cost per active tin content.
- Pharmaceuticals:Tin(II) chloride reducing agents support API synthesis for cardiovascular and antiparasitic compounds. CDSCO manufacturing license requirements in India and FDA cGMP standards in the United States enforce documented impurity profiling.
- Manufacturing:Electronics manufacturing services and display panel fabrication consume the dominant volume share. South Korean foundry-grade specifications now travel with dedicated supply chain audits and multi-year contracting structures.
- Water Treatment:Tin chloride coagulants treat industrial wastewater and potable water systems. China's MEE wastewater discharge limits elevate compliance costs for hydrated product facilities in Jiangxi and Yunnan provinces.
- Agriculture:Minor applications include tin-based fungicide formulations and soil amendment research. Agricultural chemical registrations constrain commercial deployment relative to mature end uses.
Manufacturing holds installed capacity. Pharmaceuticals is expanding most quickly.
Distribution Channel:
Direct sales capture value through purity certification co-development, while distributor relationships erode in electronic-grade segments requiring technical liaison.
- Direct Sales:Refiner-to-fab contracting eliminates distribution markups and enables specification customization. Display panel manufacturers in Taiwan and South Korea lock in multi-year agreements with volume flexibility clauses.
- Distributors:Generalist chemical distributors retain position in technical-grade hydrated products for water treatment and textile applications. REACH dossier gaps are forcing retreat from pharmaceutical-grade segments.
- Online Retail:E-commerce platforms serve small-volume laboratory and research procurement. Specified purity certificates remain unavailable through digital channels for electronic-grade requirements.
- Specialty Stores:Regional chemical supply houses support maintenance-repair-operations purchasing in manufacturing clusters. Local inventory positioning competes on delivery speed rather than specification depth.
Direct sales holds installed capacity. Distributors is ceding share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined tin metal access dictates regional production economics, with southwestern Chinese smelters commanding asymmetric feedstock advantages. Display panel fabrication clusters and pharmaceutical manufacturing hubs drive divergent purity requirements across major consumption centers.
China
Yunnan and Jiangxi provinces host integrated tin mining-to-chemical operations serving domestic electronics fabs. MEE wastewater discharge limits elevate compliance costs for hydrated product facilities. Hefei and Chengdu display clusters absorb expanding volumes of vapor-phase purified SnCl₄ for indium tin oxide deposition.
South Korea
Foundry-grade precursor specifications from Samsung and SK Hynix fabs mandate sub-ppb metallic impurity thresholds. MFDS pharmaceutical manufacturing standards govern tin(II) chloride imports for API synthesis. Busan-Ulsan chemical processing complexes anchor specialty chloride purification capacity.
United States
EPA Toxic Substances Control Act emissions constraints limit domestic manufacturing expansion. FDA cGMP standards enforce documented impurity profiling for pharmaceutical-grade procurement. Texas and Arizona electronics manufacturing services consume tin chloride for high-density interconnect PCB surface finishing.
Germany
ECHA REACH authorization requirements stabilize import volumes for fully registered direct manufacturers. TIB Chemicals AG anchors European pharmaceutical-grade supply through specialized purification infrastructure. Bavarian chemical clusters serve semiconductor material engineers with dedicated supply chain audits.
India
Production-linked incentive schemes for semiconductor and PCB fabrication create new demand centers in Gujarat and Tamil Nadu. CDSCO manufacturing license requirements filter out non-registered pharmaceutical suppliers. Surat textile processing maintains steady technical-grade consumption for mordant applications.
Tin Chloride Market Competitive Environment
Concentration sits with integrated metal-to-chemical refiners possessing captive tin smelter access. The supplier base stratifies between vapor-phase purification specialists and legacy crystallization operators. Three archetypes dominate: southwestern Chinese integrated refiners, European pharmaceutical-grade purifiers, and diversified multinational chemical conglomerates. Competitive moves center on backward integration into tin metal supply and direct refiner-to-fab contracting to bypass distribution markups.
Among China-based integrated producers, Yunnan Tin Group and Liuzhou China Tin Group exemplify the captive feedstock archetype, leveraging southwestern tin belt access to dominate anhydrous feedstock economics. European specialists TIB Chemicals AG and Merck KGaA occupy positions within the pharmaceutical-grade and semiconductor-grade tiers respectively, with the former anchoring REACH-authorized supply and the latter representing ultra-high-purity specifications for etching applications. These named entities illustrate how geographic feedstock access and regulatory certification depth stratify competitive positioning.
| Leading Market Players |
|---|
| Yunnan Tin Group |
| Mason Corporation |
| Showa America |
| TIB Chemicals AG |
| Merck KGaA |
| Alfa Aesar |
| Gulbrandsen |
| Liuzhou China Tin Group |
| William Blythe |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at southwestern Chinese smelters creates asymmetric feedstock economics that compress price floors for hydrated tin chloride while elevating premiums for vapor-phase purified grades. Scale concentration in Yunnan and Jiangxi directly shapes margin distribution between technical-grade exporters and domestic electronic-grade suppliers serving Hefei and Chengdu display clusters.
Pricing Analysis
Volume-discount tiering separates electronic-grade anhydrous specifications from technical-grade hydrated products by order-of-magnitude price multiples. Price differentiation rests on metallic impurity certification thresholds, with sub-ppb specifications commanding foundry-grade premiums from Samsung and SK Hynix procurement teams. Cost compression in technical-grade segments is intensifying because London Metal Exchange tin volatility passes directly through to non-integrated producers. Water treatment buyers in India and Southeast Asia exhibit highest price sensitivity, while semiconductor material engineers prioritize purity certification over unit cost.
Supply Chain Analysis
China and South Korea anchor tin chloride refining capacity, with Busan-Ulsan chemical complexes specializing in foundry-grade purification and southwestern Chinese smelters dominating feedstock integration. Raw material dependencies center on refined tin metal from Yunnan Belt operations, chlorine gas supply contracts, and hydrochloric acid procurement for oxide reduction routes. Single-source vulnerability concentrates in anhydrous grade supply where vapor-phase purification infrastructure remains limited to integrated metal-to-chemical refiners. Distribution runs through direct refiner-to-fab contracting for electronic grades, while technical-grade hydrated products move through regional chemical distributors serving textile and water treatment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purity certification services and long-term supply agreement management represent expanding recurring-revenue layers that outpace hardware margin growth in tin chloride markets. Technical liaison and specification co-development with semiconductor material engineers now generate sustained service attach rates exceeding traditional chemical distribution economics.
For Market Incumbents: Consolidate captive tin metal supply through backward integration into Yunnan Belt mining assets or long-term offtake agreements with Liuzhou China Tin Group. Deepen vapor-phase purification capabilities to defend against gas-phase technology fragmentation threatening batch crystallization operators. Capacity addition in Gujarat and Tamil Nadu addresses emerging Indian electronics manufacturing demand while sidestepping REACH authorization barriers constraining European expansion. For New Entrants and Emerging Players: Anchor in pharmaceutical-grade tin(II) chloride supply where CDSCO manufacturing license requirements and FDA cGMP standards filter out non-registered competitors. Target generic API manufacturers in Gujarat and Tamil Nadu piloting hypophosphite alternatives, offering documented impurity profiling as a service-layer differentiator. Pursue direct contracting with sodium-ion battery anode developers evaluating tin chloride-derived materials for next-generation energy storage qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated metal-to-chemical refiners possessing captive tin smelter access and multi-year foundry-grade supply agreements. Long-term viability over the coming decade hinges on vapor-phase purification infrastructure and direct refiner-to-fab relationship depth rather than volume throughput. Monitor qualification timelines for battery-grade tin precursors as the critical inflection signal indicating demand expansion beyond display panel and PCB applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Metal Supply | Yunnan Belt captive feedstock access eliminates London Metal Exchange price volatility exposure for anhydrous producers. |
| Vapor-Phase Purification Capacity Expansion | Gas-phase technology displacement of batch crystallization meets sub-ppb semiconductor etching precursor specifications. |
| Long-Term Supply Agreement Structuring | Multi-year contracts with volume flexibility clauses lock in display panel fab demand from Samsung and Taiwan manufacturers. |
| Pharmaceutical-Grade Certification Investment | FDA cGMP and CDSCO compliance opens generic API synthesis demand from Gujarat and Tamil Nadu manufacturers. |
| Battery-Grade Precursor Qualification | Sodium-ion anode material evaluation by energy storage developers diversifies demand beyond electronics applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electronics plating house procurement managers, pharmaceutical API manufacturing directors, tin smelter operations heads, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade data, ECHA REACH registration databases, SEC 10-K filings of listed chemical conglomerates, and MEE wastewater discharge compliance records. Bottom-up volume modeling across grade tiers and end-use segments was triangulated against top-down production capacity assessments from southwestern Chinese refining clusters.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product grade tier, end-use industry concentration, regional production hub economics, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporated London Metal Exchange tin price scenario analysis, semiconductor node migration timelines for purity threshold escalation, and production-linked incentive scheme implementation progress in Indian electronics manufacturing zones.
Material uncertainties — tin metal price volatility swings, REACH authorization timeline extensions, dual-use export control expansions, and battery-grade precursor qualification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding display panel fab capacity expansion schedules and pharmaceutical generic API demand trajectories. Recalibration cycles align with material shifts in semiconductor node purity specifications and evolving multilateral precursor chemical shipment licensing frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Plates and Sheet Coils Market
Metals
Global Welding Powder Market
Metals
Stainless Steel Round Bar Market
Metals
Europe Metal Service Centers Market
Metals
Global Flat Carbon Steel Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
North America Electrical Steel Market
Metals
Japan Aluminium Powder Market
Metals
Aluminum Casting Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
North America and Europe Metal Powder Market
Metals
High Carbon Bearing Steel Market
Metals
Electrodeposited Copper Foil Market
Metals
Zinc Ingots Market
Metals
Silver Nitrate Market
Metals
North America Iron Casting Market