
 Middle East and Africa Ferric Chloride Market | 2026-2036
Middle East and Africa Ferric Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ferric Chloride Market Analysis
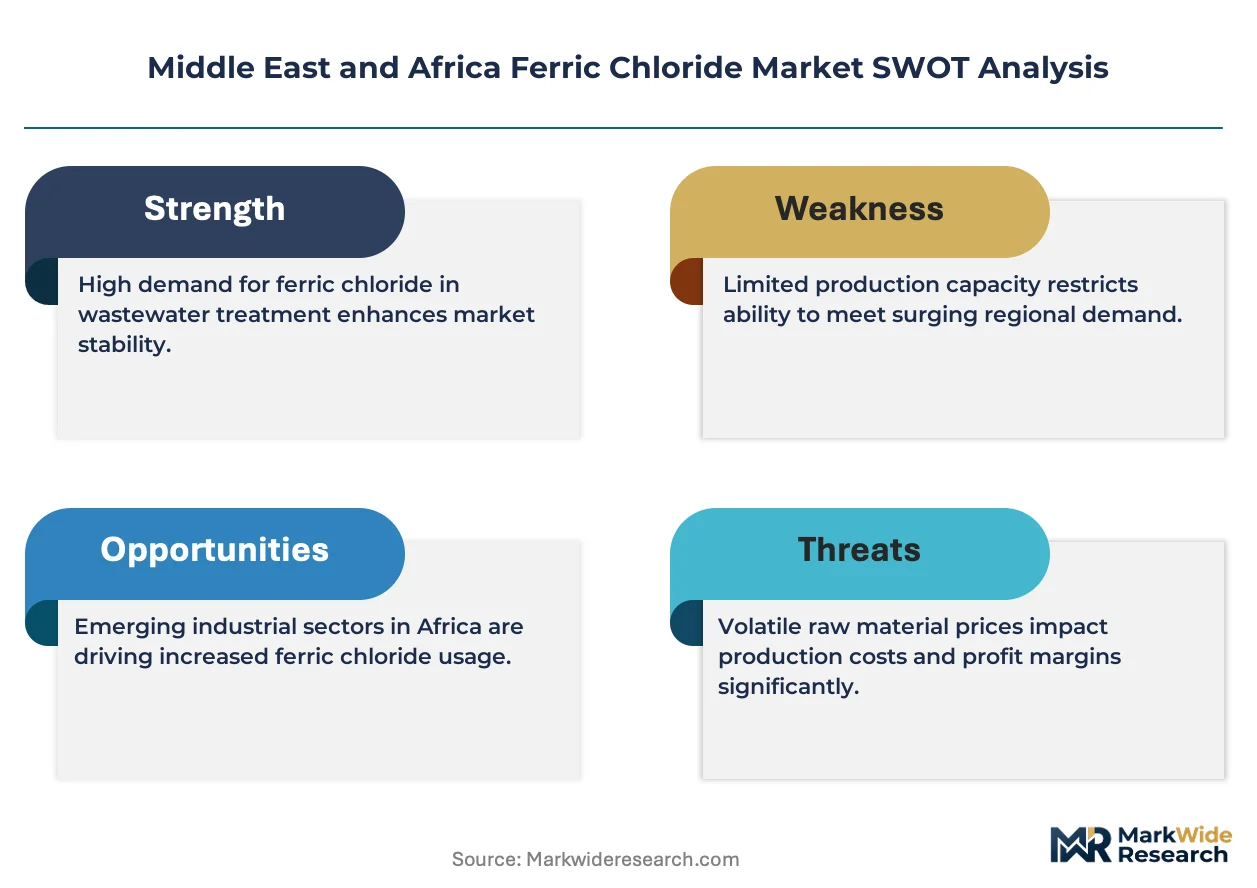
Technical-grade supply contracting is pivoting toward bundled water-treatment service agreements that embed ferric chloride within multi-year performance contracts. Kemira leverages its Nordic process technology heritage to anchor premium positioning in Gulf Cooperation Council desalination pre-treatment. Al Qahtani Chemicals Company sustains manufacturing proximity advantages across Saudi Arabia's Eastern Province industrial cluster.
Ferric chloride is an iron(III) salt, typically FeCl₃, manufactured via direct chlorination of iron scrap or oxidation of ferrous chloride in hydrochloric acid; it functions primarily as a coagulating agent for suspended solids removal and phosphate precipitation in water and wastewater systems. Liquid formulation dominates volume throughput across Middle East municipal tenders due to ease of bulk handling and automated dosing compatibility. Powder and granular grades command narrower but higher-margin niches in remote mining-camp water treatment and pigment synthesis, where packaging flexibility offsets freight premiums.
Saudi Arabia's national environmental regulator enforces industrial discharge limits that mandate enhanced chemical precipitation, while South Africa's Department of Water and Sanitation drives compliance upgrades in aging municipal infrastructure. REACH-aligned import documentation requirements from European suppliers shape product certification pathways for traders serving North African markets. Stakeholders must monitor how Gulf states integrate ferric chloride into circular water-economy frameworks and whether local chlor-alkali capacity expansions alter regional sourcing economics.
Market Dynamics
Municipal water treatment utilities across South Africa are consolidating chemical procurement under performance-based service contracts that embed ferric chloride dosing within multi-year operational agreements, compressing spot-market volumes and favoring integrated suppliers with automated dosing capabilities.
Growth Catalysts
- UAE's tightening industrial effluent standards:The national environmental regulator mandates enhanced chemical precipitation for petrochemical discharge, forcing facility upgrades across the Emirates' industrial zones.
- Saudi Arabia's circular water-economy frameworks:Captive wastewater treatment plants in the Eastern Province petrochemical corridor require consistent ferric chloride supply for phosphate removal and suspended solids reduction.
- Desalination pre-treatment expansion:Gulf Cooperation Council membrane-based desalination facilities are scaling ferric chloride dosing to protect reverse osmosis membranes from fouling.
Market Restraints
- Chlorine and hydrochloric acid cost volatility:Feedstock price swings for direct iron chlorination processes compress margin predictability for regional producers.
- European REACH-aligned import documentation:Certification pathway complexity from European suppliers creates friction for traders serving North African municipal tenders.
- Polyaluminum chloride substitution in low-turbidity applications:Alternative coagulants displace ferric chloride in select Saudi Arabian cooling water treatment systems.
Strategic Opportunities
- Nigeria's underpenetrated municipal water sector:Aging distribution infrastructure and expanding urban populations create whitespace for chemical dosing system upgrades.
- Remote mining-camp water treatment:Powder and granular grades command premium positioning in African extractive operations where packaging flexibility offsets logistics costs.
- Performance contracting models:Bundled water-treatment service agreements are embedding ferric chloride within multi-year operational contracts, shifting revenue from product sales to outcome-based fees.
Industry Challenges
- Specialized chemical dosing technician scarcity:Automated system calibration and membrane protection protocols require skills in short supply across Gulf municipal utilities.
- Legacy infrastructure integration complexity:South Africa's Department of Water and Sanitation facilities face retrofit friction when upgrading aging coagulation basins for automated ferric chloride feed systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ferric Chloride Market |
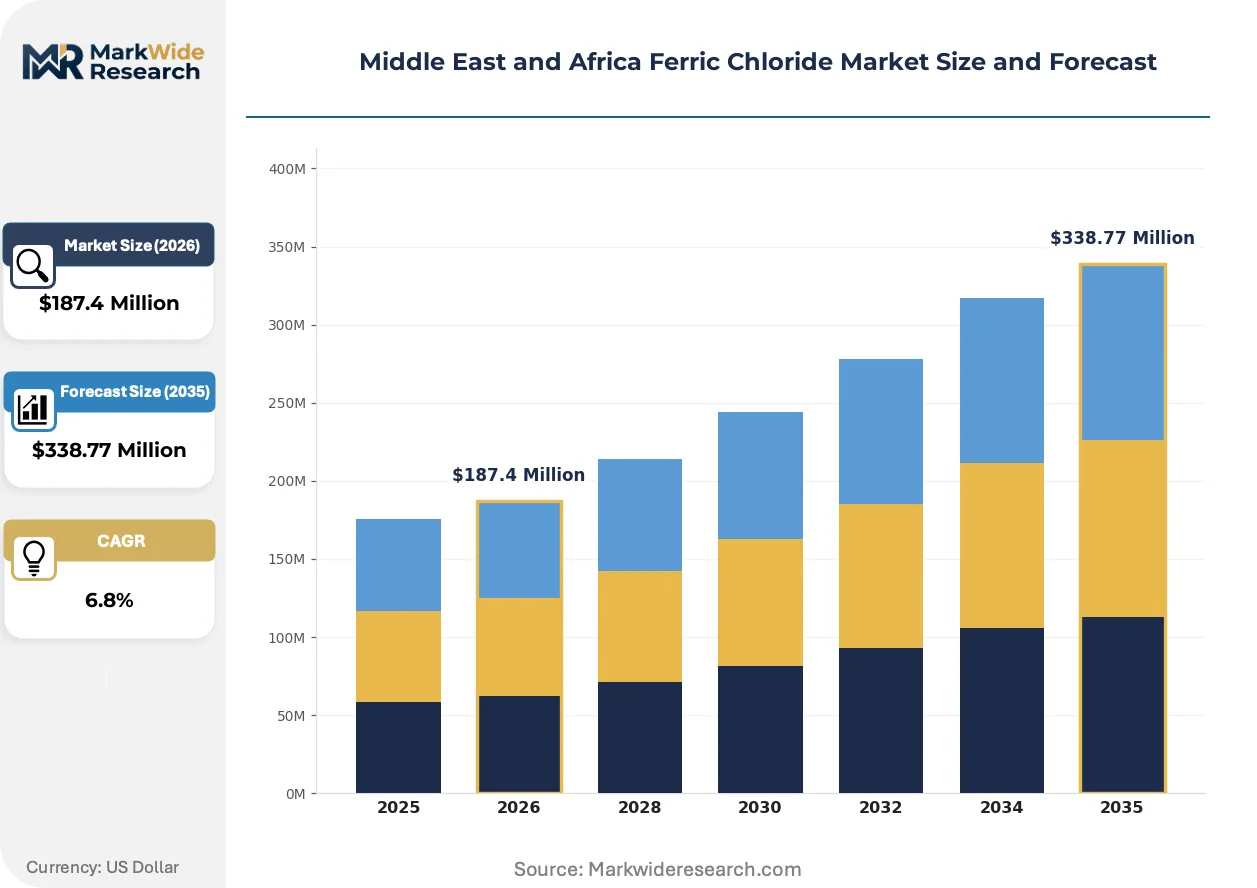
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Tablets Application: Water Treatment, Wastewater Treatment, Chemical Manufacturing, Pigment Production Packaging Type: Bags, Drums, IBC Totes, Bulk Containers Customer Type: Municipalities, Industrial Users, Water Treatment Plants, Agriculture |
| Companies Covered | Tessenderlo Group, Kemira, Al Qahtani Chemicals Company, Basic Chemical Industries, Kem One, SAT Sulphur Company, Swedish Jordanian Chemicals, Al Kout, Agua Chem Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ferric Chloride Market Emerging Trajectories
Digital dosing control systems and membrane protection chemistry are converging to reshape how ferric chloride is specified, procured, and consumed across Middle East and African water treatment operations.
Automated ferric chloride dosing skids equipped with real-time turbidity feedback loops are integrating into municipal treatment trains across the UAE's northern emirates. Dubai's utility operators are deploying these systems to optimize coagulant consumption and reduce manual laboratory testing cycles. This integration is compressing the operational window between raw water quality fluctuation and chemical adjustment response.
Saudi Arabia's national environmental regulator enforces industrial discharge limits that mandate enhanced chemical precipitation for heavy metals and phosphate. Petrochemical producers in Jubail Industrial City are retrofitting existing clarifiers with high-rate solids contact reactors to meet these standards. The regulatory pressure is accelerating specification upgrades from commodity-grade to technical-grade ferric chloride across the Eastern Province cluster.
Water treatment chemical buyers across South Africa's municipal sector are consolidating annual ferric chloride volumes under framework agreements with integrated service providers. Johannesburg's Rand Water and Cape Town's water utility are shifting from spot procurement to bundled contracts that include dosing equipment maintenance and laboratory support. This behavioral pivot is visible most acutely in metropolitan utilities with aging infrastructure compliance deadlines.
Middle East and Africa Ferric Chloride Market Segmentation
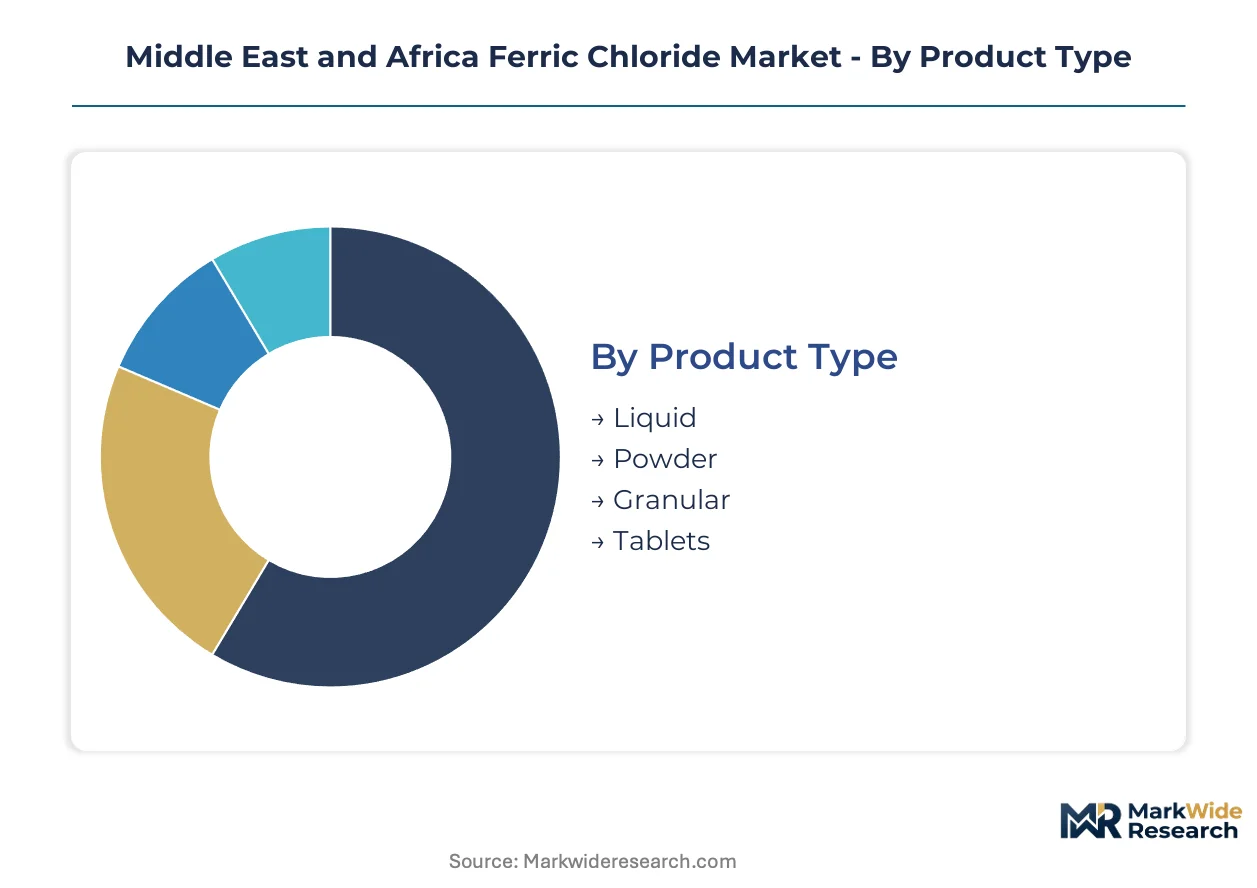
Ferric chloride procurement across the Middle East and Africa stratifies sharply by physical form, end-use chemistry, and logistics infrastructure. Specification requirements diverge between municipal tenders demanding automated dosing compatibility and remote industrial sites prioritizing packaging flexibility.
Product Type:
Certification burdens concentrate in liquid formulations requiring transport safety documentation for corrosive materials under Gulf Cooperation Council hazardous goods protocols, while solid grades face simpler warehousing compliance.
- Liquid:Aqueous ferric chloride solution at 40-45% FeCl₃ concentration dominates volume throughput. Municipal utilities in Dubai and Abu Dhabi specify liquid for automated bulk dosing systems in desalination pre-treatment.
- Powder:Anhydrous FeCl₃ crystals with 96% minimum purity serve remote mining operations. African extractive camps in Zambia and the Democratic Republic of Congo absorb powder grades where road logistics preclude bulk liquid tankers.
- Granular:Free-flowing particulate form bridges handling convenience and dissolution speed for mid-scale water treatment facilities.
- Tablets:Compressed solid form enables precise small-batch dosing in agricultural and specialty chemical applications.
Leading the category by volume: Liquid. Growing fastest: Powder.
Application:
Cost tiers separate commodity municipal water treatment from premium pigment synthesis, where iron salt purity specifications command threefold price multiples.
- Water Treatment:Coagulation and flocculation for potable water production. Saudi Arabia's national environmental regulator mandates enhanced dosing for membrane protection across Jubail desalination facilities.
- Wastewater Treatment:Phosphate precipitation and heavy metals removal. South Africa's Department of Water and Sanitation drives compliance upgrades in aging municipal clarifiers.
- Chemical Manufacturing:Etching agent and catalyst precursor for electronics and pharmaceutical intermediates.
- Pigment Production:Iron oxide precursor for construction and coatings industries.
Water Treatment commands the largest volume share. Wastewater Treatment exhibits the steepest expansion trajectory as discharge standards tighten.
Packaging Type:
Customer scale determines packaging economics, with bulk containers capturing petrochemical corridor demand and bags serving dispersed agricultural buyers.
- Bags:25-50kg woven polypropylene sacks for powder and granular grades. Nigerian municipal distributors prefer bagged product for last-mile distribution.
- Drums:200-250kg steel or plastic containers for liquid formulations. UAE industrial facilities specify drums for intermediate-scale dosing systems.
- IBC Totes:1000-liter intermediate bulk containers bridge manual handling and pump-fed automation.
- Bulk Containers:20,000+ liter ISO tank units for continuous supply to Saudi Eastern Province petrochemical complexes.
Bulk Containers lead by tonnage. IBC Totes are gaining share fastest among mid-scale utilities upgrading from drums.
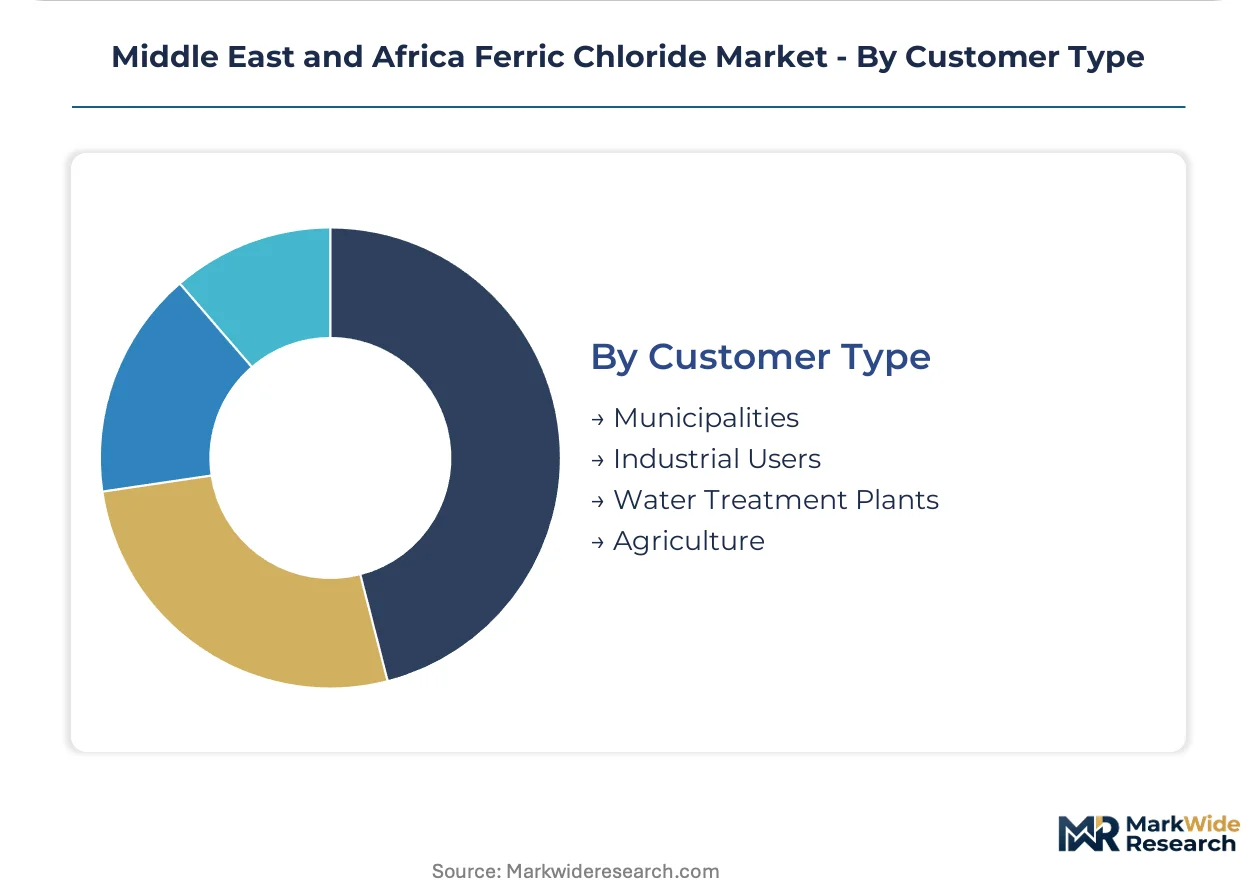
Customer Type:
Procurement sophistication varies from framework-agreement municipal buyers to spot-market agricultural purchasers with minimal technical specification.
- Municipalities:Government water utilities across South Africa and the UAE consolidate annual volumes under performance contracts embedding dosing equipment maintenance.
- Industrial Users:Petrochemical producers and mining operators with captive treatment plants. Saudi Aramco-affiliated facilities in Jubail Industrial City require consistent technical-grade supply.
- Water Treatment Plants:Third-party operators managing outsourced municipal infrastructure.
- Agriculture:Irrigation system operators and fertilizer blenders with seasonal, price-sensitive demand patterns.
Municipalities represent the largest customer segment by contract value. Industrial Users are expanding most quickly as circular water-economy frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production capacity clusters in Saudi Arabia's Eastern Province while consumption spreads across municipal utilities and industrial corridors throughout the Middle East and Africa. The UAE and South Africa absorb significant import volumes to bridge domestic supply gaps. Logistics infrastructure and chlor-alkali feedstock availability shape competitive positioning across each national market.
Saudi Arabia
Petrochemical producers in Jubail Industrial City drive technical-grade ferric chloride consumption for captive wastewater treatment. The national environmental regulator mandates enhanced chemical precipitation for phosphate removal and heavy metals reduction in industrial discharge. Eastern Province manufacturing complexes source consistently from local chlor-alkali integrated producers to minimize supply chain exposure.
United Arab Emirates
Desalination pre-treatment facilities across Dubai and Abu Dhabi scale ferric chloride dosing to protect reverse osmosis membranes from organic fouling. MOHAP oversees industrial effluent standards that force chemical dosing system upgrades in Emirates industrial zones. Northern emirate utilities deploy automated dosing skids with real-time turbidity feedback to optimize coagulant consumption.
South Africa
Municipal water treatment utilities in Johannesburg and Cape Town consolidate procurement under performance-based service contracts embedding ferric chloride dosing. The Department of Water and Sanitation drives compliance upgrades in aging clarifier infrastructure with phosphate precipitation mandates. Rand Water's metropolitan supply network represents the continent's most sophisticated chemical dosing specification environment.
Nigeria
Expanding urban populations in Lagos and Abuja strain aging distribution infrastructure, creating whitespace for chemical dosing system modernization. The country's national environmental regulator enforces evolving industrial discharge protocols that require imported technical-grade supply. Distributors prefer bagged powder formulations for last-mile delivery to dispersed municipal treatment facilities.
Egypt
Textile and chemical manufacturing clusters in the Nile Delta region generate industrial wastewater requiring ferric chloride precipitation for heavy metals compliance. The national environmental regulator aligns discharge standards with broader Mediterranean environmental frameworks. Alexandria and Damietta port facilities enable bulk liquid import for Red Sea and Suez Canal industrial zones.
Middle East and Africa Ferric Chloride Market Vendor Landscape
Top-tier vendors anchor Gulf Cooperation Council desalination and petrochemical contracts, while regional traders and local manufacturers occupy municipal and spot-market tiers. Market structure concentrates around chlor-alkali integrated producers with captive hydrochloric acid supply and Nordic technology licensors with membrane protection chemistry expertise. Strategic archetypes include feedstock-integrated Gulf producers, European technology specialists, and regional distribution-focused traders. Competitive moves center on multi-year performance contracting and automated dosing system bundling.
Among Nordic technology specialists, Kemira occupies a position exemplifying premium membrane protection chemistry heritage in Gulf desalination pre-treatment. Al Qahtani Chemicals Company represents manufacturing proximity advantages across Saudi Arabia's Eastern Province industrial cluster. Tessenderlo Group anchors European REACH-aligned supply pathways serving North African municipal tenders. These three companies illustrate how geographic origin and feedstock access stratify competitive positioning across the regional market.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Kemira |
| Al Qahtani Chemicals Company |
| Basic Chemical Industries |
| Kem One |
| SAT Sulphur Company |
| Swedish Jordanian Chemicals |
| Al Kout |
| Agua Chem Ltd |
| Others |
Supply Flow & Price Mechanics
Municipal procurement consolidation across South Africa's metropolitan utilities is compressing spot-market volumes and forcing suppliers toward bundled service contracts that embed ferric chloride within multi-year performance agreements. This buyer-side restructuring is reshaping how regional producers price technical-grade supply and allocate logistics capacity.
Pricing Analysis
Margin tightening in commodity-grade liquid formulations reflects hydrochloric acid feedstock volatility and chlorine cost swings from regional chlor-alkali plants. Three-tier pricing structure across technical-grade, standard-grade, and economy-grade levels separates membrane-protection chemistry for Gulf desalination from basic coagulation supply for Nigerian municipal tenders. Price differentiation traces to certification grade alignment with REACH-aligned import documentation and volume scale under framework agreements. Spot-market buyers in remote African mining camps exhibit highest price sensitivity, while Saudi petrochemical corridor purchasers prioritize supply consistency over unit cost.
Supply Chain Analysis
Direct-to-petrochemical-plant channels handle continuous bulk demand across Saudi Arabia's Eastern Province, with ISO tank deliveries bypassing intermediate warehousing. Geographic supply concentrates in Saudi Arabia, the UAE, and South Africa, with Egyptian bulk liquid imports bridging North African demand. Raw material dependencies center on chlorine gas, hydrochloric acid, and iron scrap feedstock from regional steel processing. Single-source vulnerability from concentrated chlor-alkali capacity in the Gulf Cooperation Council creates exposure to feedstock disruption. Distribution runs through integrated service providers for municipal utilities and direct bulk contracts for industrial captive treatment plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock-integrated Gulf producers and Nordic technology licensors are consolidating market share as framework contracting and automated dosing requirements squeeze independent traders. Polyaluminum chloride substitution in low-turbidity applications and REACH-aligned certification burdens are forcing weaker spot-market participants toward exit.
For Market Incumbents: Extend performance-contracting capabilities to capture South African municipal consolidation and defend against polyaluminum chloride displacement in Saudi cooling water systems. Deepen backward integration into captive hydrochloric acid supply to buffer margin compression from chlorine feedstock volatility. Anchor premium positioning through membrane-protection chemistry expertise in Gulf desalination pre-treatment. For New Entrants and Emerging Players: Municipal distributors in Nigeria represent the most penetrable channel, with bagged powder formulations for last-mile delivery to aging treatment infrastructure. Remote mining-camp water treatment across Zambia and the Democratic Republic of Congo offers whitespace where packaging flexibility commands premium positioning. Target performance-based service contracts with mid-scale utilities upgrading from drum-based to IBC tote systems. For Investors and Strategic Acquirers: The window for entry favors regional traders with established REACH-aligned import pathways and municipal distribution networks in North Africa. Long-term viability hinges on chlor-alkali feedstock integration and automated dosing system bundling capabilities. Monitor Gulf Cooperation Council circular water-economy framework implementation as inflection indicator for technical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive hydrochloric acid supply buffers margin compression from regional chlorine volatility. |
| Performance Contracting Model Expansion | Bundled dosing equipment maintenance shifts revenue from product sales to outcome-based fees. |
| Automated Dosing Skid Deployment | Real-time turbidity feedback integration captures UAE municipal upgrade cycles. |
| REACH-Aligned Certification Investment | European documentation compliance opens North African municipal tender pathways. |
| Remote Mining-Camp Distribution Network | Powder grade logistics flexibility penetrates African extractive operations with premium positioning. |
Methodological Framework
Document review covered customs and trade flow databases, chlor-alkali industry association reports, and municipal procurement tender records, complemented by interviews with plant managers at Saudi petrochemical facilities, procurement leads at South African water utilities, distribution channel partners serving North Africa, and technical R&D directors at Gulf desalination operators. Secondary validation drew from SEC filings of listed chemical producers, Gulf Cooperation Council hazardous goods transport regulations, and environmental regulator discharge standard documentation. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Segmented outputs across the projection horizon reflect grade tier differentiation, end-use industry concentration, packaging format preferences, and regional production hub clustering. CAGRs were derived from regression analysis of historical tender volumes and forward projection of regulatory mandate implementation timelines. Industry-specific inputs included membrane protection chemistry specification trends and circular water-economy framework adoption rates across Gulf states.
Caveats apply where feedstock price volatility, regulatory certification pathway changes, or substitution technology adoption could materially shift the outlook. Forecasts reflect documented assumptions regarding chlor-alkali capacity expansion timing and municipal procurement consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Global Butyl Acrylate Market