
 Middle East and Africa Methyl Acrylate Market | 2026-2036
Middle East and Africa Methyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Methyl Acrylate Market Foresight
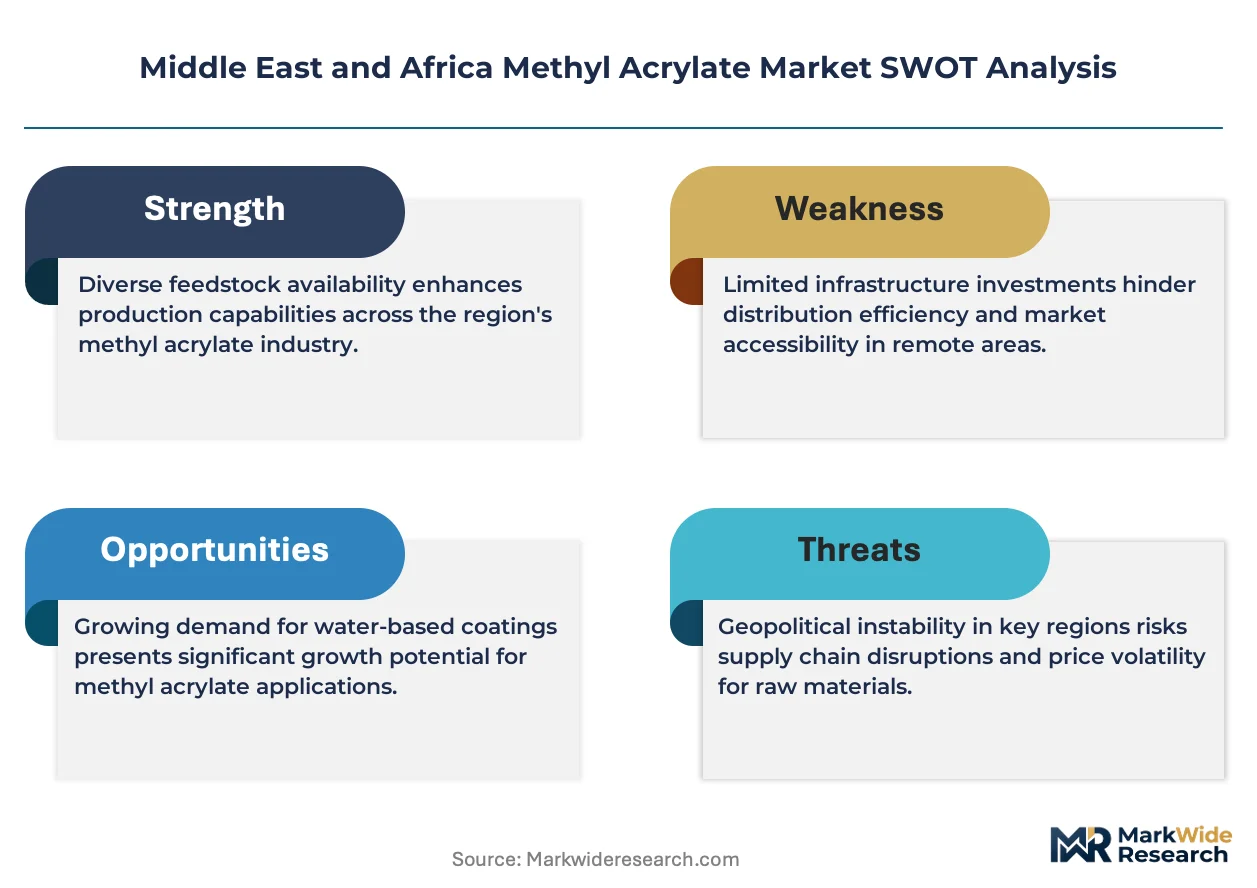
High-purity methyl acrylate grades is rotating toward dominance as coatings and adhesive formulators across the Middle East and Africa reject off-spec material. Saudi Basic Industries Corporation leverages its integrated cracker-to-derivative complex at Jubail to sustain cost-advantaged supply. BASF competes through specialized esterification technology that anchors quality consistency for waterborne coating customers. Arkema differentiates via controlled radical polymerization expertise that extends its reach into high-performance adhesive segments.
Methyl acrylate is an acrylic ester monomer produced through acid-catalyzed esterification of acrylic acid with methanol, typically supplied at purity levels exceeding 99.5 percent for polymer-grade applications. The monomer serves as a reactive building block for copolymers used in pressure-sensitive adhesives, textile sizing, and water-based protective coatings. Liquid form dominates procurement volumes across the region due to handling efficiency in bulk tank installations at coating plants. Adhesives end-use represents the fastest-expanding consumption pool as packaging and automotive assembly operations in Morocco and Egypt scale acrylate-based hot-melt formulations. Coatings maintains the largest value share, though margin compression in commodity architectural paints pushes producers toward higher-solid content methyl acrylate systems.
South Africa's National Regulator for Compulsory Specifications enforces SANS standards that restrict residual monomer content in consumer-facing coating products. The Gulf Standards Organization and Saudi Standards, Metrology and Quality Organization coordinate technical regulations for chemical imports that shape product registration timelines and testing protocols across Gulf Cooperation Council markets. Egypt's Ministry of Trade and Industry applies import inspection regimes that influence supplier qualification and documentation burdens for European and Asian methyl acrylate exporters. Stakeholders must monitor evolving VOC thresholds and local content incentives that determine whether regional blending operations or direct monomer imports offer superior route-to-market economics.
Market Dynamics
Saudi Arabia's Eastern Province petrochemical corridor anchors regional methyl acrylate supply through integrated cracker-to-derivative complexes, while South Africa's Air Quality Act VOC limits redirect formulation chemistry toward lower-emission acrylate systems across the continent.
Growth Catalysts
- Waterborne coating mandates:Gulf Standards Organization technical regulations for architectural finishes are accelerating procurement of acrylate esters for water-based systems in Saudi Arabia and the UAE.
- Pressure-sensitive adhesive expansion:Packaging and automotive assembly operations in Morocco and Egypt are scaling hot-melt formulations that rely on methyl acrylate copolymers as reactive building blocks.
- SANS residual monomer standards:South Africa's National Regulator for Compulsory Specifications enforces consumer-facing coating restrictions that favor polymer-grade purity levels exceeding 99.5 percent.
Market Restraints
- Acrylic acid feedstock volatility:Propylene price swings transmit directly into methyl acrylate production economics, compressing margin stability for non-integrated compounders.
- Jubail supply concentration:SABIC's integrated complex controls disproportionate regional capacity, creating single-source dependency risk for downstream formulators.
- Egyptian import inspection regimes:Ministry of Trade and Industry documentation burdens extend supplier qualification timelines and elevate working capital requirements for European and Asian exporters.
Strategic Opportunities
- East African underpenetration:Kenya and Ethiopia lack domestic acrylate derivative capacity, creating first-mover advantage for regional blending operations serving packaging adhesives.
- Controlled radical polymerization convergence:Advanced polymerization expertise combined with high-purity monomer supply opens high-performance adhesive segments previously served by solvent-based systems.
- Local content incentives:Gulf Cooperation Council domestic manufacturing preferences reward in-country compounding operations over direct monomer imports.
Industry Challenges
- Product registration timeline compression:Saudi Standards, Metrology and Quality Organization testing protocols create multi-month approval gaps that disrupt just-in-time formulation schedules.
- Specialized esterification skill scarcity:Regional talent pools lack depth in acid-catalyzed process optimization, forcing reliance on foreign technical service support.
- Legacy tank infrastructure incompatibility:Bulk liquid handling systems at older coating plants require capital-intensive retrofitting to meet polymer-grade purity storage standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Methyl Acrylate Market |
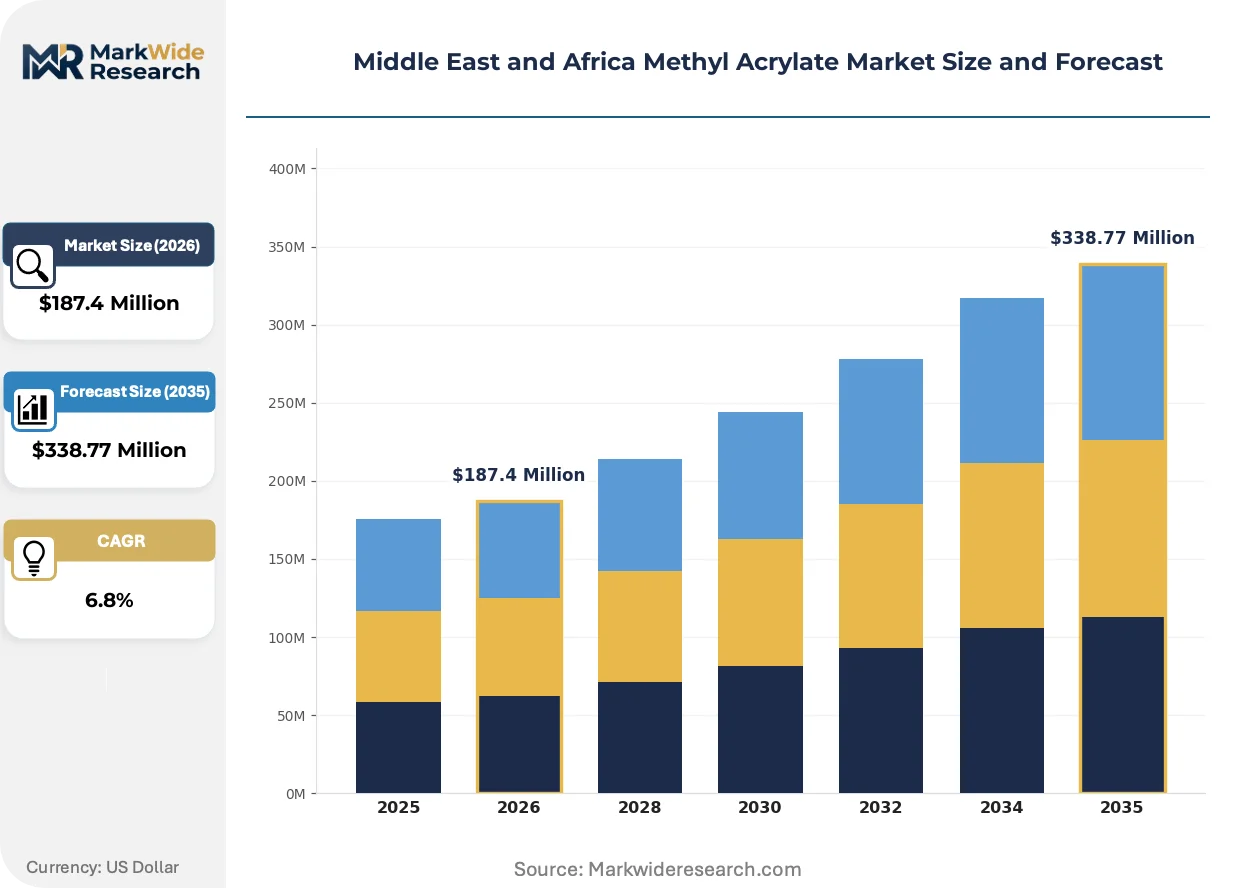
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
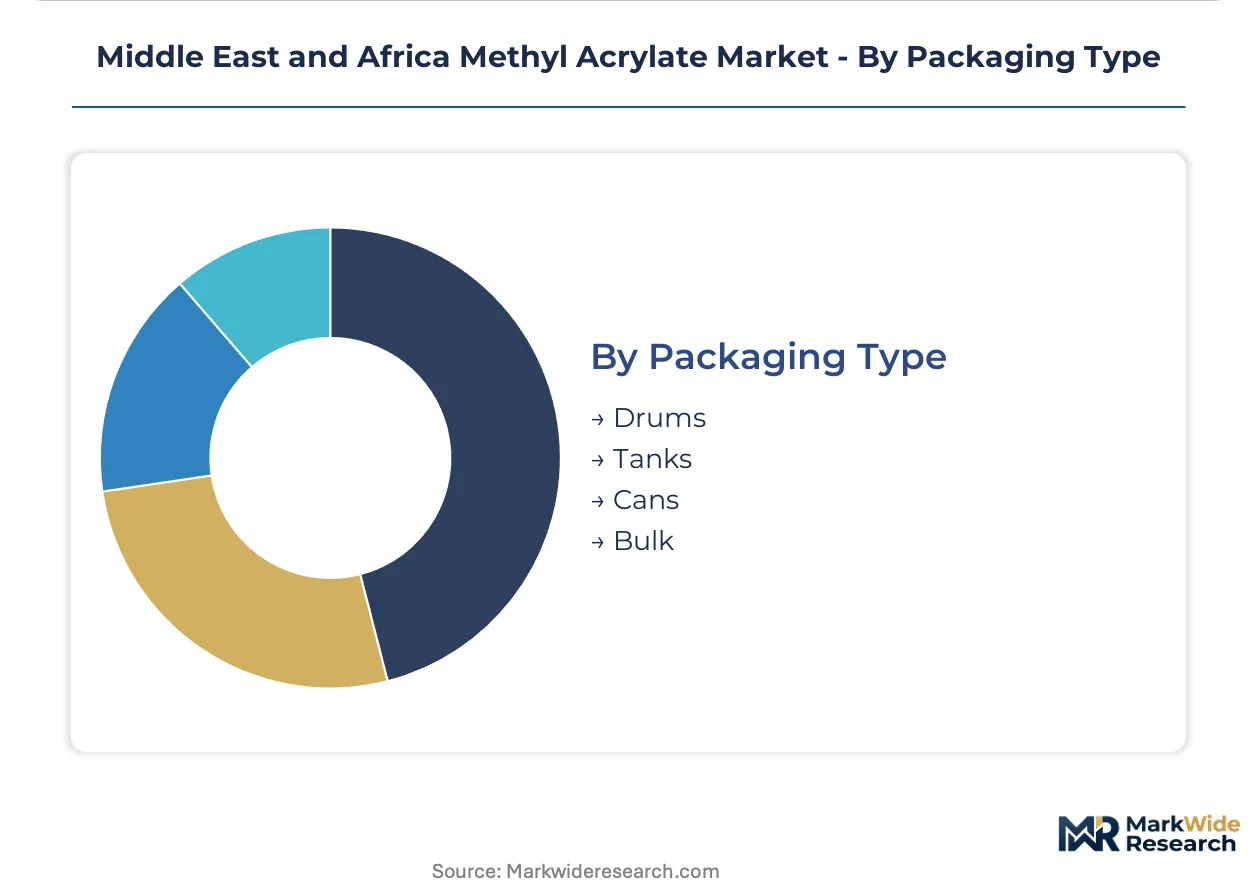
| Segmentation | Product Type: Butyl Acrylate, Ethyl Acrylate, Methyl Methacrylate, Others Form: Liquid, Solid, Powder, Emulsion End User: Adhesives, Coatings, Textiles, Construction Packaging Type: Drums, Tanks, Cans, Bulk |
| Companies Covered | Saudi Basic Industries Corporation, The Dow Chemical Company, BASF, Evonik Industries, Arkema, LG Chem, DuPont, Mitsubishi Chemical Corporation, Sumitomo Chemical, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Methyl Acrylate Market Shifts & Advancements
Formulation chemistry across the Middle East and Africa is pivoting toward higher-solid content systems and reactive hot-melt platforms, driven by regulatory emission thresholds and end-user performance specifications.
High-solid methyl acrylate systems are decomposing the traditional solvent-borne coating paradigm in Saudi Arabia's architectural finishes segment. Coatings manufacturers in Jubail and Yanbu industrial cities are adopting these platforms at accelerating pace to meet Gulf Standards Organization VOC thresholds. The technology is decomposing commodity paint margins while rewarding producers with captive esterification capability.
South Africa's Air Quality Act amendments under the National Environmental Management framework are tightening volatile organic compound limits for consumer-facing products. Industrial coating formulators in Gauteng and the Western Cape are reformulating toward water-based acrylate systems to maintain market access. The regulation most affects mid-tier architectural paint producers lacking R&D bandwidth for rapid chemistry transitions.
Buyer concentration among Gulf-based mega-project developers is compressing specification cycles for protective coatings. Procurement teams at Saudi Aramco and ADNOC-linked contractors now demand certified low-residual monomer grades with accelerated batch testing. This pattern is most visible in Saudi Arabia's Eastern Province infrastructure buildout, where single-source qualification locks out secondary suppliers.
Middle East and Africa Methyl Acrylate Market Segmentation
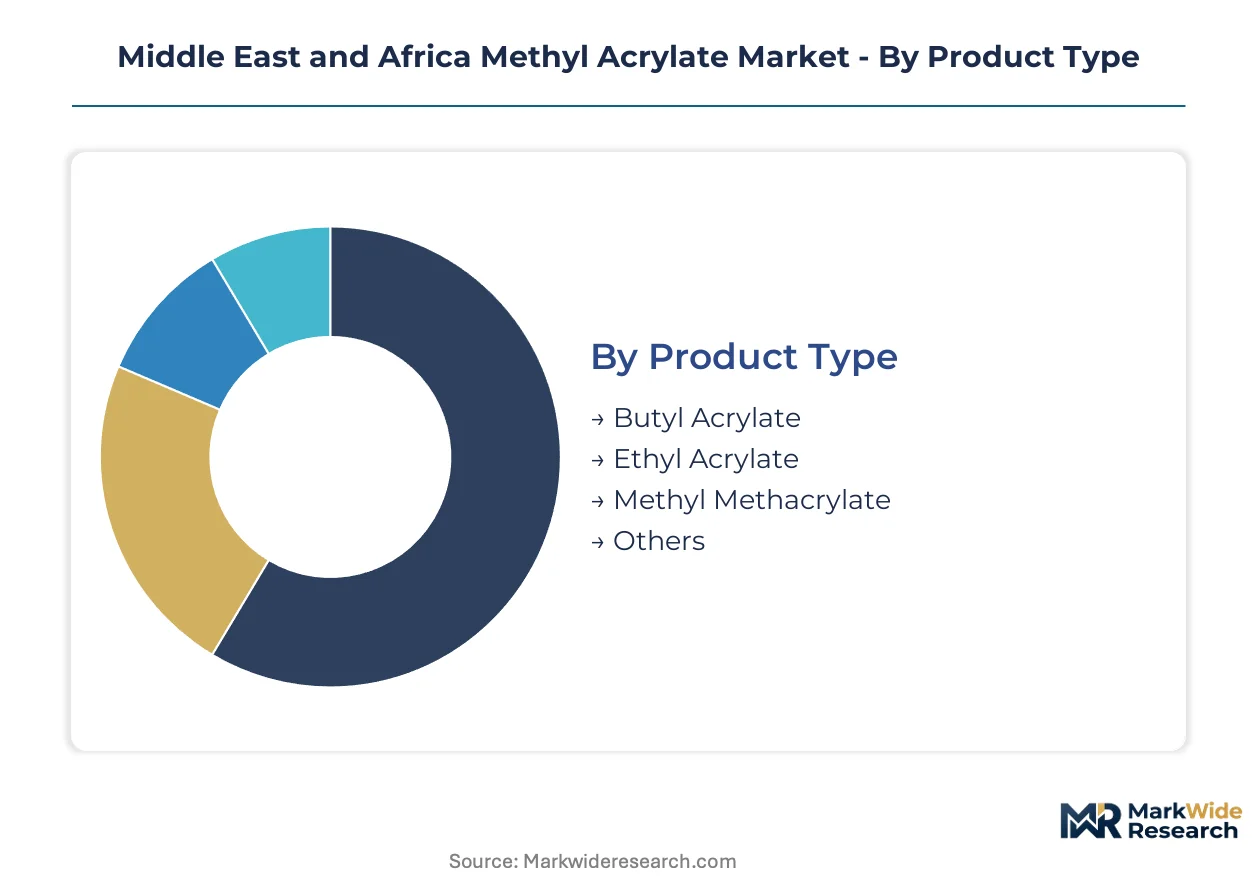
Methyl acrylate procurement patterns across the Middle East and Africa fragment across four structural dimensions. Each dimension carries distinct substitution pressures and margin implications for regional suppliers and downstream formulators.
Product Type:
Substitution pressure from alternative acrylate esters intensifies as formulators optimize cost-performance ratios across coating and adhesive applications.
- Butyl Acrylate:This longer-chain ester delivers superior flexibility and weathering resistance in exterior architectural coatings. Demand clusters in Saudi Arabia's Eastern Province infrastructure projects where Gulf Standards Organization VOC compliance mandates favor lower-emission formulations.
- Methyl Methacrylate:The methacrylic acid derivative offers enhanced thermal stability and optical clarity for specialty adhesive segments. Procurement from Morocco's packaging converters is climbing fastest as hot-melt formulation scales meet European export standards.
- Ethyl Acrylate:Intermediate chain length suits textile sizing applications across Egypt's Nile Delta spinning cluster.
- Others:Specialty esters including 2-ethylhexyl acrylate serve niche pressure-sensitive adhesive formulations in South Africa's automotive assembly corridor.
Butyl acrylate retains volume leadership; methyl methacrylate holds the steepest expansion curve.
Form:
Handling economics and purity preservation requirements divide procurement preferences between bulk liquid systems and solid alternatives.
- Liquid:Dominant format for polymer-grade supply exceeding 99.5 percent purity, delivered via dedicated tanker to Jubail and Yanbu coating complexes. Bulk liquid infrastructure at Saudi Aramco-linked terminals minimizes contamination risk during trans-shipment.
- Emulsion:Pre-dispersed aqueous systems bypass on-site dilution steps for waterborne coating manufacturers facing South African Air Quality Act compliance deadlines. Egyptian formulators in Alexandria's free trade zone are adopting emulsion feedstock to shorten batch cycle times.
- Solid:Pelletized grades serve remote textile sizing operations in Ethiopia's emerging industrial parks where bulk liquid storage is unavailable.
- Powder:Micronized formulations enable precise dosing in powder coating compounding for UAE architectural metal finishing.
Liquid form commands procurement volume; emulsion formats are expanding most quickly.
End User:
Regulatory emission thresholds and performance specifications are fragmenting demand intensity across downstream industries.
- Coatings:Architectural and protective finishes represent the largest value pool, though margin compression in commodity paints pushes producers toward higher-solid content systems. Saudi Arabia's mega-project developers specify certified low-residual monomer grades with accelerated batch testing protocols.
- Adhesives:Pressure-sensitive and hot-melt formulations for packaging and automotive assembly show the strongest volume momentum. Morocco's automotive parts suppliers and Egypt's corrugated packaging sector are scaling acrylate copolymer consumption for European market access.
- Textiles:Sizing and finishing applications in South Africa's KwaZulu-Natal apparel belt favor ethyl acrylate derivatives for yarn lubrication.
- Construction:Concrete modifiers and sealant applications in UAE infrastructure maintenance absorb specialty acrylate blends.
Coatings retains revenue leadership; adhesives holds the steepest expansion curve.
Packaging Type:
Scale of consumption and supply chain reliability requirements determine containerization preferences across the region.
- Bulk:Dedicated vessel and tank-to-tank transfer serves SABIC-integrated derivative producers and large coating compounders in Jubail Industrial City. This format eliminates drum handling costs and residual waste for high-volume consumers.
- Tanks:ISO tank containers enable flexible routing for European and Asian exporters serving Egyptian and Moroccan mid-tier formulators. The format balances working capital efficiency against smaller batch requirements.
- Drums:Standard 200-liter steel drums serve regional distributors supplying South Africa's fragmented coating SME sector.
- Cans:Smaller metal containers reach laboratory and pilot-scale users in Kenya's emerging adhesive testing facilities.
Bulk packaging dominates procurement tonnage; tank containers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the Middle East and Africa. Gulf buyers with integrated supply chains absorb feedstock volatility, while African formulators face acute cost pressure from currency exposure and import dependency.
Saudi Arabia
Waterborne coating mandates from the Saudi Standards, Metrology and Quality Organization are accelerating acrylate ester procurement for architectural finishes. The Gulf Standards Organization coordinates technical regulations that shape product registration timelines across Gulf Cooperation Council markets. Jubail Industrial City's petrochemical corridor anchors regional supply through SABIC-integrated cracker-to-derivative complexes serving downstream coating manufacturers.
United Arab Emirates
ADNOC-linked infrastructure contractors specify certified low-residual monomer grades with accelerated batch testing protocols. The Emirates Authority for Standardization and Metrology enforces VOC thresholds for consumer-facing coating products. Dubai and Abu Dhabi's mega-project developers concentrate procurement power, compressing specification cycles for protective coating suppliers.
South Africa
The National Regulator for Compulsory Specifications enforces SANS standards that restrict residual monomer content in architectural paints. Air Quality Act amendments under the National Environmental Management framework tighten volatile organic compound limits for industrial coatings. Gauteng and Western Cape formulators are redirecting chemistry toward water-based acrylate systems to maintain market access.
Egypt
Corrugated packaging and automotive parts suppliers in the Nile Delta are scaling hot-melt acrylate copolymer consumption for European export compliance. The Ministry of Trade and Industry applies import inspection regimes that extend supplier qualification timelines for European and Asian exporters. Alexandria's free trade zone coating manufacturers are adopting emulsion feedstock formats to shorten batch cycle times.
Morocco
Automotive assembly operations and packaging converters are expanding pressure-sensitive adhesive formulation for European market access. The country's national standards body aligns technical regulations with EU REACH frameworks to facilitate export qualification. Casablanca's industrial corridor concentrates demand for methyl methacrylate derivatives in specialty hot-melt applications.
Middle East and Africa Methyl Acrylate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa methyl acrylate market. Gulf-based integrated petrochemical complexes command feedstock economics, while European and Asian specialists anchor quality consistency for polymer-grade applications. The competitive terrain stratifies into three archetypes: integrated petrochemical majors with captive acrylic acid supply, specialized esterification technology providers, and controlled radical polymerization experts serving high-performance adhesive segments. Dominant competitive moves center on backward integration into propylene feedstock and technology licensing partnerships that transfer process expertise to regional compounders.
Among the integrated majors, Saudi Basic Industries Corporation exemplifies cost leadership through its Jubail complex position. BASF and Arkema occupy positions within the technology-specialist tier, representing differentiated approaches to esterification quality and advanced polymerization expertise. These three anchors illustrate how competitive positioning fragments across cost-driven and performance-driven demand pools.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation |
| The Dow Chemical Company |
| BASF |
| Evonik Industries |
| Arkema |
| LG Chem |
| DuPont |
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical |
| Others |
Supply & Pricing Matrix
Emulsion-format methyl acrylate substitution for bulk liquid is simultaneously redrawing procurement geography toward Alexandria's free trade zone and compressing working capital economics for Egyptian formulators facing Ministry of Trade and Industry inspection delays. This format shift rewards suppliers with regional blending infrastructure while penalizing distant exporters dependent on ISO tank logistics.
Pricing Analysis
After-sales technical service contracts now generate disproportionate lifetime value as coating formulators in Jubail and Yanbu industrial cities demand on-site esterification troubleshooting and rapid batch certification. Three-tier pricing structure across premium, standard, and economy levels separates SABIC-integrated supply from European specialist imports and spot-market Asian volumes. Cost compression in commodity architectural grades is intensifying because downstream margin pressure transmits upstream through concentrated buyer power at Saudi Aramco-linked contractors. Mid-tier Egyptian formulators exhibit highest price sensitivity due to currency exposure and extended qualification timelines, while Gulf mega-project developers prioritize certified low-residual monomer grades with minimal elasticity.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for Saudi Arabia's Eastern Province petrochemical corridor, where SABIC-integrated complexes anchor regional methyl acrylate availability. Propylene, methanol, and acrylic acid feedstock draws from Gulf Cooperation Council petrochemical infrastructure and Asian chemical export hubs. Single-source vulnerability concentrates in Jubail's cracker-to-derivative complexes, where non-integrated compounders lack alternative qualified supply. Distribution runs through dedicated tanker vessels for high-volume coating manufacturers, ISO tank containers for mid-tier Moroccan and Egyptian formulators, and steel drums for South Africa's fragmented SME sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and formulation support contracts are expanding faster than monomer hardware sales as coating manufacturers across the Gulf prioritize just-in-time chemistry transitions over inventory-heavy procurement.
For Market Incumbents: Compound defensive positioning through captive esterification capacity additions in Jubail Industrial City and accelerated SANS certification investments for South African market access. Moroccan packaging converter consolidation and Egyptian import inspection complexity threaten margin stability for non-integrated suppliers. Backward integration into propylene feedstock remains the priority lever for cost leadership. For New Entrants and Emerging Players: Post-sales technical service gaps in controlled radical polymerization expertise offer white-space entry as Arkema and BASF concentrate on high-volume coating accounts. Kenya and Ethiopia's underpenetrated packaging adhesive segments present the most penetrable geography with minimal incumbent technical service presence. Partner with regional distributors possessing existing Ministry of Trade and Industry registration to compress Egyptian market entry timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional compounders in Egypt's Alexandria free trade zone and Morocco's Casablanca industrial corridor. Five-to-ten-year viability hinges on waterborne formulation chemistry transition completion across Gulf Cooperation Council markets. Monitor Gulf Standards Organization VOC threshold announcements as inflection indicators for accelerated regional blending capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | SABIC's Jubail complex demonstrates cost leadership through captive cracker supply. |
| Controlled Radical Polymerization Licensing | Arkema's technology partnerships open high-performance adhesive segments for regional compounders. |
| Emulsion Format Capacity Expansion | Alexandria free trade zone manufacturers shorten batch cycles for Egyptian coating formulators. |
| SANS Certification Fast-Track Program | South Africa's National Regulator for Compulsory Specifications accelerates market access for polymer-grade suppliers. |
| East African Distribution Partnership | Kenya's packaging adhesive demand lacks domestic derivative capacity, rewarding first-mover regional blending. |
Research Methodology
Initial hypotheses were tested against primary input from coating plant managers, adhesive procurement leads at Moroccan packaging converters, SABIC technical R&D directors, and Egyptian Ministry of Trade and Industry registration specialists, then refined against customs and trade data, Gulf Standards Organization technical regulations, SEC 10-K chemical segment disclosures, and South African Air Quality Act amendment records. Bottom-up volume estimates from individual facility consumption patterns were triangulated against top-down regional production capacity assessments.
Variance decomposition across purity grades, end-use industries, packaging formats, and regional production hubs shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated Gulf Cooperation Council domestic manufacturing preference intensity and European REACH alignment progress in Morocco's automotive supplier corridor.
Material uncertainties — propylene price volatility, Egyptian inspection regime modifications, and South African VOC threshold acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation timing and feedstock cost transmission. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Welding Chemicals Market
Chemicals
Bronopol Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Linear Mercaptans Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Piroctone Olamine Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Laboratory Chemicals Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Household Insecticides Market
Chemicals
Aerosol Insecticides Market
Chemicals
Power Plant Chemicals Market
Chemicals
Isooctyl Alcohol Market